
 Europe Office Real Estate Market | 2026-2036
Europe Office Real Estate Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Office Real Estate Market Foresight
Market Context
European institutional capital is hardening its allocation to prime office stock as interest rate stabilization restores yield confidence. Savills leverages its cross-border investment platform to capture pan-European portfolio flows, while Gecina sustains its Paris-centric dominance through concentrated Grade A ownership. Aroundtown SA anchors its position across German and Dutch gateway cities with disciplined value-add repositioning.
Technical Definition and Structural Segments
Europe Office Real Estate encompasses income-producing commercial buildings designed for administrative, professional, and knowledge-work activities, typically featuring floor plates of 500–2,500 square meters, HVAC systems targeting 20–24°C operational bands, and floor load ratings of 3.5–5.0 kN per square meter to support dense workstation configurations. Traditional offices retain the largest share of institutional capital deployment, though flex offices and co-working spaces are capturing disproportionate leasing velocity as corporates seek operational agility without long-term balance sheet commitment. A Class buildings command persistent rental premiums where energy performance certificates align with EU Green Deal trajectory requirements, while B Class stock faces accelerated obsolescence risk across aging urban cores.
Regulatory Framework and Outlook
The EU Green Deal and national transpositions through building performance standards in Germany, France, and the Netherlands are mandating progressive energy efficiency thresholds that reshape capital expenditure planning and tenant selection criteria. ESG disclosure frameworks including CSRD extend transparency obligations to real estate owners, influencing financing terms and investor access. Stakeholders must monitor regulatory calibration between national implementation timelines and the availability of retrofit financing mechanisms.
Market Dynamics
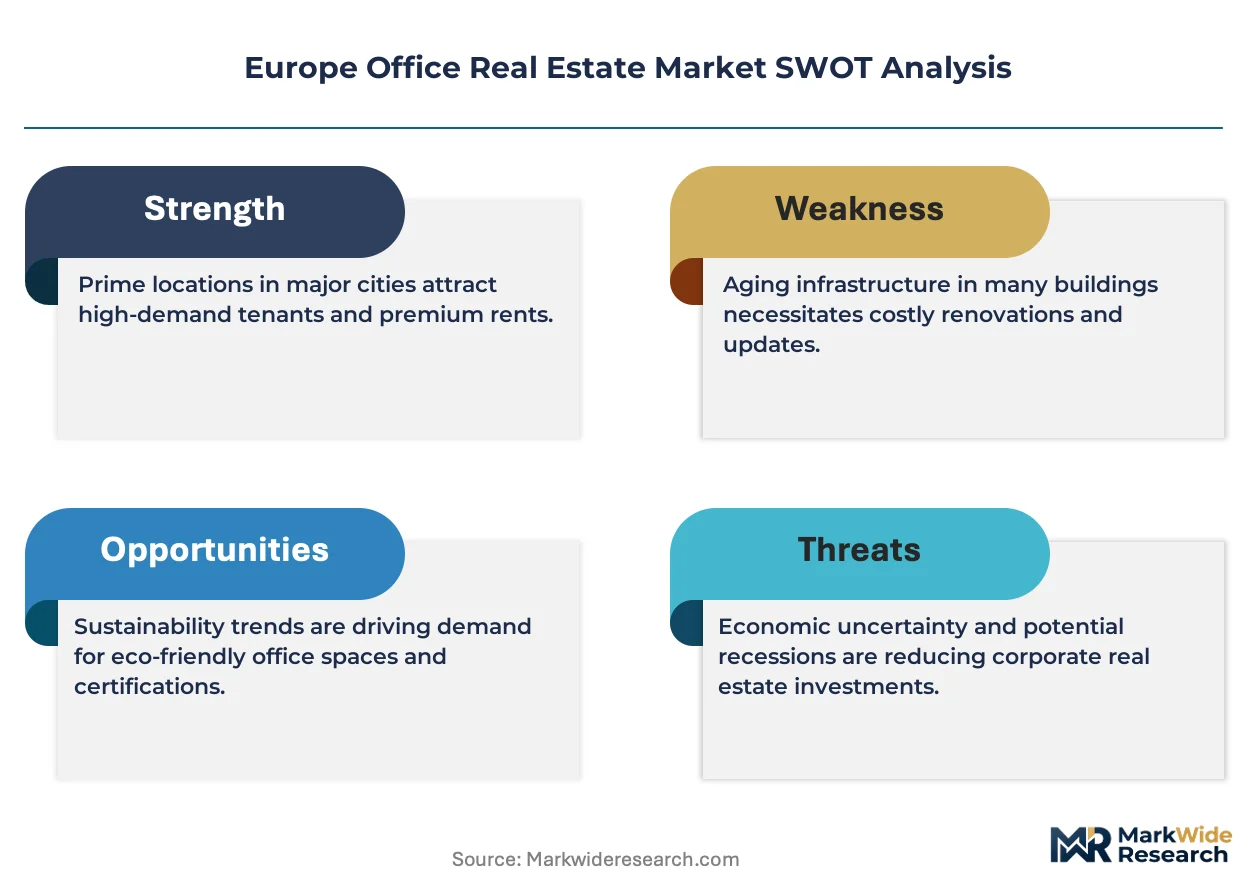
The EU Green Deal's building performance standards are compressing capital deployment timelines across European office portfolios, forcing owners to front-load energy retrofit expenditures or face accelerated asset obsolescence in gateway cities.
Growth Catalysts
- EU Green Deal retrofit mandates:National building performance standards in Germany, France, and the Netherlands are compelling energy efficiency upgrades that unlock premium rental tiers for compliant assets.
- Technology sector footprint expansion:Knowledge-work employers are scaling hybrid-ready office configurations across Berlin, Amsterdam, and Barcelona, sustaining absorption in flex and core-plus segments.
- Institutional yield stabilization:European central bank rate pauses are restoring confidence in prime office income streams, redirecting sovereign wealth and pension capital toward stabilized core assets.
Market Restraints
- Construction input cost volatility:Steel and aluminum price swings are compressing development margins on speculative office projects in London and Frankfurt corridors.
- Debt-dependent ownership concentration:Highly leveraged private equity sponsors face refinancing friction as loan-to-value covenants tighten against mark-to-market valuation declines.
- Remote work permanence:Distributed administrative functions are structurally reducing per-employee office square footage requirements across financial and professional services verticals.
Strategic Opportunities
- Poland and Romania gateway penetration:Warsaw and Bucharest office submarkets offer yield spreads of 150-200 basis points above Western European peers with improving liquidity.
- CSRD-aligned ESG data infrastructure:The Corporate Sustainability Reporting Directive creates service revenue streams for landlords providing granular carbon and energy performance transparency to tenants.
- Life sciences conversion pipeline:Obsolete B-grade office stock in suburban Paris and Munich rings is repurposing into laboratory and R&D facilities under relaxed zoning interpretations.
Industry Challenges
- Retrofit financing assembly:Stacking EU taxonomy-compliant green bonds with national subsidy layers requires specialized capital structuring expertise scarce among mid-size asset managers.
- Tenant improvement cost recovery:Shortened lease durations in flex arrangements prevent amortization of bespoke fit-out expenditures across standard ten-year hold periods.
- Grid interconnection delays:Utility upgrade timelines for electrified heating and cooling systems are extending project delivery schedules beyond lease commencement commitments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Office Real Estate Market |
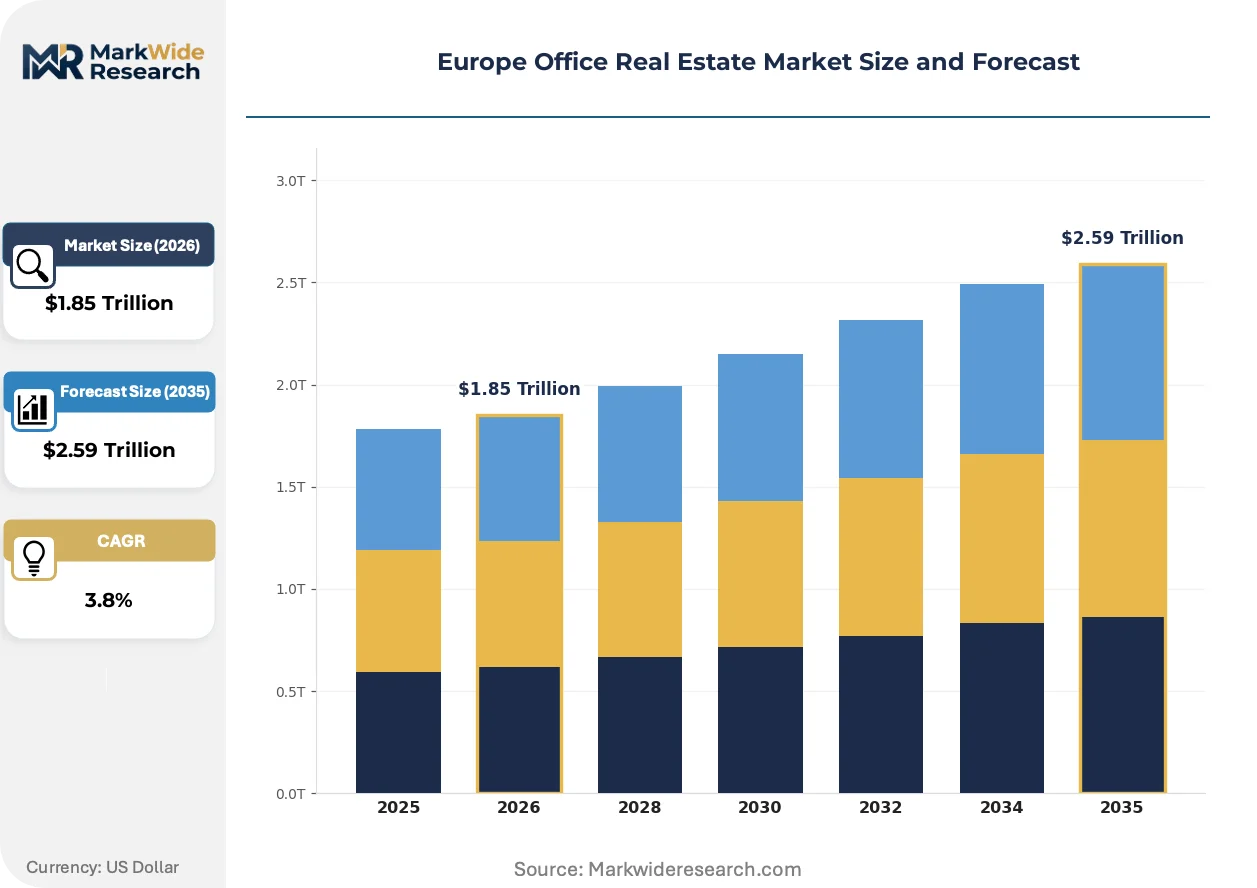
| Market Size in 2026 | $1.85 Trillion |
| Market Size in 2035 | $2.59 Trillion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Property Type: Co-working Spaces, Traditional Offices, Flex Offices, Remote Work Hubs Lease Type: Short-Term Leases, Long-Term Leases, Subleases, Flexible Contracts End User: Startups, Corporates, Freelancers, Multinationals Building Class: A Class, B Class, C Class, Mixed-Use Properties |
| Companies Covered | Savills, Aroundtown SA, Jones Lang LaSalle IP, Inc., Unibail-Rodamco-Westfield, Gecina, CBRE, Colliers, Vonovia SE, Cushman & Wakefield, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Office Real Estate Market Shifts & Advancements
Intelligent building systems and alternative lease structures are reconfiguring how office space is procured, operated, and valued across European institutional portfolios. Three developments are compressing traditional asset management approaches.
Smart building platforms integrating IoT sensors with predictive HVAC algorithms are expanding into premium office stock across Amsterdam and Frankfurt. Corporate occupiers with net-zero commitments are specifying these systems as lease preconditions. The technology is expanding into mid-market B-grade assets as landlords seek certification-driven rental premiums.
The EU's Corporate Sustainability Reporting Directive now extends disclosure obligations to real estate owners with significant tenant footprints. CSRD compliance is forcing asset-level energy data granularity that reshapes financing terms and investor access. German and French institutional landlords are responding by deploying centralized sustainability data infrastructure across distributed portfolios.
Occupiers are unbundling long-term lease commitments into shorter-duration, expansion-option contracts that transfer balance-sheet risk to landlords. This preference is displacing traditional ten-to-fifteen-year fully repairing and insuring structures in London and Paris submarkets. Financial services and technology employers are driving this shift most visibly, prioritizing operational agility over cost certainty.
Europe Office Real Estate Market Segmentation
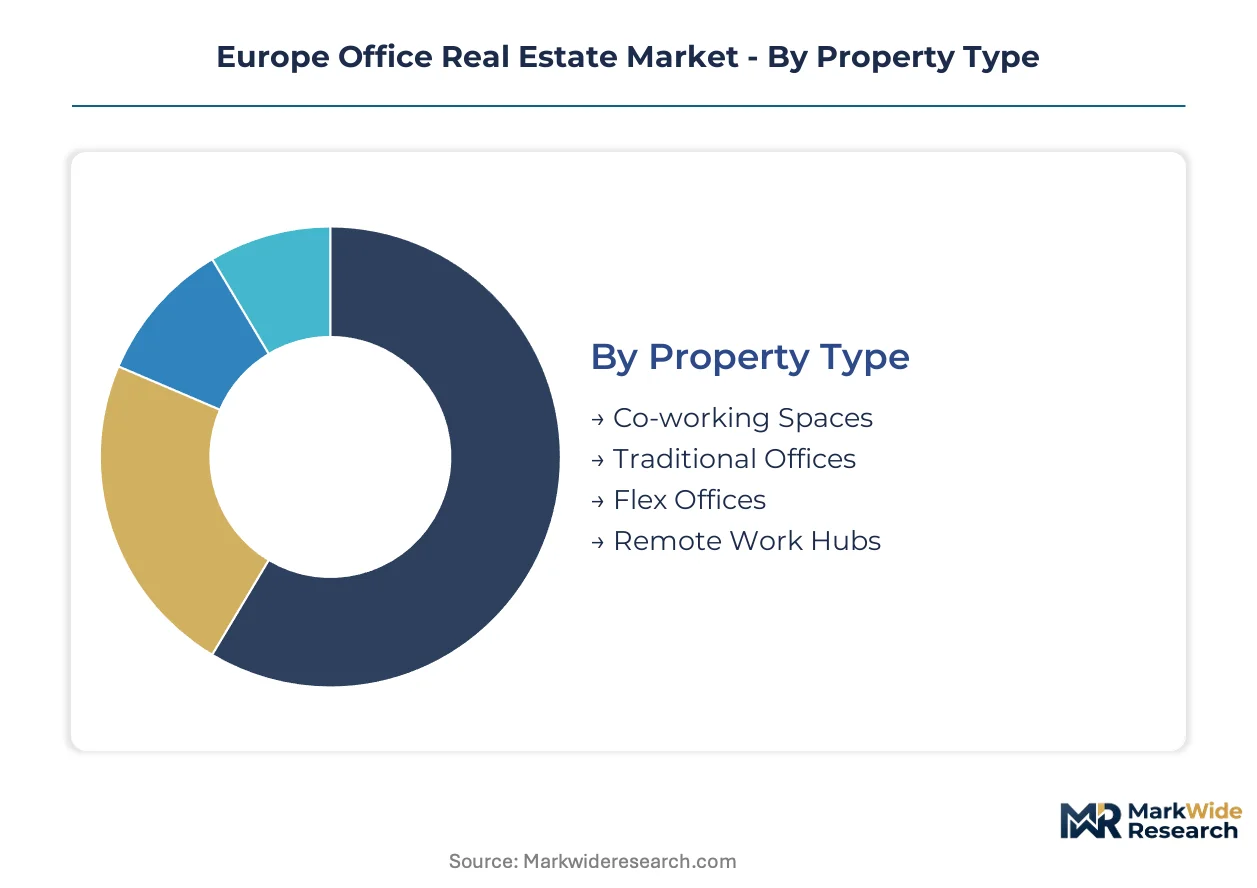
Segmentation in the Europe Office Real Estate Market reveals how regulatory pressure and tenant preferences are fragmenting capital deployment strategies. Investors must align portfolio construction with divergent energy compliance burdens and lease duration preferences across distinct property and user categories.
Property Type:
EU Green Deal energy performance certificates impose tiered retrofit deadlines that vary sharply across property configurations, with some segments facing immediate obsolescence risk while others capture premium absorption.
- Traditional Offices:Purpose-built administrative structures with floor plates of 500–2,500 square meters and HVAC systems targeting 20–24°C operational bands. Institutional capital concentrates here in Germany's major metropolitan corridors where energy retrofit timelines are most pressing under national building performance standards.
- Flex Offices:Hybrid-ready configurations with modular fit-outs and shorter lease commitment structures. Technology sector employers in Amsterdam and Barcelona are scaling these spaces fastest as they prioritize operational agility over balance sheet commitment.
- Co-working Spaces:Shared amenity-rich environments with communal reception, meeting facilities, and flexible desk arrangements. Freelancers and early-stage ventures in London submarkets drive occupancy velocity here.
- Remote Work Hubs:Satellite locations designed for distributed team gatherings rather than daily occupancy. Corporate occupiers with net-zero commitments are piloting these in secondary French and Dutch cities to reduce commuter emissions.
Traditional offices sit at the top of the volume ranking, with flex offices climbing the fastest.
Lease Type:
Capital recovery horizons and refinancing risk profiles diverge dramatically based on which lease structures dominate a given portfolio.
- Long-Term Leases:Ten-to-fifteen-year fully repairing and insuring contracts with tenant responsibility for maintenance and insurance. Pension funds and sovereign wealth vehicles in Paris favor these for yield stability.
- Flexible Contracts:Expansion-option arrangements with unbundled commitments and landlord-carried balance sheet risk. Financial services employers in London are displacing traditional structures with these agreements.
- Short-Term Leases:Duration of one to three years with limited tenant improvement allowances. Startup tenants in Berlin's Kreuzberg corridor absorb these despite higher per-square-meter rates.
- Subleases:Secondary market arrangements where original tenants monetize excess capacity. Technology sector footprint reductions in Dublin and Frankfurt are expanding sublease availability.
Long-term leases still dominate institutional portfolios, though flexible contracts are gaining share fastest among new capital deployment.
End User:
Tenant credit quality and space customization demands vary systematically across user categories, reshaping landlord underwriting criteria.
- Multinationals:Large-cap employers with centralized procurement functions and standardized global workplace standards. These occupiers in Munich and Frankfurt specify smart building platforms as lease preconditions.
- Corporates:Mid-market established enterprises with regional headquarters requirements. Dutch and Belgian corporates are consolidating into A Class stock to meet CSRD disclosure obligations.
- Startups:Venture-backed growth companies with rapid headcount volatility and limited balance sheet strength. Warsaw's emerging tech corridor attracts these users to co-working and flex arrangements.
- Freelancers:Independent professionals purchasing membership-based access rather than dedicated leases. Barcelona and Lisbon submarkets cater to this segment through hospitality-infused workspace concepts.
Multinationals anchor prime rental tiers, with corporates expanding most quickly as hybrid policies stabilize.
Building Class:
Energy performance certificate alignment with EU Green Deal trajectories is compressing valuation spreads between compliance tiers.
- A Class:Premium stock with EPC ratings meeting or exceeding national building performance standards through 2035. German institutional landlords in Frankfurt's Bankenviertel command persistent rental premiums here.
- B Class:Aging urban core assets requiring capital-intensive retrofit to avoid obsolescence. Suburban Paris and Munich rings are seeing these properties convert to life sciences use under relaxed zoning.
- C Class:Functionally obsolete structures with limited prospects for energy compliance or competitive repositioning. Value-add sponsors in secondary Dutch cities face financing friction on these assets.
- Mixed-Use Properties:Hybrid configurations integrating office with residential, retail, or hospitality components. Amsterdam's Zuidas district exemplifies this format's resilience through diversified income streams.
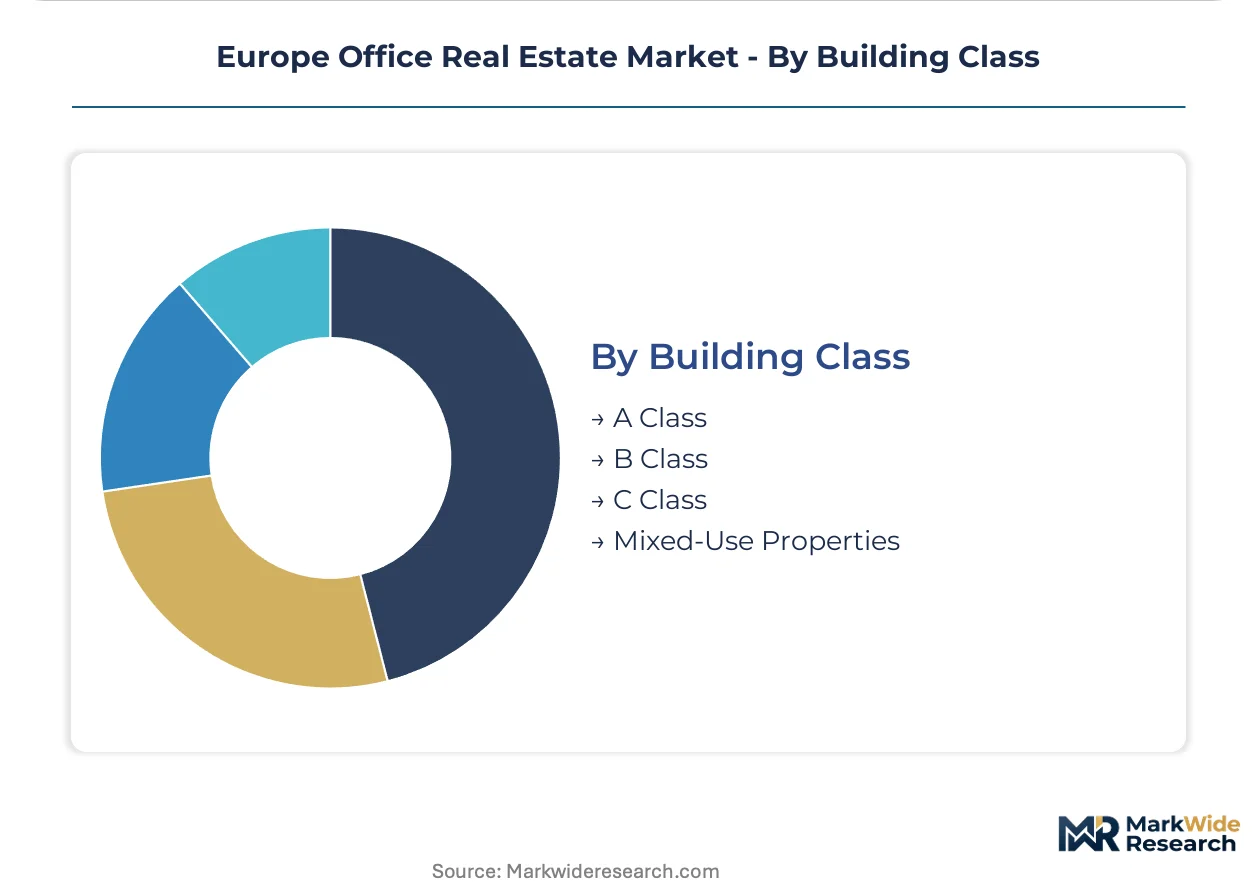
A Class buildings dominate institutional allocation, with mixed-use properties showing the steepest expansion trajectory as investors seek income diversification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting capital flows toward jurisdictions where EU Green Deal compliance costs remain manageable relative to attainable rental premiums. National building performance standards create divergent retrofit burdens that reshape cross-border investment allocation across European office corridors.
Germany
Institutional capital concentrates in Frankfurt's Bankenviertel and Berlin's Mitte district where technology sector tenants are scaling hybrid-ready configurations. The national building performance standards under the EU Green Deal mandate progressive energy efficiency thresholds that compress capital deployment timelines for aging assets. Munich's suburban rings are witnessing accelerated conversion of B-grade stock into life sciences facilities under relaxed zoning interpretations.
France
Paris-centric Grade A ownership commands persistent rental premiums where EPC ratings align with 2035 compliance trajectories. The CSRD disclosure framework extends transparency obligations to real estate owners with significant tenant footprints, influencing financing terms for institutional landlords. Île-de-France's La Défense district exemplifies concentrated sovereign wealth and pension capital deployment toward stabilized core assets.
United Kingdom
Financial services employers in London are displacing traditional ten-to-fifteen-year lease structures with flexible expansion-option contracts. The national transposition of EU-derived building performance standards continues to evolve post-Brexit, creating calibration uncertainty for cross-border portfolio managers. The City of London and Canary Wharf submarkets are absorbing technology sector footprint expansion alongside hybrid policy stabilization.
Netherlands
Amsterdam's Zuidas district demonstrates resilience through mixed-use configurations integrating office with residential and hospitality components. Dutch institutional landlords are deploying centralized sustainability data infrastructure across distributed portfolios to meet CSRD compliance requirements. Rotterdam and The Hague corridors are capturing disproportionate flex office leasing velocity as corporates prioritize operational agility.
Poland
Warsaw's emerging tech corridor attracts venture-backed growth companies to co-working and flex arrangements with rapid headcount volatility. The yield spread of 150-200 basis points above Western European peers is improving liquidity for gateway penetration strategies. Kraków and Wrocław submarkets are sustaining absorption through technology sector administrative function relocation.
Europe Office Real Estate Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue value-add repositioning and ESG-aligned retrofit specialization. The market structure consolidates around three dominant archetypes: pan-European investment platforms with cross-border portfolio capabilities, city-centric Grade A owners with concentrated prime stock, and diversified residential-commercial hybrids with scale advantages. Competitive intensity manifests through strategic M&A for platform expansion and disciplined asset recycling toward energy-compliant tiers.
Within the pan-European platform tier, Savills and Jones Lang LaSalle IP, Inc. occupy positions emphasizing cross-border transaction execution and advisory services. Gecina exemplifies the city-centric archetype through its Paris-focused institutional ownership model. Aroundtown SA anchors the value-add repositioning segment across German and Dutch gateway cities with disciplined capital deployment toward energy retrofit opportunities.
| Leading Market Players |
|---|
| Savills |
| Aroundtown SA |
| Jones Lang LaSalle IP, Inc. |
| Unibail-Rodamco-Westfield |
| Gecina |
| CBRE |
| Colliers |
| Vonovia SE |
| Cushman & Wakefield |
| Others |
Supply & Pricing Matrix
Captive development pipelines across German and Dutch gateway cities anchor supply positioning for institutional landlords while compressing pricing power for speculative developers facing EU Green Deal compliance cost uncertainty. Horizontal consolidation among pan-European asset managers reinforces tenant improvement cost recovery through scale economies in retrofit procurement.
Pricing Analysis
Direct-to-tenant lease negotiations dominate pricing formation across prime office stock in Frankfurt and Paris, with landlord margins reflecting energy performance certificate tier rather than location premium alone. Price differentiation separates A Class assets with CSRD-aligned disclosure infrastructure from B Class stock facing accelerated obsolescence. Pricing pressure stems from construction input cost volatility in steel and aluminum markets. Corporate occupiers with net-zero commitments demonstrate lowest price sensitivity, while startup tenants in flex arrangements absorb highest per-square-meter rates.
Supply Chain Analysis
Electrified heating and cooling equipment supply rests on German, Dutch, and Belgian manufacturing clusters with concentrated HVAC system production. Raw material dependencies span steel structural components, aluminum facade systems, and copper electrical infrastructure. Single-source vulnerability in smart building platform software creates procurement risk for landlords specifying IoT-integrated systems. Distribution runs through national contractor networks with specialized green certification expertise.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Office Real Estate Market functions as a stable compounder anchored by regulatory-driven retrofit demand that sustains capital deployment velocity regardless of cyclical interest rate fluctuations.
For Market Incumbents: Hedge against B Class obsolescence through accelerated repositioning into life sciences use under relaxed zoning interpretations in suburban Paris and Munich rings. Prioritize vertical integration into sustainability data infrastructure to capture CSRD compliance service revenue streams from tenant portfolios.
For New Entrants and Emerging Players: Launch via yield-focused gateway penetration into Warsaw and Bucharest submarkets where 150-200 basis point spreads above Western European peers attract improving liquidity. Target co-working and flex arrangements for venture-backed technology employers with rapid headcount volatility.
For Investors and Strategic Acquirers: Roll-up economics work for mid-size value-add sponsors because fragmented B Class ownership across secondary Dutch and German cities creates scale advantages in green bond stacking expertise. Monitor grid interconnection delay timelines as inflection indicator for project delivery risk.
| Strategic Initiative | Industry Significance |
|---|---|
| Energy Retrofit Acceleration | Front-loads capital expenditure to capture EU Green Deal premium rental tiers before compliance deadlines tighten. |
| CSRD Data Infrastructure Deployment | Creates recurring service revenue from tenants requiring granular carbon disclosure for regulatory filing obligations. |
| Life Sciences Conversion Pipeline | Repurposes obsolete B-grade suburban stock into laboratory facilities under relaxed zoning in Paris and Munich rings. |
| Flex Lease Structure Expansion | Captures technology sector demand for operational agility through unbundled commitment arrangements with expansion options. |
| Poland Gateway Market Entry | Accesses yield spreads above Western European peers with improving liquidity in Warsaw's emerging tech corridor. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with institutional asset managers, tenant procurement leads, retrofit contractors, and green bond structuring specialists alongside secondary validation through ECB interest rate filings, EU building performance standard transpositions, and national energy agency retrofit subsidy databases. Bottom-up lease transaction analysis and top-down institutional capital flow tracking were triangulated against cross-border investment platform disclosures.
Historical reference periods spanning pre-pandemic absorption patterns through post-rate-hike stabilization anchored the projection framework across the analysis window. Segmentation dimensions modeled include property type, lease structure, end user category, building class tier, and regulatory compliance trajectory. CAGRs were derived from fitted trend extrapolation with scenario-weighted adjustments for technology sector footprint expansion and remote work permanence effects on per-employee space requirements.
Several conditions sit outside the modeled scope, including geopolitical disruption to construction material supply chains and accelerated regulatory timeline revisions beyond current EU Green Deal transpositions. Forecasts reflect underlying assumptions about interest rate stabilization and tenant improvement cost recovery horizons. A small set of named triggers warrants ongoing watch: grid interconnection delays, green bond liquidity contractions, and technology sector footprint reduction announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Office Real Estate
Asean Office Real Estate Market
Office Real Estate
China Flexible Office Space Market
Office Real Estate
United States Office Real Estate Market
Office Real Estate
Saudi Arabia Real Estate Brokerage Market
Office Real Estate
Spain Office Real Estate Market
Office Real Estate
France Office Real Estate Market
Office Real Estate
Asia Pacific Flexible Office Market
Office Real Estate
United States Co-Working Office Space Market
Office Real Estate
Saudi Arabia Co-Working Office Spaces Market
Office Real Estate
UAE Flexible Office Space Market
Office Real Estate
Bahrain Co-Working Office Space Market
Office Real Estate
Qatar Co-Working Office Spaces Market
Office Real Estate
Bahrain Flexible Office Space Market
Office Real Estate
India Co-Working Office Spaces Market
Office Real Estate
Canada Flexible Office Space Market
Office Real Estate
Italy Office Real Estate Market