
 Saudi Arabia Flexible Office Space Market | 2026-2036
Saudi Arabia Flexible Office Space Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Flexible Office Space Market Analytics
Commercial real estate brokerage in Saudi Arabia is fragmenting as landlords bypass traditional intermediaries to strike direct operator partnerships. WeWork anchors its position through premium locations in Riyadh and Jeddah, leveraging government relationship networks. Regus competes on standardized service consistency across multiple Saudi cities. AstroLabs specializes in venture-backed startup communities, differentiating through curated programming rather than raw square footage.
Flexible office space denotes commercially leased work environments offering short-term contracts, shared amenities, and scalable square footage without capital-intensive fit-out obligations. Operators typically provide high-speed connectivity, meeting infrastructure, and reception services under unified management. Coworking space leads volume expansion as hybrid employment models normalize across Saudi enterprises. Serviced office retains margin concentration among established corporates seeking turnkey relocation. Virtual office segments attract capital-light freelancers and regional headquarters registrations, though facility utilization rates trail physical alternatives.
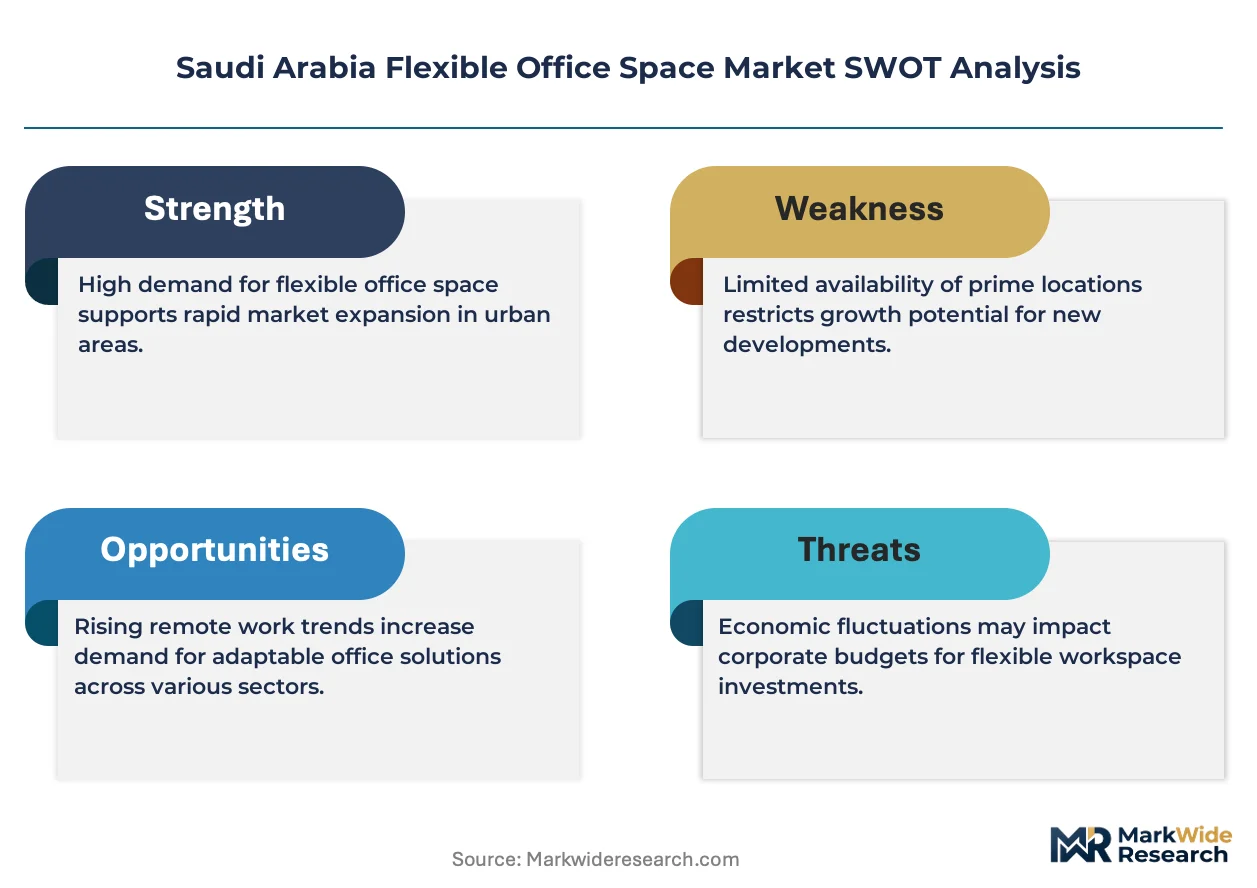
SFDA commercial licensing frameworks govern operator health and safety compliance, while municipal authorities in Riyadh and Jeddah enforce building code adaptations for multi-tenant configurations. Saudi Vision 2030's Quality of Life Program directly incentivizes flexible workspace development through zoning relaxations and foreign investment facilitation. Stakeholders must monitor regulatory harmonization between municipal planning departments and the Ministry of Municipal and Rural Affairs as secondary cities open to operator entry.
Market Dynamics
Saudi Vision 2030's entrepreneurship mandates are compressing traditional commercial lease structures as technology startups demand month-to-month scalability without capital-intensive fit-out obligations.
Growth Catalysts
- SFDA Commercial Licensing Reforms:Streamlined operator entry protocols reduce bureaucratic friction for flexible workspace providers establishing multi-tenant configurations in Riyadh and Jeddah.
- King Abdullah Financial District Concentration:Riyadh's premier business cluster generates concentrated demand from fintech and professional services firms seeking premium flexible office infrastructure.
- Hybrid Employment Normalization:Saudi enterprises across banking and technology verticals are downsizing fixed headquarters footprints in favor of distributed workspace networks.
Market Restraints
- Prime Real Estate Cost Concentration:Grade-A commercial rents in Riyadh's financial district and Jeddah's innovation corridors compress operator margins below serviced office benchmarks.
- Municipal Zoning Fragmentation:Building code adaptations for multi-tenant configurations vary between Riyadh Municipality and Jeddah Municipality, creating compliance duplication costs.
- Traditional Lease Substitution:Long-term corporate tenants in Saudi Aramco and SABIC supply chains retain preference for conventional build-to-suit arrangements with customization control.
Strategic Opportunities
- Secondary City Expansion:Dammam and Khobar in the Eastern Province present underpenetrated demand from logistics and petrochemical services firms requiring satellite offices.
- Quality of Life Program Incentives:Zoning relaxations and foreign investment facilitation under Saudi Vision 2030 reduce capital requirements for new operator market entry.
- Venture-Backed Startup Communities:Curated programming models combining workspace with mentorship and investor access attract capital-light entrepreneurs outside traditional coworking demographics.
Industry Challenges
- Multi-Tenant Building Code Compliance:Operators must navigate simultaneous SFDA health and safety requirements and municipal fire safety adaptations for shared amenity spaces.
- Technical Infrastructure Standardization:Enterprise clients demand ISO 27001-certified data infrastructure that smaller operators struggle to provision across distributed locations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Flexible Office Space Market |
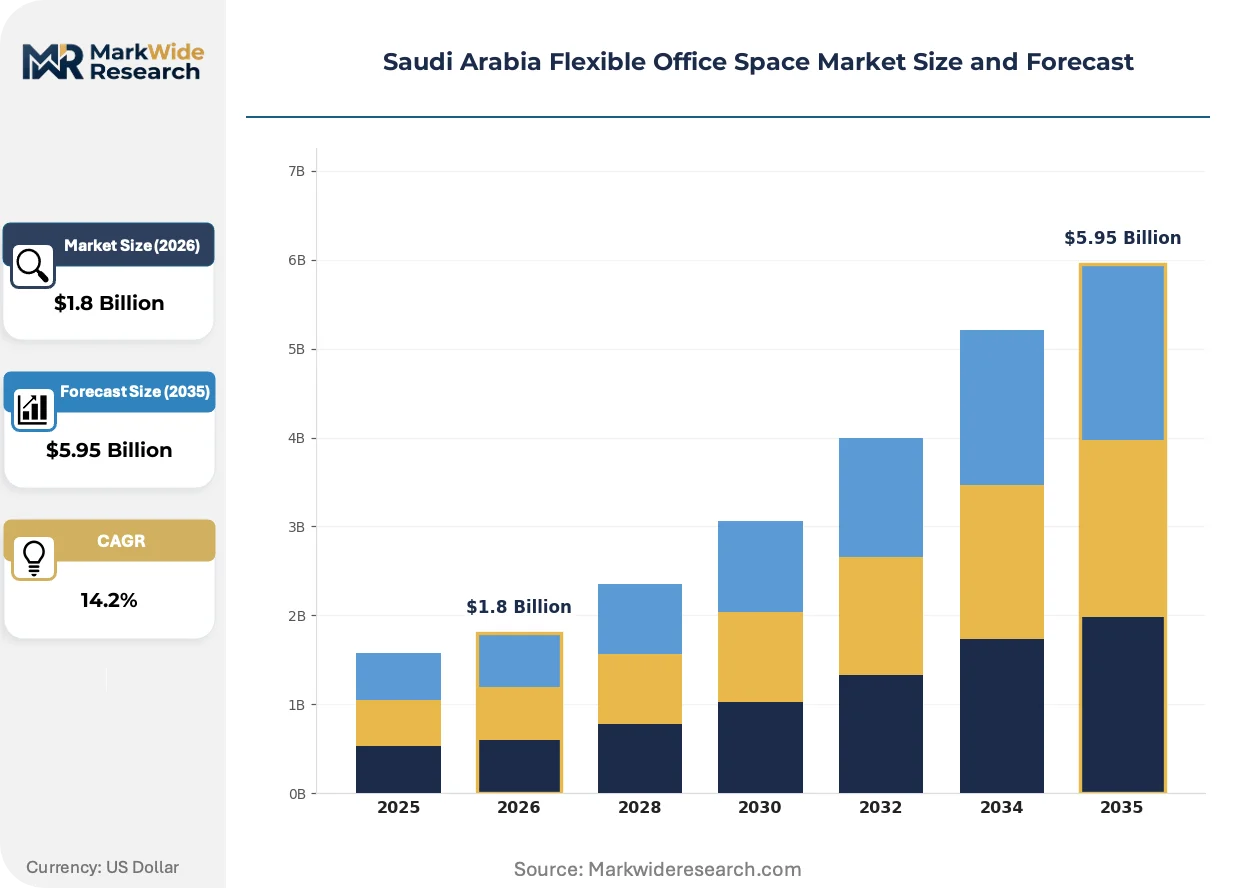
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.95 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Office Type: Serviced Office, Coworking Space, Virtual Office, Meeting Room Client Type: Startups, Freelancers, Corporates, SMEs Service Model: Pay-As-You-Go, Membership Plan, Dedicated Desk, Private Office Facility Size: Small, Medium, Large, Enterprise |
| Companies Covered | Spaces, The Hive, WeWork, White Space, AstroLabs, Regus, CBRE, Gravita, Servcorp, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Flexible Office Space Market Evolving Landscape
Workspace technology stacks and service delivery models are fragmenting as Saudi operators compete on digital infrastructure rather than square footage alone.
Smart building management platforms are migrating from proprietary on-premise installations to API-integrated cloud architectures. Mid-market operators in Riyadh are adopting these systems at accelerating pace to match WeWork's connectivity benchmarks. This migration is compressing the technology gap between premium and standard-tier providers.
Saudi Vision 2030's Quality of Life Program introduces zoning relaxations specifically targeting flexible workspace development in designated innovation zones. The policy enables mixed-use configurations previously restricted under commercial-only classifications. Secondary cities including Taif and Tabuk are responding with expedited permitting for foreign-operated workspace ventures.
Enterprise procurement departments are consolidating vendor relationships through master service agreements covering multiple Saudi cities rather than location-by-location contracting. Facility management teams at Saudi National Bank and stc Group are leading this consolidation, demanding unified service level agreements across Riyadh, Jeddah, and Dammam locations. This pattern is most visible in financial services and telecommunications verticals with distributed workforce models.
Saudi Arabia Flexible Office Space Market Segmentation
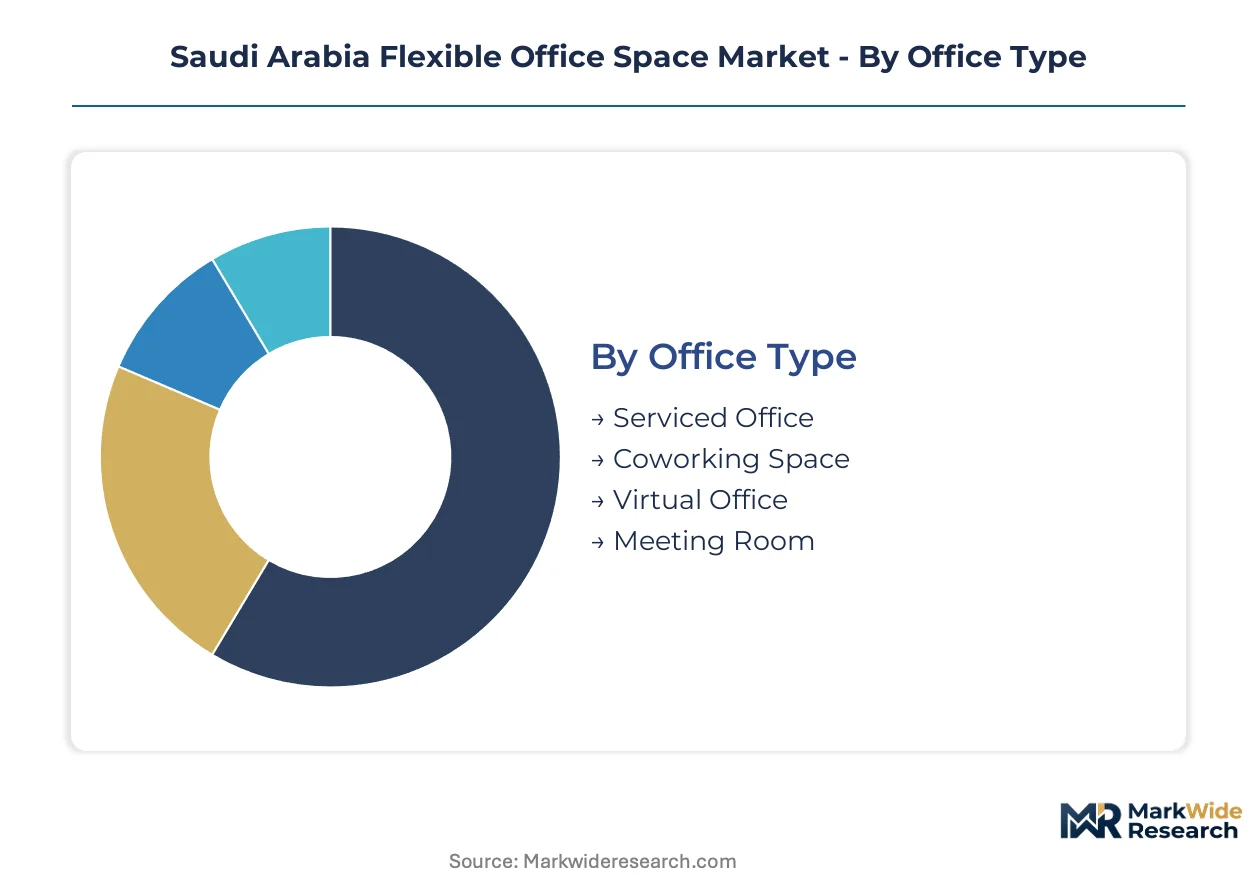
Flexible office space operators in Saudi Arabia configure service architectures around contract duration, client scale, and physical infrastructure requirements. Segmentation reveals how SFDA licensing reforms and municipal zoning variations create distinct compliance burdens across facility types and client categories.
Office Type:
Demand patterns across office configurations reflect the use-case spectrum from capital-light virtual presence to premium physical infrastructure.
- Serviced Office:Turnkey private suites with reception, IT infrastructure, and administrative support bundled under unified management. Established corporates in Riyadh's King Abdullah Financial District favor this format for satellite headquarters requiring immediate operational readiness without fit-out delays.
- Coworking Space:Open-plan environments with hot-desking, shared amenities, and community programming under short-term memberships. Technology startups under Saudi Vision 2030 entrepreneurship mandates are expanding their footprint fastest here, compressing traditional lease structures in Jeddah's innovation corridors.
- Virtual Office:Address registration and mail handling without physical workspace access. Regional headquarters registrations and capital-light freelancers drive demand, though facility utilization rates trail physical alternatives.
- Meeting Room:Bookable conference infrastructure for hourly or daily use. Professional services firms and project teams access premium presentation technology without committing to recurring space obligations.
The dominant share belongs to Serviced Office, while Coworking Space is closing the gap fastest.
Client Type:
Cost tier differentiation separates venture-backed growth companies from established institutional accounts with diverging risk tolerances.
- Startups:Venture-backed and bootstrapped companies requiring month-to-month scalability. AstroLabs and similar operators curate programming combining workspace with mentorship and investor access, attracting capital-light entrepreneurs outside traditional coworking demographics.
- Corporates:Saudi National Bank, stc Group, and similar institutions consolidating vendor relationships through master service agreements. These clients demand unified service level agreements across Riyadh, Jeddah, and Dammam locations with ISO 27001-certified data infrastructure.
- Freelancers:Independent professionals seeking address credibility and occasional physical presence without lease commitments. Virtual office segments serve this demographic with minimal facility utilization.
- SMEs:Mid-sized enterprises navigating between coworking flexibility and serviced office professionalism. Hybrid employment normalization across banking and technology verticals is expanding this segment's addressable market.
Corporates command premium pricing power, though Startups are expanding most quickly under Quality of Life Program incentives.
Service Model:
Application-specific procurement patterns range from episodic usage to committed occupancy with customization rights.
- Membership Plan:Recurring monthly subscriptions with guaranteed access tiers and bundled amenity credits. Enterprise procurement departments favor this predictability for budget planning across distributed workforce networks.
- Private Office:Enclosed suites with dedicated infrastructure and branding rights. Established corporates seeking turnkey relocation without capital-intensive fit-out obligations concentrate demand here.
- Pay-As-You-Go:Episodic booking without recurring commitments. Project-based teams and visiting executives access premium locations in Riyadh and Jeddah without long-term obligations.
- Dedicated Desk:Reserved workstation in shared environments with storage and personalization allowances. Individual professionals requiring consistency without private office overhead select this intermediate tier.
Membership Plan holds the installed base, while Private Office is gaining share fastest among financial services verticals.
Facility Size:
Volume concentration and margin structure vary dramatically across scale categories, with enterprise deployments requiring fundamentally different capital and operational architectures.
- Large:Multi-floor configurations with dedicated building management and customized infrastructure. WeWork anchors its position through premium locations of this scale in Riyadh and Jeddah.
- Enterprise:Campus-style developments or full-building leases with operator-branded identity. SFDA commercial licensing reforms streamline entry for operators establishing these flagship configurations in designated innovation zones.
- Medium:Single-floor or partial-floor operations in Grade-A commercial towers. Mid-market operators adopt smart building management platforms at accelerating pace to match premium connectivity benchmarks.
- Small:Boutique locations with limited desk counts and community-focused programming. Secondary cities including Taif and Tabuk are responding with expedited permitting for foreign-operated ventures at this scale.
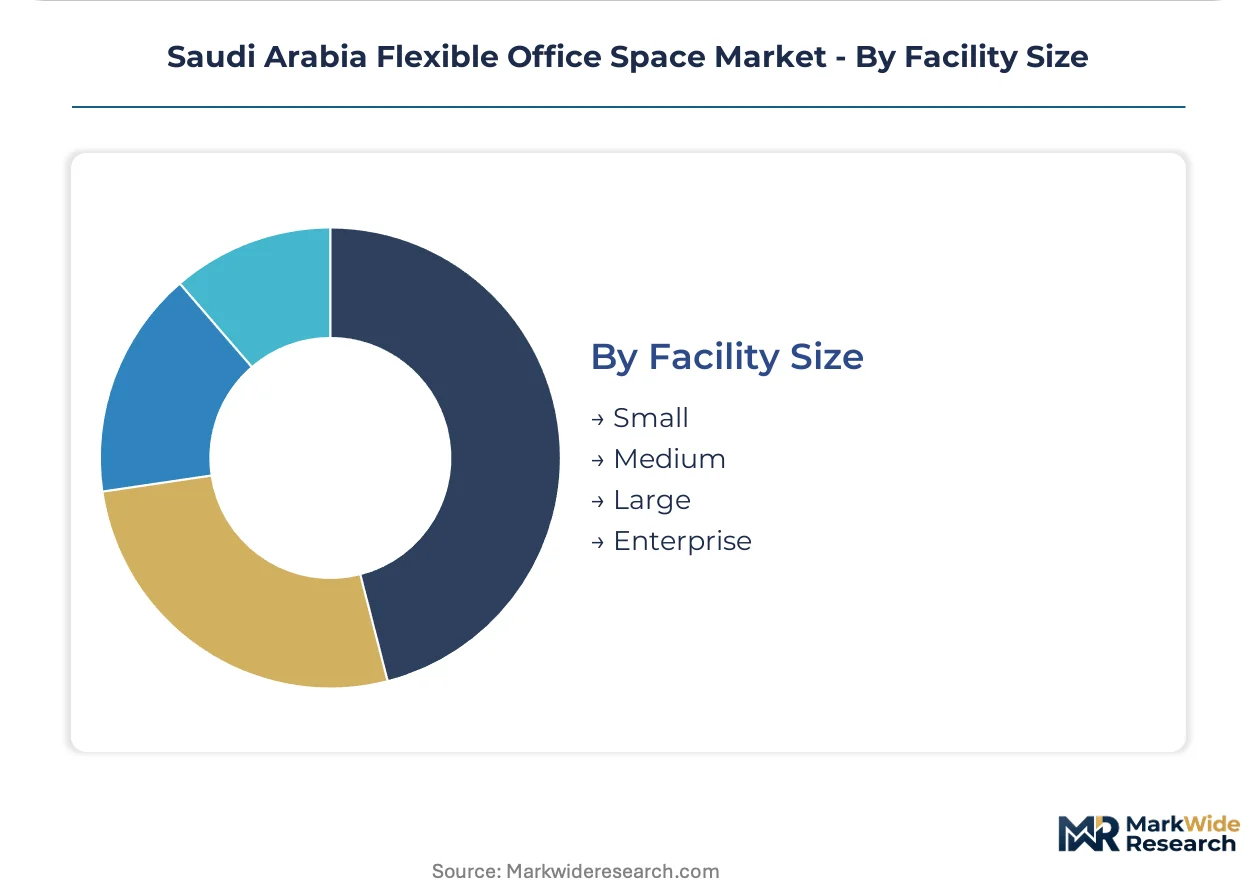
Large facilities generate the revenue concentration, though Enterprise is climbing the fastest under municipal zoning relaxations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Riyadh commands premium lease rates that exceed Jeddah benchmarks by double-digit margins, concentrating operator investment in the capital's financial district while secondary cities absorb mid-market expansion strategies.
Riyadh
Technology startups under Saudi Vision 2030 entrepreneurship mandates drive demand compression in King Abdullah Financial District. SFDA commercial licensing reforms streamline multi-tenant operator entry for fintech and professional services satellite offices. Grade-A commercial towers in the financial district generate concentrated serviced office deployments.
Eastern Province
Logistics and petrochemical services firms in Dammam and Khobar require flexible satellite offices for supply chain coordination. Municipal authorities in the Eastern Province enforce building code adaptations for shared amenity spaces under Ministry of Municipal and Rural Affairs guidance. Industrial services corridors near King Fahd Industrial Port anchor mid-market coworking expansion.
Jeddah
Hybrid employment normalization across banking and telecommunications verticals accelerates workspace network downsizing in Jeddah's innovation corridors. Quality of Life Program zoning relaxations enable mixed-use configurations previously restricted under commercial-only classifications. Red Sea coastal development zones attract foreign-operated workspace ventures with expedited permitting.
NEOM Northwest
Future city construction phases generate temporary project office demand for engineering and consulting consortiums. Saudi Vision 2030 foreign investment facilitation reduces capital requirements for operators establishing boutique configurations in designated innovation zones. The linear city development corridor presents long-term enterprise facility deployment opportunities.
Taif and Tabuk
Secondary city municipal authorities respond to Quality of Life Program incentives with accelerated permitting for small-scale foreign-operated ventures. Regional headquarters registrations and capital-light freelancers drive virtual office segment growth outside major metros. Boutique community-focused programming models penetrate these underpenetrated demand pools.
Saudi Arabia Flexible Office Space Market Competitive Landscape
Premium-network operators and standardized-service providers split the market between relationship-driven government contracting and consistency-focused multi-city coverage. Market structure tilts toward consolidation as landlords bypass traditional commercial real estate brokerage to strike direct operator partnerships. Three archetypes dominate: global workspace networks with government relationship infrastructure, regional specialists in venture-backed startup communities, and diversified real estate service firms extending into flexible space management. Competitive moves concentrate on premium location anchoring and smart building technology licensing.
Within the global-network tier, WeWork and Regus occupy positions that exemplify contrasting scale strategies. AstroLabs represents the venture-community specialist archetype through curated programming rather than raw square footage competition. These three operators anchor the competitive landscape as landlords increasingly prefer direct partnership structures over traditional intermediary arrangements.
| Leading Market Players |
|---|
| Spaces |
| The Hive |
| WeWork |
| White Space |
| AstroLabs |
| Regus |
| CBRE |
| Gravita |
| Servcorp |
| Others |
Value Network & Pricing Analysis
Overcapacity in Jeddah's innovation corridors is compressing operator margins and forcing landlords toward direct partnership structures that bypass traditional brokerage fees. This utilization squeeze simultaneously pressures pricing postures across Riyadh's premium tier and accelerates supply chain consolidation among facility management vendors.
Pricing Analysis
The customization-premium spread between configured private offices and standard hot-desking memberships spans approximately three-to-one in Riyadh's King Abdullah Financial District. Pricing stratifies across premium, standard, and economy tiers, with ISO 27001 certification and smart building platform integration driving differentiation at the top. Cost compression in the mid-market tier is intensifying because municipal zoning fragmentation duplicates compliance spend across multi-tenant configurations. Enterprise procurement departments at Saudi National Bank and stc Group exhibit lowest price sensitivity, while bootstrapped startups in AstroLabs communities represent the most elastic demand segment.
Supply Chain Analysis
Upstream feedstock for flexible workspace development centers on Grade-A commercial tower availability concentrated in Saudi Arabia's three major metros, with secondary sourcing from UAE-based fit-out contractors and European smart building technology providers. Critical inputs include fiber-optic infrastructure, HVAC systems adapted for multi-tenant occupancy, and cloud-managed access control hardware. Single-source vulnerability runs through the limited pool of SFDA-licensed facility management operators capable of navigating simultaneous health and safety and municipal fire code requirements. Distribution runs through landlord-direct partnerships that disintermediate traditional commercial real estate brokerage.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue streams including IT infrastructure management and curated programming layers are expanding faster than raw square footage leases, transforming operator economics from transactional occupancy toward recurring relationship value.
For Market Incumbents: Entrench market position through exclusive master service agreements with distributed enterprises requiring unified SLAs across Riyadh, Jeddah, and Dammam. Deepen backward integration into smart building platform development to reduce licensing costs to WeWork-level connectivity benchmarks. Counter the threat of municipal zoning fragmentation by pre-certifying multi-tenant configurations with SFDA and Ministry of Municipal and Rural Affairs in parallel.
For New Entrants and Emerging Players: Taif and Tabuk's underpenetrated demand pools offer white-space entry with expedited permitting under Quality of Life Program incentives. Target venture-backed startup communities seeking mentorship programming rather than commodity square footage. Penetrate through boutique community-focused models at small facility scale before expanding to medium configurations.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among operators with enterprise master service agreements and ISO 27001-certified infrastructure portfolios. Long-term viability over the next decade hinges on technology platform ownership rather than lease arbitrage. Monitor SFDA licensing reform velocity as the inflection signal for secondary city expansion feasibility.
| Strategic Initiative | Industry Significance |
|---|---|
| Smart Building Platform Integration | API-integrated cloud architectures compress the technology gap between premium and standard-tier providers. |
| Secondary City Geographic Expansion | Taif and Tabuk municipal authorities offer expedited permitting for foreign-operated ventures under Quality of Life Program zoning relaxations. |
| Enterprise Master Service Agreement Consolidation | Saudi National Bank and stc Group procurement departments demand unified SLAs across distributed workforce networks. |
| SFDA Pre-Certification Investment | Simultaneous health and safety and municipal fire code clearance reduces compliance duplication costs for multi-tenant configurations. |
| Venture-Community Programming Development | AstroLabs-style curated mentorship and investor access attracts capital-light entrepreneurs outside traditional coworking demographics. |
Research Methodology
Cross-validation between primary interviews with flexible workspace operators, facility management vendors, and enterprise real estate procurement directors and secondary sources including SFDA commercial licensing frameworks, municipal zoning filings from Riyadh and Jeddah municipalities, and Saudi Vision 2030 policy documentation anchors the qualitative findings. Bottom-up triangulation from individual facility economics and top-down validation against sector-level investment flows ensure consistency.
Calibration against historical absorption rates in King Abdullah Financial District and Jeddah innovation corridors informs the analytical framework across the analysis window. Segmentation dimensions modeled include office type, client scale, service model commitment structure, and facility size tier. CAGRs derive from fitted trend extrapolation adjusted for regulatory reform velocity and foreign investment facilitation policy implementation.
The forecast holds incumbent behavior within observed patterns; aggressive moves by global workspace networks with government relationship infrastructure would shift outcomes. Cross-checking against Ministry of Municipal and Rural Affairs permitting velocity data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Office Real Estate
UAE Flexible Office Space Market
Office Real Estate
Asia Pacific Flexible Office Market
Office Real Estate
Canada Office Real Estate Market
Office Real Estate
United Kingdom Office Real Estate Market
Office Real Estate
Saudi Arabia Real Estate Brokerage Market
Office Real Estate
Asean Office Real Estate Market
Office Real Estate
India Flexible Office Space Market
Office Real Estate
Japan Office Real Estate Market
Office Real Estate
United Kingdom Flexible Office Space Market
Office Real Estate
Saudi Arabia Office Real Estate Market
Office Real Estate
United States Co-Working Office Space Market
Office Real Estate
Europe Flexible Office Market
Office Real Estate
India Co-Working Office Spaces Market
Office Real Estate
Bahrain Co-Working Office Space Market
Office Real Estate
Office Real Estate Market
Office Real Estate
France Office Real Estate Market