
 United States Automated Material Handling Market | 2026-2036
United States Automated Material Handling Market Size, Share, and Industry Trends Forecast 2026-2036
United States Automated Material Handling Market Analytics
Third-party logistics channel control is reshaping how automated material handling systems reach end users in the United States. Dematic leverages extensive integration capabilities to anchor large-scale distribution center deployments. Honeywell Intelligrated competes through sustained software-hardware convergence in conveyor and sortation platforms. Bastian Solutions Inc. specializes in modular robotic systems for e-commerce fulfillment, differentiating its offerings against standardized competitors.
Automated material handling encompasses conveyor networks, robotic palletizers, automated guided vehicles, and AI-driven sortation systems designed to transport, store, and retrieve goods with minimal human intervention. These systems integrate sensors, control software, and mechanical actuators to achieve throughput rates exceeding manual operations by orders of magnitude in high-volume facilities. Conveyor Systems and Sortation Systems command established installed bases across warehousing and manufacturing, while Robotic Palletizers capture expanding margin pools as labor costs rise in Food & Beverage processing. RFID Technology and IoT Solutions within the technology dimension are gaining traction fastest, enabling real-time inventory visibility that underpins modern order fulfillment architectures.
OSHA enforces powered industrial truck safety standards that directly shape AGV design requirements and operator training protocols. The FAA regulates emerging autonomous aerial delivery systems that will eventually interface with ground-based material handling infrastructure. NHTSA commercial vehicle automation guidelines further influence how intra-facility transport connects with last-mile distribution. Stakeholders must monitor regulatory convergence between workplace safety, aviation, and surface transportation agencies as automation layers compound across the supply chain.
Market Dynamics
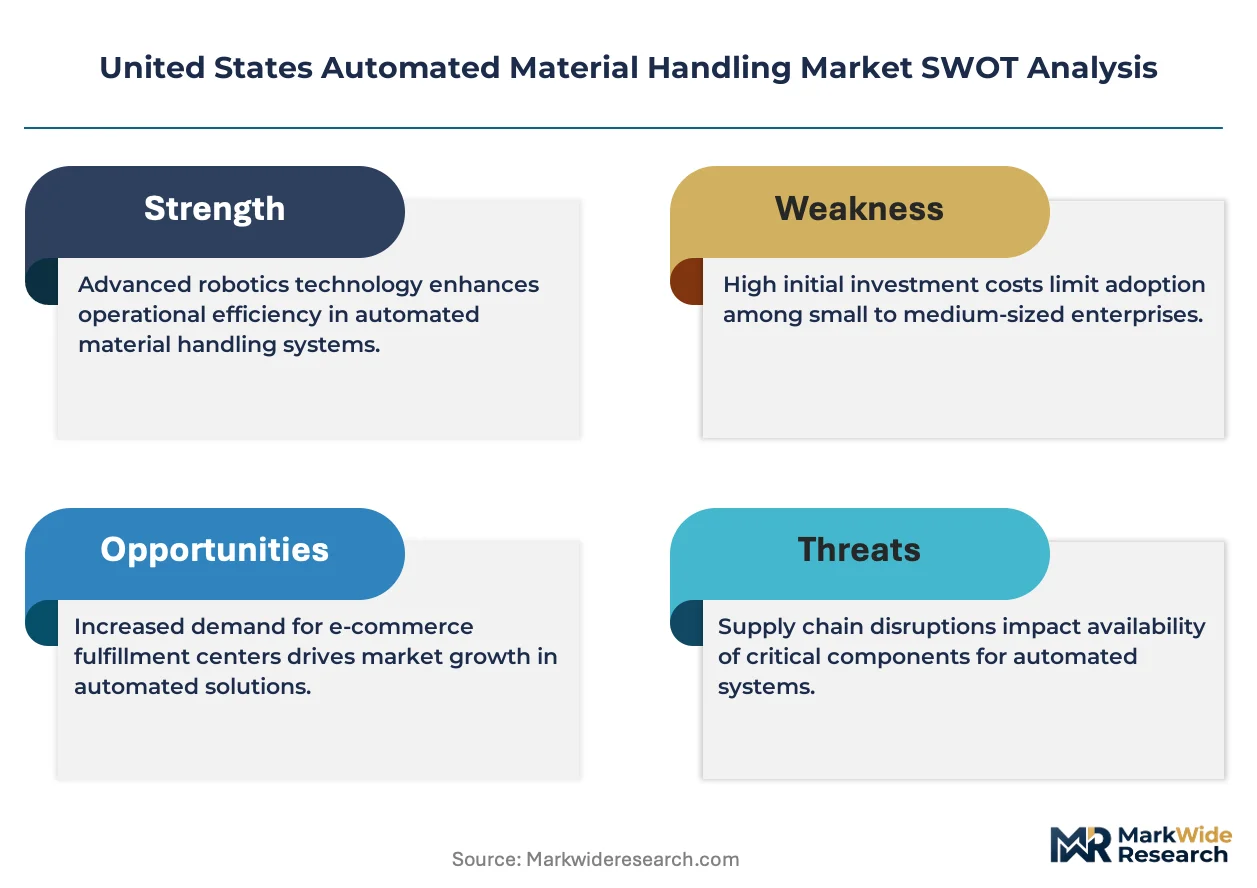
OSHA's powered industrial truck safety standards are compressing deployment timelines for automated guided vehicles while forcing retrofits across California's warehouse clusters. E-commerce fulfillment velocity demands are simultaneously pulling capital toward robotic sortation and away from conventional conveyor networks.
Growth Catalysts
- OSHA Workplace Safety Mandates:Stricter powered industrial truck standards are accelerating forklift replacement with sensor-equipped AGVs in high-throughput distribution centers. Compliance deadlines are compressing procurement cycles.
- E-Commerce Fulfillment Density:California's Inland Empire logistics corridor is driving concentrated demand for robotic palletizers and AI-driven sortation systems. Facility throughput requirements now exceed manual labor capacity.
- FAA Drone Delivery Framework:Expanding regulatory pathways for autonomous aerial systems are creating interface requirements between ground-based material handling and last-mile air infrastructure.
Market Restraints
- Steel and Semiconductor Input Volatility:Conveyor network fabrication depends on steel pricing swings, while AGV production faces chip allocation constraints from automotive sector competition.
- Integration Technical Limitation:Legacy warehouse management systems lack API standardization, forcing costly middleware development for robotic system connectivity.
- California Regulatory Friction:State-level emissions standards for material handling equipment add certification layers beyond federal OSHA requirements, extending deployment timelines.
Strategic Opportunities
- Texas Gulf Coast Logistics Expansion:Underpenetrated warehouse development around Houston and Dallas-Fort Worth offers greenfield deployment of fully automated systems without legacy retrofit burden.
- RFID-IoT Technology Convergence:Real-time inventory visibility platforms are creating new service revenue streams through predictive maintenance and throughput optimization subscriptions.
- Inflation Reduction Act Clean Energy Incentives:Federal tax credits for electrified industrial equipment are improving ROI calculations for battery-powered AGV fleets versus propane alternatives.
Industry Challenges
- Controls Engineering Talent Gap:Shortage of PLC programmers and robotic integration specialists is extending commissioning timelines for multi-vendor system deployments.
- Interoperability Certification Complexity:Lack of unified ANSI standards for AGV-to-WMS communication forces case-by-case validation testing, inflating project risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Automated Material Handling Market |
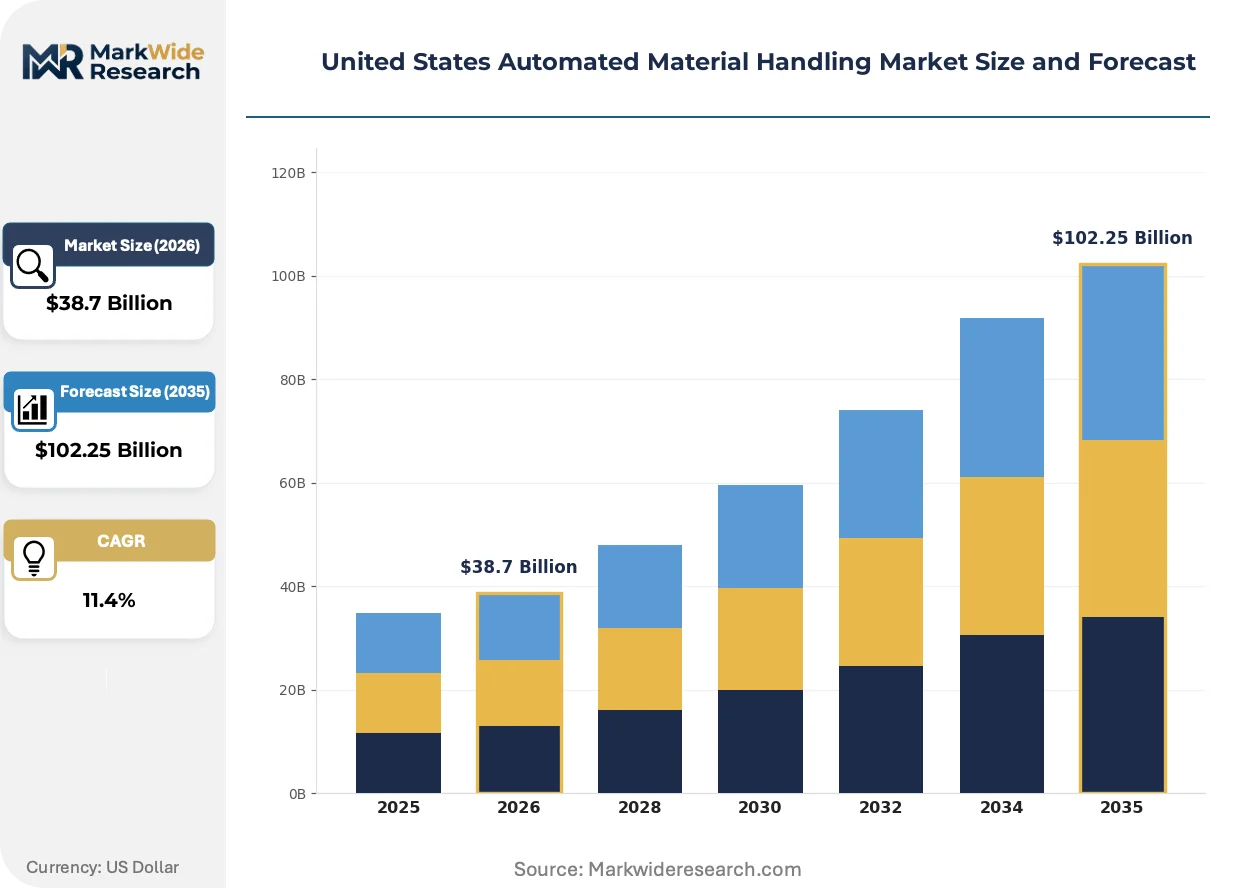
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $102.25 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
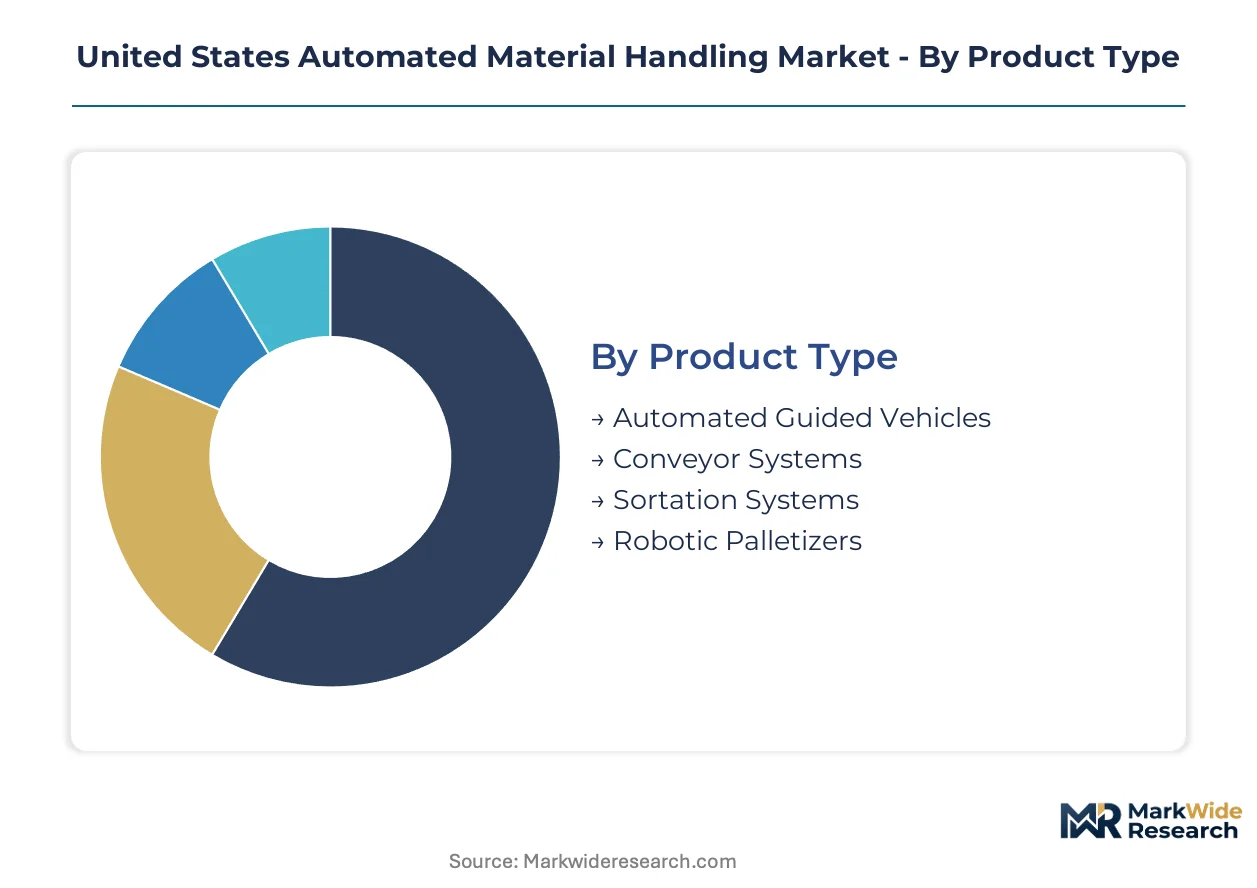
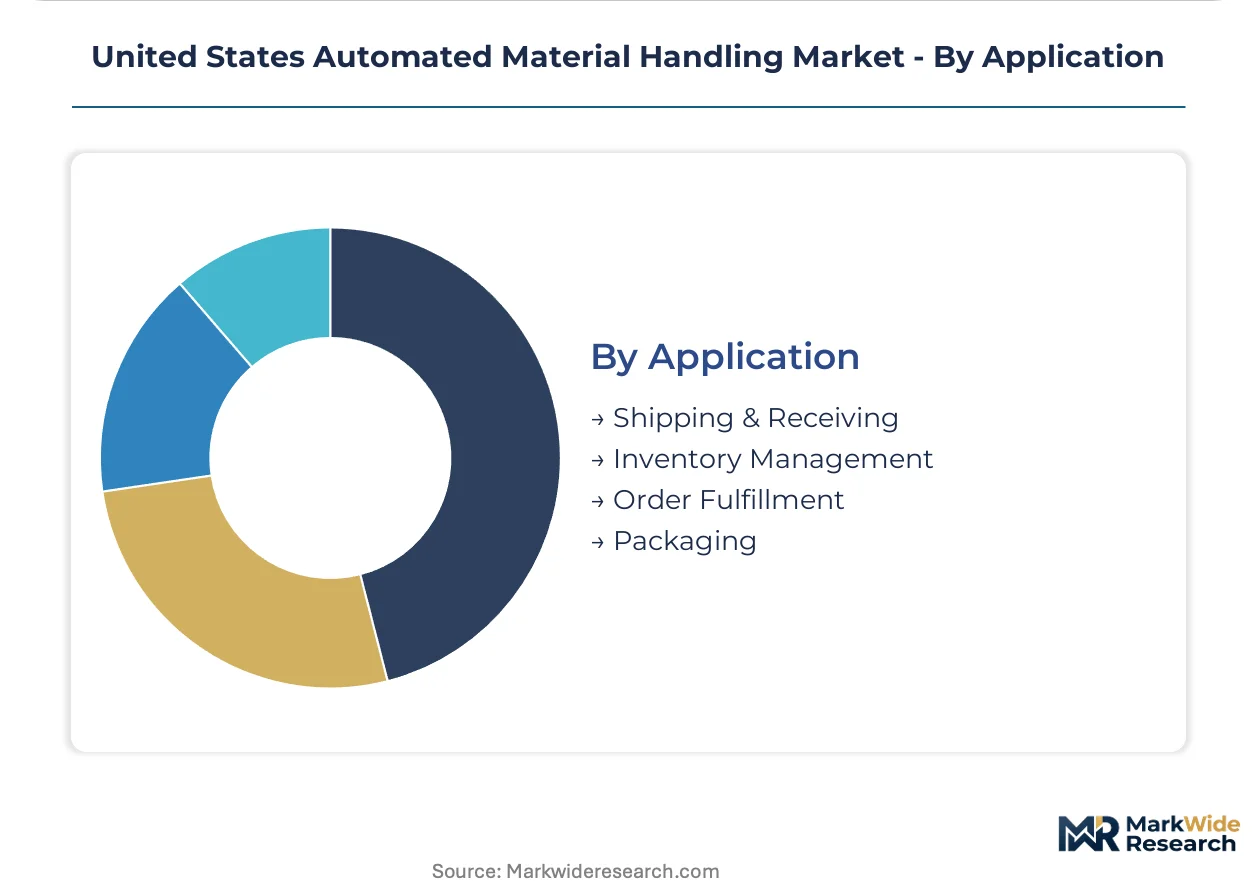
| Segmentation | Product Type: Automated Guided Vehicles, Conveyor Systems, Sortation Systems, Robotic Palletizers End User: Manufacturing, Warehousing, E-Commerce, Food & Beverage Technology: AI & Machine Learning, IoT Solutions, Robotic Automation, RFID Technology Application: Shipping & Receiving, Inventory Management, Order Fulfillment, Packaging |
| Companies Covered | Bastian Solutions Inc., DMW&H, Westfalia Technologies Inc., Dorner Manufacturing Corporation, Honeywell Intelligrated, Dematic, Daifuku Co. Ltd, SSI Schaefer, Kion Group AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Automated Material Handling Market Evolving Landscape
Digital twin platforms are virtualizing physical warehouse operations before capital deployment, compressing design risk and accelerating commissioning timelines. Three converging forces are restructuring how automated material handling systems are specified, financed, and operated.
Digital twin software is virtualizing facility layout and throughput simulation for greenfield distribution centers. Third-party logistics operators in California and Texas are adopting these platforms to validate robotic sortation configurations prior to concrete pouring. This capability is virtualizing traditional design-build risk allocation between integrators and end users.
OSHA's pending update to 29 CFR 1910.178 standards is mandating enhanced pedestrian detection systems on all new AGV deployments. Food and beverage processing facilities face the steepest compliance curves due to 24-hour operational requirements and high worker density. The regulation is forcing early retirement of first-generation laser-guided vehicles lacking camera-based safety overlays.
Third-party logistics providers are unbundling equipment ownership from operational responsibility, shifting toward robotics-as-a-service contracts with throughput-based pricing. This model is displacing traditional capex-heavy procurement in mid-market e-commerce fulfillment. The shift is most visible among California-based 3PLs serving direct-to-consumer brands with seasonal demand volatility.
United States Automated Material Handling Market Segmentation
Automated material handling systems serve distinct operational requirements across facility types, with technology choices and application priorities varying sharply between manufacturing plants and e-commerce fulfillment centers. Segmentation reveals where capital concentrates and which integration challenges dominate procurement decisions.
Product Type:
Facility operators select equipment based on throughput velocity, SKU diversity, and labor substitution economics across California's warehouse clusters and Midwest manufacturing belts.
- Conveyor Systems:Belt and roller configurations transport unit loads through fixed-path routing at sustained speeds exceeding manual cart movement. California's Inland Empire logistics corridor deploys these networks most intensively, driven by e-commerce fulfillment density that demands continuous material flow without bottlenecks.
- Automated Guided Vehicles:Sensor-equipped mobile robots navigate warehouse floors using laser guidance or vision systems to transport pallets and totes autonomously. OSHA's powered industrial truck safety mandates are accelerating forklift replacement with AGVs in high-throughput distribution centers where pedestrian-worker proximity creates compliance pressure.
- Sortation Systems:Divert mechanisms and cross-belt sorters direct packages to outbound shipping lanes based on destination coding.
- Robotic Palletizers:Articulated arm systems stack cases onto unit loads with repeatability exceeding manual labor in Food & Beverage processing environments.
The dominant share belongs to Conveyor Systems, while Automated Guided Vehicles is closing the gap fastest.
End User:
Procurement patterns diverge sharply between asset-heavy manufacturing and inventory-turn-focused fulfillment operations, with regulatory exposure varying by sector.
- Warehousing:Third-party logistics operators and dedicated distribution centers deploy integrated conveyor-AGV-sortation systems to maximize cubic utilization and order cycle speed. Texas Gulf Coast greenfield developments favor fully automated configurations without legacy system retrofit burdens.
- E-Commerce:Direct-to-consumer fulfillment networks require robotic piece-picking and high-speed sortation to handle extreme SKU proliferation and seasonal demand spikes. California-based 3PLs serving consumer brands are shifting toward robotics-as-a-service contracts with throughput-based pricing to manage volatility.
- Manufacturing:Assembly plants and production facilities integrate material handling with just-in-time supply chains.
- Food & Beverage:Processing plants face stringent sanitation requirements and 24-hour operational demands.
Warehousing commands the largest installed base, though E-Commerce is expanding most quickly as fulfillment velocity requirements intensify.
Technology:
Technology selection determines integration complexity and data architecture, with connectivity standards still fragmenting across vendor ecosystems.
- RFID Technology:Radio-frequency identification tags and readers enable real-time inventory tracking without line-of-sight requirements, feeding warehouse management systems with location and condition data. Demand concentrates in high-value apparel and electronics fulfillment where shrinkage control justifies tag costs.
- IoT Solutions:Sensor networks and edge computing platforms monitor equipment health, energy consumption, and throughput metrics across distributed facility footprints. Predictive maintenance subscriptions are emerging as service revenue streams for integrators serving multi-site operators.
- AI & Machine Learning:Algorithmic optimization engines adjust routing and pacing based on order patterns and congestion signals.
- Robotic Automation:Collaborative and industrial robots execute pick, place, and packing operations with adaptive grippers.
RFID Technology holds established penetration in asset tracking, while IoT Solutions is gaining share fastest through predictive maintenance monetization.
Application:
Application priority sequencing reflects where labor substitution delivers immediate ROI versus where integration risk delays deployment.
- Order Fulfillment:Pick, pack, and ship operations combine robotic piece handling with automated packaging to meet same-day delivery commitments. E-commerce velocity demands are pulling capital toward this application fastest, with seasonal peaks exceeding manual labor capacity in California fulfillment clusters.
- Inventory Management:Cycle counting, put-away, and slotting optimization systems maintain accuracy without operational shutdowns. Food & Beverage cold storage facilities prioritize this application for traceability compliance under FDA food safety requirements.
- Shipping & Receiving:Dock door automation and yard management systems coordinate inbound and outbound freight flows.
- Packaging:Automated case erecting, filling, and sealing systems integrate with downstream palletizing.
Order Fulfillment represents the primary investment focus, while Inventory Management is climbing the fastest as traceability mandates tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Long Beach and Los Angeles port complex anchors California's logistics supremacy, handling 40% of US containerized imports. This maritime gateway feeds the Inland Empire warehouse corridor through dedicated rail links and interstate freight corridors.
California
E-commerce fulfillment velocity demands from Amazon, Walmart, and Target drive concentrated AGV procurement across the Inland Empire. OSHA's powered industrial truck safety mandates accelerate forklift replacement timelines in Riverside and San Bernardino counties. The Ontario-Mira Loma logistics cluster deploys robotic sortation systems at densities unmatched elsewhere in the country.
Texas
Greenfield warehouse development around Houston and Dallas-Fort Worth favors fully automated configurations without legacy retrofit burdens. The Inflation Reduction Act's clean energy tax credits improve battery-powered AGV ROI calculations versus propane alternatives. The AllianceTexas development north of Fort Worth anchors the state's fastest-growing automated distribution footprint.
Illinois
Chicago's intermodal rail terminals and O'Hare cargo infrastructure sustain Midwest manufacturing supply chain automation. NHTSA commercial vehicle automation guidelines influence how intra-facility transport connects with regional trucking networks. The I-55 logistics corridor through Joliet and Rochelle concentrates food and beverage processing automation investment.
Ohio
Manufacturing belt demand for just-in-time material handling integrates robotic palletizers with automotive and consumer goods production. The state's warehouse development lags coastal peers but accelerates near Columbus and Cincinnati. Prologis and Duke Realty developments in the Rickenbacker intermodal zone adopt conveyor-AGV-sortation integration.
Georgia
Hartsfield-Jackson Atlanta International Airport's cargo volume supports southeastern distribution automation for apparel and electronics. The Savannah Port expansion feeds inland warehouse clusters with automated receiving infrastructure. The I-75 corridor through Macon and Valdosta attracts 3PL operators seeking lower land costs than California or Texas.
United States Automated Material Handling Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying conveyors, sensors, and control modules. The vendor base stratifies between full-service integrators capable of greenfield design-build and modular equipment fabricators serving retrofit markets. Two archetypes dominate: convergence players bundling software-hardware stacks, and robotics-as-a-service operators unbundling ownership from operations. M&A activity concentrates on software capability acquisition, while capacity expansion targets Texas and Southeast greenfield corridors.
Among full-service integrators, Dematic and Honeywell Intelligrated anchor the North American system tier, each representing distinct convergence strategies. Daifuku Co. Ltd exemplifies the Japanese multinational archetype with integrated manufacturing and deployment capabilities. These three occupy positions across the premium-to-mid-market spectrum, with differentiation resting on software stack depth versus hardware fabrication scale.
| Leading Market Players |
|---|
| Bastian Solutions Inc. |
| DMW&H |
| Westfalia Technologies Inc. |
| Dorner Manufacturing Corporation |
| Honeywell Intelligrated |
| Dematic |
| Daifuku Co. Ltd |
| SSI Schaefer |
| Kion Group AG |
| Others |
Value Network & Pricing Analysis
Steel mills in China and South Korea anchor global conveyor fabrication, feeding margin concentration into systems integrators with captive metalworking capacity. Component volatility propagates through AGV battery packs and semiconductor motor controllers, compressing procurement flexibility for U.S. distributors.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates Dematic and Honeywell Intelligrated's software-integrated deployments from modular retrofit suppliers and commodity conveyor fabricators. Price differentiation centers on UL certification tier and after-sales service bundling, with California-based 3PLs showing highest sensitivity to upfront capex while food processors prioritize uptime guarantees. Cost compression in standard-tier AGVs is intensifying because automotive sector chip allocation constrains motor controller supply. E-commerce fulfillment operators prove least price-sensitive due to robotics-as-a-service contract structures that shift payment to throughput-based opex models.
Supply Chain Analysis
Steel feedstock from China, South Korea, and domestic U.S. mills supplies conveyor network fabrication, while lithium-ion cells draw from South Korean and Japanese chemical producers. Semiconductor motor controllers, RFID sensors, and precision bearings rest on Taiwan and South Korean foundry output. Single-source vulnerability concentrates in advanced vision systems and laser guidance modules, where German and Japanese suppliers dominate without qualified alternatives. Distribution runs through systems integrators who bundle component procurement with installation and commissioning services, capturing margin that would otherwise flow to discrete equipment vendors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where switching costs lock in multi-year integration contracts and regulatory certification burdens entrench established players against modular disruptors.
For Market Incumbents: Build switching-cost moats through deep WMS-AGV API integration that raises replacement costs for multi-site operators. Expand captive service revenue via predictive maintenance subscriptions tied to IoT sensor networks. Defend against robotics-as-a-service challengers by offering throughput-based financing structures that neutralize their capital-light positioning. Prioritize backward integration into battery pack assembly to secure supply against automotive sector competition.
For New Entrants and Emerging Players: Establish a beachhead in Texas Gulf Coast greenfield developments where legacy system absence eliminates incumbent retrofit advantages. Target mid-market 3PLs serving seasonal e-commerce brands with modular AGV-sortation configurations that deploy without custom middleware. Exploit the controls engineering talent gap by offering turnkey commissioning packages that compress project timelines versus multi-vendor integration approaches.
For Investors and Strategic Acquirers: Capital is best deployed toward software-convergence specialists with proven WMS integration libraries and recurring revenue traction. Long-term viability favors integrators who have migrated from equipment sales to subscription-based throughput optimization services. Monitor FAA drone delivery framework advancement as signal for ground-air interface investment timing, since autonomous aerial systems will eventually demand synchronized material handling infrastructure.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Battery Assembly | Captive lithium-ion pack production insulates AGV margins from automotive sector allocation competition. |
| Robotics-as-a-Service Contract Launch | Throughput-based pricing structures neutralize capex barriers for mid-market e-commerce 3PLs in Texas. |
| Predictive Maintenance Platform Rollout | IoT-enabled service subscriptions convert one-time equipment sales into recurring revenue streams. |
| OSHA Compliance Certification Investment | Enhanced pedestrian detection capabilities lock out uncertified competitors from California warehouse procurement. |
| Digital Twin Software Acquisition | Virtual commissioning capabilities compress design risk and accelerate greenfield project timelines. |
Research Methodology
Operator-level perspectives from warehouse operations directors, 3PL procurement executives, systems integration engineers, and aftermarket service managers anchored the qualitative base. These primary insights combined with secondary validation from OSHA regulatory filings, FAA drone delivery dockets, SEC 10-K equipment disclosures, and customs import records for steel and semiconductor components. Bottom-up facility deployment tallies and top-down logistics sector capex estimates underwent triangulation to reconcile volume figures.
Scenario-bracketing around steel price volatility, semiconductor allocation constraints, and regulatory compliance timelines shaped the analytical framework across the projection horizon. Segmentation modeling incorporated product type, end-user sector, technology tier, and application priority dimensions alongside regional warehouse density patterns. CAGRs derived from facility automation penetration curves and e-commerce fulfillment velocity requirements, with cross-checks against logistics real estate development pipelines and 3PL capital expenditure surveys.
Macroeconomic conditions sit as an overlay; deviation in interest rate environments and construction materials inflation would shift the trajectory for greenfield automation investments. Forecasts reflect documented assumptions regarding OSHA implementation schedules and FAA rulemaking progress. Cross-checking against MHI industry association capital expenditure benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Global Pipe and Tube Bending Machine Market
Material Handling Equipment
Hydraulic Cylinder Rod Market
Material Handling Equipment
Belt Weigh Feeder Market
Material Handling Equipment
Pick and Carry (PNC) Crane Market
Material Handling Equipment
Material Rack Correction Machine Market
Material Handling Equipment
Compaction Machines Market
Material Handling Equipment
Portable Loading Ramps Market
Material Handling Equipment
Dust Extractors Market
Material Handling Equipment
Europe Conveyor Belt Market
Material Handling Equipment
Compactor Market
Material Handling Equipment
Heavy Equipment Movers Market
Material Handling Equipment
Material Handling Automation Market
Material Handling Equipment
Roll Handling Machine Market
Material Handling Equipment
Loaded Container Handler Market
Material Handling Equipment
Log Stackers Market
Material Handling Equipment
Vertical Reciprocating Conveyor Market