
 Global Rolling Mill Rolls Market | 2026-2036
Global Rolling Mill Rolls Market Size, Share, and Industry Trends Forecast 2026-2036
Global Rolling Mill Rolls Market Foresight
Stainless steel foil output from electronics and food packaging OEMs is repositioning the rolling mill rolls market toward precision-ground, high-wear grades. SMS Group GmbH leverages its German engineering base to dominate specialty cold-rolling installations across Europe. Kaida Roll anchors Chinese supply through integrated casting and machining operations in Jiangsu province. Nippon Steel Corporation differentiates via metallurgical R&D partnerships with Japanese automotive stampers requiring ultra-thin gauge capability.
Rolling mill rolls are hardened cylindrical tools, typically forged from alloy steel or high-speed steel with surface hardness exceeding 60 HRC, that apply compressive force to reduce metal slab or billet thickness through successive passes. Their primary purpose is dimensional accuracy control and surface finish refinement across hot and cold rolling lines. Work rolls and backup rolls together constitute the critical load-bearing pair, with composite-material variants capturing margin pools from aluminum sheet producers seeking extended campaign life. High-speed steel grades are outpacing carbon steel in new mill specifications as rolling speeds climb and thermal cycling intensifies.
The US EPA enforces particulate emissions limits that push foundries toward cleaner induction-melting routes for roll casting, while China's SAMR mandates GB standards compliance for imported metallurgical equipment. India's BIS certification requirements for steel plant machinery create non-tariff entry barriers for European and Japanese suppliers. Stakeholders must monitor how carbon-border adjustment mechanisms and evolving alloy-sourcing rules reshape total cost of ownership calculations for mill operators.
Market Dynamics
Stainless steel foil demand from electronics and food packaging OEMs is compressing tolerance specifications and forcing roll producers to migrate from carbon steel toward high-speed steel and composite material grades. This specification escalation is restructuring supplier qualification timelines and capital deployment across the value chain.
Growth Catalysts
- EU F-Gas Regulation:Emissions limits on industrial cooling systems are accelerating replacement cycles for thermal-fatigued rolls in cold-rolling lines, creating pull-through demand for high-performance grades.
- Automotive ultra-thin gauge stamping:Japanese and German automotive OEMs are specifying sub-0.3mm stainless foil for battery enclosures and structural components, requiring precision-ground roll surfaces below 0.5 micrometer Ra.
- India's PLI scheme for specialty steel:Production-linked incentives for cold-rolled stainless capacity are funneling investment toward JSW Steel and Tata Steel expansion projects in Maharashtra and Odisha.
Market Restraints
- Alloy input cost volatility:Molybdenum and vanadium price swings in spot markets are compressing margins for forged high-speed steel rolls, forcing producers toward fixed-price long-term supply contracts.
- Chinese supply concentration:Jiangsu province hosts over sixty percent of global centrifugal casting capacity for large backup rolls, creating single-source vulnerability for European mill operators.
- Induction melting capex barriers:US EPA particulate limits are rendering cupola furnace routes uneconomical, but induction furnace retrofits require capital outlays that strand mid-tier foundries.
Strategic Opportunities
- Vietnam and Indonesia greenfield capacity:Southeast Asian stainless cold-rolling installations are procuring rolls outside established Chinese supply channels, opening qualification windows for European and Japanese suppliers.
- Digital twin integration:Rolls embedded with thermal sensors and edge-computing modules are converging with predictive maintenance platforms, enabling performance-based service contracts.
- India BIS certification gaps:Domestic testing infrastructure for metallurgical equipment remains underdeveloped, creating first-mover advantage for foreign suppliers establishing in-country calibration facilities.
Industry Challenges
- Precision grinding skill scarcity:Achieving sub-micron surface finishes requires journeymen with ten-plus years of specialized experience, a cohort thinning across Germany and Japan.
- Legacy mill integration friction:Retrofitting Industry 4.0 sensor packages onto 1970s-era rolling stands requires mechanical redesigns that extend commissioning timelines.
- GB standards compliance timelines:China's SAMR mandates third-party certification for imported metallurgical equipment, adding six to nine months to supplier qualification cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Rolling Mill Rolls Market |
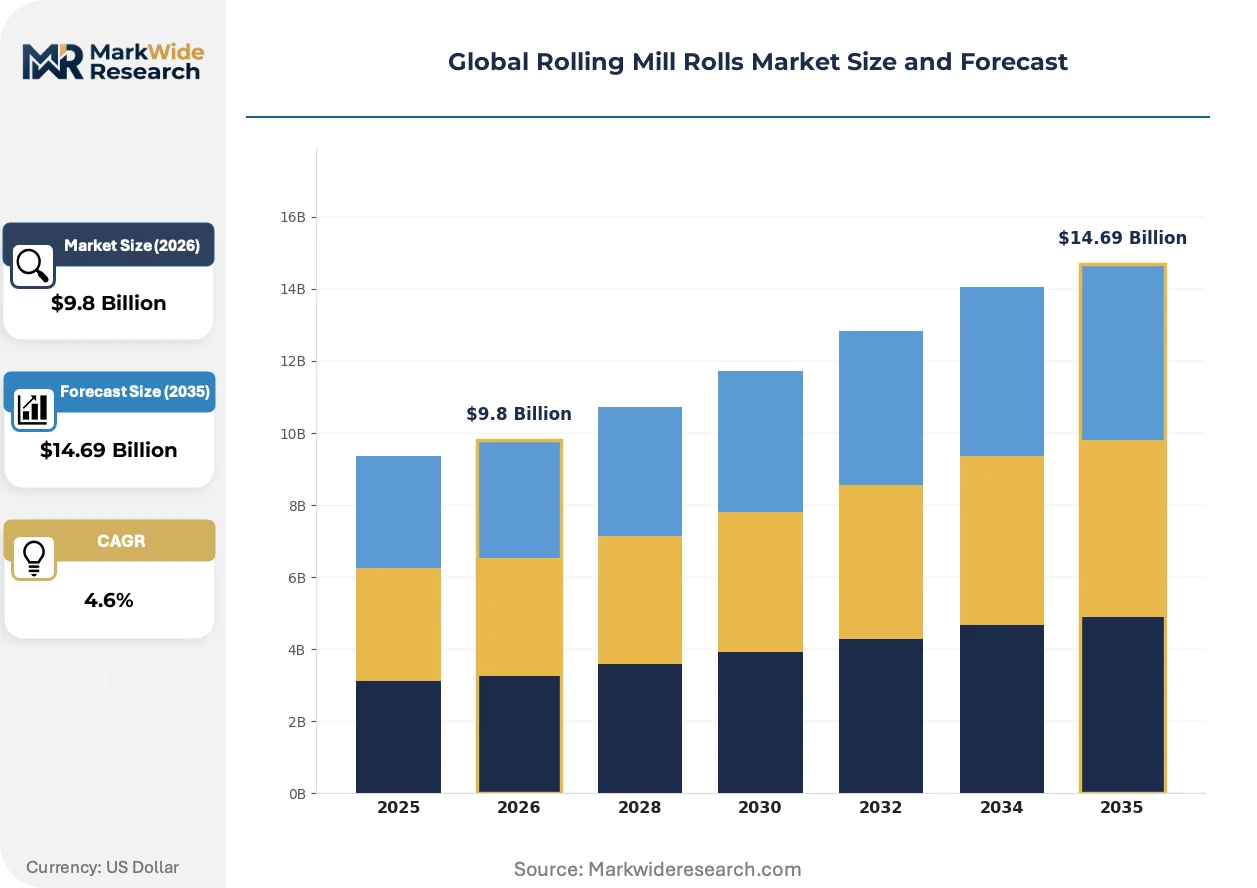
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $14.69 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Work Rolls, Backup Rolls, Guide Rolls, Pinch Rolls, Intermediate Rolls Material Grade: Carbon Steel, Alloy Steel, High-Speed Steel, Ceramics, Composite Material Application: Steel Plates, Aluminum Sheets, Copper Strips, Tin Coils, Stainless Steel Foils End User Industry: Metal Fabricators, Machinery Manufacturers, Forging Plants, Foundries, Casting Units |
| Companies Covered | Leon Roll China Co., Ltd., TSR Rolls, SMS Group GmbH, Häggblom Group, Nippon Steel Corporation, Primetals Technologies Limited, Kaida Roll, Tenova S.p.A., Danieli & C. Officine Meccaniche S.p.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Rolling Mill Rolls Market Shifts & Advancements
Additive manufacturing of stellite hardfacing layers is compressing repair cycle times and enabling geometric complexity impossible through traditional weld-overlay methods. This capability shift is redrawing competitive boundaries between original equipment manufacturers and independent reconditioning specialists.
Composite roll construction—ceramic cores with steel shells—is converging with aluminum sheet producers' demands for extended campaign life between regrinds. Novelis and Constellium are specifying these hybrid designs for continuous tandem mills in Tennessee and Kentucky. The technology is compressing total cost of ownership calculations and displacing solid forged backup rolls in high-speed lines.
China's GB standards for metallurgical equipment are tightening alloy traceability requirements through the SAMR's mandatory certification pathway. Mill operators must now document heat treatment records and chemical composition back to primary smelting. European suppliers are responding by establishing captive audit trails through blockchain-anchored material passports.
Buyers are consolidating supplier panels from six-to-eight vendors down to two-to-three strategic partners with full lifecycle service capabilities. This consolidation is displacing transactional spot purchasing for roll regrinds and recores. The pattern is most visible in India's integrated steel sector, where JSW Steel and Tata Steel are executing multi-year framework agreements with SMS Group and Kaida Roll.
Global Rolling Mill Rolls Market Segmentation
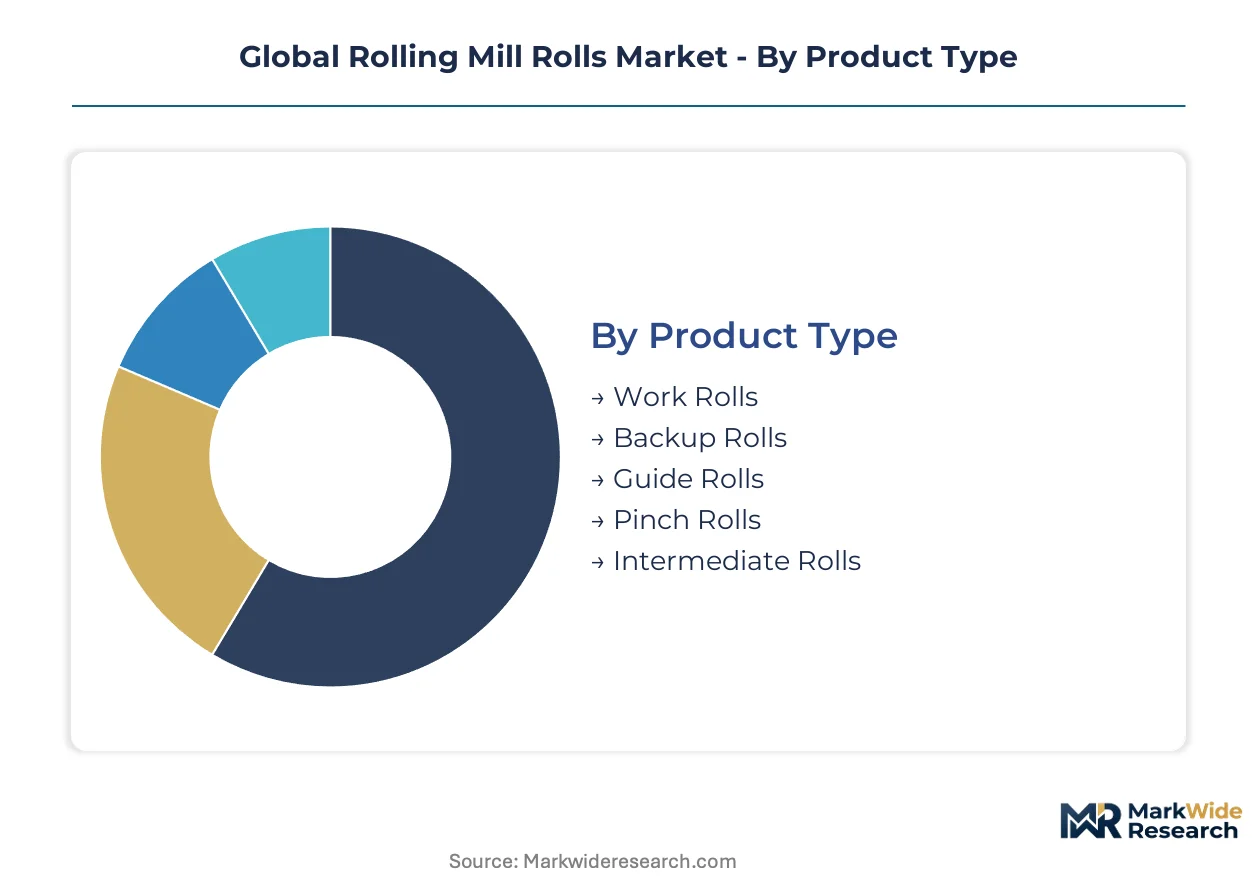
Roll specification tiers determine certification pathways and supplier qualification timelines across the value chain. Procurement teams segment requirements by thermal load, surface finish tolerance, and campaign life expectations.
Product Type:
Certification burden varies sharply: work rolls face GB standards compliance for surface hardness documentation, while backup rolls trigger SAMR third-party verification for load-bearing structural integrity.
- Work Rolls:These hardened cylinders apply direct compressive force to metal stock, with surface hardness exceeding 60 HRC and Ra finishes below 0.5 micrometers for precision lines. Demand concentrates in Japanese automotive stamping for battery enclosure foil, where sub-0.3mm gauge capability requires thermal-sensor-embedded designs.
- Backup Rolls:These support work rolls against bending deflection under multi-thousand-ton rolling loads, forged from alloy steel with diameter-to-length ratios optimized for specific mill stands. European cold-rolling installations are replacing these on accelerated cycles driven by EU F-Gas Regulation thermal-fatigue limits.
- Guide Rolls:Directional control elements in continuous casting and rolling trains.
- Pinch Rolls:Tension-maintaining pairs at entry and exit points of processing lines.
- Intermediate Rolls:Load-distribution elements in cluster-type cold-rolling mills.
Leading the category by volume: Work Rolls. Growing fastest: Backup Rolls with embedded sensor packages.
Material Grade:
Cost tier stratification separates commodity procurement from performance-specified supply chains, with alloy content driving three-to-five-year contract structures versus spot purchasing.
- High-Speed Steel:Tungsten-molybdenum-vanadium alloys deliver superior red hardness for high-speed tandem mills exceeding 2,000 meters per minute. Indian PLI scheme cold-rolling investments in Maharashtra are specifying these grades for stainless foil output.
- Composite Material:Ceramic cores with steel shells extend campaign life between regrinds by 40-60% in aluminum sheet applications. Novelis and Constellium continuous mills in Tennessee and Kentucky have adopted these hybrid designs.
- Carbon Steel:Baseline grade for low-speed, low-temperature applications with standard tolerance requirements.
- Alloy Steel:Chromium-nickel-molybdenum formulations balancing cost and performance for general-purpose rolling.
- Ceramics:Oxide or nitride-based rolls for extreme thermal environments in specialized heat-treatment lines.
Carbon Steel dominates procurement volume. Composite Material is climbing the fastest as aluminum producers recalculate total cost of ownership.
Application:
Customer type determines margin structure: automotive-qualified suppliers command premium positioning versus commodity steel plate vendors.
- Stainless Steel Foils:Sub-0.3mm gauge output for electronics and food packaging OEMs demands precision-ground surfaces and full heat-treatment traceability. China's SAMR now mandates blockchain-anchored material passports for these specifications.
- Aluminum Sheets:Continuous tandem mill operations prioritize extended campaign life, driving composite roll adoption. Kentucky and Tennessee installations specify ceramic-core designs for high-speed lines.
- Steel Plates:Heavy-gauge structural and shipbuilding applications with standard tolerance bands.
- Copper Strips:Electrical conductivity applications in transformer and motor winding production.
- Tin Coils:Food can stock with surface quality requirements for coating adhesion.
Steel Plates lead by volume. Stainless Steel Foils show steepest expansion trajectory on electronics and battery enclosure demand.
End User Industry:
Supply concentration patterns differ: integrated steel mills consolidate to two-to-three strategic partners, while independent fabricators maintain broader vendor panels.
- Metal Fabricators:Tier-one automotive stampers in Germany and Japan specify sub-micron surface finishes and full lifecycle service capabilities. These buyers have compressed supplier panels from six-to-eight vendors to two-to-three framework agreements.
- Foundries:Roll casting operations face US EPA particulate limits pushing cupola-to-induction retrofits, with capital barriers stranding mid-tier operators. Induction-melting qualification opens supply to cleaner European and Japanese producers.
- Machinery Manufacturers:Original equipment builders for greenfield mill installations.
- Forging Plants:In-house roll production for captive steel mill consumption.
- Casting Units:Centrifugal and static casting operations for roll reconditioning services.
Metal Fabricators lead procurement volume. Foundries are gaining share fastest on environmental retrofit cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Jiangsu province host over sixty percent of global centrifugal casting capacity for large backup rolls, concentrating supply chain leverage within a single Chinese coastal corridor. This geographic clustering shapes procurement vulnerability assessments for European and Japanese mill operators.
China
Stainless steel foil production for electronics OEMs in the Yangtze River Delta is compressing tolerance specifications toward sub-micron surface finishes. SAMR mandates GB standards compliance with six-to-nine-month third-party certification timelines for imported metallurgical equipment. Xuzhou and Changzhou foundry clusters dominate centrifugal casting output for global backup roll supply.
Germany
Automotive OEMs in Bavaria and Baden-Württemberg specify sub-0.3mm stainless foil for battery enclosures, requiring precision-ground roll surfaces below 0.5 micrometer Ra. EU F-Gas Regulation thermal-fatigue limits are accelerating replacement cycles for cold-rolling line rolls. SMS Group anchors specialty cold-rolling installations from its engineering base in North Rhine-Westphalia.
India
JSW Steel and Tata Steel are expanding cold-rolling capacity in Maharashtra and Odisha under PLI scheme incentives for specialty steel production. BIS certification requirements for steel plant machinery create non-tariff entry barriers for European and Japanese suppliers. Mumbai-Pune industrial corridor procurement teams are consolidating supplier panels toward multi-year framework agreements.
Japan
Ultra-thin gauge stamping demand from automotive stampers in Toyota City and Yokohama clusters requires metallurgical R&D partnerships for sub-0.3mm capability. METI industrial standards align with JIS certification pathways for high-performance roll grades. Nagoya-area steel mills specify thermal-sensor-embedded work roll designs for battery enclosure foil production.
United States
Novelis and Constellium continuous tandem mills in Tennessee and Kentucky specify composite ceramic-core roll designs for extended campaign life. EPA particulate emissions limits are pushing foundries toward induction-melting retrofits that strand mid-tier cupola operators. Appalachian and Midwest steel corridors face capital barriers to environmental compliance.
Global Rolling Mill Rolls Market Competitive Landscape
Top-tier vendors anchor precision-grade supply for automotive-qualified specifications, while commodity-grade producers compete on casting throughput and regional logistics. The vendor base stratifies across three tiers: integrated technology providers with full lifecycle service capabilities, specialized roll foundries with captive metallurgical expertise, and regional reconditioning specialists serving legacy mill maintenance. Market consolidation is compressing supplier panels from six-to-eight vendors down to two-to-three strategic partners. Competitive moves center on multi-year framework agreements and digital twin integration for predictive maintenance platforms.
Within the integrated technology tier, SMS Group GmbH and Primetals Technologies Limited represent German-engineered positioning for specialty cold-rolling installations. Among Asian foundry specialists, Kaida Roll anchors Chinese supply through its Jiangsu province operations. Japanese metallurgical R&D leadership is exemplified by Nippon Steel Corporation's partnerships with automotive stampers requiring ultra-thin gauge capability. These three archetypes—European system integrators, Chinese scale producers, and Japanese precision specialists—occupy distinct competitive positions without direct overlap in customer qualification pathways.
| Leading Market Players |
|---|
| Leon Roll China Co., Ltd. |
| TSR Rolls |
| SMS Group GmbH |
| Häggblom Group |
| Nippon Steel Corporation |
| Primetals Technologies Limited |
| Kaida Roll |
| Tenova S.p.A. |
| Danieli & C. Officine Meccaniche S.p.A. |
| Others |
Supply & Pricing Matrix
Additive manufacturing of stellite hardfacing layers is compressing repair cycle times while simultaneously concentrating premium pricing power among technology-integrated reconditioning specialists in Germany and Japan. This production-method transition rewards suppliers with captive metallurgical R&D capabilities and marginalizes commodity foundries dependent on conventional weld-overlay routes.
Pricing Analysis
Short lead-time premiums of fifteen to twenty percent above contract baselines apply to precision-ground work rolls for automotive battery enclosure foil specifications. Pricing stratifies across automotive-qualified, industrial-standard, and commodity-regrind tiers, with alloy-grade certification and embedded sensor packages as primary differentiation drivers. Cost compression in carbon steel grades intensifies as Chinese centrifugal casting capacity expands. Independent metal fabricators exhibit highest price sensitivity, while integrated steel mills prioritize total cost of ownership over unit pricing.
Supply Chain Analysis
Regional distribution centers in Duisburg, Rotterdam, and Singapore maintain finished roll inventory for European and Southeast Asian mill operators. Supply concentrates in China, Germany, and Japan, with Jiangsu province hosting over sixty percent of global centrifugal casting capacity for large backup rolls. Raw material dependencies center on molybdenum from Chile, vanadium from South Africa, and high-purity iron ore from Australia. Single-source vulnerability in Chinese backup roll casting creates structural risk for European cold-rolling installations. Distribution runs through mill-direct contracts with logistics managed by specialized heavy-lift freight operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Composite roll construction with ceramic cores is displacing solid forged designs across aluminum tandem mill specifications. This technology-transition phase compresses incumbent reconditioning revenue streams while opening qualification windows for integrated technology providers.
For Market Incumbents: Deploy predictive maintenance platform integration to capture performance-based service contracts and lock in multi-year framework agreements. Establish captive blockchain-anchored material passport systems to preempt China's SAMR GB standards compliance requirements. Defend against independent reconditioning specialists by embedding thermal sensors and edge-computing modules in original equipment specifications.
For New Entrants and Emerging Players: India's PLI scheme for specialty steel production opens a window for cold-rolling roll qualification at JSW Steel and Tata Steel expansion projects in Maharashtra and Odisha. Target Vietnam and Indonesia greenfield stainless cold-rolling installations seeking supply channel diversification outside established Chinese procurement networks. Enter through digital twin integration partnerships rather than commodity casting competition.
For Investors and Strategic Acquirers: Re-rating potential sits with European system integrators possessing full lifecycle service capabilities given EU F-Gas Regulation replacement cycle acceleration. Long-term viability favors technology-anchored positions over pure-play foundry assets across the analysis window. Monitor induction-melting retrofit completion rates at US foundries as inflection indicator for environmental compliance-driven supplier consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alloy Supply | Captive molybdenum and vanadium sourcing insulates SMS Group from spot market volatility. |
| Digital Twin Platform Deployment | Thermal sensor integration enables predictive maintenance contracts with Novelis and Constellium. |
| Blockchain Material Passport Implementation | GB standards compliance through SAMR certification pathway accelerates Chinese market access. |
| Regional Distribution Center Establishment | Singapore hub reduces lead times for Southeast Asian greenfield stainless cold-rolling projects. |
| Composite Roll Technology Licensing | Ceramic-core steel-shell designs displace solid forged backup rolls in Kentucky and Tennessee mills. |
Research Methodology
Multi-period observation of rolling mill campaign life, surface finish tolerance specifications, and thermal fatigue replacement cycles anchored the trend analysis, supplemented by interviews with maintenance directors at integrated steel mills, procurement leads at aluminum sheet producers, aftermarket service heads at roll reconditioning specialists, and technical R&D directors at metallurgical equipment manufacturers. Secondary validation drew from customs and trade data, SEC filings of publicly listed steel producers, foundry emissions disclosures to the US EPA, and SAMR certification records. Bottom-up volume estimates from individual mill operator procurement patterns triangulated against top-down capacity assessments from regional steel association reports.
Input-output matrices modeled roll demand across product type, material grade, application specification, and end-user industry dimensions throughout the forecast period. CAGRs derived from regression analysis of historical replacement cycle data and projected greenfield capacity installations. Industry-specific forecast inputs included automotive ultra-thin gauge stamping penetration rates and aluminum sheet producer composite roll adoption curves.
The model assumes a particular technology adoption path for additive manufacturing hardfacing; alternative pathways for conventional weld-overlay repair would alter the outlook for independent reconditioning specialist market share. Forecasts reflect documented assumptions regarding regulatory compliance timelines, alloy price stabilization, and induction-melting retrofit completion rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Swivel Coupler Market
Material Handling Equipment
Arrestor Cables Market
Material Handling Equipment
Conveyor Scales Market
Material Handling Equipment
Resistance Welding Products Market
Material Handling Equipment
US and Mexico Metal Stamping Market
Material Handling Equipment
Overhead Hoist Transport (OHT) Market
Material Handling Equipment
Automated Material Handling (AMH) Market
Material Handling Equipment
Sifter Fitment Market
Material Handling Equipment
Industrial Wood Chipper Market
Material Handling Equipment
Pipe Wrapping Machines Market
Material Handling Equipment
Reach Stacker Market
Material Handling Equipment
Loaded Container Handler Market
Material Handling Equipment
Australia Forklift Rental Market
Material Handling Equipment
Portable Loading Ramps Market
Material Handling Equipment
Water Hose Market
Material Handling Equipment
Dynamic Compactor Market