
 Shiplifts & Transfer Systems Market | 2026-2036
Shiplifts & Transfer Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Shiplifts & Transfer Systems Market Insights
Electro-hydraulic synchronization is narrowing the performance gap between legacy mechanical shiplifts and fully automated electric systems. Syncrolift AS leverages its Nordic engineering heritage to dominate synchronized multi-point lifting architectures for naval and commercial yards. Bosch Rexroth AG sustains technology leadership through in-house production of high-pressure hydraulic drive trains purpose-built for corrosive marine environments. Larsen & Toubro Limited anchors its position across Indian defense and civilian shipyards with localized manufacturing scale and aftermarket service density.
Shiplifts & transfer systems comprise synchronized hoisting platforms, rail-mounted transfer carriages, and docking blocks engineered to raise, lower, and horizontally reposition vessels up to several thousand tonnes displacement, typically employing steel wire rope arrays or rack-and-pinion mechanisms with positional feedback within millimetric tolerances. Their primary purpose is to transfer hulls between water and land-based maintenance bays without traditional graving dock flooding. Vertical shiplifts occupy the largest installed base due to decades of proven performance in constrained waterway geometries, though electric drive technology is displacing hydraulic power packs fastest among newbuild greenfield yards seeking reduced energy intensity and predictive maintenance integration. Transfer systems capture concentrated margin pools where yard automation demands integrate AGV routing, automated docking block placement, and enterprise scheduling software into unified material flow architectures.
ISO 3874 container handling standards, Lloyd's Register's ship lifting appliance rules, and DNV's offshore lifting standards collectively shape equipment certification pathways, load testing protocols, and operator qualification requirements across major shipbuilding jurisdictions. Compliance with these frameworks determines market access for European and Asian manufacturers bidding on NATO naval yard contracts or Middle Eastern port authority tenders. Stakeholders must monitor how classification society updates to dynamic load modeling and cyber-physical system safety will redefine competitive differentiation between hydraulic incumbents and electric challengers.
Market Dynamics
Electrification of heavy-lift architectures is compressing the traditional dominance of hydraulic drive trains, forcing incumbent suppliers to reengineer power transmission systems for millimetric synchronization tolerances demanded by naval classification rules.
Growth Catalysts
- NATO naval modernization mandates:Fleet renewal programs across member states are generating sustained procurement of synchronized multi-point lifting platforms for submarine and surface combatant maintenance. These programs specify Lloyd's Register-certified load-bearing precision.
- Greenfield yard automation:New shipbuilding facilities in South Korea and the Middle East are specifying integrated AGV routing with automated docking block placement. This convergence creates demand for unified material flow architectures combining vertical lifts with horizontal transfer systems.
- Corrosion-resistant hydraulic alloys:Advances in high-pressure sealing materials purpose-built for saltwater immersion are extending maintenance intervals for legacy installations. This technical progression sustains retrofit demand alongside newbuild electric alternatives.
Market Restraints
- Specialized steel supply concentration:High-tensile wire rope and rack-and-pinion gearing production clusters in Germany and Japan create input cost volatility when raw material tariffs fluctuate.
- Graving dock substitution economics:Traditional flooded dry docks remain cost-competitive for single-vessel maintenance in ports with ample waterfront footprint, limiting shiplift penetration in mature European facilities.
- Certification timeline friction:DNV's dynamic load modeling updates and Lloyd's Register's cyber-physical system safety protocols are extending type-approval cycles for electric drive systems by 8-14 months.
Strategic Opportunities
- Indian defense-civilian dual-use expansion:The country's PLI scheme for heavy engineering and localized manufacturing incentives for defense procurement create entry points for integrated lift-and-transfer system providers.
- Predictive maintenance convergence:Integration of IoT sensor arrays with enterprise scheduling software enables condition-based servicing contracts. This service model captures recurring revenue streams beyond equipment sale margins.
- Middle Eastern port authority tenders:Greenfield developments in Saudi Arabia and the UAE specify fully automated electric systems with reduced energy intensity, bypassing legacy hydraulic infrastructure entirely.
Industry Challenges
- Electro-mechanical synchronization expertise scarcity:The talent pool for programming multi-point lift control systems with sub-millimeter positional feedback remains shallow relative to hydraulic system engineering depth.
- Legacy system integration complexity:Retrofitting electric drive trains into existing steel superstructures requires structural recertification under updated ISO 3874 load testing protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Shiplifts & Transfer Systems Market |
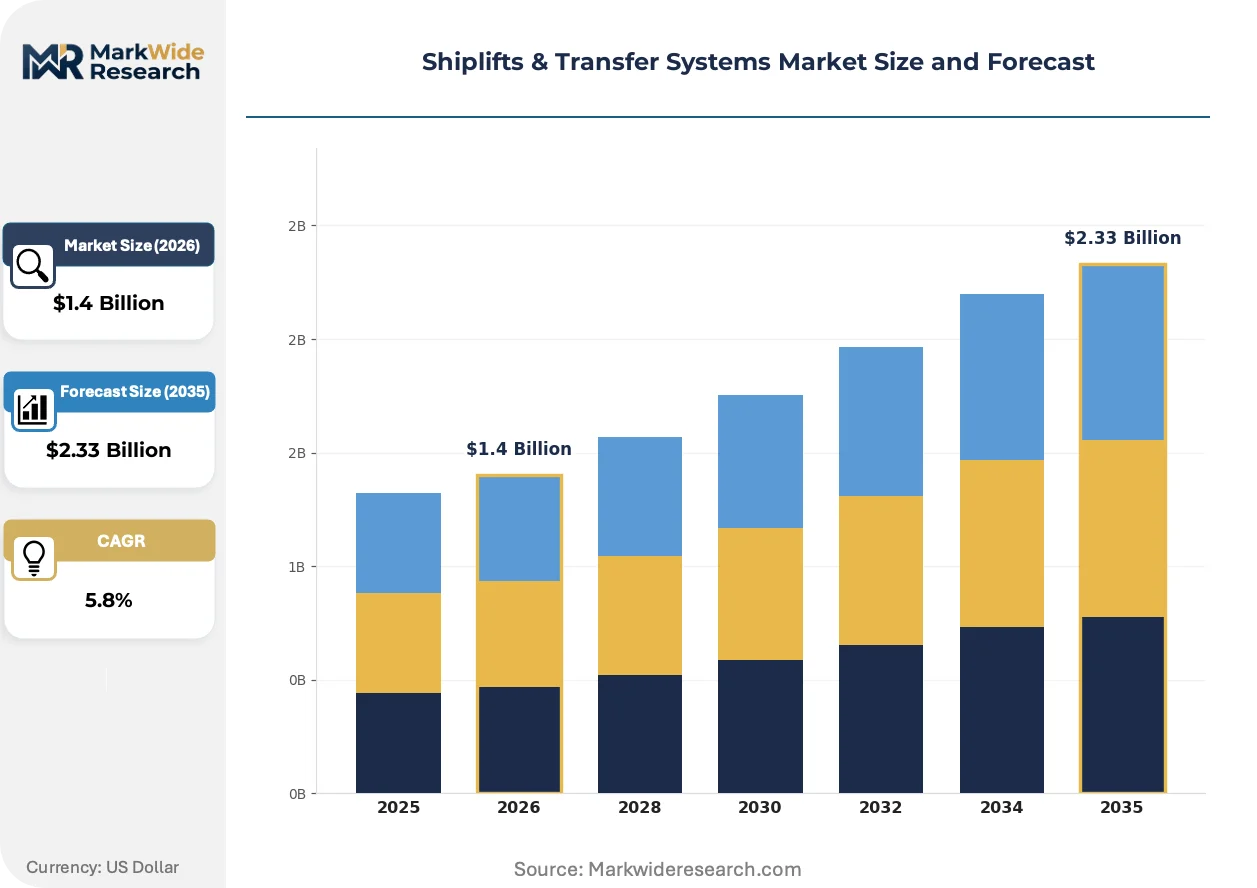
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.33 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vertical Shiplift, Horizontal Shiplift, Transfer Platform, Transfer System Technology: Hydraulic, Pneumatic, Mechanical, Electric Application: Vessel Maintenance, Dry Docking, Cargo Handling, Launching End User: Shipyards, OEMs, Maritime Services, Offshore Platforms |
| Companies Covered | Pearlson Shiplift Corporation, Syncrolift AS, TTS Group ASA, Bardex Corporation, Damen Shipyards Group, Bosch Rexroth AG, GANTREX, Larsen & Toubro Limited, Maschinenfabrik Bröhl GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Shiplifts & Transfer Systems Market Trends and Innovations
Active substitution of hydraulic power transmission by electric drive architectures is redefining competitive differentiation, while classification society updates to safety protocols are compressing product development cycles.
Rack-and-pinion electric drive systems with integrated regenerative braking are migrating from niche greenfield installations to mainstream naval yard specifications. South Korean shipbuilders are specifying these architectures for new dry-docking capacity to achieve predictive maintenance integration and energy consumption targets. The technology is migrating from premium segment positioning toward standard configuration status as Bosch Rexroth and Syncrolift AS scale production.
The EU's F-Gas Regulation and accompanying machinery safety directives are mandating sealed hydraulic systems with leak detection for equipment operating in sensitive coastal zones. This regulatory pressure is accelerating R&D investment in fully electric alternatives by European manufacturers bidding on public sector contracts. Naval yards in France and Germany are responding by specifying electric systems exclusively for new procurement.
Service contract unbundling is fragmenting traditional equipment-plus-maintenance bundles into separate performance-based agreements and parts-only supply arrangements. Port authorities with in-house engineering capabilities are purchasing lift platforms without aftermarket service commitments, pressuring OEM margin structures. This pattern is most visible in South Korea's heavy industrial clusters where Hyundai Heavy Industries and Samsung Heavy Industries maintain captive maintenance workforces.
Shiplifts & Transfer Systems Market Segmentation
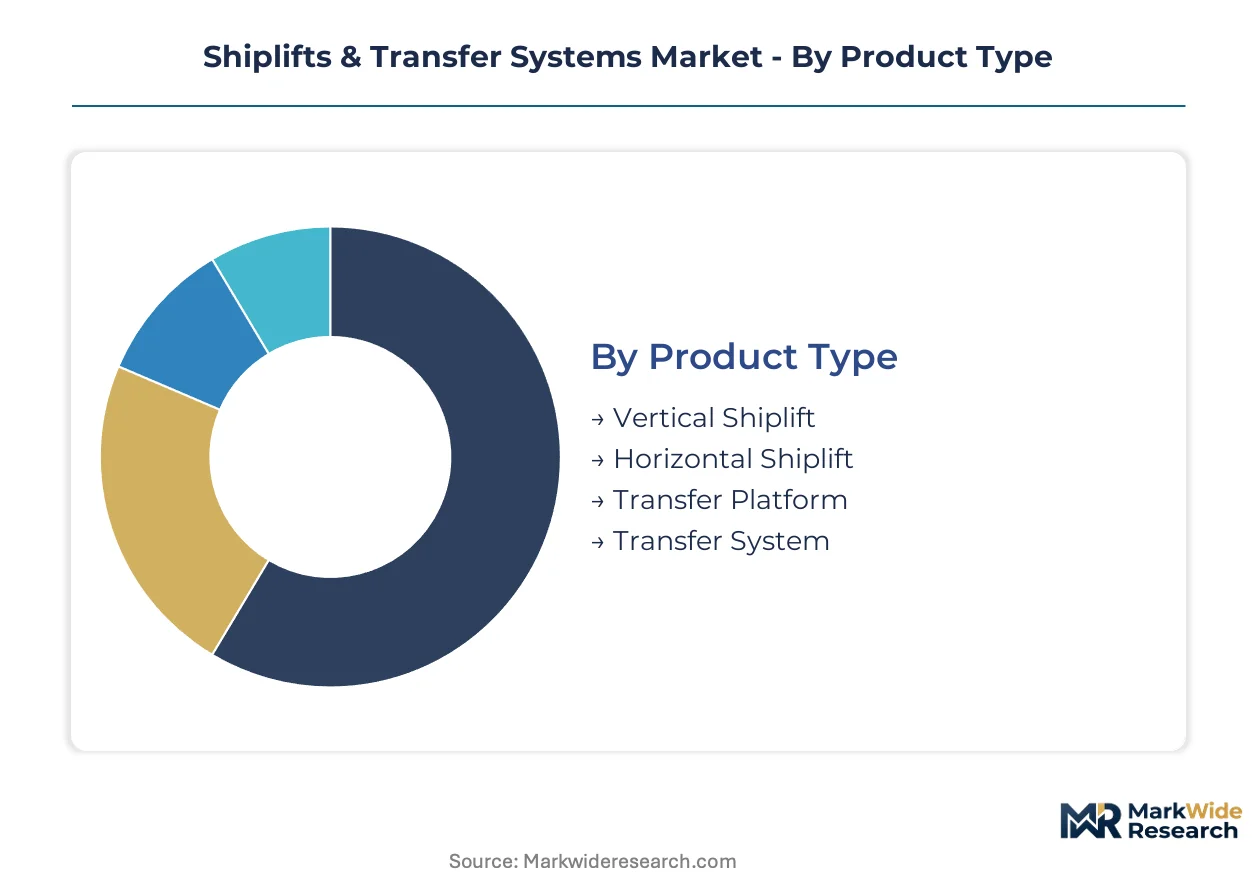
Segmentation in shiplifts and transfer systems reveals how procurement priorities diverge between naval yards demanding Lloyd's Register-certified precision and commercial operators optimizing throughput economics. Understanding these splits illuminates where electric drive architectures displace legacy hydraulic systems and where corrosion-resistant alloys sustain incumbent technology.
Product Type:
Naval fleet modernization programs and greenfield yard automation are reshaping procurement across the lift-platform spectrum, with specification intensity varying sharply by vessel displacement and maintenance frequency.
- Vertical Shiplift:Steel superstructure platforms employing synchronized wire rope arrays or rack-and-pinion mechanisms to raise vessels vertically from constrained waterway geometries. Decades of proven performance in NATO naval yards and South Korean heavy industrial clusters sustain dominant installed base position despite longer commissioning cycles than horizontal alternatives. Established volume favors vertical shiplifts; emerging adoption favors transfer systems.
- Horizontal Shiplift:Rail-mounted carriage architectures that translate hulls laterally between water and land-based maintenance bays without vertical displacement. Greenfield developments in Saudi Arabia and the UAE specify these for reduced energy intensity and AGV routing integration.
- Transfer Platform:Modular docking block systems with automated placement capabilities serving intermediate vessel repositioning within yard layouts.
- Transfer System:Unified material flow architectures combining vertical lifts, horizontal carriages, and enterprise scheduling software into integrated automation layers.
Cost tiering separates premium naval specifications from standard commercial configurations.
Technology:
Drive train selection determines energy intensity, predictive maintenance integration, and certification pathway complexity across shipyard operator profiles.
- Hydraulic:High-pressure power transmission systems with sealed alloy components purpose-built for saltwater immersion and corrosive marine atmospheres. Extended maintenance intervals and established Lloyd's Register certification pathways sustain retrofit demand in mature European facilities.
- Electric:Rack-and-pinion architectures with regenerative braking and IoT sensor arrays enabling condition-based servicing contracts. South Korean shipbuilders specify these exclusively for new dry-docking capacity to meet energy consumption targets and millimetric synchronization tolerances.
- Pneumatic:Compressed air drive systems occupying niche applications where explosion resistance or rapid cycling speed outweighs precision requirements.
- Mechanical:Legacy gear-and-cam architectures with minimal electronic control complexity, persisting in budget-constrained retrofit scenarios.
Application intensity clusters on vessel maintenance; technology margins concentrate in electric architectures.
Application:
Operational purpose dictates load-bearing precision requirements, cycle frequency, and integration depth with yard automation infrastructure.
- Vessel Maintenance:Synchronized multi-point lifting for submarine and surface combatant hull work demanding sub-millimeter positional feedback and NATO classification compliance. Procurement concentrates in French and German naval yards responding to EU F-Gas Regulation mandates for sealed systems.
- Dry Docking:Routine hull inspection and repainting operations where throughput volume and turnaround speed determine equipment specification. Hyundai Heavy Industries and Samsung Heavy Industries drive continuous capacity expansion here.
- Cargo Handling:Container vessel loading support applications with lower precision tolerances and higher cycle frequency requirements.
- Launching:Newbuild vessel entry-to-water operations requiring synchronized descent control and emergency braking redundancy.
Customer procurement patterns favor integrated lift-and-transfer bundles in naval yards and unbundled platform-only purchases in commercial clusters.
End User:
Operator capability and captive engineering resources determine service contract structure and aftermarket revenue capture potential.
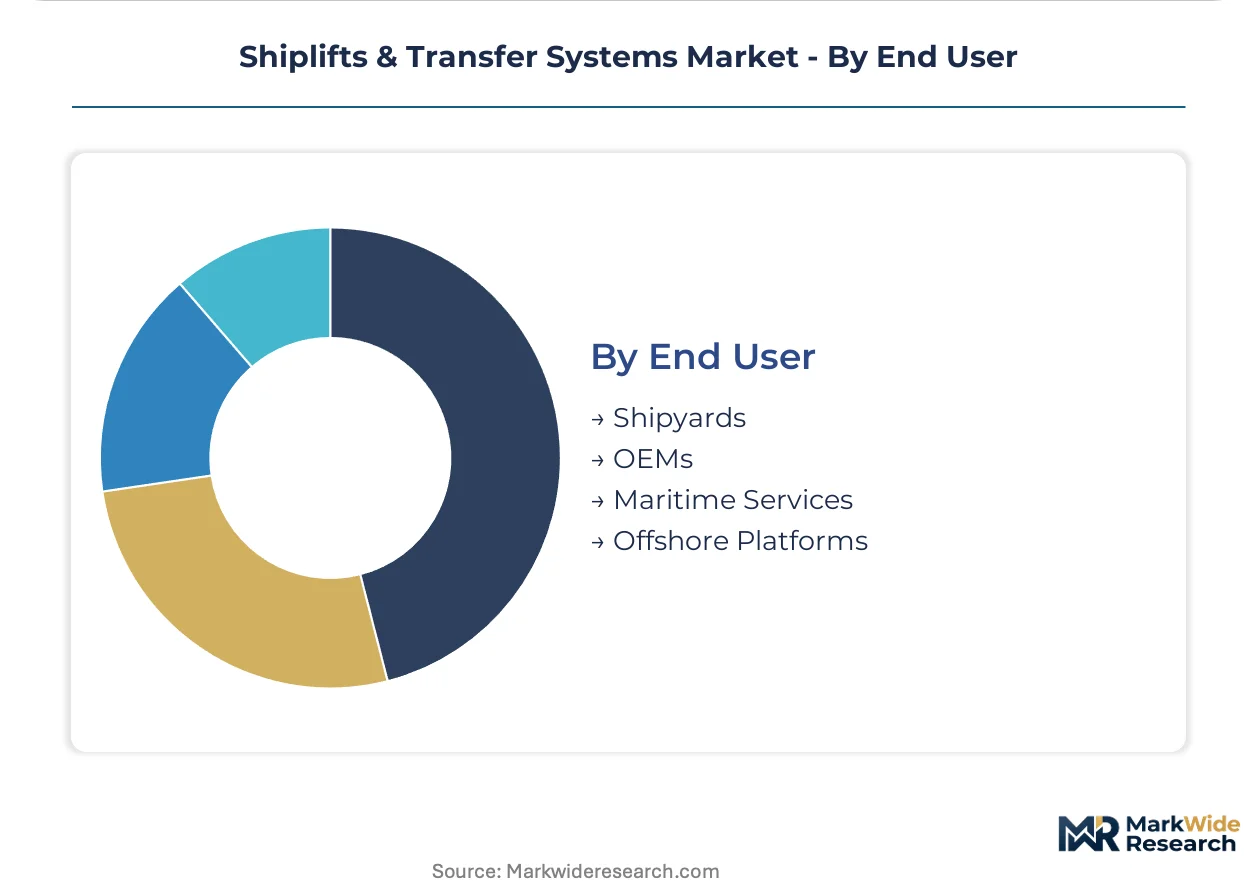
- Shipyards:Integrated maintenance and newbuild facilities with in-house engineering workforces, predominantly in South Korea and India. India's PLI scheme for heavy engineering creates localized manufacturing incentives for defense-civilian dual-use expansion.
- OEMs:Original equipment manufacturers supplying complete lift platforms to third-party yard operators, capturing margin through technology licensing and core component supply.
- Maritime Services:Independent maintenance contractors bidding on port authority tenders with performance-based service agreements rather than capital equipment ownership.
- Offshore Platforms:Oil and gas installation support vessels requiring specialized heavy-lift capabilities in harsh environment specifications.
Supply concentration in Germany and Japan for high-tensile components shapes procurement lead times across end-user categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German engineering houses export precision rack-and-pinion systems to South Korean shipbuilders, while Nordic suppliers route synchronized lifting architectures through NATO naval procurement channels. This trade-flow pattern concentrates technology transfer within allied defense-industrial networks and greenfield commercial developments.
South Korea
Hyundai Heavy Industries and Samsung Heavy Industries drive continuous dry-docking capacity expansion across the Busan-Ulsan corridor. The MFDS oversees marine equipment safety certification, though defense procurement falls under separate agency jurisdiction. Daegu-Gyeongbuk hosts specialized steel fabrication clusters feeding wire rope array production for vertical shiplift installations.
Germany
High-tensile rack-and-pinion gearing production clusters in Baden-Württemberg and North Rhine-Westphalia supply precision components for NATO naval yard specifications. The KBA coordinates with Lloyd's Register on machinery safety compliance for export-bound equipment. Hamburg's port engineering ecosystem sustains captive design expertise for synchronized multi-point lifting architectures.
United States
Navy fleet modernization programs generate sustained procurement of Lloyd's Register-certified load-bearing systems for submarine maintenance facilities. The Department of Defense acquisition framework mandates Buy American provisions for critical shipyard infrastructure. Virginia and Maine coastal clusters concentrate naval yard retrofit activity for legacy hydraulic-to-electric conversions.
India
The PLI scheme for heavy engineering creates localized manufacturing incentives for defense-civilian dual-use lift system expansion. BIS standards govern structural steel certification for port infrastructure equipment. Gujarat and Maharashtra coastal zones attract integrated transfer system providers serving both naval dockyards and commercial repair facilities.
United Arab Emirates
Greenfield port developments in Dubai and Abu Dhabi specify fully automated electric systems with reduced energy intensity, bypassing legacy hydraulic infrastructure. MOHAP and port authority tender specifications emphasize predictive maintenance integration and AGV routing compatibility. Sharjah's emerging maritime services cluster demands transfer platforms for independent maintenance contractors.
Shiplifts & Transfer Systems Market Competitive Landscape
On the supply side, the industry is bifurcated between hydraulic incumbents with decades of Lloyd's Register certification lineage and electric challengers scaling rack-and-pinion architectures for greenfield automation. The vendor base clusters geographically: Nordic engineering houses dominate naval synchronized lifting, German component specialists anchor precision gearing supply, and South Korean conglomerates integrate captive fabrication. Three archetypes define positioning: classification-society-certified system integrators, high-pressure drive train component suppliers, and yard-scale automation platform providers. Competitive moves concentrate on technology licensing partnerships for electric drive scaling and strategic capacity placement near Indian and Middle Eastern greenfield developments.
Within the naval-certified system integrator tier, Syncrolift AS exemplifies Nordic engineering heritage in synchronized multi-point lifting, while TTS Group ASA occupies a parallel position in transfer carriage architectures. Among diversified industrial conglomerates, Larsen & Toubro Limited anchors Indian defense-civilian dual-use positioning through localized manufacturing scale. Bosch Rexroth AG represents the component-specialist archetype, with in-house production of high-pressure hydraulic drive trains purpose-built for corrosive marine environments. These three occupy distinct competitive spaces rather than direct overlap, reflecting market segmentation by certification pathway and geographic procurement channel.
| Leading Market Players |
|---|
| Pearlson Shiplift Corporation |
| Syncrolift AS |
| TTS Group ASA |
| Bardex Corporation |
| Damen Shipyards Group |
| Bosch Rexroth AG |
| GANTREX |
| Larsen & Toubro Limited |
| Maschinenfabrik Bröhl GmbH |
| Others |
Pricing and Supply Chain Analysis
Tariff exposure on German and Japanese high-tensile steel inputs compresses margin structures across both premium naval specifications and standard commercial configurations, forcing procurement arbitrage between Lloyd's Register-certified precision systems and cost-optimized alternatives while simultaneously reshaping supplier geography toward Indian and South Korean fabrication clusters.
Pricing Analysis
Current-generation electric rack-and-pinion systems command substantial premia over legacy hydraulic architectures, while prior-generation mechanical systems occupy residual budget retrofit demand and next-generation fully integrated automation platforms remain pre-commercial. Three-tier pricing structure across premium, standard, and economy levels separates Lloyd's Register-certified naval specifications from commercial dry-docking configurations and basic transfer carriage offerings. Price differentiation rests on certification grade and after-sales service bundling. Cost compression in the standard tier is intensifying because South Korean shipbuilders with captive maintenance workforces are unbundling service contracts. Commercial operators with in-house engineering capabilities exhibit highest price sensitivity; NATO naval procurement with mandated precision tolerances exhibits lowest.
Supply Chain Analysis
Extended payment terms from South Korean shipbuilders and supply-chain finance facilities arranged through German component houses are restructuring working capital requirements for tier-two fabricators. Production gravity centers on Germany for precision rack-and-pinion gearing, Japan for high-tensile wire rope arrays, and South Korea for integrated platform assembly. The supply chain draws from specialized alloy steel, high-pressure hydraulic seals, and precision-machined gearing. Single-source vulnerability in German and Japanese steel supply creates structural exposure to raw material tariff fluctuations. Distribution runs through OEM direct sales for naval contracts and port authority tender processes for commercial installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Graving dock substitution economics present a persistent displacement threat that electric drive incumbents must neutralize through performance differentiation and total cost-of-ownership repositioning.
For Market Incumbents: Build certification moats through accelerated Lloyd's Register and DNV pathway investment ahead of pending cyber-physical system safety updates. Defensive consolidation should prioritize backward integration into high-tensile steel supply through offtake agreements with German and Japanese mills, while capacity addition in Gujarat and Maharashtra captures Indian PLI scheme incentives before localization requirements tighten. For New Entrants and Emerging Players: Establish a beachhead in Middle Eastern greenfield port developments where fully automated electric specifications bypass legacy hydraulic infrastructure entirely. The most penetrable segment sits in transfer system integration for Saudi Arabian and UAE port authorities seeking unified material flow architectures. Go-to-market execution should emphasize predictive maintenance convergence with IoT sensor arrays and enterprise scheduling software. For Investors and Strategic Acquirers: The market sits at a technology substitution phase that favors electric drive specialists with established naval certification lineage over hydraulic incumbents facing stranded asset risk. Long-term viability across the projection horizon hinges on classification society alignment and greenfield automation penetration. Acquisition targets should display synchronized multi-point lifting expertise with Lloyd's Register certification depth. The signal to watch is DNV dynamic load modeling update adoption velocity as inflection indicator for electric system type-approval acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Technology Licensing Partnership | Electric drive scaling through Bosch Rexroth and Syncrolift AS production agreements accelerates greenfield deployment. |
| Backward Integration | Captive high-tensile steel supply from German and Japanese mills insulates against tariff volatility. |
| Certification Pre-Investment | Early Lloyd's Register cyber-physical system compliance creates competitive exclusion for laggards. |
| Geographic Capacity Placement | Manufacturing footprint in Gujarat and Maharashtra secures Indian defense-civilian dual-use procurement. |
| Service Contract Unbundling | Performance-based agreements separate equipment margins from recurring predictive maintenance revenue. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with shipyard maintenance directors, naval procurement officers, port authority engineering leads, and aftermarket service heads, validated against Lloyd's Register certification databases, DNV offshore lifting standards documentation, Korean MFDS marine equipment safety filings, and Indian BIS structural steel certification records, with bottom-up installation data triangulated against top-down market sizing.
Calibration against historical procurement volumes and announced greenfield capacity investments anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, drive train technology, application intensity, and end-user capability profile. CAGRs were derived from slope analysis of technology substitution curves and naval modernization program commitments. Industry-specific forecast inputs encompass NATO fleet renewal timelines and South Korean dry-docking capacity expansion announcements.
Stress conditions across tariff exposure on German and Japanese steel inputs, DNV certification timeline extensions, and graving dock substitution economics were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions concerning electrification adoption velocity and classification society update implementation. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Spiral Fitting Machines Market
Material Handling Equipment
Sweep Depalletizers Market
Material Handling Equipment
Log Loaders Market
Material Handling Equipment
Global Loading Dock Bumpers Market
Material Handling Equipment
Japan Conveyor Belt Market
Material Handling Equipment
Log Stackers Market
Material Handling Equipment
Eye and Eye Turnbuckle Market
Material Handling Equipment
Truck Loader Crane Market
Material Handling Equipment
Hook Loader Market
Material Handling Equipment
Cherry Picker Crane Market
Material Handling Equipment
Hoist Market
Material Handling Equipment
Automatic Conveyor Market
Material Handling Equipment
North America Forklift Market
Material Handling Equipment
Loaded Container Handler Market
Material Handling Equipment
Material Handling Monorails Market
Material Handling Equipment
Global Tension Control Market