
 Attention Deficit Hyperactivity Disorder (ADHD) Therapeutics Market | 2026-2036
Attention Deficit Hyperactivity Disorder (ADHD) Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Attention Deficit Hyperactivity Disorder (ADHD) Therapeutics Market Analytics
Market Context
Fragmentation across pediatric specialty clinics and telehealth platforms is repositioning how ADHD therapeutics reach end users. Eli Lilly and Company leverages its long-acting methylphenidate portfolio to sustain loyalty among institutional prescribers. Takeda Pharmaceutical Company anchors its presence through Vyvanse distribution networks that dominate the adult indication segment. Novartis AG competes with an established Ritalin franchise that still occupies substantial formulary slots across European hospital systems.
Technical Definition and Segment Structure
Attention Deficit Hyperactivity Disorder therapeutics comprise pharmacological agents that modulate dopamine and norepinephrine transmission to improve executive function, impulse control, and sustained attention in diagnosed patients. Stimulant formulations—methylphenidate and amphetamine salts—remain the first-line intervention, manufactured through controlled chemical synthesis under strict DEA and EMA quotas. The stimulant product category still leads in prescription volume, though the non-stimulant segment is capturing margin pools as adult patients seek alternatives with lower abuse liability. Pediatric indication demand dominates absolute patient numbers, yet the adult indication segment is expanding fastest as retrospective diagnosis trends accelerate in working-age populations across developed economies.
Regulatory Framework and Outlook
The FDA, DEA, and EMA collectively govern ADHD therapeutic access through controlled substance scheduling, manufacturing quotas, and pediatric study requirements that constrain supply elasticity. The FDA's Risk Evaluation and Mitigation Strategy for stimulants shapes prescriber behavior and pharmacy dispensing protocols, while the DEA's annual production quota system directly limits commercial volume expansion. Stakeholders must monitor how evolving digital therapeutics regulations and telehealth prescribing rules reshape patient acquisition economics and formulary positioning.
Market Dynamics
The DEA's annual production quota system for Schedule II stimulants creates artificial supply scarcity that distorts prescribing patterns and pharmacy inventory management across the United States. This regulatory bottleneck forces manufacturers to allocate limited active pharmaceutical ingredient stocks across competing formulations while patients face intermittent shortages of first-line therapies.
Growth Catalysts
- Adult diagnostic expansion:Retrospective ADHD identification in working-age populations drives new patient enrollment in employer-sponsored health plans and telehealth platforms.
- Telehealth prescribing flexibility:Post-pandemic regulatory accommodations for remote controlled-substance evaluation broaden prescriber reach into underserved rural counties and secondary metropolitan areas.
- Non-stimulant pipeline maturation:Novel norepinephrine reuptake inhibitors and alpha-2A agonist formulations diversify therapeutic options for patients with stimulant intolerance or substance-use histories.
Market Restraints
- API supply concentration:Bulk methylphenidate and amphetamine salt production concentrates among three specialized chemical manufacturers in India and China, exposing formulations to export licensing delays.
- DEA quota rigidity:The Drug Enforcement Administration's annual manufacturing allotment system prevents rapid volume response to demand surges, creating predictable shortage cycles during academic calendar peaks.
- Abuse liability stigma:Persistent concerns about stimulant diversion and non-medical use among college-age populations sustain prescriber conservatism and institutional formulary restrictions.
Strategic Opportunities
- Digital therapeutics integration:FDA-cleared prescription digital therapeutics for ADHD symptom management create combination therapy protocols that differentiate clinic service lines and capture recurring revenue streams.
- Employer-sponsored screening:Workplace productivity programs and occupational health contracts offer direct-to-employer channels that bypass traditional payer gatekeeping for adult diagnosis and treatment initiation.
- Long-acting formulation substitution:Once-daily extended-release stimulants and prodrug designs reduce pharmacy visit frequency and improve adherence metrics for value-based care contracts.
Industry Challenges
- Pediatric trial recruitment:FDA-mandated juvenile toxicity studies face enrollment bottlenecks and extended timelines that delay label expansion for new molecular entities.
- Controlled substance logistics:Specialized warehousing, dual-lock transportation, and serialized dispensing infrastructure impose fixed cost burdens that disadvantage smaller regional pharmacy networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Attention Deficit Hyperactivity Disorder (ADHD) Therapeutics Market |
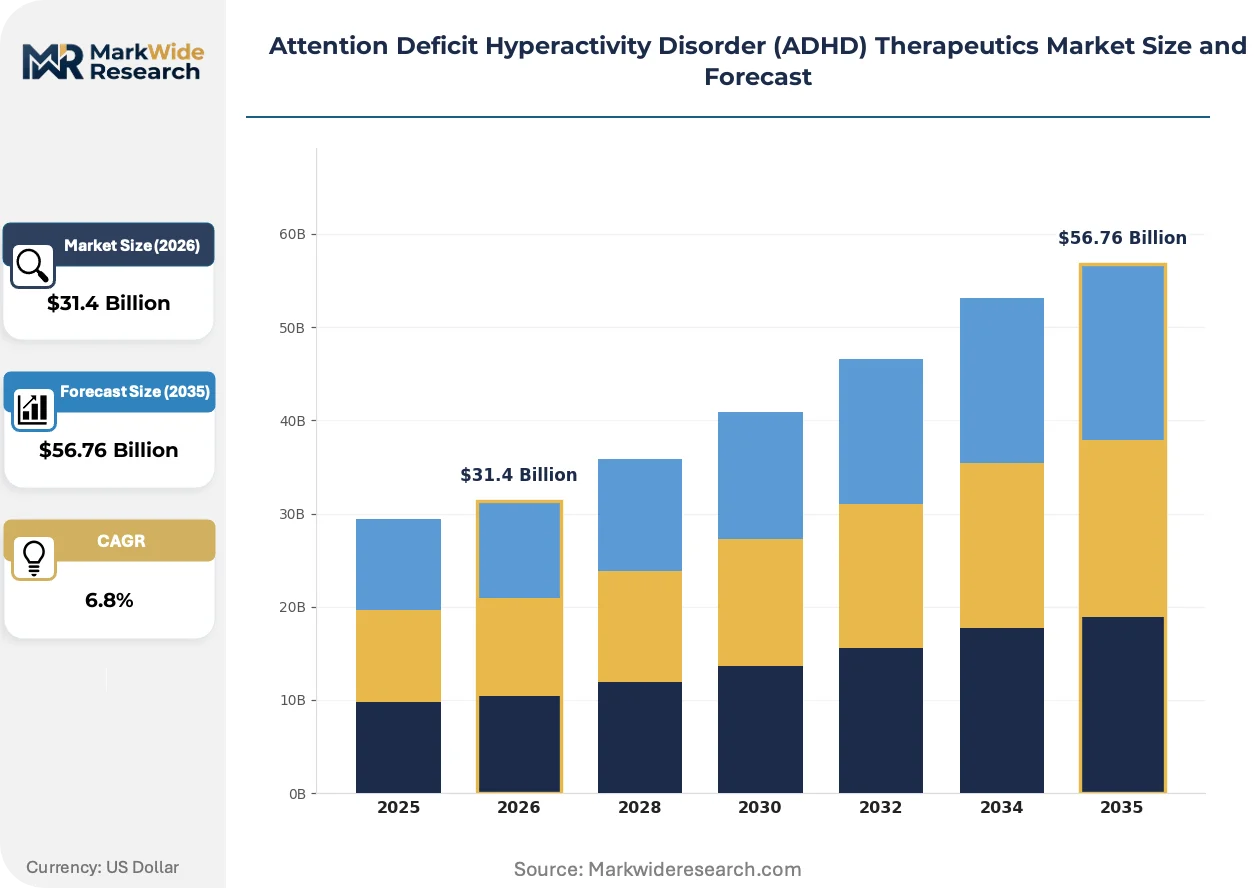
| Market Size in 2026 | $31.4 Billion |
| Market Size in 2035 | $56.76 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stimulants, Non-Stimulants, Antidepressants, Antipsychotics Indication: Pediatric, Adult, Combination Therapy, Additional Comorbidities Delivery Mode: Oral, Transdermal, Injectable, Inhalation End User: Hospitals, Clinics, Homecare, Specialty Pharmacies |
| Companies Covered | Novartis AG, Eli Lilly and Company, Johnson & Johnson, Takeda Pharmaceutical Company, Pfizer, Supernus Pharmaceuticals, Neos Therapeutics, Tris Pharma, Lupin, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Attention Deficit Hyperactivity Disorder (ADHD) Therapeutics Market Evolving Landscape
Pharmacogenomic guidance and biomarker-assisted dosing are displacing empirical titration protocols that dominated ADHD management for decades. These precision approaches promise to reduce adverse event rates and accelerate therapeutic optimization in heterogeneous patient populations.
Transdermal methylphenidate delivery systems are expanding into school-age populations where oral medication administration during instructional hours creates logistical friction. School nurses and pediatric practices in the United States and Germany are adopting patch-based alternatives to circumvent midday dosing disruptions. This modality is expanding into previously underserved patient segments that oral formulations failed to retain.
EMA's updated pediatric investigation plan requirements now mandate long-term neurodevelopmental outcome tracking for all novel ADHD therapeutics seeking European market authorization. This regulatory elevation extends trial duration and increases post-marketing surveillance obligations for sponsors. The stimulant segment faces disproportionate compliance burden as legacy products undergo retrospective safety reassessment under modern pharmacovigilance standards.
Direct-to-consumer diagnostic platforms and employer wellness integrations are compressing the traditional specialist referral pathway for adult ADHD evaluation. Primary care physicians and telehealth prescribers now initiate treatment without formal neuropsychological assessment in integrated health systems across California, Texas, and Florida. This channel migration is most visible among technology sector employees and independent contractors seeking rapid credentialing for workplace accommodation requests.
Attention Deficit Hyperactivity Disorder (ADHD) Therapeutics Market Segmentation
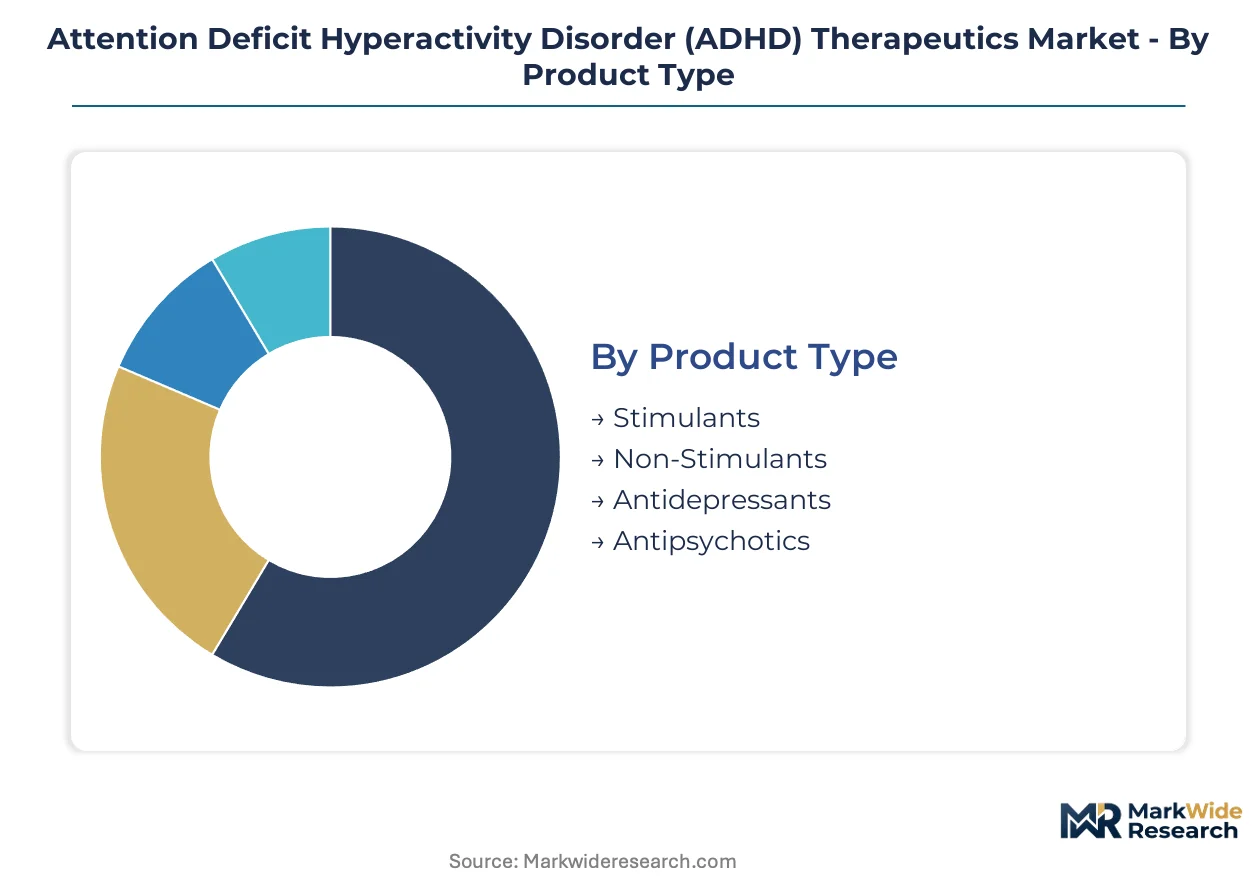
ADHD therapeutics segmentation reveals how prescriber preferences, regulatory constraints, and patient life-stage requirements fragment commercial opportunity across incompatible product-positioning strategies. Manufacturers must align formulation investments with specific channel access rules and reimbursement gatekeepers that vary dramatically by segment.
Product Type:
Prescriber risk tolerance and institutional formulary policies drive selection between controlled and non-controlled therapeutic classes, with DEA scheduling status overriding clinical efficacy considerations in many procurement decisions.
- Stimulants:Methylphenidate and amphetamine salt formulations modulate dopamine and norepinephrine transmission through controlled substance synthesis under strict DEA and EMA quotas. Demand concentrates in United States institutional formularies where long-acting formulations command preferred tier placement, though DEA quota rigidity creates predictable shortage cycles during academic calendar peaks.
- Non-Stimulants:Atomoxetine, guanfacine, and clonidine formulations target norepinephrine reuptake or alpha-2A adrenergic receptors without Schedule II classification. Adult patients in employer-sponsored plans increasingly select this category to avoid controlled-substance monitoring requirements and workplace credentialing friction.
- Antidepressants:Bupropion and tricyclic compounds prescribed off-label for ADHD symptoms in patients with comorbid mood disorders.
- Antipsychotics:Aripiprazole and risperidone adjuncts reserved for severe behavioral dyscontrol with tic or aggression comorbidities.
Stimulants lead on scale; non-stimulants lead on momentum.
Indication:
Patient age at diagnosis determines reimbursement pathway, prescriber specialty, and therapeutic duration, with adult-onset evaluation bypassing traditional pediatric neurodevelopmental assessment infrastructure.
- Pediatric:School-age diagnosis through age 17 dominates absolute patient enrollment and drives seasonal demand patterns aligned with academic calendars. United States pediatric psychiatry clinics and school-based health centers in Texas, Florida, and California generate concentrated prescription volume for extended-release formulations.
- Adult:Retrospective diagnosis in working-age populations accelerates through telehealth platforms and employer wellness programs, with direct-to-consumer evaluation compressing traditional specialist referral timelines. Technology sector employees and independent contractors seeking workplace accommodation credentials fuel steepest expansion trajectory.
- Combination Therapy:Stimulant plus behavioral intervention or pharmacologic adjunct protocols for treatment-resistant presentations.
- Additional Comorbidities:Anxiety, depression, or substance-use disorder modifications to standard therapeutic regimens.
Pediatric captures volume concentration; adult captures growth acceleration.
Delivery Mode:
Administration logistics and patient autonomy requirements shape formulation selection, with school and workplace constraints driving innovation in discreet or extended-interval dosing technologies.
- Oral:Immediate-release and extended-release tablets and capsules constitute the dominant administration format, with once-daily prodrug designs reducing pharmacy visit frequency for value-based care contracts. United States retail and specialty pharmacy networks prioritize oral inventory given reimbursement familiarity and patient preference.
- Transdermal:Methylphenidate patches circumvent midday dosing disruptions in school-age populations where oral administration during instructional hours creates logistical friction. School nurses in Germany and United States districts adopt patch-based alternatives for previously non-adherent patients.
- Injectable:Long-acting depot formulations for severe adherence challenges or forensic psychiatric settings.
- Inhalation:Investigational dry-powder stimulant delivery systems targeting rapid onset with reduced abuse liability.
Oral formulations dominate accessibility; transdermal systems gain share fastest in institutional pediatric settings.
End User:
Site-of-care regulations and controlled-substance dispensing infrastructure determine channel economics, with specialized logistics requirements disadvantaging smaller regional pharmacy networks.
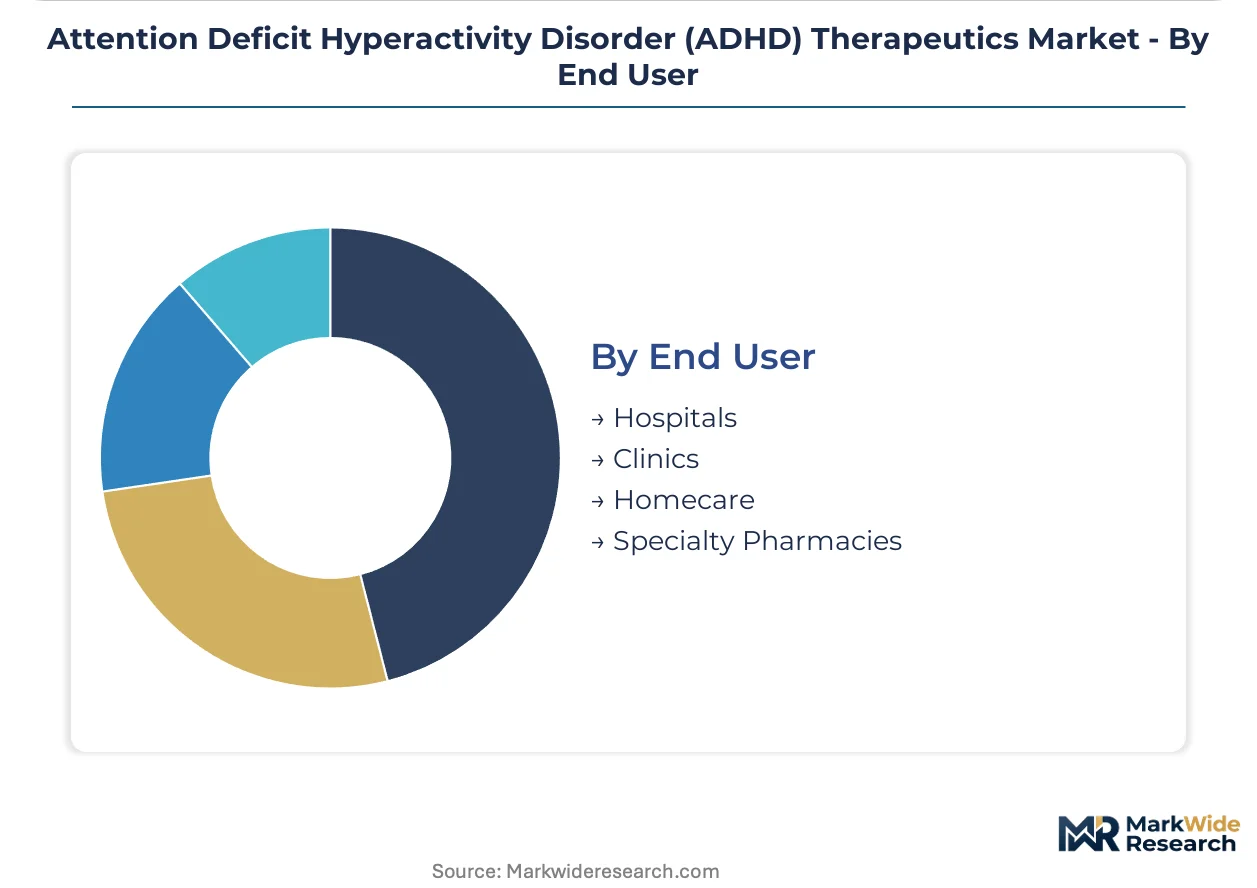
- Hospitals:Inpatient psychiatric units and emergency departments manage acute agitation and initial diagnostic workup, with formulary committees prioritizing long-acting injectables for severe presentations. European hospital systems maintain Ritalin franchise placement for legacy protocol compliance.
- Clinics:Pediatric psychiatry and adult ADHD specialty practices initiate and titrate therapy, with telehealth platforms expanding prescriber reach into underserved rural counties. Post-pandemic regulatory accommodations for remote controlled-substance evaluation reshape patient acquisition economics.
- Homecare:Direct-to-patient dispensing for stable maintenance therapy with established adherence documentation.
- Specialty Pharmacies:Controlled-substance warehousing and serialized dispensing infrastructure for high-abuse-liability formulations.
Clinics anchor prescription initiation volume; specialty pharmacies capture margin concentration on restricted-distribution products.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States diagnosis rates substantially outpace German patient enrollment, while India's emerging market infrastructure constrains comparable therapeutic access despite comparable prevalence estimates.
United States
Pediatric psychiatry clinics in Texas, Florida, and California drive concentrated prescription volume for extended-release stimulant formulations. The FDA's Risk Evaluation and Mitigation Strategy shapes prescriber behavior through controlled-substance monitoring requirements. Telehealth platforms in secondary metropolitan areas expand prescriber reach into underserved rural counties.
Germany
School-based health centers adopt transdermal methylphenidate patches to circumvent midday dosing disruptions during instructional hours. EMA pediatric investigation plan requirements mandate long-term neurodevelopmental outcome tracking for novel therapeutics. Hospital systems in Bavaria and North Rhine-Westphalia maintain legacy Ritalin franchise placement for protocol compliance.
United Kingdom
Adult retrospective diagnosis accelerates through employer wellness programs and direct-to-consumer evaluation platforms. NHS formulary committees prioritize non-stimulant alternatives to reduce controlled-substance dispensing infrastructure costs. London and Southeast England concentrate specialist referral capacity for complex comorbid presentations.
India
Bulk methylphenidate and amphetamine salt active pharmaceutical ingredient production concentrates among specialized chemical manufacturers in Maharashtra and Gujarat. CDSCO regulatory pathways for controlled substances create extended timelines for imported formulation market authorization. Domestic manufacturers in Telangana and Karnataka expand generic stimulant production for export markets.
Japan
PMDA scheduling restrictions on stimulant therapeutics sustain non-stimulant preference among institutional prescribers. Workplace productivity programs in Tokyo and Osaka metropolitan areas drive adult diagnostic expansion through occupational health contracts. Kansai region clinics pioneer pharmacogenomic guidance integration into empirical titration protocols.
Attention Deficit Hyperactivity Disorder (ADHD) Therapeutics Market Competitive Landscape
United States pharmaceutical conglomerates anchor the stimulant formulation tier; Swiss and Japanese specialists hold positions in non-stimulant and long-acting delivery technologies. The vendor base concentrates around legacy central nervous system franchises with established DEA quota allocations and institutional formulary relationships. Three strategic archetypes dominate: vertically integrated API-to-formulation manufacturers, prodrug and extended-release technology licensors, and regional generic specialists with quota-advantaged production capacity. Competitive moves center on long-acting formulation substitution to capture value-based care contracts and digital therapeutics integration to differentiate clinic service lines.
Within the established franchise tier, Novartis AG and Eli Lilly and Company exemplify divergent strategic positioning. Novartis anchors European hospital system loyalty through its Ritalin franchise and legacy protocol compliance. Eli Lilly leverages its long-acting methylphenidate portfolio to sustain institutional prescriber relationships across North American formularies. Takeda Pharmaceutical Company occupies a distinct position in the adult indication segment through Vyvanse distribution network concentration.
| Leading Market Players |
|---|
| Novartis AG |
| Eli Lilly and Company |
| Johnson & Johnson |
| Takeda Pharmaceutical Company |
| Pfizer |
| Supernus Pharmaceuticals |
| Neos Therapeutics |
| Tris Pharma |
| Lupin |
| Others |
Value Network & Pricing Analysis
Long-acting methylphenidate formulation transitions toward once-daily prodrug designs simultaneously compress manufacturing cost curves and concentrate active pharmaceutical ingredient sourcing among DEA-quota-advantaged producers in India and the United States, creating asymmetric pricing power across institutional formularies and retail pharmacy networks.
Pricing Analysis
Capacity additions in Telangana and Karnataka are reshaping price floors for generic stimulant formulations as Indian API manufacturers expand methylphenidate bulk production for export markets. Pricing stratifies across branded extended-release, authorized generic, and commodity immediate-release tiers, with DEA quota scarcity sustaining premium capture for quota-holding incumbents. Cost compression in the immediate-release segment intensifies because of import substitution from domestic Indian manufacturers. Employer-sponsored health plans exhibit highest price sensitivity; specialty pharmacy networks show lowest due to controlled-substance dispensing infrastructure requirements.
Supply Chain Analysis
Dual-sourcing qualification mandates from United States retail pharmacy chains and European hospital systems force formulation sponsors to maintain redundant API supplier relationships across India and China despite concentration economics favoring single-source contracts. Bulk methylphenidate and amphetamine salt production draws from specialized chemical manufacturers in Maharashtra, Gujarat, and select coastal Chinese provinces. Single-source vulnerability persists where DEA quota allocations tether to specific manufacturing sites. Distribution runs through serialized controlled-substance warehouses to dual-lock pharmacy infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between United States DEA quota constraints and Indian CDSCO export licensing timelines creates margin capture opportunities for manufacturers with quota-advantaged production capacity and established international distribution infrastructure.
For Market Incumbents: To counter non-stimulant pipeline maturation from norepinephrine reuptake inhibitor specialists, incumbents should deepen backward integration into long-acting formulation technologies and secure digital therapeutics FDA clearances for combination therapy protocols that differentiate clinic service lines and lock in institutional formulary placement. For New Entrants and Emerging Players: FDA's updated guidance on controlled substance prescribing in the United States opens a window for telehealth-integrated diagnostic platforms that compress traditional specialist referral pathways. The most penetrable white-space sits in employer-sponsored adult screening programs and direct-to-consumer evaluation platforms in Texas, Florida, and California. A go-to-market angle anchored in workplace productivity credentialing bypasses traditional payer gatekeeping. For Investors and Strategic Acquirers: Valuations sit cheapest among regional generic specialists with quota-advantaged production capacity and limited formulation differentiation. Long-term viability over the coming decade hinges on DEA quota allocation stability and pediatric indication label expansion. The signal to watch as inflection indicator is EMA pediatric investigation plan requirement enforcement intensity for novel therapeutic submissions.| Strategic Initiative | Industry Significance |
|---|---|
| Long-Acting Formulation Substitution | Once-daily prodrug designs reduce pharmacy visit frequency for value-based care contracts. |
| Digital Therapeutics Integration | FDA-cleared prescription digital therapeutics create recurring revenue streams for clinic service lines. |
| API Manufacturing Scale-Up | DEA quota-advantaged capacity expansion in India secures supply security for export markets. |
| Telehealth Prescribing Platform | Remote controlled-substance evaluation broadens prescriber reach into underserved rural counties. |
| Pharmacogenomic Guidance Development | Biomarker-assisted dosing protocols displace empirical titration and reduce adverse event rates. |
Research Methodology
Direct dialogue with pediatric psychiatry clinic directors, formulary committee chairs at United States hospital systems, DEA quota allocation specialists, Indian API manufacturing executives, and European EMA regulatory affairs leads grounded qualitative findings, cross-validated against FDA controlled substance filings, ClinicalTrials.gov pediatric investigation plans, DEA annual production quota publications, and European hospital procurement databases through bottom-up and top-down triangulation.
Bottom-up modeling anchored volume and value outputs across the projection horizon through treatment line, dosage form, patient population, and regional regulatory cluster segmentation dimensions. CAGRs derived from historical prescription volume trajectories, quota allocation trends, and adult diagnostic expansion rates in employer-sponsored plans. Key forecast inputs included DEA manufacturing quota elasticity assumptions and telehealth prescribing regulatory accommodation persistence.
Revisions become necessary when DEA quota allocation methodology shifts, EMA pediatric investigation plan requirements escalate, or major API manufacturing jurisdictions impose export licensing restrictions materialize. Deviation in controlled substance scheduling policy or digital therapeutics reimbursement determination would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmacology
Intranasal Drug and Vaccine Delivery Market
Pharmacology
Propranolol Drug Market
Pharmacology
Anti-Obesity Therapeutics Market
Pharmacology
Ketoprofen API Market
Pharmacology
Anti-Hypertensive Drugs Market
Pharmacology
Hypertension Drug Market
Pharmacology
Cough Remedies Market
Pharmacology
Global Migraine Therapeutics Market
Pharmacology
Prescription Narcotic Cough Preparations and Expectorants Market
Pharmacology
Hyperkalemia Drugs Market
Pharmacology
Drug Repurposing Market
Pharmacology
Aspirin API Market
Pharmacology
Angiotensin II Receptor Blockers (Arbs) Market
Pharmacology
Pegylated Drugs Market
Pharmacology
Alzheimer Drugs Market
Pharmacology
Anti Inflammatory Therapeutics Market