
 Hyperkalemia Drugs Market | 2026-2036
Hyperkalemia Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Hyperkalemia Drugs Market Outlook
Hospital procurement channels for hyperkalemia therapies are reshaping competitive access across integrated delivery networks. AstraZeneca leverages its cardiovascular franchise infrastructure to sustain formulary positioning in major health systems. CSL Vifor anchors its presence through nephrology specialty distribution, while Ardelyx competes on the basis of differentiated mechanism of action in the outpatient setting.
Hyperkalemia drugs encompass pharmaceutical agents that modulate serum potassium levels through binding, excretion, or intracellular shift mechanisms, with sodium zirconium cyclosilicate and patiromer representing non-absorbed polymer-based binders engineered for selective potassium capture in the gastrointestinal tract. These agents serve the clinical imperative of preventing life-threatening cardiac arrhythmias in patients with renal insufficiency, heart failure, or RAAS inhibitor therapy. Oral tablets dominate volume due to chronic maintenance indications, while intravenous formulations retain priority in emergency medicine and acute care settings where rapid potassium reduction is essential. Cardiology and nephrology therapy areas concentrate the deepest margin pools, reflecting longitudinal patient relationships and recurring prescription patterns.
The FDA maintains stringent cardiovascular safety evaluation standards for novel hyperkalemia agents, while the EMA's MDR framework imposes additional post-market surveillance obligations across European markets. Health Canada and TGA align with ICH efficacy benchmarks, creating a convergent but jurisdictionally fragmented approval landscape. Stakeholders must monitor evolving label expansions for heart failure populations and the integration of potassium binders into value-based renal care contracts.
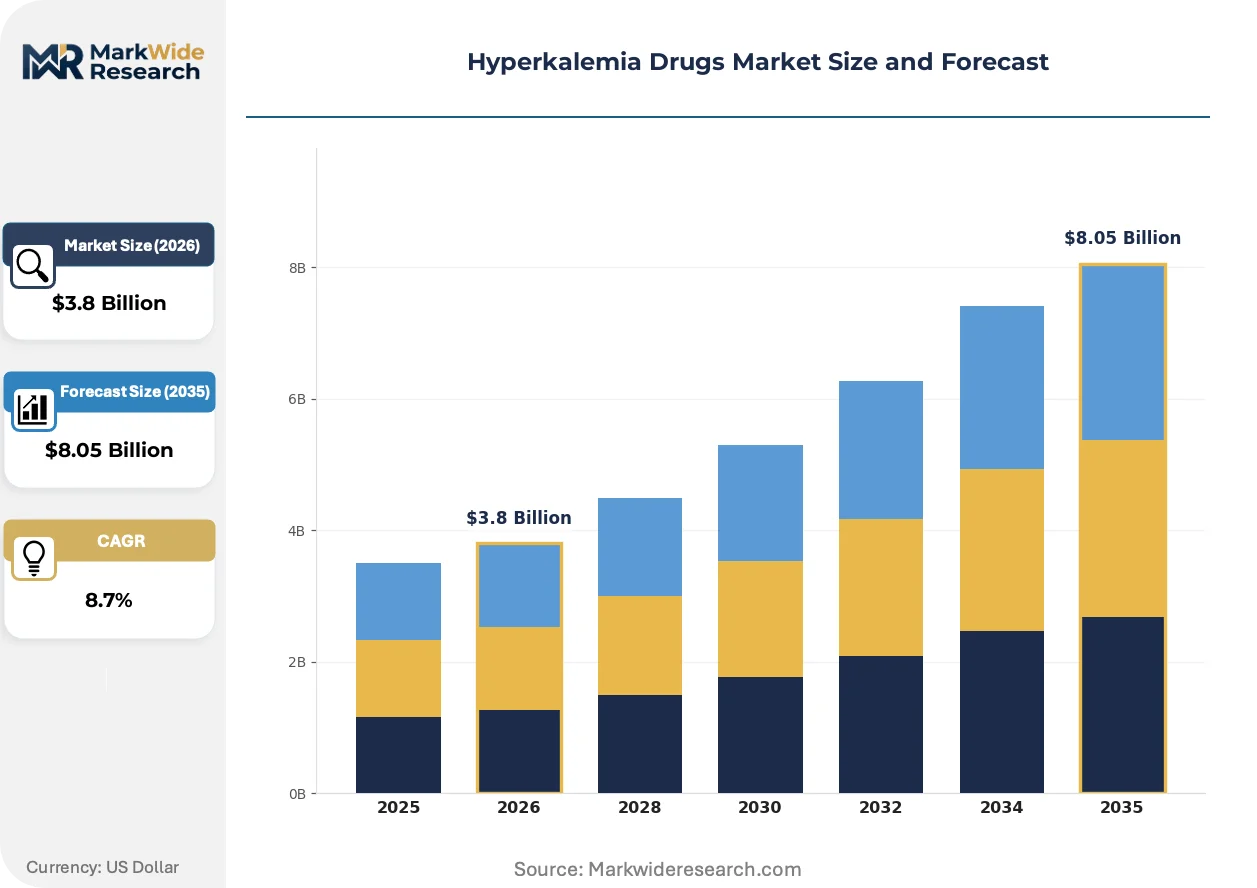
Market Dynamics
Hospital procurement consolidation is reshaping access pathways for hyperkalemia therapies, as integrated delivery networks centralize formulary decisions around cardiovascular outcome data and long-term cost modeling rather than unit pricing alone.
Growth Catalysts
- RAAS Inhibitor Expansion:Cardiology guidelines now endorse broader renin-angiotensin-aldosterone system inhibitor use in heart failure, expanding the addressable patient pool requiring potassium management support.
- EMA MDR Framework:Europe's strengthened post-market surveillance requirements for medical devices and drug-device combinations are accelerating evidence generation for oral binder safety profiles.
- Dialysis Center Density:United States end-stage renal disease facility expansion in Medicare Advantage networks is creating dedicated channels for chronic hyperkalemia therapy initiation.
Market Restraints
- API Supply Concentration:Zirconium silicate raw material processing concentrates among Chinese specialty chemical manufacturers, exposing formulation supply to geopolitical friction.
- FDA Cardiovascular Outcome Trial Burden:The agency's mandatory safety database requirements for novel potassium binders extend development timelines and inflate registration costs.
- Generic Sodium Polystyrene Sulfonate:Low-cost resin-based alternatives retain emergency department formulary slots, constraining premium oral binder penetration in acute care.
Strategic Opportunities
- Japan's Aging Dialysis Population:PMDA's streamlined review pathways for drugs addressing unmet nephrology needs offer faster market entry than US or EU equivalents.
- Remote Patient Monitoring Integration:Home potassium testing devices paired with digital therapeutics platforms enable proactive dose adjustment and reduce hospitalization events.
- India's PLI Scheme:Production-linked incentives for active pharmaceutical ingredient manufacturing are attracting contract development partners for polymer synthesis capabilities.
Industry Challenges
- Clinical Pharmacology Talent Scarcity:Nephrology-focused drug development expertise concentrates among a limited set of contract research organizations, creating bidding pressure for trial execution.
- Legacy EHR Integration:Hospital system electronic health record architectures require custom potassium alert buildouts to support real-time binder prescribing decision support.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hyperkalemia Drugs Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Potassium Binders, Diuretics, Parrent Beverages, Supplements Therapy Area: Cardiology, Nephrology, Endocrinology, Emergency Medicine Delivery Mode: Intravenous, Oral Tablets, Subcutaneous, Inhalation End User: Hospitals, Outpatient Clinics, Home Care, Rehabilitation Centers |
| Companies Covered | AstraZeneca, CSL Vifor, Sanofi, Ardelyx, Perrigo Company, Vifor Pharma, ZS Pharma, Bayer, KVK-Tech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hyperkalemia Drugs Market Strategic Shifts
Novel polymer engineering is expanding the therapeutic index of gastrointestinal potassium binders, while regulatory pressure for real-world evidence is compressing traditional clinical development paradigms across major markets.
Next-generation zirconium silicate formulations are hybridizing crystalline structure design with controlled-release polymer coatings to improve palatability and reduce pill burden. Nephrology practices in Medicare Advantage networks are piloting these enhanced formulations for medication adherence programs. The technology is hybridizing chronic disease management protocols by enabling once-daily dosing regimens that align with value-based renal care contracts.
REACH authorization requirements for polymer manufacturing byproducts are tightening environmental release standards for European production facilities. ECHA's expanded substance evaluation obligations now capture residual monomer content in finished drug products. German and French manufacturing sites are responding by retrofitting purification systems ahead of 2026 compliance deadlines.
Specialty pharmacy distribution is displacing traditional wholesale channels for outpatient hyperkalemia maintenance therapy. Payers are mandating 90-day dispensing through limited network pharmacies to capture adherence rebates and reduce emergency utilization. This channel migration is most advanced in United States commercial insurance segments, where pharmacy benefit managers have carved out nephrology therapeutics for exclusive distribution arrangements.
Hyperkalemia Drugs Market Segmentation
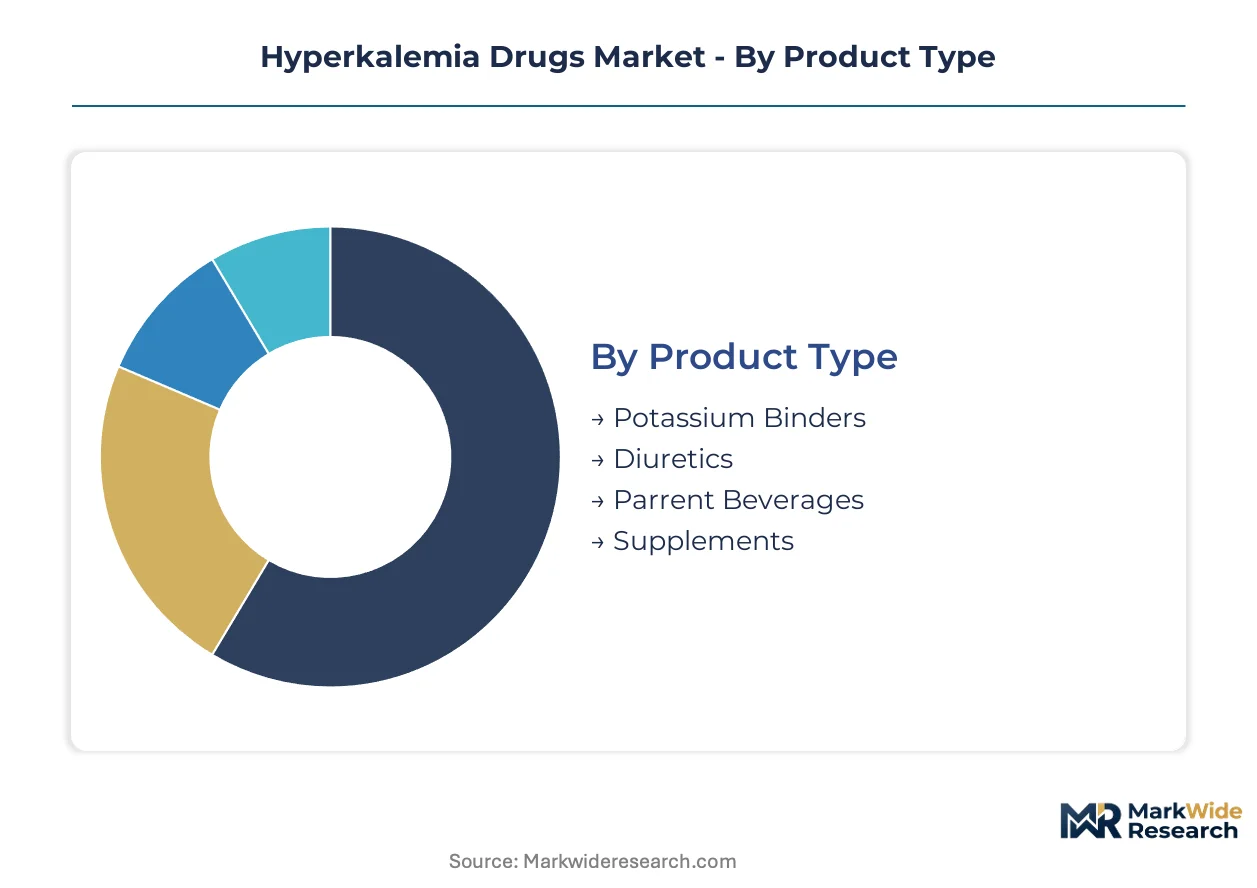
Hyperkalemia drug segmentation reveals divergent margin profiles across therapeutic modalities. Product formulation and care setting determine reimbursement pathways, prescribing authority, and competitive intensity for each category.
Product Type:
After-sales service intensity varies sharply across product categories, with polymer-based binders requiring specialized patient education programs and adherence monitoring support.
- Potassium Binders:Sodium zirconium cyclosilicate and patiromer polymers operate through non-systemic gastrointestinal ion exchange. United States nephrology practices drive demand concentration as Medicare Advantage networks expand chronic disease management protocols for dialysis populations.
- Diuretics:Loop and thiazide agents promote renal potassium excretion through established pharmacological mechanisms. Cardiology departments in integrated delivery networks favor these for acute hyperkalemia episodes where rapid onset offsets binding agent lag time.
- Parent Beverages:Oral rehydration formulations with potassium-binding adjuncts serve transitional care settings.
- Supplements:Dietary potassium management products address mild elevation prevention in outpatient monitoring programs.
Potassium binders hold the largest share; momentum sits with diuretics as emergency protocols prioritize speed-to-effect.
Therapy Area:
Cost tier stratification separates chronic maintenance indications from acute intervention protocols across clinical specialties.
- Cardiology:Heart failure populations on RAAS inhibitors generate recurring demand for prophylactic potassium management. German hospital systems are embedding binder initiation protocols into post-acute discharge bundles for reduced 30-day readmission rates.
- Nephrology:End-stage renal disease patients require longitudinal potassium control as dialysis frequency alone proves insufficient. Japanese dialysis center networks are piloting home-based binder dispensing to reduce facility congestion.
- Endocrinology:Diabetic nephropathy patients with potassium-sparing medication regimens represent an emerging addressable population.
- Emergency Medicine:Acute hyperkalemia with electrocardiographic changes demands intravenous calcium and insulin-glucose protocols where binders play adjunctive roles.
Cardiology commands premium pricing; nephrology is climbing the fastest as value-based renal care contracts expand.
Delivery Mode:
Application requirements dictate formulation selection, with acute versus chronic use cases driving route-of-administration decisions.
- Intravenous:Calcium gluconate and insulin-glucose infusions provide immediate cardiac membrane stabilization. United States emergency departments retain these formulations as first-line for life-threatening arrhythmia prevention despite hospital formulary cost pressures.
- Oral Tablets:Polymer-based binders in tablet or powder form enable outpatient chronic maintenance. Australian nephrology practices are transitioning stable patients to 90-day dispensing models through specialty pharmacy channels.
- Subcutaneous:Novel depot formulations in development aim to reduce dosing frequency for non-adherent populations.
- Inhalation:Investigational aerosolized potassium modulators target rapid systemic absorption without gastrointestinal transit delays.
Oral tablets dominate prescription volume; subcutaneous delivery shows steepest expansion trajectory in clinical pipelines.
End User:
Customer type determines procurement channel, with institutional buyers commanding price concessions unavailable to retail dispensers.
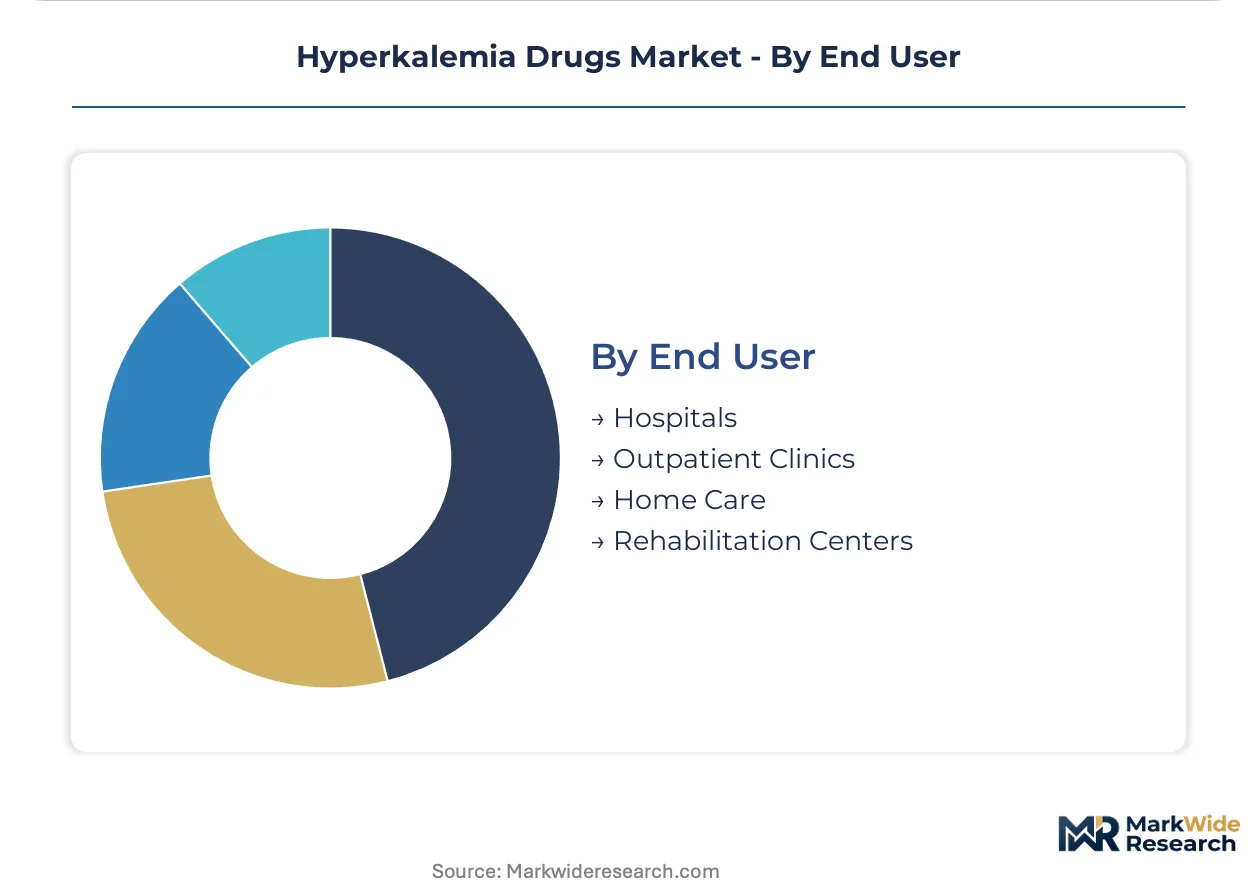
- Hospitals:Integrated delivery networks centralize formulary decisions around cardiovascular outcome data and long-term cost modeling rather than unit pricing alone. United States health systems are consolidating nephrology therapeutics into standardized protocols across affiliated facilities.
- Outpatient Clinics:Independent nephrology practices and cardiology groups prescribe maintenance binders with prior authorization requirements varying by payer. French clinic networks are adopting digital adherence monitoring platforms to demonstrate outcomes for regional health authority contracts.
- Home Care:Skilled nursing and home health agencies administer binders for post-acute patients with mobility limitations.
- Rehabilitation Centers:Subacute facilities manage potassium levels during cardiac recovery protocols.
Hospitals capture the largest share; home care is gaining share fastest as remote patient monitoring enables safe community-based management.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States, where Medicare Advantage networks and integrated delivery systems extract volume rebates that compress margins unavailable to European hospital buyers operating under centralized health technology assessment frameworks.
United States
Dialysis-dependent populations and heart failure comorbidities drive sustained prescribing volume for oral potassium binders. The FDA's cardiovascular outcome trial requirements reshape clinical development pathways for novel therapies. Hospital-based nephrology departments in the Southeast and Midwest are expanding adoption of chronic hyperkalemia management protocols.
Germany
Heart failure populations on RAAS inhibitors generate recurring demand for prophylactic potassium management. EMA's MDR framework imposes additional post-market surveillance obligations for polymer-based binders. Hospital systems in Bavaria and North Rhine-Westphalia embed binder initiation protocols into post-acute discharge bundles.
Japan
Aging dialysis populations expand the addressable patient pool for chronic hyperkalemia therapies. PMDA's streamlined review pathways for drugs addressing unmet nephrology needs offer faster market entry than US equivalents. Dialysis center networks in the Kanto region pilot home-based binder dispensing to reduce facility congestion.
France
Independent nephrology practices and cardiology groups prescribe maintenance binders with prior authorization requirements varying by regional health authority. ECHA's REACH authorization requirements tighten environmental release standards for zirconium silicate manufacturing. Clinic networks in Île-de-France adopt digital adherence monitoring platforms to demonstrate outcomes for regional contracts.
India
Production-linked incentives for active pharmaceutical ingredient manufacturing attract contract development partners for polymer synthesis capabilities. CDSCO aligns with ICH efficacy benchmarks for hyperkalemia drug approvals. Manufacturing clusters in Maharashtra and Gujarat retrofit purification systems to meet residual monomer content standards for export markets.
Hyperkalemia Drugs Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in the supply chain. The market structure consolidates around cardiovascular franchise operators with nephrology specialty distribution capabilities. Three archetypes dominate: large-cap pharmaceutical conglomerates with hospital formulary leverage, mid-cap nephrology-focused developers with differentiated mechanisms, and generic resin manufacturers competing on emergency department unit cost. Competitive moves center on formulary positioning through cardiovascular outcome data and specialty pharmacy channel exclusivity arrangements.
Within the large-cap platform tier, AstraZeneca leverages its cardiovascular franchise infrastructure to sustain formulary positioning in major health systems. CSL Vifor anchors its presence through nephrology specialty distribution. Ardelyx occupies a position competing on the basis of differentiated mechanism of action in the outpatient setting.
| Leading Market Players |
|---|
| AstraZeneca |
| CSL Vifor |
| Sanofi |
| Ardelyx |
| Perrigo Company |
| Vifor Pharma |
| ZS Pharma |
| Bayer |
| KVK-Tech |
| Others |
Value Chain & Pricing Dynamics
Shanghai-to-Rotterdam container freight corridors carry zirconium silicate precursor shipments whose rate volatility feeds directly into polymer manufacturing cost structures and downstream binder pricing tiers across European hospital procurement networks.
Pricing Analysis
Customization-premium spreads separate standard sodium zirconium cyclosilicate tablets from patient-adherence program bundles that incorporate remote monitoring and specialty pharmacy counseling services. Three-tier pricing structure across premium, standard, and economy levels reflects FDA cardiovascular outcome trial certification status and volume commitment scale. Cost compression in the emergency department resin segment intensifies because generic sodium polystyrene sulfonate retains formulary slots despite inferior safety profiles. Dialysis-dependent populations in Medicare Advantage networks demonstrate lowest price sensitivity due to value-based renal care contract bundling.
Supply Chain Analysis
Supplier-financing facilities from Chinese specialty chemical manufacturers extend 180-day payment terms to formulation partners, easing working capital pressure for zirconium silicate polymer producers. Active pharmaceutical ingredient manufacturing concentrates in China, India, and Germany, with polymer synthesis capabilities drawing from zirconium ore processing in Australia and South Africa. Single-source vulnerability sits with Jiangsu province zirconium refining capacity exposed to environmental regulatory shutdowns. Distribution runs through specialty pharmacy channels for outpatient maintenance therapy and integrated delivery network central warehouses for hospital acute care.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hyperkalemia drug demand cycles track RAAS inhibitor prescribing patterns in heart failure populations, with guideline expansions driving recovery phases and generic resin competition compressing margin troughs.
For Market Incumbents: Entrench formulary positioning through cardiovascular outcome data investments that satisfy FDA safety database requirements and preempt generic binder substitution. Consolidate nephrology specialty distribution relationships before Medicare Advantage networks complete therapeutic protocol standardization. Backward integration into zirconium silicate raw material sourcing reduces exposure to Chinese environmental regulatory actions.
For New Entrants and Emerging Players: Pursue Japan's PMDA streamlined review pathways for nephrology unmet needs, where aging dialysis populations expand addressable patient pools with faster market entry than US equivalents. Target home care settings with subcutaneous depot formulations that reduce dosing frequency for non-adherent populations. Deploy digital therapeutics platforms paired with remote potassium monitoring as differentiated go-to-market anchors.
For Investors and Strategic Acquirers: Carve-out targets emerge from large-cap pharmaceutical conglomerates divesting non-core nephrology assets amid cardiovascular franchise restructuring. Long-term viability hinges on value-based renal care contract penetration and real-world evidence generation capabilities. Watch FDA label expansion decisions for heart failure populations as inflection indicators for chronic maintenance therapy addressable market expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Cardiovascular Outcome Trial Investment | FDA safety database requirements reshape clinical development pathways for novel potassium binders. |
| Specialty Pharmacy Channel Exclusivity | Payer-mandated 90-day dispensing through limited networks captures adherence rebates and reduces emergency utilization. |
| Backward Integration into API Manufacturing | India's PLI scheme attracts contract development partners for polymer synthesis capabilities and supply security. |
| Remote Patient Monitoring Integration | Home potassium testing devices paired with digital platforms enable proactive dose adjustment and hospitalization reduction. |
| EMA MDR Compliance Investment | Post-market surveillance obligations for polymer-based binders accelerate evidence generation across European markets. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with nephrology department heads, hospital formulary directors, specialty pharmacy network managers, and regulatory affairs leads at polymer manufacturers. Secondary validation drew from FDA New Drug Application filings, EMA marketing authorization submissions, ClinicalTrials.gov protocol registries, and CMS Medicare Part D claims databases. Bottom-up patient population modeling and top-down pharmaceutical market sizing were triangulated to reconcile volume estimates.
Calibration against historical prescription audit data and dialysis facility census projections anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product formulation, therapy area specialization, delivery mode, and end-user procurement channel. CAGRs were derived from longitudinal prescribing pattern analysis and RAAS inhibitor expansion trajectory assumptions. Forecast inputs incorporated Medicare Advantage network penetration rates and value-based renal care contract adoption curves.
Macroeconomic conditions sit as an overlay; deviation in reimbursement policy, dialysis facility funding, or cardiovascular guideline revision timelines would shift the trajectory. Forecasts reflect documented assumptions about regulatory pathway duration and polymer manufacturing capacity expansion. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmacology
Antimycotics Market
Pharmacology
Drug Eruptions Treatment Market
Pharmacology
Drug Repurposing Market
Pharmacology
Anti Inflammatory Therapeutics Market
Pharmacology
Global Olanzapine Market
Pharmacology
Medication Adherence Market
Pharmacology
Hypertension Drug Market
Pharmacology
Alzheimer Drugs Market
Pharmacology
Global Asthma Therapeutics Market
Pharmacology
Hepatitis C Drug Market
Pharmacology
Attention Deficit Hyperactivity Disorder (ADHD) Therapeutics Market
Pharmacology
Cough Remedies Market
Pharmacology
Influenza Medication Market
Pharmacology
Ibuprofen API Market
Pharmacology
Olanzapine API Market
Pharmacology
Aspirin API Market