
 Alzheimer Drugs Market | 2026-2036
Alzheimer Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Alzheimer Drugs Market Intelligence
FDA accelerated approval pathways is hardening the cost-of-entry calculus for new entrants in the Alzheimer drugs space. Biogen Inc. leverages its vertical integration across clinical development and commercial infrastructure to sustain market presence. Eli Lilly and Company anchors its competitive position through deep R&D intensity in amyloid and tau pathway science. Eisai Co., Ltd. differentiates through co-development alliances and specialized neurology channel control.
Alzheimer drugs comprise pharmaceutical agents targeting neurotransmitter modulation, amyloid-beta clearance, and tau protein aggregation to slow cognitive decline or manage behavioral symptoms in neurodegenerative disease. These therapies function through cholinesterase inhibition, NMDA receptor antagonism, or monoclonal antibody-mediated plaque removal, with injectable biologics requiring cold-chain distribution and specialized infusion center administration. Disease modification through injectable delivery now captures the fastest expansion as amyloid-clearing antibodies shift treatment from symptom management to progression delay. Oral cholinesterase inhibitors occupy the mature volume base where generic competition has compressed margins. Long-term care facilities represent a concentrated demand node where formulary decisions and reimbursement protocols determine access patterns.
FDA, EMA, and CMS collectively shape market access through divergent evidentiary standards for clinical benefit, pricing negotiation mandates, and coverage determination frameworks that filter which therapies reach patients. The FDA's accelerated approval contingent on confirmatory trials creates binary revenue risk for developers, while EMA's benefit-risk reassessments and CMS national coverage determinations add layered gatekeeping. Stakeholders must monitor regulatory convergence on surrogate endpoint acceptability and real-world evidence requirements to anticipate which development programs will secure sustainable market access.
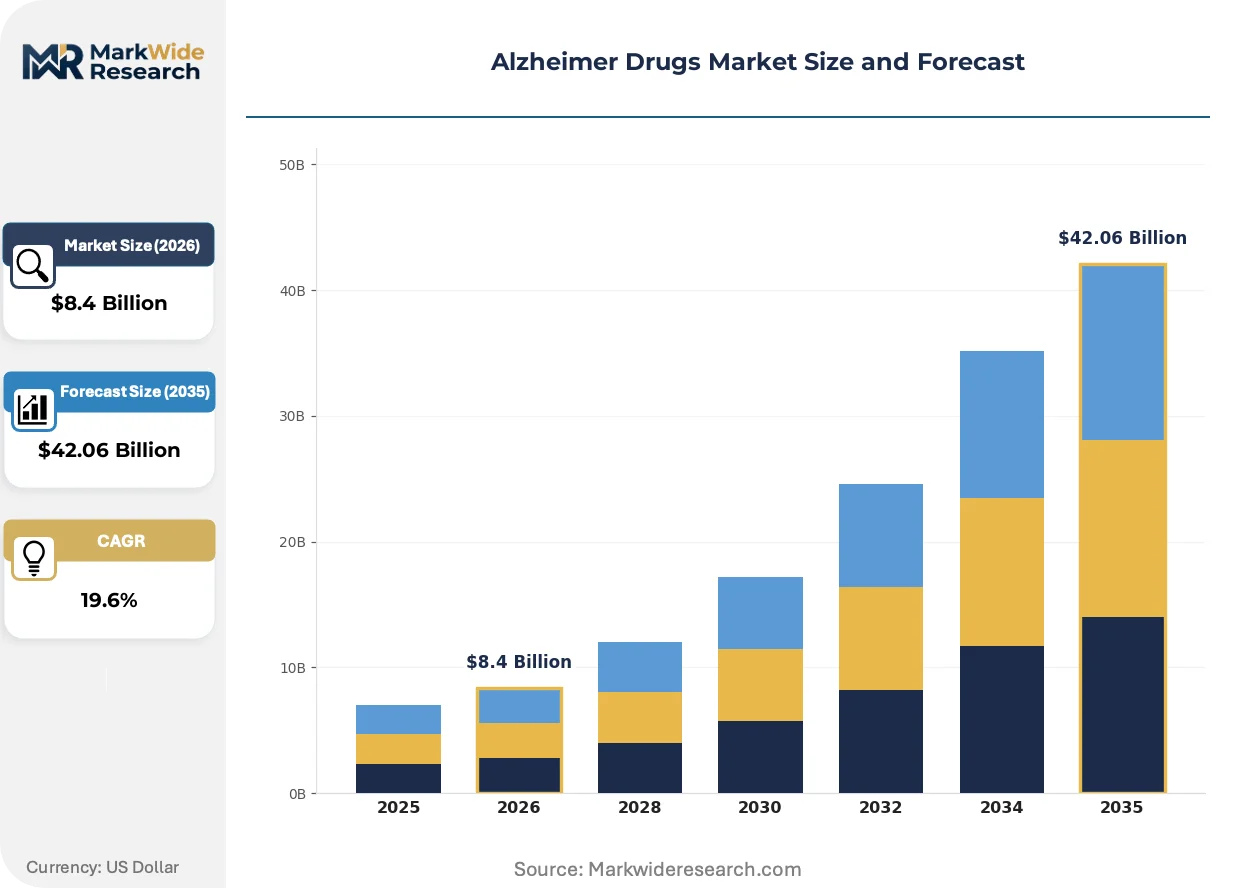
Market Dynamics
FDA accelerated approval pathways for amyloid-targeting biologics have fundamentally altered how developers calculate cost-of-entry, forcing capital reallocation toward confirmatory trial infrastructure and specialized neurology channel buildout.
Growth Catalysts
- Medicare Coverage Determinations:CMS national coverage decisions for disease-modifying therapies in the United States concentrate prescriber networks and unlock patient access at scale.
- Specialty Neurology Clinic Expansion:Infusion center infrastructure in tertiary care hospitals enables administration of cold-chain biologics requiring monitored delivery environments.
- Surrogate Endpoint Acceptance:FDA guidance on amyloid PET imaging as a predictive biomarker compresses trial timelines and reduces clinical development risk for plaque-clearing antibodies.
Market Restraints
- Confirmatory Trial Binary Risk:FDA accelerated approval contingent on post-marketing studies creates revenue volatility if clinical benefit fails to materialize in Phase IV.
- Cold-Chain Distribution Concentration:Injectable biologics require temperature-controlled logistics networks concentrated among limited specialty pharmacy distributors.
- Generic Cholinesterase Inhibition:Patent expiration on oral symptom-management drugs compresses pricing power in the volume base segment.
Strategic Opportunities
- Combination Therapy Protocols:Tau aggregation inhibitors paired with amyloid-clearing antibodies represent untested mechanistic synergy in late-stage pipelines.
- Long-Term Care Formulary Control:Institutional purchasing in skilled nursing facilities creates concentrated demand nodes for behavioral symptom management agents.
- Real-World Evidence Mandates:EMA's evolving benefit-risk reassessment frameworks reward developers with established patient registry infrastructure.
Industry Challenges
- Specialized Infusion Workforce Scarcity:Administration of monoclonal antibodies requires trained neurology nurses concentrated in academic medical centers.
- Biomarker Diagnostic Integration:Amyloid PET and CSF testing protocols must synchronize with treatment initiation, creating care pathway complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Alzheimer Drugs Market |
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $42.06 Billion |
| CAGR (2026 – 2036) | 19.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Donepezil, Rivastigmine, Galantamine, Memantine Delivery Mode: Oral, Injectable, Transdermal, Intranasal End User: Hospitals, Clinics, Home Care, Long-term Care Facilities Therapy Area: Cognitive Enhancement, Behavioral Management, Symptom Relief, Disease Modification |
| Companies Covered | Biogen Inc., Eisai Co., Ltd., Eli Lilly and Company, F. Hoffmann-La Roche Ltd., AbbVie Inc., Pfizer Inc., Novartis AG, Johnson & Johnson, Merck & Co., Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Alzheimer Drugs Market Strategic Shifts & Innovations
Injectable disease-modifying biologics are displacing oral symptomatic agents as the central competitive battleground, reshaping manufacturing scale requirements and distribution infrastructure investments across the therapeutic landscape.
Blood-based amyloid biomarker assays are consolidating diagnostic workflows by enabling scalable screening outside specialized imaging centers. Primary care networks in the United States and Germany are adopting these platforms to streamline specialist referral pathways. The technology is consolidating patient identification economics by reducing per-screen cost and expanding addressable populations beyond memory clinic catchments.
EMA's benefit-risk reassessment protocols for accelerated approvals are tightening evidentiary requirements for surrogate endpoint validation. Developers must now commit to larger confirmatory trial populations and longer follow-up periods before conditional marketing authorization converts to full approval. European neurology practices are responding by prioritizing therapies with established Phase III completion timelines over earlier-stage mechanisms.
Specialty pharmacy carve-out arrangements are restructuring how payers manage infused biologic spend. United States Medicare Advantage plans and large self-insured employers are contracting directly with infusion center networks to capture site-of-care cost differentials. This channel compression is most visible in Florida and Texas, where vertically integrated health systems have consolidated neurology infusion capacity.
Alzheimer Drugs Market Segmentation
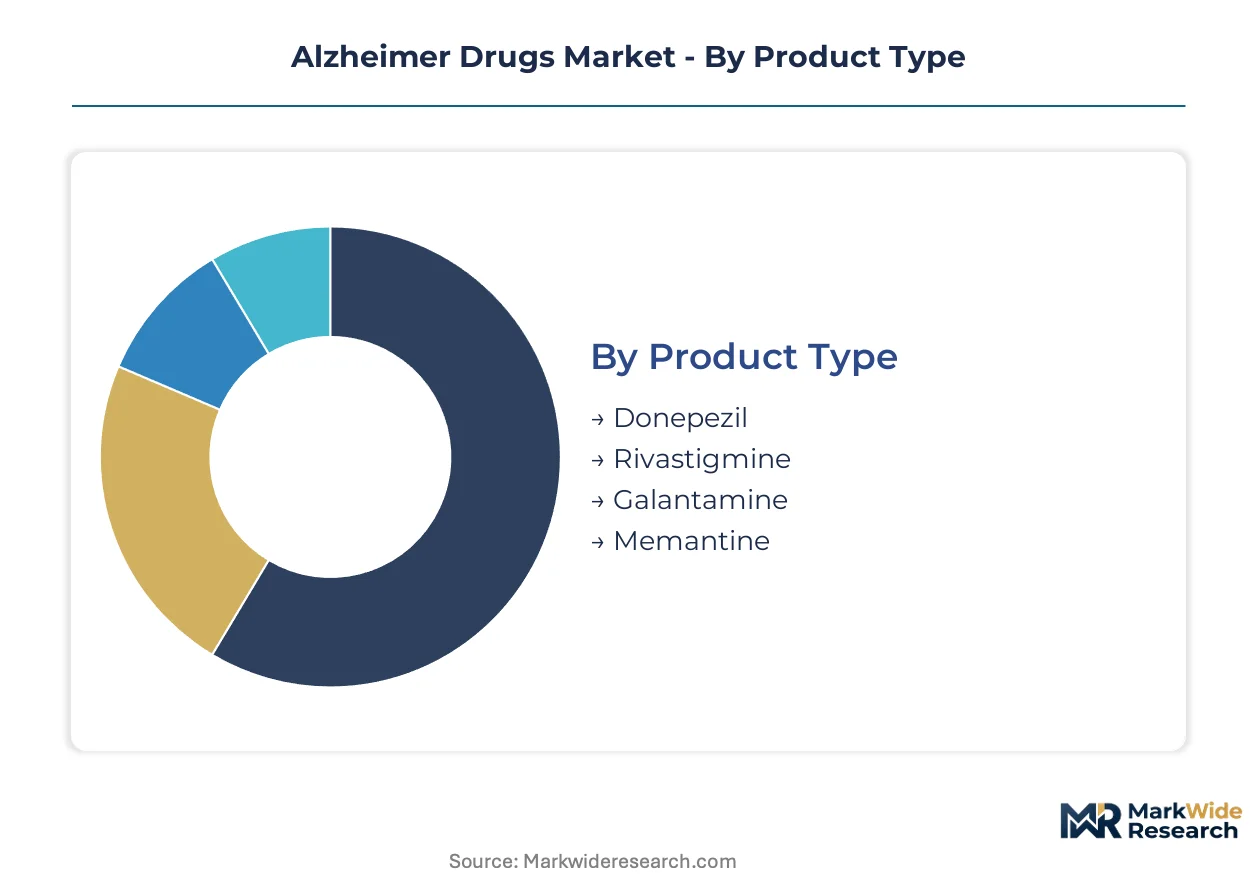
Alzheimer drug segmentation reveals how therapeutic innovation, administration logistics, and care setting economics interact to determine commercial viability. Each axis exposes distinct margin structures and access barriers that shape portfolio prioritization.
Product Type:
Mechanism of action defines reimbursement tiering and prescriber specialization intensity across the therapeutic landscape.
- Donepezil:A reversible acetylcholinesterase inhibitor with once-daily oral dosing that has become the standard-of-care reference in mild-to-moderate disease. Demand concentrates in Medicare Part D formularies where generic substitution rates exceed 90%, compressing branded revenue to near-zero.
- Rivastigmine:Dual cholinesterase and butyrylcholinesterase inhibition available in oral and transdermal patch formulations. The patch delivery captures preference in long-term care facilities where medication adherence monitoring is resource-constrained.
- Galantamine:A cholinesterase inhibitor with additional nicotinic receptor modulation properties. Prescription volume trails donepezil due to twice-daily dosing requirements and narrower formulary placement.
- Memantine:NMDA receptor antagonist indicated for moderate-to-severe disease stages, often prescribed in combination with cholinesterase inhibitors. Medicaid programs in New York and California drive disproportionate volume through institutional dispensing.
Donepezil leads on scale; disease-modifying biologics in development pipelines lead on momentum.
Delivery Mode:
Administration complexity directly determines distribution infrastructure requirements and site-of-care economics.
- Oral:Tablet and capsule formulations dominate prescription volume through retail pharmacy channels. Generic erosion has collapsed pricing power, though convenience sustains adherence advantages in home-based care.
- Injectable:Monoclonal antibody infusions requiring cold-chain logistics and specialized neurology nursing. Tertiary hospitals in Boston, Cleveland, and Baltimore anchor initial deployment due to amyloid PET imaging co-location.
- Transdermal:Patch delivery systems bypass first-pass metabolism and gastrointestinal side effects. Skilled nursing facilities in Florida and Arizona favor this modality for behavioral symptom management.
- Intranasal:Emerging delivery route for investigational therapies targeting direct CNS penetration through olfactory pathways. Phase II programs are evaluating pharmacokinetic equivalence to intravenous administration.
Oral formulations lead on scale; injectable biologics lead on revenue per patient.
End User:
Care setting concentration shapes formulary control points and reimbursement pathway complexity.
- Hospitals:Academic medical centers with integrated neurology departments administer infused disease-modifying therapies. CMS new technology add-on payments determine adoption velocity for amyloid-clearing antibodies.
- Clinics:Specialty neurology practices concentrate prescriber networks and patient identification through cognitive assessment protocols. Medicare Advantage plans in Texas and Pennsylvania are contracting directly with these sites.
- Home Care:Oral symptomatic agents dispensed through mail-order pharmacy dominate this channel. Caregiver burden and medication management complexity limit biologic penetration.
- Long-term Care Facilities:Institutional pharmacies negotiate consolidated purchasing for behavioral management agents. Formulary committees in multi-facility operators drive generic substitution rates above national averages.
Long-term care facilities lead on prescription volume concentration; hospital infusion centers lead on revenue intensity per encounter.
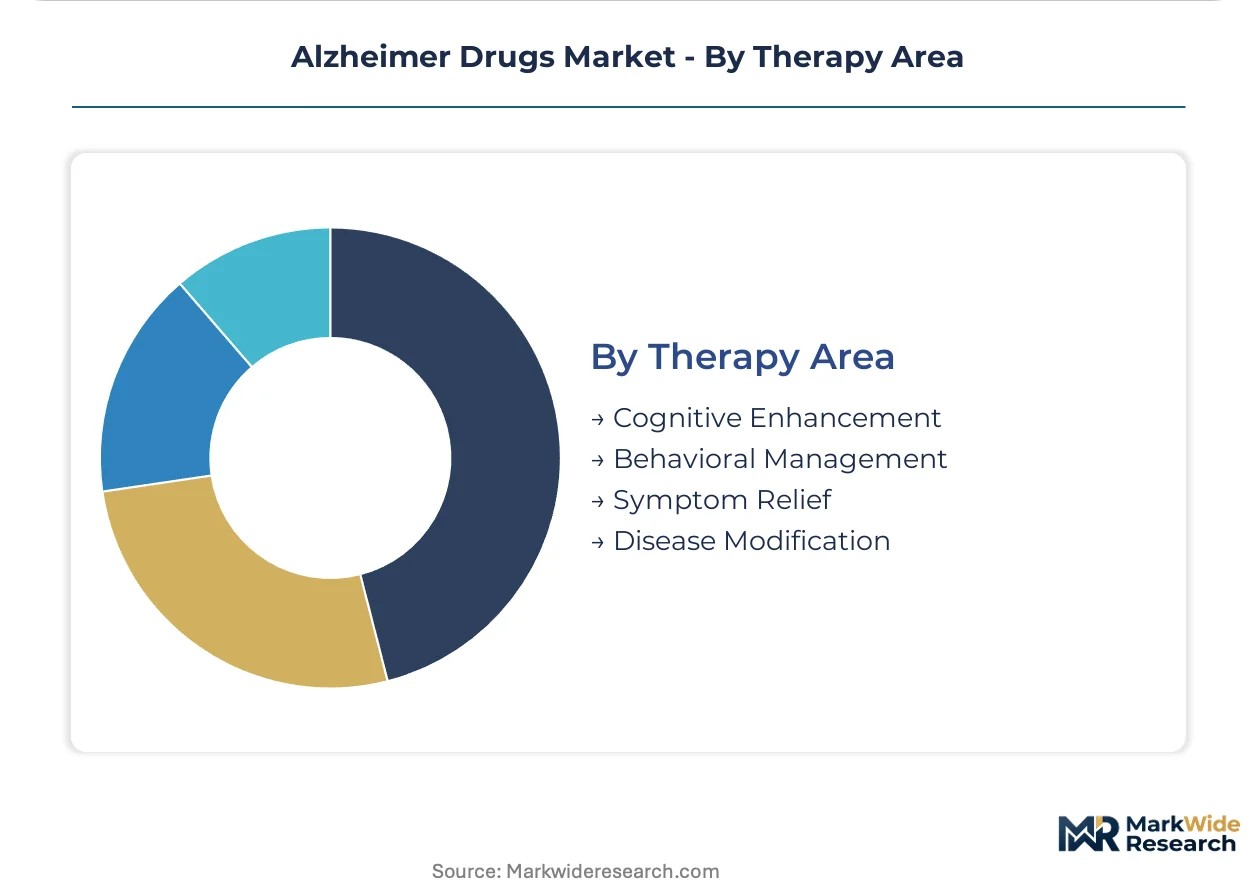
Therapy Area:
Treatment objective determines evidentiary requirements, trial design complexity, and regulatory pathway duration.
- Cognitive Enhancement:Cholinesterase inhibitors and memantine targeting memory, attention, and executive function. FDA approval historically required six-month placebo-controlled trials with ADAS-Cog endpoints.
- Behavioral Management:Agents addressing agitation, psychosis, and sleep disturbance in later disease stages. Black box warnings on antipsychotics have shifted demand toward safer alternatives in nursing home settings.
- Symptom Relief:Short-term interventions for specific manifestations like anxiety or depression comorbid with dementia. Psychiatric consultation requirements fragment prescribing authority.
- Disease Modification:Amyloid-clearing and tau-targeting biologics aiming to slow neurodegenerative progression. FDA accelerated approval contingent on biomarker surrogate endpoints has compressed initial launch timelines while extending confirmatory study obligations.
Cognitive enhancement leads on current patient volume; disease modification leads on pipeline investment and pricing potential.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Alzheimer drugs industry crystallized in the United States during the 1990s with the FDA approval of cholinesterase inhibitors, establishing regulatory and commercial templates that subsequently diffused to Europe and Asia-Pacific markets.
United States
Medicare coverage determinations and concentrated prescriber networks drive demand concentration in tertiary care hospitals. FDA accelerated approval pathways for amyloid-targeting biologics have compressed development timelines while extending confirmatory obligations. The Boston-Cleveland-Baltimore corridor anchors infusion center deployment for monoclonal antibody administration.
Germany
EMA benefit-risk reassessment protocols tighten evidentiary requirements for surrogate endpoint validation in accelerated approvals. The country's statutory health insurance system negotiates pricing through the Federal Joint Committee, creating layered access gatekeeping. Heidelberg and Munich academic medical centers concentrate amyloid PET imaging capacity and neurology nursing specialization.
Japan
PMDA consultation frameworks for dementia drug development attract multinational trial investment from Western developers. The Ministry of Health, Labour and Welfare's pricing methodology for innovative biologics rewards disease-modifying mechanisms with premium reimbursement tiers. Tokyo and Osaka metropolitan areas host specialized memory clinics that coordinate diagnostic-to-treatment pathways.
United Kingdom
NICE technology appraisals for dementia treatments create binary access decisions that filter which therapies reach National Health Service formularies. The Medicines and Healthcare products Regulatory Agency aligns post-Brexit with FDA evidentiary standards to streamline developer submissions. London and Cambridge neuroscience clusters concentrate early-phase clinical trial infrastructure.
Switzerland
Swissmedic's accelerated assessment procedures for drugs addressing unmet medical needs attract developer headquarters and clinical operations. The country's compulsory health insurance system permits price premiums for therapies demonstrating disease modification. Basel and Zurich anchor pharmaceutical R&D clusters with integrated neurology research hospitals.
Alzheimer Drugs Market Key Industry Players
The competitive structure tilts toward integrated biopharmaceutical conglomerates with captive neurology commercial infrastructure. Market concentration reflects the capital intensity of amyloid-clearing antibody development and the specialized distribution requirements of cold-chain biologics. Two archetypes dominate: vertically integrated developers controlling clinical-to-commercial pipelines, and alliance-dependent specialists leveraging co-development partnerships for risk sharing. Dominant competitive moves include capacity expansion in infusion center networks and technology licensing for blood-based diagnostic companion platforms.
Within the integrated developer tier, Biogen Inc. and Eli Lilly and Company exemplify archetypes of commercial infrastructure control. Eisai Co., Ltd. occupies a position representing alliance-structured market access, reflecting the prevalence of Japanese-European co-development frameworks in neurology. These three entities anchor the competitive landscape without exhausting its structural variation.
| Leading Market Players |
|---|
| Biogen Inc. |
| Eisai Co., Ltd. |
| Eli Lilly and Company |
| F. Hoffmann-La Roche Ltd. |
| AbbVie Inc. |
| Pfizer Inc. |
| Novartis AG |
| Johnson & Johnson |
| Merck & Co., Inc. |
| Others |
Cost & Logistics Intelligence
Injectable biologic manufacturing scale-up simultaneously compresses per-unit production economics and concentrates supply capacity among FDA-registered fill-finish facilities in the United States and Switzerland. This dual transformation hardens pricing power for disease-modifying therapies while amplifying vulnerability to cold-chain logistics bottlenecks.
Pricing Analysis
Bundled service pricing for amyloid-clearing antibodies separates drug acquisition from infusion administration and biomarker monitoring, while unbundled oral generics compete purely on pharmacy benefit manager rebate tiers. Price differentiation rests on FDA accelerated approval status and site-of-care delivery cost, with Medicare Advantage plans in Florida and Texas showing highest sensitivity to administration fees. Pricing pressure intensifies in the cholinesterase inhibitor base as 90% generic substitution rates collapse branded margins to near-zero. Long-term care facilities demonstrate lowest price sensitivity for behavioral management agents where formulary control overrides unit cost.
Supply Chain Analysis
Reverse-logistics infrastructure for temperature-deviated biologics remains underdeveloped, forcing destruction protocols that inflate effective cost per delivered dose. Active pharmaceutical ingredient synthesis concentrates in Ireland and Switzerland, with fill-finish capacity anchored in Massachusetts and North Carolina facilities. Monoclonal antibody production draws from Chinese hamster ovary cell lines, recombinant protein media, and single-use bioreactor systems. Single-source vulnerability permeates the amyloid PET tracer supply, where cyclotron production radius limits geographic coverage. Distribution runs through specialty pharmacy networks with direct-to-infusion-center contracting replacing traditional wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Alzheimer drugs market functions as a regulatory compounder where FDA accelerated approval contingent on confirmatory trials creates binary revenue events that reshape competitive positioning. CMS national coverage determinations for disease-modifying therapies represent the pivotal regulatory milestone concentrating demand and unlocking patient access at scale.
For Market Incumbents: Extend infusion center network control through direct contracting with Medicare Advantage plans in Texas and Pennsylvania, securing site-of-care cost differentials that lock out competitors. Fortify amyloid PET imaging co-location capacity in the Boston-Cleveland-Baltimore corridor to synchronize diagnostic-to-treatment pathways. Biogen and Eli Lilly's integrated infrastructure faces emerging threat from alliance-structured entrants leveraging Japanese-European co-development frameworks for risk sharing. For New Entrants and Emerging Players: Launch via long-term care formulary carve-outs targeting multi-facility operators in Florida and Arizona where behavioral symptom management agents face generic substitution pressure and demand safer alternatives. Blood-based amyloid screening platforms offer the most penetrable diagnostic entry point, enabling primary care patient identification outside academic memory clinic catchments. Partner with institutional pharmacy networks for consolidated purchasing access. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap developers with Phase II tau aggregation inhibitors paired with established amyloid-clearing antibodies in combination protocols. Long-term viability over the next decade hinges on confirmatory trial completion rates and EMA benefit-risk reassessment outcomes. Watch FDA confirmatory trial readouts as the critical inflection signal distinguishing sustainable revenue from accelerated approval withdrawal.| Strategic Initiative | Industry Significance |
|---|---|
| Confirmatory Trial Infrastructure Investment | Post-marketing study completion determines accelerated approval conversion and revenue sustainability under FDA pathways. |
| Specialty Neurology Channel Buildout | Infusion center capacity in tertiary hospitals enables cold-chain biologic administration and captures Medicare reimbursement. |
| Blood-Based Diagnostic Companion Development | Amyloid screening assays expand addressable populations beyond memory clinic constraints and streamline specialist referrals. |
| Long-Term Care Formulary Positioning | Institutional purchasing committees in skilled nursing facilities drive generic substitution rates for behavioral agents. |
| Tau-Amyloid Combination Pipeline Advancement | Mechanistic synergy in late-stage development represents untested therapeutic protocols with premium pricing potential. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with drug development executives, regulatory affairs leads, formulary directors at Medicare Advantage plans, and hospital procurement managers with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and CMS national coverage determination databases. Bottom-up patient-flow modeling and top-down therapeutic class revenue triangulation anchored market sizing.
Comparable-period anchoring tied projection horizons to historical cholinesterase inhibitor generic erosion curves and monoclonal antibody launch trajectories across the analysis window. Segmentation dimensions spanned mechanism of action, delivery mode, care setting, and regional regulatory cluster. CAGRs derived from patient population epidemiology, treatment penetration assumptions, and pricing evolution by therapy area. Forecast inputs incorporated Medicare coverage determination timelines and EMA benefit-risk reassessment protocols.
Forecast precision tightens around the base case; tail outcomes carry wider variance under confirmatory trial failure scenarios or CMS coverage restriction shifts. Practitioners should monitor FDA Phase IV readout schedules and EMA conditional marketing authorization conversion rates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmacology
Antitussive Drugs Market
Pharmacology
Intranasal Drug and Vaccine Delivery Market
Pharmacology
Global Migraine Therapeutics Market
Pharmacology
Angiotensin II Receptor Blockers (Arbs) Market
Pharmacology
Medication Adherence Market
Pharmacology
Anti Inflammatory Therapeutics Market
Pharmacology
Alexipharmic Drugs Market
Pharmacology
Hepatitis C Drug Market
Pharmacology
Alzheimer's Therapeutics Market
Pharmacology
Artemisinin Antimalarial Drugs Market
Pharmacology
Thromboprophylactic Drugs Market
Pharmacology
ACE Inhibitors Market
Pharmacology
Influenza Medication Market
Pharmacology
Global Artemisinin Combination Therapy Market
Pharmacology
Global Asthma Therapeutics Market
Pharmacology
Propranolol Drug Market