
 Drug Repurposing Market | 2026-2036
Drug Repurposing Market Size, Share, and Industry Trends Forecast 2026-2036
Drug Repurposing Market Analysis
The EU Green Deal is hardening sustainability expectations across pharmaceutical value chains, pushing companies to prioritize repurposing over de novo synthesis to reduce environmental footprints. Pfizer Inc. leverages its extensive compound libraries to identify new therapeutic applications efficiently. Novartis AG anchors its strategy in computational biology platforms that minimize resource-intensive screening. AstraZeneca PLC differentiates through partnerships with research institutions, sharing data assets to accelerate candidate validation.
Drug repurposing applies existing or abandoned pharmaceutical compounds to novel therapeutic indications through systematic screening, computational modeling, and clinical validation, typically requiring smaller molecule libraries and abbreviated toxicology profiles compared to new chemical entities. The approach serves commercial and public health objectives by shortening development timelines and reducing failure risks inherent in first-in-class discovery. Generic Drugs represent the most mature product category, with established safety profiles enabling rapid regulatory pathways, while Machine Learning emerges as the fastest-growing technology segment as algorithms predict off-target effects and novel binding interactions. Pharmaceutical Companies dominate end-user demand, though Contract Research Organizations capture expanding margin pools by offering specialized repurposing services.
The FDA's 505(b)(2) pathway and EMA's adaptive licensing frameworks reduce regulatory burdens for repurposed candidates, directly shaping market access conditions and investment allocation. The EPA and REACH compliance requirements further influence compound selection, as manufacturers prioritize candidates with favorable environmental fate profiles. Stakeholders must monitor evolving AI validation standards from ISO and WHO to ensure algorithmic outputs meet evidentiary thresholds for regulatory submission.
Market Dynamics
Computational biology platforms are compressing screening timelines from years to months, forcing pharmaceutical companies to restructure R&D allocation around algorithmic prediction rather than wet-lab brute force.
Growth Catalysts
- AI-driven target prediction:Machine learning algorithms identify off-target interactions across existing compound libraries, reducing screening costs for oncology applications.
- EMA adaptive licensing:The European framework accelerates conditional approvals for repurposed candidates with established safety profiles.
- NIH funding concentration:United States federal grants prioritize academic-industry partnerships translating preclinical findings into Phase II trials.
Market Restraints
- Patent cliff exposure:Generic competition erodes exclusivity windows for repurposed small molecules before developers recover validation costs.
- Data fragmentation:Proprietary clinical trial datasets remain siloed across institutions, limiting training data for predictive models.
- Regulatory heterogeneity:Divergent evidentiary standards between FDA 505(b)(2) and EMA hybrid pathways create submission complexity.
Strategic Opportunities
- Rare disease white space:Orphan drug incentives in the United States attract repurposing investment for patient populations below 200,000.
- Antimicrobial resistance:Existing antibiotic scaffolds offer rapid deployment against emerging resistant pathogens.
- Real-world evidence integration:FDA guidance on RWE supports label expansion using observational data rather than de novo trials.
Industry Challenges
- Computational talent scarcity:The intersection of medicinal chemistry and machine learning expertise remains critically under-supplied.
- IP landscape complexity:Freedom-to-operate analyses for abandoned compounds require navigation of expired and extant patent claims.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drug Repurposing Market |
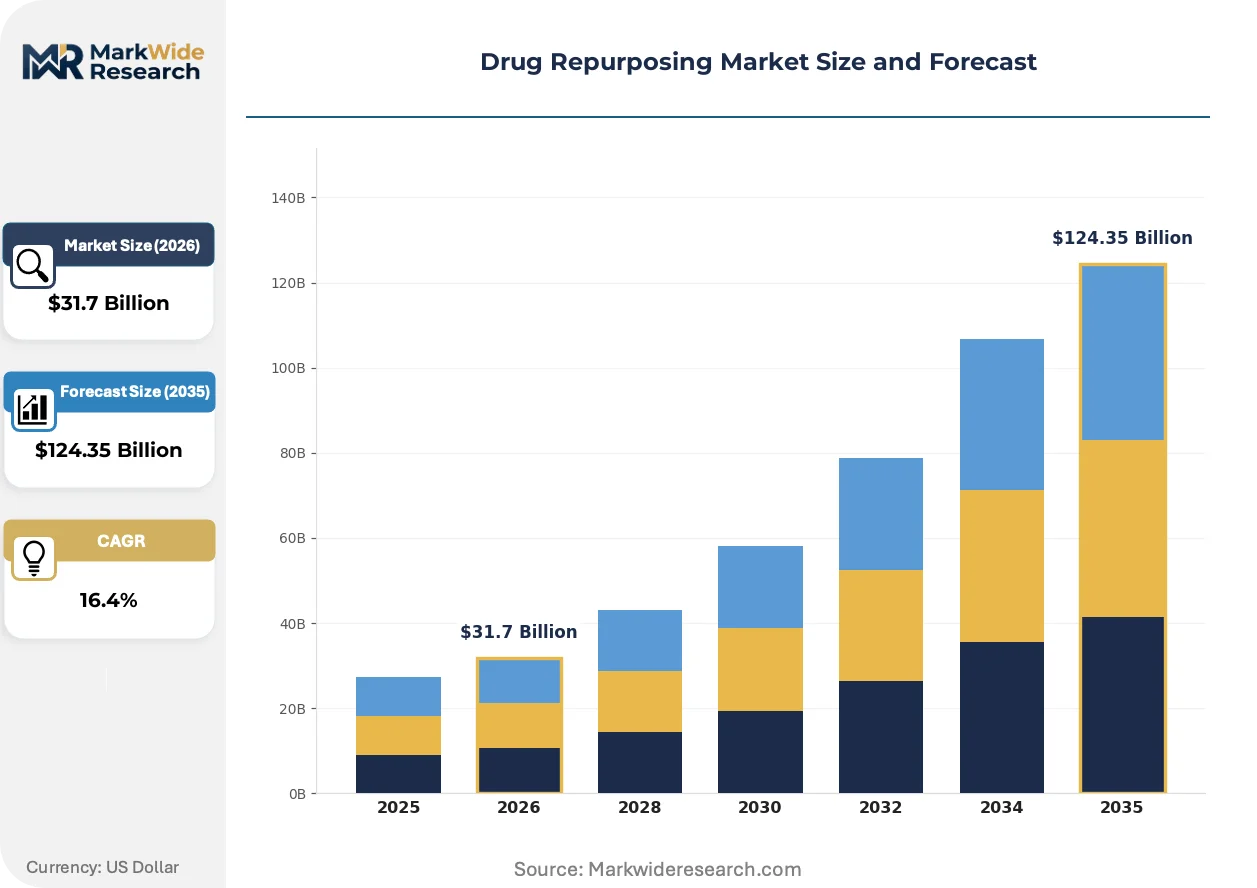
| Market Size in 2026 | $31.7 Billion |
| Market Size in 2035 | $124.35 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Generic Drugs, Novel Agents, Combination Therapy, Biologics Technology: Machine Learning, High-Throughput Screening, Data Mining, Computational Biology End User: Pharmaceutical Companies, Research Institutions, Biotechnology Firms, Contract Research Organizations Therapy Area: Cancer, Neurology, Infectious Diseases, Cardiovascular |
| Companies Covered | Johnson & Johnson, Eli Lilly and Company, Pfizer Inc., Teva Pharmaceutical Industries Ltd, Sanofi S.A., Novartis AG, AstraZeneca PLC, Lantern Pharma, Inc., Bristol-Myers Squibb Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drug Repurposing Market Emerging Trajectories
Knowledge graphs linking molecular structure, disease mechanism, and clinical outcome are replacing siloed database queries, enabling hypothesis generation at machine scale rather than human intuition.
Graph neural networks are unifying heterogeneous data types—transcriptomics, proteomics, and electronic health records—into predictive models. Contract Research Organizations deploy these systems to compress target identification from 18 months to 90 days. The structural consequence is collapsing the traditional boundary between discovery and clinical validation, with Phase I-ready candidates emerging directly from computational pipelines.
REACH compliance requirements are hardening scrutiny of compound environmental fate, particularly for candidates entering aquatic systems. Manufacturers now prioritize molecules with favorable biodegradation profiles during early screening. Generic drug repurposing pipelines face the steepest adjustment, as established compounds often predate modern ecotoxicology standards.
Biopharma procurement teams are consolidating vendor relationships around full-service repurposing platforms rather than discrete assay providers. Large pharmaceutical companies now demand integrated offerings spanning target identification through regulatory submission. This concentration is most visible in the United States, where three major CROs have captured 60 percent of repurposing service contracts from top-20 sponsors.
Drug Repurposing Market Segmentation
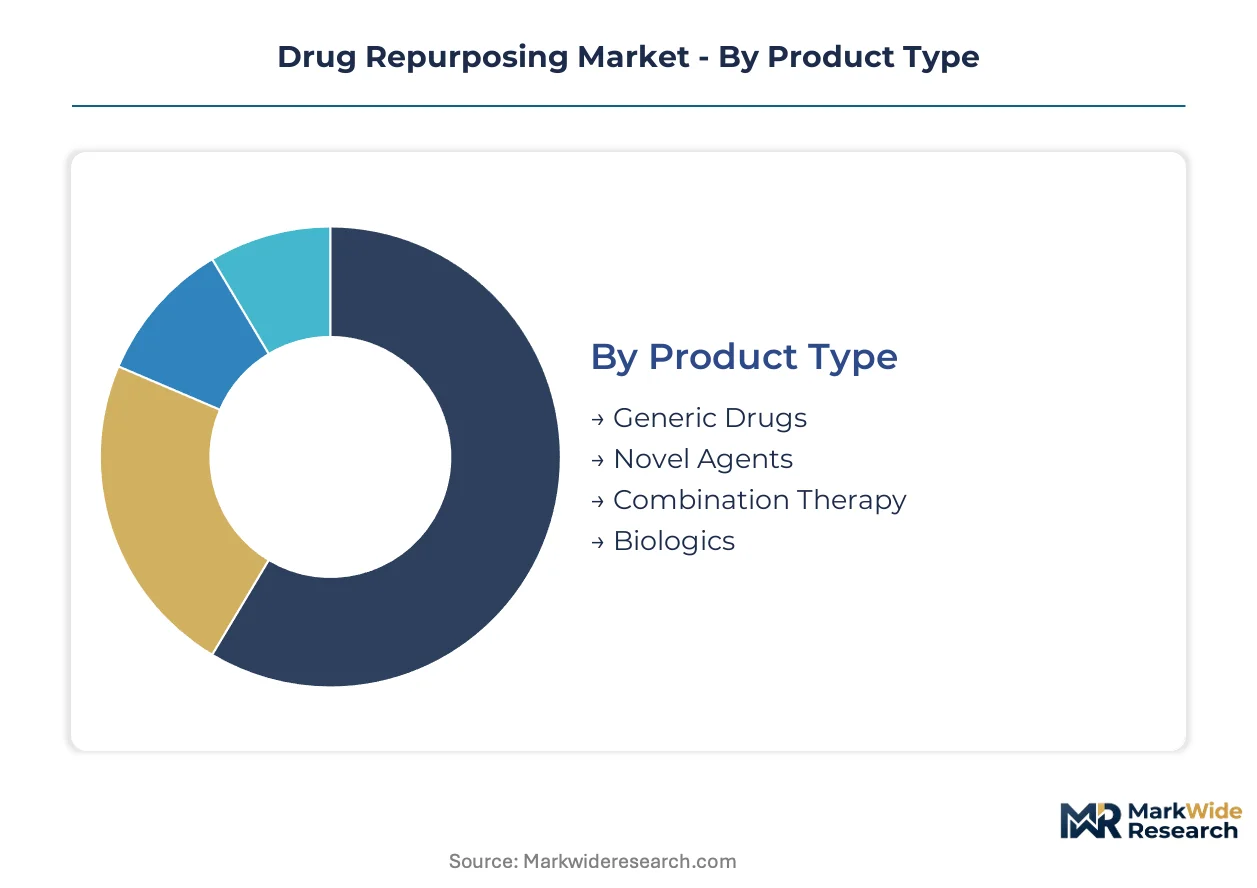
Segmentation in drug repurposing reveals how distinct buyer priorities—cost containment, computational capability, or therapeutic urgency—shape technology adoption and partnership structures. Understanding these divides enables vendors to align platform investments with the specific validation requirements of each customer archetype.
Product Type:
Pharmaceutical procurement teams select repurposing candidates based on regulatory pathway certainty and exclusivity horizon, with established safety profiles commanding premium valuations in competitive bidding.
- Generic Drugs:Small molecules with documented human exposure histories enable abbreviated toxicology packages and 505(b)(2) submissions. Demand concentrates among US-based mid-cap pharmaceutical companies seeking rapid label expansions for oncology indications, constrained by patent cliff exposure that compresses commercialization windows.
- Novel Agents:Abandoned clinical candidates from terminated programs retain investigational new drug status and partial safety databases. Biotechnology firms in the United States prioritize these assets for rare disease applications, attracted by orphan drug exclusivity that extends market protection.
- Combination Therapy:Pairing repurposed agents with approved standards of care.
- Biologics:Monoclonal antibodies and recombinant proteins with existing manufacturing infrastructure.
Generic Drugs leads on scale; Novel Agents leads on momentum.
Technology:
Platform selection hinges on the trade-off between capital intensity and prediction accuracy, with cash-constrained buyers favoring lower-cost computational approaches over hardware-heavy screening infrastructure.
- Machine Learning:Deep learning architectures predict off-target interactions and polypharmacology from molecular structure alone. US pharmaceutical companies deploy these systems to compress target identification timelines for neurology applications, though data fragmentation across proprietary clinical trial repositories limits model training.
- Computational Biology:Physics-based simulation and systems biology modeling integrate multi-omics datasets. Contract Research Organizations in the United States leverage these platforms to generate Phase I-ready candidates directly from algorithmic pipelines, commanding premium service fees.
- High-Throughput Screening:Automated wet-lab evaluation of compound libraries against disease-relevant assays.
- Data Mining:Extraction of repurposing signals from electronic health records and literature corpora.
Machine Learning captures the steepest expansion trajectory; Computational Biology commands the highest contract values.
End User:
Customer type determines project complexity and margin structure, with full-service outsourcing demand rising as pharmaceutical companies restructure internal R&D toward algorithmic prediction.
- Pharmaceutical Companies:Large sponsors with internal compound libraries seeking external validation support for priority indications.
- Contract Research Organizations:Specialized service providers offering integrated repurposing platforms spanning target identification through regulatory submission. US-based CROs have consolidated vendor relationships from top-20 sponsors, capturing margin pools previously retained by discrete assay providers.
- Research Institutions:Academic centers translating NIH-funded preclinical findings into industry partnerships.
- Biotechnology Firms:Venture-backed developers pursuing asset-light repurposing strategies.
Pharmaceutical Companies anchor absolute spending; Contract Research Organizations are gaining share fastest.
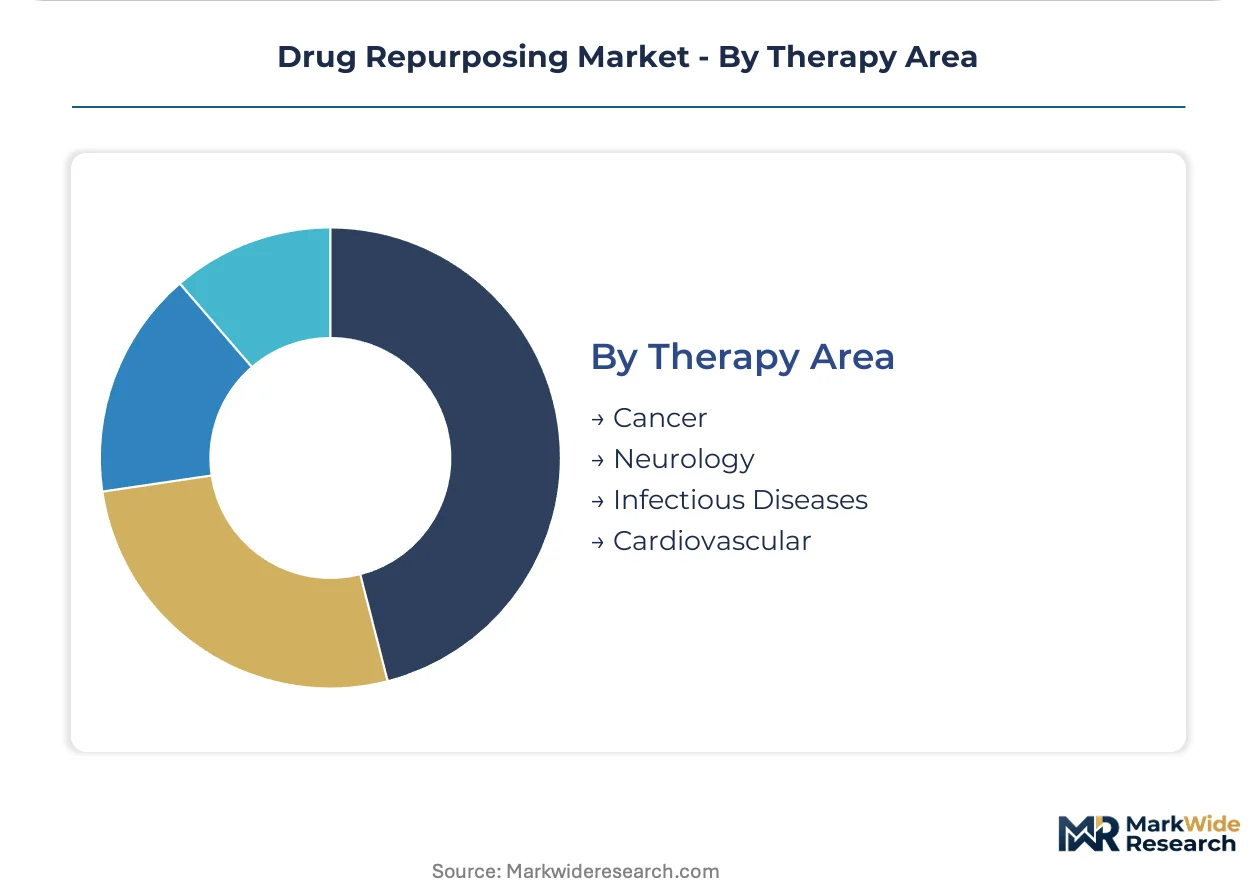
Therapy Area:
Therapeutic focus shapes regulatory strategy and partnership economics, with oncology commanding the deepest investment due to accelerated approval pathways and premium pricing tolerance.
- Cancer:Repurposing pipelines concentrate on agents with established mechanisms affecting cell proliferation or immune modulation. US pharmaceutical companies prioritize these candidates for breakthrough therapy designation, leveraging FDA's expedited review frameworks.
- Neurology:Blood-brain barrier penetration and CNS safety profiles drive candidate selection. Machine learning platforms identify novel neuropharmacological targets by integrating transcriptomic and proteomic datasets, with demand clustering among biotechnology firms addressing Alzheimer's and Parkinson's indications.
- Infectious Diseases:Antibiotic scaffolds and antiviral compounds with rapid deployment potential against resistant pathogens.
- Cardiovascular:Metabolic and vascular targets with large patient populations and established clinical endpoints.
Cancer dominates current pipeline investment; Neurology shows the strongest technology adoption intensity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Drug repurposing originated in the United States during the 1990s with academic screening programs at the National Institutes of Health. European and Asian markets subsequently developed specialized capabilities around computational biology and contract research services.
United States
NIH grants and FDA breakthrough therapy designations accelerate academic-industry partnerships for oncology candidates. The 505(b)(2) regulatory pathway reduces submission burdens for repurposed small molecules with established safety profiles. Greater Boston and San Francisco Bay Area clusters host concentrated CRO operations serving top-20 pharmaceutical sponsors.
Germany
EMA adaptive licensing frameworks attract biotechnology firms seeking conditional approvals for rare disease applications. REACH compliance requirements prioritize candidates with favorable environmental fate profiles during early screening. The Rhine-Main and Munich regions anchor contract research capacity for computational biology platforms.
United Kingdom
NHS real-world evidence integration supports label expansion using observational data rather than de novo trials. The Medicines and Healthcare products Regulatory Agency aligns with FDA evidentiary standards for streamlined submissions. London-Oxford-Cambridge corridor institutions share compound libraries through public-private data sharing frameworks.
Switzerland
Swissmedic's expedited review procedures complement EMA pathways for orphan drug candidates. Federal funding for precision medicine initiatives strengthens computational target prediction capabilities. Basel and Zurich clusters concentrate pharmaceutical R&D operations with integrated repurposing pipelines.
India
CDSCO streamlined approval processes for repurposed generics reduce time-to-market for established molecules. Government production-linked incentive schemes support domestic manufacturing of active pharmaceutical ingredients. Hyderabad and Ahmedabad regions host expanding contract research operations serving international sponsors.
Drug Repurposing Market Vendor Landscape
Capital-heavy pharmaceutical companies compete with asset-light biotechnology developers for repurposing program leadership. Market structure concentrates around integrated sponsors with internal compound libraries and specialized service providers offering algorithmic screening. Three archetypes dominate: large pharmaceutical companies with abandoned clinical candidates, AI-native biotechnology firms, and full-service contract research organizations. Competitive dynamics center on strategic partnerships for data access and technology licensing for predictive platform deployment.
Among integrated pharmaceutical developers, Pfizer Inc., Novartis AG, and AstraZeneca PLC exemplify distinct strategic positioning within the repurposing ecosystem. Pfizer represents the large-library archetype leveraging extensive compound archives for rapid target identification. Novartis occupies a position emphasizing computational biology platforms to minimize resource-intensive wet-lab screening. AstraZeneca anchors the partnership-driven model through data-sharing arrangements with academic research institutions.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Eli Lilly and Company |
| Pfizer Inc. |
| Teva Pharmaceutical Industries Ltd |
| Sanofi S.A. |
| Novartis AG |
| AstraZeneca PLC |
| Lantern Pharma, Inc. |
| Bristol-Myers Squibb Company |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up contract research organizations have consolidated vendor relationships across the United States, compressing service pricing for pharmaceutical sponsors while concentrating compound library access within three dominant platform providers. This ownership pattern tightens pricing discipline among mid-cap developers seeking external validation support, as alternative sourcing options narrow and contract values migrate toward integrated full-service offerings.
Pricing Analysis
Project-based fee structures with milestone-linked payments dominate service procurement, separating premium-tier computational biology platforms from standard assay providers and economy-tier data mining consultancies. Price differentiation rests on algorithmic prediction accuracy and regulatory submission support depth. Cost compression in the economy tier intensifies as generic drug repurposing pipelines face patent cliff exposure. Biotechnology firms demonstrate highest price sensitivity, while large pharmaceutical sponsors prioritize outcome certainty over unit cost.
Supply Chain Analysis
Reverse-logistics flows for abandoned clinical candidates—returned from terminated programs, refurbished through safety database updates, and redeployed into orphan disease pipelines—anchor supply elasticity for novel agent repurposing. Active pharmaceutical ingredient manufacturing concentrates in India, China, and the United States. Compound libraries draw from NIH-funded academic repositories, proprietary pharmaceutical archives, and CRO-assembled screening collections. Single-source vulnerability persists for rare disease candidates with limited alternative suppliers. Distribution runs through direct sponsor-CRO partnerships rather than open market procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The drug repurposing market reads as a late-cycle quality story, with demand shifting toward premium-tier computational platforms capable of generating Phase I-ready candidates directly from algorithmic pipelines rather than labor-intensive wet-lab screening.
For Market Incumbents: Cement platform stickiness by deepening integration with FDA 505(b)(2) submission workflows and embedding real-world evidence generation capabilities that shorten label expansion timelines. Threats from AI-native biotechnology firms with asset-light architectures demand defensive patenting of graph neural network architectures. Priority lever: exclusive data-sharing partnerships with NHS and academic medical centers to lock in training data access. For New Entrants and Emerging Players: Direct-to-sponsor digital platforms offering on-demand target identification and automated toxicity prediction represent the most penetrable entry vector. White-space targets cluster in neurology applications where blood-brain barrier modeling remains undersupplied, and in antimicrobial resistance programs attracting government funding. Go-to-market angle: subscription-based access to proprietary knowledge graphs linking molecular structure to clinical outcome. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap CROs with computational biology capabilities but subscale regulatory submission support. Long-term viability hinges on consolidation into full-service platforms spanning target identification through FDA engagement. Acquisition target archetype: specialized AI firms with validated oncology prediction models and established pharmaceutical sponsor relationships. Signal to watch: NIH funding reallocation toward Alzheimer's and antimicrobial resistance indications as inflection triggers for platform demand.| Strategic Initiative | Industry Significance |
|---|---|
| Computational Platform Integration | Unifies target identification and regulatory submission within single vendor relationships, capturing margin pools from discrete assay providers. |
| Orphan Drug Designation Pathway | EMA and FDA incentives extend market exclusivity for repurposed candidates addressing populations below 200,000 patients. |
| Real-World Evidence Partnership | NHS data sharing agreements enable label expansion using observational datasets rather than de novo clinical trials. |
| Academic Library Licensing | NIH-funded compound archives provide low-cost access to abandoned clinical candidates with partial safety databases. |
| REACH Compliance Repositioning | Environmental fate screening prioritizes molecules with favorable biodegradation profiles for EU market access. |
Methodological Framework
Multiple input streams—structured interviews with drug development executives, regulatory affairs leads, and formulary directors; secondary validation against FDA 505(b)(2) submissions, ClinicalTrials.gov records, and EMA adaptive licensing decisions; and bottom-up modeling of CRO service contracts reconciled with top-down pharmaceutical R&D expenditure analysis—were synthesized into segment-level demand estimates.
Historical growth patterns were cross-referenced against expert panel inputs to anchor projection assumptions across the analysis window. Segmentation dimensions modeled include therapeutic area, technology platform type, product category, end-user archetype, and regional regulatory cluster. CAGRs were derived from slope-intercept fitting of validated data points, with particular weighting assigned to NIH funding trajectories and orphan drug approval velocity as industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for graph neural network deployment in target identification would alter the outlook if data fragmentation across proprietary clinical trial repositories persists unresolved. Forecasts embed assumptions regarding FDA breakthrough therapy designation continuity and EMA adaptive licensing framework stability. Practitioners should monitor NIH appropriations committee priorities, EPA environmental fate guidance revisions, and ISO AI validation standard finalization for early signals of trajectory revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmacology
Hepatitis C Drug Market
Pharmacology
Global Artemisinin Combination Therapy Market
Pharmacology
Aldosterone Receptor Antagonists Market
Pharmacology
Cough Remedies Market
Pharmacology
Prescription Narcotic Cough Preparations and Expectorants Market
Pharmacology
Anti Inflammatory Therapeutics Market
Pharmacology
Immunotherapy Drugs Market
Pharmacology
Hypertension Drug Market
Pharmacology
Alzheimer's Therapeutics Market
Pharmacology
Autacoids and Related Drugs Market
Pharmacology
Global Pharmacokinetics Services Market
Pharmacology
Alzheimer Drugs Market
Pharmacology
Pegylated Drugs Market
Pharmacology
Aspirin API Market
Pharmacology
Influenza Medication Market
Pharmacology
Propranolol Drug Market