
 Hypertension Drug Market | 2026-2036
Hypertension Drug Market Size, Share, and Industry Trends Forecast 2026-2036
Hypertension Drug Market Analysis
Home care patient segments is repositioning procurement priorities across the hypertension drug supply chain. Pfizer leverages its manufacturing scale to dominate bulk oral tablet supply for large hospital systems. Novartis anchors its position through R&D intensity in combination therapies that target resistant hypertension populations. Daiichi Sankyo Company, Limited specializes in ARB-class innovations that differentiate its portfolio across Asian and European markets.
Hypertension drugs comprise pharmacological agents that modulate blood pressure through renin-angiotensin-aldosterone system inhibition, diuretic action, or sympathetic nervous system blockade, with bioavailability parameters and half-life specifications determining dosing frequency and patient adherence profiles. These agents serve the primary commercial purpose of reducing cardiovascular morbidity in chronic patient populations requiring sustained pharmacological intervention. ACE inhibitors and angiotensin II receptor blockers together command the largest revenue pool due to their established efficacy in comorbid diabetes and chronic kidney disease populations, while transdermal patches represent the fastest-growing delivery mode as manufacturers invest in patient adherence technologies. Oral tablets remain the mature volume backbone, though margin compression in this segment pushes incumbents toward specialty resistant hypertension formulations.
FDA bioequivalence standards and EMA quality guidelines shape product development timelines and generic substitution patterns across major markets, while WHO prequalification programs influence procurement decisions in lower-income healthcare systems. The EU MDR and FDA cGMP frameworks enforce manufacturing consistency that raises barriers for new entrants lacking validated production infrastructure. Stakeholders must monitor evolving pharmacovigilance requirements for ARB nitrosamine impurities and assess how real-world evidence mandates from regulators will reshape post-market clinical commitments.
Market Dynamics
CMS value-based care penalties are forcing hospital systems to expand ambulatory hypertension management programs, redirecting procurement volume toward oral tablet formulations that support patient self-administration and reduce costly readmissions.
Growth Catalysts
- Resistant hypertension populations:Combination therapies targeting patients unresponsive to first-line monotherapy are expanding addressable patient pools across chronic disease management protocols.
- EMA quality guidelines:Harmonized bioequivalence standards accelerate generic substitution patterns, lowering procurement costs for national health systems and expanding access.
- Transdermal patch technology:Manufacturers investing in adherence-monitoring delivery systems are capturing patient segments struggling with oral dosing compliance.
Market Restraints
- ARB nitrosamine impurity recalls:Pharmacovigilance-driven supply disruptions have forced batch withdrawals, creating procurement uncertainty for hospital formularies.
- API concentration in India and China:Active pharmaceutical ingredient manufacturing geographic clustering exposes supply chains to trade policy volatility and logistics bottlenecks.
- FDA cGMP compliance costs:Validated production infrastructure requirements raise capital barriers for new entrants seeking abbreviated new drug approvals.
Strategic Opportunities
- WHO prequalification programs:Lower-income healthcare systems in sub-Saharan Africa and Southeast Asia present procurement expansion pathways for manufacturers meeting international quality benchmarks.
- Home care channel expansion:Mail-order pharmacy and direct-to-patient distribution models are bypassing traditional hospital procurement for maintenance therapy refills.
- Real-world evidence mandates:Post-market clinical commitment requirements create data monetization opportunities for manufacturers with robust patient registries.
Industry Challenges
- Formulation scientist scarcity:Specialized expertise in controlled-release oral tablet development is concentrated among a limited pool of experienced pharmaceutical chemists.
- Legacy ERP integration:Hospital procurement systems require extensive customization to track lot-level nitrosamine testing documentation for ARB inventory.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hypertension Drug Market |
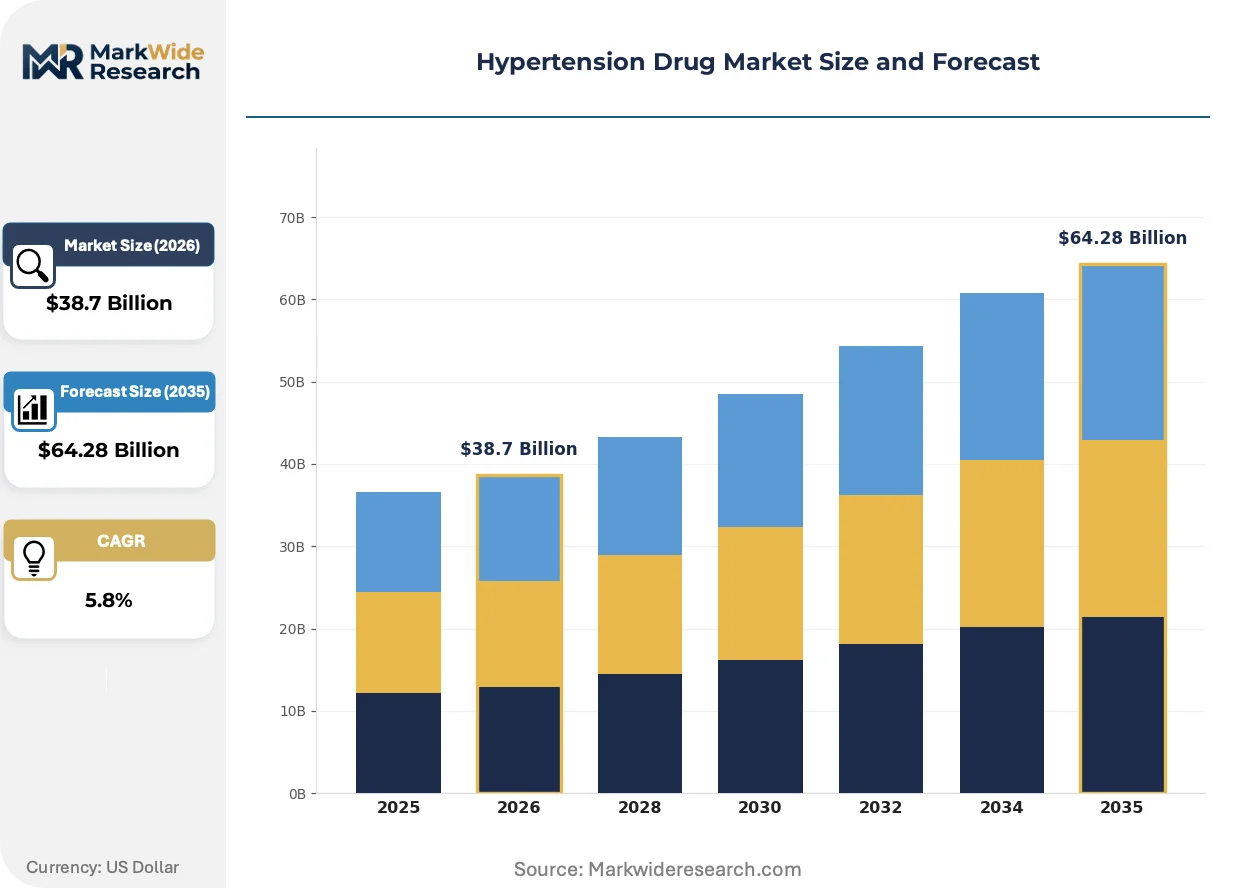
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $64.28 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: ACE Inhibitors, Angiotensin II Receptor Blockers, Diuretics, Beta Blockers Delivery Mode: Oral Tablets, Injectable Solutions, Transdermal Patches, Sublingual Sprays End User: Hospital Patients, Home Care Patients, Ambulatory Patients, Pharmacies Therapy Area: Primary Hypertension, Secondary Hypertension, Resistant Hypertension, Pediatric Hypertension |
| Companies Covered | Pfizer, Novartis, AstraZeneca, Sanofi, Bayer, Boehringer Ingelheim International GmbH, Merck, Johnson & Johnson Services, Inc., Daiichi Sankyo Company, Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hypertension Drug Market Emerging Trajectories
Patient adherence technologies are reshaping competitive differentiation in hypertension therapeutics, with delivery mechanism innovation outpacing molecular discovery in near-term value creation.
Transdermal patch systems incorporating electronic monitoring sensors are overtaking conventional oral tablets in adherence-critical patient segments. Large hospital systems piloting these devices for high-risk populations report measurable reductions in uncontrolled blood pressure episodes. The technology is compressing margins for generic oral tablet suppliers unable to match connected-device value propositions.
EU MDR post-market surveillance requirements are extending clinical evidence obligations for established ARB and ACE inhibitor portfolios. Manufacturers must now maintain active safety databases beyond original approval timelines, elevating compliance costs for legacy products. European hospital procurement committees are prioritizing suppliers with demonstrated MDR technical documentation completeness.
Home care patients are consolidating prescription fulfillment through integrated pharmacy-benefit platforms that bundle adherence coaching with automated refill scheduling. Traditional clinic-based dispensing models are losing volume to these vertically integrated channels. United States Medicare Advantage plans are driving this behavioral shift through star-rating incentives tied to medication adherence metrics.
Hypertension Drug Market Segmentation
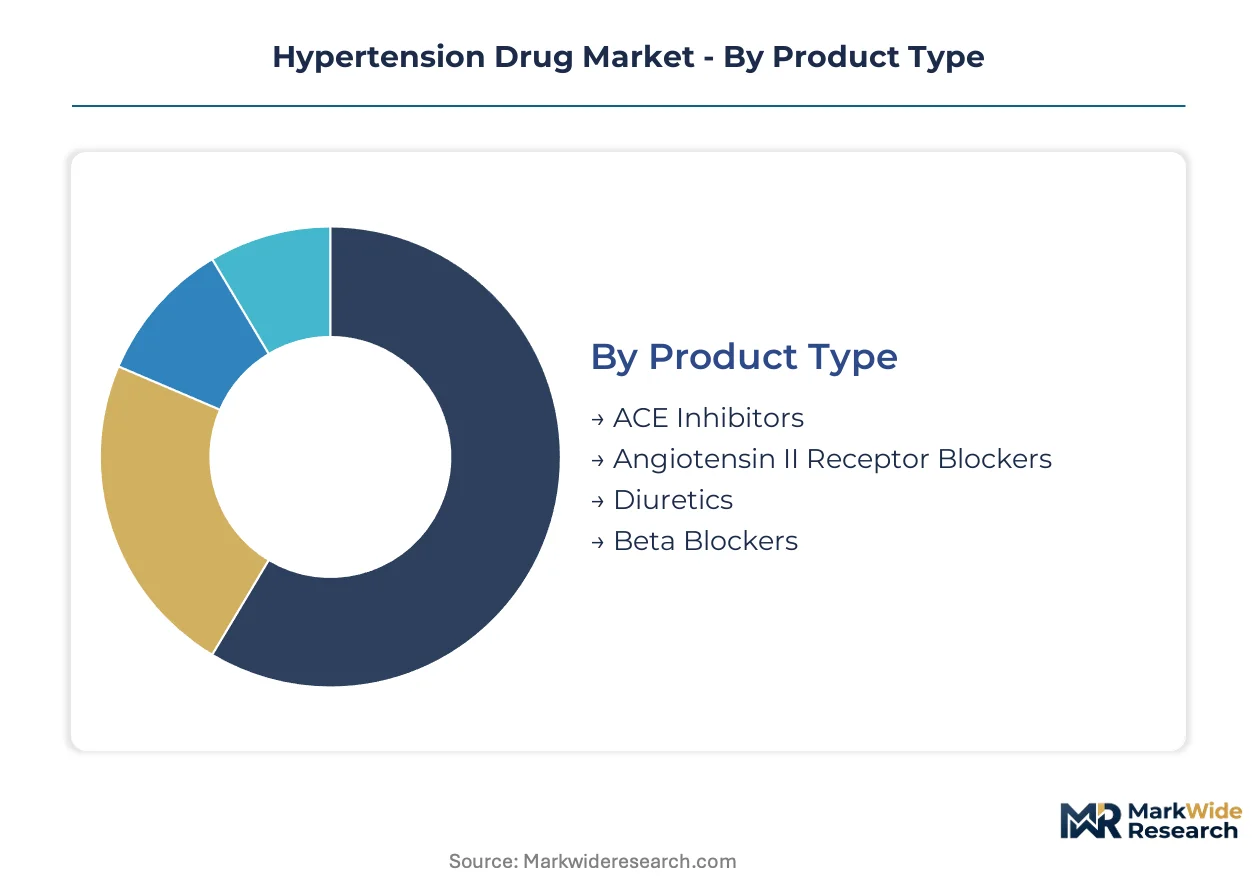
Hypertension drug procurement patterns diverge sharply across formulation types and care settings. Hospital formularies prioritize oral tablet standardization while home care channels drive demand for adherence-optimized delivery systems.
Product Type:
Renin-angiotensin-aldosterone system inhibitors anchor therapeutic protocols through distinct molecular mechanisms.
- ACE Inhibitors:These agents block angiotensin-converting enzyme to reduce peripheral vascular resistance. Demand concentrates in hospital discharge protocols for diabetic comorbidity populations where renal protection is prioritized.
- Angiotensin II Receptor Blockers:Selective AT1 receptor antagonists provide comparable efficacy with reduced cough incidence. European hospital systems favor ARB first-line prescribing following EMA cardiovascular outcome guidance.
- Diuretics:Thiazide-class agents remain foundational in stepped-care algorithms for cost-sensitive national health systems.
- Beta Blockers:Sympathetic blockade therapies retain niche positioning in hypertensive patients with concurrent heart failure or arrhythmia indications.
Mature deployment sits with ACE Inhibitors. Newer deployment is concentrated in Angiotensin II Receptor Blockers.
Delivery Mode:
Patient self-administration capability determines reimbursement eligibility and procurement volume allocation across channels.
- Oral Tablets:Immediate-release and controlled-release solid dosages dominate maintenance therapy dispensing. Home care patients in United States Medicare Advantage plans prefer 90-day mail-order supplies that reduce pharmacy visit burden.
- Transdermal Patches:Matrix-type adhesive systems enable steady-state plasma concentrations with weekly application. Japanese hospital systems pilot electronic monitoring patches for medication adherence verification in resistant hypertension populations.
- Injectable Solutions:Intravenous formulations serve acute hypertensive emergency management in emergency departments.
- Sublingual Sprays:Rapid-onset delivery addresses episodic blood pressure elevation in ambulatory settings with swallowing difficulties.
Established volume concentrates in Oral Tablets. Steepest expansion trajectory belongs to Transdermal Patches.
End User:
Care setting economics reshape distribution infrastructure and adherence support requirements.
- Hospital Patients:Inpatient acute management drives parenteral formulation procurement with formulary restriction protocols.
- Home Care Patients:Self-directed chronic disease management creates demand for patient-friendly packaging and remote monitoring integration. United States hospital systems expanding discharge planning services redirect procurement toward 30-day oral tablet starter supplies.
- Ambulatory Patients:Clinic-based monitoring programs in Germany emphasize combination therapy titration with pharmacist-led counseling.
- Pharmacies:Retail dispensing channels in India face inventory pressure from ARB nitrosamine testing documentation requirements.
Traditional procurement flows through Hospital Patients. Channel shift momentum favors Home Care Patients.
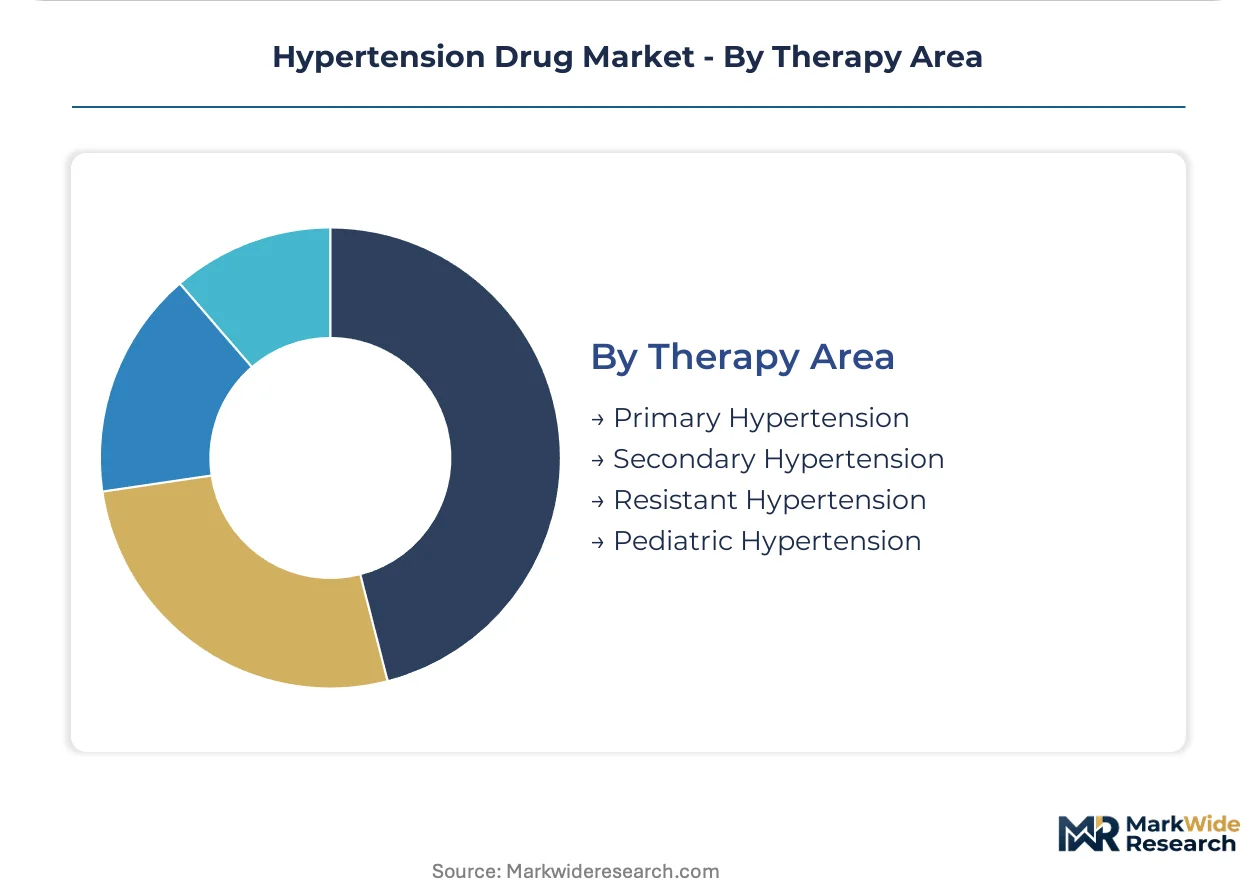
Therapy Area:
Pathophysiology classification determines treatment intensity and specialist referral patterns.
- Primary Hypertension:Essential hypertension without identifiable secondary cause represents the foundational patient population for first-line monotherapy protocols.
- Resistant Hypertension:Failure to achieve target blood pressure despite three-drug regimens including diuretic therapy. United States academic medical centers drive demand for mineralocorticoid receptor antagonist add-on therapies in this segment.
- Secondary Hypertension:Identifiable renal, endocrine, or vascular etiologies require disease-specific intervention rather than standard antihypertensive classes.
- Pediatric Hypertension:Age-appropriate dosing formulations and indication extensions remain limited compared to adult therapeutic options.
Volume concentration rests with Primary Hypertension. Unmet need expansion centers on Resistant Hypertension.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones for pharmaceutical manufacturing in India and China concentrate active pharmaceutical ingredient production, while tax-advantaged research corridors in the United States and Switzerland drive formulation innovation. Hospital procurement patterns diverge across these jurisdictions based on regulatory harmonization status and reimbursement mechanism design.
United States
Medicare Advantage star-rating incentives accelerate mail-order pharmacy adoption for maintenance antihypertensive therapy. FDA cGMP enforcement raises manufacturing compliance costs for foreign suppliers seeking abbreviated new drug approvals. The Research Triangle Park corridor in North Carolina hosts contract manufacturing organizations specializing in controlled-release oral tablet development.
Germany
EMA cardiovascular outcome guidance favors angiotensin II receptor blocker first-line prescribing in hospital discharge protocols. EU MDR post-market surveillance requirements extend clinical evidence obligations for established ACE inhibitor portfolios. The Rhine-Main pharmaceutical cluster around Frankfurt maintains concentration in combination therapy formulation facilities.
Japan
PMDA pharmacovigilance standards mandate rigorous nitrosamine impurity testing documentation for ARB imports. METI industrial policy supports transdermal patch manufacturing through targeted R&D subsidies. The Kansai region surrounding Osaka hosts specialized adhesive matrix production for electronic monitoring delivery systems.
India
CDSCO bioequivalence standards accelerate generic substitution for cost-sensitive national health system procurement. PLI scheme incentives attract formulation capacity expansion for export-oriented oral tablet manufacturing. The Hyderabad-Visakhapatnam corridor concentrates contract research organizations supporting ANDA filing for US-bound generics.
Switzerland
Swissmedic quality guidelines enforce manufacturing consistency that elevates barriers for non-European suppliers. Federal tax incentives for intellectual property holding structures concentrate combination therapy patent portfolios. The Basel biopharmaceutical cluster anchors European headquarters functions for resistant hypertension drug development.
Hypertension Drug Market Vendor Landscape
Top-tier vendors anchor hospital formulary contracting, while mid-cap specialists occupy niche resistant hypertension segments. The vendor base stratifies across three tiers: multinational incumbents with manufacturing scale, regional champions with regulatory specialization, and emerging entrants with novel delivery technologies. Strategic archetypes include scale-driven bulk suppliers, R&D-intensive combination therapy developers, and adherence-technology integrators. Dominant competitive moves encompass backward integration into active pharmaceutical ingredient production and strategic partnerships with mail-order pharmacy platforms.
Within the scale-driven tier, Pfizer and Novartis exemplify divergent strategic positioning. Pfizer leverages manufacturing footprint to dominate bulk oral tablet supply for large United States hospital systems. Novartis anchors its competitive position through R&D intensity in combination therapies targeting resistant hypertension populations. Daiichi Sankyo Company, Limited occupies a specialized position in angiotensin II receptor blocker class innovations across Asian and European markets.
| Leading Market Players |
|---|
| Pfizer |
| Novartis |
| AstraZeneca |
| Sanofi |
| Bayer |
| Boehringer Ingelheim International GmbH |
| Merck |
| Johnson & Johnson Services, Inc. |
| Daiichi Sankyo Company, Limited |
| Others |
Supply Flow & Price Mechanics
Backward integration into active pharmaceutical ingredient production anchors both supply security and pricing power for established hypertension drug manufacturers. Pfizer's captive supply of ACE inhibitor precursors insulates its oral tablet margins from Indian and Chinese API price volatility, while Novartis controls mineralocorticoid receptor antagonist synthesis through Swiss manufacturing corridors that command premium formulary positioning.
Pricing Analysis
Short lead-time premiums dominate hospital procurement negotiations, with 30-day oral tablet starter supplies commanding price advantages over 90-day mail-order contracts. Three-tier pricing structure across originator brands, authorized generics, and commodity generics stratifies procurement budgets, with FDA cGMP certification tier serving as the primary price differentiation driver. Cost compression in the generic oral tablet segment is intensifying because EMA bioequivalence harmonization accelerates substitution, while home care patients in United States Medicare Advantage plans show lowest price sensitivity due to star-rating adherence incentives.
Supply Chain Analysis
Returns and batch withdrawal flows from ARB nitrosamine recalls have forced reverse-logistics infrastructure investments across wholesale distribution networks. Active pharmaceutical ingredient manufacturing concentrates in India, China, and Switzerland, with sartan-class precursor chemistry drawing from specialized chemical intermediate suppliers in the Gujarat and Zhejiang corridors. Single-source vulnerability in ACE inhibitor catalyst supply creates procurement contingency planning requirements for European hospital systems. Distribution runs through three-tier wholesale networks in developed markets and direct government procurement channels in lower-income systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as FDA cGMP compliance costs and EMA MDR surveillance obligations force sub-scale generic manufacturers toward exit. Surviving players will capture formulary volume from distressed asset sales.
For Market Incumbents: Cement formulary lock-in through backward integration into ARB API production and investment in electronic monitoring patch R&D. Novartis-style combination therapy pipelines defend against generic erosion in resistant hypertension segments. Capture mail-order pharmacy platform partnerships before channel consolidation completes. For New Entrants and Emerging Players: Begin with WHO prequalification pathways for sub-Saharan African procurement tenders, the most penetrable geography for quality-certified generics. Target transdermal patch manufacturing partnerships with Japanese adhesive technology specialists as the differentiated entry angle. Avoid direct oral tablet competition with Pfizer-scale incumbents. For Investors and Strategic Acquirers: Exit pathways concentrate in mid-cap specialists with validated resistant hypertension pipelines and MDR-complete technical documentation. Five-to-ten year viability hinges on real-world evidence database assets that satisfy post-market surveillance mandates. Monitor EMA pharmacovigilance guidance updates for ARB class safety signals as the inflection indicator for portfolio revaluation.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Pfizer's bulk oral tablet capacity secures multi-year hospital system contracts with volume discount structures. |
| Regulatory Approval Pathway | WHO prequalification unlocks procurement eligibility across sub-Saharan African national health systems. |
| Pipeline Diversification | Novartis mineralocorticoid receptor antagonist combinations address resistant hypertension unmet need. |
| Licensing Agreement | Japanese adhesive matrix technology partnerships accelerate transdermal patch commercialization timelines. |
| Backward Integration | Captive API production insulates margins from Indian and Chinese intermediate price volatility. |
Methodological Framework
FDA filings, EMA submission databases, and ClinicalTrials.gov formed the secondary backbone of this analysis, cross-referenced with formulary database extracts and CMS Medicare utilization data. Primary interviews with drug development executives, hospital procurement managers, regulatory affairs leads, and payer access specialists validated secondary findings. Bottom-up patient population modeling and top-down pharmaceutical revenue triangulation anchored market size estimation.
Historical trendline analysis across approved antihypertensive molecule revenue trajectories informed projection frameworks over the analysis window. Segmentation modeling incorporated treatment line, dosage form, administration route, and regional regulatory cluster dimensions. CAGRs derived from patent expiry schedules, generic entry timing, and formulary shift elasticity parameters, with resistant hypertension prevalence curves and mail-order pharmacy adoption rates serving as key forecast inputs.
Underlying measurement precision varies by segment; oral tablet volume estimates carry tighter precision than transdermal patch projections due to established dispensing channel transparency. Forecasts reflect assumptions regarding EMA MDR implementation timelines and WHO prequalification program expansion. Practitioners should monitor ARB nitrosamine testing protocol changes and CMS value-based care penalty adjustments for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmacology
Anti Inflammatory Therapeutics Market
Pharmacology
Drug Eruptions Treatment Market
Pharmacology
Clot Busting Drugs Market
Pharmacology
Antimycotics Market
Pharmacology
Anti-Asthma Drugs Market
Pharmacology
Thromboprophylactic Drugs Market
Pharmacology
Aspirin API Market
Pharmacology
Global Geriatric Medicines Market
Pharmacology
Injectable Drugs Market
Pharmacology
Artemisinin Antimalarial Drugs Market
Pharmacology
Drug Repurposing Market
Pharmacology
Anti-Hypertensive Drugs Market
Pharmacology
Global Asthma Therapeutics Market
Pharmacology
Pegylated Drugs Market
Pharmacology
Ketoprofen API Market
Pharmacology
Antithrombotic Drugs Market