
 Angiotensin II Receptor Blockers (Arbs) Market | 2026-2036
Angiotensin II Receptor Blockers (Arbs) Market Size, Share, and Industry Trends Forecast 2026-2036
Angiotensin II Receptor Blockers (Arbs) Market Outlook
India is narrowing its API supply gap for sartan molecules through bulk fermentation investments and contract chemistry scale-up. Pfizer Inc. leverages vertical integration across active pharmaceutical ingredient sourcing and finished dose manufacturing to protect margin. Novartis AG anchors its position through sustained R&D intensity in fixed-dose combination therapies. Daiichi Sankyo Company Limited specializes in Asian regulatory navigation and region-specific formulation development.
Angiotensin II receptor blockers constitute a class of synthetic, nonpeptide antagonists that selectively bind AT1 receptors to inhibit vasoconstriction and aldosterone secretion, with losartan potassium representing the prototypical biphenyl tetrazole structure first approved for hypertension management. These agents serve primarily as first-line antihypertensive therapy and renoprotective treatment in diabetic populations. The valsartan product type occupies the largest revenue pool due to extensive generic substitution and cardiovascular outcome trial data supporting prescriber confidence. Extended-release capsules within the delivery mode dimension represent the fastest-growing format as patient adherence programs prioritize reduced dosing frequency. Home care settings among end users are deepening as remote blood pressure monitoring and direct-to-patient pharmacy distribution expand post-pandemic.
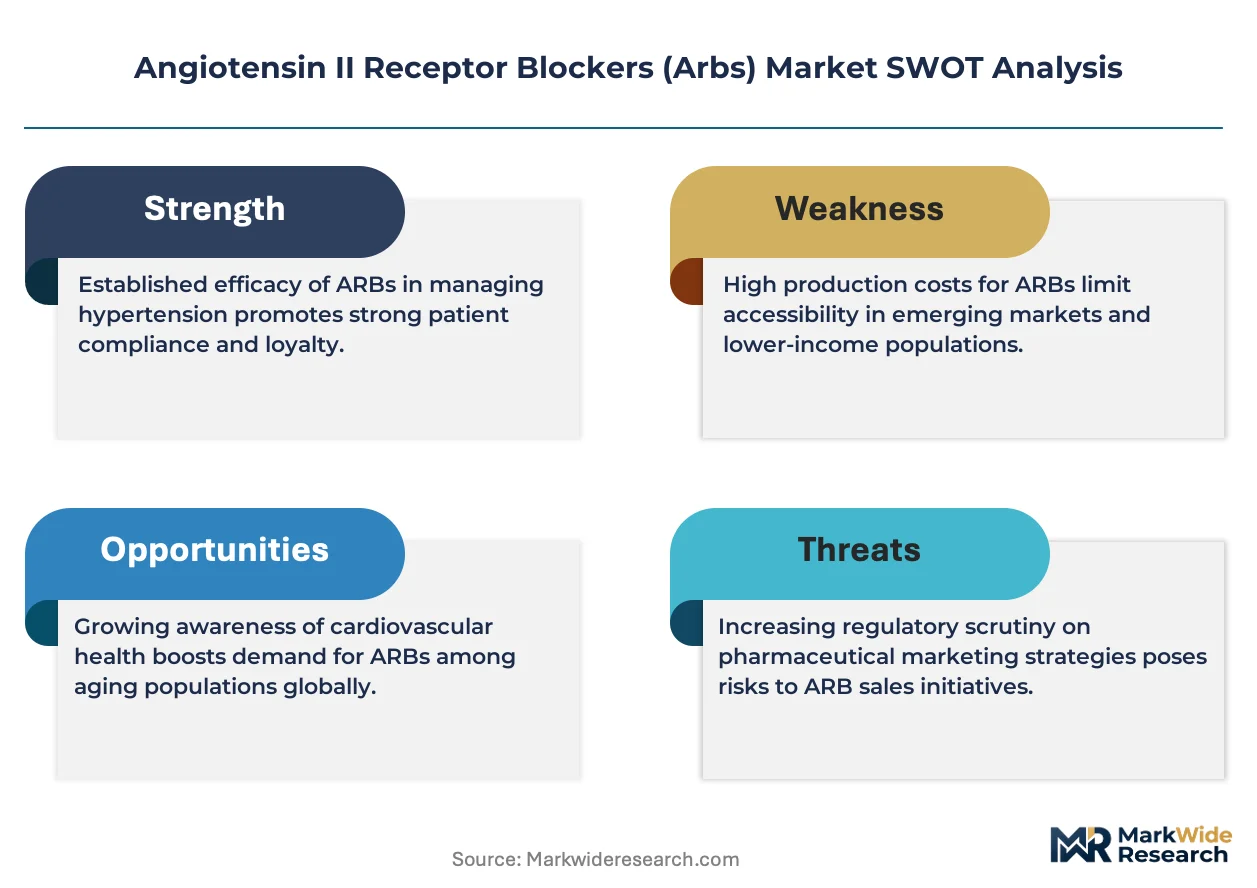
FDA enforces nitrosamine impurity testing mandates for all ARB API batches, forcing manufacturers to revalidate supply chains and upgrade analytical capabilities. EMA's revised GMP Annex 1 requirements for sterile manufacturing apply to injectable solution formats entering European markets. India's CDSCO alignment with ICH Q3D elemental impurity guidelines adds compliance layers for exporters. Stakeholders must monitor evolving pharmacopeial monograph revisions and bioequivalence study design changes that could alter competitive access timelines.
Market Dynamics
FDA nitrosamine impurity mandates and EMA revised GMP Annex 1 requirements are forcing ARB manufacturers to revalidate supply chains, upgrade analytical capabilities, and absorb compliance costs that reshape competitive economics across the value chain.
Growth Catalysts
- Cardiology protocol expansion:Hospital systems in the United States, Germany, and Japan are embedding ARBs deeper into hypertension management pathways as first-line therapy.
- Remote patient monitoring infrastructure:Post-pandemic home care settings now integrate direct-to-patient pharmacy distribution with connected blood pressure devices.
- Fixed-dose combination R&D:Sustained investment in dual-mechanism formulations addresses polypharmacy burden in diabetic populations with comorbid cardiovascular risk.
Market Restraints
- API supply concentration:Bulk fermentation capacity for sartan molecules remains geographically concentrated, exposing finished dose manufacturers to single-source vulnerability.
- Generic substitution ceiling:Valsartan's extensive generic penetration limits pricing power for originator formulations despite clinical trial differentiation.
- Analytical compliance burden:FDA batch testing mandates for nitrosamine impurities require capital-intensive HPLC-MS equipment upgrades at contract manufacturing sites.
Strategic Opportunities
- Extended-release formulation development:Reduced dosing frequency capsules address adherence gaps in elderly populations with complex medication regimens.
- Indian API manufacturing scale-up:Contract chemistry investments in bulk fermentation are narrowing the supply gap for sartan active pharmaceutical ingredients.
- Asian regulatory pathway specialization:Region-specific formulation development tailored to PMDA and CDSCO pharmacopeial requirements opens access to high-volume markets.
Industry Challenges
- Bioequivalence study redesign:Tightening FDA and EMA standards for generic valsartan purity are compressing trial timelines and raising clinical development costs.
- Legacy quality system integration:Manufacturers must harmonize ICH Q3D elemental impurity guidelines with existing GMP infrastructure across multi-site production networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Angiotensin II Receptor Blockers (Arbs) Market |
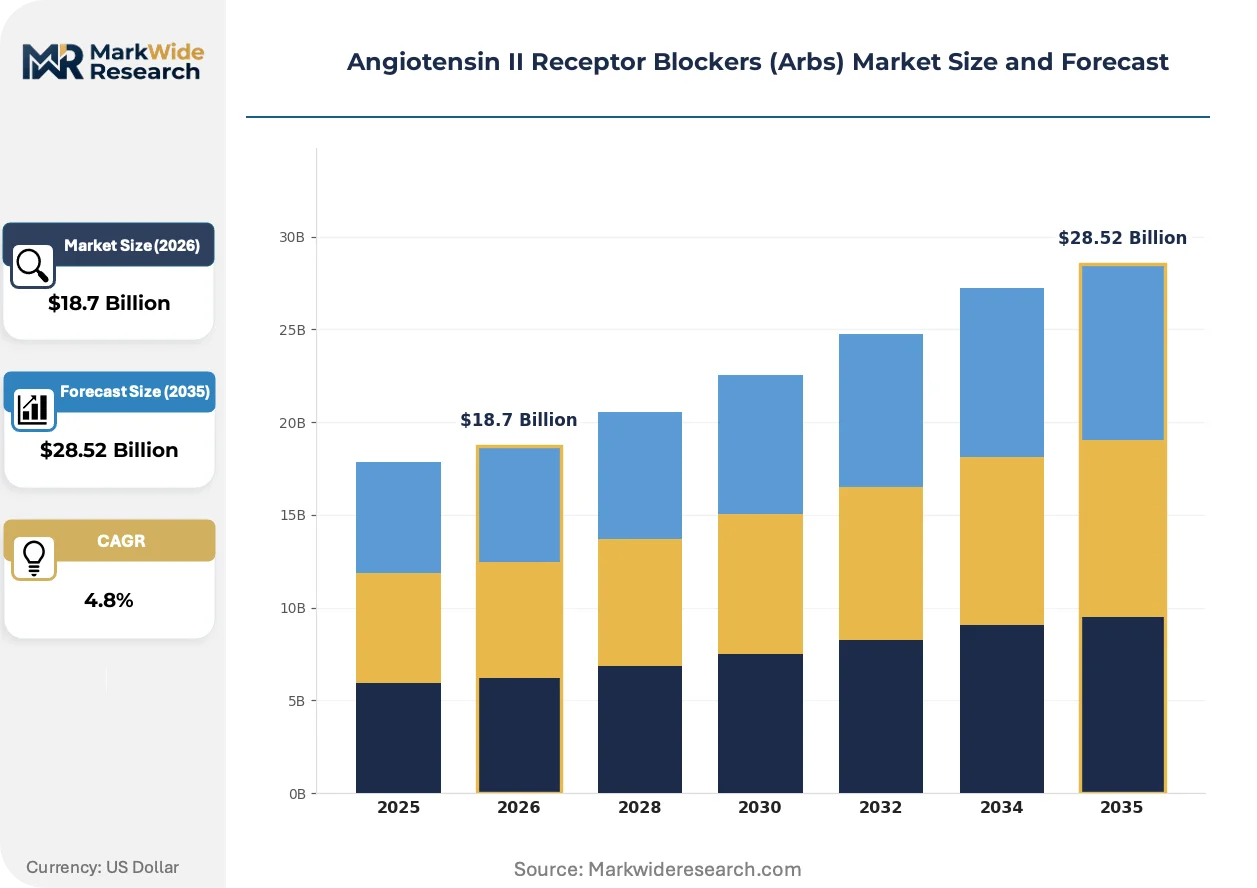
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Losartan, Valsartan, Irbesartan, Candesartan Delivery Mode: Oral Tablets, Injectable Solutions, Extended-Release Capsules, Liquid Formulations Therapy Area: Hypertension, Heart Failure, Chronic Kidney Disease, Diabetic Nephropathy End User: Hospitals, Outpatient Clinics, Home Care Settings, Pharmacies |
| Companies Covered | Pfizer Inc., Novartis AG, Merck & Co. Inc., AstraZeneca Plc., GSK Plc., Sanofi S.A., Bayer AG, Daiichi Sankyo Company Limited, Teva Pharmaceutical Industries Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Angiotensin II Receptor Blockers (Arbs) Market Strategic Shifts
Continuous manufacturing technologies and real-time release testing are displacing batch processing in ARB production, while regulatory pharmacogenomic guidance and patient stratification tools reshape prescribing patterns.
Continuous direct compression systems with integrated process analytical technology are collapsing the traditional batch release timeline for tablet formulations. Large-scale generic manufacturers in India and contract development organizations in Europe are adopting these platforms to accelerate FDA pre-approval inspection readiness. This compression of manufacturing cycle time is collapsing working capital requirements and enabling just-in-time inventory models for hospital system procurement.
EMA's evolving guidance on pharmacogenomic biomarkers in cardiovascular therapy is reshaping prescriber segmentation strategies for ARB selection. The industrial consequence is accelerated investment in companion diagnostic partnerships by formulation developers seeking differentiated positioning. Fixed-dose combination therapies targeting specific renin-angiotensin system polymorphisms are most affected, with sponsors now integrating biomarker stratification into Phase III trial designs.
Hospital system consolidation in the United States is compressing formulary decision cycles and privileging sole-source contracts for chronic disease medications. Integrated delivery networks are displacing independent physician prescribing autonomy with protocol-driven ARB selection algorithms. This behavioral shift is most visible in Medicare Advantage populations, where risk-adjusted reimbursement models reward adherence metrics over molecule-level clinical differentiation.
Angiotensin II Receptor Blockers (Arbs) Market Segmentation
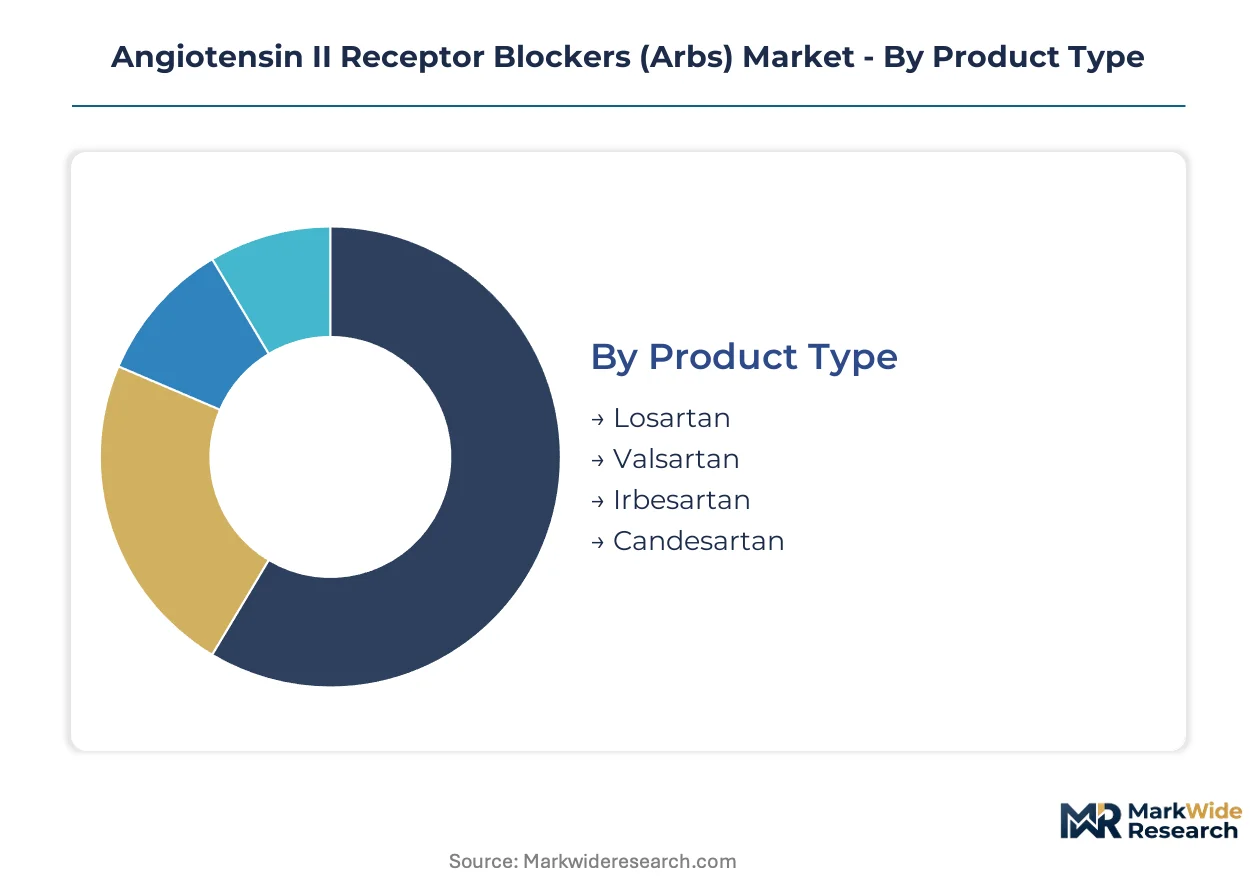
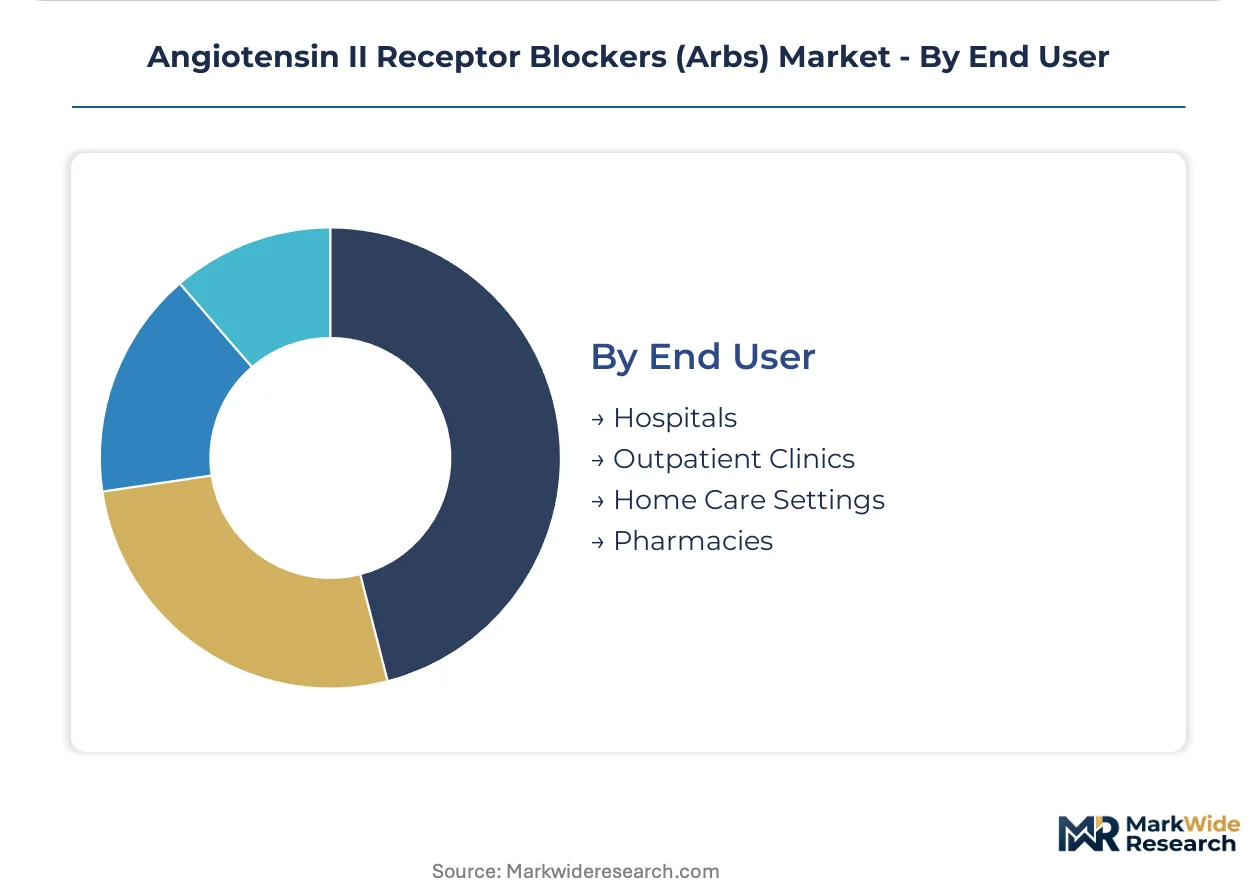
ARB prescribing patterns fragment across molecule selection, dosing convenience, and care setting economics. Manufacturers calibrate formulation investments against adherence program requirements and reimbursement pathway structures.
Product Type:
The use-case spectrum spans first-line hypertension management through renoprotective therapy in diabetic populations, with each molecule carrying distinct outcome trial histories and generic substitution profiles.
- Losartan:The prototypical biphenyl tetrazole structure established the ARB therapeutic class. Losartan potassium formulations dominate Medicare Part D formularies in the United States due to extensive generic availability and cardiovascular outcome data supporting prescriber confidence.
- Valsartan:This molecule commands the largest revenue concentration following the Valsartan Antihypertensive Long-term Use Evaluation trial. Generic substitution has compressed originator pricing power, though FDA bioequivalence tightening after nitrosamine contamination events has restored some differentiation to validated supply chains.
- Irbesartan:Renoprotective indications in type 2 diabetic nephropathy distinguish this segment.
- Candesartan:Heart failure mortality benefit data supports hospital formulary placement.
The dominant share belongs to Valsartan, while Losartan is closing the gap fastest through volume expansion in value-based care contracts.
Delivery Mode:
Cost tier differentiation separates commodity oral tablets from premium extended-release and sterile injectable formats requiring specialized manufacturing infrastructure.
- Oral Tablets:Immediate-release tablets constitute the volume baseline for chronic hypertension management. Indian contract manufacturers and large-scale generic houses in Europe compete on FDA pre-approval inspection readiness and continuous direct compression technology adoption.
- Extended-Release Capsules:Matrix-based or osmotic pump formulations reduce dosing frequency to support elderly adherence. Hospital systems in Japan and Germany are prioritizing these formats for Medicare Advantage populations where risk-adjusted reimbursement rewards medication persistence metrics.
- Injectable Solutions:Sterile ARB formulations serve acute hypertensive emergency settings in hospital systems.
- Liquid Formulations:Pediatric and dysphagia patient populations drive demand for oral solutions.
Oral tablets retain the dominant share, though extended-release capsules are gaining share fastest as integrated delivery networks consolidate formularies around adherence-optimized formats.
Therapy Area:
Application intensity concentrates in cardiovascular and renal indications where guideline-directed medical therapy mandates ARB placement.
- Hypertension:First-line antihypertensive positioning in JNC-8 and European Society of Cardiology guidelines sustains volume. United States hospital systems embed ARBs deeper into protocol-driven selection algorithms, displacing independent physician autonomy in Medicare Advantage networks.
- Diabetic Nephropathy:Renoprotective efficacy in type 2 diabetes with albuminuria represents the highest-margin application. Fixed-dose combination development with SGLT2 inhibitors is reshaping competitive positioning in this segment.
- Heart Failure:Post-myocardial infarction indications with reduced ejection fraction support hospital formulary placement.
- Chronic Kidney Disease:Proteinuria reduction independent of blood pressure control drives nephrology prescribing.
Hypertension holds the dominant share, while diabetic nephropathy is expanding most quickly through combination therapy development.
End User:
Customer type economics separate acute inpatient administration from chronic outpatient dispensing and emerging direct-to-patient models.
- Hospitals:Inpatient hypertensive emergency management and heart failure protocols drive formulary decisions. EMA revised GMP Annex 1 requirements for sterile manufacturing apply to injectable formats entering European hospital procurement systems.
- Home Care Settings:Remote blood pressure monitoring infrastructure and direct-to-patient pharmacy distribution are deepening post-pandemic. Connected device integration enables adherence tracking that supports risk-adjusted reimbursement in United States Medicare Advantage plans.
- Outpatient Clinics:Cardiology and nephrology specialty practices drive guideline-directed therapy initiation.
- Pharmacies:Retail dispensing faces generic substitution pressure and 340B program dynamics.
Hospitals command the dominant share, while home care settings are climbing the fastest through remote monitoring infrastructure deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bulk fermentation capacity for sartan active pharmaceutical ingredients clusters in India and China, exposing finished dose manufacturers in the United States, Germany, and Japan to single-source vulnerability. Cardiology departments in these demand centers are expanding ARB prescribing protocols as aging demographics sustain hypertension prevalence. Regulatory tightening around nitrosamine impurity testing is forcing supply chain revalidation across all major markets.
United States
Medicare Advantage networks are embedding ARBs deeper into protocol-driven hypertension management pathways, displacing independent physician prescribing autonomy. FDA nitrosamine impurity mandates require capital-intensive HPLC-MS equipment upgrades at contract manufacturing sites. The Greater Boston biopharma corridor hosts formulation developers integrating companion diagnostic partnerships for pharmacogenomic biomarker stratification.
Germany
Hospital system consolidation is compressing formulary decision cycles around adherence-optimized extended-release capsule formats. EMA revised GMP Annex 1 requirements for sterile manufacturing apply to injectable ARB solutions entering European procurement systems. The Rhine-Main industrial zone anchors analytical services capacity serving batch release testing for German and neighboring markets.
Japan
PMDA regulatory navigation and region-specific formulation development sustain Daiichi Sankyo's position in this high-volume market. METI industrial policy supports continuous manufacturing technology adoption to collapse batch release timelines. The Kansai pharmaceutical belt around Osaka concentrates finished dose manufacturing for domestic distribution and Asian export.
India
CDSCO alignment with ICH Q3D elemental impurity guidelines adds compliance layers for API exporters targeting regulated markets. Bulk fermentation investments in Hyderabad and Ahmedabad are narrowing the supply gap for sartan molecules. Gujarat's contract chemistry cluster is scaling continuous direct compression systems for FDA pre-approval inspection readiness.
United Kingdom
NHS Integrated Care Systems are consolidating chronic disease medication procurement around sole-source contracts for ARB therapy. MHRA post-Brexit regulatory autonomy is maintaining alignment with EMA bioequivalence standards while streamlining generic approval pathways. The Southeast England life sciences corridor houses pharmacovigilance operations supporting European market access.
Angiotensin II Receptor Blockers (Arbs) Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in API fermentation and analytical services. The market structure exhibits tiered consolidation with originator pharmaceutical companies, large-scale generic houses, and regional formulation developers occupying distinct competitive positions. Three archetypes dominate: vertically integrated multinationals controlling captive supply chains, contract development organizations specializing in regulatory navigation, and Indian API manufacturers leveraging fermentation scale. Competitive moves center on backward integration into active pharmaceutical ingredient sourcing and strategic partnerships for fixed-dose combination development.
Among vertically integrated multinationals, Pfizer Inc. and Novartis AG exemplify platform control across sourcing and finished dose manufacturing. Daiichi Sankyo Company Limited occupies a position as a regional specialist anchoring Asian regulatory pathway expertise. These three entities represent the spectrum from global scale to geography-specific formulation development, with each archetype responding differently to FDA and EMA purity tightening.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Novartis AG |
| Merck & Co. Inc. |
| AstraZeneca Plc. |
| GSK Plc. |
| Sanofi S.A. |
| Bayer AG |
| Daiichi Sankyo Company Limited |
| Teva Pharmaceutical Industries Ltd. |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in Indian bulk fermentation facilities for sartan active pharmaceutical ingredients is driving contract manufacturers to prioritize validated supply chains, compressing pricing power for unvalidated generic entrants while elevating premiums for FDA-audited batches.
Pricing Analysis
FDA nitrosamine impurity mandates dictate the pricing tier structure across the ARB market. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated originator formulations from pre-audited generic batches and unvalidated commodity supplies. Price differentiation hinges on analytical certification grade and geographic delivery cost to regulated markets. Pricing pressure stems from extensive generic substitution in valsartan, compressing originator margins. Hospital procurement committees exhibit highest price sensitivity, while specialty nephrology practices demonstrate lowest sensitivity due to outcome trial allegiance.
Supply Chain Analysis
Extended payment terms from European finished dose manufacturers are financing working capital cycles for Indian API suppliers. Bulk fermentation capacity concentrates in India and China, with secondary sourcing from Germany. Sartan molecule production draws from biphenyl tetrazole intermediates, fermentation-derived starting materials, and HPLC-MS analytical reagents. Single-source vulnerability persists for nitrosamine-tested API batches. Distribution runs through contract manufacturing organizations to hospital system procurement and direct-to-patient pharmacy channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of FDA-audited analytical testing capacity for nitrosamine compliance is concentrating margin capture among validated suppliers, leaving unvalidated manufacturers exposed to exclusion from hospital system formularies.
For Market Incumbents: Harden analytical infrastructure through HPLC-MS equipment upgrades at contract manufacturing sites to preempt regulatory exclusion. Secure captive supply of sartan APIs through backward integration into Indian fermentation capacity. Pfizer and Novartis exemplify this posture through vertical control across sourcing and finished dose manufacturing. For New Entrants and Emerging Players: Establish a beachhead in extended-release capsule formats where adherence-optimized positioning commands premium access to Medicare Advantage formularies. Target home care settings with connected blood pressure monitoring integration as the most penetrable end-user segment. Pursue Asian regulatory pathway specialization through PMDA and CDSCO pharmacopeial alignment as the primary go-to-market angle. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among contract development organizations with FDA pre-approval inspection readiness. Long-term viability across the analysis window favors platform integrators controlling captive supply chains over commodity generic houses. Target acquisition archetype: Indian API manufacturers with validated fermentation scale and European analytical services partnerships. Signal to watch: CDSCO enforcement actions against unvalidated exporters as inflection indicator for competitive consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Continuous direct compression adoption collapses batch release timelines for FDA pre-approval readiness. |
| Regulatory Approval Pathway | PMDA region-specific formulation development opens access to Japan's high-volume hypertension market. |
| Backward Integration | Captive API fermentation capacity insulates margin from nitrosamine testing mandate cost pass-through. |
| Strategic Partnership | Companion diagnostic alliances enable pharmacogenomic biomarker stratification for fixed-dose combinations. |
| Pipeline Diversification | SGLT2 inhibitor co-formulation development addresses diabetic nephropathy's highest-margin application. |
Study Parameters
Desk research of FDA filings, EMA submissions, ClinicalTrials.gov records, and pharmacopeial monograph revisions preceded structured interviews with regulatory affairs leads, hospital formulary directors, contract manufacturing executives, and API procurement managers. Primary fieldwork combined with secondary validation against customs data, SEC 10-K pharmaceutical disclosures, and CMS Medicare Part D utilization statistics. Bottom-up volume modeling and top-down value triangulation anchored segmentation outputs.
Fixed assumptions held regulatory tightening trajectory and aging demographic hypertension prevalence constant across the projection horizon, while varying generic substitution rates and continuous manufacturing adoption curves. Segmentation dimensions spanned molecule type, delivery mode, therapy area, and end-user setting. CAGRs were derived from regression analysis against historical volume trends and elasticity-adjusted pricing scenarios. Forecast inputs incorporated nitrosamine testing mandate compliance costs and extended-release formulation development pipelines.
Stress conditions across API supply disruption severity, FDA inspection enforcement intensity, and Medicare Advantage reimbursement rate adjustment were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory pathway timelines and hospital system consolidation velocity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmacology
Alzheimer Drugs Market
Pharmacology
Propranolol Drug Market
Pharmacology
Aspirin API Market
Pharmacology
Autacoids and Related Drugs Market
Pharmacology
Injectable Drugs Market
Pharmacology
Intranasal Drug and Vaccine Delivery Market
Pharmacology
Drug Repurposing Market
Pharmacology
Cough Remedies Market
Pharmacology
Drug Delivery Across the Blood-Brain Barrier Market
Pharmacology
Olanzapine API Market
Pharmacology
Drug Eruptions Treatment Market
Pharmacology
Artemisinin Antimalarial Drugs Market
Pharmacology
Antihyperlipidemic Drugs Market
Pharmacology
Global Pharmacokinetics Services Market
Pharmacology
Attention Deficit Hyperactivity Disorder (ADHD) Therapeutics Market
Pharmacology
Ibuprofen API Market