
 Prescription Narcotic Cough Preparations and Expectorants Market | 2026-2036
Prescription Narcotic Cough Preparations and Expectorants Market Size, Share, and Industry Trends Forecast 2026-2036
Prescription Narcotic Cough Preparations and Expectorants Market Outlook
Multi-source API procurement is pivoting toward captive manufacturing as DEA quota scarcity intensifies. Teva Pharmaceutical Industries anchors North American hydrocodone syrup supply through backward integration into active pharmaceutical ingredient production. Sun Pharmaceutical Industries competes on cost by operating high-volume oral liquid facilities in India. Merck KGaA differentiates through extended-release formulation technology that commands premium positioning in European hospital tenders.
Prescription narcotic cough preparations and expectorants combine opioid antitussives or non-narcotic suppressants with mucolytic agents in standardized concentrations ranging from 5 mg to 10 mg per 5 mL, manufactured under Schedule II DEA controls with tamper-evident packaging requirements. These formulations suppress cough reflex or reduce sputum viscosity in patients with persistent respiratory symptoms. Codeine-based syrups retain the largest revenue share in hospital formularies, while extended-release tablets capture the fastest-growing margin pool through reduced dosing frequency and improved compliance. Guaifenesin monotherapy segments face commoditization pressure as pharmacy chains drive generic substitution.
The U.S. Drug Enforcement Administration sets aggregate production quotas that directly constrain hydrocodone and codeine API availability, while FDA Risk Evaluation and Mitigation Strategies mandate prescriber certification for certain narcotic cough suppressants. The European Medicines Agency enforces stricter addiction-risk labeling under its pharmacovigilance framework, limiting market access for new opioid-containing entrants. Stakeholders must monitor DEA quota announcements and state-level prescription drug monitoring program expansions to anticipate supply constraints and reimbursement shifts.
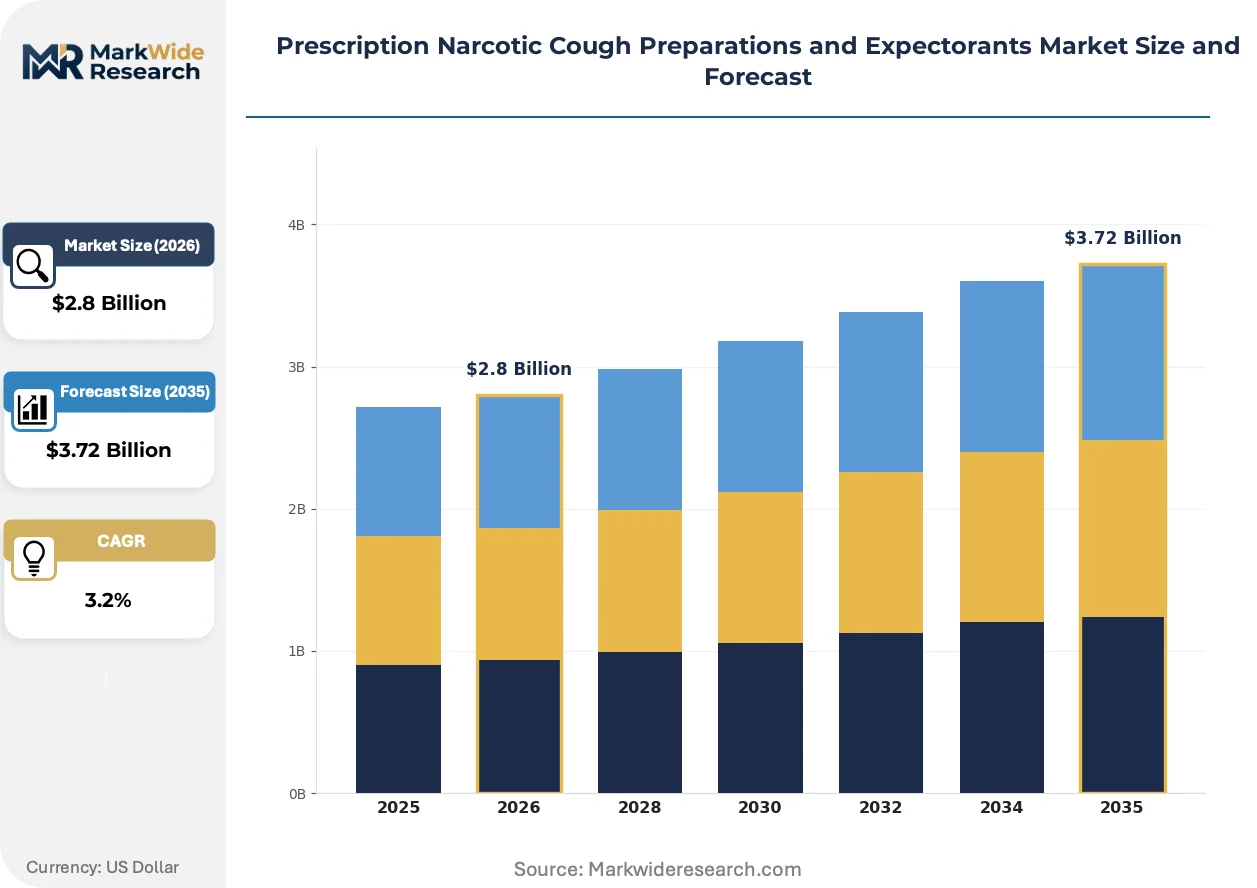
Market Dynamics
The DEA's aggregate production quota system for Schedule II controlled substances functions as the market's central constraint, directly capping hydrocodone and codeine API volumes while forcing manufacturers toward backward integration strategies.
Growth Catalysts
- Hospital formulary standardization:Large health systems in the United States are consolidating purchasing around preferred narcotic cough suppressant SKUs, concentrating volume with qualified suppliers.
- FDA Risk Evaluation and Mitigation Strategies:Prescriber certification requirements for certain opioid-containing products are filtering out marginal competitors and reinforcing positions of compliant manufacturers.
- Seasonal respiratory illness clustering:The Southeast United States generates predictable demand surges that allow inventory pre-positioning and manufacturing schedule optimization.
Market Restraints
- DEA quota scarcity:The Drug Enforcement Administration's annual hydrocodone and codeine production limits create absolute supply ceilings regardless of demand signals.
- API import dependency:Active pharmaceutical ingredient sourcing concentrates among Indian and Chinese manufacturers, exposing supply chains to geopolitical friction and customs delays.
- Generic substitution pressure:Pharmacy benefit managers and retail chains aggressively promote guaifenesin monotherapy alternatives, compressing branded expectorant margins.
Strategic Opportunities
- Extended-release formulation development:Reduced dosing frequency products command premium positioning in European hospital tenders where EMA pharmacovigilance labeling already restricts new opioid entrants.
- Captive API manufacturing:In-house production of controlled substances insulates against DEA quota volatility and creates supply security differentiation.
- Tamper-evident packaging innovation:Advanced closure technologies address FDA abuse-deterrence expectations while creating patent-protected product distinctions.
Industry Challenges
- Controlled substance compliance expertise:DEA registration maintenance, quota application processes, and security protocol auditing require specialized regulatory affairs personnel in short supply.
- Legacy liquid manufacturing infrastructure:Oral syrup production lines demand capital-intensive stainless steel equipment and dedicated cleaning validation protocols that resist rapid product changeover.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Prescription Narcotic Cough Preparations and Expectorants Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $3.72 Billion |
| CAGR (2026 – 2036) | 3.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Codeine, Hydrocodone, Dextromethorphan, Guaifenesin Use Case: Chronic Cough, Acute Cough, Post-Surgical, Allergic Cough Delivery Mode: Oral Liquid, Tablets, Syrup, Extended-Release End User: Hospitals, Clinics, Pharmacies, Home Care |
| Companies Covered | Teva Pharmaceutical Industries, Zydus Lifesciences, Franklin Laboratories, Perrigo Company, Sun Pharmaceutical Industries, Johnson & Johnson, Sanofi, Merck KGaA, Mylan, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Prescription Narcotic Cough Preparations and Expectorants Market Strategic Shifts
Formulation science and regulatory compliance technology are converging to reshape how narcotic cough preparations are manufactured, tracked, and prescribed across controlled substance supply chains.
Automated dispensing and inventory management systems are automating hospital pharmacy workflows for Schedule II narcotics. Large integrated delivery networks in the United States are deploying these platforms to reduce diversion risk and satisfy DEA record-keeping mandates. The technology is automating compliance documentation while compressing labor costs in high-volume dispensing environments.
EMA's stricter addiction-risk labeling requirements under its pharmacovigilance framework are limiting market access for new opioid-containing cough preparations in Europe. Manufacturers must now generate additional safety data before approval, extending development timelines and raising entry costs. Extended-release tablet developers are responding by targeting hospital tenders where clinical pharmacists influence formulary decisions.
Prescription drug monitoring program integration is altering prescriber behavior in state-level implementations across the United States. Real-time patient history access is reducing duplicate prescribing and enabling intervention protocols. The Southeast region shows the most pronounced shift as seasonal volume peaks now trigger automated alerts for high-frequency prescribers.
Prescription Narcotic Cough Preparations and Expectorants Market Segmentation
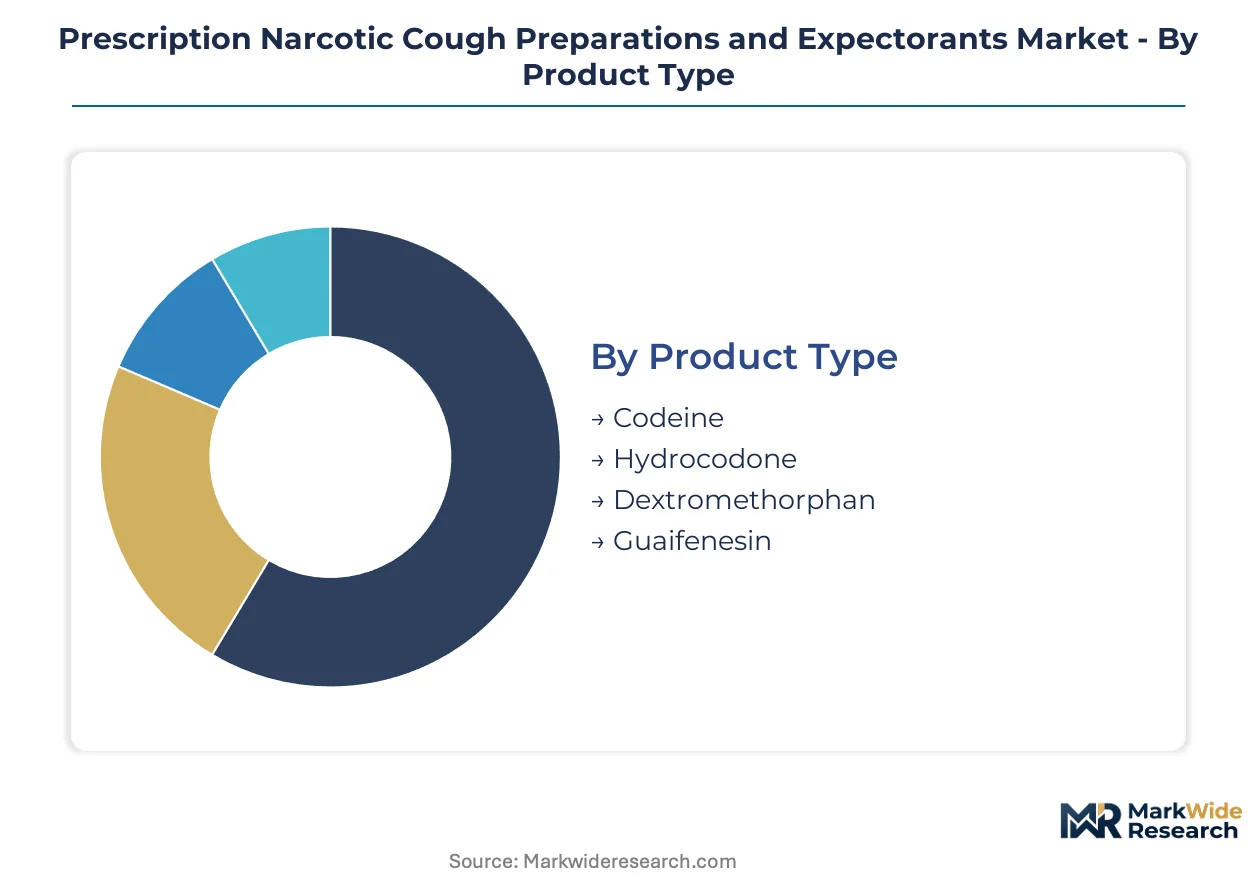
DEA quota scarcity forces manufacturers to prioritize high-margin segments while pharmacy benefit managers drive commoditization in others. Segmentation reveals where formulation complexity creates defensible positioning versus where generic substitution erodes returns.
Product Type:
Formulation chemistry determines regulatory burden, manufacturing complexity, and pricing power across this controlled substance market.
- Codeine:Morphine-derived Schedule II opioid requiring tamper-evident packaging and DEA quota allocation. Hospital formularies in the United States Southeast concentrate demand during seasonal respiratory peaks, though EMA addiction-risk labeling restricts European access for new entrants.
- Hydrocodone:Semi-synthetic opioid with higher potency per milligram, commanding premium positioning in post-surgical recovery protocols. Backward integration into API production insulates manufacturers from DEA production quota volatility.
- Dextromethorphan:Non-narcotic suppressant avoiding Schedule II controls and enabling broader retail pharmacy distribution without prescriber certification requirements.
- Guaifenesin:Expectorant monotherapy facing aggressive generic substitution pressure from pharmacy chains, compressing branded margins toward commodity levels.
Codeine leads volumes today; hydrocodone is gaining share fastest through hospital formulary consolidation.
Use Case:
Clinical setting and symptom duration shape prescriber authority, reimbursement pathways, and formulation selection.
- Chronic Cough:Persistent symptoms exceeding eight weeks requiring specialist referral and extended-release formulations. European hospital tenders favor reduced dosing frequency products under EMA pharmacovigilance frameworks.
- Acute Cough:Short-duration symptoms from viral infection driving seasonal volume surges. United States Southeast clusters generate predictable demand spikes enabling inventory pre-positioning.
- Post-Surgical:Hospital-controlled recovery protocols mandating hydrocodone-based suppressants with documented diversion-risk protocols.
- Allergic Cough:Antihistamine combination therapies competing with non-narcotic alternatives in outpatient clinic settings.
Acute cough dominates prescription counts; chronic cough commands the steepest expansion trajectory through extended-release adoption.
Delivery Mode:
Manufacturing infrastructure investment and abuse-deterrence requirements segment competitors by capital intensity.
- Oral Liquid:Standardized 5 mg to 10 mg per 5 mL concentrations requiring stainless steel production lines and dedicated cleaning validation protocols. Legacy infrastructure resists rapid product changeover.
- Tablets:Solid dose forms enabling precise unit-dose packaging and automated hospital dispensing system integration.
- Syrup:Flavored liquid preparations targeting pediatric compliance with sugar-free formulation variants.
- Extended-Release:Matrix or reservoir technologies commanding premium positioning where reduced dosing frequency improves compliance. FDA Risk Evaluation and Mitigation Strategies filter out non-compliant competitors.
Oral liquid maintains manufacturing scale leadership; extended-release climbs the fastest through European hospital tender capture.
End User:
Purchasing consolidation and regulatory compliance sophistication separate high-barrier institutional buyers from price-sensitive retail channels.
- Hospitals:Integrated delivery networks consolidating formularies around preferred SKUs with automated dispensing platforms satisfying DEA record-keeping mandates. Large United States health systems concentrate volume with qualified suppliers.
- Clinics:Outpatient settings requiring prescription drug monitoring program integration to reduce duplicate prescribing and enable intervention protocols.
- Pharmacies:Retail chains aggressively promoting generic guaifenesin substitution, compressing branded expectorant margins through pharmacy benefit manager steering.
- Home Care:Long-term respiratory management with caregiver-administered dosing, expanding through aging population demographics.
Hospitals anchor procurement concentration; home care expands most quickly through chronic condition management shift.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States Southeast anchors global prescription narcotic cough preparation consumption through seasonal respiratory illness clustering and hospital formulary consolidation. DEA quota allocations and FDA Risk Evaluation and Mitigation Strategies shape manufacturing capacity and prescriber certification requirements across the country. Four additional markets demonstrate distinct regulatory and demand profiles.
United States
Hospital procurement of hydrocodone-based syrups is expanding through integrated delivery network consolidation around preferred SKUs. The DEA's aggregate production quota system caps API availability regardless of demand signals from the Southeast's seasonal peaks. Atlanta and Nashville health systems deploy automated dispensing platforms to satisfy record-keeping mandates while reducing diversion risk.
Germany
Extended-release tablet formulations command premium positioning in hospital tenders where clinical pharmacists influence formulary decisions. EMA pharmacovigilance frameworks enforce stricter addiction-risk labeling that limits new opioid-containing entrants. The Rhine-Ruhr industrial corridor hosts formulation technology specialists serving European institutional buyers.
India
High-volume oral liquid manufacturing facilities compete on cost through API export and finished dosage form production for regulated markets. CDSCO oversight and DEA import restrictions create dual compliance burdens for Schedule II controlled substance shipments. Gujarat and Maharashtra pharmaceutical clusters concentrate backward-integrated hydrocodone and codeine production capacity.
United Kingdom
Prescription drug monitoring program integration is altering prescriber behavior through real-time patient history access and intervention protocols. MHRA guidelines align with EMA pharmacovigilance standards while maintaining distinct national formularies. London and the Southeast anchor specialist respiratory referral networks managing chronic cough cases exceeding eight weeks duration.
Japan
PMDA review timelines for opioid-containing cough preparations extend development schedules compared to non-narcotic alternatives. METI industrial policy supports domestic formulation manufacturing despite API import dependency from Indian and Chinese suppliers. The Kanto region around Tokyo concentrates hospital pharmacy automation deployment for controlled substance inventory management.
Prescription Narcotic Cough Preparations and Expectorants Market Competitive Environment
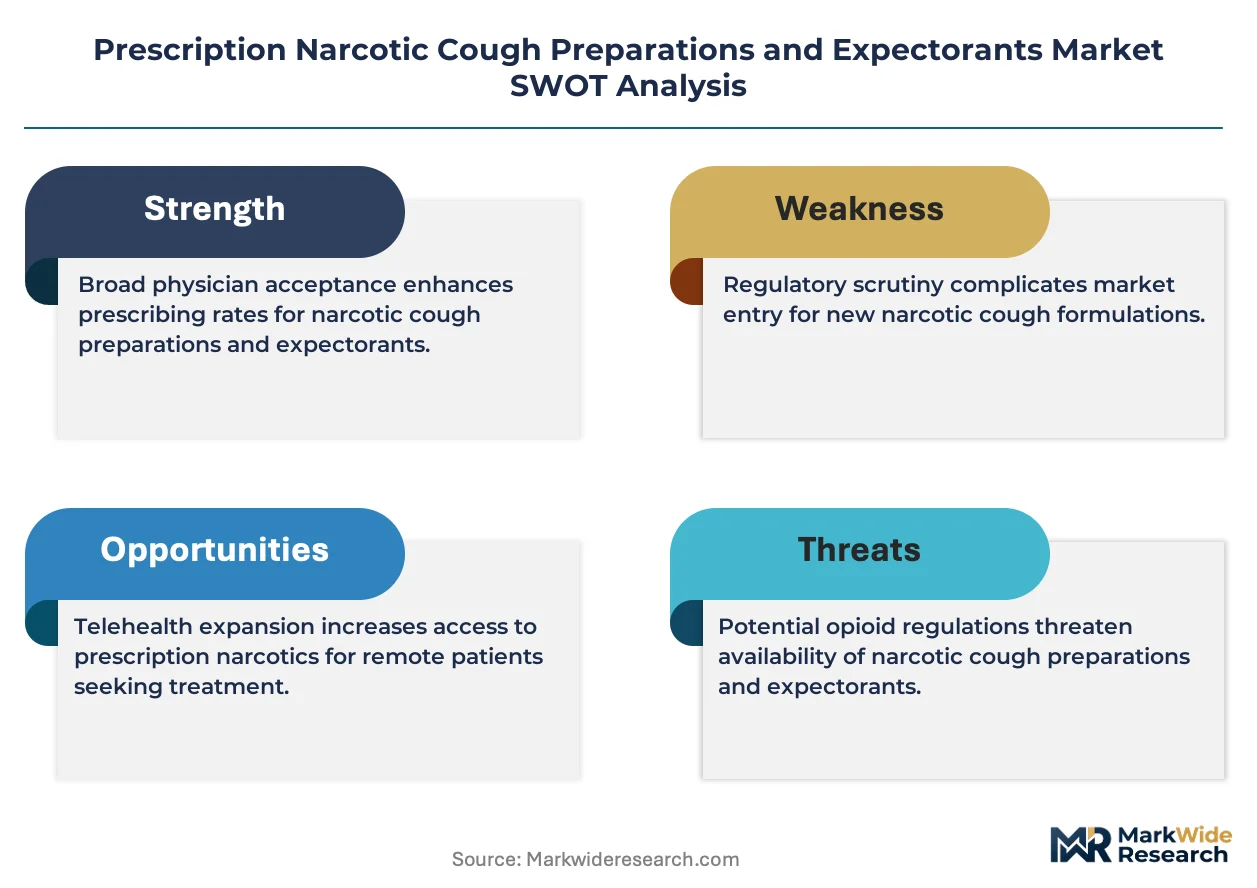
Global majors compete with regional champions across DEA quota access and formulation technology differentiation. Market structure tilts toward consolidation as backward integration requirements and controlled substance compliance expertise filter out marginal participants. Three archetypes dominate: integrated API-to-dosage manufacturers, high-volume oral liquid specialists, and extended-release technology licensors. M&A activity targets captive manufacturing assets while portfolio diversification moves emphasize tamper-evident packaging patents.
Within the integrated manufacturing tier, Teva Pharmaceutical Industries anchors North American hydrocodone syrup supply through in-house API production that insulates against quota volatility. Sun Pharmaceutical Industries exemplifies cost-competitive oral liquid manufacturing from Indian facilities serving export markets. Merck KGaA occupies a premium technology position through extended-release formulation capabilities that satisfy European hospital tender requirements under EMA pharmacovigilance constraints.
| Leading Market Players |
|---|
| Teva Pharmaceutical Industries |
| Zydus Lifesciences |
| Franklin Laboratories |
| Perrigo Company |
| Sun Pharmaceutical Industries |
| Johnson & Johnson |
| Sanofi |
| Merck KGaA |
| Mylan |
| Others |
Value Chain & Pricing Dynamics
Automated dispensing platform deployment across United States hospital systems simultaneously compresses labor costs and concentrates procurement volume with qualified suppliers possessing DEA registration and quota access. This technology shift reshapes cost economics by reducing diversion-related losses while amplifying pricing power for manufacturers with compliant supply chains.
Pricing Analysis
API cost pass-through from Indian and Chinese hydrocodone and codeine suppliers drives contract-based long-term offtake pricing for oral liquid formulations. Price differentiation hinges on DEA quota security and tamper-evident packaging certification, with hospital systems least sensitive to price and retail pharmacies most responsive to generic guaifenesin substitution. Pricing pressure stems from pharmacy benefit manager steering toward non-narcotic alternatives, compressing branded expectorant margins.
Supply Chain Analysis
Regional distribution centers in the United States Southeast pre-position inventory ahead of seasonal respiratory peaks, creating hub-and-spoke patterns anchored by Atlanta and Nashville health system networks. API production concentrates in India, China, and the United States, with finished dosage form manufacturing drawing from stainless steel syrup production lines in Gujarat and Maharashtra. Single-source vulnerability rests on DEA import restrictions for Schedule II controlled substances. Distribution runs through integrated delivery networks with automated compliance documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily through chronic cough prevalence expansion and extended-release formulation adoption, with demographic aging and hospital formulary consolidation providing durable demand underpinnings.
For Market Incumbents:Acquire captive API manufacturing assets to insulate against DEA quota volatility and create supply security differentiation. Secure additional Schedule II controlled substance registrations in high-demand states before prescription drug monitoring program expansions tighten prescriber certification requirements. Backward integration into hydrocodone production anchors margin defense against Indian cost competitors.
For New Entrants and Emerging Players:The premium-economy price gap in extended-release tablets creates white-space opportunity for matrix technology specialists targeting European hospital tenders. Focus initial penetration on chronic cough segments where EMA pharmacovigilance frameworks already restrict new opioid entrants, reducing competitive intensity. Pursue licensing partnerships with established DEA-registered manufacturers to bypass quota application barriers.
For Investors and Strategic Acquirers:Valuations sit cheapest among oral liquid manufacturers facing generic substitution pressure without extended-release technology pipelines. Five-to-ten year viability favors backward-integrated players with DEA quota history and hospital system contract concentration. Monitor DEA aggregate production quota announcements as the critical inflection signal for supply-constrained pricing power shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive API Manufacturing Acquisition | Backward integration into hydrocodone production insulates Teva against DEA quota scarcity. |
| Extended-Release Formulation Development | Matrix technology commands premium positioning in German hospital tenders under EMA constraints. |
| Automated Dispensing Platform Deployment | Atlanta health systems reduce diversion risk while satisfying DEA record-keeping mandates. |
| Tamper-Evident Packaging Patent Filing | Advanced closure technologies create FDA-compliant abuse-deterrence differentiation. |
| Prescription Drug Monitoring Program Integration | Real-time patient history access reduces duplicate prescribing in Southeast United States clinics. |
Study Parameters
Direct dialogue with formulary directors, DEA compliance officers, hospital procurement managers, and regulatory affairs specialists grounded qualitative insights in operational reality. Secondary validation drew from FDA Risk Evaluation and Mitigation Strategy filings, DEA aggregate production quota announcements, CMS Medicare Part D utilization data, and state-level prescription drug monitoring program expansion records. Bottom-up prescription volume modeling and top-down pharmaceutical spending allocation triangulated market sizing across the analysis window.
Bottom-up demand modeling segmented by product type, delivery mode, and end user generated volume foundations, while top-down healthcare expenditure allocation confirmed value projections throughout the forecast period. CAGRs derived from historical prescription trends, demographic projections, and regulatory constraint modeling across formulation categories. Forecast inputs incorporated DEA quota trajectory assumptions and EMA pharmacovigilance framework evolution.
Caveats apply where DEA production quota reductions, EMA addiction-risk labeling expansion, or generic substitution acceleration could materially shift the outlook. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmacology
Anti-Asthma Drugs Market
Pharmacology
Intranasal Drug and Vaccine Delivery Market
Pharmacology
Drug Delivery Across the Blood-Brain Barrier Market
Pharmacology
Propranolol Drug Market
Pharmacology
UK Pharmacovigilance Market
Pharmacology
Alzheimer's Therapeutics Market
Pharmacology
Anti-Obesity Therapeutics Market
Pharmacology
Ketoprofen API Market
Pharmacology
Angiotensin II Receptor Blockers (Arbs) Market
Pharmacology
Global Geriatric Medicines Market
Pharmacology
Global Olanzapine Market
Pharmacology
Antitussive Drugs Market
Pharmacology
Olanzapine API Market
Pharmacology
Hepatitis C Drug Market
Pharmacology
Immunotherapy Drugs Market
Pharmacology
Anti-Hypertensive Drugs Market