
 Pegylated Drugs Market | 2026-2036
Pegylated Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Pegylated Drugs Market Outlook
Hospital procurement consolidation is rebalancing buying power toward integrated delivery networks across North America and Western Europe. Amgen Inc. leverages its legacy pegfilgrastim franchise to sustain manufacturing scale advantages in oncology support care. Pfizer Inc. competes through biosimilar pegfilgrastim positioning, while Novo Nordisk A/S anchors its diabetes and obesity portfolio with PEGylated peptide expertise.
Pegylated drugs attach polyethylene glycol chains to therapeutic proteins, peptides, or small molecules to extend circulating half-life, reduce immunogenicity, and improve solubility through steric hindrance and hydrodynamic radius enlargement. The oncology therapy area dominates current revenue pools due to established neutropenia and anemia management protocols, while infectious disease applications show structural momentum as long-acting antiviral PEG-interferon derivatives address adherence gaps. Injectable formulations maintain market leadership given the biological complexity of PEG-protein conjugates, though transdermal research programs target patient compliance improvements in chronic administration settings.
FDA biosimilar guidance and EMA's quality guidelines for PEGylated biologics create dual compliance thresholds for market entry, with ISO 10993 biocompatibility standards adding material safety verification layers. The WHO's prequalification pathway for essential biologics shapes access dynamics in lower-income health systems. Stakeholders must monitor evolving immunogenicity assessment requirements and payer real-world evidence demands to anticipate portfolio repositioning needs.
Market Dynamics
Hospital procurement consolidation is concentrating buying power within integrated delivery networks, forcing manufacturers to restructure pricing and service models around formulary access rather than individual physician preference.
Growth Catalysts
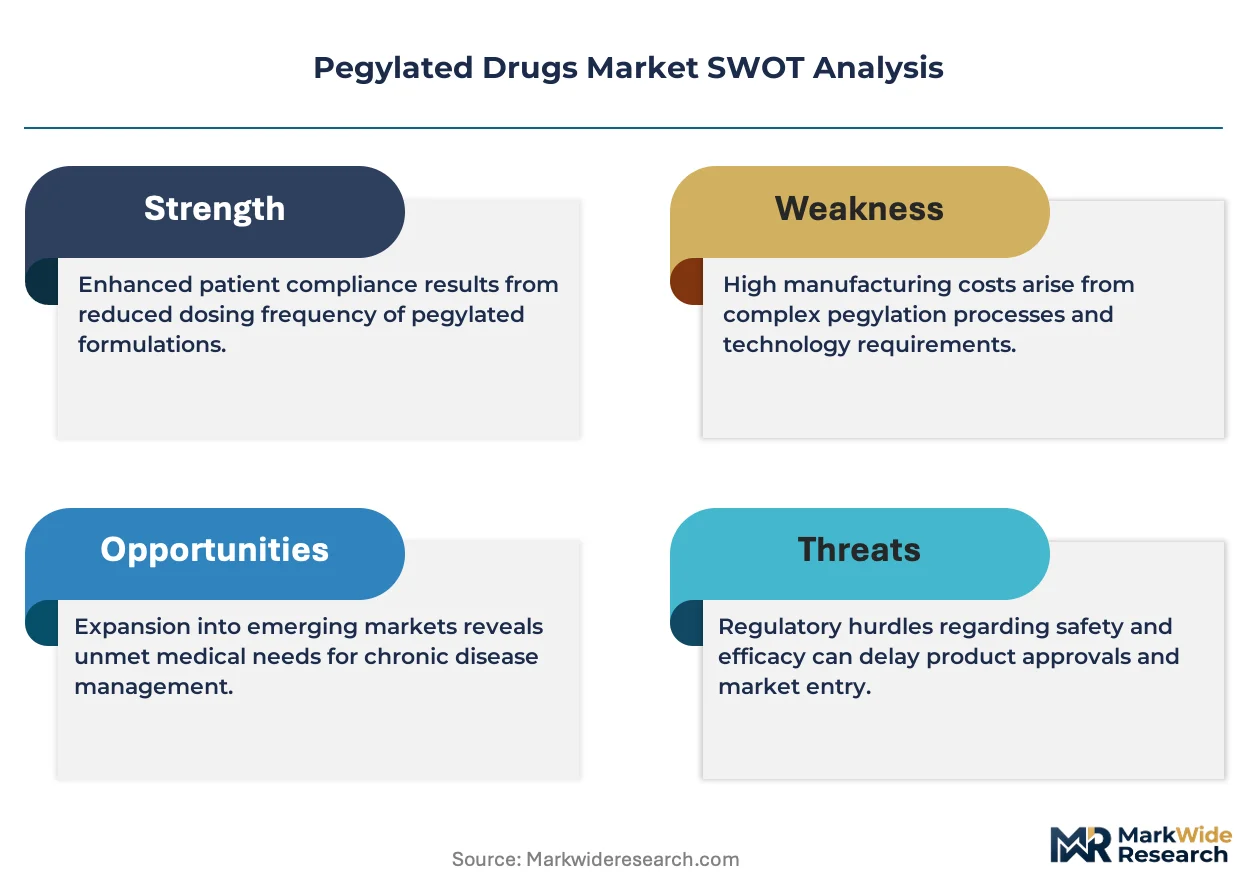
- FDA Biosimilar Pathway:The abbreviated approval framework accelerates competitive entry for PEGylated protein therapies, expanding patient access while pressuring originator pricing.
- Oncology Support Care Expansion:Hospital systems in the United States and Germany are embedding pegfilgrastim into first-line neutropenia protocols, creating institutional demand pull.
- PEGylation Chemistry Advances:Site-specific conjugation technologies reduce batch heterogeneity, improving manufacturing yields and regulatory submission quality.
Market Restraints
- Raw Material Concentration:High-purity polyethylene glycol supply concentrates among specialty chemical producers in China and Germany, creating input vulnerability.
- Immunogenicity Assessment Burden:EMA's evolving guidance on anti-PEG antibody detection extends development timelines and increases clinical trial costs.
- Biologic Substitution Limits:Pharmacist-level interchangeability remains restricted for PEGylated proteins, limiting automatic substitution that drives volume in small-molecule generics.
Strategic Opportunities
- Diabetes and Obesity Portfolio Extension:PEGylated peptide architectures enable weekly dosing for GLP-1 receptor agonists, addressing adherence gaps in chronic metabolic management.
- WHO Prequalification Pathway:Essential biologics designation for PEG-interferon opens procurement channels in lower-income health systems through multilateral purchasing.
- Transdermal Delivery Research:Microneedle array technologies targeting PEG-protein administration are advancing through preclinical programs, potentially displacing injectable dependence.
Industry Challenges
- Analytical Methodology Standardization:PEG molecular weight distribution characterization lacks harmonized protocols across FDA and EMA, creating duplicate validation requirements.
- Specialized Manufacturing Talent Scarcity:Conjugation chemistry expertise and aseptic processing for high-viscosity biologics concentrates among limited contract development organizations.
- Legacy Formulation Integration:PEGylated drug products require cold-chain infrastructure incompatible with last-mile distribution networks in tropical climates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pegylated Drugs Market |
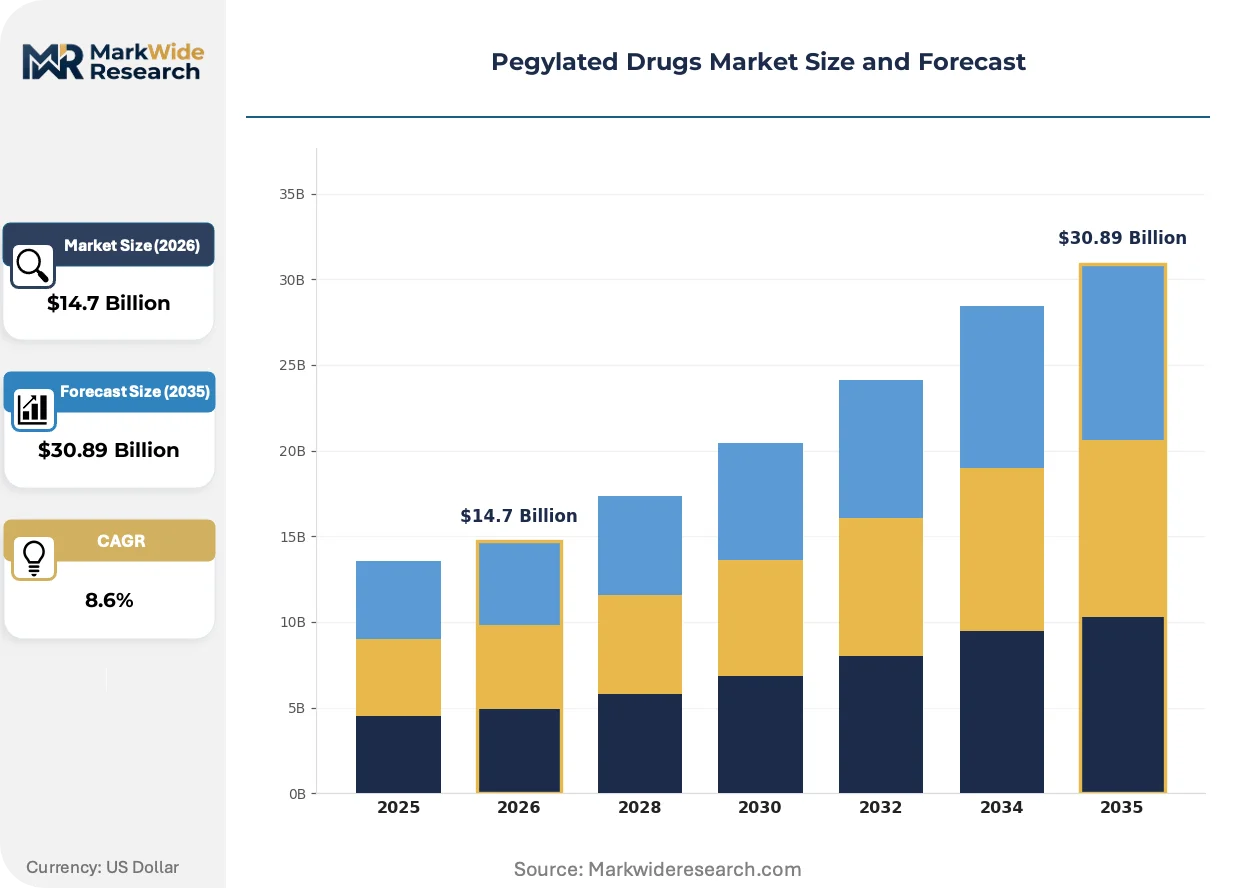
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $30.89 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Therapy Area: Oncology, Hematology, Rheumatology, Infectious Diseases Formulation Type: Injectable, Oral, Transdermal, Implantable End User: Hospitals, Clinics, Research Institutions, Homecare Manufacturing Process: Synthetic, Biotechnological, Purification, Quality Control |
| Companies Covered | Amgen Inc., Pfizer Inc., Merck & Co., Inc., Roche, AstraZeneca, Novo Nordisk A/S, Teva Pharmaceutical Industries Ltd, Bristol-Myers Squibb, Nektar Therapeutics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pegylated Drugs Market Strategic Shifts
PEGylation technology is extending beyond oncology into metabolic and infectious disease applications, while regulatory frameworks evolve to accommodate next-generation conjugation architectures.
Site-specific PEGylation using enzymatic ligation and click chemistry is rewriting manufacturing economics for complex biologics. Contract manufacturers in Switzerland and Massachusetts are adopting these platforms to reduce batch failure rates. The shift is compressing time-to-market for second-generation PEGylated therapies.
EMA's 2023 revision to quality guidelines for PEGylated biologics mandates enhanced characterization of PEG shedding and metabolite profiling. Manufacturers must now submit additional stability data covering forced degradation conditions. Oncology-focused drug developers in Germany and France are restructuring CMC packages to preempt regulatory queries.
Integrated delivery networks in the United States are consolidating pegylated drug procurement under pharmacy benefit managers, displacing traditional wholesaler relationships. Hospital systems now negotiate multi-year supply agreements tied to real-world evidence generation. This concentration is most visible in California and Texas, where IDN market share exceeds sixty percent of institutional volume.
Pegylated Drugs Market Segmentation
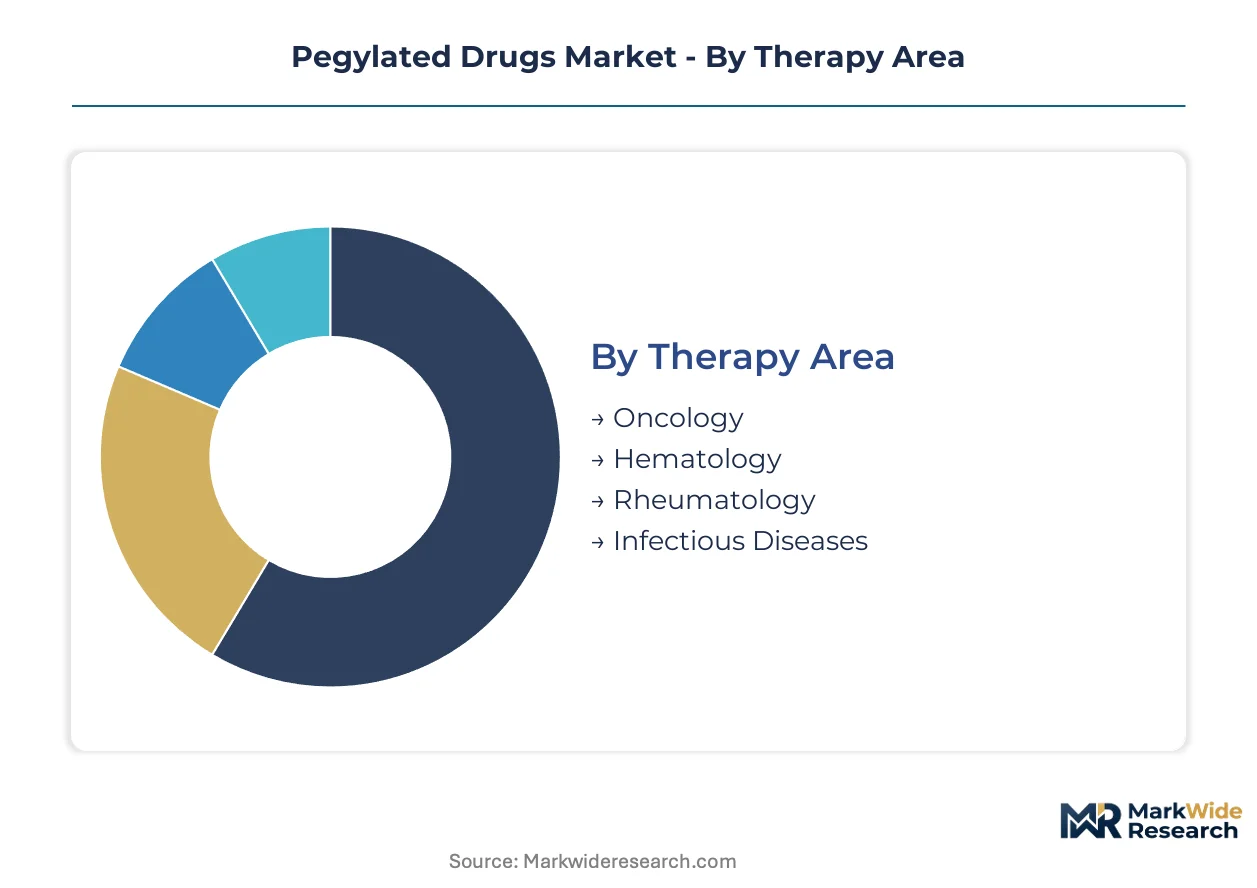
PEGylated drug architectures vary dramatically across therapeutic applications, with formulation complexity and manufacturing constraints dictating viable commercial pathways. Supply chain configuration and end-user infrastructure requirements fragment competitive positioning across each dimension.
Therapy Area:
Oncology commands the deepest manufacturing expertise and highest purity PEG inputs, concentrating contract manufacturing capacity in Switzerland and Massachusetts.
- Oncology:Neutropenia and anemia management protocols anchor current revenue pools, with hospital systems in the United States and Germany embedding pegfilgrastim into first-line biologic regimens. Site-specific conjugation technologies are compressing batch failure rates for complex PEG-protein architectures.
- Hematology:Stem cell mobilization and myeloproliferative disorder applications require extended circulating half-life profiles that only branched PEG configurations achieve. Academic medical centers in Japan and Germany drive protocol standardization for these indications.
- Rheumatology:PEGylated cytokine inhibitors address dosing frequency limitations in chronic inflammatory management.
- Infectious Diseases:Long-acting PEG-interferon derivatives target adherence gaps in hepatitis and emerging antiviral protocols.
Oncology absorbs the bulk of installed capacity; Infectious Diseases is expanding most quickly.
Formulation Type:
Biological complexity of PEG-protein conjugates has historically constrained viable delivery routes, though preclinical research is broadening the feasible set.
- Injectable:Parenteral administration maintains market leadership due to molecular weight thresholds that oral absorption cannot accommodate. Cold-chain infrastructure requirements concentrate distribution capabilities among specialized logistics providers in Germany and the United States.
- Transdermal:Microneedle array technologies targeting PEG-protein administration are advancing through preclinical programs at Massachusetts and Swiss research institutes. Patient compliance advantages in chronic metabolic management are accelerating investment.
- Oral:Gastrointestinal degradation barriers limit current applicability to small-molecule PEG conjugates only.
- Implantable:Depot formulations for long-acting hormonal and metabolic applications remain niche.
Injectable formulations dominate current manufacturing output; Transdermal research programs are climbing the fastest toward clinical validation.
End User:
Procurement consolidation is rebalancing buying power toward integrated delivery networks and away from individual physician preference.
- Hospitals:Institutional pharmacy and therapeutics committees now control formulary access for PEGylated biologics, with IDN market share exceeding sixty percent in California and Texas. Multi-year supply agreements increasingly tie pricing to real-world evidence generation.
- Homecare:Self-administration of PEGylated peptides for diabetes and obesity is expanding addressable markets beyond traditional clinical settings. Novo Nordisk's GLP-1 portfolio demonstrates weekly dosing viability for metabolic management.
- Clinics:Outpatient infusion centers handle specialty biologic administration for smaller patient volumes.
- Research Institutions:Academic medical centers drive protocol innovation and investigator-initiated trials.
Hospitals absorb the bulk of procurement volume; Homecare is gaining share fastest as self-administration protocols mature.
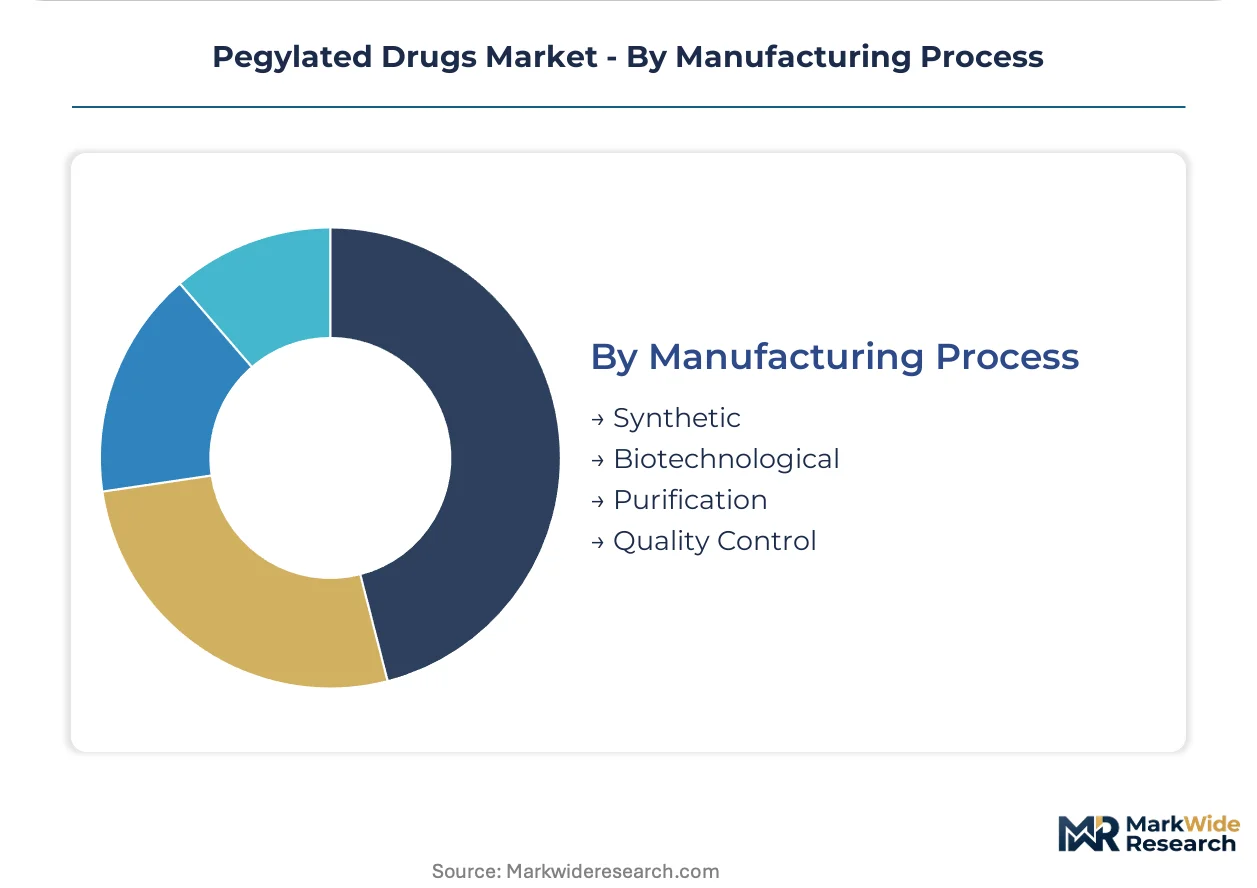
Manufacturing Process:
Conjugation chemistry expertise and aseptic processing for high-viscosity biologics concentrate among limited contract development organizations.
- Biotechnological:Enzymatic ligation and click chemistry platforms are rewriting manufacturing economics, with Swiss and Massachusetts contract manufacturers adopting these technologies to reduce batch heterogeneity. Site-specific conjugation improves regulatory submission quality and time-to-market compression.
- Quality Control:EMA's revised guidance mandates enhanced characterization of PEG shedding and metabolite profiling, forcing additional stability data submissions. Analytical methodology standardization gaps between FDA and EMA create duplicate validation requirements.
- Synthetic:Chemical PEGylation remains dominant for established oncology support care products.
- Purification:Chromatographic separation of PEGylated species from unreacted protein and free PEG determines final product quality.
Biotechnological processes absorb the bulk of R&D investment; Quality Control infrastructure is expanding most quickly to meet evolving regulatory thresholds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement for pegylated biologics concentrates in the United States, Germany, and Japan, where integrated delivery networks and national formularies favor extended half-life therapies. Payer consolidation and biosimilar entry timelines vary sharply across these markets. Manufacturing clusters in Switzerland and Massachusetts supply conjugation expertise globally.
United States
Oncology support care protocols at academic medical centers drive institutional demand for pegfilgrastim and PEG-epoetin. FDA's biosimilar approval pathway accelerates competitive entry for PEGylated protein therapies. The Greater Boston and San Francisco Bay Area biotech corridors host contract manufacturers specializing in site-specific conjugation chemistry.
Germany
Hospital pharmacy and therapeutics committees embed PEGylated neutropenia management into first-line cancer care standards. EMA's revised quality guidelines for PEGylated biologics mandate enhanced PEG shedding characterization. The Rhine-Main and Munich metropolitan regions concentrate aseptic processing capacity for high-viscosity biologics.
Japan
PMDA's evolving guidance on PEGylated protein immunogenicity assessment shapes development timelines for domestic and imported therapies. Tokyo and Osaka academic medical centers standardize protocols for PEG-interferon in infectious disease management. Kansai region contract manufacturers specialize in chromatographic purification of PEGylated species.
Switzerland
Swissmedic's alignment with EMA quality standards positions the country as a regulatory submission hub for European market access. Basel and Zurich host contract development organizations with enzymatic ligation and click chemistry platforms. These facilities reduce batch heterogeneity for second-generation PEGylated therapies.
India
CDSCO's biosimilar pathway and WHO prequalification eligibility open procurement channels for essential PEG-interferon in lower-income health systems. Hyderabad and Bangalore biotech parks develop conjugation capacity for export markets. Domestic manufacturers target cost-competitive PEGylation for emerging market access.
Pegylated Drugs Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue metabolic and infectious disease applications beyond oncology support care. Market structure consolidates around legacy pegfilgrastim franchises and biosimilar positioning strategies. Three archetypes dominate: originator biologics manufacturers defending patent-cliff portfolios, biosimilar specialists leveraging abbreviated approval pathways, and peptide-focused innovators extending half-life for diabetes and obesity therapies. Competitive moves center on manufacturing scale defense and site-specific conjugation technology licensing.
Among North American biologics manufacturers, Amgen Inc. and Pfizer Inc. occupy positions reflecting distinct strategic postures. Amgen exemplifies the originator archetype with legacy manufacturing scale in oncology support care. Pfizer represents biosimilar competitive entry through abbreviated pathway positioning. Novo Nordisk A/S anchors the peptide-focused tier with PEGylated expertise in metabolic disease portfolios.
| Leading Market Players |
|---|
| Amgen Inc. |
| Pfizer Inc. |
| Merck & Co., Inc. |
| Roche |
| AstraZeneca |
| Novo Nordisk A/S |
| Teva Pharmaceutical Industries Ltd |
| Bristol-Myers Squibb |
| Nektar Therapeutics |
| Others |
Value Chain & Pricing Dynamics
EMA's revised quality guidelines for PEGylated biologics gate qualified supply access for premium-tier manufacturers while compressing margins for standard-grade competitors unable to absorb enhanced characterization costs. ISO 10993 biocompatibility verification and site-specific conjugation certification now separate contractable suppliers from spot-market participants.
Pricing Analysis
Volume concentration in hospital procurement against margin defense by originator manufacturers structures pricing dynamics across the pegylated drugs market. Three-tier pricing structure across premium, standard, and economy levels differentiates by conjugation chemistry sophistication and regulatory submission quality. Cost compression in biosimilar tiers intensifies because FDA's abbreviated approval pathway accelerates competitive entry. Integrated delivery networks exhibit highest price sensitivity due to multi-year supply agreement leverage, while academic medical centers prioritize clinical protocol alignment over unit cost.
Supply Chain Analysis
Cold-chain logistics costs for high-viscosity biologics concentrate distribution capabilities among specialized providers in Germany and the United States. High-purity polyethylene glycol supply draws from specialty chemical producers in China and Germany, with enzymatic ligation reagents sourcing from Swiss and Massachusetts contract manufacturers. Single-source vulnerability in chromatographic purification equipment creates chokepoint exposure for second-generation PEGylated therapies. Distribution runs through hospital pharmacy and therapeutics committees with formulary gatekeeping authority.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized manufacturing capacity for site-specific conjugation chemistry represents the binding constraint propping pricing premiums across standard and premium tiers. Contract development organization scarcity limits rapid supply expansion regardless of demand signals.
For Market Incumbents: Acquire enzymatic ligation platform capabilities to defend manufacturing scale advantages against biosimilar entrants exploiting FDA's abbreviated pathway. Backward integration into high-purity polyethylene glycol supply buffers raw material concentration risk from Chinese and German specialty chemical producers. Site-specific conjugation patent estates anchor pricing power as EMA's immunogenicity assessment requirements extend competitor development timelines. For New Entrants and Emerging Players: The premium-to-economy price-point gap in diabetes and obesity PEGylated peptides opens white-space targeting for weekly-dosing GLP-1 architectures. Homecare self-administration protocols represent the most penetrable segment given Novo Nordisk's established patient education infrastructure. WHO prequalification pathway positioning unlocks procurement channels in lower-income health systems through multilateral purchasing agreements. For Investors and Strategic Acquirers: First FDA biosimilar approval for a PEGylated oncology support care product is the leading indicator that originator margin compression will accelerate across the analysis window. Contract manufacturers with click chemistry platforms and Swissmedic-aligned quality systems present acquisition targets with defensive moats. Site-specific conjugation technology licensing deals signal inflection toward manufacturing economics rewriting.| Strategic Initiative | Industry Significance |
|---|---|
| Site-Specific Conjugation Platform Licensing | Swiss and Massachusetts contract manufacturers reduce batch heterogeneity for second-generation therapies. |
| WHO Prequalification Pathway Entry | Essential biologics designation opens multilateral procurement channels in lower-income health systems. |
| EMA Quality Guidelines Compliance Investment | Enhanced PEG shedding characterization preempts regulatory queries and accelerates submission timelines. |
| Integrated Delivery Network Supply Agreements | Multi-year contracts tied to real-world evidence generation lock formulary access in California and Texas. |
| Transdermal Delivery Research Partnership | Microneedle array technologies at Massachusetts and Swiss institutes target patient compliance improvements. |
Study Parameters
Independent corroboration across drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers underwrites the qualitative findings. FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases provide secondary validation. Bottom-up segmentation modeling triangulates against top-down market sizing across therapy area, formulation type, and end-user dimensions.
Rate-of-change decomposition separates volume expansion from price trajectory across the projection horizon. Segmentation dimensions include therapy area, formulation complexity, manufacturing process sophistication, and regional regulatory cluster. CAGRs derive from patient population forecasting, protocol penetration assumptions, and biosimilar entry scenario modeling. Conjugation chemistry yield improvements and cold-chain infrastructure expansion feed industry-specific forecast inputs.
Inputs from clinical trial databases and hospital procurement systems were available through the study window; gaps in real-world evidence generation timelines introduce uncertainty bands around protocol adoption assumptions. Forecasts reflect documented assumptions regarding regulatory pathway evolution and payer formulary behavior. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmacology
Antitussive Drugs Market
Pharmacology
Global Migraine Therapeutics Market
Pharmacology
Cough Remedies Market
Pharmacology
Anti Inflammatory Therapeutics Market
Pharmacology
Apixaban Market
Pharmacology
Antithrombotic Drugs Market
Pharmacology
Influenza Medication Market
Pharmacology
Drug Repurposing Market
Pharmacology
Intranasal Drug and Vaccine Delivery Market
Pharmacology
Clot Busting Drugs Market
Pharmacology
Attention Deficit Hyperactivity Disorder (ADHD) Therapeutics Market
Pharmacology
Drug Delivery Across the Blood-Brain Barrier Market
Pharmacology
Hyperkalemia Drugs Market
Pharmacology
Semaglutide API Market
Pharmacology
Antihyperlipidemic Drugs Market
Pharmacology
Medication Adherence Market