
 Anti Inflammatory Therapeutics Market | 2026-2036
Anti Inflammatory Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Anti Inflammatory Therapeutics Market Analysis
Biosimilar compounds are repositioning cost structures across the anti-inflammatory landscape. AbbVie Inc. leverages its Humira franchise infrastructure to sustain manufacturing scale advantages in immunology. Pfizer Inc. anchors its position through vertical control over active pharmaceutical ingredient supply for NSAID formulations. Johnson & Johnson competes via differentiated delivery platforms in the injectable segment.
Anti inflammatory therapeutics comprise pharmacological agents that modulate immune-mediated inflammatory cascades through cyclooxygenase inhibition, cytokine neutralization, or glucocorticoid receptor agonism, with potency measured by C-reactive protein reduction and Disease Activity Score improvement. These agents serve to halt tissue destruction in chronic autoimmune conditions and acute inflammatory episodes. Biologics command the dominant margin pool due to manufacturing complexity and patent-protected moats, while interleukin inhibitors represent the fastest-expanding category driven by expanded approvals in dermatology and gastroenterology. The oral administration route retains the largest volume share, though intravenous delivery captures premium pricing in hospital-based rheumatology protocols.
The FDA maintains stringent chemistry, manufacturing, and controls requirements that extend development timelines but protect innovator returns, while the EMA's biosimilar interchangeability guidelines shape competitive entry dynamics across European markets. India's CDSCO has streamlined biosimilar approval pathways under its PLI scheme, accelerating domestic production capacity for export markets. Stakeholders must monitor evolving interchangeability designations and their impact on formulary placement decisions.
Market Dynamics
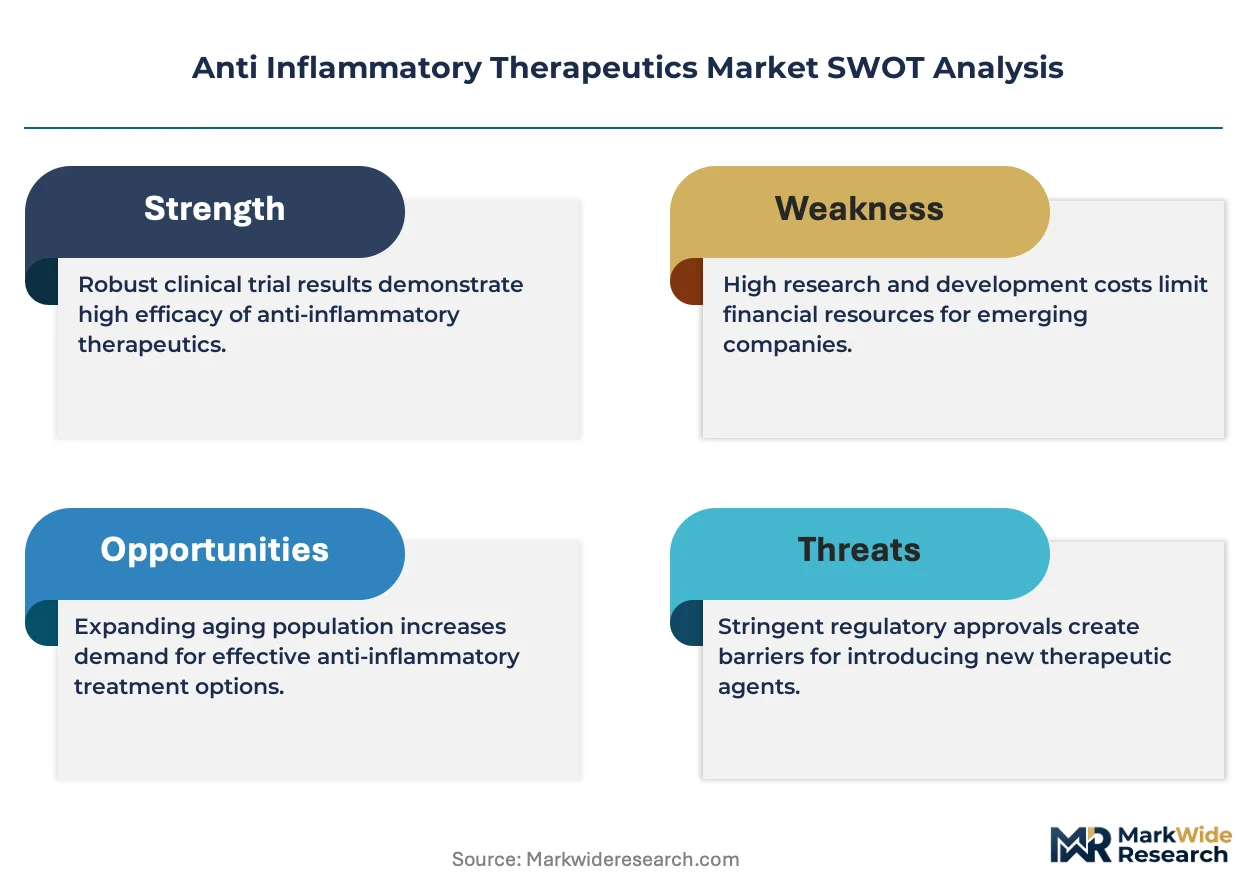
The FDA's accelerated approval pathways for biosimilars are compressing development timelines and forcing innovator firms to defend margin pools through manufacturing scale rather than patent exclusivity alone.
Growth Catalysts
- Interleukin inhibitor expansion:The EMA's broadened reimbursement criteria in Germany for dermatology and gastroenterology indications is pulling patient volume toward biologic infusion centers.
- Biosimilar infrastructure:India's CDSCO has streamlined approval pathways under its PLI scheme, accelerating domestic production capacity for export markets.
- Biologic infusion capacity:Rheumatology clinics across the United States are expanding physical infrastructure to accommodate rising patient volumes for intravenous delivery protocols.
Market Restraints
- Manufacturing complexity:Biologics require living-cell production systems that concentrate supply risk among a handful of contract manufacturing organizations in Switzerland and Singapore.
- Regulatory friction:The FDA's chemistry, manufacturing, and controls requirements extend development timelines and protect innovator returns, delaying competitive entry.
- Substitution dynamics:EMA biosimilar interchangeability guidelines create formulary placement uncertainty that constrains rapid adoption of follow-on biologics.
Strategic Opportunities
- Injectable delivery platforms:Differentiated administration technologies for hospital-based rheumatology protocols offer premium pricing capture beyond molecule commoditization.
- Active pharmaceutical ingredient control:Backward integration into NSAID raw material supply secures margin protection against intermediate price volatility.
- CDSCO export pathways:India's streamlined biosimilar approvals enable domestic manufacturers to supply regulated markets with cost-advantaged production.
Industry Challenges
- Interchangeability designation complexity:Evolving FDA and EMA guidance on biosimilar substitution creates formulary negotiation friction and delays payer contract finalization.
- Biologic manufacturing talent scarcity:Living-cell production expertise concentrates among a limited pool of specialists, constraining capacity expansion timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anti Inflammatory Therapeutics Market |
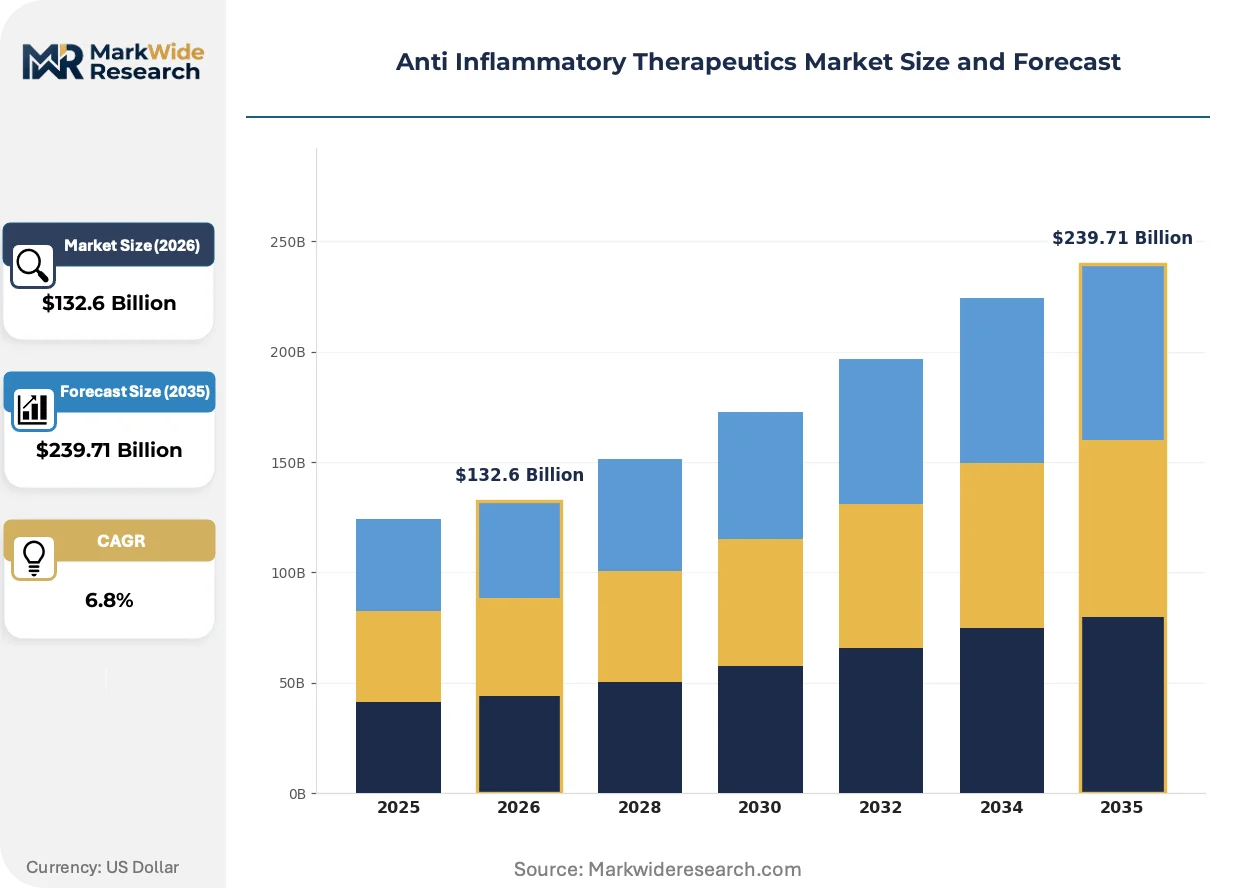
| Market Size in 2026 | $132.6 Billion |
| Market Size in 2035 | $239.71 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biologics, Non-Steroidal Anti-Inflammatory Drugs, Corticosteroids, Interleukin Inhibitors End User: Hospitals, Clinics, Homecare, Ambulatory Surgical Centers Application: Rheumatoid Arthritis, Osteoarthritis, Inflammatory Bowel Disease, Psoriasis Administration Route: Oral, Injectable, Topical, Intravenous |
| Companies Covered | AbbVie Inc., Johnson & Johnson, Pfizer Inc., Novartis AG, Merck & Co., Inc., AstraZeneca PLC, Amgen Inc., F. Hoffmann-La Roche Ltd., Eli Lilly and Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anti Inflammatory Therapeutics Market Emerging Trajectories
Biosimilar compounds are repositioning cost structures while regulatory pathways compress development timelines. Three forces are actively reshaping competitive positioning and value capture mechanisms.
Subcutaneous delivery technologies are decentralizing administration from hospital infusion centers to home-based settings. Rheumatology patients and dermatology clinics are adopting autoinjector platforms at accelerating pace. This shift is decentralizing site-of-care economics and compressing the premium pricing power historically attached to intravenous hospital protocols.
REACH and RoHS frameworks in Europe are tightening purity requirements for pharmaceutical excipients and packaging materials. Manufacturers must reformulate or respecify supply chains to maintain market access. The injectable biologics segment is responding by qualifying alternative suppliers and accelerating validation timelines for European market entry.
Hospital procurement committees are consolidating vendor relationships for biologic categories to simplify formulary management and capture volume discounts. Group purchasing organizations are displacing individual hospital negotiations as the dominant contracting channel. This concentration is most visible in Germany, where statutory health insurance reimbursement structures favor centralized tender processes for interleukin inhibitors.
Anti Inflammatory Therapeutics Market Segmentation
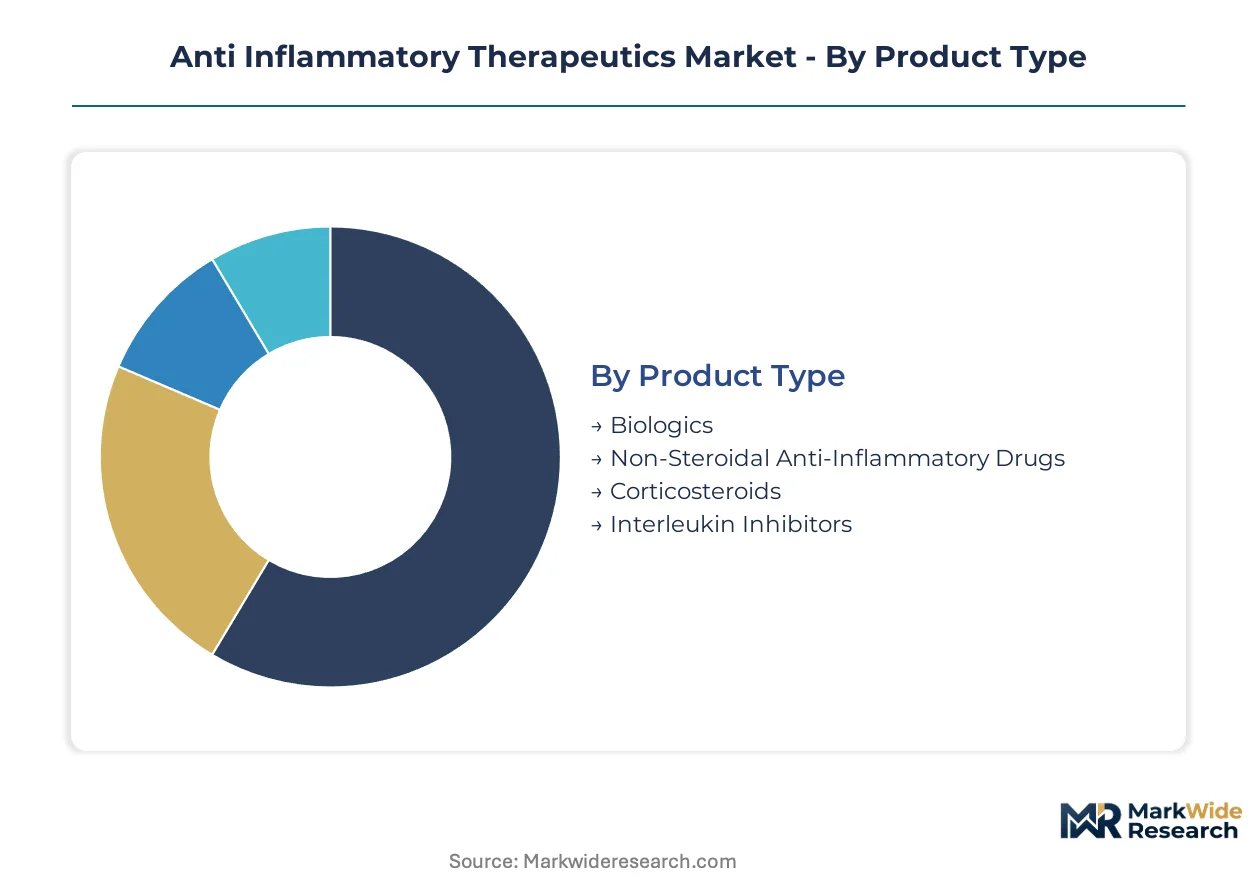
Segmentation in anti-inflammatory therapeutics reveals how regulatory pathways, site-of-care economics, and administration technologies partition value capture. Each dimension carries distinct certification burdens and margin profiles that shape competitive entry and portfolio prioritization.
Product Type:
FDA chemistry, manufacturing, and controls requirements vary sharply across molecular classes, with living-cell biologics demanding the most extensive validation protocols.
- Biologics:Manufactured through recombinant DNA technology in mammalian cell cultures, these agents target specific cytokine pathways with high specificity. Demand concentrates in United States hospital infusion centers where rheumatology protocols favor intravenous tocilizumab and infliximab for refractory cases, though manufacturing complexity limits supplier diversity to a handful of contract organizations.
- Interleukin Inhibitors:A subclass of biologics neutralizing IL-1, IL-6, IL-12/23, or IL-17 signaling, these agents require cold-chain distribution and specialized handling certifications. Germany's statutory health insurance reimbursement expansion for dermatology and gastroenterology indications is accelerating patient volume toward these agents, particularly in academic medical center outpatient settings.
- Non-Steroidal Anti-Inflammatory Drugs:Small-molecule cyclooxygenase inhibitors with established pharmacopeial standards and abbreviated approval pathways.
- Corticosteroids:Glucocorticoid receptor agonists available in oral, injectable, and topical formulations with generic substitution dynamics dominating pricing.
Leading the category by volume: Non-Steroidal Anti-Inflammatory Drugs. Expanding most quickly: Interleukin Inhibitors.
End User:
Site-of-care economics and reimbursement rates create tiered margin pools across delivery settings, with hospital outpatient departments commanding premium pricing for infused biologics.
- Hospitals:Academic medical centers and community hospital systems administer infused biologics under buy-and-bill reimbursement structures that preserve margin on high-cost agents. United States rheumatology departments are expanding infusion suite capacity to accommodate rising patient volumes, with 340B pricing programs creating additional margin complexity for eligible entities.
- Clinics:Independent rheumatology and dermatology practices deliver subcutaneous biologics via in-office injection or prescribe for home administration. Germany's ambulatory care reimbursement structures favor clinic-based initiation of interleukin inhibitors before transitioning stable patients to home injection.
- Homecare:Self-administration of subcutaneous biologics through autoinjector platforms, supported by nursing services for patient training and adherence monitoring.
- Ambulatory Surgical Centers:Limited role for acute perioperative corticosteroid administration in orthopedic procedures, with minimal biologic utilization.
Highest reimbursement rates attach to hospital outpatient infusion. Fastest patient volume shift: Clinics transitioning stable patients to home-based administration.
Application:
Disease-specific indication expansions and unmet medical need severity determine which therapeutic areas attract development investment and payer prioritization.
- Rheumatoid Arthritis:The foundational indication for TNF-alpha inhibitors and subsequent biologic classes, with well-established treat-to-target protocols and extensive long-term safety data. United States rheumatology clinics concentrate infusion capacity for this population, though biosimilar entry has compressed pricing power for originator molecules.
- Psoriasis:Dermatology adoption of IL-17 and IL-23 inhibitors has transformed treatment paradigms, with Germany's broadened reimbursement criteria accelerating access expansion. Patient preference for clear skin outcomes supports premium pricing despite competitive entry.
- Inflammatory Bowel Disease:Crohn's disease and ulcerative colitis represent growing biologic utilization, with gastroenterology infusion centers expanding to meet demand.
- Osteoarthritis:Predominantly managed with NSAIDs and intra-articular corticosteroid injections, with limited biologic penetration due to pathophysiology mismatch.
Largest treated population: Rheumatoid Arthritis. Steepest expansion trajectory: Psoriasis.
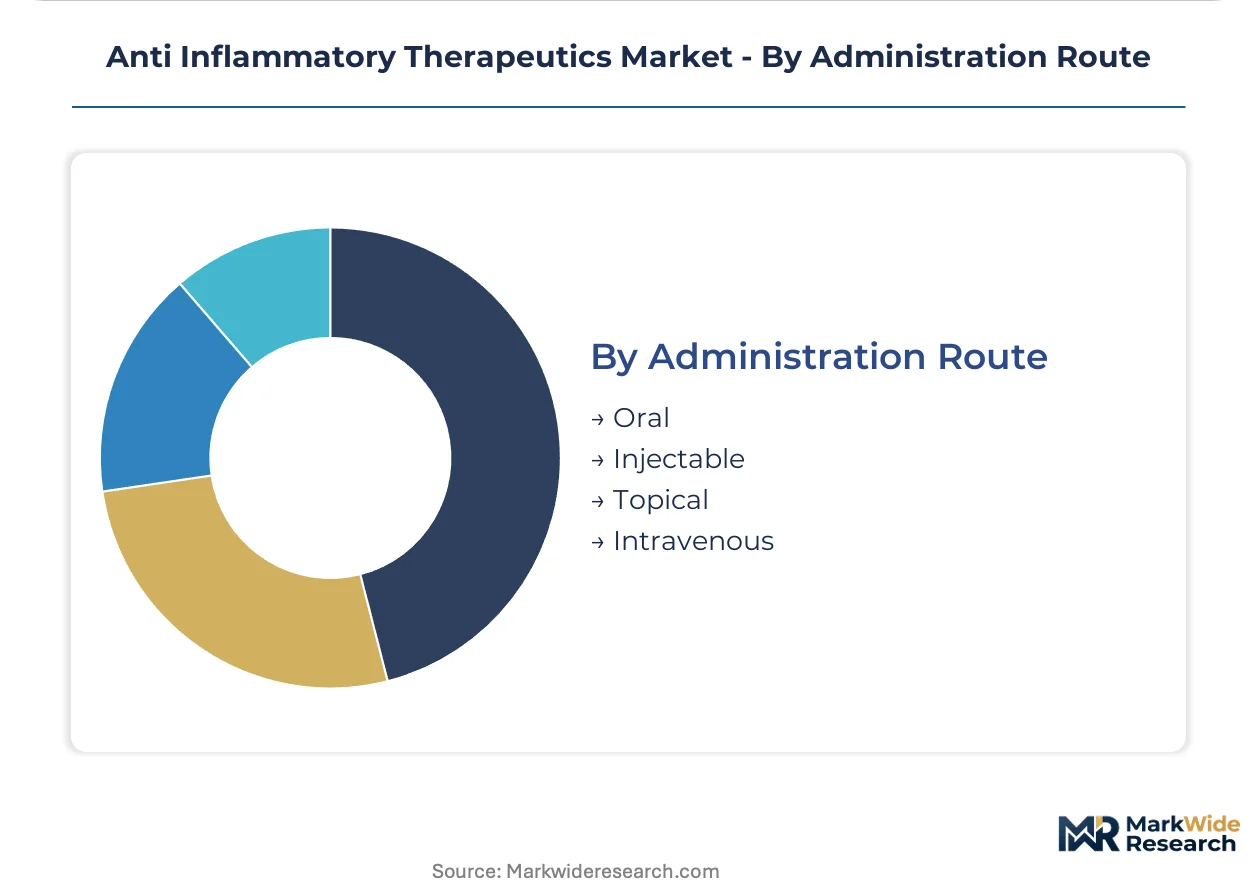
Administration Route:
Delivery technology differentiation creates pricing tiers and competitive moats beyond molecule composition, with formulation science protecting margin in commoditizing categories.
- Injectable:Subcutaneous autoinjector and pre-filled syringe platforms enable home administration with reduced healthcare utilization. Johnson & Johnson competes through differentiated delivery technologies that extend half-life or reduce injection frequency, capturing premium positioning in rheumatology.
- Intravenous:Hospital-based infusion protocols for biologics requiring controlled administration or higher volumes, with site-of-care economics supporting premium pricing. United States rheumatology clinics are expanding physical infrastructure to accommodate rising patient volumes for this delivery mode.
- Oral:NSAIDs and corticosteroids in tablet and capsule formulations dominate prescription volume through pharmacy distribution.
- Topical:Dermatology-focused corticosteroid and calcineurin inhibitor preparations for localized inflammatory conditions.
Dominant volume share: Oral. Premium pricing capture: Intravenous.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Patient volume concentrates in the United States, Germany, and Japan, where rheumatology infrastructure and reimbursement frameworks sustain biologic utilization. Regulatory pathways in India and Switzerland are reshaping supply-side positioning through accelerated biosimilar approvals and contract manufacturing investment.
United States
Rheumatology clinics are expanding infusion suite capacity to accommodate rising patient volumes for intravenous biologics. FDA accelerated approval pathways for biosimilars are compressing development timelines and forcing originator firms to defend positioning through manufacturing scale. The 340B pricing program creates margin complexity for eligible hospital entities in urban medical centers.
Germany
Statutory health insurance reimbursement expansion for interleukin inhibitors in dermatology and gastroenterology is accelerating patient volume toward biologic therapies. EMA biosimilar interchangeability guidelines shape competitive entry dynamics and formulary placement negotiations. Hospital procurement committees in Berlin and Munich are consolidating vendor relationships to capture volume discounts through centralized tender processes.
Japan
PMDA streamlined review pathways for follow-on biologics are attracting development investment from domestic and foreign sponsors. METI industrial policy supports biopharmaceutical manufacturing infrastructure in the Kanto region. Tokyo-based academic medical centers are expanding outpatient infusion capacity for IL-6 and IL-17 inhibitors in rheumatology and dermatology protocols.
India
CDSCO streamlined biosimilar approval pathways under the PLI scheme are accelerating domestic production capacity for export markets. The country's national pharmaceutical regulator has reduced validation timelines for contract manufacturers supplying regulated markets. Hyderabad and Bengaluru clusters are attracting investment in mammalian cell culture capacity to serve European and United States demand.
Switzerland
Contract manufacturing organizations in Basel and Zurich concentrate living-cell production expertise for global biologic supply. Swissmedic maintains stringent chemistry, manufacturing, and controls requirements that protect quality standards while enabling efficient regulatory navigation. The country's specialized workforce pool constrains capacity expansion timelines despite sustained demand from United States and European sponsors.
Anti Inflammatory Therapeutics Market Vendor Landscape
Portfolio diversification dominates the current landscape as incumbents extend biologic franchises into adjacent immunology indications. The market structure concentrates around large-cap pharmaceutical firms with established rheumatology sales infrastructure and manufacturing scale. Three archetypes define competitive positioning: originator biologic developers defending patent-expired franchises, biosimilar specialists capturing cost-driven substitution, and delivery technology innovators differentiating through administration convenience. Capacity expansion and strategic partnerships represent the dominant competitive moves, with firms securing contract manufacturing slots or co-development arrangements to accelerate market entry.
Within the originator biologic tier, AbbVie Inc., Johnson & Johnson, and Pfizer Inc. exemplify divergent defensive strategies against biosimilar erosion. AbbVie Inc. occupies a position anchored by manufacturing scale advantages in immunology. Johnson & Johnson exemplifies differentiation through injectable delivery platform investment. Pfizer Inc. represents backward integration into active pharmaceutical ingredient supply as a margin protection mechanism against intermediate price volatility.
| Leading Market Players |
|---|
| AbbVie Inc. |
| Johnson & Johnson |
| Pfizer Inc. |
| Novartis AG |
| Merck & Co., Inc. |
| AstraZeneca PLC |
| Amgen Inc. |
| F. Hoffmann-La Roche Ltd. |
| Eli Lilly and Company |
| Others |
Supply Flow & Price Mechanics
Biologics-versus-generics divergence creates a bifurcated margin architecture where living-cell manufacturing complexity sustains premium capture for infused monoclonal antibodies while commoditized small-molecule NSAIDs compete on raw material sourcing efficiency. This tier split manifests in supply chain configuration: high-cost biologics concentrate production among Swiss and Singaporean contract manufacturers with validated mammalian cell culture capacity, whereas oral NSAIDs draw from distributed API synthesis networks in India and China where cost minimization dominates supplier selection.
Pricing Analysis
Volume-mix splits heavily toward oral NSAIDs capturing prescription volume through pharmacy channels, yet intravenous biologics command disproportionate margin pools through hospital buy-and-bill reimbursement structures. Price differentiation separates originator biologics with patent-protected moats from biosimilars competing on manufacturing scale and interchangeability certification, with Germany's statutory health insurance tender processes intensifying cost compression for follow-on entrants. Cost compression in the biosimilar tier is intensifying because EMA interchangeability guidelines create formulary negotiation friction that delays rapid substitution. Hospital outpatient departments demonstrate lowest price sensitivity due to 340B pricing program protections, while independent rheumatology clinics face highest sensitivity as they transition stable patients to home-based subcutaneous administration.
Supply Chain Analysis
Cold-chain logistics and specialized freight handling for biologics add substantial cost layers that compound the base manufacturing expense for interleukin inhibitors requiring temperature-controlled distribution from Swiss contract manufacturing sites to United States infusion centers. Geographic supply concentration centers on Switzerland, Singapore, and India, with Basel-Zurich clusters housing living-cell production expertise, Singapore providing Asia-Pacific distribution hubs, and Hyderabad-Bengaluru accelerating mammalian cell culture capacity under CDSCO's PLI scheme. Raw material dependencies include recombinant cell lines, specialized bioreactor media, and pharmaceutical-grade excipients subject to REACH and RoHS purity requirements. Single-source vulnerability concentrates among a limited pool of contract manufacturing organizations with validated biologic production expertise. Distribution runs through hospital procurement committees and group purchasing organizations that consolidate vendor relationships to capture volume discounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure is forcing weaker players toward exit as biosimilar entry compresses originator pricing power and manufacturing scale requirements raise capital barriers. EMA interchangeability uncertainty and FDA accelerated approval pathways favor incumbents with established regulatory navigation capabilities.
For Market Incumbents: Lock in manufacturing scale advantages through captive bioreactor capacity expansion in Switzerland or Singapore, insulating margin pools from biosimilar cost competition. Secure interchangeability designation early through FDA pathway navigation to preempt formulary displacement, while backward integration into active pharmaceutical ingredient supply for NSAID portfolios protects against intermediate price volatility from Indian and Chinese API markets. For New Entrants and Emerging Players: Autoinjector platform differentiation offers a technology-first wedge into the subcutaneous delivery segment where patient preference for home administration outpaces hospital infusion growth. Target dermatology clinic networks in Germany where statutory health insurance reimbursement expansion for interleukin inhibitors creates accessible patient volume without requiring established rheumatology sales infrastructure. Partner with CDSCO-authorized Indian manufacturers for cost-advantaged biosimilar supply to European tender markets. For Investors and Strategic Acquirers: Exit pathways concentrate in delivery technology specialists with validated autoinjector platforms and half-life extension formulation capabilities that command premium positioning beyond molecule commoditization. Long-term viability hinges on regulatory navigation expertise and manufacturing scale rather than single-product patent protection. Monitor EMA interchangeability designation announcements as the critical inflection signal for biosimilar adoption velocity and originator franchise erosion timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Bioreactor capacity expansion in Switzerland protects biologic margin pools against biosimilar cost competition. |
| Interchangeability Designation | FDA pathway completion accelerates formulary placement and preempts originator defensive contracting. |
| Backward Integration | Captive API production for NSAID formulations insulates against Indian and Chinese intermediate price volatility. |
| Delivery Platform Investment | Autoinjector development captures premium positioning in subcutaneous rheumatology and dermatology administration. |
| CDSCO Export Pathway | Indian PLI scheme authorization enables cost-advantaged biosimilar supply to European tender markets. |
Methodological Framework
Multi-period observation of biologic infusion capacity expansion, biosimilar approval velocity, and interleukin inhibitor reimbursement criteria anchored the trend analysis, supplemented by interviews with drug development executives, regulatory affairs leads at EMA and FDA, hospital procurement managers, and formulary directors. Secondary validation drew from FDA biosimilar approval databases, EMA interchangeability guidelines, ClinicalTrials.gov enrollment data, and German statutory health insurance reimbursement bulletins. Bottom-up patient volume modeling across rheumatology, dermatology, and gastroenterology indications triangulated against top-down pharmaceutical revenue disclosures.
Input-output matrix framing structured the analytical approach, with segmentation dimensions spanning product type, administration route, end-user setting, and regional regulatory cluster across the analysis window. CAGRs derived from trend extrapolation of infusion center capacity buildouts, biosimilar substitution rates, and reimbursement policy shifts. Forecast inputs incorporated CDSCO PLI scheme implementation timelines, REACH and RoHS compliance cost trajectories, and group purchasing organization consolidation patterns.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated EMA interchangeability designation or sudden API supply disruptions from Indian manufacturing clusters. Forecasts reflect documented assumptions regarding biosimilar adoption curves and reimbursement policy stability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmacology
Clot Busting Drugs Market
Pharmacology
Ibuprofen API Market
Pharmacology
Semaglutide API Market
Pharmacology
UK Pharmacovigilance Market
Pharmacology
Artemisinin Antimalarial Drugs Market
Pharmacology
Anti-Obesity Therapeutics Market
Pharmacology
Attention Deficit Hyperactivity Disorder (ADHD) Therapeutics Market
Pharmacology
Antimycotics Market
Pharmacology
Thromboprophylactic Drugs Market
Pharmacology
Global Olanzapine Market
Pharmacology
Hepatitis C Drug Market
Pharmacology
Drug Eruptions Treatment Market
Pharmacology
Injectable Drugs Market
Pharmacology
Olanzapine API Market
Pharmacology
Autacoids and Related Drugs Market
Pharmacology
Huoxiang Zhengqi Drug Market