
 At-Home Testing Market | 2026-2036
At-Home Testing Market Size, Share, and Industry Trends Forecast 2026-2036
At-Home Testing Market Analysis
Subscription-based leasing of diagnostic platforms is reconfiguring capital requirements for new entrants, lowering barriers in a field once dominated by heavy R&D investment. Abbott Laboratories leverages its vertically integrated manufacturing footprint to sustain cost advantages across blood and saliva test lines. Quest Diagnostics anchors its position through lab-integrated kit offerings that bridge home collection with centralized analysis.
At-home testing encompasses self-administered diagnostic procedures using biosensor strips, lateral flow cassettes, or microfluidic cartridges designed to detect biomarkers in blood, urine, or saliva specimens without clinical supervision, with sensitivity thresholds typically ranging from ng/mL to pg/mL depending on analyte class. These systems serve the primary commercial purpose of decentralizing healthcare delivery while reducing facility-based consultation costs. Blood tests occupy the largest revenue pool within product type segmentation due to established glucose and cholesterol monitoring protocols, while smartphone-enabled kits within delivery mode represent the fastest structural expansion as Bluetooth-connected readers and app-based result interpretation displace manual readout devices. PCR testing technology maintains premium positioning for infectious disease panels despite longer processing windows compared to lateral flow alternatives.
The FDA oversees premarket notification and quality system regulation for U.S. at-home diagnostics, while the EU MDR and CE marking framework govern conformity assessment for European market access, with both regimes tightening clinical evidence requirements for self-test claims. These standards directly shape product development timelines, reimbursement eligibility, and cross-border commercialization strategies for kit manufacturers. Stakeholders must monitor evolving software-as-medical-device classifications that could reclassify smartphone-enabled reader applications under more stringent premarket pathways.
Market Dynamics
The At-Home Testing Market is experiencing fundamental restructuring as FDA software-as-medical-device classifications force smartphone-enabled reader applications through more stringent premarket pathways, compressing development timelines and reshaping competitive entry barriers.
Growth Catalysts
- EU MDR Convergence:The EU MDR and CE marking framework's tightening clinical evidence requirements for self-test claims is accelerating investment in robust validation protocols, elevating product quality benchmarks across European distribution channels.
- Preventive Care Models:Healthcare systems in Japan and Germany are shifting reimbursement structures toward chronic disease monitoring protocols, expanding addressable demand for glucose and cholesterol biosensor strips among senior citizen populations.
- Bluetooth-Connected Readers:Smartphone-enabled kits are displacing manual readout devices as primary delivery mode, with Bluetooth-connected readers enabling real-time data transmission to telehealth platforms and reducing result interpretation errors.
Market Restraints
- Input Cost Volatility:Microfluidic cartridge production depends on specialized polymer substrates and precision-molded components, with supply concentration in German and Japanese specialty chemical suppliers creating margin pressure during raw material price spikes.
- PCR Processing Windows:PCR testing technology maintains sensitivity advantages for infectious disease panels but requires thermal cycling equipment and longer processing windows compared to lateral flow alternatives, limiting deployment in time-critical screening scenarios.
- Cross-Border Regulatory Friction:Divergent FDA premarket notification requirements and EU MDR conformity assessment timelines force manufacturers to maintain parallel quality systems, inflating compliance overhead for multi-territory kit launches.
Strategic Opportunities
- Subscription Platform Models:Diagnostic platform leasing arrangements are lowering capital barriers for new entrants, enabling mid-sized developers to access manufacturing infrastructure without captive production investment.
- Saliva Biomarker Expansion:Saliva-based detection protocols for cortisol, testosterone, and infectious markers are opening non-invasive testing categories previously dominated by blood draw requirements, appealing to pediatric and needle-averse consumer segments.
- Retail Pharmacy Networks:Direct-to-consumer health platforms and retail pharmacy distribution networks in the United States are creating dedicated shelf space for at-home diagnostics, bypassing traditional clinical procurement channels.
Industry Challenges
- Software Validation Timelines:Smartphone application components requiring FDA software-as-medical-device classification face extended premarket review cycles, delaying synchronized hardware-software launches and compressing effective patent life.
- Interoperability Standards:Absence of universal data exchange protocols between Bluetooth-connected readers and electronic health record systems forces redundant development efforts, fragmenting platform ecosystems and raising consumer switching costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | At-Home Testing Market |
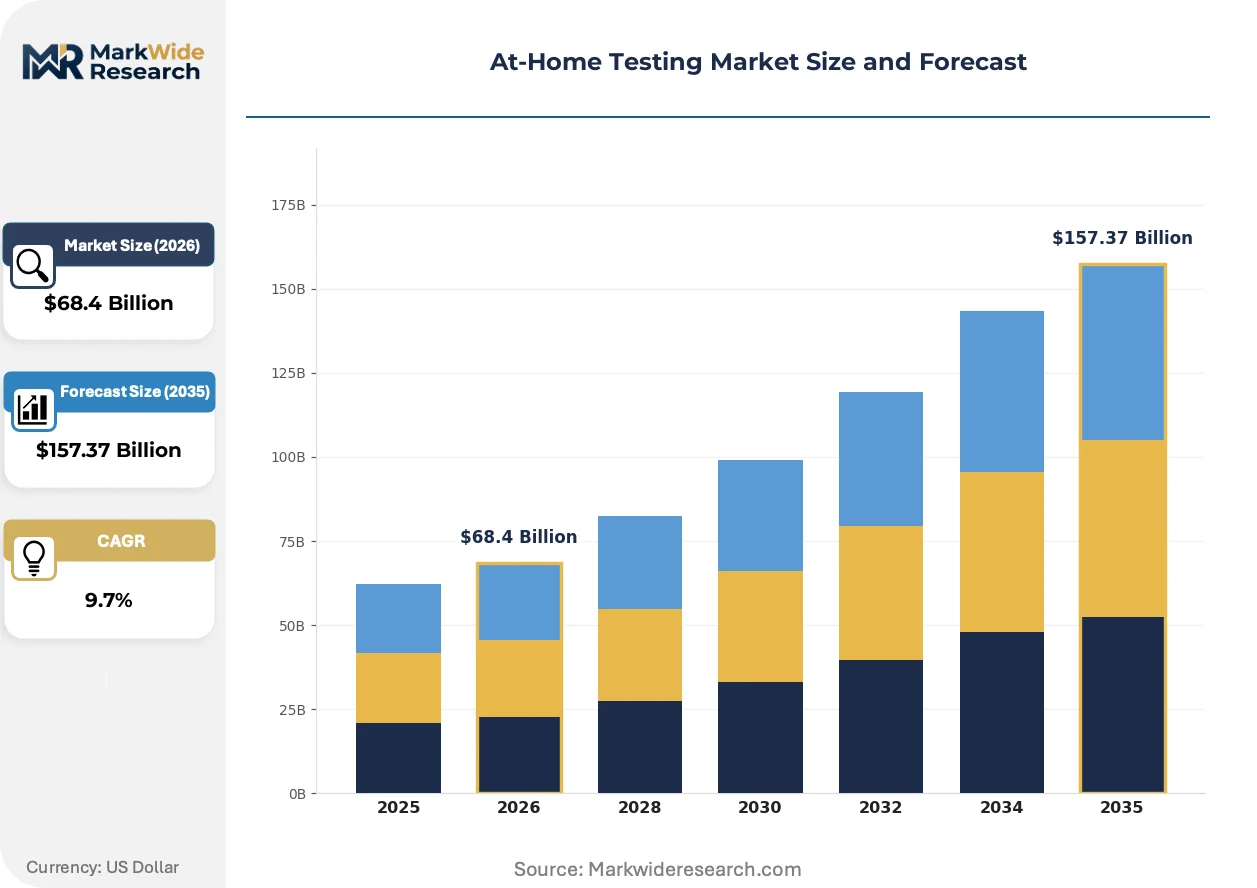
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $157.37 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blood Tests, Urine Tests, Saliva Tests, Genetic Tests Technology: PCR Testing, Lateral Flow, Microfluidics, Biosensors Delivery Mode: Mail-in Kits, Instant Results Kits, Smartphone-enabled Kits, Lab-integrated Kits End User: Individuals, Families, Senior Citizens, Healthcare Professionals |
| Companies Covered | Abbott Laboratories, Quidel Corporation, OraSure Technologies, ACON Laboratories, Everly Health, LetsGetChecked, LabCorp, Quest Diagnostics, F. Hoffmann-La Roche Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
At-Home Testing Market Emerging Trajectories
Technology convergence between microfluidics, biosensor miniaturization, and mobile health platforms is compressing the traditional boundaries between home collection and laboratory-grade analysis, enabling new performance thresholds in self-administered diagnostics.
Microfluidic cartridge designs are migrating from single-analyte detection toward multiplexed panels capable of simultaneous biomarker quantification. Chronic disease management programs in Germany and the Netherlands are adopting these platforms for remote patient monitoring, reducing facility-based consultation frequency while maintaining clinical oversight through telehealth integration.
FDA guidance evolution on over-the-counter diagnostic clearances is compressing approval pathways for well-characterized biomarker classes. The agency's streamlined premarket notification process for glucose and cholesterol monitoring protocols is accelerating product launches, though novel analyte claims still face extended clinical evidence requirements that favor established manufacturers with validation infrastructure.
Consumer purchasing patterns are fragmenting across channel types, with direct-to-consumer health platforms capturing growing share from retail pharmacy distribution. Younger demographics in urban United States markets are prioritizing subscription-based kit delivery over episodic pharmacy purchases, while senior populations maintain preference for in-person consultation support at retail locations, creating bifurcated channel strategies for kit manufacturers.
At-Home Testing Market Segmentation
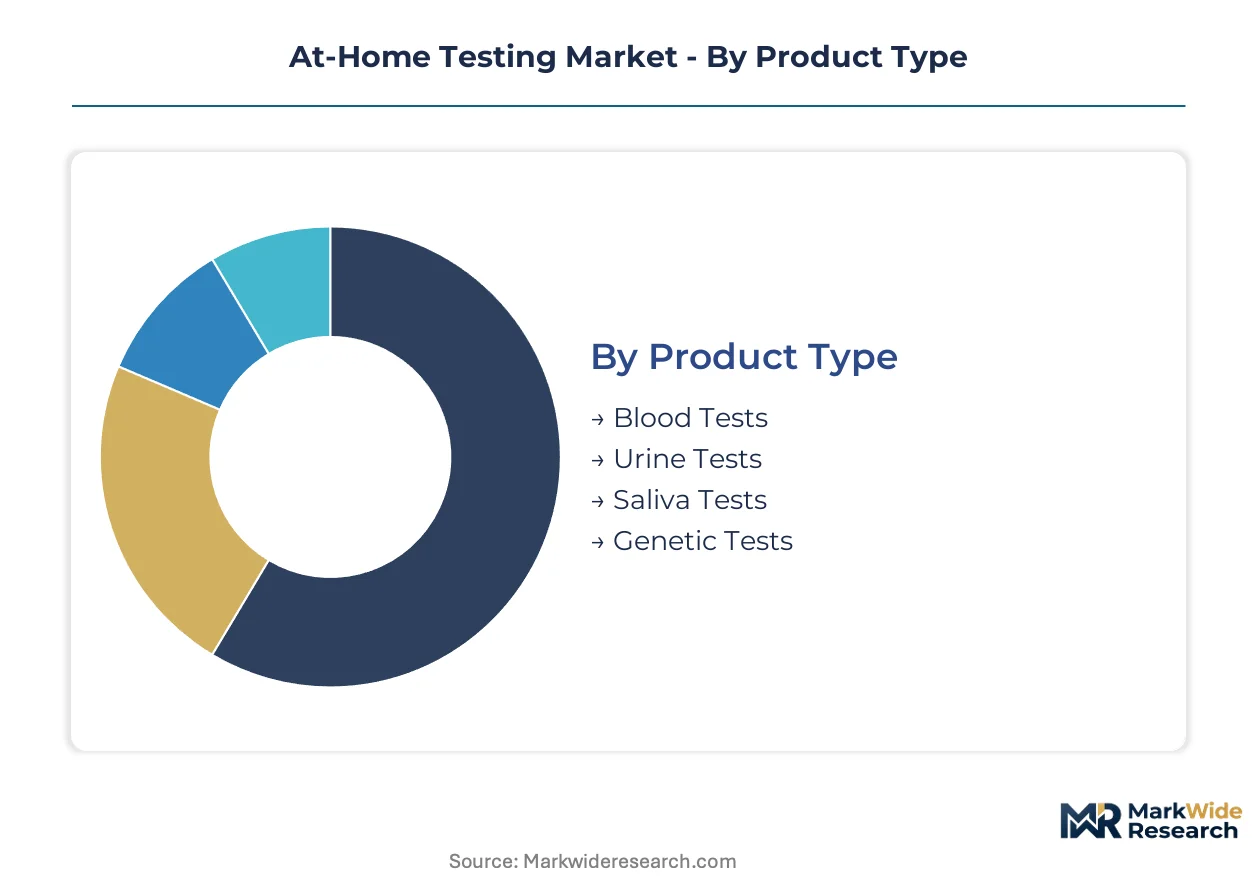
Segmentation in the at-home testing market reveals divergent margin structures and replacement cycles across product categories. Blood glucose strips and lateral flow cassettes turn over monthly, while genetic panels and PCR platforms exhibit multi-year purchase intervals.
Product Type:
Blood tests rotate inventory fastest due to chronic disease monitoring protocols, while genetic tests sit at the opposite extreme with one-time purchase patterns.
- Blood Tests:Biosensor strips and microfluidic cartridges detect glucose, cholesterol, and cardiac markers through capillary blood sampling. Demand concentrates in the United States among senior citizens managing diabetes and cardiovascular conditions, with Medicare reimbursement sustaining recurring purchase behavior.
- Saliva Tests:Non-invasive collection devices measure cortisol, testosterone, and infectious disease biomarkers without needle requirements. Pediatric and needle-averse consumer segments in urban United States markets are adopting these for hormone monitoring and wellness screening, bypassing clinical phlebotomy.
- Urine Tests:Lateral flow cassettes for pregnancy, ovulation, and metabolic markers.
- Genetic Tests:SNP analysis and pharmacogenomic panels for ancestry and drug response prediction.
Blood tests dominate installed base. Saliva tests are where expansion concentrates.
Technology:
Cost tiers separate disposable lateral flow cassettes from capital-intensive PCR thermal cyclers and reusable biosensor platforms.
- Lateral Flow:Immunochromatographic strips deliver qualitative or semi-quantitative results within minutes through capillary-driven fluid movement. Infectious disease screening in retail pharmacy channels and emergency response settings favors these for speed and stability without cold chain requirements.
- Microfluidics:Precision-molded polymer cartridges enable multiplexed biomarker quantification from microliter sample volumes. Chronic disease management programs in Germany and the Netherlands are integrating these into remote patient monitoring protocols, reducing facility consultation frequency.
- PCR Testing:Nucleic acid amplification with thermal cycling for high-sensitivity pathogen detection.
- Biosensors:Electrochemical and optical transducers for continuous or discrete metabolite monitoring.
Lateral flow dominates installed base. Microfluidics is where expansion concentrates.
Delivery Mode:
Application urgency drives channel selection, from emergency screening requiring immediate readout to longitudinal monitoring favoring laboratory integration.
- Smartphone-enabled Kits:Bluetooth-connected readers and app-based result interpretation displace manual readout devices. Younger demographics in United States urban markets prioritize these for fertility tracking and wellness monitoring, with real-time data transmission to telehealth platforms reducing interpretation errors.
- Lab-integrated Kits:Home collection devices with centralized analysis through CLIA-certified facilities. Quest Diagnostics and similar operators anchor this segment, bridging consumer convenience with clinical-grade assay sensitivity for complex biomarker panels.
- Instant Results Kits:Self-contained lateral flow and biosensor devices producing visible readouts within minutes.
- Mail-in Kits:Sample collection containers with prepaid return logistics for laboratory processing.
Instant results kits dominate installed base. Smartphone-enabled kits are expanding most quickly.
End User:
Customer type determines price sensitivity, with healthcare professionals accepting premium pricing for clinical-grade accuracy while individual consumers prioritize unit economics.
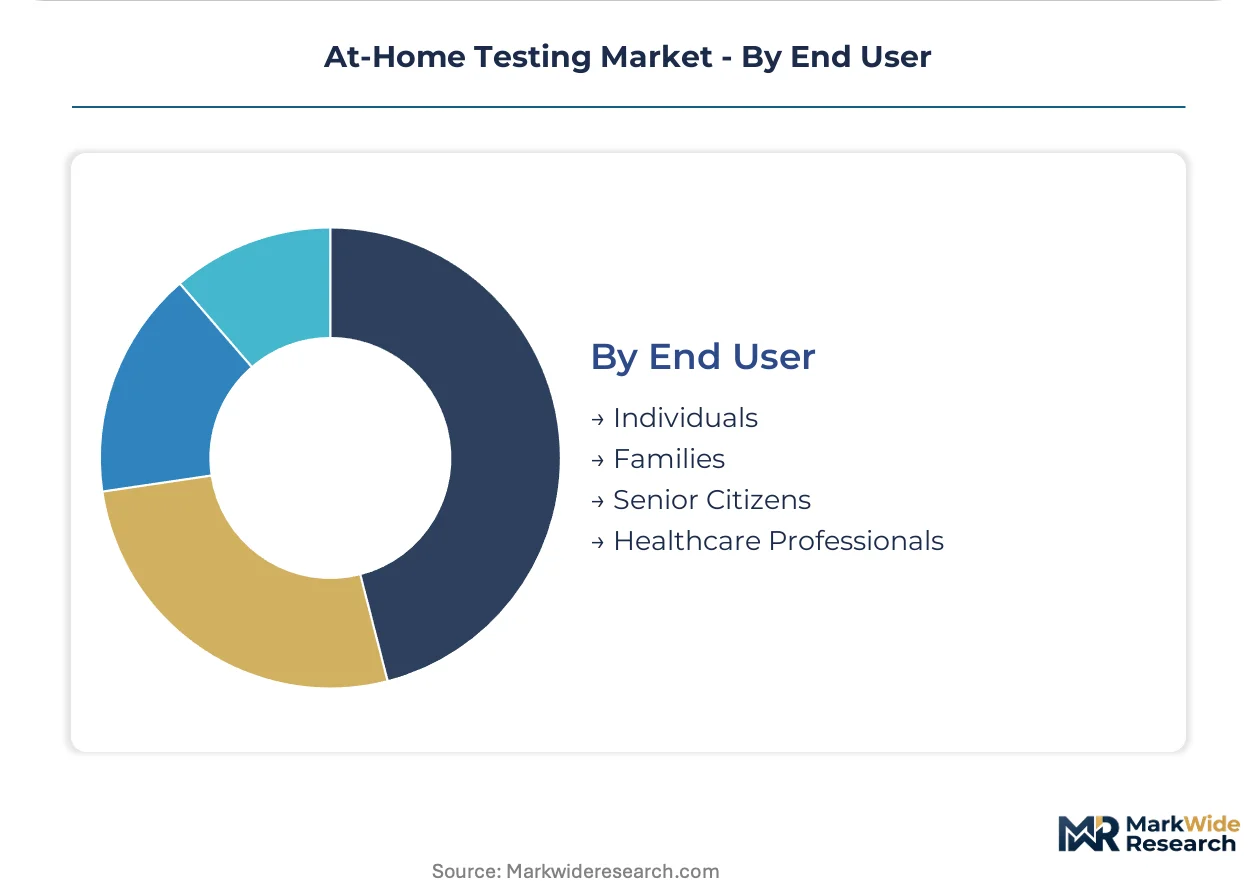
- Senior Citizens:Medicare-eligible populations with established chronic disease monitoring protocols. Germany and Japan are shifting reimbursement structures toward glucose and cholesterol biosensor strips for this segment, expanding addressable demand through preventive care models.
- Individuals:Direct-to-consumer purchasers seeking privacy and convenience for fertility, sexual health, and wellness screening. United States direct-to-consumer health platforms capture growing share from retail pharmacy for this segment through subscription-based kit delivery.
- Families:Multi-user households purchasing infectious disease and allergy screening panels.
- Healthcare Professionals:Clinicians deploying point-of-care diagnostics for patient triage and monitoring.
Senior citizens dominate installed base. Individuals are where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependence for specialized polymer substrates and precision-molded microfluidic components concentrates supply risk in German and Japanese specialty chemical suppliers, while finished kit exports flow predominantly through United States and European distribution channels.
United States
Medicare reimbursement for glucose and cholesterol biosensor strips sustains recurring purchase behavior among senior citizens managing diabetes and cardiovascular conditions. FDA premarket notification requirements for smartphone-enabled reader applications are compressing development timelines through evolving software-as-medical-device classifications. Direct-to-consumer health platforms in urban markets are capturing growing share from retail pharmacy distribution networks through subscription-based kit delivery models.
Germany
Chronic disease management programs are adopting multiplexed microfluidic platforms for remote patient monitoring, reducing facility-based consultation frequency while maintaining clinical oversight. EU MDR conformity assessment timelines and tightening clinical evidence requirements for self-test claims are elevating product quality benchmarks across distribution channels. The Netherlands and Germany jointly anchor European demand for Bluetooth-connected readers enabling real-time data transmission to telehealth platforms.
Japan
Healthcare systems are shifting reimbursement structures toward preventive care models, expanding addressable demand for glucose monitoring protocols among aging populations. METI standards alignment with international quality frameworks facilitates cross-border commercialization for domestic kit manufacturers. Tokyo and Osaka metropolitan clusters concentrate distribution infrastructure for saliva-based detection devices serving pediatric and needle-averse consumer segments.
United Kingdom
Retail pharmacy chains are creating dedicated shelf space for lateral flow cassettes and infectious disease screening panels, bypassing traditional clinical procurement channels. MHRA post-Brexit regulatory divergence from EU MDR frameworks forces manufacturers to maintain parallel quality systems for multi-territory launches. London and Southeast England concentrate direct-to-consumer platform development for fertility tracking and wellness monitoring applications.
China
Domestic manufacturing capacity for immunochromatographic strips and biosensor components is reducing import dependence for base-level diagnostic materials. NMPA oversight of in-vitro diagnostic device registrations is tightening clinical evidence requirements for novel analyte claims. Yangtze River Delta industrial clusters specialize in precision-molded polymer substrates serving both domestic kit assembly and export markets.
At-Home Testing Market Vendor Landscape
On the supply side, the industry is consolidating around vertically integrated manufacturers with captive production of biosensor strips and microfluidic cartridges, while mid-sized developers access infrastructure through subscription-based platform leasing arrangements. Three archetypes dominate: diversified healthcare conglomerates with diagnostic divisions, specialized point-of-care device manufacturers, and digital health platforms integrating kit distribution with telehealth services. Competitive moves concentrate on strategic partnerships bridging hardware manufacturing with software development, and geographic expansion through regional regulatory approvals.
Among diversified healthcare conglomerates, Abbott Laboratories and F. Hoffmann-La Roche Ltd occupy positions exemplifying vertically integrated manufacturing footprints that sustain cost advantages across blood and saliva test lines. Quest Diagnostics anchors the lab-integrated kit segment, bridging home collection convenience with centralized analysis through CLIA-certified facilities. Quidel Corporation represents the specialized infectious disease screening archetype, with lateral flow expertise translating across retail pharmacy and emergency response distribution channels.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Quidel Corporation |
| OraSure Technologies |
| ACON Laboratories |
| Everly Health |
| LetsGetChecked |
| LabCorp |
| Quest Diagnostics |
| F. Hoffmann-La Roche Ltd |
| Others |
Supply Flow & Price Mechanics
Trans-Pacific air freight corridors connecting German precision-molded component suppliers to United States kit assembly facilities transmit cost volatility directly into downstream pricing tiers, with specialized polymer substrate tariffs amplifying margin compression for mid-tier lateral flow manufacturers while Abbott Laboratories and F. Hoffmann-La Roche Ltd sustain premium positioning through captive polymer production.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in the at-home testing market. FDA premarket notification tier and ISO 13485 certification grade separate premium smartphone-enabled kits from standard lateral flow cassettes and economy-grade biosensor strips. Pricing pressure stems from Medicare reimbursement compression for glucose monitoring protocols, squeezing standard-tier margins. Individual consumers through direct-to-consumer platforms exhibit highest price sensitivity, while hospital purchasing committees and GPO contracts demonstrate lowest sensitivity due to clinical-grade accuracy requirements.
Supply Chain Analysis
Foxconn and Jabil Medical hold concentrated contract manufacturing capacity for Bluetooth-connected reader hardware and microfluidic cartridge assembly. Precision-molded polymer substrates draw from German and Japanese specialty chemical suppliers, while immunochromatographic membrane materials source from China and the United States. Single-source vulnerability for nitrocellulose membranes creates structural risk during geopolitical trade disruptions. Distribution runs through retail pharmacy networks and direct-to-consumer health platforms, with Amazon and CVS Health capturing growing downstream share.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The at-home testing market is entering a cyclical recovery phase as FDA software-as-medical-device classification clarity restores predictable approval timelines after years of regulatory uncertainty compressed investment cycles.
For Market Incumbents: Entrench market position by deepening backward integration into precision-molded polymer substrate production, mirroring Abbott Laboratories' captive supply strategy. Acquire mid-sized developers with validated lateral flow portfolios before EU MDR conformity assessment timelines extend. FDA software-as-medical-device reclassification threats demand accelerated smartphone application validation infrastructure investment. For New Entrants and Emerging Players: Saliva-based hormone monitoring for pediatric and needle-averse segments in urban United States markets represents the most penetrable entry point, with cortisol and testosterone panels underserved by established glucose-centric incumbents. Bluetooth-connected fertility tracking kits for subscription-based direct-to-consumer platforms offer second white-space target. Pursue strategic partnerships with telehealth platforms for real-time data transmission integration rather than standalone hardware launches. For Investors and Strategic Acquirers: FDA's evolving over-the-counter diagnostic clearance pathway reshapes the acquisition landscape by compressing validation timelines for well-characterized biomarker classes. Five-to-ten year viability favors vertically integrated manufacturers with CLIA-certified laboratory networks bridging home collection with centralized analysis. Target acquisition archetype: mid-cap developers with EU MDR technical documentation packages nearing completion. Signal to watch is Medicare reimbursement expansion for remote patient monitoring protocols in Germany and Japan as inflection indicator for chronic disease management demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Software-as-Medical-Device Submission | Accelerates synchronized hardware-software launches before patent cliff erosion. |
| EU MDR Technical Documentation Completion | Unlocks European distribution channels with elevated quality benchmarks. |
| Hospital System Partnership | Secures GPO contract access for lab-integrated kit volume commitments. |
| Telehealth Platform Integration | Enables real-time data transmission to electronic health record systems. |
| Reimbursement Strategy Development | Positions glucose and cholesterol strips for Medicare coverage expansion. |
Methodological Framework
A standing panel of regulatory affairs leads at FDA-cleared device manufacturers, hospital purchasing committee chairs, GPO contracts managers, and direct-to-consumer platform executives provided ongoing calibration across the analysis window. Primary interview insights triangulated against FDA 510(k) premarket notification databases, EU MDR technical documentation filings, CMS Medicare reimbursement schedules, and hospital procurement database records. Bottom-up segment sizing across product type, technology, delivery mode, and end user categories validated through top-down macroeconomic anchor checks.
Scenario-bracketing framed volume and value outputs across the projection horizon, with segmentation dimensions spanning blood versus saliva versus urine specimen types, lateral flow versus microfluidics versus PCR technology tiers, smartphone-enabled versus instant-read versus lab-integrated delivery modes, and senior citizen versus individual versus family end user archetypes. CAGRs derived from regression analysis of historical approval-to-launch intervals and reimbursement expansion trajectories, incorporating telehealth adoption curves and chronic disease prevalence demographics as industry-specific forecast inputs.
Practitioners should monitor FDA software-as-medical-device classification rulings, EU MDR notified body capacity constraints, and Medicare remote patient monitoring reimbursement policy shifts for early signals of forecast revision. Quarterly review of 510(k) clearance velocity, CE marking timeline extensions, and telehealth platform partnership announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Pyrogen Testing Market
Testing Services
Tablet Hardness Testers Market
Testing Services
Gastrointestinal Testing Panels Market
Testing Services
North America Drug Screening Market
Testing Services
Cholesterol Test Market
Testing Services
US Pharmaceutical Sterility Testing Market
Testing Services
Global Enzyme Linked Immunosorbent Assay (ELISA) Testing Market
Testing Services
Aerospace and Life Sciences TIC Market
Testing Services
Pneumonia Testing Market
Testing Services
Faecal Calprotectin Testing Market
Testing Services
Global Enteric Disease Testing Market
Testing Services
Nanoparticle Drug Delivery Size and Zeta Potential Measurement Instruments Market
Testing Services
Cell Line Authentication and Characterization Tests Market
Testing Services
Global Roadside Drug Testing Devices Market
Testing Services
STD Testing Devices Market
Testing Services
North America Testing Inspection and Certification (TIC) Market