
 Global Enzyme Linked Immunosorbent Assay (ELISA) Testing Market | 2026-2036
Global Enzyme Linked Immunosorbent Assay (ELISA) Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Global Enzyme Linked Immunosorbent Assay (ELISA) Testing Market Intelligence
Synthetic polymer microplates are decoupling from traditional polystyrene substrates in high-throughput ELISA workflows, reducing well-to-well variability and cutting per-test reagent costs. Thermo Fisher Scientific Inc. leverages its integrated reagent-instrument platform to dominate contract research workflows. Bio-Rad Laboratories Inc. sustains competitive positioning through specialized calibration standards that anchor clinical laboratory purchasing decisions. Merck KGaA controls upstream supply of high-purity detection enzymes, extending its influence across kit manufacturers.
Enzyme Linked Immunosorbent Assay (ELISA) Testing denotes a solid-phase immunoassay technique that uses enzyme-conjugated antibodies to detect antigens or antibodies in liquid samples, typically requiring 96-well or 384-well microplate formats with optical density readouts at 450 nm for quantification. The method serves as a foundational diagnostic and research tool for protein detection, serological screening, and therapeutic monitoring across clinical and pharmaceutical settings. Sandwich ELISA configurations capture the largest share of product demand due to superior specificity in cytokine and biomarker quantification, while multiplex techniques represent the fastest-expanding technique category as researchers pursue simultaneous multi-analyte detection. Diagnostic centers and clinical laboratories together constitute the dominant end-user channel, though pharmaceutical companies are deepening internal ELISA capabilities for in-process biologics testing.
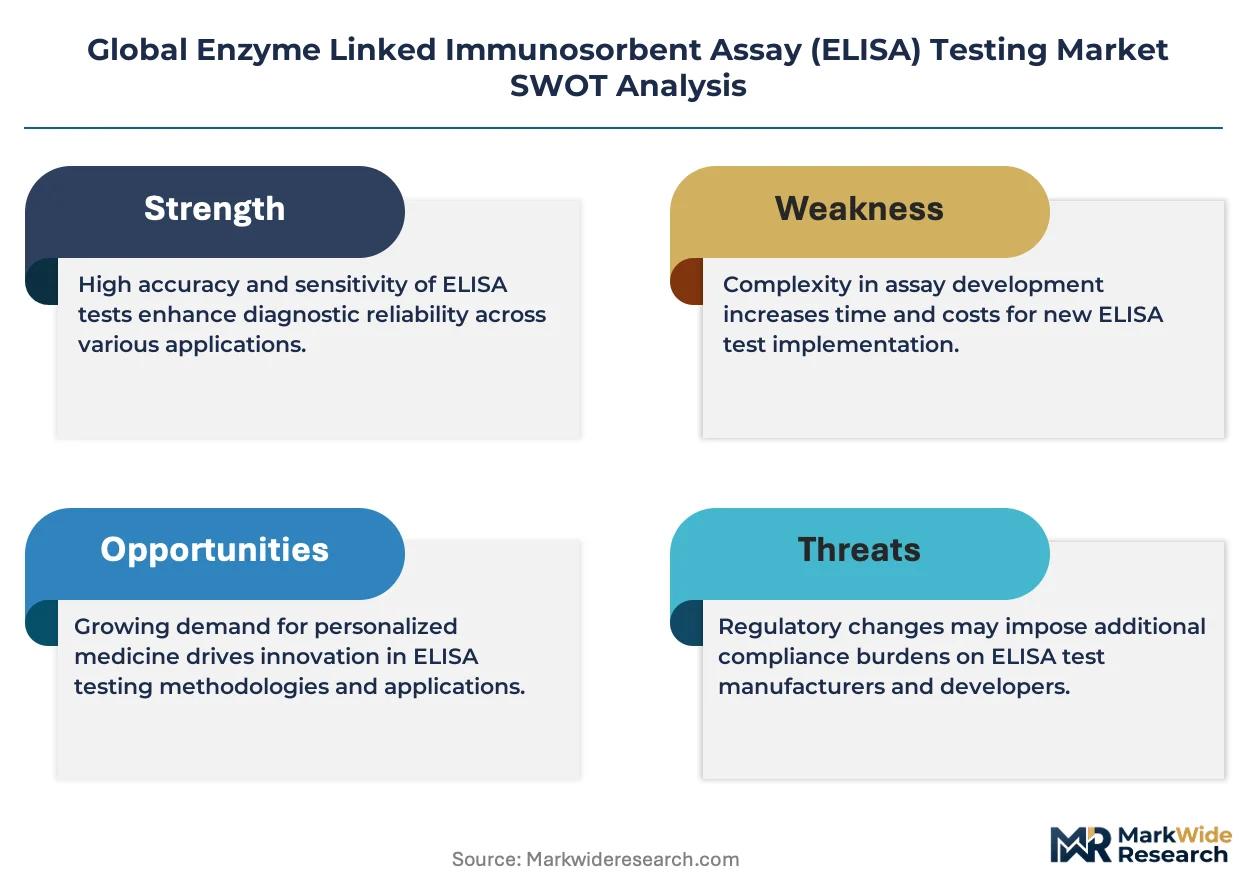
The FDA's bioanalytical method validation guidelines shape kit performance thresholds and documentation requirements for US market access, while the EU's In Vitro Diagnostic Regulation (IVDR) and MDR frameworks are recalibrating conformity assessment burdens for European suppliers. China's NMPA has tightened registration pathways for imported diagnostic reagents, compelling multinationals to localize manufacturing or partner with domestic license holders. Stakeholders must monitor divergent regulatory timelines across these three jurisdictions to anticipate certification bottlenecks and prioritize market entry sequencing.
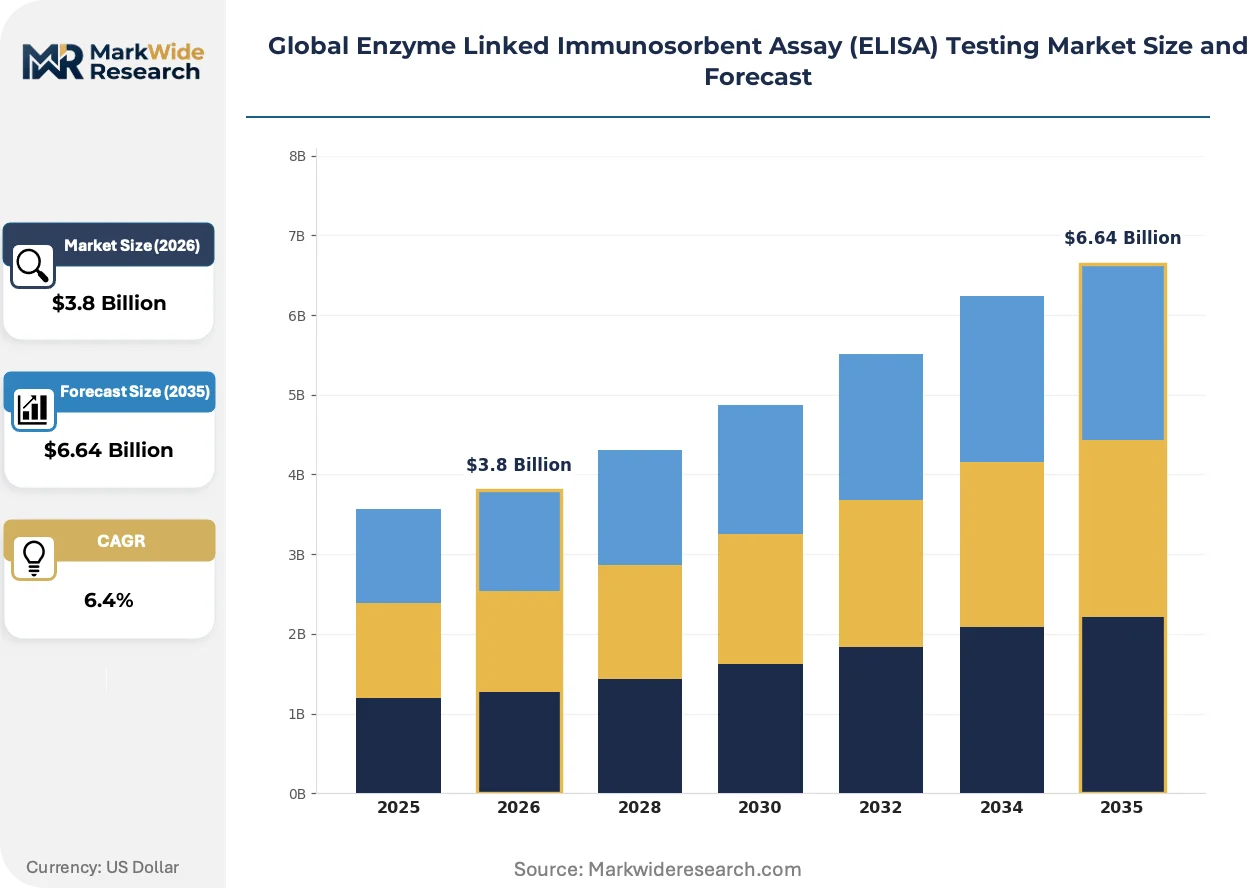
Market Dynamics
Synthetic polymer microplates are decoupling from polystyrene substrates, compressing well-to-well variability and forcing kit manufacturers to recalibrate quality control protocols across high-throughput workflows.
Growth Catalysts
- IVDR implementation:The EU's In Vitro Diagnostic Regulation is mandating enhanced performance documentation, compelling laboratories to upgrade to validated ELISA platforms with traceable calibration chains.
- Biologics manufacturing expansion:Pharmaceutical companies are internalizing in-process testing capabilities for therapeutic proteins, creating sustained kit demand for cytokine quantification and host cell protein detection.
- Multiplex technique advancement:Simultaneous multi-analyte detection platforms are capturing researcher preference in academic and contract research settings, displacing sequential single-plex workflows.
Market Restraints
- Purified enzyme supply concentration:Detection enzyme production clusters with a limited supplier base in Germany and Switzerland, creating input vulnerability for kit assemblers.
- NMPA localization mandates:China's tightened registration pathways for imported diagnostic reagents are extending market entry timelines and compelling partnership structures with domestic license holders.
- Automated immunoassay substitution:Chemiluminescence and electrochemiluminescence platforms are displacing ELISA in high-volume clinical chemistry laboratories seeking reduced manual handling.
Strategic Opportunities
- Point-of-care decentralization:Miniaturized ELISA formats are penetrating rural clinical networks in India and Brazil where centralized laboratory infrastructure remains underdeveloped.
- FDA bioanalytical guidance alignment:Evolving method validation standards are creating service revenue streams for contract laboratories specializing in pharmacokinetic study support.
- CRISPR-ELISA convergence:Integration of nucleic acid amplification with immunoassay readouts is opening infectious disease detection applications beyond traditional protein targets.
Industry Challenges
- Cross-trained technician scarcity:Laboratories report difficulty recruiting personnel proficient in both immunoassay optimization and regulatory documentation required under FDA and IVDR frameworks.
- Legacy instrument interoperability:Microplate readers with proprietary software architectures resist integration with modern laboratory information management systems, complicating data integrity compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Enzyme Linked Immunosorbent Assay (ELISA) Testing Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Direct ELISA, Indirect ELISA, Sandwich ELISA, Competitive ELISA End User: Clinical Laboratories, Research Institutions, Pharmaceutical Companies, Diagnostic Centers Application: Infectious Diseases, Hormonal Testing, Cancer Diagnostics, Allergies Technique: Quantitative, Qualitative, Semi-Quantitative, Multiplex |
| Companies Covered | Thermo Fisher Scientific Inc., Bio-Rad Laboratories Inc., Merck KGaA, Danaher Corporation, Siemens Healthineers, Agilent Technologies Inc., PerkinElmer Inc., bioMérieux SA, Promega Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Enzyme Linked Immunosorbent Assay (ELISA) Testing Market Strategic Shifts & Innovations
Workflow integration pressures are compressing the gap between sample preparation and analytical readout, with vendors repositioning around complete system solutions rather than discrete consumables.
Digital microfluidic platforms are unifying reagent dispensing, incubation, and detection within sealed cartridge formats. Pharmaceutical quality control laboratories in the United States and Germany are piloting these systems at pilot-scale biologics manufacturing sites. This unification is compressing the competitive relevance of standalone open-platform microplate suppliers that lack integrated liquid handling capabilities.
REACH substance restrictions are recalibrating adhesive and blocking buffer formulations used in European-manufactured ELISA kits. Industrial consequence includes accelerated substitution of traditional protein-based blockers with synthetic polymer alternatives to maintain supply continuity. Kit manufacturers serving the EU market are responding by dual-sourcing critical reagents and accelerating validation of reformulated products.
Consolidated procurement frameworks are displacing decentralized purchasing decisions in hospital network laboratories across the United States. Group purchasing organizations are negotiating multi-year supply agreements that bundle ELISA consumables with instrument service contracts, compressing vendor switching flexibility. This pattern is most visible in integrated delivery networks spanning multiple states, where standardization committees now mandate platform uniformity across affiliated clinical sites.
Global Enzyme Linked Immunosorbent Assay (ELISA) Testing Market Segmentation
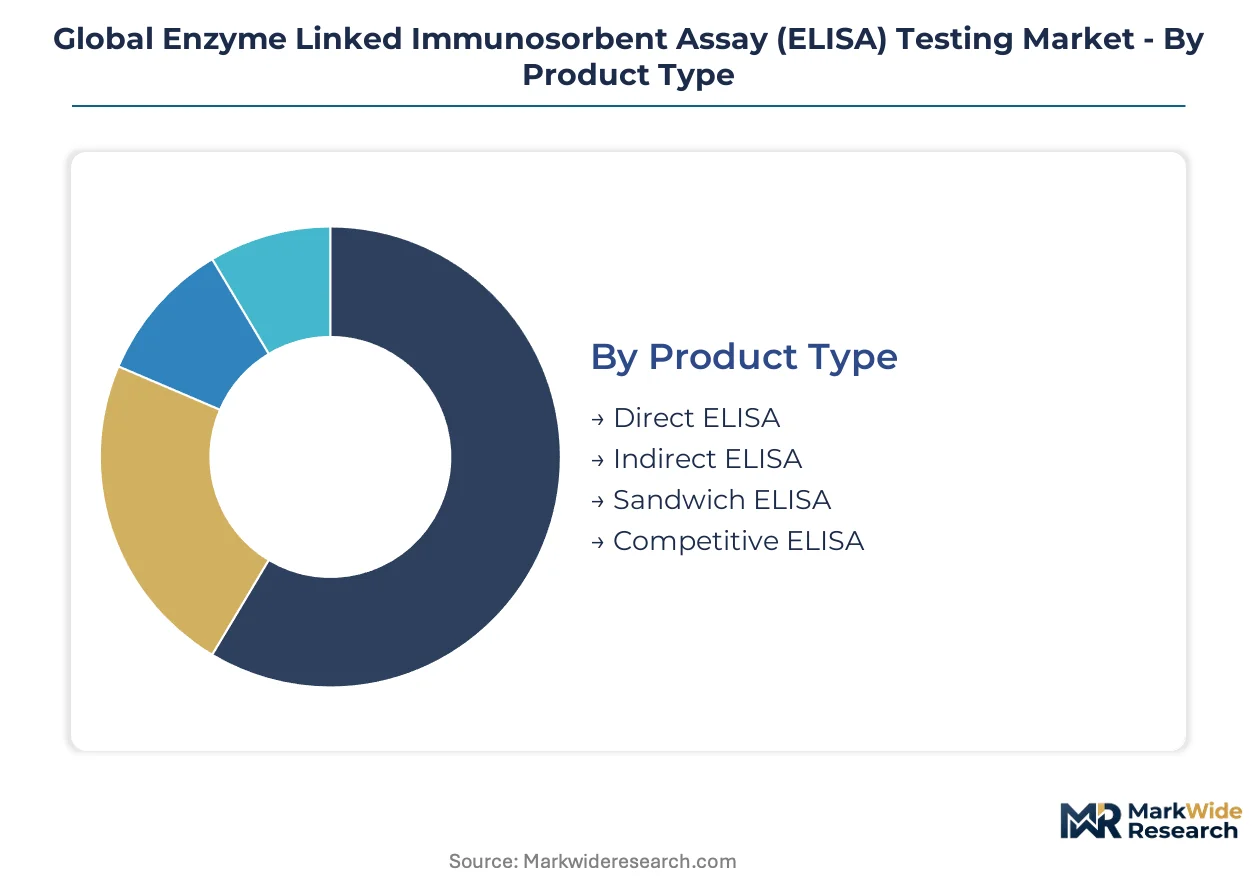
ELISA testing segments diverge sharply in regulatory burden and margin structure. Product configurations determine FDA bioanalytical validation pathways, while end-user channels dictate procurement scale and documentation intensity.
Product Type:
Certification requirements intensify with assay complexity, with sandwich and competitive formats demanding the most extensive performance documentation under FDA and IVDR frameworks.
- Sandwich ELISA:Dual-antibody capture architecture delivers superior specificity for cytokine and biomarker quantification. Pharmaceutical quality control laboratories in Germany and the United States drive volume for host cell protein detection workflows.
- Competitive ELISA:Single-antibody format with labeled antigen competition suits small molecule and hapten detection where molecular weight limits sandwich construction. Toxicology screening programs in forensic laboratories generate concentrated demand.
- Direct ELISA:Single-step conjugate binding simplifies protocol design for high-volume infectious disease screening.
- Indirect ELISA:Secondary antibody amplification boosts signal intensity for serological antibody detection in blood bank settings.
Sandwich ELISA sits at the top of the volume ranking, with competitive ELISA climbing the fastest.
End User:
Procurement scale separates institutional buyers, with pharmaceutical companies consolidating multi-site contracts while diagnostic centers negotiate reagent-only agreements.
- Pharmaceutical Companies:In-process biologics testing demands GMP-compliant kits with lot-to-lot consistency documentation. Internalization of cytokine quantification and host cell protein detection at manufacturing sites in Switzerland and Massachusetts creates sustained high-margin demand.
- Diagnostic Centers:High-throughput infectious disease screening operates on razor-thin per-test economics. India's urban diagnostic chains and Brazil's regional laboratory networks prioritize cost-optimized open-platform configurations.
- Clinical Laboratories:Hospital-affiliated sites balance automated platform integration with IVDR transition compliance.
- Research Institutions:Academic laboratories favor flexible kit configurations supporting protocol customization for novel biomarker discovery.
Pharmaceutical companies command the largest contract values, with diagnostic centers expanding most rapidly.
Application:
Test menu breadth determines platform selection, with infectious disease panels justifying dedicated instrumentation while oncology applications demand multiplex capability.
- Infectious Diseases:HIV, hepatitis, and COVID-19 serology constitute the highest-volume test category. National screening programs in South Africa and Thailand mandate standardized ELISA confirmation workflows.
- Cancer Diagnostics:Tumor marker quantification requires ng/mL sensitivity thresholds. Reference laboratories in Tokyo and Paris invest in automated platforms for CEA and PSA monitoring.
- Hormonal Testing:Fertility and thyroid panels serve reproductive endocrinology practices.
- Allergies:Specific IgE quantification supports immunology specialist practices.
Infectious diseases maintains volume leadership, with cancer diagnostics showing steepest expansion trajectory.
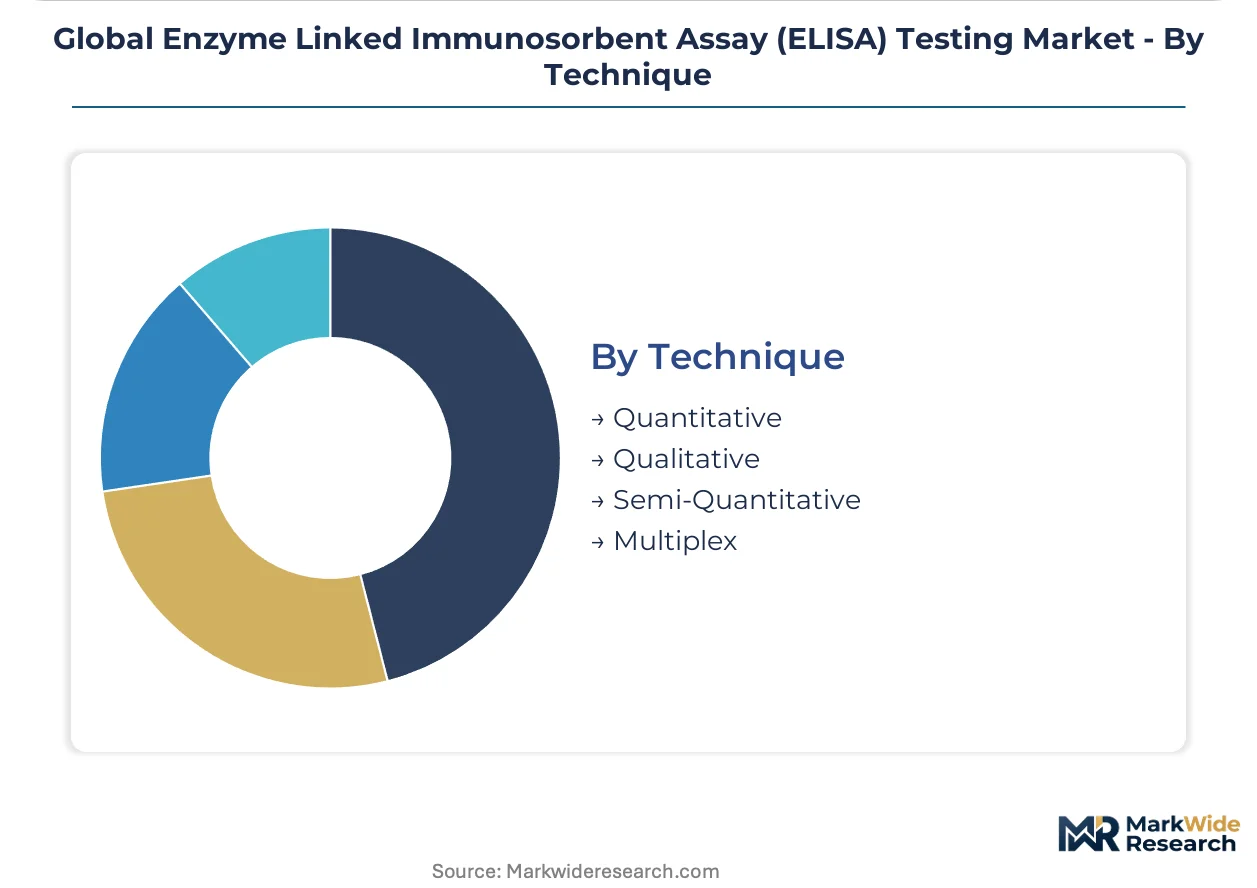
Technique:
Data output requirements segment the technique landscape, with quantitative methods demanding rigorous calibration traceability.
- Multiplex:Simultaneous multi-analyte detection within single wells compresses sample consumption and throughput time. Academic core facilities and contract research organizations in California and Cambridge (UK) drive adoption for cytokine profiling.
- Quantitative:Standard curve-based concentration reporting anchors therapeutic drug monitoring and pharmacokinetic studies. FDA bioanalytical method validation guidelines mandate specific acceptance criteria for these workflows.
- Qualitative:Cutoff-based positive/negative reporting suffices for screening applications.
- Semi-Quantitative:Titer or index values provide ordinal ranking without absolute concentration.
Quantitative techniques dominate current revenue, with multiplex gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Massachusetts anchors the biopharmaceutical manufacturing corridor driving ELISA kit demand for host cell protein detection and cytokine quantification workflows. Clinical trial expansion in Switzerland and contract research growth in California are redistributing testing volumes across three continents. Regulatory divergence between FDA bioanalytical guidance, EU IVDR implementation, and NMPA localization mandates is fragmenting certification pathways.
United States
Pharmaceutical quality control laboratories in Massachusetts and North Carolina are internalizing in-process biologics testing capabilities. FDA bioanalytical method validation guidelines tighten performance documentation requirements for pharmacokinetic study support. The San Francisco Bay Area contract research cluster is piloting digital microfluidic platforms for integrated sample-to-answer workflows.
Germany
Detection enzyme production concentrates in Baden-Württemberg and Bavaria, creating upstream supply leverage over kit assemblers. REACH substance restrictions are forcing reformulation of adhesive and blocking buffer components in European-manufactured products. The Munich biotech corridor is consolidating procurement through group purchasing organizations bundling consumables with service contracts.
China
Domestic diagnostic chains in Shanghai and Guangzhou are scaling high-throughput infectious disease screening operations. NMPA tightened registration pathways for imported reagents, compelling multinationals to partner with domestic license holders or localize manufacturing. The Yangtze River Delta biologics manufacturing base is deepening internal ELISA capabilities for therapeutic protein release testing.
Switzerland
High-purity detection enzyme supply chains cluster around Basel and Zurich, extending influence across European kit manufacturers. Swissmedic maintains alignment with EU IVDR conformity assessment timelines while preserving distinct national notification procedures. The Basel pharmaceutical manufacturing hub is driving sustained demand for GMP-compliant cytokine quantification kits.
India
Urban diagnostic chains in Mumbai and Bangalore are adopting cost-optimized open-platform ELISA configurations for infectious disease panels. CDSCO regulatory harmonization with ICH guidelines is streamlining import pathways for reference standards and calibrated controls. Point-of-care miniaturized formats are penetrating rural clinical networks in Maharashtra and Tamil Nadu where centralized laboratory infrastructure remains underdeveloped.
Global Enzyme Linked Immunosorbent Assay (ELISA) Testing Market Key Industry Players
Global majors compete with regional champions across integrated platform versus open-system positioning. The market structures around three tiers: diversified life science conglomerates controlling upstream reagent supply, specialized diagnostics firms anchoring clinical laboratory relationships, and regional kit assemblers serving cost-sensitive screening programs. Dominant competitive moves include strategic partnerships for regulatory localization and portfolio diversification into multiplex detection formats.
Within the diversified conglomerate tier, Thermo Fisher Scientific Inc. and Danaher Corporation exemplify integrated reagent-instrument platform strategies. Bio-Rad Laboratories Inc. and Merck KGaA occupy positions anchoring specialized calibration standards and upstream enzyme supply respectively. Siemens Healthineers and bioMérieux SA represent European-based clinical diagnostics specialists competing on automated platform integration.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Bio-Rad Laboratories Inc. |
| Merck KGaA |
| Danaher Corporation |
| Siemens Healthineers |
| Agilent Technologies Inc. |
| PerkinElmer Inc. |
| bioMérieux SA |
| Promega Corporation |
| Others |
Cost & Logistics Intelligence
Certification-grade bifurcation between GMP-compliant pharmaceutical kits and cost-optimized open-platform configurations shapes both margin structures and sourcing geography. Pharmaceutical buyers in Massachusetts and Basel absorb 40-60% premiums for lot-to-lot consistency documentation, while diagnostic chains in Mumbai and São Paulo drive procurement toward unbundled reagent contracts that strip out calibration and validation services.
Pricing Analysis
Input-cost pass-through from high-purity detection enzymes and specialized microplate substrates directly compresses kit assembler margins, particularly for mid-tier manufacturers lacking backward integration into enzyme production. Three-tier pricing structure across premium, standard, and economy levels stratifies by validation depth: premium tiers bundle FDA bioanalytical compliance documentation, standard tiers offer IVDR-aligned performance data, and economy tiers serve screening programs with minimal traceability. Pricing pressure stems from automated chemiluminescence displacement in high-volume clinical chemistry laboratories. Diagnostic centers in India and Brazil exhibit highest price sensitivity, while pharmaceutical quality control laboratories in Switzerland and Germany demonstrate lowest sensitivity due to regulatory non-negotiability.
Supply Chain Analysis
Reverse-logistics flows for expired reagents and recalled kits remain underdeveloped, with most manufacturers relying on destruction-at-destination rather than refurbishment or remanufacturing recovery. Detection enzyme production concentrates in Germany, Switzerland, and the United States, creating single-source vulnerability for kit assemblers dependent on horseradish peroxidase and alkaline phosphatase supply. Raw material dependencies extend to polystyrene and synthetic polymer microplates, enzyme stabilizers, and protein-based blocking buffers now facing REACH-driven substitution. Tariff exposure runs through NMPA localization mandates compelling import substitution. Distribution runs through group purchasing organizations in the United States and direct hospital network contracts in Germany, with regional distributors serving fragmented diagnostic markets in India and Brazil.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ELISA testing market functions as a regulatory compounder where IVDR implementation and FDA bioanalytical guidance tightening create sustained demand for validated platforms with traceable calibration chains. Compliance documentation intensity separates sustainable revenue streams from commoditized screening economics.
For Market Incumbents: To counter automated chemiluminescence displacement in high-throughput clinical laboratories, incumbents must anchor hospital network relationships through multi-year consumables-service bundling and deepen backward integration into detection enzyme production to secure input cost control. Thermo Fisher Scientific Inc. and Danaher Corporation exemplify integrated platform strategies that compress competitor switching flexibility. For New Entrants and Emerging Players: Direct-to-diagnostic-chain digital procurement platforms offer the most penetrable route for bypassing established GPO lock-in, particularly targeting mid-tier Indian and Brazilian laboratory networks seeking cost-optimized open-platform configurations without legacy instrument switching costs. CRISPR-ELISA convergence applications in infectious disease detection represent an unclaimed white-space segment. For Investors and Strategic Acquirers: Consolidation pressure builds where regulatory documentation capabilities concentrate among fewer suppliers capable of serving pharmaceutical quality control workflows under FDA and IVDR frameworks. Long-term viability favors targets with captive enzyme supply or established calibration standard authority. The signal to watch is NMPA partnership announcement velocity as proxy for China market access competitiveness.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Localization Partnership | NMPA-aligned manufacturing in Yangtze River Delta secures China market entry against import restrictions. |
| Detection Enzyme Backward Integration | Captive supply of horseradish peroxidase in Baden-Württemberg insulates margin from input volatility. |
| Digital Microfluidic Platform Launch | Integrated sample-to-answer cartridges displace standalone microplate suppliers in pharmaceutical QC. |
| Multiplex Detection Format Expansion | Simultaneous multi-analyte capability captures cytokine profiling demand in California and Cambridge. |
| Group Purchasing Organization Contract | Multi-year bundled agreements with US integrated delivery networks lock out competitor switching. |
Research Approach
Coverage spans the United States, Germany, China, Switzerland, and India, with primary inputs from each market combining structured interviews with regulatory affairs leads at kit manufacturers, procurement managers at pharmaceutical quality control laboratories, and contracts managers at group purchasing organizations, validated against secondary sources including FDA bioanalytical guidance documents, EMA IVDR implementation timelines, NMPA registration databases, and SEC filings from publicly traded life science conglomerates. Bottom-up and top-down triangulation reconciles segment-level kit volume estimates with aggregate market value benchmarks.
Rate-of-change decomposition separates volume expansion from price-mix effects across the projection horizon, with analytical framework modeling product type (sandwich, competitive, direct, indirect), end-user channel (pharmaceutical, diagnostic, clinical, research), application (infectious disease, cancer, hormonal, allergy), and technique (multiplex, quantitative, qualitative, semi-quantitative) dimensions. CAGRs derive from regression-adjusted historical trajectory analysis incorporating regulatory milestone timing and biologics manufacturing capacity buildout schedules as industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for digital microfluidic platform penetration would alter the outlook if pharmaceutical QC laboratories accelerate integrated system replacement beyond baseline assumptions. Forecasts reflect assumptions about IVDR transition completion timing and NMPA localization compliance rates. Practitioners should monitor CDSCO regulatory harmonization progress and REACH substance restriction enforcement intensity for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Thailand Point-Of-Care Testing (POCT) Market
Testing Services
Europe Medical Device Testing Market
Testing Services
Europe Antimicrobial Susceptibility Testing Market
Testing Services
Thyroid Test Market
Testing Services
Global Bilirubin Colorimeter Assay Market
Testing Services
US C-Reactive Protein Testing Market
Testing Services
Drug Testing Market
Testing Services
Blood Borne Testing Market
Testing Services
Apolipoprotein Testing Market
Testing Services
Global Urinalysis Test Market
Testing Services
Global Vitamin D Testing Market
Testing Services
Global Immunoprecipitation Testing Market
Testing Services
North America Testing Inspection and Certification (TIC) Market
Testing Services
Allergy Tester Market
Testing Services
INR Test Meter Market
Testing Services
Cell Line Authentication and Characterization Tests Market