
 Global Enteric Disease Testing Market | 2026-2036
Global Enteric Disease Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Global Enteric Disease Testing Market Foresight
Asset-light leasing models for multiplex molecular diagnostic platforms are rewriting competitive entry barriers in enteric disease testing. Thermo Fisher Scientific leverages its installed base of real-time PCR systems to sustain recurring consumable revenue across clinical reference laboratories. bioMérieux SA anchors its competitive position through integrated stool culture and identification workflows that span automated specimen processing. Quest Diagnostics competes by controlling geographic access to high-volume gastrointestinal testing through its national phlebotomy network.
Enteric disease testing encompasses laboratory and point-of-care methods that detect bacterial, viral, parasitic, fungal, protozoan, and helminthic pathogens in clinical specimens, primarily stool, with PCR-based assays amplifying target nucleic acid sequences through thermal cycling for pathogen-specific identification. The primary commercial purpose is to enable targeted antimicrobial therapy, reduce empiric prescription, and support public health surveillance of foodborne and waterborne outbreaks. PCR testing dominates the technique landscape due to superior sensitivity and turnaround time compared to conventional culture, while next-generation sequencing occupies an emerging position for outbreak investigation and resistance profiling. The stool sample category generates the largest volume flow given its centrality to gastrointestinal pathogen detection, though blood and cerebrospinal fluid specimens command premium pricing in invasive enteric fever cases.
The FDA's in vitro diagnostic regulatory framework shapes product development timelines and clinical validation requirements for US market entry, while the EMA's CE marking process under the In Vitro Diagnostic Regulation governs European commercialization pathways. WHO prequalification and the Global Benchmarking Tool influence procurement eligibility for enteric testing products in Gavi-eligible countries and WHO member state tenders. Stakeholders must monitor the convergence of antimicrobial stewardship mandates with diagnostic reimbursement policy, as payer coverage decisions for multiplex GI panels increasingly determine laboratory adoption economics and manufacturer revenue stability.
Market Dynamics
Multiplex molecular diagnostic platforms are compressing turnaround times from days to hours, forcing laboratories to restructure workflows around PCR-based panels rather than sequential culture methods. This technological displacement is redistributing value from standalone rapid tests toward integrated syndromic panels.
Growth Catalysts
- WHO Prequalification Pathway:Accelerated product registration timelines in low-income settings are expanding addressable markets for IVD manufacturers seeking Gavi-eligible country tenders.
- India's National Health Mission:District hospital integration of multiplex stool PCR is creating institutional demand for automated nucleic acid extraction systems.
- Antimicrobial Stewardship Mandates:Hospital reimbursement penalties for excessive empiric antibiotic use are driving laboratory investment in pathogen-specific identification technologies.
Market Restraints
- Reagent Supply Concentration:Polymerase and fluorescent probe manufacturing clusters in Germany and the United States create single-source dependency risks for regional laboratories.
- FDA Validation Burden:Clinical trial requirements for multiplex GI panels extend product development timelines by 18-24 months compared to single-target assays.
- Culture-Based Substitution:Antibiotic susceptibility testing still requires viable organisms, limiting complete displacement of stool culture workflows.
Strategic Opportunities
- Point-of-Care Decentralization:Battery-operated PCR devices are enabling testing at rural clinics in sub-Saharan Africa outside centralized laboratory networks.
- Next-Generation Sequencing Convergence:Resistance gene profiling combined with outbreak surveillance is creating premium service tiers for public health reference laboratories.
- Leasing Model Innovation:Per-test reagent rental agreements are lowering capital barriers for mid-volume clinical laboratories in Southeast Asia.
Industry Challenges
- Bioinformatics Talent Scarcity:Interpretation of complex resistance patterns from sequencing data requires specialized computational pathology expertise that outpaces training pipeline output.
- Legacy LIS Integration:Hospital information systems built around culture-based ordering codes require expensive middleware development for seamless PCR result reporting.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Enteric Disease Testing Market |
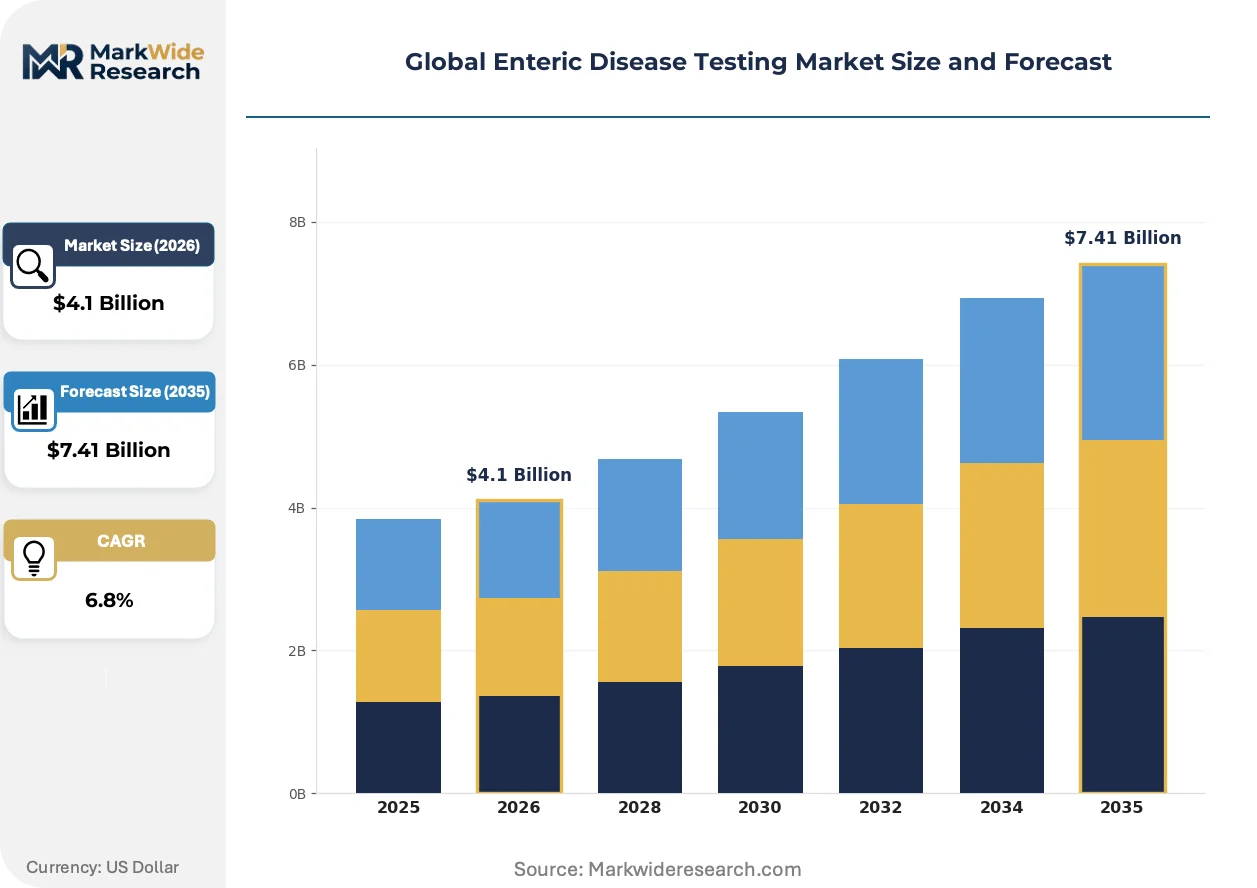
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $7.41 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Testing Technique: PCR, ELISA, Culture Method, Immunofluorescence Assay, Next-Generation Sequencing, Flow Cytometry Sample Type: Stool, Blood, Urine, Saliva, Tissue Biopsy, Cerebrospinal Fluid Target Pathogen: Bacterial, Viral, Parasitic, Fungal, Protozoan, Helminthic End User: Diagnostic Laboratories, Research Institutes, Public Health Agencies, Academic Centers, Veterinary Clinics |
| Companies Covered | Abbott Laboratories, bioMérieux SA, Becton Dickinson and Company, Bio-Rad Laboratories, Cepheid, Thermo Fisher Scientific, Quest Diagnostics, DiaSorin S.p.A., Meridian Bioscience, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Enteric Disease Testing Market Shifts & Advancements
Digital pathology and cloud-based result interpretation are restructuring how gastrointestinal diagnostics are delivered, with artificial intelligence-assisted pattern recognition entering routine workflow validation. These shifts are compressing the gap between raw instrument output and clinically actionable reports.
Cloud-connected multiplex analyzers are virtualizing laboratory expertise by enabling remote quality control, automated flag interpretation, and real-time epidemiological surveillance across distributed hospital networks. Regional health systems in the United States are adopting these platforms to standardize testing quality across acquired community hospitals. This architecture is virtualizing the traditional role of on-site microbiology directors, allowing centralized specialists to oversee multiple sites simultaneously.
EMA's In Vitro Diagnostic Regulation is mandating clinical evidence requirements for Class C devices that previously relied on analytical validation alone. Manufacturers must now generate prospective performance data across multiple European member states before CE marking. Multiplex GI panel producers are responding by restructuring clinical affairs teams to manage parallel study execution across France, Germany, and Italy.
Hospital procurement departments are consolidating gastrointestinal testing contracts under single-source agreements that bundle instruments, reagents, and service into per-test pricing. Independent reference laboratories are losing access to high-volume health system accounts as integrated delivery networks centralize spend. This concentration is most visible in the United States, where Catholic health system alliances and for-profit hospital chains are standardizing on single vendor platforms across dozens of facilities.
Global Enteric Disease Testing Market Segmentation
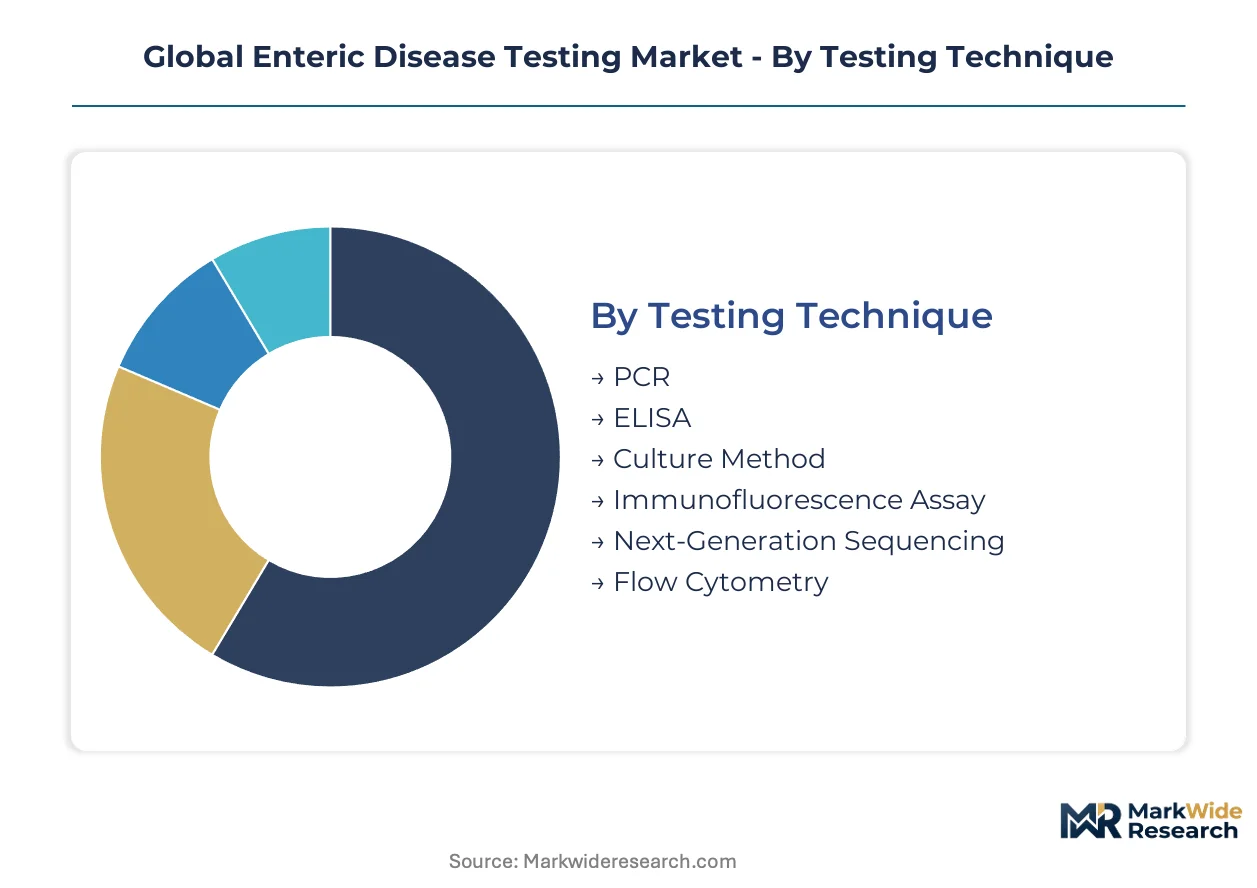
Segmentation in enteric disease testing reveals divergent economic profiles across techniques, sample types, and institutional buyers. Cycle times for consumables versus capital equipment create fundamentally different revenue predictability for manufacturers serving this market.
Testing Technique:
Turnaround velocity separates molecular platforms from classical microbiology, with thermal cycling completing in hours while culture-based confirmation extends across days.
- PCR:Polymerase chain reaction amplifies pathogen-specific nucleic acid sequences through automated thermal cycling, delivering same-day results. Demand concentrates in US clinical reference laboratories where antimicrobial stewardship mandates penalize delayed diagnosis. The technique commands premium reimbursement but requires substantial capital investment in extraction robotics.
- Culture Method:Conventional stool culture isolates viable organisms on selective media for phenotypic identification and antibiotic susceptibility testing. District hospitals in India under the National Health Mission retain this workflow where PCR infrastructure remains uneconomical. Turnaround times of 48-72 hours limit revenue per specimen but sustain essential susceptibility data.
- ELISA:Enzyme-linked immunosorbent assays detect pathogen antigens or host antibodies with moderate sensitivity.
- Immunofluorescence Assay:Fluorescent antibody staining visualizes pathogen-specific antigens in clinical specimens.
- Next-Generation Sequencing:Massively parallel sequencing enables outbreak investigation and resistance gene profiling.
- Flow Cytometry:Laser-based cell counting and sorting supports specialized research applications.
PCR dominates installed base in high-income settings. Culture Method is where expansion concentrates in Gavi-eligible procurement pathways.
Sample Type:
Collection logistics and reimbursement tiers create sharp margin stratification across specimen categories, with invasive sampling commanding multiples of routine stool pricing.
- Stool:Fecal specimens generate the highest testing volumes given non-invasive collection and broad pathogen detection capability. India's district hospital integration of multiplex PCR targets this sample type for enteric fever surveillance. Automated nucleic acid extraction systems are scaling specifically for high-throughput stool processing.
- Blood:Blood cultures and serum testing support invasive enteric fever diagnosis with premium clinical value. US hospital reimbursement codes for bacteremia detection sustain elevated pricing despite lower specimen frequency compared to stool.
- Urine:Urinary antigen detection offers convenience for select enteric pathogens.
- Saliva:Oral fluid collection simplifies pediatric and community screening programs.
- Tissue Biopsy:Histopathological examination confirms invasive enteric disease complications.
- Cerebrospinal Fluid:CSF analysis addresses rare neurological manifestations of enteric infection.
Stool captures the highest absolute revenue dollars. Blood is climbing the fastest on per-specimen value metrics.
Target Pathogen:
Diagnostic development prioritization follows disease burden and outbreak surveillance imperatives, with bacterial and viral targets attracting disproportionate R&D investment.
- Bacterial:Salmonella, Shigella, Campylobacter, and pathogenic E. coli drive the largest testing volumes in foodborne illness surveillance. FDA-cleared multiplex GI panels standardize on bacterial target combinations for US clinical laboratories.
- Viral:Norovirus and rotavirus detection supports hospital infection control and pediatric gastroenteritis management. WHO prequalification pathways prioritize viral enteric diagnostics for low-income country immunization program monitoring.
- Parasitic:Giardia, Cryptosporidium, and Entamoeba histolytica detection serves travel medicine and immunocompromised patient populations.
- Fungal:Candida and rare enteric mycoses occupy niche diagnostic applications.
- Protozoan:Single-celled eukaryotic pathogens require specialized microscopy or molecular methods.
- Helminthic:Intestinal worm detection persists in neglected tropical disease programs.
Bacterial targets anchor commercial panel development. Viral detection is gaining share fastest through syndromic testing adoption.
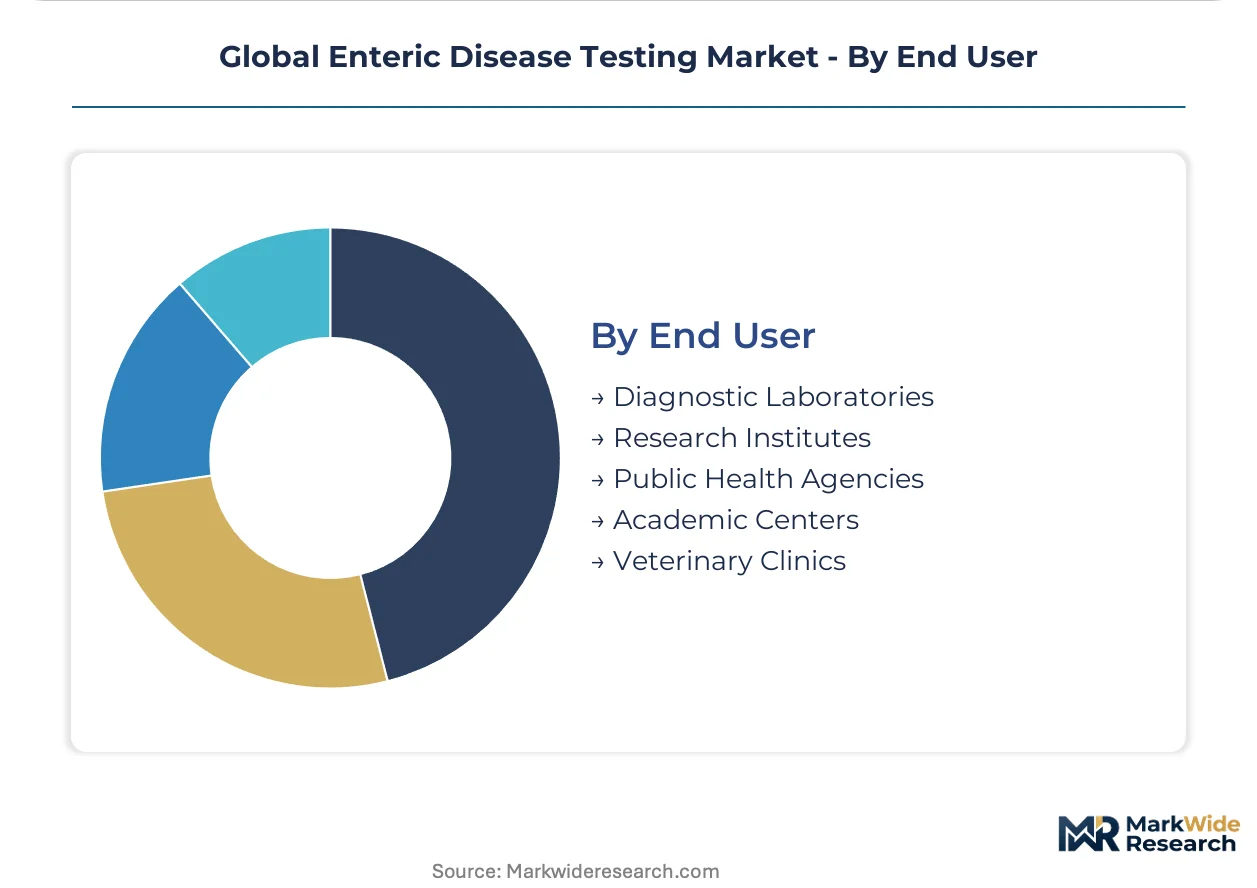
End User:
Procurement authority and testing volume concentration vary dramatically across institutional categories, shaping vendor salesforce deployment and contract negotiation strategies.
- Diagnostic Laboratories:Commercial and hospital-affiliated laboratories process the majority of enteric testing specimens under capitated or fee-for-service arrangements. Quest Diagnostics and similar networks consolidate purchasing power through multi-site instrument standardization in the United States.
- Public Health Agencies:State and national reference laboratories conduct outbreak investigation and surveillance with specialized sequencing capabilities. The US CDC and equivalent European agencies drive demand for whole-genome sequencing in foodborne disease tracking.
- Research Institutes:Academic and commercial research organizations support assay development and epidemiological studies.
- Academic Centers:Teaching hospitals combine clinical service with training and method evaluation.
- Veterinary Clinics:Animal health applications address zoonotic enteric pathogen transmission.
Diagnostic Laboratories dominate installed instrument base. Public Health Agencies are where sequencing capability expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government procurement programs and antimicrobial stewardship mandates are redistributing testing infrastructure across national health systems. India, the United States, Germany, China, and Brazil concentrate distinct competitive dynamics shaped by regulatory pathways and institutional purchasing power.
United States
Hospital antimicrobial stewardship programs penalize delayed pathogen identification, driving laboratory investment in multiplex PCR platforms. The FDA's in vitro diagnostic framework shapes clinical validation timelines for multiplex GI panel manufacturers. Boston and San Diego anchor molecular diagnostic development clusters where reference laboratories standardize instrument procurement.
India
District hospital networks under the National Health Mission generate institutional demand for automated nucleic acid extraction systems. The Central Drugs Standard Control Organization accelerates registration pathways for WHO-prequalified enteric diagnostics. Hyderabad and Mumbai concentrate manufacturing partnerships between global IVD suppliers and domestic distributors serving public tenders.
Germany
EMA's In Vitro Diagnostic Regulation mandates prospective clinical evidence for Class C device CE marking, extending development timelines for multiplex panel producers. The country's statutory health insurance system reimburses pathogen-specific identification at premium rates. Berlin and Munich host clinical affairs teams managing parallel multi-member state studies.
China
National Health Commission directives prioritize domestic IVD production for enteric fever surveillance in provincial hospital networks. The National Medical Products Administration streamlines registration for locally manufactured molecular platforms. Shanghai and Suzhou concentrate reagent manufacturing clusters supplying Asia-Pacific distribution channels.
Brazil
ANVISA's regulatory convergence with international standards enables accelerated product registration for European and US manufacturers. Public health laboratories in São Paulo and Rio de Janeiro coordinate foodborne disease surveillance with sequencing-based outbreak investigation. Federal procurement aggregates demand under centralized tenders favoring integrated platform suppliers.
Global Enteric Disease Testing Market Competitive Landscape
On the supply side, the industry is consolidating around integrated platform providers capable of bundling instruments, reagents, and service contracts. Three archetypes dominate: diversified life science conglomerates with installed base leverage, specialized diagnostic manufacturers with automated workflow integration, and commercial laboratory networks controlling geographic access to specimen volume. Competitive positioning hinges on per-test pricing flexibility and leasing model innovation rather than capital equipment sales alone.
Among diversified conglomerates, Thermo Fisher Scientific occupies a position exemplifying installed base monetization through consumable recurring revenue. bioMérieux SA represents the specialized diagnostic archetype with integrated specimen-to-result workflows. Quest Diagnostics anchors the laboratory network model, consolidating purchasing power through multi-site standardization and controlling patient access via phlebotomy infrastructure.
| Leading Market Players |
|---|
| Abbott Laboratories |
| bioMérieux SA |
| Becton Dickinson and Company |
| Bio-Rad Laboratories |
| Cepheid |
| Thermo Fisher Scientific |
| Quest Diagnostics |
| DiaSorin S.p.A. |
| Meridian Bioscience |
| Others |
Supply & Pricing Matrix
Single-source dependency on German and United States polymerase manufacturing clusters exposes regional laboratories to simultaneous pricing tier compression and supply chain fragility. This concentration forces buyers into long-term reagent contracts that widen spreads between premium CE-marked panels and economy-grade alternatives while tethering procurement decisions to transatlantic logistics chokepoints.
Pricing Analysis
Certification level creates the primary spread between premium FDA-cleared multiplex panels and economy-grade alternatives lacking WHO prequalification. Per-test reagent rental agreements dominate the pricing model, with antimicrobial stewardship mandates in US hospitals sustaining premium tiers while India's National Health Mission procurement drives standard-tier volume. Pricing pressure stems from Gavi-eligible tender aggregation favoring bundled instrument-service contracts over standalone reagent sales. Public health reference laboratories exhibit lowest price sensitivity due to surveillance mandates, while mid-volume Southeast Asian clinical laboratories face acute cost compression.
Supply Chain Analysis
Thermo Fisher Scientific and bioMérieux SA concentrate contract manufacturing capacity for automated nucleic acid extraction systems across Germany, the United States, and Singapore. Production draws from specialized polymerase enzymes, fluorescent probe chemistries, and precision thermal cycling components. Single-source vulnerability in Taq polymerase supply from Bavarian manufacturing clusters creates exposure to regulatory inspection delays. Distribution runs through integrated delivery networks consolidating gastrointestinal testing contracts under single-source agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Multiplex stool PCR penetration in India's district hospital networks signals early-cycle expansion with institutional procurement tailwinds accelerating platform adoption across Gavi-eligible health systems.
For Market Incumbents: Harden installed base monetization through consumable lock-in contracts that extend beyond instrument depreciation cycles. Threaten emerging point-of-care battery-operated PCR entrants by accelerating cloud-connected analyzer deployment for remote quality control. Priority lever rests on backward integration into fluorescent probe chemistry manufacturing to neutralize German supply cluster dependency. For New Entrants and Emerging Players: Sub-Saharan Africa's rural clinic infrastructure outside centralized laboratory networks offers the most penetrable white-space for battery-operated PCR device deployment. Target district hospital procurement officers in Ethiopia and Kenya with per-test leasing models that eliminate capital expenditure barriers. Go-to-market angle emphasizes WHO prequalification pathway acceleration for Gavi tender eligibility. For Investors and Strategic Acquirers: The market sits at a platform consolidation phase that favors specialized diagnostic manufacturers with automated specimen-to-result workflow integration. Long-term viability hinges on antimicrobial stewardship mandate expansion beyond US hospital systems into European statutory insurance frameworks. Acquisition target archetype: mid-cap firms with CE marking under IVDR and established clinical affairs teams in France, Germany, and Italy. Signal to watch is EMA Class C device clinical evidence requirement enforcement intensity.| Strategic Initiative | Industry Significance |
|---|---|
| WHO Prequalification Pathway Acceleration | Unlocks Gavi-eligible country tenders and institutional procurement eligibility. |
| CE Marking Under IVDR | Enables European commercialization through EMA-mandated prospective clinical evidence. |
| Hospital System Partnership | Secures single-source contract consolidation under integrated delivery network agreements. |
| Software Companion Development | Supports cloud-connected multiplex analyzers with AI-assisted pattern recognition. |
| Reimbursement Strategy | Aligns pathogen-specific identification codes with antimicrobial stewardship penalty structures. |
Research Methodology
Initial hypotheses were tested against primary input from clinical laboratory directors, hospital procurement managers, biomedical engineers, and GPO contracts specialists and refined through secondary validation. Sources included FDA 510(k) filings, EMA IVDR technical documentation, WHO prequalification assessment reports, hospital procurement databases, and CMS Medicare reimbursement codes. Bottom-up instrument installation data triangulated against top-down health system expenditure estimates.
Demand-supply balance modeling across the analysis window incorporated testing technique segmentation by turnaround velocity, sample type stratification by reimbursement tier, target pathogen prioritization by surveillance mandate, and end-user procurement authority concentration. CAGRs derived from instrument placement trajectories, consumable pull-through rates, and tender award patterns. Industry-specific inputs captured antimicrobial stewardship penalty implementation timelines and district hospital automation integration curves.
Practitioners should monitor EMA IVDR clinical evidence enforcement, WHO prequalification pathway backlog clearance, and Gavi tender aggregation shifts for early signals. Quarterly review of district hospital automation procurement awards and integrated delivery network contract consolidation announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Global IVD Regulatory Affairs Outsourcing Market
Testing Services
Warfarin Sensitivity Testing Market
Testing Services
Cerebrospinal Fluid (CSF) Testing Market
Testing Services
Global Anti Thrombin III Testing Market
Testing Services
Global Drug Abuse Testing Market
Testing Services
North America Testing Inspection and Certification (TIC) Market
Testing Services
Continuous Tablet Manufacturing At-Line Quality Test Systems Market
Testing Services
Rapid Hepatitis Testing Market
Testing Services
Middle East and Africa IVD Regulatory Affairs Outsourcing Market
Testing Services
Preclinical Medical Device Testing Services Market
Testing Services
Pharmaceutical Analytical Testing Market
Testing Services
Point of Care Lipid Test Market
Testing Services
Global Diagnostic Testing Market
Testing Services
Beta-Hydroxybutyrate Testing Market
Testing Services
Global CA 125 Test Market
Testing Services
Global Lipid Panel Testing Market