
 Global Roadside Drug Testing Devices Market | 2026-2036
Global Roadside Drug Testing Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Roadside Drug Testing Devices Market Foresight
Saliva-based biosensor miniaturization is tilting device architecture toward integrated cartridge systems with embedded microfluidics. Drägerwerk AG & Co. KGaA leverages its breathalyzer heritage to dominate European law enforcement tenders. Abbott Laboratories anchors North American distribution through its established clinical diagnostics infrastructure. Thermo Fisher Scientific, Inc. competes on mass spectrometry precision for confirmatory workflows.
Roadside drug testing devices are electrochemical or optical instruments designed to detect psychoactive substances in biological matrices within minutes, typically achieving sensitivity thresholds of 10-50 ng/mL for common analytes. Their primary purpose is to provide probable cause for law enforcement detention while reducing reliance on centralized laboratory confirmation. Breathalyzers retain the largest installed base among product types due to decades of alcohol-focused precedent, yet saliva test devices represent the fastest-expanding category as oral fluid correlates more directly with recent cannabis exposure. Deployment mode segmentation reveals handheld devices capturing the majority of new procurement budgets, though vehicle-mounted equipment commands premium pricing from specialized highway patrol units.
The U.S. Department of Transportation, Germany's Federal Highway Research Institute, and the European Union's In-Vitro Diagnostic Regulation collectively shape device approval pathways, calibration protocols, and cross-border interoperability standards. FDA 510(k) clearance and CE marking under the EU IVDR create divergent compliance burdens that fragment supplier go-to-market strategies. Stakeholders must monitor evolving THC per se limits across U.S. state laboratories and European reference institutes, as threshold harmonization would reshape competitive positioning for multi-analyte platforms.
Market Dynamics
Saliva-based biosensor miniaturization is compressing device refresh cycles as law enforcement agencies prioritize rapid roadside turnaround over laboratory-dependent workflows. This technological inflection is redistributing procurement budgets toward integrated cartridge systems with embedded microfluidics.
Growth Catalysts
- Oral fluid testing guidelines:The U.S. Department of Transportation's updated protocols are mandating portable screening infrastructure replacement across state highway patrol fleets.
- European certification requirements:Germany's Federal Highway Research Institute standards are accelerating device validation timelines and cross-border tender harmonization.
- Handheld format preference:Police forces are redirecting capital expenditure toward single-officer deployable units, bypassing vehicle-mounted installation complexity.
Market Restraints
- THC threshold fragmentation:Divergent per se limits across U.S. state laboratories and European reference institutes are forcing redundant product variants and compliance duplication.
- Optical component supply concentration:Specialized photodetector manufacturing clusters in East Asia are creating procurement vulnerability for electrochemical sensor producers.
- Confirmatory workflow dependency:Mass spectrometry precision requirements for legal admissibility are limiting standalone device revenue potential.
Strategic Opportunities
- Multi-analyte platform development:Simultaneous detection of cannabis, opioids, and stimulants is opening consolidated procurement contracts previously split across separate devices.
- Workplace safety expansion:Mining and logistics operators in Australia and Canada are adopting roadside-equivalent protocols for pre-shift screening.
- Cloud-connected evidence chains:Integration with digital ticketing systems is creating subscription-based service revenue adjacent to hardware sales.
Industry Challenges
- Forensic toxicology talent scarcity:Device manufacturers face recruitment bottlenecks for analytical chemists capable of bridging electrochemical engineering and legal admissibility standards.
- FDA 510(k) and CE-IVDR parallel track complexity:Divergent documentation requirements are extending time-to-market for dual-territory launches by 12-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Roadside Drug Testing Devices Market |
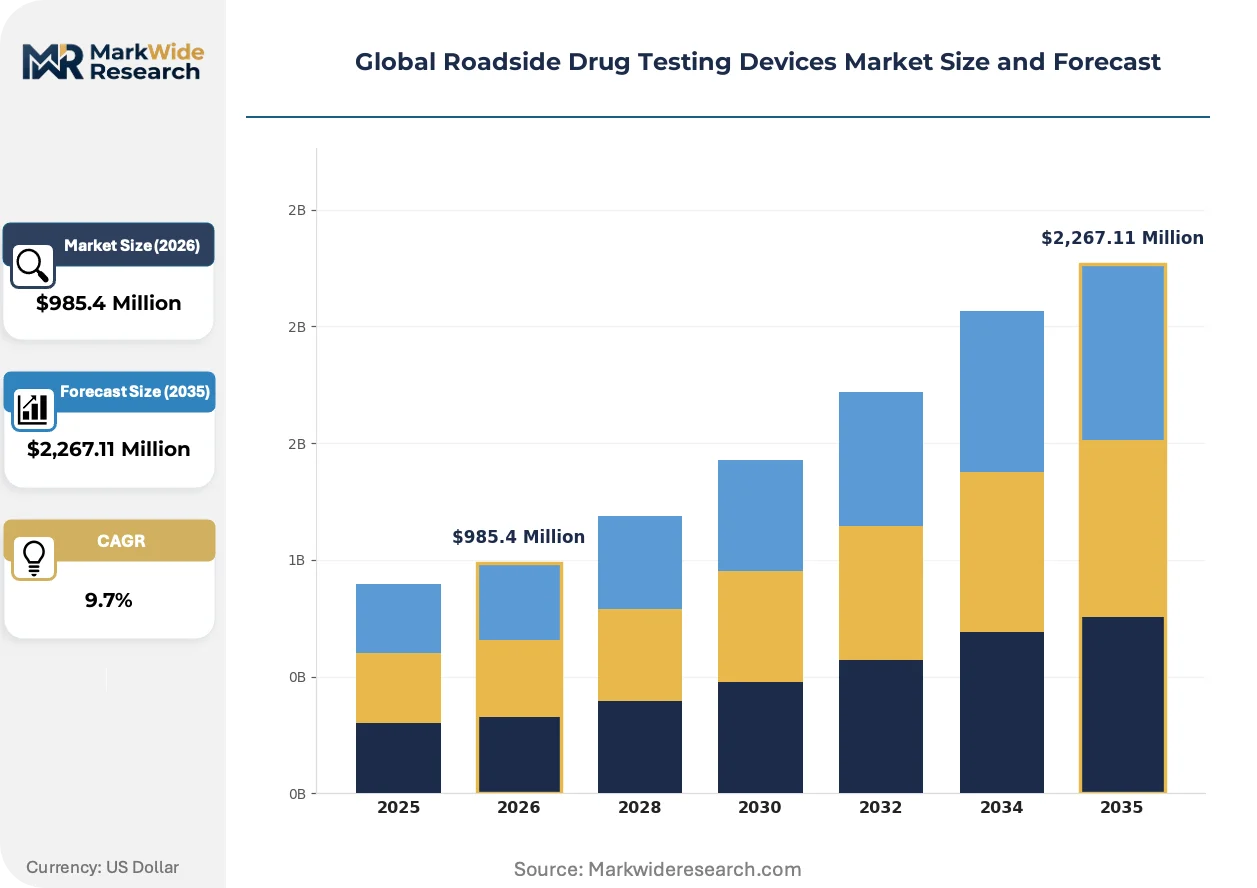
| Market Size in 2026 | $985.4 Million |
| Market Size in 2035 | $2,267.11 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Immunoassay Test Kits, Breathalyzers, Saliva Test Devices, Urine Test Strips Detection Technology: Enzyme Multiplied Immunoassay Technique, Gas Chromatography, Mass Spectrometry, Infrared Spectroscopy End User: Law Enforcement Agencies, Transportation Companies, Workplace Safety Officers, Insurance Assessors Deployment Mode: Portable Units, Handheld Devices, Vehicle-Mounted Equipment, Stationary Testing Centers |
| Companies Covered | Drägerwerk AG & Co. KGaA, Abbott Laboratories, Alcohol Countermeasure Systems Corp., Cannabix Technologies Inc., Lifeloc Technologies, Inc., AK GlobalTech Corporation, Oranoxis Inc., Intelligent Fingerprinting, Thermo Fisher Scientific, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Roadside Drug Testing Devices Market Shifts & Advancements
Device architecture is pivoting from standalone instruments toward connected ecosystems where data integrity and chain-of-custody automation command premium positioning. This shift is redefining competitive advantage around software integration rather than sensor sensitivity alone.
Microfluidic cartridge systems are collapsing the boundary between sample collection and analytical processing. Police training academies in the United Kingdom and Netherlands are adopting these all-in-one units to eliminate officer handling steps. The technology is collapsing error rates associated with sample contamination while compressing roadside processing time below 90 seconds.
The European Union's In-Vitro Diagnostic Regulation is mandating clinical-grade performance documentation for law enforcement devices previously regulated under industrial safety frameworks. Manufacturers must now submit analytical sensitivity studies equivalent to hospital laboratory equipment. Breathalyzer-dominant suppliers are responding by acquiring clinical diagnostics capabilities to satisfy notified body expectations.
Leasing arrangements with bundled calibration services are displacing capital purchase models among municipal police departments with constrained annual budgets. Distributors in France and Italy are piloting per-test pricing structures that include device maintenance and reagent supply. This financial restructuring is most visible in Southern European markets where austerity-era procurement restrictions persist.
Global Roadside Drug Testing Devices Market Segmentation
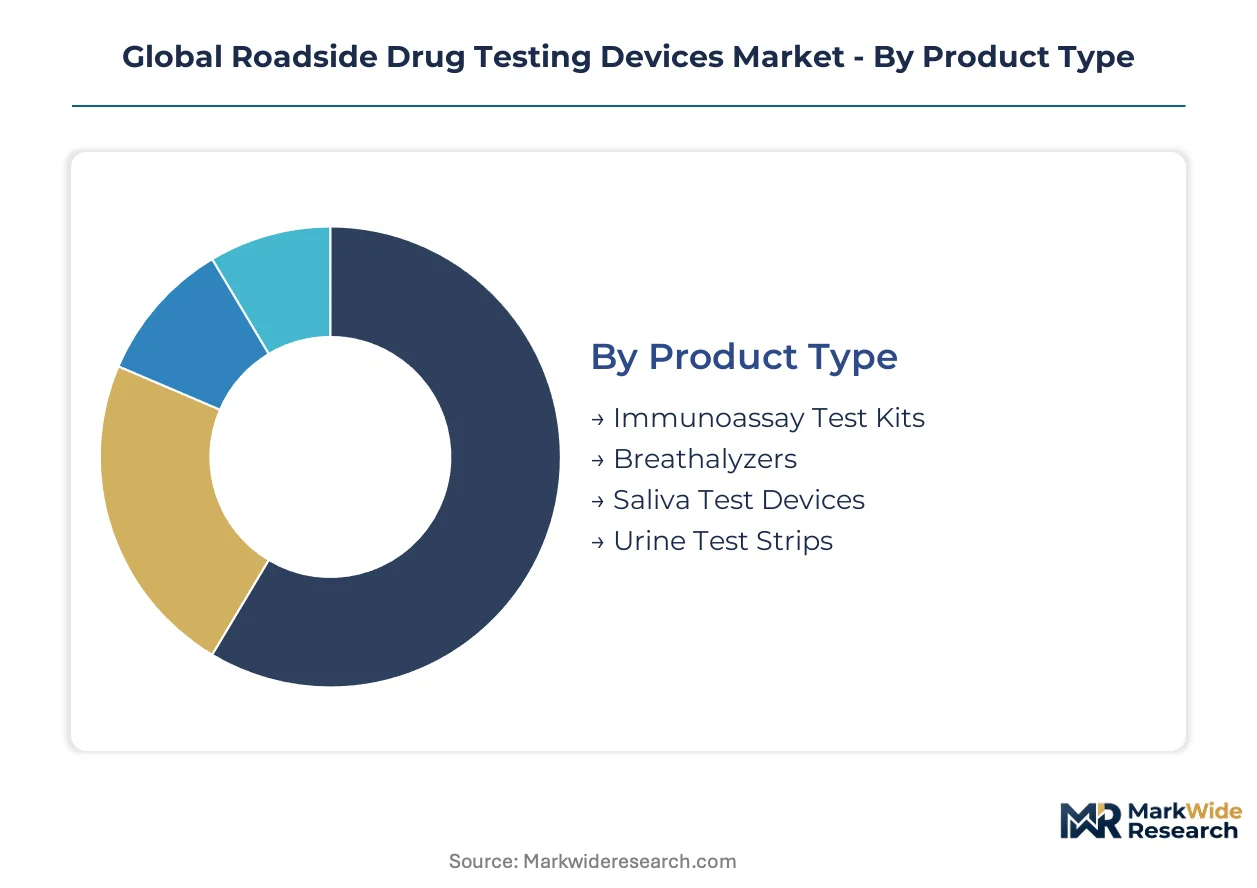
Segmentation in roadside drug testing devices reflects divergent procurement priorities across enforcement, occupational safety, and insurance verification contexts. Technology choices and deployment formats directly determine regulatory compliance pathways and operational cost structures for end-users.
Product Type:
Cost tier differentiation separates single-use consumables from capital-intensive analytical instruments, with procurement budgets fragmenting across disposable reagent supplies and durable hardware platforms.
- Breathalyzers:Electrochemical fuel cell or infrared sensor architectures measure blood alcohol concentration through expired breath analysis. State highway patrol fleets in the United States and Germany's KBA-certified police units maintain the largest installed bases, though cannabis detection limitations are redirecting replacement budgets toward multi-analyte alternatives.
- Saliva Test Devices:Oral fluid collection cartridges with integrated lateral flow immunoassay strips detect recent psychoactive substance exposure within detection windows of 24-48 hours. Australian mining operators and Canadian trucking consortiums are expanding procurement for pre-shift screening protocols, bypassing the privacy complications of urine collection.
- Immunoassay Test Kits:Antibody-based reagent systems for laboratory or field confirmation workflows.
- Urine Test Strips:Dipstick formats with colorimetric readouts for workplace and clinical settings.
Breathalyzers command the established base. The steepest expansion runs through saliva test devices.
Detection Technology:
Application requirements for speed versus forensic precision split procurement between rapid presumptive screening and legally admissible confirmatory methods.
- Mass Spectrometry:Gas chromatography-tandem mass spectrometry (GC-MS/MS) configurations deliver quantitative analyte identification with detection thresholds below 1 ng/mL. European reference laboratories under EU IVDR oversight and U.S. state forensic toxicology facilities require this technology for per se limit enforcement, though capital costs and operator training requirements restrict deployment to centralized facilities.
- Enzyme Multiplied Immunoassay Technique:EMIT-based systems leverage enzyme-labeled competitive binding for rapid semi-quantitative screening. French municipal police and Italian Carabinieri units prioritize these platforms for roadside turnaround under 5 minutes, accepting reduced specificity in exchange for operational throughput.
- Gas Chromatography:Separation-based methods for confirmatory quantification in laboratory settings.
- Infrared Spectroscopy:Non-destructive molecular fingerprinting for breath alcohol and emerging drug detection applications.
Mass spectrometry anchors forensic admissibility standards. EMIT platforms are gaining share fastest in decentralized enforcement applications.
End User:
Customer type determines purchasing authority structures, with public sector procurement cycles diverging sharply from corporate safety compliance timelines.
- Law Enforcement Agencies:Police departments and highway patrol units operate under judicial scrutiny requirements that mandate chain-of-custody documentation and evidentiary-grade calibration protocols. The U.S. Department of Transportation's oral fluid testing guidelines and Germany's Federal Highway Research Institute certification standards are accelerating device refresh cycles across North American and European patrol fleets.
- Transportation Companies:Commercial trucking, aviation, and maritime operators face DOT, EASA, and IMO regulatory mandates for substance testing. Australian iron ore haulers and Canadian long-haul logistics providers are adopting roadside-equivalent screening for remote site access control.
- Workplace Safety Officers:Occupational health departments in manufacturing and resource extraction sectors.
- Insurance Assessors:Claims verification specialists evaluating impairment in accident reconstruction contexts.
Law enforcement agencies dominate cumulative installed value. Transportation companies are expanding most quickly as sector-specific mandates proliferate.
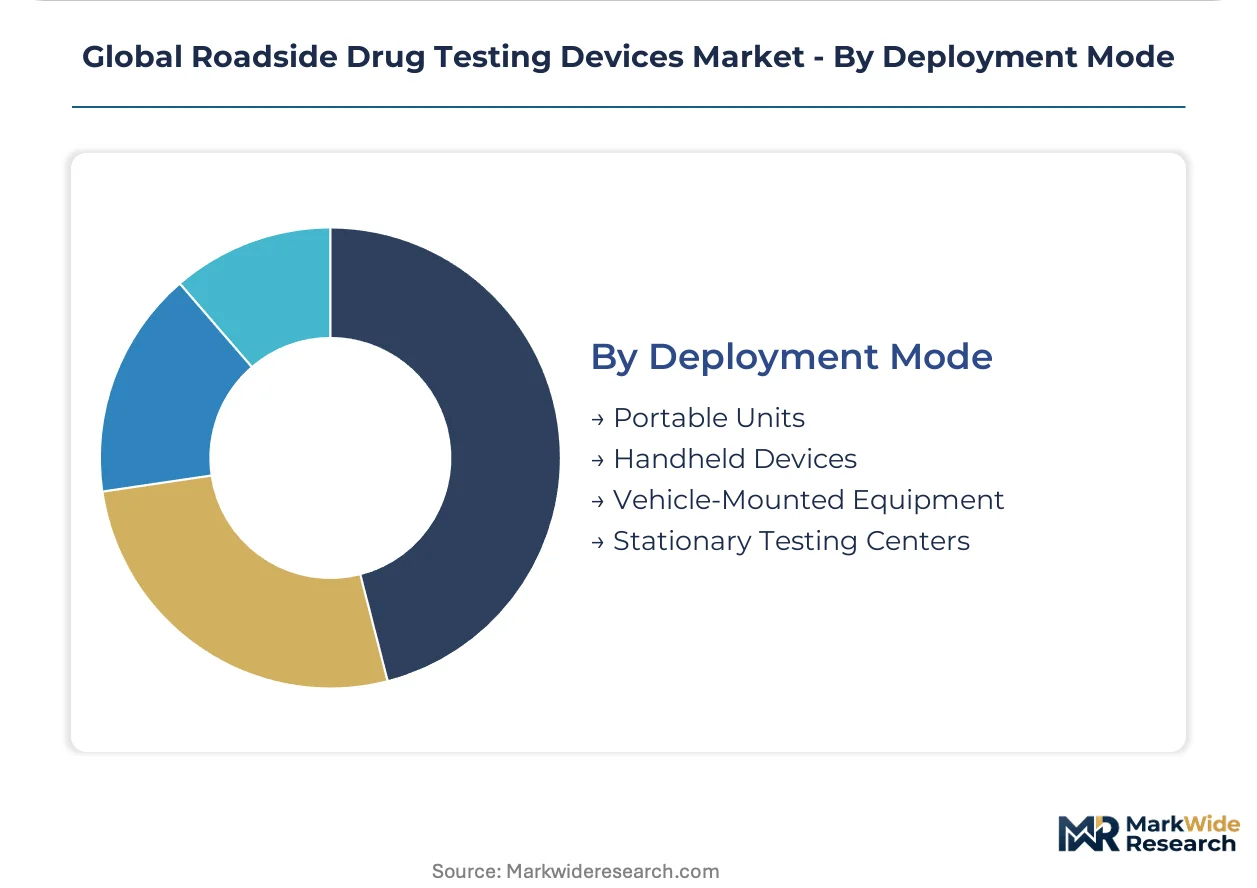
Deployment Mode:
Volume and mobility requirements shape hardware form factors, with officer-carried units displacing vehicle-integrated systems in procurement priorities.
- Handheld Devices:Battery-powered single-operator units weighing under 500 grams enable roadside administration without vehicle proximity constraints. Dutch police training academies and United Kingdom constabularies are standardizing on these formats to eliminate installation costs and cross-fleet compatibility issues.
- Vehicle-Mounted Equipment:Dashboard-integrated or trunk-installed systems with external power supplies and printer documentation capabilities. Specialized highway patrol units in Italy and Spain retain preference for these configurations despite premium pricing, leveraging superior environmental protection and evidence chain automation.
- Portable Units:Briefcase-sized systems for flexible field deployment with optional vehicle docking.
- Stationary Testing Centers:Fixed-site installations for high-throughput processing and confirmatory workflows.
Vehicle-mounted equipment retains premium positioning in specialized units. Handheld devices are climbing the fastest through general patrol procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Police procurement departments in Germany, the United States, Australia, the United Kingdom, and Canada concentrate the majority of device procurement budgets. These buyers prioritize rapid roadside turnaround and evidentiary-grade calibration protocols.
United States
State highway patrol fleets in California, Texas, and Florida are replacing legacy breathalyzer infrastructure with oral fluid-compatible systems. The Department of Transportation's updated guidelines mandate portable screening capabilities by 2026. Device validation laboratories in Phoenix and Chicago are certifying multi-analyte platforms for per se limit enforcement.
Germany
Federal Highway Research Institute certification requirements are accelerating device refresh cycles across state police forces. The KBA maintains Europe's most stringent performance documentation standards for law enforcement tenders. Manufacturing clusters in Lübeck and Trier supply electrochemical sensor modules to European patrol fleets.
Australia
Iron ore haulers in Western Australia and Queensland coal operators are adopting roadside-equivalent screening for remote site access control. The Therapeutic Goods Administration regulates device performance claims for workplace safety applications. Mining consortiums in Perth and Brisbane are consolidating pre-shift testing contracts under single-supplier arrangements.
United Kingdom
Constabularies in England and Wales are standardizing on handheld formats to eliminate cross-fleet compatibility issues. The Home Office sets THC threshold guidance that shapes device sensitivity requirements. Training academies in Staffordshire and Hampshire are certifying officers on microfluidic cartridge systems.
Canada
Long-haul logistics providers in Ontario and Alberta are implementing roadside-equivalent protocols for commercial driver screening. Health Canada oversees device approval for both law enforcement and workplace applications. Police services in Toronto and Calgary are piloting cloud-connected evidence chains integrated with digital ticketing systems.
Global Roadside Drug Testing Devices Market Competitive Landscape
Channel-controlling players compete with product-specialist players across procurement tiers. The market structures around three concentration nodes: breathalyzer heritage suppliers, clinical diagnostics conglomerates, and emerging biosensor specialists. Strategic archetypes include integrated system vendors, component-focused suppliers, and service-bundle distributors. M&A activity targets clinical-grade capabilities, while geographic expansion concentrates on dual-territory FDA and CE-IVDR certification.
Among heritage breathalyzer suppliers, Drägerwerk AG & Co. KGaA and Alcohol Countermeasure Systems Corp. occupy positions shaped by decades of law enforcement relationships. Abbott Laboratories and Thermo Fisher Scientific, Inc. exemplify the clinical-diagnostics conglomerate archetype, leveraging hospital laboratory infrastructure for forensic precision workflows. These three companies anchor competitive positioning across European and North American procurement channels.
| Leading Market Players |
|---|
| Drägerwerk AG & Co. KGaA |
| Abbott Laboratories |
| Alcohol Countermeasure Systems Corp. |
| Cannabix Technologies Inc. |
| Lifeloc Technologies, Inc. |
| AK GlobalTech Corporation |
| Oranoxis Inc. |
| Intelligent Fingerprinting |
| Thermo Fisher Scientific, Inc. |
| Others |
Supply & Pricing Matrix
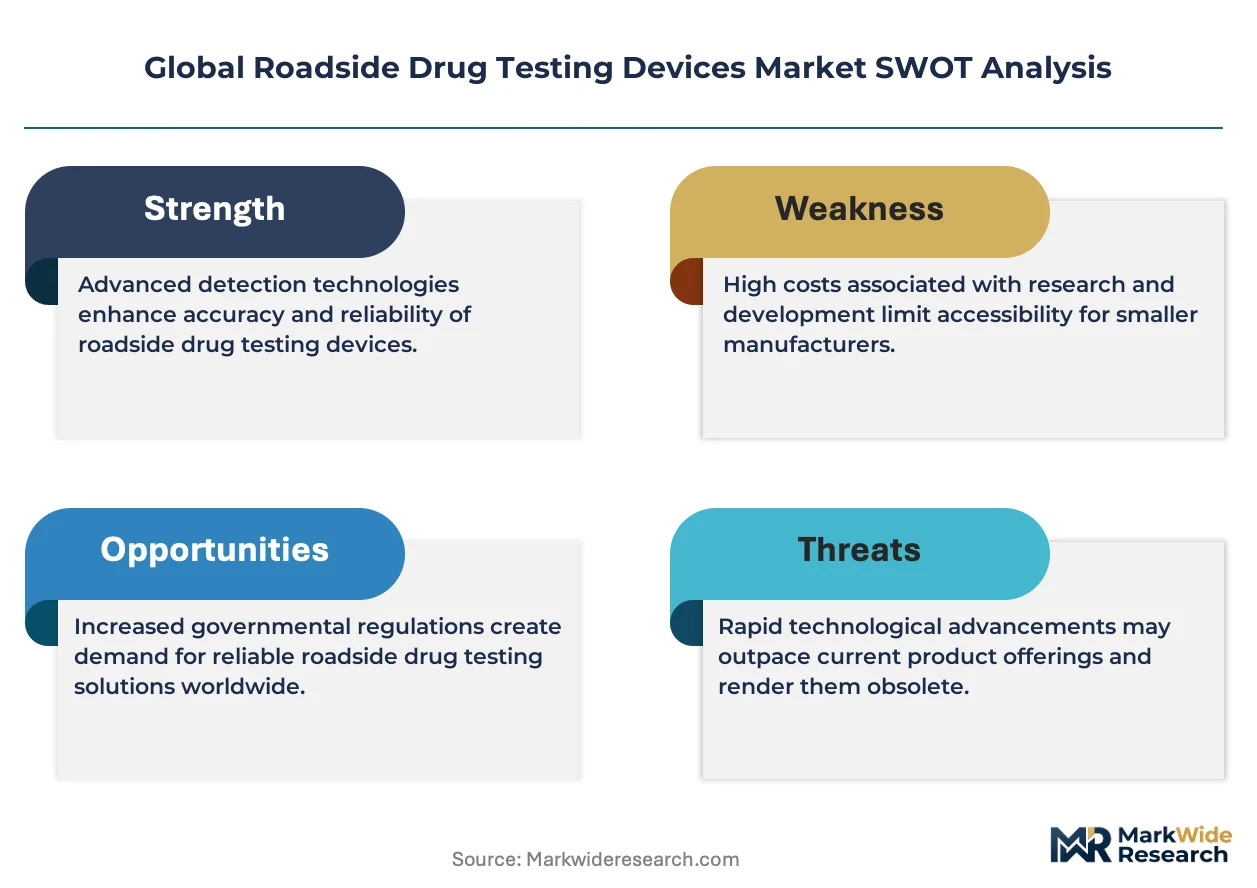
Overcapacity in East Asian photodetector fabrication is compressing margins for electrochemical sensor producers while forcing European device assemblers toward dual-sourcing strategies. This utilization imbalance concentrates pricing power with specialized optical component foundries in Taiwan and South Korea, amplifying procurement vulnerability for handheld device manufacturers dependent on infrared spectroscopy modules.
Pricing Analysis
Cost-plus contracts with semiconductor indexation dominate procurement agreements between German law enforcement agencies and device manufacturers, insulating suppliers from raw material volatility while capping margin expansion. Pricing stratifies across FDA 510(k)-cleared premium tiers, CE-IVDR standard tiers, and uncertified economy tiers for workplace safety applications. Cost compression in the economy tier is intensifying because Australian mining operators are consolidating pre-shift testing contracts under single-supplier arrangements. Transportation companies exhibit the highest price sensitivity due to thin fleet operating margins, whereas specialized highway patrol units in Italy and Spain accept premium pricing for vehicle-mounted equipment with evidence chain automation.
Supply Chain Analysis
Upstream feedstock for microfluidic cartridge substrates draws from German polymer specialists, Japanese precision molding houses, and Taiwanese semiconductor foundries. Specialized photodetectors and electrochemical sensor membranes hinge on concentrated manufacturing clusters in East Asia. Single-source vulnerability persists for infrared spectroscopy modules used in breathalyzer architectures. Distribution runs through clinical diagnostics distributors in North America and direct tender relationships with national police procurement offices in Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is entering a cyclical recovery phase as device refresh cycles accelerate under the U.S. Department of Transportation's oral fluid testing mandate and Germany's Federal Highway Research Institute certification requirements.
For Market Incumbents: Pre-empt emerging biosensor specialists by acquiring clinical-grade capabilities to satisfy EU IVDR notified body expectations. Secure backward integration into electrochemical sensor production to reduce exposure to East Asian photodetector supply concentration. Channel control through established law enforcement relationships remains the priority defensive lever against Abbott Laboratories and Thermo Fisher Scientific's clinical diagnostics infrastructure.
For New Entrants and Emerging Players: Canadian long-haul logistics providers represent underpenetrated white-space as workplace safety mandates proliferate beyond law enforcement. Australian iron ore haulers offer consolidated pre-shift testing contracts previously split across separate devices. A cloud-connected evidence chain integration with digital ticketing systems provides the most penetrable go-to-market angle for municipal police departments with constrained annual budgets.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across saliva-based biosensor miniaturization as integrated cartridge systems displace standalone instrument architectures. Five-to-ten year viability favors manufacturers with dual-territory FDA and CE-IVDR certification capabilities. Acquisition targets should display clinical diagnostics heritage bridging electrochemical engineering and legal admissibility standards. Monitor THC per se limit harmonization across U.S. state laboratories and European reference institutes as the critical inflection signal for multi-analyte platform consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Analyte Platform Development | Simultaneous cannabis, opioid, and stimulant detection opens consolidated procurement contracts previously split across separate devices. |
| Cloud-Connected Evidence Chain Integration | Digital ticketing system compatibility creates subscription-based service revenue adjacent to hardware sales for Canadian police services. |
| Clinical Diagnostics Capability Acquisition | EU IVDR compliance requirements mandate analytical sensitivity studies equivalent to hospital laboratory equipment for law enforcement tenders. |
| Microfluidic Cartridge System Deployment | All-in-one units eliminate officer handling steps and compress roadside processing time below 90 seconds for UK constabularies. |
| Per-Test Pricing Structure Pilot | Leasing arrangements with bundled calibration services displace capital purchase models among French and Italian municipal police departments. |
Research Methodology
The analysis maps handheld devices, vehicle-mounted equipment, breathalyzers, and saliva test devices, each validated through procurement officers at state highway patrol fleets, forensic toxicology laboratory directors, and workplace safety compliance managers. Primary interviews with device manufacturers, clinical diagnostics distributors, and police training academy instructors combined with secondary validation against FDA 510(k) filings, CE-IVDR notified body documentation, and U.S. Department of Transportation guideline releases. Bottom-up unit shipment estimates triangulated against top-down law enforcement budget allocations across the analysis window.
Assumptions held fixed include current THC per se limit fragmentation and existing FDA 510(k) versus CE-IVDR parallel track complexity, while regulatory harmonization scenarios and optical component supply disruption events were varied. Segmentation dimensions modeled encompass product type, detection technology, deployment mode, and end-user procurement authority structure across the projection horizon. CAGRs derived from device refresh cycle velocity, tender award patterns, and replacement demand elasticity. Forecast inputs included state-level oral fluid testing guideline adoption timelines and mining sector workplace safety mandate expansion rates.
Practitioners should monitor THC threshold harmonization initiatives and photodetector manufacturing capacity utilization for early signals of competitive repositioning. Forecasts reflect assumptions regarding regulatory pathway stability and supply chain geographic concentration. Cross-checking against U.S. Department of Transportation enforcement statistics and European reference laboratory certification data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
South Korea GMP Testing Service Market
Testing Services
Alcohol Breathalyzer and Drug Testing Equipment Market
Testing Services
Adiponectin Testing Market
Testing Services
Europe Point-Of-Care-Testing (POCT) Market
Testing Services
Osmometer Market
Testing Services
Activated Partial Thromboplastin Test Market
Testing Services
Drug Testing Equipment Market
Testing Services
Global Sterility Testing Market
Testing Services
Medical Device Testing, Inspection, and Certification Market
Testing Services
Global Ovulation Test Market
Testing Services
Blood Testing Market
Testing Services
Friability Tester Market
Testing Services
Allergy Skin Test Market
Testing Services
Hemotransmissive Infections Testing Market
Testing Services
Instrument Calibration Services Market
Testing Services
Minimal Residual Disease Testing Market