
 North America Testing Inspection and Certification (TIC) Market | 2026-2036
North America Testing Inspection and Certification (TIC) Market Size, Share, and Industry Trends Forecast 2026-2036
North America Testing Inspection and Certification (TIC) Market Insights
Market Context with Strategic Players
Direct laboratory-to-manufacturer relationships is narrowing as digital platform intermediaries and consolidated procurement channels reshape how TIC services reach end users. Bureau Veritas leverages its marine and industrial heritage to sustain dominant positions in energy sector inspections across the Gulf Coast. Intertek Group plc anchors its North American footprint through extensive consumer goods testing networks that serve retail compliance programs. UL LLC differentiates through deep specialization in electrical safety certification that commands premium positioning in building technology markets.
Technical Definition and Structural Segments
Testing, Inspection and Certification encompasses the independent verification of product conformity, system integrity, and process compliance against defined technical standards, employing methodologies ranging from destructive materials analysis to non-destructive electromagnetic testing and management systems auditing. Its primary commercial purpose is to transfer risk from manufacturers and buyers to accredited third-party bodies, enabling market access while reducing liability exposure across complex supply chains. Certification services command the most durable margin pools due to recurring surveillance audit requirements and brand-dependent trust premiums, while testing revenues expand fastest in automotive battery validation and aerospace additive manufacturing qualification. End user demand from healthcare and construction verticals is structurally shifting toward integrated auditing bundles that combine ISO quality management with regulatory compliance verification.
Regulatory Frame and Forward-Looking Close
FDA medical device quality system regulations, EPA environmental testing mandates, and OSHA workplace safety inspection requirements collectively expand the mandatory addressable market for accredited TIC providers across the United States and Canada. ASTM standards development and CE marking facilitation for exporters further deepen service penetration among manufacturers seeking cross-border market access. Stakeholders must monitor how the proposed harmonization between FDA's quality management system requirements and international ISO 13485 standards will reshape certification scope and competitive positioning for medical technology suppliers.
Market Dynamics
Digital platform intermediaries are consolidating laboratory-to-manufacturer relationships, compressing procurement cycles and forcing accredited providers to restructure service delivery around real-time data exchange rather than episodic audit schedules.
Growth Catalysts
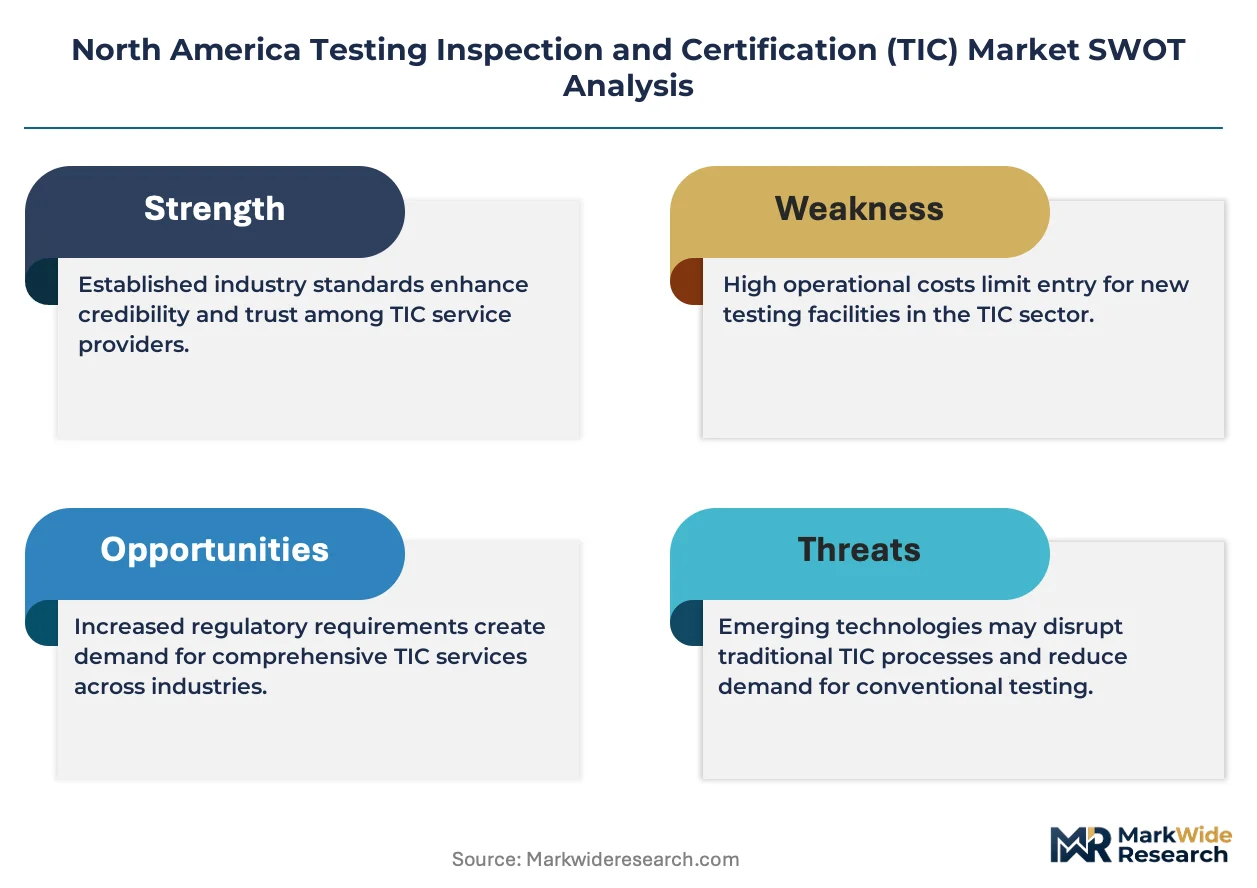
- FDA Quality System Regulations:Evolving medical device oversight compels healthcare suppliers to seek independent third-party certification, expanding mandatory addressable market for accredited TIC services across the United States.
- Semiconductor cluster concentration:California's technology corridor generates specialized testing demand from battery startups and chip manufacturers requiring environmental compliance and product safety verification.
- Aerospace additive manufacturing:Qualification protocols for 3D-printed airframe components create new testing revenue streams as manufacturers validate supply chain integrity for FAA airworthiness standards.
Market Restraints
- PhD-level talent scarcity:Electromagnetic testing and materials analysis expertise concentrates in coastal metropolitan labor markets, inflating compensation costs for specialized technical staff.
- Accreditation maintenance burden:ISO 17025 laboratory certification requires continuous capital reinvestment in calibration equipment and proficiency testing programs.
- Destructive testing input volatility:Rare earth materials and specialized chemical reagents face supply concentration risks from limited domestic refining capacity.
Strategic Opportunities
- Integrated auditing bundles:Healthcare and construction verticals seek combined ISO quality management with regulatory compliance verification, creating service packaging white space.
- CE marking facilitation:United States exporters to European Union markets require intermediary certification support for REACH and RoHS conformity assessment.
- Automotive battery validation:Electric vehicle supply chain expansion in Michigan and Tennessee generates underpenetrated demand for thermal runaway testing and cycle life verification.
Industry Challenges
- Surveillance audit compression:Certification bodies must execute recurring ISO surveillance visits within tightening client-mandated windows while maintaining auditor utilization rates.
- Legacy system integration:Laboratory information management systems require costly middleware development to interface with manufacturer ERP platforms for real-time certificate delivery.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Testing Inspection and Certification (TIC) Market |
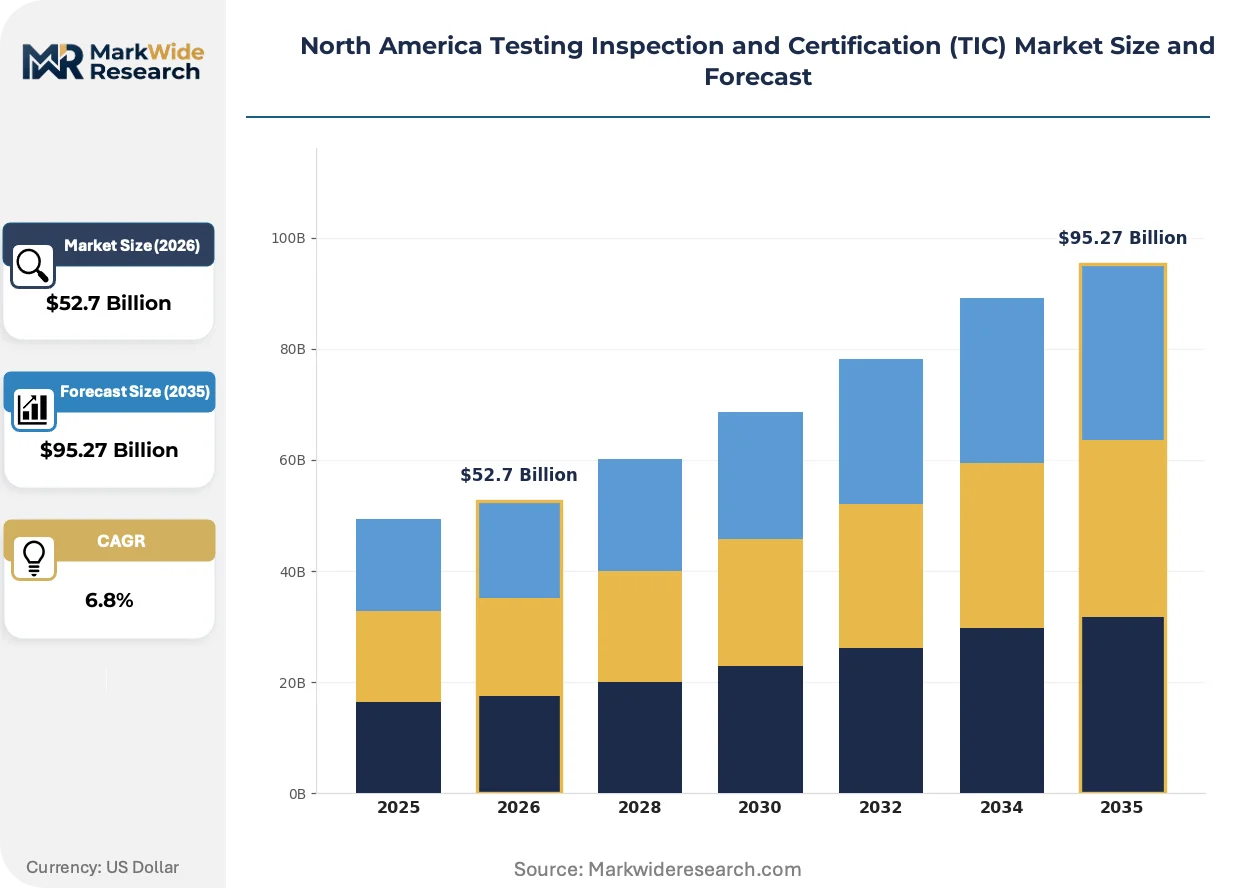
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $95.27 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Testing, Inspection, Certification, Auditing End User: Consumer Goods, Manufacturing, Construction, Healthcare Industry Vertical: Automotive, Aerospace, Energy, Food & Beverage Regulatory Compliance: ISO, ASTM, FDA, CE Marking |
| Companies Covered | Bureau Veritas, Intertek Group plc, SGS SA, TÜV SÜD, UL LLC, DEKRA, NSF International, Element Materials Technology, TÜV Rheinland, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Testing Inspection and Certification (TIC) Market Trends and Innovations
Remote sensing technologies and blockchain-based certificate verification are restructuring how conformity assessment data flows between testing facilities and regulatory filers, collapsing traditional document review timelines.
Non-destructive electromagnetic testing is migrating from aerospace maintenance depots to semiconductor fabrication facilities. Intel and TSMC Arizona operations now deploy eddy current arrays for wafer-level defect detection. This migration is compressing capital equipment replacement cycles as multi-sector demand converges on identical hardware platforms.
EPA environmental testing mandates for per- and polyfluoroalkyl substances (PFAS) are expanding analytical scope requirements for water and soil laboratories. The industrial consequence is mandatory method validation investments for LC-MS/MS instrumentation. Environmental consultancies in the Great Lakes region are most affected, accelerating partnerships with academic research facilities to meet detection limit specifications.
Buyer concentration among consolidated retail compliance programs is disintermediating small regional testing laboratories. Walmart and Target supplier qualification systems now route all consumer goods testing through pre-approved national laboratory networks. This consolidation is most visible in apparel and electronics verticals, where vendor reduction initiatives eliminate secondary certification options for mid-tier manufacturers.
North America Testing Inspection and Certification (TIC) Market Segmentation
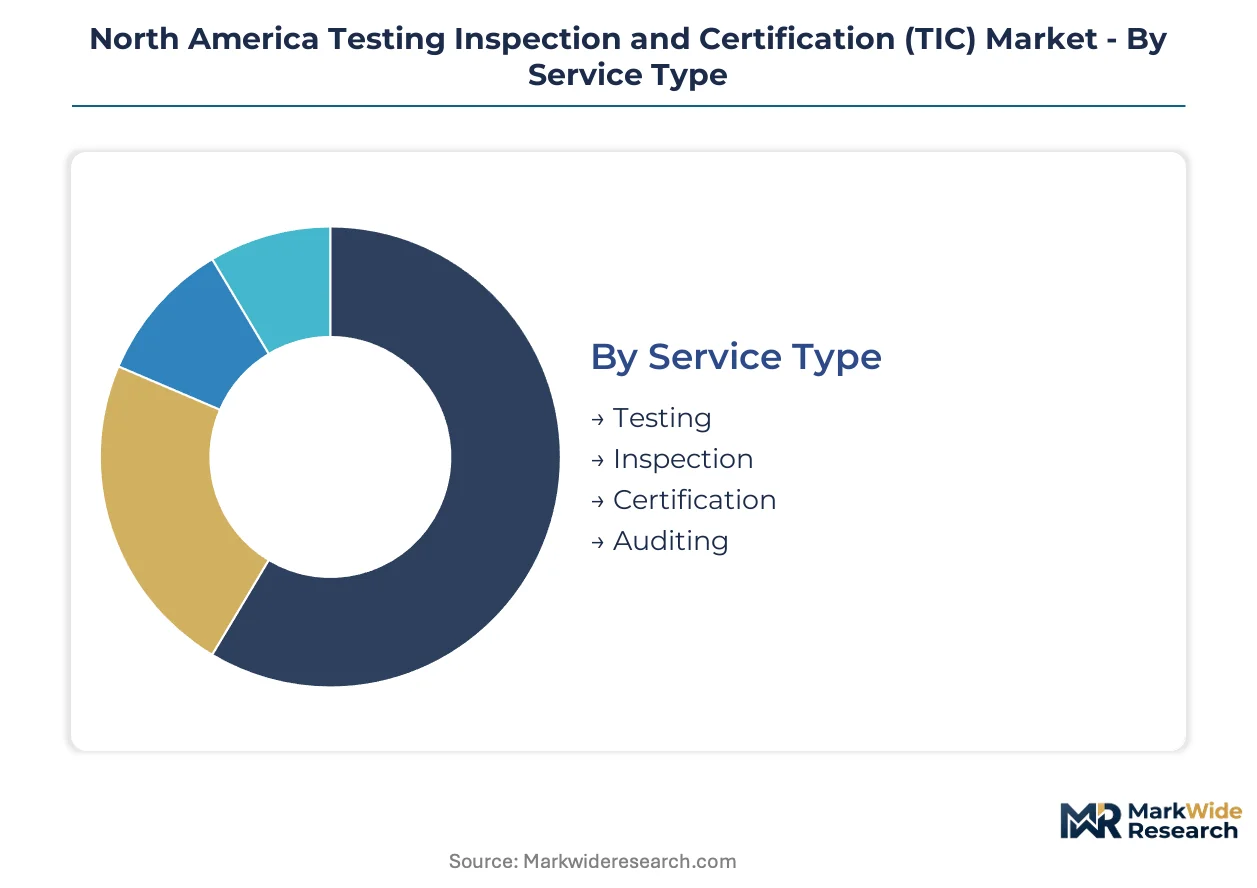
Service delivery models in the North America TIC market diverge sharply based on technical complexity, audit frequency, and regulatory mandate intensity. Segment boundaries blur as integrated bundles displace standalone offerings across healthcare and construction verticals.
Service Type:
Technical requirements span destructive materials analysis through non-destructive electromagnetic verification, with each service commanding distinct margin profiles and capital intensity.
- Testing:Destructive and non-destructive methodologies verify material composition, electromagnetic compatibility, and environmental stress tolerance. California semiconductor fabs and Michigan battery plants drive concentrated demand for thermal cycling and failure analysis protocols.
- Certification:Brand-dependent trust premiums and recurring surveillance audit requirements sustain the most durable margin pools. FDA quality system regulations and FAA airworthiness standards compel healthcare and aerospace suppliers into long-term certification relationships.
- Inspection:Supply chain integrity verification for additive manufacturing components and imported consumer goods. Gulf Coast energy infrastructure and Tennessee automotive assembly lines generate recurring site-based inspection demand.
- Auditing:Management systems evaluation combining ISO 9001 quality frameworks with sector-specific regulatory compliance. Healthcare and construction verticals increasingly specify integrated auditing bundles over standalone assessments.
The dominant share belongs to Testing, while Certification is closing the gap fastest through recurring surveillance mandates.
End User:
Procurement sophistication varies dramatically across buyer categories, from consolidated retail compliance programs to fragmented construction subcontractor networks.
- Consumer Goods:Walmart and Target supplier qualification systems now mandate pre-approved national laboratory networks, disintermediating regional testing providers. Apparel and electronics verticals face the most acute vendor consolidation pressure.
- Healthcare:FDA medical device quality system regulations and evolving ISO 13485 harmonization compel independent third-party verification. Minnesota and Massachusetts medical technology clusters generate specialized sterilization validation and biocompatibility testing demand.
- Manufacturing:Spanning automotive, electronics, and industrial equipment producers requiring incoming materials verification and finished goods conformity assessment. Michigan and Ohio manufacturing belts sustain high-volume routine testing relationships.
- Construction:Building code compliance and structural materials certification for commercial and infrastructure projects. Texas and Florida building booms drive demand for concrete strength testing and electrical safety verification.
Healthcare commands premium pricing power, while Consumer Goods is expanding most quickly through retail compliance program consolidation.
Industry Vertical:
Technical specifications and regulatory oversight intensity create divergent service packaging requirements across industrial sectors.
- Aerospace:FAA airworthiness standards and additive manufacturing qualification protocols demand specialized NDT expertise. Boeing and Airbus supply chains in Washington State and Quebec sustain premium-positioned inspection relationships.
- Automotive:Electric vehicle battery validation requirements—thermal runaway testing, cycle life verification—generate underpenetrated demand in Tennessee and Michigan production corridors. NHTSA safety standards and EPA emissions compliance expand mandatory testing scope.
- Energy:Gulf Coast offshore platforms and Texas renewable installations require corrosion monitoring and electrical safety inspection. FERC pipeline safety mandates and state renewable portfolio standards deepen regulatory compliance obligations.
- Food & Beverage:FDA food safety modernization act requirements and USDA organic certification sustain microbiological testing demand. California Central Valley agriculture and Wisconsin dairy processing anchor regional laboratory networks.
Automotive holds the steepest expansion trajectory, while Aerospace maintains the highest margin concentration.
Regulatory Compliance:
Standard adoption patterns reflect cross-border market access requirements and domestic enforcement intensity variations.
- ISO:Quality management and laboratory accreditation standards providing baseline conformity frameworks. ISO 17025 certification requirements force continuous capital reinvestment in calibration equipment across accredited providers.
- FDA:Medical device quality system regulations and food safety mandates compelling independent third-party verification. Proposed harmonization with ISO 13485 will reshape certification scope for healthcare technology suppliers.
- ASTM:Materials and testing standards development organization whose specifications underpin construction and manufacturing conformity assessment. ASTM methods provide reference protocols for domestic arbitration and litigation support.
- CE Marking:European Union market access facilitation requiring REACH and RoHS conformity assessment support. United States exporters to EU markets generate intermediary certification demand for chemical safety and electrical compliance documentation.
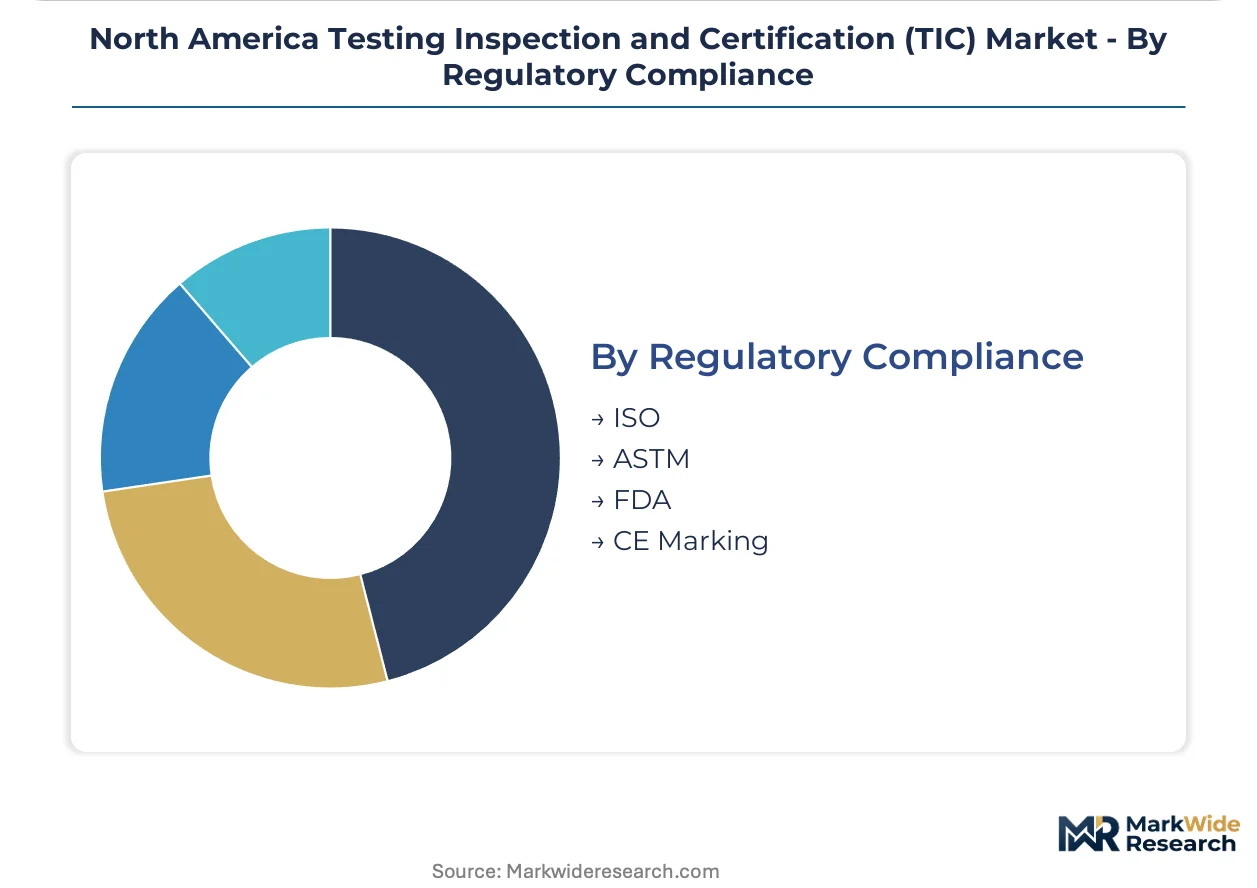
ISO standards provide the foundational compliance layer, while FDA regulations are gaining share fastest through medical device oversight expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Houston's petrochemical throughput and the Trans-Canada pipeline network anchor North American energy sector inspection demand, while cross-border manufacturing corridors sustain testing volumes across automotive and electronics supply chains.
United States
California's semiconductor fabrication cluster generates specialized electromagnetic compatibility testing demand from Intel and TSMC Arizona operations. FDA medical device quality system regulations compel Minnesota and Massachusetts medical technology suppliers into independent certification relationships. Texas and Florida building booms drive concrete strength testing and electrical safety verification for commercial construction projects.
Canada
Quebec's aerospace supply chain sustains premium-positioned inspection relationships for Boeing and Airbus additive manufacturing qualification. Health Canada and PMRA pharmaceutical oversight expands mandatory testing scope for Ontario-based generic drug manufacturers. Alberta oil sands operations require corrosion monitoring and pipeline integrity verification under federal energy regulator mandates.
Mexico
Nuevo León automotive assembly corridors generate incoming materials verification demand from Tennessee and Michigan-based tier-one suppliers. Mexico's national standards body NOM certification requirements facilitate cross-border market access for United States consumer goods exporters. Bajío Region electronics manufacturing clusters deploy environmental stress testing for automotive battery component qualification.
North America Testing Inspection and Certification (TIC) Market Competitive Landscape
On the supply side, the industry is consolidating around digital platform intermediaries that compress procurement cycles and reshape laboratory-to-manufacturer relationships. Three strategic archetypes dominate: diversified multinational conglomerates with heritage specializations, consumer goods-focused testing networks serving retail compliance programs, and electrical safety specialists commanding premium positioning in building technology markets. Dominant competitive moves include portfolio diversification into integrated auditing bundles and geographic expansion through acquisition of regional laboratory networks.
Within the diversified multinational tier, Bureau Veritas and SGS SA exemplify heritage-driven positioning across energy and industrial verticals. Intertek Group plc occupies a position representing consumer goods testing concentration, while UL LLC anchors the electrical safety specialization archetype with deep building technology market penetration.
| Leading Market Players |
|---|
| Bureau Veritas |
| Intertek Group plc |
| SGS SA |
| TÜV SÜD |
| UL LLC |
| DEKRA |
| NSF International |
| Element Materials Technology |
| TÜV Rheinland |
| Others |
Pricing and Supply Chain Analysis
Rare earth refining capacity concentrated in China and domestic lithium processing bottlenecks in the United States directly determine margin capture downstream, with specialized chemical reagent costs compressing profitability for environmental testing laboratories serving EPA PFAS mandates.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates service delivery, with FDA medical device certification and FAA airworthiness validation commanding premium positioning while routine consumer goods testing faces commoditization. Price differentiation hinges on accreditation tier and geographic proximity to California semiconductor clusters or Texas energy corridors. Cost compression in standard-tier environmental testing is intensifying because Walmart and Target supplier qualification systems mandate national laboratory network participation. Mid-tier regional providers exhibit highest price sensitivity, while aerospace and healthcare verticals demonstrate inelastic demand for specialized NDT and sterilization validation services.
Supply Chain Analysis
Contract manufacturing concentration among Foxconn, Jabil, and Flex Ltd. in Mexico's Bajío Region and Nuevo León anchors incoming materials verification demand from Tennessee and Michigan-based automotive tier-one suppliers. Testing equipment draws from precision instrumentation clusters in Germany, Japan, and the United States, while rare earth materials and specialized chemical reagents rest on limited domestic refining capacity. Single-source vulnerability in lithium hexafluorophosphate electrolyte supply creates exposure for battery validation laboratories. Distribution runs through digital platform intermediaries that compress procurement cycles and consolidate laboratory-to-manufacturer relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electromagnetic testing expertise and materials science PhD talent pools are narrowing faster than accredited laboratory expansion, creating persistent capability gaps that favor incumbents with established training pipelines and university research partnerships.
For Market Incumbents: Entrench market position through backward integration into specialized chemical reagent supply and captive calibration equipment manufacturing, reducing input cost volatility from China-dependent rare earth flows. Expand ISO 17025-accredited capacity in Tennessee and Michigan automotive corridors before electric vehicle battery validation demand saturates national laboratory networks. Digital platform intermediaries threaten direct laboratory relationships; counter through proprietary customer portal development with real-time certificate delivery. For New Entrants and Emerging Players: Establish a beachhead in automotive battery thermal runaway testing, where NHTSA safety standards and EPA emissions compliance expand mandatory scope faster than incumbent capacity addition. Target CE marking facilitation for United States exporters to European Union markets, leveraging REACH and RoHS conformity assessment gaps left by consumer goods-focused national networks. Deploy remote sensing and blockchain-based certificate verification as differentiated go-to-market positioning against legacy audit-schedule incumbents. For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap specialists with ISO 13485 medical device certification and established FDA quality system relationships, given recurring surveillance audit revenue durability and brand-dependent trust premiums. Long-term viability favors providers with integrated auditing bundles combining ISO quality management with regulatory compliance verification across healthcare and construction verticals. Watch for FDA-ISO 13485 harmonization implementation as inflection indicator for certification scope expansion and competitive repositioning among healthcare technology suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Acquisition of Specialist Laboratory Networks | Consolidates regional electromagnetic testing capacity serving Intel and TSMC Arizona operations. |
| Integrated Auditing Bundle Development | Combines ISO 9001 frameworks with FDA quality system compliance for Minnesota medical technology clusters. |
| Digital Platform Intermediary Partnership | Secures placement in Walmart and Target pre-approved supplier qualification systems. |
| Remote Sensing Technology Deployment | Collapses document review timelines for FAA airworthiness certification in Washington State aerospace. |
| CE Marking Facilitation Service Launch | Captures intermediary demand from United States exporters facing REACH and RoHS conformity requirements. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, EPA environmental testing method validations, ASTM standards documentation, and SEC 10-K disclosures from accredited laboratory networks. Primary interviews engaged laboratory operations directors, aerospace quality assurance managers, medical device regulatory affairs leads, automotive tier-one supplier procurement officers, and construction project compliance coordinators. Bottom-up service revenue estimates triangulate against top-down regulatory mandate expansion projections.
Forecast inputs span service type segmentation, end-user vertical concentration, and regulatory compliance standard adoption across the projection horizon. Modeled dimensions include testing methodology intensity, certification surveillance frequency, and geographic clustering of semiconductor fabrication and automotive battery production. CAGRs derive from regression analysis against historical accreditation expansion rates and mandatory testing scope enlargement under FDA, FAA, and EPA oversight.
Macroeconomic conditions sit as an overlay; deviation in electric vehicle production targets, aerospace manufacturing output, or federal infrastructure spending would shift the trajectory. Forecasts reflect assumptions regarding regulatory enforcement intensity and cross-border trade volume maintenance. Quarterly review of FDA quality system regulation updates, EPA PFAS method validation timelines, and automotive OEM battery qualification pipeline indicators is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Outsourced Testing Services Market
Testing Services
Urodynamic Testing Market
Testing Services
Testing and Analysis Services Market
Testing Services
Retrovirus Testing Market
Testing Services
Global Endocrine Testing Market
Testing Services
Global Lipid Panel Testing Market
Testing Services
Adenovirus Testing Market
Testing Services
Global Anti Thrombin III Testing Market
Testing Services
Home Care Testing Market
Testing Services
Comprehensive Metabolic Panel (CMP) Testing Market
Testing Services
Nucleic Acid Testing Market
Testing Services
US Bowie Dick Test Pack Market
Testing Services
STD Testing Devices Market
Testing Services
Sickle Cell Anemia Testing and Screening Market
Testing Services
Legionnaire Disease Testing Market
Testing Services
South America Endotoxin and Pyrogen Testing Market