
 Cell Line Authentication and Characterization Tests Market | 2026-2036
Cell Line Authentication and Characterization Tests Market Size, Share, and Industry Trends Forecast 2026-2036
Cell Line Authentication and Characterization Tests Market Outlook
A capital-intensity divergence between integrated platform providers and specialized assay developers is reorganizing competitive dynamics in cell line authentication. Thermo Fisher Scientific leverages its end-to-end instrumentation portfolio to dominate workflow consolidation. Charles River Laboratories anchors its position through captive laboratory services for pharmaceutical clients. Eurofins Scientific competes via geographic density in European contract testing.
Cell line authentication and characterization tests encompass molecular methodologies that verify identity, purity, and functional attributes of biological cultures used in research and manufacturing. STR analysis constitutes the dominant methodology, employing polymorphic short tandem repeat loci to generate unique genetic fingerprints with discrimination power exceeding one in ten billion. Pharmaceutical research applications command the largest revenue share due to mandatory submission requirements for investigational new drug filings. Kit-based testing represents the fastest-expanding delivery mode as laboratories seek standardized reagent systems that reduce protocol variability and accelerate turnaround.
FDA guidelines for biologics development and EMA cell line characterization requirements create binding demand for documented authentication protocols across submission pathways. ISO 17025 accreditation and WHO recommendations on cell line quality further tighten compliance thresholds for commercial and academic laboratories. Stakeholders must evaluate whether to internalize testing capabilities or rely on outsourced providers as regulatory stringency escalates and sample volumes expand.
Market Dynamics
Workflow consolidation around integrated STR-to-sequencing platforms is compressing vendor margins while elevating switching costs for pharmaceutical laboratories. Thermo Fisher's end-to-end instrumentation bundling and Charles River's captive service models exemplify this consolidation pressure.
Growth Catalysts
- FDA Biologics Guidance:Mandatory cell line verification for investigational new drug submissions binds pharmaceutical sponsors to documented authentication protocols, creating recurring demand for STR analysis and karyotyping services.
- Biobank Accreditation Standards:ISO 20387 requirements for biological resource centers mandate genetic identity confirmation for deposited lines, expanding authentication testing into academic and government repository networks.
- Gene Therapy Manufacturing:Viral vector production facilities require clonal derivation verification and copy number assessment, extending characterization requirements beyond traditional small-molecule cell substrates.
Market Restraints
- Reference Standard Fragmentation:Lack of harmonized STR allele databases across Japanese, Chinese, and European jurisdictions forces duplicate testing for multinational studies, inflating compliance costs.
- Specialized Reagent Supply Concentration:Fluorescently labeled primer sets for multiplex STR analysis derive from limited German and US chemical synthesis suppliers, exposing laboratories to batch-to-batch variability and extended lead times.
- Next-Generation Sequencing Substitution:Whole-genome sequencing for identity verification offers superior resolution but requires capital-intensive instrumentation and bioinformatics infrastructure that mid-sized contract labs cannot justify.
Strategic Opportunities
- Indian Contract Research Expansion:CDSCO's alignment with ICH Q5D guidelines for biologics registration creates authentication demand among Bangalore and Hyderabad-based manufacturing service providers serving export markets.
- Cell Therapy Autologous Workflows:Patient-derived starting material requires identity confirmation at multiple manufacturing stages, opening recurring testing slots for regional laboratories adjacent to clinical trial sites.
- Blockchain Documentation Systems:Immutable chain-of-custody records for cell line provenance address FDA and EMA audit trail requirements while differentiating service providers in competitive bidding for pharmaceutical contracts.
Industry Challenges
- Bioinformatics Talent Scarcity:Interpretation of complex karyotype abnormalities and copy number variation profiles requires specialized cytogeneticists, with training pipelines failing to match expansion of cell therapy manufacturing capacity.
- Multi-Site Harmonization:Pharmaceutical sponsors operating across US, German, and Singaporean facilities struggle to enforce consistent STR calling thresholds and contamination alert protocols, risking regulatory inspection findings.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cell Line Authentication and Characterization Tests Market |
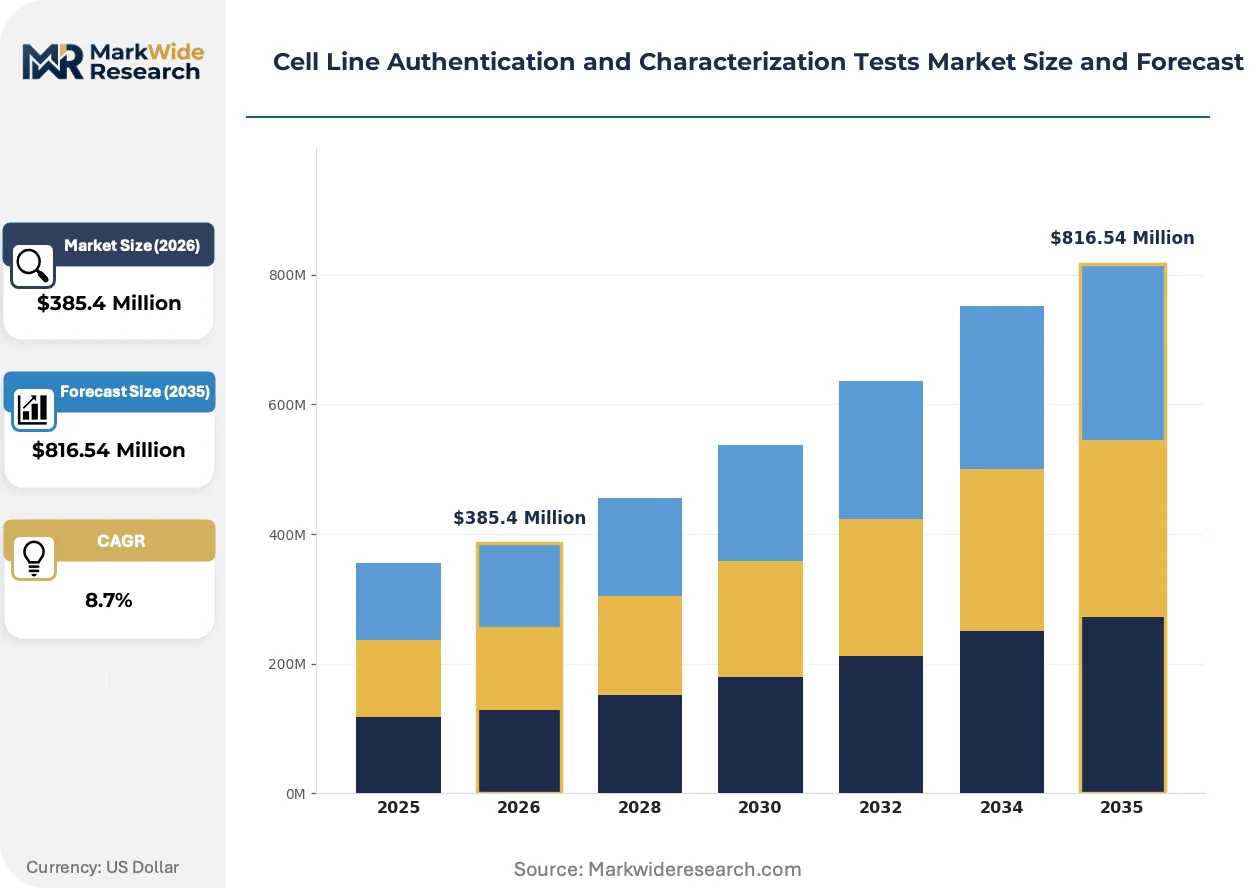
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $816.54 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Test Type: DNA Sequencing, STR Analysis, RNA Profiling, SNP Analysis Application: Biobanks, Pharmaceutical Research, Academic Research, Diagnostics End User: Biotechnology Companies, Research Institutions, Academic Laboratories, Hospitals Delivery Mode: In-House Testing, Outsourced Testing, Kit-Based Testing, Online Services |
| Companies Covered | Promega Corporation, Bio-Rad Laboratories, Thermo Fisher Scientific, Laboratory Corporation of America Holdings, Agilent Technologies, Merck KGaA, Eurofins Scientific, ATCC, Charles River Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cell Line Authentication and Characterization Tests Market Strategic Shifts
Digital authentication workflows and automated sample tracking are compressing turnaround times while elevating data integrity standards. These shifts favor laboratories with integrated laboratory information management systems and cloud-based reporting infrastructure.
SNP-based identity panels are displacing traditional STR analysis in gene therapy applications. These single-nucleotide polymorphism assays offer enhanced stability for degraded DNA samples and compatibility with massively parallel sequencing platforms. Viral vector manufacturers in Massachusetts and North Carolina are adopting SNP workflows for rapid identity confirmation during shortened production campaigns. This displacement is compressing demand for capillary electrophoresis instrumentation while expanding bioinformatics service contracts.
EMA's revised cell line characterization requirements for advanced therapy medicinal products now mandate whole-exome sequencing for genetic stability assessment. This policy shift elevates documentation burdens for European biologics sponsors and forces contract testing organizations to acquire sequencing capacity or partner with specialized genomics providers. German and Swiss pharmaceutical manufacturers are responding by consolidating testing relationships with full-service laboratories capable of integrated STR, karyotype, and sequencing deliverables.
Consolidated vendor relationships are displacing fragmented multi-supplier procurement in large pharmaceutical quality control departments. Procurement teams now favor single-source contracts covering reagents, instrumentation, and validation support to reduce audit complexity and standardize data formats. This concentration is most visible among top-twenty biologics sponsors with internal cell bank facilities in California, Massachusetts, and Basel.
Cell Line Authentication and Characterization Tests Market Segmentation
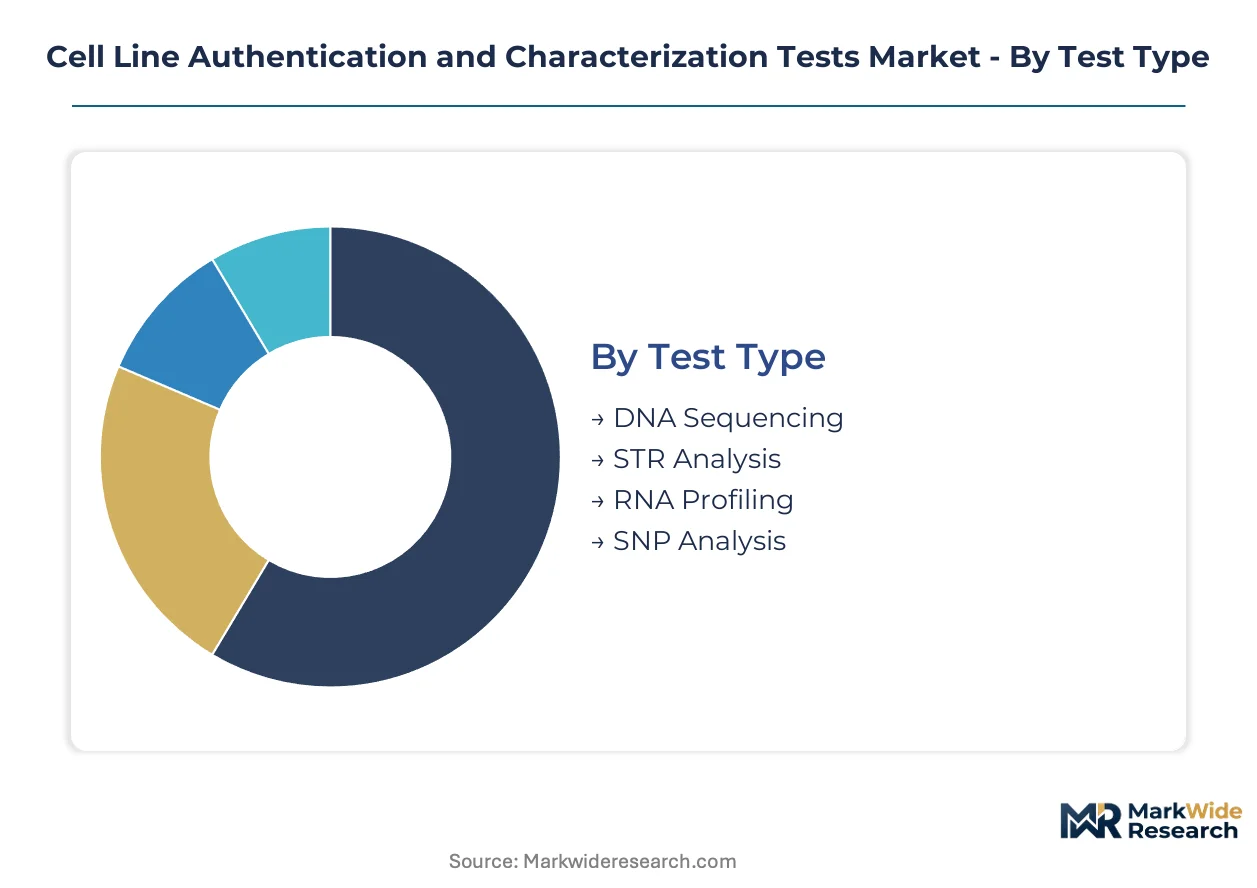
Segmentation in cell line authentication reveals how substitution pressures and regulatory mandates reshape purchasing patterns across test methodologies and service delivery models. Laboratories now reconfigure procurement around integrated platforms that compress turnaround times while satisfying FDA and EMA documentation requirements.
Test Type:
SNP analysis and whole-genome sequencing are displacing established STR workflows in gene therapy manufacturing, forcing vendors to defend installed bases of capillary electrophoresis instrumentation.
- STR Analysis:Short tandem repeat profiling generates unique genetic fingerprints through polymorphic loci discrimination. Pharmaceutical quality control departments in Massachusetts and Basel rely on STR for mandatory IND submission documentation, though SNP panels are eroding share in viral vector applications.
- SNP Analysis:Single-nucleotide polymorphism assays offer superior stability for degraded DNA samples and seamless integration with massively parallel sequencing platforms. North Carolina viral vector facilities adopt SNP workflows for rapid identity confirmation during accelerated production campaigns.
- DNA Sequencing:Whole-genome and whole-exome methods provide comprehensive genetic stability assessment for advanced therapy medicinal products under EMA revised guidelines.
- RNA Profiling:Transcriptomic characterization verifies functional attributes and expression stability in engineered cell lines for biologics manufacturing.
STR analysis anchors the volume base while SNP analysis gains share at the steepest rate.
Application:
Cost tier differentiation separates high-throughput pharmaceutical operations from resource-constrained academic repositories, with biobank accreditation standards forcing uniform compliance investments across funding levels.
- Pharmaceutical Research:Investigational new drug filings mandate documented cell line verification through STR or sequencing protocols. Sponsors in California and Basel internalize testing capabilities to protect intellectual property and compress submission timelines.
- Biobanks:ISO 20387 requirements for biological resource centers mandate genetic identity confirmation for deposited lines. European repositories in Germany and Switzerland expand authentication capacity to maintain accreditation status.
- Academic Research:University laboratories face funding constraints that favor kit-based testing and shared core facility access over dedicated instrumentation investments.
- Diagnostics:Clinical reference laboratories integrate cell line authentication into quality control workflows for companion diagnostic development and validation.
Pharmaceutical research commands the premium pricing tier while biobanks drive standardization requirements across the value chain.
End User:
Customer type fragmentation creates distinct procurement patterns, with biotechnology companies prioritizing speed and research institutions emphasizing cost recovery and training accessibility.
- Biotechnology Companies:Venture-backed cell therapy developers in Massachusetts and the San Francisco Bay Area require rapid turnaround for clonal derivation verification during abbreviated manufacturing campaigns.
- Research Institutions:National laboratory networks negotiate volume contracts with full-service providers capable of integrated STR, karyotype, and sequencing deliverables.
- Academic Laboratories:University core facilities balance equipment utilization rates against per-sample pricing sensitivity through shared access models.
- Hospitals:Clinical cell therapy programs at academic medical centers require identity confirmation at multiple manufacturing stages for patient-derived starting material.
Biotechnology companies generate the highest per-account revenue while hospitals represent the most complex contracting environment.
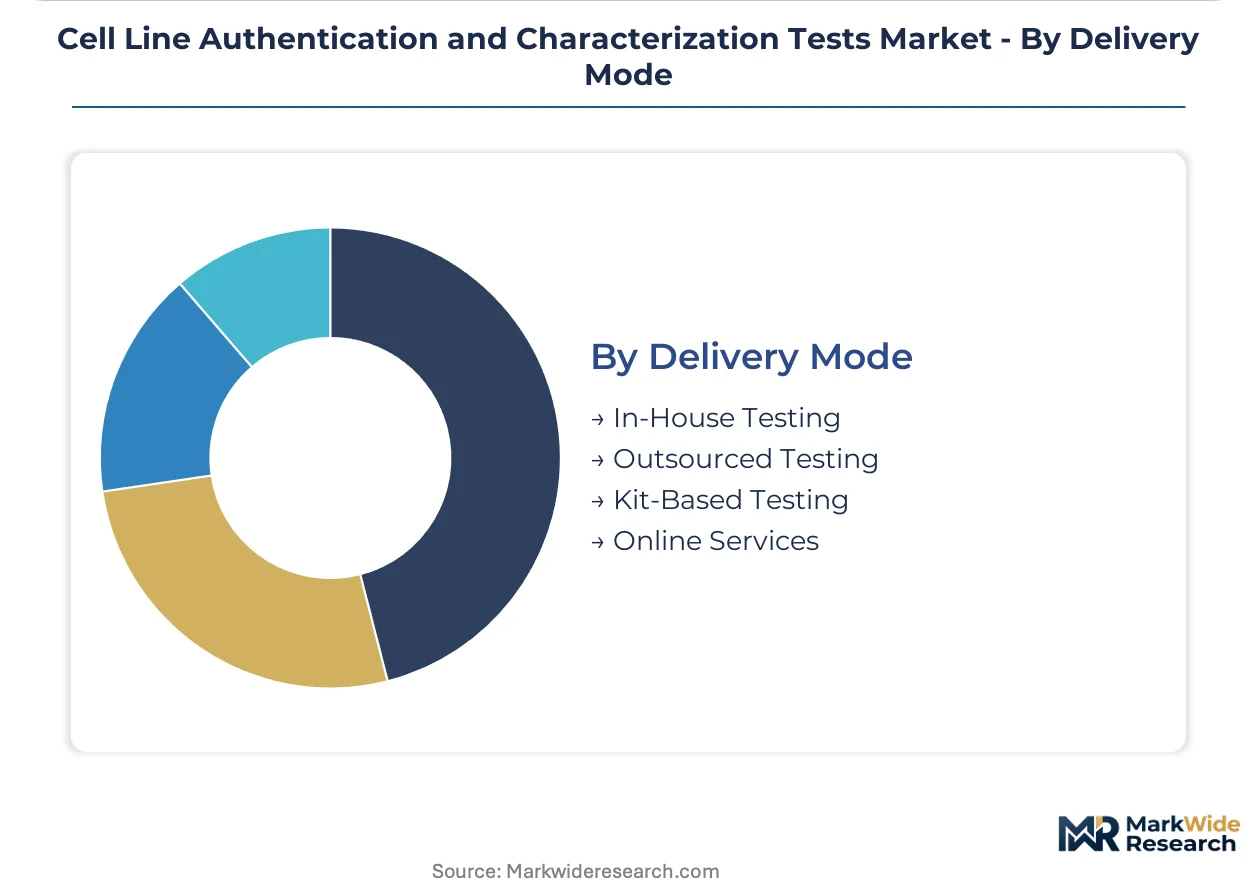
Delivery Mode:
Supply concentration among integrated platform vendors and specialized assay developers reorganizes how laboratories access authentication capabilities.
- Kit-Based Testing:Standardized reagent systems reduce protocol variability and accelerate turnaround for mid-sized contract laboratories. German and US chemical synthesis suppliers control fluorescently labeled primer sets for multiplex STR analysis, exposing buyers to batch-to-batch variability risks.
- Outsourced Testing:Full-service laboratories in Germany and Switzerland capture European biologics sponsor relationships through integrated STR-to-sequencing workflows and blockchain documentation systems.
- In-House Testing:Top-twenty biologics sponsors with internal cell bank facilities consolidate vendor relationships to reduce audit complexity and standardize data formats.
- Online Services:Cloud-based reporting infrastructure and automated sample tracking compress turnaround times for distributed research networks.
Outsourced testing dominates European pharmaceutical procurement while kit-based systems expand most quickly in mid-sized North American laboratories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Authentication testing intensity varies sharply by geography. German and Swiss pharmaceutical manufacturers favor comprehensive sequencing bundles for EMA submissions, while United States sponsors prioritize rapid STR turnaround for FDA investigational new drug filings. Indian contract research organizations adopt kit-based workflows to serve export markets under CDSCO-aligned ICH Q5D standards.
United States
Massachusetts and North Carolina viral vector facilities drive SNP panel adoption for accelerated production campaigns. FDA mandates for biologics development bind sponsors to documented authentication protocols. California and Greater Boston biotech clusters internalize testing capabilities to compress submission timelines and protect intellectual property.
Germany
Baden-Württemberg and Bavaria pharmaceutical manufacturers consolidate testing relationships with full-service laboratories. EMA revised guidelines for advanced therapy medicinal products mandate whole-exome sequencing for genetic stability assessment. German chemical synthesis suppliers control fluorescently labeled primer sets for multiplex STR analysis, creating supply concentration risks for European laboratories.
Switzerland
Basel-based biologics sponsors demand integrated STR-to-sequencing deliverables from contract testing organizations. Swissmedic requirements align with EMA standards for cell line characterization in advanced therapy submissions. Zurich and Geneva service providers invest in blockchain documentation systems to differentiate in competitive pharmaceutical bidding.
India
Bangalore and Hyderabad manufacturing service providers expand authentication capacity to serve export markets. CDSCO alignment with ICH Q5D guidelines for biologics registration creates mandatory testing demand among contract research organizations. Indian laboratories favor kit-based systems to reduce protocol variability and accelerate turnaround for multinational studies.
United Kingdom
London and Cambridge biotech clusters require rapid clonal derivation verification for cell therapy manufacturing. MHRA post-Brexit regulatory frameworks maintain EMA-equivalent standards for cell line documentation. Oxford and Manchester academic repositories expand authentication capacity to meet ISO 20387 accreditation requirements for biological resource centers.
Cell Line Authentication and Characterization Tests Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in cell line authentication. Thermo Fisher Scientific leverages end-to-end instrumentation bundling to dominate workflow consolidation. Charles River Laboratories anchors its position through captive laboratory services for pharmaceutical clients. Eurofins Scientific competes via geographic density in European contract testing. Strategic moves concentrate on M&A for sequencing capacity and partnerships for blockchain documentation systems.
Within the integrated platform tier, Thermo Fisher Scientific, Charles River Laboratories, and Eurofins Scientific exemplify divergent competitive approaches. Thermo Fisher represents the instrumentation bundling archetype through its end-to-end portfolio dominance. Charles River occupies a position as the captive service model specialist for pharmaceutical quality control departments. Eurofins sits within the geographic density archetype, leveraging European laboratory networks to capture biologics sponsor relationships. These three anchors illustrate how capital-intensity divergence between integrated platform providers and specialized assay developers reorganizes procurement patterns across pharmaceutical, biotechnology, and academic end users.
| Leading Market Players |
|---|
| Promega Corporation |
| Bio-Rad Laboratories |
| Thermo Fisher Scientific |
| Laboratory Corporation of America Holdings |
| Agilent Technologies |
| Merck KGaA |
| Eurofins Scientific |
| ATCC |
| Charles River Laboratories |
| Others |
Value Chain & Pricing Dynamics
SNP panel substitution for traditional STR workflows simultaneously redraws supply geography toward sequencing reagent manufacturers and compresses pricing power for capillary electrophoresis incumbents. German and US chemical synthesis suppliers now capture premium positioning for fluorescently labeled primer sets, while mid-sized contract laboratories face margin pressure from batch-to-batch variability in multiplex STR analysis inputs.
Pricing Analysis
Long-term offtake contracts dominate procurement relationships between top-twenty biologics sponsors and full-service testing laboratories, insulating premium-tier providers from spot-market volatility. Price differentiation hinges on ISO 17025 certification tier and volume scale, with accredited European laboratories commanding substantial premiums over uncertified competitors. Pricing pressure stems from kit-based testing commoditization in mid-sized North American markets, eroding per-sample margins. Academic laboratories exhibit highest price sensitivity, favoring shared core facility access over dedicated instrumentation investments.
Supply Chain Analysis
Fluorescently labeled primer synthesis capacity concentrates in Germany and the United States, creating single-source vulnerability for European and North American laboratories dependent on multiplex STR reagents. Raw material dependencies span oligonucleotide synthesis chemicals, polymerase enzymes, and capillary electrophoresis consumables. Supply chain risk centers on regulatory restriction exposure from EMA and FDA documentation requirements that disqualify non-validated reagent batches. Distribution runs through direct vendor relationships with large pharmaceutical quality control departments and regional distributor networks serving academic repositories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Interpretation of complex karyotype abnormalities and copy number variation profiles demands specialized cytogeneticists whose training pipelines lag cell therapy manufacturing expansion, concentrating value capture among laboratories with captive expertise development programs.
For Market Incumbents: Secure blockchain documentation capabilities to differentiate in competitive pharmaceutical bidding and defend against emerging full-service laboratories offering integrated STR-to-sequencing workflows. Deepen vertical integration into sequencing capacity or partner with specialized genomics providers to address EMA revised guidelines for advanced therapy medicinal products. Prioritize certification investment in ISO 20387 compliance for biobank accreditation standards. For New Entrants and Emerging Players: Regional bioinformatics service gaps adjacent to Massachusetts and North Carolina viral vector facilities present white-space targets where incumbents under-serve accelerated production campaigns. Indian contract research organizations in Bangalore and Hyderabad offer the most penetrable geography, with CDSCO alignment to ICH Q5D guidelines creating mandatory testing demand among export-oriented manufacturing service providers. Pursue kit-based testing partnerships as the go-to-market angle to reduce capital requirements. For Investors and Strategic Acquirers: EMA's revised cell line characterization requirements for advanced therapy medicinal products reshapes the acquisition landscape toward laboratories with integrated sequencing deliverables and cloud-based reporting infrastructure. Target acquisition archetypes include mid-sized European contract testing organizations with established pharmaceutical sponsor relationships and underdeveloped sequencing capacity. Watch for CDSCO enforcement consistency as the signal indicating inflection in Indian authentication demand.| Strategic Initiative | Industry Significance |
|---|---|
| Sequencing Capacity Acquisition | EMA whole-exome sequencing mandates force laboratories to acquire NGS infrastructure or partner with genomics specialists. |
| Blockchain Documentation Integration | Immutable chain-of-custody records address FDA and EMA audit trail requirements while differentiating service providers. |
| Kit-Based Testing Standardization | Standardized reagent systems reduce protocol variability for mid-sized contract laboratories serving multinational studies. |
| Regional Laboratory Expansion | Geographic density in European contract testing captures biologics sponsor relationships through integrated workflow bundling. |
| Bioinformatics Talent Development | Specialized cytogeneticist training programs address capability scarcity constraining cell therapy manufacturing quality control. |
Study Parameters
The analysis maps STR analysis, SNP profiling, and whole-genome sequencing sub-sectors, each validated through quality control directors at pharmaceutical sponsors, regulatory affairs leads at contract testing organizations, and procurement managers at academic biobanks. Primary interviews with laboratory directors, cytogeneticists, and reagent supplier technical specialists combined with secondary validation against FDA guidance documents, EMA submission requirements, ISO accreditation databases, and WHO cell line quality recommendations. Bottom-up testing volume estimates and top-down market sizing triangulate through cross-referencing against instrument installation records and reagent shipment data.
Consistency checks validated volume and value outputs against external benchmarks including regulatory filing volumes, biobank accreditation expansion rates, and cell therapy manufacturing facility buildouts across the analysis window. Segmentation dimensions modeled encompass test methodology, application area, end-user type, and delivery mode, with regional regulatory cluster as an additional cross-cutting dimension. CAGRs derived from regression analysis of historical adoption curves and forward projection of regulatory mandate enforcement intensity, incorporating gene therapy manufacturing capacity expansion and biobank ISO 20387 compliance timelines as industry-specific inputs.
Underlying assumptions cover sustained FDA and EMA enforcement of cell line verification requirements, with deviation risk concentrated in sequencing technology substitution rates and harmonization of STR allele databases across jurisdictions. Forecasts reflect these assumptions with explicit sensitivity ranges for regulatory timeline acceleration and reagent supply disruption scenarios. Revision becomes warranted when CDSCO enforcement consistency or EMA advanced therapy guidance implementation crosses thresholds that materially alter authentication testing intensity per biologics submission.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Global Extractables and Leachables Testing Services Market
Testing Services
Esoteric Testing Market
Testing Services
Global at-Home Drug of Abuse (DOA) Testing Market
Testing Services
US Pharmaceutical Analytical Testing Outsourcing Market
Testing Services
Carbapenem-Resistant Enterobacteriaceae Testing Market
Testing Services
Global Enzyme Linked Immunosorbent Assay (ELISA) Testing Market
Testing Services
South America Endotoxin and Pyrogen Testing Market
Testing Services
Home Care Testing Market
Testing Services
Activated Partial Thromboplastin Test Market
Testing Services
Global IVD Regulatory Affairs Outsourcing Market
Testing Services
Global Medical Device Testing and Certification Market
Testing Services
Global Direct to Consumer Laboratory Testing Market
Testing Services
Drug Tester Market
Testing Services
Apolipoprotein Testing Market
Testing Services
Global Enteric Disease Testing Market
Testing Services
Global Metabolic Testing Market