
 Cholesterol Test Market | 2026-2036
Cholesterol Test Market Size, Share, and Industry Trends Forecast 2026-2036
Cholesterol Test Market Analysis
Home care end user demand is broadening faster than hospital-based testing as consumers prioritize convenience and remote health management. Abbott Laboratories leverages its point-of-care device portfolio to capture clinic and home settings. Siemens Healthineers anchors its position through integrated lab automation systems that serve high-throughput diagnostic laboratories.
A cholesterol test measures lipid fractions in serum or plasma to assess cardiovascular risk, typically quantifying LDL, HDL, triglycerides, and total cholesterol through enzymatic or colorimetric reactions with defined analytical sensitivity thresholds. The primary commercial purpose is enabling clinicians and patients to initiate or modify statin therapy and lifestyle interventions based on quantified atherosclerotic risk. Enzymatic assays occupy the largest installed base due to cost efficiency and standardization across clinical chemistry platforms, while NMR spectroscopy generates premium-margin demand from specialized lipidology practices seeking particle subfraction analysis. Point-of-care testing delivery mode is expanding fastest in retail pharmacy and employer clinic channels where immediate results drive compliance.
The FDA governs cholesterol test kits and analyzers through premarket notification and quality system regulation pathways that determine market entry timelines and clinical claim scope. Clinical Laboratory Improvement Amendments set proficiency standards that shape whether testing consolidates into centralized labs or disperses to physician office laboratories. Stakeholders must monitor evolving CMS reimbursement determinations for home-based lipid monitoring as these decisions will reallocate volume between laboratory and consumer channels.
Market Dynamics
Home-based lipid monitoring is compressing the traditional laboratory channel as FDA clearance pathways for over-the-counter devices enable direct consumer access without clinician intermediaries.
Growth Catalysts
- Preventive cardiology mandates:Employer wellness programs in the United States now require biometric screenings including lipid panels, institutionalizing recurring test demand.
- CLIA-waived point-of-care expansion:Clinical Laboratory Improvement Amendments proficiency standards for moderate-complexity testing allow physician office laboratories to deploy enzymatic analyzers.
- NMR spectroscopy adoption:Specialized lipidology practices seeking particle subfraction analysis drive premium-margin demand beyond standard lipid panels.
Market Restraints
- Reagent cost volatility:Enzymatic assay consumables face input pressure from specialty chemical supply concentration in Germany and Switzerland.
- Centralized lab consolidation:Health system mergers in the United States concentrate purchasing power among integrated delivery networks, compressing margins for independent device vendors.
- Substitution by non-invasive risk scores:Polygenic risk calculators and coronary artery calcium scoring displace some diagnostic lipid testing in low-risk stratification protocols.
Strategic Opportunities
- Retail pharmacy channel penetration:MinuteClinic and similar walk-in formats in the United States create new deployment sites for rapid-result lipid analyzers.
- Remote patient monitoring integration:Bluetooth-enabled home devices connecting to electronic health records enable longitudinal tracking outside traditional care settings.
- Indian preventive health expansion:Corporate health check-up mandates in tier-1 cities drive demand for affordable point-of-care lipid testing in clinic networks.
Industry Challenges
- Interoperability with legacy EHR systems:Home device data formats often fail to integrate with hospital information systems, requiring middleware development.
- CLIA personnel certification timelines:Laboratory director qualifications for physician office laboratories create hiring bottlenecks in rural geographies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cholesterol Test Market |
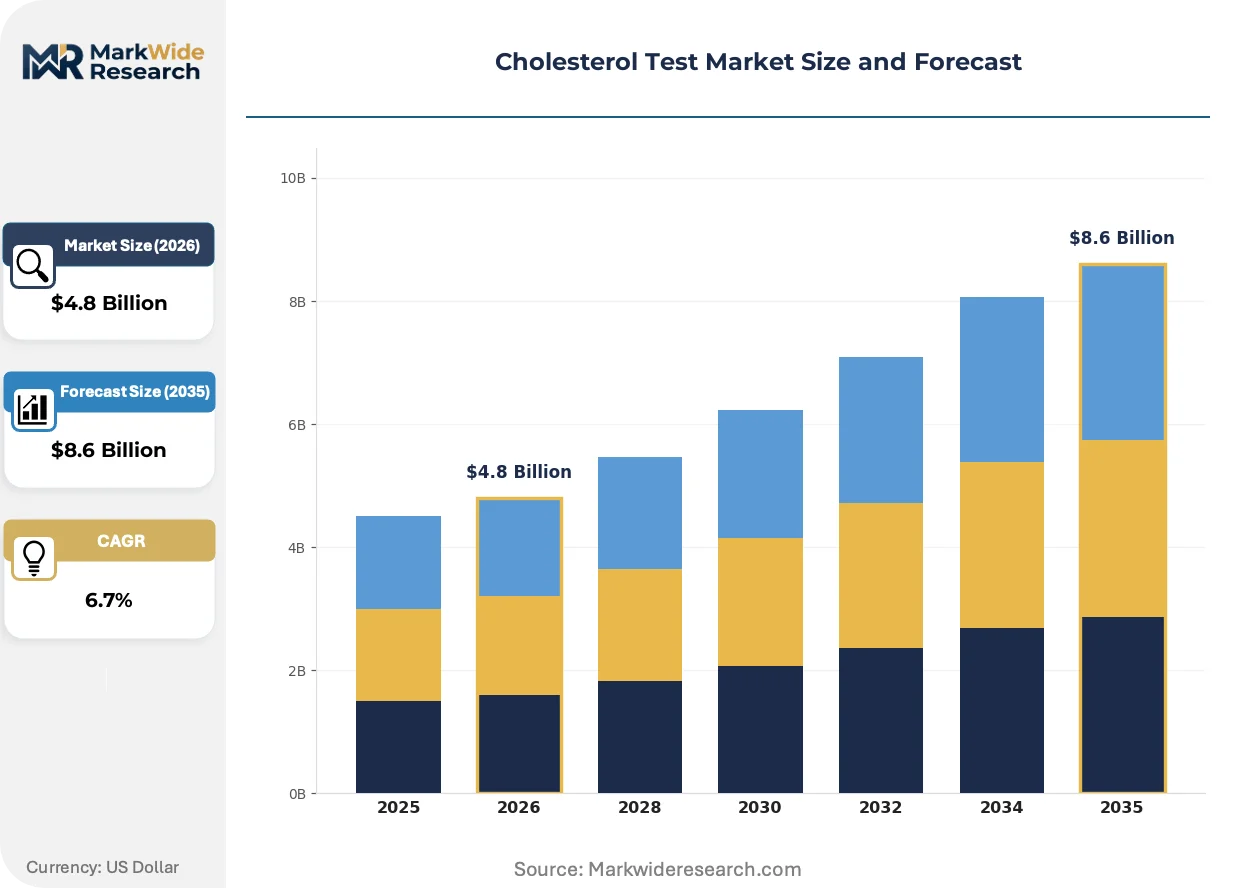
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LDL Tests, HDL Tests, Triglyceride Tests, Total Cholesterol Tests Technology: Enzymatic Assays, Colorimetric Assays, Immunoassays, NMR Spectroscopy End User: Hospitals, Clinics, Home Care, Diagnostic Laboratories Delivery Mode: Tests Kits, Point-of-Care Testing, Lab Testing, Home Testing |
| Companies Covered | Thermo Fisher Scientific, Quest Diagnostics, Abbott Laboratories, Danaher Corporation, Laboratory Corporation of America Holdings, Roche Diagnostics, Randox Laboratories, Bio-Rad Laboratories, Siemens Healthineers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cholesterol Test Market Emerging Trajectories
Digital biomarker integration and decentralized testing infrastructure are redistributing cholesterol monitoring from centralized laboratories to consumer-controlled environments.
Microfluidic cartridge technology is rewriting how lipid panels are processed. These disposable test strips integrate sample preparation, reagent reaction, and optical detection into single-use formats. Retail pharmacy chains and employer clinic operators are adopting microfluidic platforms at accelerated procurement cycles. The technology is rewriting capital deployment patterns by eliminating analyzer maintenance and calibrant inventory management.
The FDA's over-the-counter clearance pathway for dual-analyte lipid and glucose devices is reshaping market access models. This regulatory channel permits direct-to-consumer marketing without prescription requirements. Home care end users and telehealth platforms are responding by building subscription-based monitoring programs around these cleared devices.
Consumer-directed health spending is fragmenting the traditional laboratory channel. Patients now purchase lipid tests through direct-pay retail and employer-sponsored screening events rather than physician-ordered laboratory referrals. United States metropolitan markets exhibit the most pronounced channel shift, with pharmacy-based testing volumes growing fastest in suburban corridors.
Cholesterol Test Market Segmentation
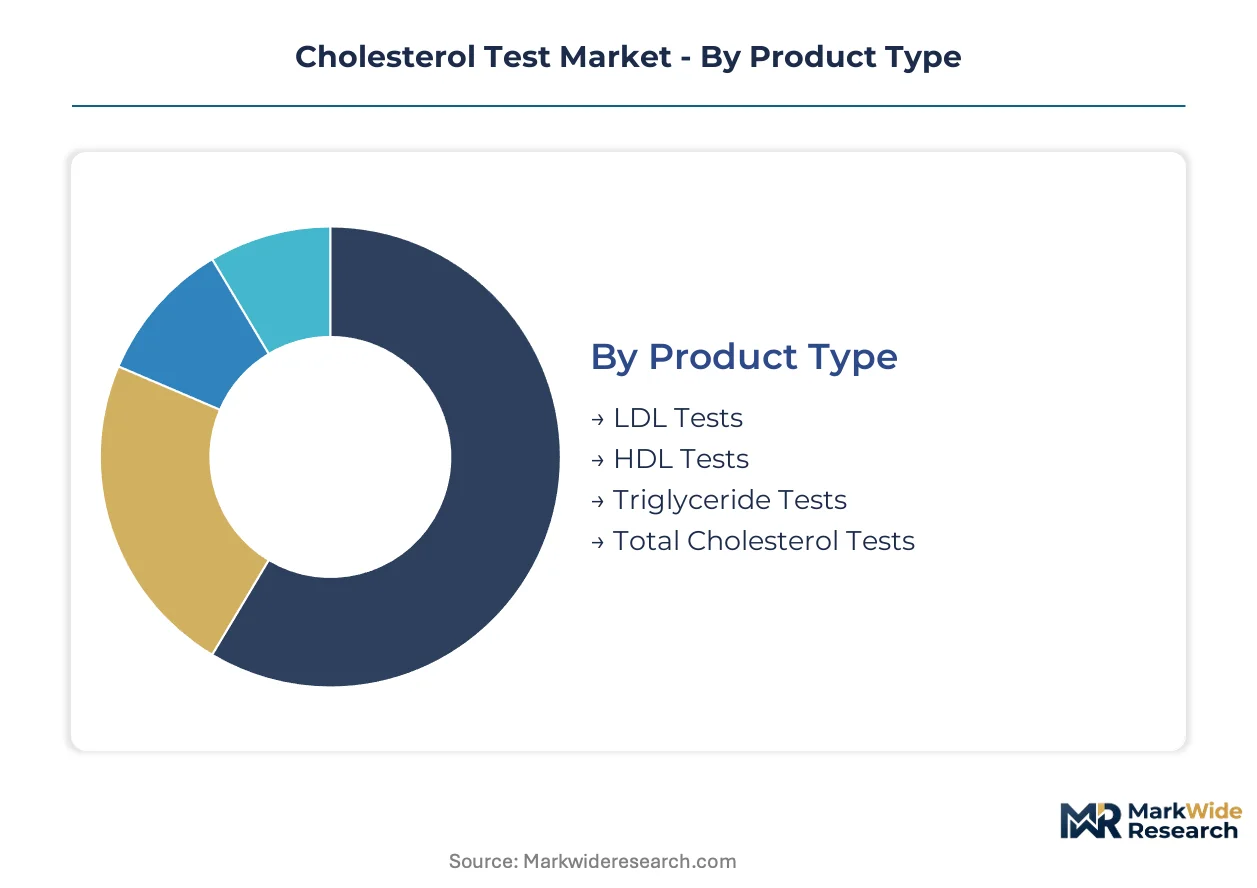
Cholesterol testing segments fragment across technology sophistication, care setting, and consumer access models. Each dimension carries distinct margin profiles and regulatory pathways that reshape competitive positioning.
Product Type:
Volume concentrates in standard lipid panels while premium margins accrue to specialized fraction tests.
- LDL Tests:Quantifies low-density lipoprotein cholesterol through direct measurement or Friedewald calculation. Hospital laboratories in the United States drive demand as statin therapy protocols mandate precise LDL targets for cardiovascular risk management.
- HDL Tests:Measures high-density lipoprotein cholesterol as a protective biomarker. Preventive cardiology programs and employer wellness mandates in suburban United States corridors expand testing frequency beyond acute care settings.
- Triglyceride Tests:Assesses circulating triglyceride levels alongside fasting glucose for metabolic syndrome screening.
- Total Cholesterol Tests:Provides aggregate lipid quantification as the lowest-cost entry point for mass screening programs.
Today's leader: LDL Tests. Tomorrow's challenger: HDL Tests.
Technology:
Cost tiers separate commodity enzymatic platforms from premium spectroscopic instrumentation.
- Enzymatic Assays:Catalytic reactions with cholesterol esterase and oxidase enzymes generate colorimetric readouts on automated chemistry analyzers. Clinical laboratories across Germany and Switzerland deploy these systems at scale due to reagent standardization and CLIA-waived protocol compatibility.
- NMR Spectroscopy:Nuclear magnetic resonance platforms quantify lipoprotein particle subfractions including small dense LDL. Specialized lipidology practices in the United States and academic medical centers absorb premium pricing for advanced atherosclerotic risk stratification.
- Colorimetric Assays:Simplified chromogenic reactions enable low-cost point-of-care deployment in resource-limited settings.
- Immunoassays:Antibody-based detection provides alternative specificity profiles for non-fasting samples.
Enzymatic Assays anchor installed base economics. NMR Spectroscopy climbs the fastest as precision medicine protocols advance.
End User:
Patient control over testing location is redistributing volume from institutional to consumer-directed channels.
- Home Care:Direct-to-consumer devices with Bluetooth connectivity enable longitudinal monitoring outside clinical supervision. FDA over-the-counter clearance pathways for dual-analyte lipid and glucose devices accelerate adoption in United States metropolitan markets.
- Hospitals:Emergency departments and inpatient units require rapid turnaround for acute cardiovascular event protocols. Integrated delivery networks concentrate purchasing power across United States health system mergers.
- Clinics:Physician office laboratories leverage CLIA-waived moderate-complexity certifications for same-visit results.
- Diagnostic Laboratories:Centralized high-throughput facilities process reference-grade panels with comprehensive quality controls.
Diagnostic Laboratories process peak volume today. Home Care gains share fastest as remote patient monitoring platforms mature.
Delivery Mode:
Supply concentration in reagent manufacturing shapes channel economics and geographic availability.
- Point-of-Care Testing:Portable analyzers deliver results within minutes at retail pharmacies and employer clinics. MinuteClinic formats in United States suburban corridors deploy rapid-result lipid analyzers to capture walk-in demand.
- Home Testing:Microfluidic cartridge technology integrates sample preparation and optical detection into disposable strips. Telehealth platforms build subscription programs around FDA-cleared over-the-counter devices.
- Test Kits:Mail-in specimen collection enables laboratory-grade analysis without clinical visits.
- Lab Testing:Traditional venipuncture and centralized processing maintains gold-standard accuracy for complex cases.
Lab Testing retains accuracy leadership. Point-of-Care Testing expands most quickly through retail pharmacy penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redistributing cholesterol test manufacturing capacity toward jurisdictions with streamlined device approval pathways and lower cost-of-compliance structures. Production migration concentrates where FDA predicate device databases and EU MDR notified body capacity create divergent market entry timelines.
United States
Employer wellness mandates and preventive cardiology protocols institutionalize recurring lipid panel demand across suburban corridors. FDA over-the-counter clearance pathways for dual-analyte devices accelerate direct-to-consumer channel development. The Dallas-Fort Worth metroplex anchors point-of-care device distribution networks serving retail pharmacy chains.
Germany
Specialty chemical supply concentration for enzymatic reagents sustains high-throughput analyzer manufacturing clusters. EMA quality system regulations and IVDR transition timelines shape export-oriented production strategies. The Rhine-Main region around Frankfurt hosts reagent standardization facilities serving clinical chemistry platform vendors.
Switzerland
Precision diagnostic instrument engineering capabilities support premium NMR spectroscopy platform development. Swissmedic device regulations and ISO 13485 certification infrastructure attract specialized lipidology technology developers. The Basel-Zurich corridor concentrates particle subfraction analysis R&D operations for academic medical center partnerships.
India
Corporate health check-up mandates in tier-1 cities drive affordable point-of-care lipid testing demand across clinic networks. CDSCO medical device rules and PLI scheme incentives reshape domestic manufacturing capacity for enzymatic assay platforms. Bangalore and Hyderabad anchor diagnostic device engineering operations serving Southeast Asian export markets.
China
Hospital laboratory automation upgrades and health system consolidation expand high-throughput analyzer procurement volumes. NMPA Class II device registration pathways and dual carbon goals influence reagent production facility location decisions. The Yangtze River Delta around Shanghai concentrates clinical chemistry platform assembly operations for domestic and Belt-and-Road distribution.
Cholesterol Test Market Vendor Landscape
Strategic partnerships dominate the current landscape as device vendors seek reagent supply security and distribution channel access. The vendor base concentrates around integrated diagnostic conglomerates with dual capabilities in analyzer hardware and consumable chemistry. Three archetypes define competitive positioning: diversified life science conglomerates with clinical chemistry heritage, specialized point-of-care device developers, and reference laboratory operators with captive testing demand. M&A activity and technology licensing agreements represent the primary competitive moves, with particular emphasis on microfluidic cartridge IP and CLIA-waived assay portfolios.
Among diversified diagnostic conglomerates, Abbott Laboratories and Roche Diagnostics exemplify the integrated hardware-reagent archetype that anchors hospital laboratory relationships. Siemens Healthineers occupies a position within the automation-focused tier, leveraging installed base economics in high-throughput settings. Quest Diagnostics represents the reference laboratory operator model, converting captive testing volume into device specification influence.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Quest Diagnostics |
| Abbott Laboratories |
| Danaher Corporation |
| Laboratory Corporation of America Holdings |
| Roche Diagnostics |
| Randox Laboratories |
| Bio-Rad Laboratories |
| Siemens Healthineers |
| Others |
Supply Flow & Price Mechanics
Backward integration into enzymatic reagent manufacturing anchors both supply security and pricing power for diagnostic conglomerates operating in the United States and Germany. Captive production of cholesterol esterase and oxidase enzymes insulates vendors from specialty chemical supply volatility while enabling premium positioning against non-integrated competitors.
Pricing Analysis
Distributor margin compression in the point-of-care channel is reshaping how device vendors capture value from lipid panel sales. Pricing stratifies across FDA-cleared premium tiers, CLIA-waived moderate-complexity certifications, and economy-grade colorimetric platforms without regulatory claims. Cost compression in the home testing segment intensifies as microfluidic cartridge producers compete for telehealth platform partnerships. Employer wellness programs exhibit lowest price sensitivity due to mandated biometric screening budgets, while individual consumers purchasing direct-to-consumer devices face highest elasticity.
Supply Chain Analysis
ISO 13485 certification and FDA quality system regulation gating concentrate viable manufacturing capacity among established diagnostic hubs in Germany, Switzerland, and the United States. Enzymatic assay production draws from specialty chemical feedstocks concentrated in the Rhine-Main region, while NMR spectroscopy instrumentation sources precision magnets and cryogenic cooling systems from Swiss engineering clusters. Single-source vulnerability in cholesterol esterase enzyme supply creates exposure to batch contamination or facility shutdown events. Distribution runs through integrated delivery network procurement offices in United States health systems and regional diagnostic distributors serving European clinical laboratories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cholesterol test market represents a late-cycle quality story as demand migrates toward NMR spectroscopy particle subfraction analysis and Bluetooth-enabled home monitoring platforms with longitudinal data capabilities.
For Market Incumbents: Acquire CLIA-waived assay portfolios to defend physician office laboratory relationships against point-of-care device specialists. Consolidate reagent manufacturing capacity in Germany to offset specialty chemical supply concentration risks. Anchor hospital system contracts through integrated lab automation bundles that raise switching costs for integrated delivery networks. For New Entrants and Emerging Players: FDA over-the-counter clearance pathways in the United States open a window for direct-to-consumer lipid and glucose dual-analyte devices bypassing clinician intermediaries. Target retail pharmacy walk-in formats in suburban United States corridors with rapid-result microfluidic platforms. Pursue subscription-based telehealth partnerships as the primary go-to-market channel for home care penetration. For Investors and Strategic Acquirers: Consolidation pressure builds where fragmented point-of-care device developers lack captive reagent supply and face margin compression from health system purchasing concentration. Long-term viability favors vertically integrated diagnostic conglomerates with dual hardware-chemistry capabilities and FDA predicate device databases for accelerated clearance timelines. Monitor CMS reimbursement determinations for home-based lipid monitoring as the signal indicating channel volume reallocation between laboratory and consumer settings.| Strategic Initiative | Industry Significance |
|---|---|
| CLIA-Waived Assay Portfolio Acquisition | Expands addressable market into physician office laboratories seeking same-visit results. |
| Microfluidic Cartridge Technology Licensing | Enables retail pharmacy deployment without analyzer maintenance overhead. |
| FDA Over-the-Counter Clearance Pathway | Unlocks direct-to-consumer marketing for dual-analyte lipid and glucose devices. |
| Bluetooth EHR Integration Development | Connects home devices to hospital information systems for longitudinal tracking. |
| Reagent Manufacturing Capacity Expansion | Reduces dependency on German and Swiss specialty chemical supply concentration. |
Methodological Framework
Multiple input streams — primary interviews with point-of-care device manufacturers, clinical laboratory directors, and telehealth platform operators, alongside secondary validation against FDA 510(k) filings, CMS reimbursement databases, and hospital procurement records — were reconciled through bottom-up and top-down triangulation. Conversations with GPO contracts managers and biomedical engineers informed installed base dynamics and technology substitution patterns. SEC filings of publicly traded diagnostic conglomerates provided revenue segmentation by product category and geographic market.
Historical volume trajectories were cross-referenced against panel input from industry stakeholders to construct analytical frameworks across the projection horizon. Segmentation dimensions modeled include technology tier, end-user setting, delivery mode, and regional regulatory cluster. CAGRs were derived from curve-fitting approaches applied to technology adoption S-cycles and reimbursement policy phase-ins. Forecast inputs incorporated CLIA-waived test volume expansion rates and employer wellness program mandate penetration by metropolitan statistical area.
Revisions become necessary when FDA clearance timelines for novel device categories extend beyond standard review windows or when CMS issues negative national coverage determinations for home-based monitoring. Forecasts reflect assumptions regarding continued employer wellness program institutionalization and stable enzymatic reagent supply from established chemical manufacturers. A model refresh is warranted upon material change in point-of-care testing reimbursement parity with laboratory-based lipid panels.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Hemostasis Testing Systems Market
Testing Services
Hospital Microbiology Testing Market
Testing Services
Global Vitamin D Testing Market
Testing Services
Asia-Pacific Hereditary Cancer Testing Market
Testing Services
Drug Tester Market
Testing Services
Metabolic Biomarker Testing Market
Testing Services
Nipah Virus Testing Market
Testing Services
Sports Drug Testing Market
Testing Services
Carbapenem-Resistant Enterobacteriaceae Testing Market
Testing Services
Activated Partial Thromboplastin Test Market
Testing Services
Outsourced Testing Services Market
Testing Services
Global at-Home Drug of Abuse (DOA) Testing Market
Testing Services
Solid Tumor Testing Market
Testing Services
Medical Device Analytical Testing Outsourcing Market
Testing Services
Aerospace and Life Science Testing Certification Market
Testing Services
Global Endotoxin and Pyrogen Testing Market