
 Gastrointestinal Testing Panels Market | 2026-2036
Gastrointestinal Testing Panels Market Size, Share, and Industry Trends Forecast 2026-2036
Gastrointestinal Testing Panels Market Analysis
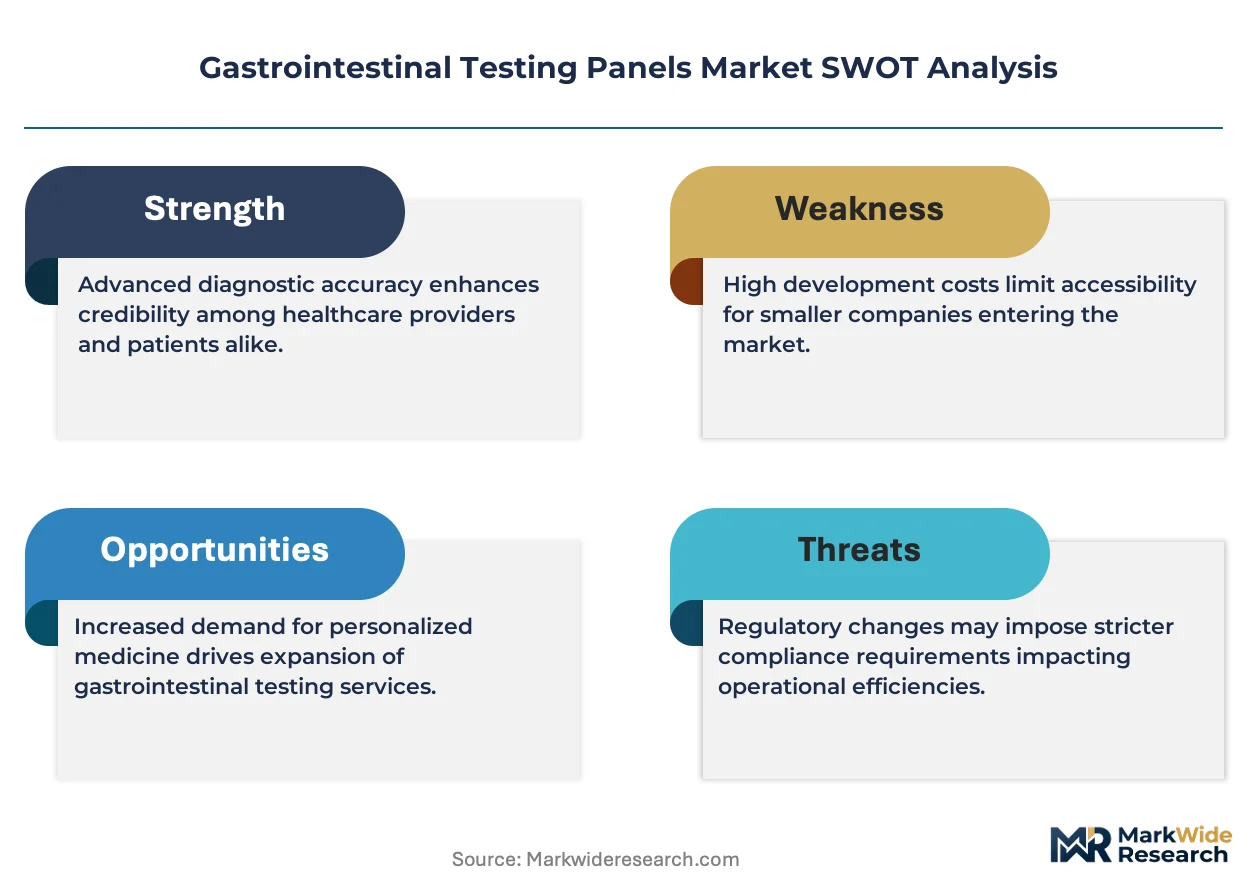
The gap between premium molecular diagnostics and commodity immunoassay panels is repositioning procurement strategies across health systems. Becton, Dickinson and Company leverages its automated platform footprint to sustain high-throughput laboratory relationships. bioMérieux SA specializes in syndromic panel design that differentiates its molecular menu from standard enzyme-based alternatives. Roche Diagnostics anchors European reference laboratory networks with integrated workflow solutions.
Gastrointestinal testing panels are multiplex diagnostic assays that detect pathogens, biomarkers, or genetic markers from stool, breath, blood, or tissue specimens using technologies ranging from enzyme immunoassay to mass spectrometry, designed to identify infectious agents, inflammatory conditions, nutritional deficiencies, or neoplastic changes in a single test run. Molecular diagnostics commands the fastest expansion trajectory as laboratories replace sequential culture methods with parallel nucleic acid detection, while enzyme immunoassay retains volume dominance in cost-sensitive clinic settings where reimbursement constraints limit capital investment. Stool analysis generates the deepest margin pools due to complex sample preparation requirements and specialized collection logistics that create barriers to commoditization.
FDA premarket notification pathways and Clinical Laboratory Improvement Amendments standards govern US market entry, while the EU In Vitro Diagnostic Regulation enforces stricter performance documentation for CE-marked panels sold across European member states. Health Canada and Australia's TGA apply parallel evidentiary frameworks that manufacturers must navigate for priority market access. Stakeholders should track how multiplex claim expansions trigger payer technology assessment reviews that determine category III CPT code assignments.
Market Dynamics
Hospital laboratories are consolidating procurement around multiplex molecular platforms that compress pathogen detection timelines from days to hours, forcing manufacturers to reconfigure R&D pipelines toward integrated workflow solutions rather than standalone assays.
Growth Catalysts
- CLIA complexity:Specialized laboratory certification requirements under Clinical Laboratory Improvement Amendments create stickiness for incumbent panel providers with established quality systems.
- Integrated health networks:United States hospital systems are centralizing microbiology testing into regional reference laboratories, concentrating volume with vendors offering scalable automation.
- Next-generation sequencing:Metagenomic approaches are expanding pathogen detection menus beyond bacterial and viral targets to include parasitic and fungal agents in single workflows.
Market Restraints
- Reimbursement compression:Medicare's Clinical Laboratory Fee Schedule reductions for molecular GI panels constrain pricing power in the largest addressable market.
- Sample logistics concentration:Cold-chain stool specimen transport depends on a limited network of specialized couriers, creating geographic service gaps.
- Culture method persistence:Antimicrobial susceptibility testing still requires viable organism isolation, preventing full displacement of traditional microbiology.
Strategic Opportunities
- At-home collection models:Direct-to-consumer stool sampling kits bypass clinical site logistics, opening primary care and wellness screening channels.
- EU IVDR transition:Stricter performance documentation requirements under the In Vitro Diagnostic Regulation favor well-capitalized manufacturers with robust clinical evidence portfolios.
- AI-assisted interpretation:Machine learning algorithms applied to multiplex panel results are enabling probabilistic pathogen ranking and resistance prediction.
Industry Challenges
- Bioinformatics talent scarcity:Clinical laboratories struggle to hire computational biologists capable of validating and maintaining metagenomic analysis pipelines.
- LIS integration friction:Middleware connectivity between molecular instruments and legacy laboratory information systems requires costly customization per health system.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gastrointestinal Testing Panels Market |
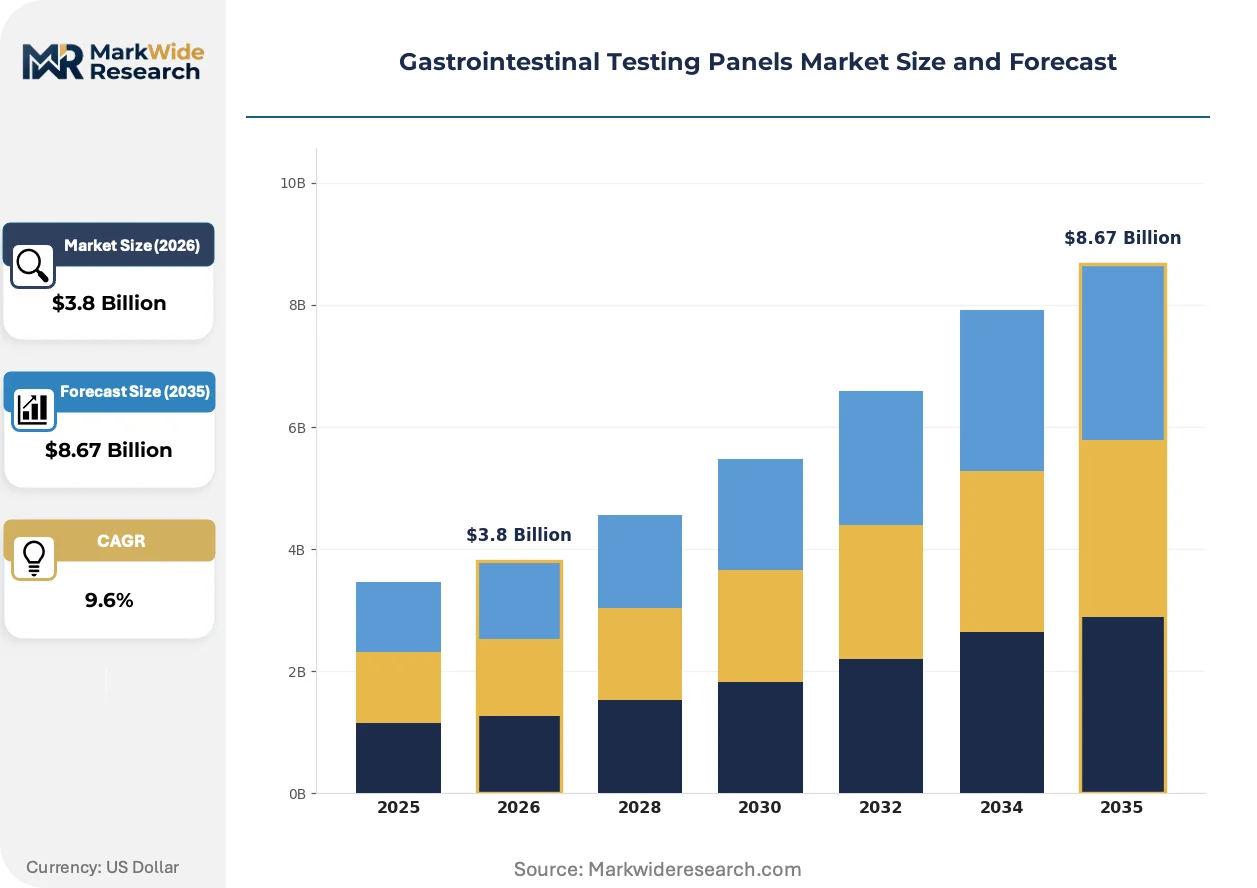
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.67 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Test Type: Stool Analysis, Breath Tests, Blood Tests, Biopsy End User: Hospitals, Clinics, Diagnostic Laboratories, Research Institutions Application: Infectious Diseases, Nutritional Disorders, Inflammatory Conditions, Cancer Screening Technology: Enzyme Immunoassay, Molecular Diagnostics, Microbial Culture, Mass Spectrometry |
| Companies Covered | Becton, Dickinson and Company, bioMérieux SA, DiaSorin S.p.A., QIAGEN, Seegene, Inc., Roche Diagnostics, Abbott Laboratories, Thermo Fisher Scientific, Luminex Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gastrointestinal Testing Panels Market Emerging Trajectories
Digital PCR and CRISPR-based detection chemistries are compressing limits of quantification for low-abundance pathogens, while regulatory frameworks on both sides of the Atlantic accelerate toward post-market surveillance models.
Digital PCR is absorbing sample preparation workflows previously handled by separate nucleic acid extraction platforms. Reference laboratories in the United States are adopting these integrated systems to reduce hands-on time and contamination risk. The technology is absorbing capital budgets that previously supported multiple discrete instruments, consolidating vendor relationships around fewer platform decisions.
REACH substance restrictions and the EU Green Deal chemical sustainability mandates are pressuring reagent manufacturers to reformulate buffer chemistries and plastic consumables. Panel producers must document substance safety profiles across extended supply chains to maintain CE marking under MDR and IVDR convergence. European reference networks are responding by qualifying suppliers with pre-validated sustainable chemistry portfolios.
Health system procurement offices are unbundling instrument placement from reagent contracts, separating capital acquisition decisions from ongoing consumable commitments. This purchasing model disrupts traditional lease-tie arrangements that locked laboratories into single-vendor ecosystems. The shift is most visible in United States integrated delivery networks where supply chain teams now negotiate reagent pricing independently of platform procurement.
Gastrointestinal Testing Panels Market Segmentation
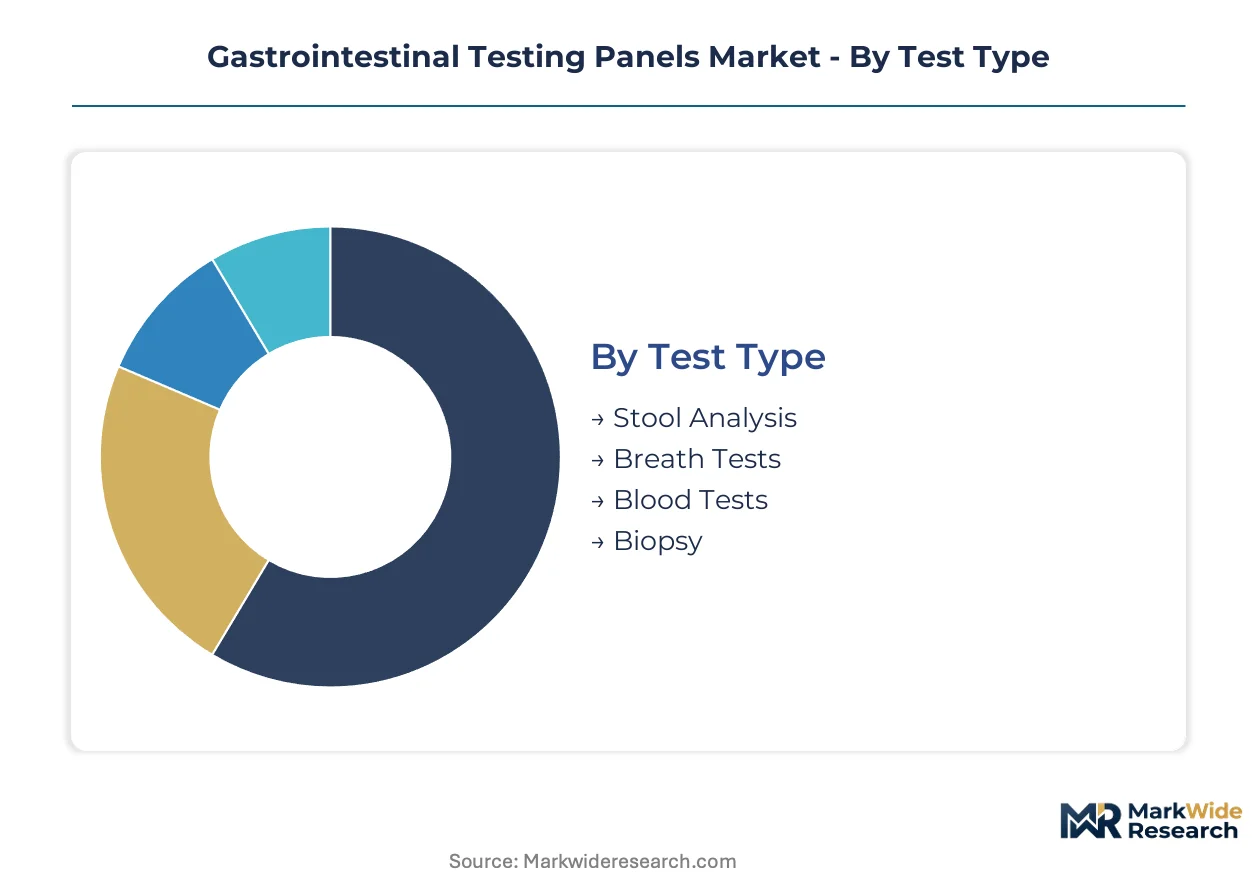
Gastrointestinal testing panels fragment across specimen type, care setting, clinical indication, and detection chemistry. Procurement decisions hinge on capital requirements, reimbursement codes, and workflow integration depth.
Test Type:
Capital intensity varies sharply by specimen logistics and processing complexity. Stool analysis demands specialized collection infrastructure and cold-chain handling that smaller laboratories struggle to fund.
- Stool Analysis:Multiplex nucleic acid detection from fecal specimens requires automated DNA extraction platforms and validated transport media. United States hospital laboratories concentrate demand here, driven by CLIA complexity barriers that protect incumbent providers with established quality systems.
- Breath Tests:Hydrogen and methane quantification for small intestinal bacterial overgrowth relies on portable gas analyzers with lower capital thresholds. Clinics in cost-sensitive settings favor these instruments where reimbursement constraints limit molecular platform investment.
- Blood Tests:Serological panels for celiac disease and inflammatory markers run on standard immunoassay analyzers with minimal incremental equipment needs.
- Biopsy:Histopathological examination of tissue specimens requires embedding centers and microscopy suites with substantial fixed-cost footprints.
Most installed capacity flows through Stool Analysis. Expansion is steepest in Breath Tests.
End User:
Customer scale determines reagent contract structures and platform placement terms. Consolidated purchasers extract pricing concessions unavailable to fragmented buyers.
- Hospitals:Integrated delivery networks in the United States centralize microbiology testing into regional reference laboratories. These facilities negotiate reagent pricing independently of platform procurement, disrupting traditional lease-tie arrangements.
- Diagnostic Laboratories:Independent reference labs compete on turnaround time and panel breadth. Bioinformatics talent scarcity constrains their ability to validate metagenomic analysis pipelines.
- Clinics:Point-of-care settings prioritize enzyme immunoassay instruments with minimal maintenance requirements and lower per-test costs.
- Research Institutions:Academic medical centers drive early adoption of next-generation sequencing approaches for novel pathogen discovery.
Procurement volume concentrates in Hospitals. Research Institutions are climbing the fastest.
Application:
Clinical utility and reimbursement density vary by indication severity and guideline incorporation.
- Infectious Diseases:Syndromic panels detecting bacterial, viral, and parasitic agents command the deepest revenue pools. FDA premarket notification pathways for stool-based DNA assays reshape product development timelines for manufacturers targeting this segment.
- Cancer Screening:Non-invasive colorectal neoplasia detection via methylated DNA markers attracts capital from integrated health networks seeking centralized laboratory procurement efficiencies.
- Inflammatory Conditions:Calprotectin and lactoferrin quantification for inflammatory bowel disease monitoring runs on established immunoassay platforms with predictable reimbursement.
- Nutritional Disorders:Malabsorption and microbiome composition testing occupies a smaller commercial footprint with emerging payer recognition.
Technology investment concentrates in Infectious Diseases. Cancer Screening is gaining share fastest.
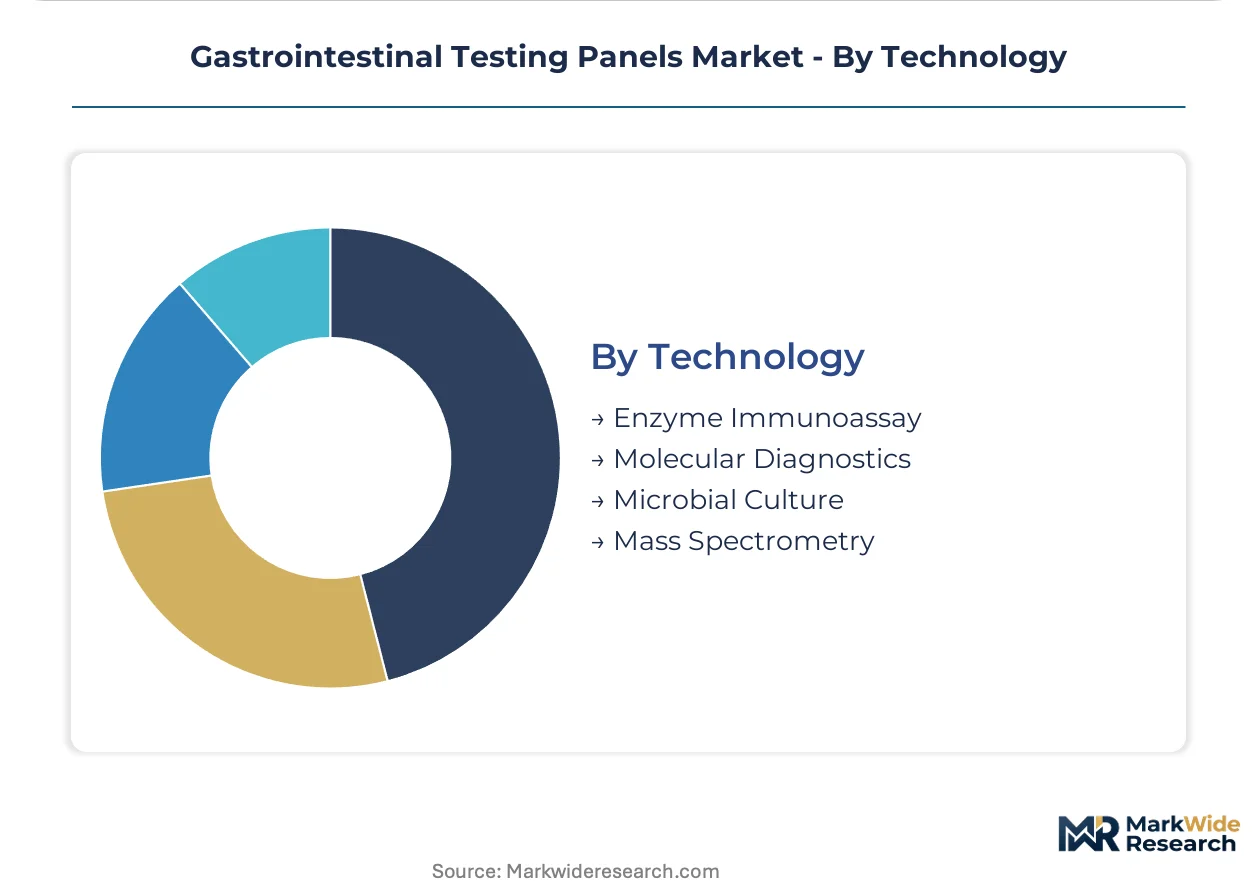
Technology:
Detection chemistry selection locks laboratories into specific reagent ecosystems and skill base requirements.
- Molecular Diagnostics:Parallel nucleic acid detection replaces sequential culture methods, compressing pathogen identification from days to hours. Digital PCR and CRISPR-based chemistries compress limits of quantification for low-abundance targets.
- Enzyme Immunoassay:Antibody-antigen binding assays retain volume dominance in cost-sensitive clinic settings. These platforms require minimal bioinformatics infrastructure.
- Microbial Culture:Viable organism isolation persists for antimicrobial susceptibility testing, preventing full displacement despite longer turnaround times.
- Mass Spectrometry:MALDI-TOF identification of cultured isolates offers rapid species-level classification with moderate capital requirements.
Installed base concentrates in Enzyme Immunoassay. Steepest expansion trajectory belongs to Molecular Diagnostics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States concentrates procurement volume through integrated health networks, while Germany anchors European reference laboratory automation. Japan and South Korea drive molecular platform adoption in Asia-Pacific, with Australia and Canada representing mature secondary markets with distinct regulatory pathways.
United States
Hospital laboratories centralize microbiology testing into regional reference facilities, concentrating demand with scalable automation vendors. FDA premarket notification pathways and CLIA complexity requirements protect incumbent providers with established quality systems. The Boston-Cambridge corridor houses multiple diagnostic developers advancing syndromic panel designs.
Germany
Reference laboratory networks prioritize integrated workflow solutions that compress pathogen detection timelines. EU IVDR enforcement demands stricter performance documentation for CE-marked panels, favoring manufacturers with robust clinical evidence portfolios. The Rhine-Main metropolitan cluster hosts several automated platform specialists serving central European markets.
Japan
Academic medical centers drive early adoption of next-generation sequencing for novel pathogen discovery, while hospital systems emphasize high-throughput molecular platforms. PMDA regulatory frameworks align with international standards but require localized validation studies. The Kanto region around Tokyo concentrates diagnostic instrument distribution and technical support infrastructure.
South Korea
Diagnostic laboratories compete aggressively on turnaround time and panel breadth, accelerating multiplex platform deployment. MFDS approval pathways enable rapid market entry for manufacturers with existing US or EU clearances. The Seoul Capital Area hosts dense networks of independent reference labs and hospital-affiliated testing facilities.
Australia
TGA evidentiary frameworks apply parallel requirements to FDA pathways, creating streamlined access for pre-cleared manufacturers. Geographic dispersion creates demand for robust cold-chain logistics supporting stool specimen transport. Sydney and Melbourne anchor specialized courier networks serving regional laboratory networks.
Gastrointestinal Testing Panels Market Vendor Landscape
Top-tier vendors anchor high-throughput laboratory relationships, while mid-scale specialists occupy syndromic panel niches. The vendor base stratifies across automated platform providers, molecular menu designers, and integrated workflow solution suppliers. Strategic archetypes include capital-intensive automation leaders, bioinformatics-enabled metagenomic specialists, and reagent-focused contract manufacturers. Competitive moves concentrate on unbundling instrument placement from reagent contracts and securing CLIA-complexity certifications that create switching costs.
Among US-based diversified health technology conglomerates, Becton, Dickinson and Company occupies a position exemplifying automated platform scale, while Abbott Laboratories represents the integrated diagnostics portfolio archetype. European specialists include bioMérieux SA, which anchors the syndromic molecular design tier, and Roche Diagnostics, which exemplifies the reference network workflow integration model. These named entities represent strategic positioning patterns rather than specific competitive actions or market share claims.
| Leading Market Players |
|---|
| Becton, Dickinson and Company |
| bioMérieux SA |
| DiaSorin S.p.A. |
| QIAGEN |
| Seegene, Inc. |
| Roche Diagnostics |
| Abbott Laboratories |
| Thermo Fisher Scientific |
| Luminex Corporation |
| Others |
Supply Flow & Price Mechanics
Digital PCR platform consolidation simultaneously compresses per-test cost economics and concentrates procurement power among laboratories with capital to absorb integrated extraction-detection workflows, reshaping vendor-customer bargaining dynamics across the United States and European reference networks.
Pricing Analysis
Bundled instrument-reagent contracts versus unbundled procurement splits pricing power between vendors and health systems. Three-tier pricing structure across premium molecular, standard immunoassay, and economy culture-based tiers reflects CLIA certification depth and automation scale. Cost compression in standard immunoassay segments intensifies as Medicare Clinical Laboratory Fee Schedule reductions constrain reimbursement ceilings. Clinic settings exhibit highest price sensitivity due to capital constraints, while integrated delivery networks leverage volume concentration for reagent concessions.
Supply Chain Analysis
Dual-sourcing mandates from United States hospital procurement offices require qualified backup suppliers for critical reagents and transport media, fragmenting volume across multiple vendors. Manufacturing concentrates in the United States, Germany, and Japan for precision instrumentation, while plastic consumables and buffer chemistries draw from Chinese and South Korean suppliers. Cold-chain stool specimen logistics rests on limited specialized courier networks, creating geographic service gaps. Tariff exposure on Chinese-sourced consumables threatens margin stability. Distribution runs through regional reference laboratory hubs serving consolidated health network demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where manufacturers can exploit the gap between FDA premarket notification requirements and EU IVDR documentation burdens to stage product launches in lower-evidentiary-threshold jurisdictions first.
For Market Incumbents: Cement CLIA-complexity certifications as switching-cost barriers against emerging metagenomic specialists threatening reference laboratory relationships. Deepen backward integration into automated DNA extraction chemistry production to defend margin position against reagent contract unbundling. Lock in multi-year exclusive servicing agreements with integrated delivery networks before next-generation sequencing platforms mature.
For New Entrants and Emerging Players: Launch via direct-to-consumer at-home collection models bypassing hospital laboratory procurement gatekeepers to access primary care and wellness screening channels. Target breath test segments where portable gas analyzer capital thresholds remain accessible and reimbursement constraints limit molecular platform competition. Pursue AI-assisted interpretation software partnerships with diagnostic laboratories struggling with bioinformatics talent scarcity.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale syndromic panel designers with CE marking but lacking FDA clearance, offering regulatory-arbitrage upside. Long-term viability over the next decade hinges on successful navigation of EU IVDR performance documentation requirements and Medicare reimbursement strategy execution. Watch for multiplex claim expansions triggering payer technology assessment reviews as the inflection signal for category III CPT code assignment timing.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Premarket Notification Pathway | Accelerates United States market entry for stool-based DNA assay developers ahead of competitors awaiting full PMA review. |
| EU IVDR Performance Documentation | Stricter CE marking requirements favor manufacturers with robust clinical evidence portfolios against undercapitalized rivals. |
| Hospital System Partnership | Integrated delivery network centralization concentrates volume with vendors offering scalable automation and CLIA-compliant quality systems. |
| Software Companion Development | Machine learning algorithms for probabilistic pathogen ranking differentiate molecular menus from commodity enzyme-based alternatives. |
| Reimbursement Strategy | Category III CPT code assignments determine pricing power and market access depth for novel multiplex panel claims. |
Methodological Framework
Coverage spans the United States, Germany, Japan, South Korea, and Australia, with primary inputs from each market's reference laboratory networks and regulatory environments. The approach combines structured interviews with hospital laboratory directors, diagnostic procurement managers, biomedical engineers, and CLIA compliance officers with secondary validation from FDA 510(k) filings, EU IVDR technical documentation, CMS Medicare reimbursement databases, and hospital GPO contract records. Bottom-up instrument placement and reagent consumption estimates triangulate against top-down health system expenditure data.
Granularity-level modeling disaggregates volume and value across test type, end user, application, and technology dimensions, with additional segmentation by regional regulatory cluster and automation tier. CAGRs derive from fitted growth curves applied to installed base expansion and test menu penetration rates across the projection horizon. Industry-specific inputs include CLIA laboratory certification counts, syndromic panel FDA submission timelines, and integrated delivery network microbiology consolidation patterns.
Forecast precision tightens around the base case; tail outcomes carry wider variance under scenarios of accelerated Medicare reimbursement compression or disruptive CRISPR-based detection chemistry adoption. Deviation in EU IVDR enforcement timing or FDA premarket notification pathway restructuring would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Global Cholesterol Testing Products and Services Market
Testing Services
Diagnostic Shipper Market
Testing Services
Global Thyroid Function Test Market
Testing Services
US at-Home Testing Kits Market
Testing Services
Drug Testing Equipment Market
Testing Services
Global Sterility Testing Market
Testing Services
Global Molecular Quality Controls Market
Testing Services
Hospital Acquired Disease Testing Market
Testing Services
North America Endotoxin and Pyrogen Testing Market
Testing Services
Home DNA Testing Market
Testing Services
Antibiotic Residue Test Kits Market
Testing Services
US & Europe Extractable and Leachable Testing Services Market
Testing Services
Anti-Asthma TDM Assay Kits Market
Testing Services
Global Urinalysis Test Market
Testing Services
Mono Rapid Testing Market
Testing Services
Global Vitamin D Testing Market