
 North America Simulator Windows and Simulator Skylights Market | 2026-2036
North America Simulator Windows and Simulator Skylights Market Size, Share, and Industry Trends Forecast 2026-2036
North America Simulator Windows and Simulator Skylights Market Insights
Certified optical technician shortages across the United States and Canada is redrawing how simulator window suppliers scale production. CAE Inc. leverages captive glass fabrication partnerships to secure specialty coated substrates for its full-flight simulators. L3Harris Technologies anchors its position through vertically integrated photonics laboratories in Florida. Thales Group competes by sustaining dual-source supply chains for laminated display assemblies serving military and civilian training programs.
Simulator windows and simulator skylights are multi-layer optical assemblies incorporating laminated glass, anti-reflective coatings, and electromagnetic interference shielding, manufactured to precise angular distortion tolerances for immersive visual environments. These components channel high-resolution projected imagery into pilot training devices while maintaining structural integrity under repeated pressurization cycles. Fixed Windows dominate current procurement volumes as baseline configurations for established flight training organizations, while Custom Solutions capture expanding margin pools from next-generation mixed-reality simulator programs. Energy Efficient features are gaining specification share as training centers face escalating HVAC loads from high-brightness projection enclosures.
FAA Technical Standard Orders govern optical transmission specifications for certified flight simulation devices, while EASA CS-FSTD references shape cross-border design requirements for Canadian manufacturers exporting to European operators. OSHA workplace illumination standards influence skylight placement in simulator bay maintenance areas. Stakeholders must monitor evolving photonic safety thresholds as laser-projection simulators replace legacy lamp-based systems across North American training infrastructure.
Market Dynamics
FAA Technical Standard Order revisions are compressing certification timelines for optical assemblies while laser-projection adoption accelerates specification volatility across North American training infrastructure.
Growth Catalysts
- FAA Certification Intensification:Tightening optical fidelity standards for Level D full-flight simulators is mandating replacement cycles for legacy window assemblies across Texas and Arizona training campuses.
- Electromagnetic Interference Shielding:Next-generation dome projection systems require upgraded conductive coatings, pulling demand for multi-layer laminated substrates into military and civilian programs simultaneously.
- Energy Code Convergence:ASHRAE 90.1 adoption across Florida and California simulator facilities is specifying low-emissivity skylight configurations for climate-controlled bay environments.
Market Restraints
- Specialty Glass Concentration:Borosilicate substrate supply concentrates among three North American float-glass producers, exposing procurement to capacity allocation volatility.
- Coating Equipment Lead Times:Magnetron sputtering systems for anti-reflective deposition carry 18-month delivery cycles from German and Japanese capital equipment suppliers.
- Technician Certification Bottlenecks:FAA-approved optical technician training programs graduate fewer than 200 specialists annually across the United States and Canada.
Strategic Opportunities
- Canadian Export Alignment:EASA CS-FSTD harmonization with Transport Canada standards is opening certified supplier pathways for Ontario and Quebec manufacturers into European operator procurement.
- Mixed-Reality Convergence:Integration of LED volume walls with traditional collimated displays is creating demand for adjustable-transmittance smart glass in next-generation simulator architectures.
- Maintenance Channel Expansion:Simulator bay operators are unbundling window replacement from OEM service contracts, creating independent aftermarket procurement channels.
Industry Challenges
- Angular Distortion Calibration:Maintaining sub-arcminute tolerance across multi-panel installations requires specialized metrology equipment rarely available outside OEM facilities.
- Legacy Pressurization Cycle Fatigue:Older simulator domes built to 1980s structural specifications face premature delamination failures incompatible with modern optical transmission requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Simulator Windows and Simulator Skylights Market |
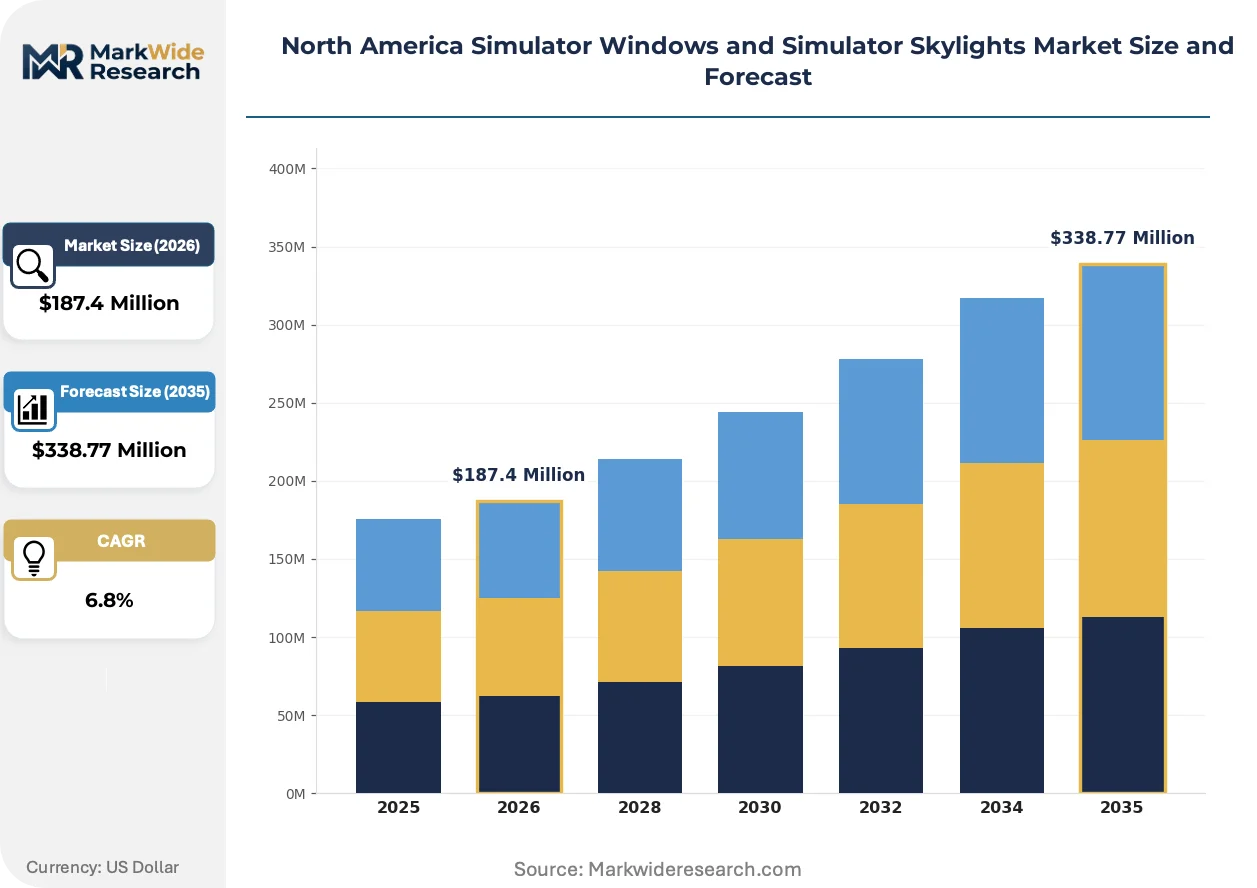
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Windows, Ventilated Skylights, Tubular Skylights, Custom Solutions Application: Residential Use, Commercial Spaces, Educational Institutions, Workshop Environments Feature: Energy Efficient, UV Resistant, Soundproof, Aesthetic Designs Installation: New Construction, Retrofitting, Modular Installations, DIY Options |
| Companies Covered | CAE Inc., L3Harris Technologies, Thales Group, Rockwell Collins Inc., Frasca International, FlightSafety International, LIXIL, VELUX, YKKAP, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Simulator Windows and Simulator Skylights Market Trends and Innovations
Laser-projection technology is destabilizing established optical specifications while regulatory pressure on energy performance accelerates material substitution in simulator enclosure design.
Dynamic dimmable glazing is bifurcating the fixed-window category. Electrochromic interlayers from Saint-Gobain and View Glass enable real-time luminance matching between projected imagery and ambient bay lighting. CAE and FlightSafety International are specifying these assemblies for next-generation Level D programs. The technology is bifurcating procurement into static-laminate and active-control supply chains with diverging vendor qualification pathways.
FAA Advisory Circular 60-6D updates are mandating photobiological safety testing for laser-illuminated display systems. Simulator operators must now document optical radiation exposure levels at pilot eye positions during certification audits. Military training programs at Randolph Air Force Base and Naval Air Station Patuxent River are experiencing the steepest compliance cost escalation as they field the highest-brightness projection configurations.
Consolidated procurement through aviation training group purchasing organizations is displacing direct OEM relationships for window replacement cycles. L3Harris and TRU Simulation + Training are channeling aftermarket demand through preferred supplier frameworks with pre-negotiated coating specifications. Texas and Arizona campus operators report 15-20% unit cost compression under these arrangements versus legacy spot-buying patterns.
North America Simulator Windows and Simulator Skylights Market Segmentation
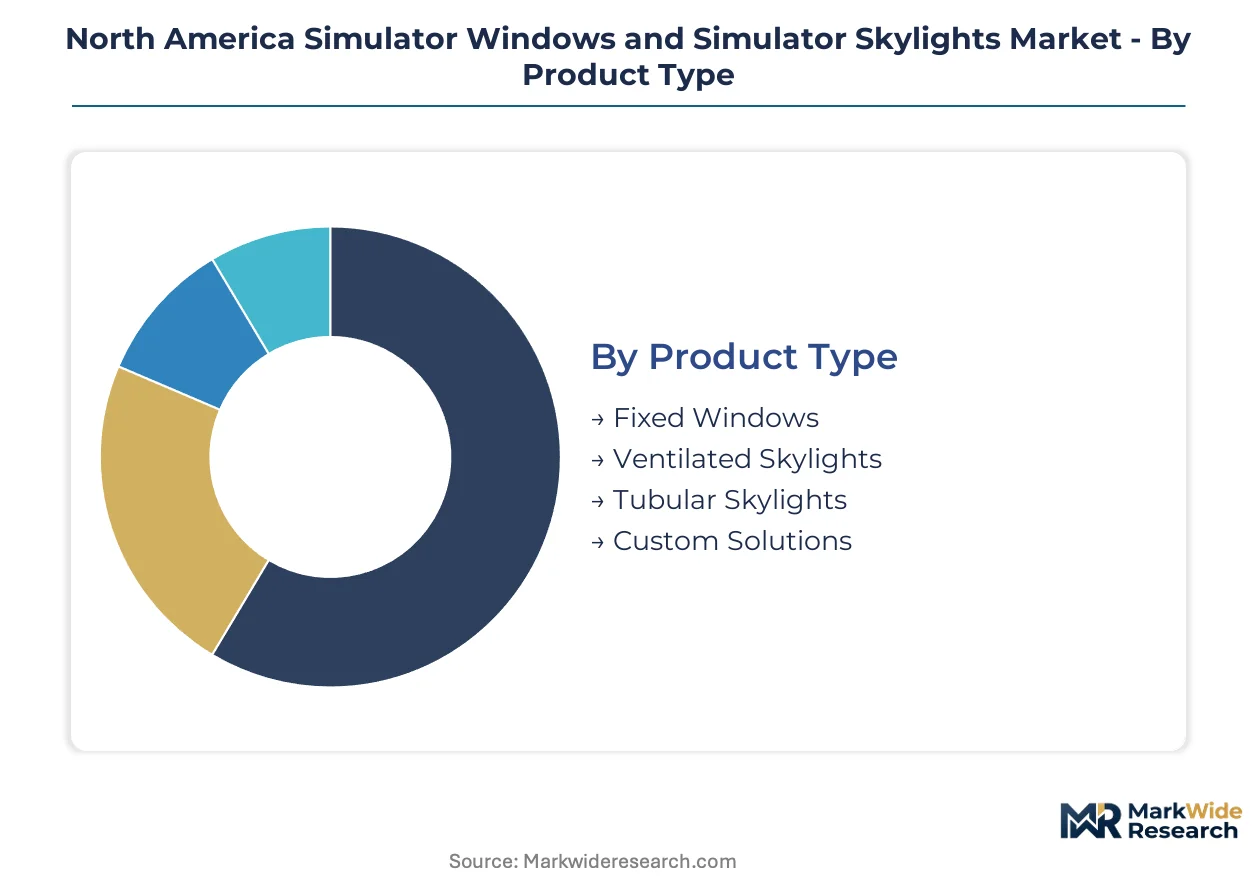
Optical specification divergence across civilian and military training programs fragments procurement patterns. Segmentation reveals how certification grade, installation context, and performance tier reshape supplier positioning across United States and Canadian simulator infrastructure.
Product Type:
Domestic demand concentrates in standardized configurations for FAA-certified programs, while Canadian manufacturers target export-oriented custom fabrication for EASA-aligned European operators.
- Fixed Windows:Laminated glass assemblies with anti-reflective coatings and EMI shielding form the baseline for Level D full-flight simulators. Procurement clusters at Texas and Arizona training campuses where CAE and FlightSafety International operate legacy dome facilities. FAA Technical Standard Order compliance drives replacement cycles as optical fidelity thresholds tighten.
- Custom Solutions:Multi-layer optical stacks engineered to precise angular distortion tolerances for mixed-reality simulator architectures. Demand originates from next-generation programs at Naval Air Station Patuxent River and Randolph Air Force Base integrating LED volume walls with collimated displays. Adjustable-transmittance smart glass specifications are expanding margin pools beyond standard laminate configurations.
- Ventilated Skylights:Climate-controlled bay environments in Florida and California specify these for HVAC load management.
- Tubular Skylights:Maintenance corridor illumination in simulator facilities employs compact daylighting for OSHA workplace compliance.
Fixed Windows holds the largest share; momentum sits with Custom Solutions.
Application:
Cost tier stratification separates military-grade optical specifications from commercial training center procurement, with educational institutions occupying a mid-tier certification band.
- Commercial Spaces:Aviation training centers and airline-owned simulator facilities constitute the volume anchor. Texas, Arizona, and Florida campuses drive procurement of standardized window assemblies for Level C and Level D devices. Consolidated purchasing through group purchasing organizations is compressing unit costs 15-20% below legacy spot-buying patterns.
- Workshop Environments:Maintenance bay skylight specifications emphasize durability under pressurization cycle fatigue. Older simulator domes built to 1980s structural standards face premature delamination failures, creating aftermarket replacement demand. OSHA workplace illumination standards govern skylight placement in technician servicing areas.
- Residential Use:Private pilot training installations in Arizona and Florida represent niche demand.
- Educational Institutions:University aviation programs in Texas and Ohio procure entry-level simulator configurations.
Commercial Spaces dominates procurement volume; Workshop Environments is expanding most quickly as legacy infrastructure ages out.
Feature:
Margin concentration tracks regulatory pressure, with energy performance and photobiological safety emerging as specification differentiators.
- Energy Efficient:Low-emissivity coatings and thermally broken frames address ASHRAE 90.1 adoption across climate-controlled simulator bays. California and Florida facilities face escalating HVAC loads from high-brightness projection enclosures, pulling demand for insulating glass units with solar heat gain coefficient optimization.
- UV Resistant:Laminated interlayers with ultraviolet-blocking substrates protect projection screen polymers from photodegradation. FAA Advisory Circular 60-6D mandates photobiological safety testing for laser-illuminated systems, requiring UV exposure documentation at pilot eye positions during certification audits.
- Soundproof:Acoustic dampening interlayers for simulator facilities near active runways.
- Aesthetic Designs:Curved and tinted options for visitor-facing display installations.
Energy Efficient commands specification share; UV Resistant is gaining fastest from laser-projection compliance mandates.
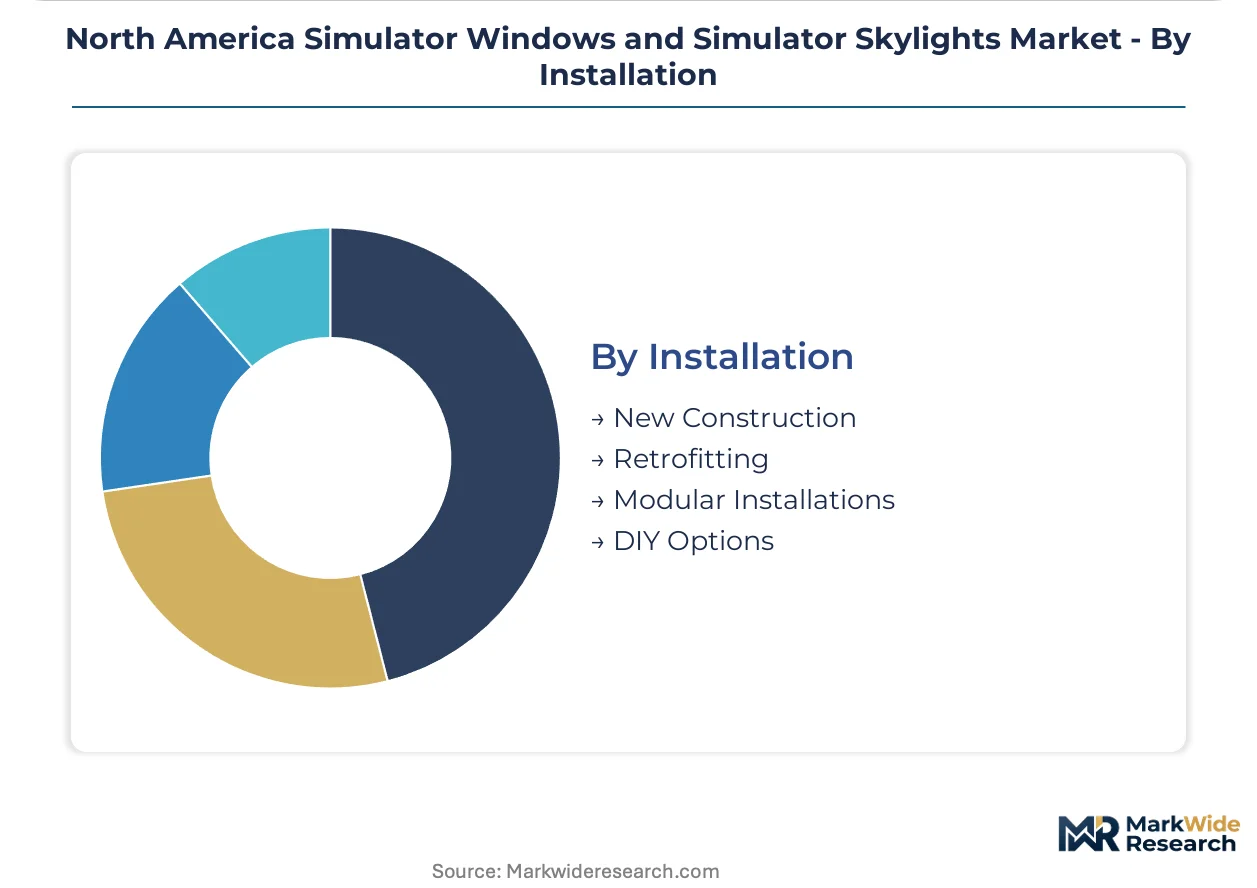
Installation:
Customer type bifurcation separates OEM-integrated new construction from independent aftermarket channels unbundling window replacement from service contracts.
- New Construction:Greenfield simulator facilities in Texas and Arizona specify windows during dome structural fabrication. L3Harris and TRU Simulation + Training channel demand through preferred supplier frameworks with pre-negotiated coating specifications. Magnetron sputtering equipment lead times from German and Japanese suppliers compress project scheduling flexibility.
- Retrofitting:Legacy dome window replacement creates independent procurement pathways as operators unbundle maintenance from OEM contracts. Canadian manufacturers in Ontario and Quebec leverage EASA CS-FSTD harmonization with Transport Canada standards to supply European-aligned retrofit programs.
- Modular Installations:Prefabricated window assemblies for rapid simulator bay deployment.
- DIY Options:Limited to non-certified training device applications.
New Construction retains volume leadership; Retrofitting is climbing the fastest as maintenance channel expansion accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Texas and Arizona training corridors while Canadian manufacturers compete on EASA-aligned export specifications. United States facilities absorb premium coatings costs from German and Japanese equipment lead times. Canadian producers leverage Transport Canada harmonization to undercut European domestic suppliers on retrofit timelines.
United States
Texas and Arizona training campuses drive fixed-window procurement for Level D full-flight simulators. FAA Technical Standard Order revisions compress certification timelines for optical assemblies. Dallas-Fort Worth and Phoenix-Mesa corridors concentrate CAE and FlightSafety International dome facilities undergoing replacement cycles.
Canada
Ontario and Quebec manufacturers target EASA CS-FSTD export pathways for European operator procurement. Transport Canada standards harmonization reduces certification friction for cross-border supply. Montreal and Toronto fabrication clusters specialize in custom angular-distortion tolerances for mixed-reality architectures.
Florida
Climate-controlled bay environments specify ventilated skylights for ASHRAE 90.1 HVAC load management. Laser-projection adoption accelerates photobiological safety compliance costs at military training installations. Orlando and Tampa aviation corridors concentrate L3Harris vertically integrated photonics laboratories.
California
Energy code convergence specifies low-emissivity skylight configurations for high-brightness projection enclosures. OSHA workplace illumination standards govern maintenance bay daylighting placement. Southern California simulator clusters face escalating cooling loads from LED volume wall integration.
North America Simulator Windows and Simulator Skylights Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the North American simulator window supply base. The market structures around three tiers: aerospace/defense integrators with captive optical laboratories, specialized glass fabricators with coating partnerships, and building products specialists adapting skylight platforms for industrial bay environments. Dominant competitive moves include preferred supplier framework consolidation and backward integration into specialty substrate supply.
Among aerospace-integrated specialists, CAE Inc., L3Harris Technologies, and Thales Group occupy positions spanning captive fabrication to dual-source supply chain management. CAE exemplifies the laboratory-anchored archetype through glass fabrication partnerships securing coated substrates. L3Harris represents vertical control over photonics capabilities in Florida corridor proximity. Thales sits within the dual-source supply archetype sustaining laminated display assembly channels for cross-program military and civilian demand.
| Leading Market Players |
|---|
| CAE Inc. |
| L3Harris Technologies |
| Thales Group |
| Rockwell Collins Inc. |
| Frasca International |
| FlightSafety International |
| LIXIL |
| VELUX |
| YKKAP |
| Others |
Pricing and Supply Chain Analysis
FAA Technical Standard Order certification gates both supplier qualification and price differentiation simultaneously, as uncertified optical assemblies cannot access Level D simulator procurement channels regardless of cost position. This regulatory threshold compresses margin pools for non-compliant fabricators while concentrating pricing power among the limited base of approved coating specialists.
Pricing Analysis
Configured-to-order pricing for custom angular-distortion tolerances commands substantial premiums over standard fixed-window configurations, with certification grade and volume scale serving as the primary differentiation levers. Three-tier pricing structure across premium, standard, and economy levels separates military-grade EMI-shielded laminates from commercial training center specifications. Cost compression in standard configurations is intensifying because consolidated group purchasing organizations displace direct OEM relationships. Educational institutions and smaller aviation programs exhibit the highest price sensitivity, while military installations at Randolph Air Force Base and Naval Air Station Patuxent River prioritize optical fidelity over unit economics.
Supply Chain Analysis
Inbound logistics costs from German and Japanese magnetron sputtering equipment suppliers extend coating system delivery cycles, constraining North American production expansion. Specialty borosilicate substrate supply concentrates among United States, Canada, and Mexico float-glass producers, with raw material dependencies on germanium dioxide, cerium oxide polishing compounds, and silver-based conductive coatings. Single-source vulnerability in anti-reflective deposition equipment creates procurement bottlenecks for capacity-constrained fabricators. Distribution runs through preferred supplier frameworks anchored by CAE, L3Harris, and FlightSafety International, with independent aftermarket channels emerging as operators unbundle window replacement from OEM service contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The acute shortage of FAA-approved optical technicians—graduating fewer than 200 specialists annually across the United States and Canada—constrains production scaling and concentrates capability among incumbent laboratories. This talent scarcity justifies defensive consolidation moves and targeted capability acquisition strategies.
For Market Incumbents: Compound laboratory capacity advantages through captive substrate partnerships and backward integration into specialty coating supply, while defending against independent aftermarket channels by embedding replacement windows within long-term service agreements. Magnetron sputtering equipment lead times from German and Japanese suppliers represent a critical vulnerability requiring dual-source capital equipment strategies. For New Entrants and Emerging Players: Anchor in Canadian export pathways leveraging EASA CS-FSTD harmonization with Transport Canada standards, targeting European operator retrofit programs where certification friction disadvantages domestic European suppliers. The most penetrable white-space sits in adjustable-transmittance smart glass for mixed-reality simulator architectures, with go-to-market execution through direct engagement with LED volume wall integrators at military training installations. For Investors and Strategic Acquirers: FAA Advisory Circular 60-6D photobiological safety mandates reshape the acquisition landscape by elevating certified testing laboratory capabilities above commodity fabrication assets. Long-term viability rests on positioning for laser-projection compliance infrastructure rather than legacy lamp-based simulator supply chains. The acquisition target archetype combines optical metrology expertise with existing FAA certification relationships. The signal to watch is Transport Canada-EASA mutual recognition agreement expansion timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Substrate Supply | CAE's captive glass fabrication partnerships insulate against borosilicate concentration risk. |
| Dual-Source Capital Equipment Strategy | Thales sustains laminated display assembly channels through redundant magnetron sputtering supplier relationships. |
| Certified Testing Laboratory Acquisition | Photobiological safety compliance infrastructure gains value from FAA Advisory Circular 60-6D enforcement. |
| Preferred Supplier Framework Consolidation | L3Harris compresses procurement costs 15-20% through pre-negotiated coating specifications with Texas campus operators. |
| Electrochromic Interlayer Development Partnership | Saint-Gobain and View Glass enable real-time luminance matching for next-generation Level D programs. |
Research Methodology
Operator-level perspectives from simulator facility directors, FAA certification engineers, optical coating specialists, and aviation training procurement managers anchored the qualitative base for this analysis. Primary interview data combined with secondary validation from FAA Technical Standard Order filings, EASA CS-FSTD documentation, ASHRAE 90.1 energy code adoption records, and SEC 10-K disclosures from publicly traded aerospace integrators. Bottom-up demand modeling across installation type and feature tier triangulated against top-down market sizing from capital expenditure disclosures at major training campuses.
Sensitivity analysis around laser-projection adoption timelines and certification engineer graduation rates tested forecast robustness across the analysis window. Segmentation dimensions modeled include product type, application tier, feature specification, and installation context, with regional regulatory cluster as an additional aerospace-specific dimension. CAGRs derived from installed base replacement cycle analysis and greenfield facility construction pipelines, incorporating high-brightness projection enclosure penetration and HVAC load management requirements as industry-specific demand drivers.
Material uncertainties—tariff exposure on German and Japanese capital equipment, FAA certification timeline compression, and borosilicate float-glass capacity allocation volatility—sit outside the modeled envelope. Forecasts reflect assumptions regarding EASA-Transport Canada harmonization continuity and military training budget prioritization for laser-projection infrastructure. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Simulation and Training
Dynamic Flight Training Compartments Market
Simulation and Training
Global Healthcare Games and Simulation Market
Simulation and Training
Military Simulation Virtual Training Market
Simulation and Training
Satellite Simulator Market
Simulation and Training
Asia-Pacific Ship Bridge Simulators Market
Simulation and Training
Global Military Airborne Simulation and Training Market
Simulation and Training
Trainer Aircraft Market
Simulation and Training
Asia-Pacific Civil Aviation Simulators Market
Simulation and Training
Military Aerospace Simulation and Training Market
Simulation and Training
Pilot Training Market
Simulation and Training
Europe Flight Training and Simulation Market
Simulation and Training
UAV Flight Training and Simulation Market
Simulation and Training
Military Training Aircraft Market
Simulation and Training
Middle East and Africa Ship Bridge Simulators Market
Simulation and Training
Military Vehicles and Aircraft Simulations Market
Simulation and Training
Military Simulation Software Market