
 Tethered Drones Market | 2026-2036
Tethered Drones Market Size, Share, and Industry Trends Forecast 2026-2036
Tethered Drones Market Outlook
Israeli defense contractors is repositioning tethered drone manufacturing toward NATO-aligned specifications. Elistair Sas leverages its proprietary micro-tether power systems to dominate European emergency response deployments. Hoverfly Technology Inc. anchors North American commercial sales through FAA-compliant persistent aerial platforms for infrastructure inspection.
Tethered drones are unmanned aerial vehicles physically connected to a ground station via a power and data-transmitting cable, enabling indefinite flight duration with continuous electrical supply for sensors, communications relays, or surveillance payloads. Multiple rotor configurations lead current procurement volumes due to vertical takeoff precision in urban canyons and confined maritime spaces. Military end users represent the deepest margin pool, while commercial telecommunications applications demonstrate the fastest deployment velocity as cellular network densification demands persistent aerial nodes.
FAA regulations governing beyond-visual-line-of-sight operations and power-over-tether safety certifications shape product design requirements for US market entry, while EU CE marking and RoHS compliance govern European hardware distribution. Military buyers require NATO STANAG interoperability standards for command-and-control integration. Stakeholders must monitor evolving spectrum allocation rules for tethered relay platforms and anticipate procurement shifts as defense agencies prioritize resilient communications architectures against electronic warfare threats.
Market Dynamics
FAA Part 107 waivers for beyond-visual-line-of-sight tethered operations are compressing deployment timelines for commercial operators while NATO procurement standards are reshaping manufacturer specifications.
Growth Catalysts
- Cellular Network Densification:Telecommunications carriers require persistent aerial nodes for 5G coverage extension in urban corridors. Tethered platforms deliver continuous power for relay equipment without battery swap logistics.
- FAA Regulatory Pathway:Power-over-tether safety certifications under Part 107 waivers enable commercial beyond-visual-line-of-sight operations. This framework removes altitude and duration restrictions that constrain free-flying alternatives.
- NATO STANAG Interoperability:Military command-and-control integration mandates drive standardization of data protocols and ground station interfaces. Allied defense agencies prioritize platforms meeting these specifications for joint operations.
Market Restraints
- Copper Tether Cost Volatility:Conductive cable materials face price pressure from electrification demand across automotive and grid infrastructure sectors. Manufacturers absorb margin compression or pass through to defense buyers with long procurement cycles.
- Winch System Supplier Concentration:Precision motorized tether management systems concentrate among German and Swiss component specialists. Single-source dependencies create vulnerability for volume scaling.
- Optical Fiber Substitution Threat:Free-space optical communication links bypass tether infrastructure entirely for certain high-bandwidth applications. Laser relay systems compete for military communications contracts.
Strategic Opportunities
- India Critical Infrastructure Protection:Border surveillance and port security agencies seek persistent aerial platforms under the country's PLI scheme for domestic manufacturing. Local assembly requirements favor joint ventures with established tether system providers.
- Hybrid Hydrogen-Tether Convergence:Fuel cell power integration extends operational radius beyond fixed ground station constraints. Maritime patrol applications benefit from combined energy architectures.
- EU Green Deal Public Procurement:RoHS-compliant tether systems qualify for preferential treatment in European emergency response fleet modernization. Battery-free operation aligns with circular economy mandates for reduced hazardous material deployment.
Industry Challenges
- Electromagnetic Compatibility Certification:Co-location with high-power radar and communications equipment requires extensive testing under NATO STANAG 4370 environmental standards. Timeline extension delays contract awards.
- Legacy C4ISR Integration Complexity:Armed forces require backward compatibility with existing command networks dating to prior decade architectures. Software bridge development consumes engineering resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tethered Drones Market |
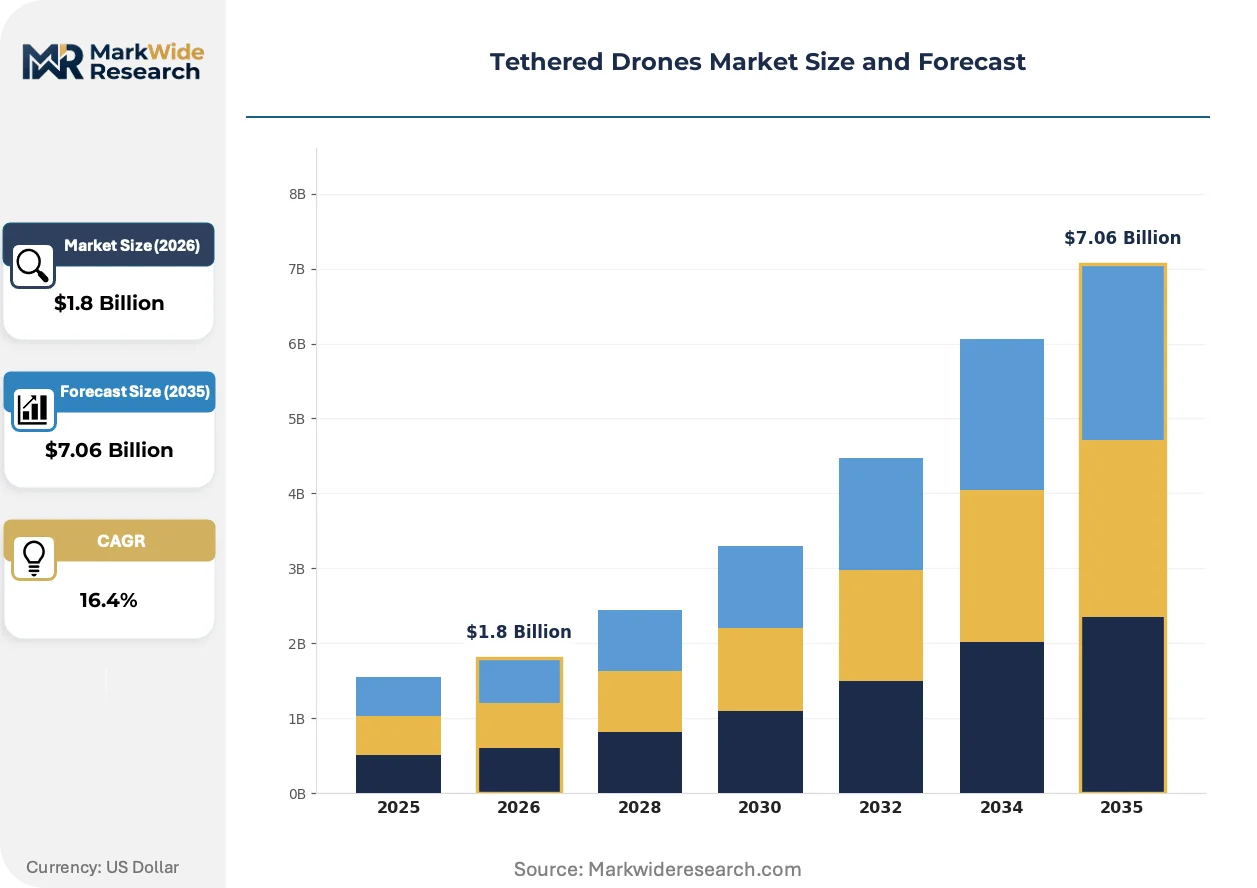
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $7.06 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Multiple Rotor, Fixed Wing, Hybrid, Solar Powered End User: Military, Commercial, Emergency Services, Infrastructure Deployment: Onshore, Offshore, Urban, Rural Application: Surveillance, Telecommunications, Monitoring, Search & Rescue |
| Companies Covered | COMSovereign Holding Corp., Novadem, Elistair Sas, Menet Aero LLC., Perspective Robotics AG, Hoverfly Technology Inc., Dragonfly Pictures Inc., Mistral Solutions Pvt. Ltd., Flyfocus sp. z o.o, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tethered Drones Market Strategic Shifts
Power transmission architectures and regulatory frameworks are converging to expand addressable use cases beyond traditional defense applications into telecommunications and emergency response sectors.
Micro-tether power systems are modularizing across rotor configurations to enable rapid payload swapping in field conditions. Emergency response agencies in France and Germany deploy standardized ground stations with interchangeable sensor packages. This architecture compresses equipment procurement cycles by separating airframe investment from mission-specific payload expenditure.
FCC spectrum allocation proceedings for unmanned aerial system command links are reshaping frequency planning for tethered relay platforms. The industrial consequence mandates dual-band redundancy in new platform designs. Military buyers in the United States now require software-defined radio architectures to accommodate prospective reallocation.
Defense agencies are consolidating vendor relationships around full-service fleet management contracts rather than equipment-only procurement. Systems integrators displace direct manufacturer sales in NATO member states. France and the United Kingdom exhibit the fastest contract structure migration toward availability-based payment models.
Tethered Drones Market Segmentation
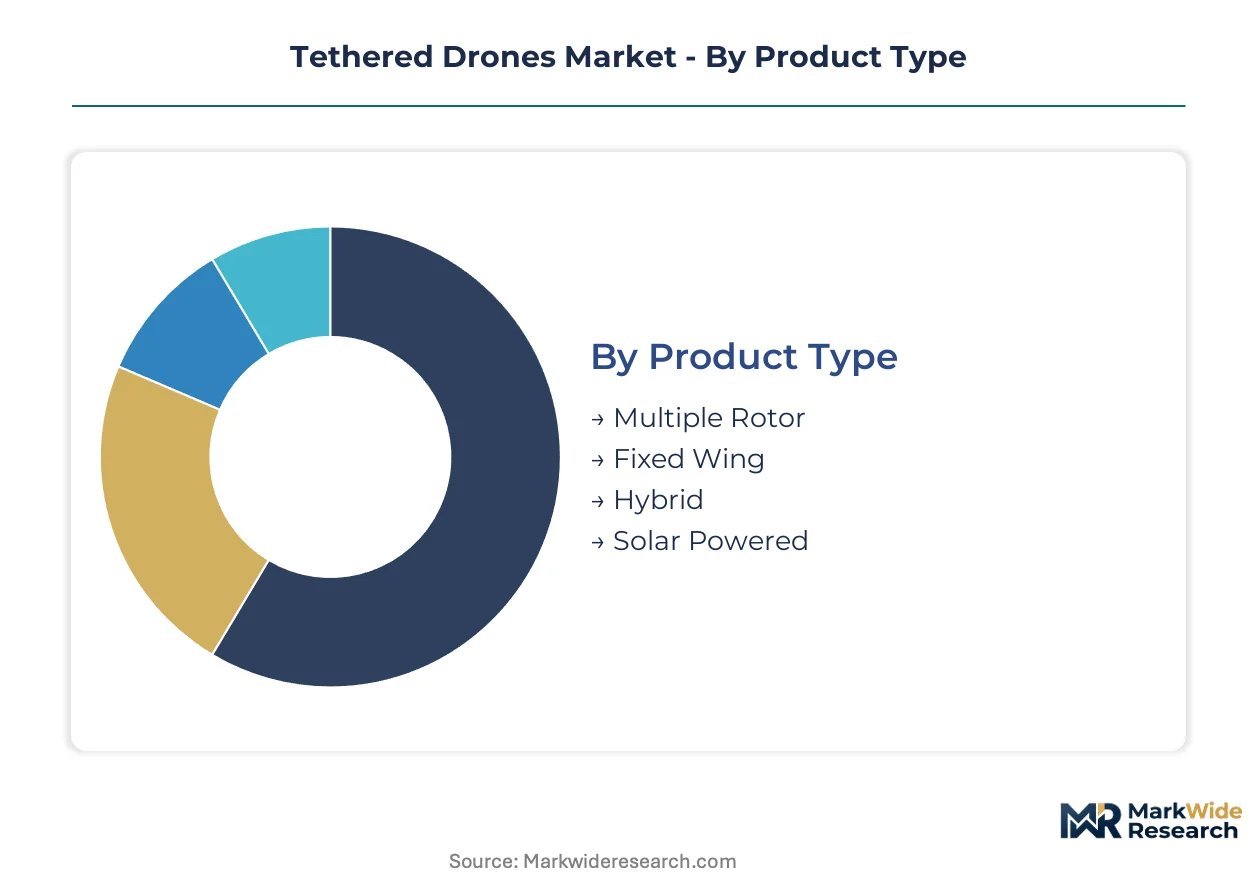
Tethered drone procurement splits across aerodynamic architecture, operational domain, and mission payload requirements. Each segmentation axis carries distinct regulatory footprints and margin profiles that reshape manufacturer positioning.
Product Type:
Rotor configuration determines power draw, tether diameter requirements, and wind resistance thresholds.
- Multiple Rotor:Vertical takeoff capability with precision hovering in confined airspace. Urban infrastructure inspection and maritime surveillance concentrate demand here, driven by NATO procurement for persistent harbor monitoring.
- Fixed Wing:Extended endurance through aerodynamic lift generation with reduced power consumption per hour aloft. Rural border patrol and linear infrastructure corridors favor this architecture for coverage efficiency.
- Hybrid:Combines VTOL convenience with forward-flight efficiency via tilt-rotor or tail-sitter mechanisms. Emergency response agencies in France deploy these for rapid deployment followed by loiter operations.
- Solar Powered:Photovoltaic wing surfaces supplement ground-station power for daylight mission extension. Experimental deployments concentrate in Middle Eastern climates with high insolation consistency.
Mature deployment sits with Multiple Rotor platforms. Newer deployment is concentrated in Hybrid configurations gaining share fastest.
End User:
Buyer sophistication and procurement cycle length create tiered margin structures across customer categories.
- Military:NATO STANAG interoperability mandates drive hardened communications and encrypted data protocols. Defense agencies in the United States and United Kingdom anchor volume through multi-year fleet availability contracts.
- Commercial:Telecommunications carriers require persistent aerial nodes for 5G densification without battery swap logistics. FAA Part 107 waivers enable beyond-visual-line-of-sight operations for cellular relay missions.
- Emergency Services:Fire departments and police units prioritize rapid deployment with standardized ground stations. RoHS compliance under EU Green Deal procurement rules qualifies tether systems for preferential treatment.
- Infrastructure:Port authorities and power grid operators conduct continuous asset monitoring without manned aerial patrol costs. Critical infrastructure protection budgets in India favor domestic assembly under PLI scheme incentives.
Revenue concentration rests with Military buyers. Procurement velocity is climbing fastest in Commercial telecommunications applications.
Deployment:
Environmental conditions dictate tether material selection and winch system corrosion ratings.
- Onshore:Standard copper-conductor tethers with moderate weatherproofing suffice for terrestrial operations. FAA certification pathways dominate deployment protocols in the United States.
- Offshore:Salt-resistant cable sheathing and stabilized marine platforms withstand corrosive maritime atmospheres. NATO naval procurement specifies these for fleet protection and harbor surveillance.
- Urban:Electromagnetic compatibility with dense RF environments requires shielded power transmission. European CE marking mandates govern electromagnetic emissions in city deployments.
- Rural:Extended tether lengths and higher-altitude operations demand reinforced mechanical strength. Border surveillance agencies in India prioritize these for remote frontier coverage.
Established volume flows through Onshore deployments. Regulatory momentum is building fastest around Urban corridor densification.
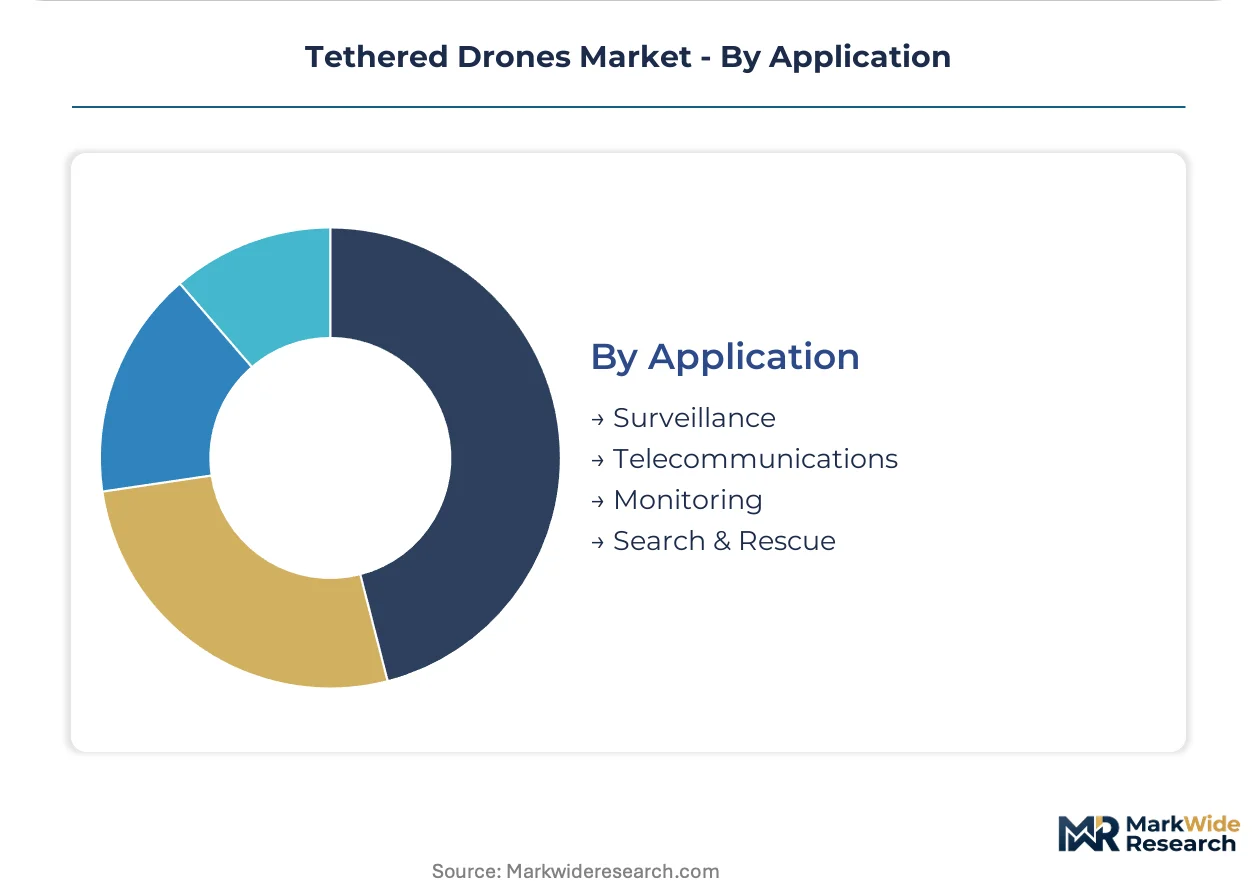
Application:
Mission payload determines sensor power requirements and data bandwidth specifications.
- Surveillance:Electro-optical and infrared sensor suites demand stable power for continuous target tracking. Military end users in NATO member states represent the primary procurement source.
- Telecommunications:Cellular relay equipment requires uninterrupted power for signal processing and backhaul transmission. 5G network densification drives carrier investment in persistent aerial nodes.
- Monitoring:Environmental and industrial sensor arrays collect continuous data streams for predictive maintenance. Power grid operators deploy these for transmission line thermal monitoring.
- Search & Rescue:Thermal imaging and loudspeaker payloads assist localization and communication with missing persons. Emergency services in Germany and France standardize ground stations for rapid field deployment.
Surveillance applications anchor current fleet utilization. Telecommunications represents the steepest expansion trajectory as cellular carriers densify coverage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Copper conductor supply chains in Arizona and Chile anchor tether manufacturing costs for North American and European defense contractors. Procurement patterns track these raw material nodes while regulatory divergence across FAA, EASA, and national military standards fragments certification pathways.
United States
Defense contracts through the Department of Defense and critical infrastructure protection budgets drive fleet expansion. FAA Part 107 waivers for beyond-visual-line-of-sight tethered operations reshape commercial deployment pathways for telecommunications carriers. Greater Boston and Washington DC corridors concentrate systems integrators serving NATO-aligned specifications.
Germany
Winch system manufacturing concentrates among precision motorized component specialists in Baden-Württemberg and Bavaria. CE marking and RoHS compliance under EU Green Deal procurement rules govern hardware distribution for emergency response fleets. Stuttgart anchors automotive-electronics crossover talent pools entering tether power management.
France
Emergency response agencies deploy standardized ground stations with interchangeable sensor packages under Ministry of Interior modernization programs. ANSM and CNIL data governance frameworks shape payload encryption requirements for surveillance missions. Toulouse and Paris-Saclay clusters concentrate aerospace systems integration expertise.
India
Border surveillance and port security agencies seek persistent aerial platforms under the PLI scheme for domestic manufacturing. BIS certification and DGFT import substitution policies favor joint ventures with established tether system providers. Gujarat and Maharashtra host emerging assembly operations for critical infrastructure protection fleets.
United Kingdom
Multi-year fleet availability contracts through the Ministry of Defence anchor NATO STANAG interoperability procurement. Availability-based payment models displace equipment-only sales faster here than in continental Europe. Bristol and Greater London concentrate systems integrators consolidating vendor relationships.
Tethered Drones Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue adjacent spaces in hydrogen-hybrid architectures and maritime-specific corrosion ratings. The vendor base clusters around three maturity tiers: defense-prime integrators, specialized tether-system pure-plays, and regional emergency-response equipment suppliers. Two strategic archetypes dominate: full-service fleet management contractors capturing NATO availability-based contracts, and component specialists controlling precision winch and power transmission subsystems. Competitive moves concentrate on strategic partnerships with copper cable manufacturers and backward integration into ground station software stacks.
Within the European specialist tier, Elistair Sas and Novadem represent tether-system pure-play positioning, while Hoverfly Technology Inc. anchors North American commercial sales through FAA-compliant platform architectures. These three exemplify geographic segmentation of regulatory expertise: French and German entities concentrate CE-marked emergency response deployments, while US-incorporated structures capture Part 107 waiver pathways. Perspective Robotics AG occupies a position bridging precision manufacturing heritage with software-defined radio architectures demanded by spectrum reallocation proceedings.
| Leading Market Players |
|---|
| COMSovereign Holding Corp. |
| Novadem |
| Elistair Sas |
| Menet Aero LLC. |
| Perspective Robotics AG |
| Hoverfly Technology Inc. |
| Dragonfly Pictures Inc. |
| Mistral Solutions Pvt. Ltd. |
| Flyfocus sp. z o.o |
| Others |
Value Chain & Pricing Dynamics
Precision electromechanical engineering talent pools in Baden-Württemberg and Bavaria create labor-cost differentials that widen pricing-tier spreads between German-engineered winch systems and Asian-assembled alternatives. FAA certification investment requirements for Part 107 waiver eligibility further stratify procurement budgets, separating NATO-compliant defense contractors from commercial telecommunications operators seeking basic persistent aerial platforms.
Pricing Analysis
Extended warranty and field-service bundling separate premium defense contracts from unbundled commercial equipment sales. Three-tier pricing structure across premium, standard, and economy levels tracks NATO STANAG certification grade and software-defined radio architecture inclusion. Cost compression in standard-tier commercial platforms intensifies because telecommunications carriers prioritize capital efficiency over hardened specifications. Emergency response agencies exhibit highest price sensitivity due to municipal budget constraints, while defense buyers demonstrate lowest sensitivity given multi-year fleet availability contract structures.
Supply Chain Analysis
Workforce availability for precision motorized component manufacturing concentrates in Germany, Switzerland, and select Japanese industrial clusters. Copper conductor supply draws from Arizona and Chilean mining operations, while optical fiber sheathing materials rest on specialized polymer production in South Korea and Germany. Single-source vulnerability pervades precision winch system procurement, with German and Swiss component specialists controlling critical subassembly supply. Distribution runs through systems integrators consolidating NATO vendor relationships rather than direct manufacturer channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where FAA Part 107 certification investment and NATO STANAG interoperability testing create barrier-to-entry moats favoring incumbent players with established regulatory pathways.
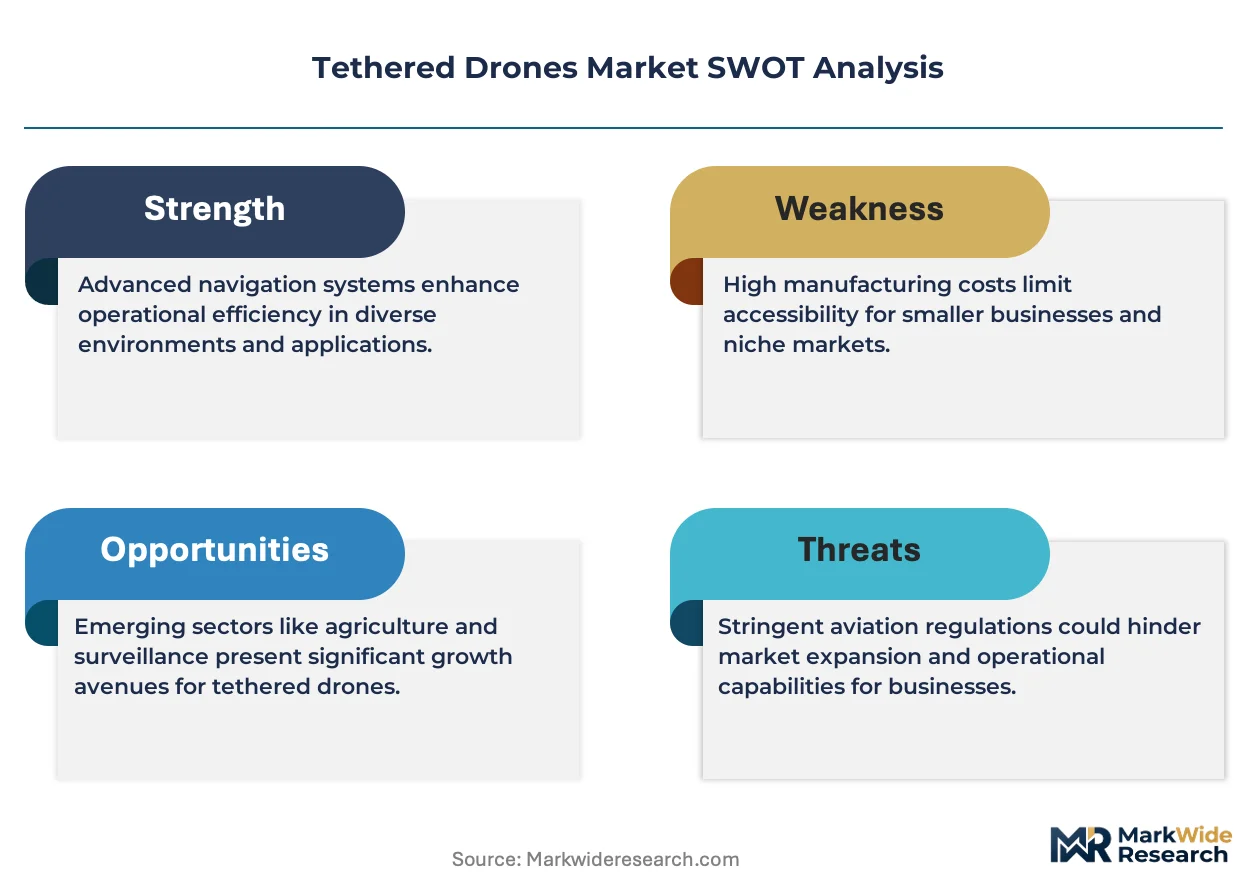
For Market Incumbents: Cement fleet availability contract structures with NATO defense agencies before competitor systems integrators consolidate vendor relationships. Backward integration into ground station software stacks reduces exposure to optical fiber substitution threats from free-space laser relay competitors. Priority investment in electromagnetic compatibility certification under STANAG 4370 preserves access to military procurement pipelines requiring radar co-location testing. For New Entrants and Emerging Players: Capture India's critical infrastructure protection segment through PLI scheme joint ventures with established tether system providers, where domestic assembly requirements favor partnership models over direct market entry. Target commercial telecommunications relay applications as the most penetrable vertical given FAA Part 107 waiver pathway standardization and carrier demand for persistent aerial nodes. Lead with hydrogen-hybrid power architecture differentiation to bypass incumbent copper-tether supply dependencies. For Investors and Strategic Acquirers: Re-rating potential sits with software-defined radio architecture specialists given FCC spectrum reallocation proceedings mandating dual-band redundancy in new platform designs. Long-term viability over the next decade hinges on regulatory compliance asset value as defense procurement consolidates around full-service fleet management contracts. Watch NATO availability-based payment model adoption velocity as the inflection signal distinguishing equipment-only vendors from integrated service providers.| Strategic Initiative | Industry Significance |
|---|---|
| FAA Part 107 Certification Investment | Unlocks beyond-visual-line-of-sight commercial operations for telecommunications carriers seeking persistent aerial relay nodes. |
| NATO STANAG Interoperability Compliance | Enables command-and-control integration with allied defense networks, qualifying platforms for multi-year fleet availability contracts. |
| Backward Integration into Ground Station Software | Captures recurring revenue streams and reduces vendor dependency in systems integrator-dominated procurement channels. |
| Hydrogen-Hybrid Power Architecture Development | Extends operational radius beyond fixed ground station constraints for maritime patrol and remote border surveillance applications. |
| Joint Venture Formation under India's PLI Scheme | Satisfies domestic assembly requirements for critical infrastructure protection budgets in Gujarat and Maharashtra manufacturing clusters. |
Study Parameters
Independent corroboration across defense procurement officers, commercial telecommunications network engineers, and emergency response fleet managers underwrites the qualitative findings. Primary interviews with FAA certification consultants, NATO standards compliance specialists, and precision winch system manufacturing executives combined with secondary validation from FAA Part 107 waiver databases, NATO STANAG documentation repositories, and EU CE marking registries. Bottom-up segment sizing across rotor configuration, end-user category, and deployment environment triangulates against top-down defense budget allocation analysis.
Comparable-period anchoring to historical NATO procurement cycles and commercial telecommunications infrastructure investment waves structured the forecast window. Modeled dimensions span aerodynamic architecture, operational domain, mission payload requirement, and regulatory compliance tier. CAGRs derive from segment-level demand elasticity analysis against defense agency electronic warfare resilience priorities and cellular network densification velocity. Industry-specific inputs include copper conductor price volatility indices and FCC spectrum allocation proceeding timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to optical fiber substitution technology maturation and hydrogen fuel cell power density improvements. Forecasts reflect documented assumptions regarding FAA regulatory pathway stability and NATO procurement standard continuity. Material deviation in copper tether cost trajectories or electromagnetic compatibility certification timeline extensions warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
UAV
North America Drone Software Market
UAV
Counter Drone System Market
UAV
Fixed Wing Military Drones Market
UAV
Europe Drones Market
UAV
Asia-Pacific Tactical UAV Market
UAV
Asia-Pacific Drone Motor Market
UAV
UAV Navigation Systems Market
UAV
Industrial Drones Market
UAV
UAV Market
UAV
Drone Inspection Service Market
UAV
Anti-Drone Technology Market
UAV
GCC Drone Pilot Training Market
UAV
Firefighting Drone Market
UAV
Drone Lens Market
UAV
Drones Market
UAV
Solar Powered Drones Market