
 Sensor Signal Conditioner (SSC) Ics Market | 2026-2036
Sensor Signal Conditioner (SSC) Ics Market Size, Share, and Industry Trends Forecast 2026-2036
Sensor Signal Conditioner (SSC) Ics Market Analytics
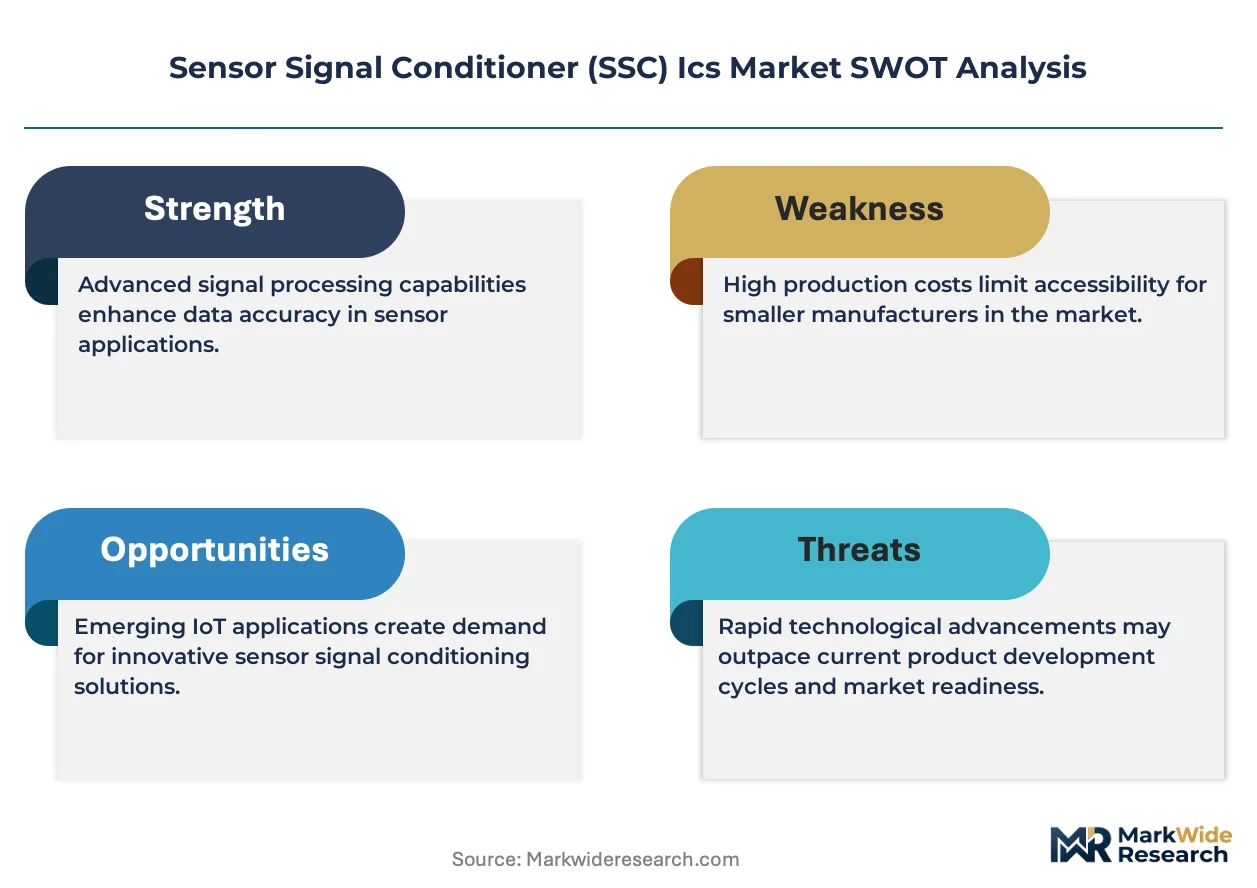
China's wafer fab capacity expansion is narrowing the geographic supply gap for precision analog ICs. Texas Instruments leverages its 300-mm Richardson fab to sustain cost leadership in high-volume SSC lines. Analog Devices anchors its position through proprietary iMEMS integration that differentiates its signal-conditioning portfolio. Renesas Electronics Corporation competes by embedding SSC functions inside its automotive MCU platforms, reducing board-level component count.
Sensor Signal Conditioner ICs are mixed-signal integrated circuits that amplify, filter, linearize, and convert raw sensor outputs into standardized electrical signals compatible with downstream acquisition systems, typically achieving input-referred noise below microvolt levels and offset drift under microvolts per degree Celsius. Their primary purpose is to bridge the gap between transducer-level signals and digital processing domains in precision measurement chains. Analog product types still occupy the largest revenue share in industrial temperature and pressure loops, though digital variants with embedded calibration engines are gaining ground in medical device applications where FDA traceability requirements demand deterministic error budgets. Voltage-mode technology leads in automotive wheel-speed and position sensing, while adaptive temperature compensation architectures are emerging fastest in environmental monitoring nodes deployed across distributed air-quality networks.
REACH and the EU Green Deal constrain halogenated flame retardants and conflict minerals in European-bound SSC modules, forcing substrate and molding compound reformulations that extend qualification cycles. The US FDA and EPA impose parallel demands on medical and industrial environmental sensor interfaces through electromagnetic compatibility and substance restriction rules that shape exportable product architectures. China's GB standards and MIIT directives add local certification layers for SSC ICs incorporated into domestic smart-manufacturing equipment. Stakeholders must monitor how diverging regional substance rules and functional safety grades fragment SKU portfolios and test load requirements.
Market Dynamics
Electric powertrain architectures are forcing SSC IC vendors to redesign offset drift specifications and temperature compensation circuits for battery management systems operating across wider thermal envelopes than internal combustion platforms.
Growth Catalysts
- EU Green Deal material mandates:REACH-compliant substrate reformulations are creating first-mover advantages for European packaging houses that pre-qualified halogen-free molding compounds ahead of competitors.
- Automotive wheel-speed sensing:Voltage-mode SSC architectures are capturing expanded socket opportunities as OEMs consolidate sensor fusion electronics into integrated corner modules.
- China's wafer fab expansion:Domestic 300-mm analog capacity additions are shortening lead times for precision SSC wafers serving industrial automation OEMs.
Market Restraints
- Specialized foundry concentration:Mature-node analog capacity at TSMC and GlobalFoundries remains tight, constraining multi-source strategies for high-reliability automotive grades.
- Palladium and gold wire bonding costs:Precious metal volatility in semiconductor interconnects is compressing gross margins on industrial temperature-loop products.
- MEMS co-integration complexity:Proprietary iMEMS processes limit second-source availability for medical device manufacturers requiring FDA traceability.
Strategic Opportunities
- India's PLI scheme for electronics:Local assembly incentives are attracting SSC module packaging investments for smart-manufacturing equipment serving domestic textile and pharmaceutical sectors.
- Environmental monitoring node deployment:Adaptive temperature compensation architectures are opening sockets in distributed air-quality networks requiring sub-ppm drift stability.
- FDA digital health pre-certification:Embedded calibration engines with deterministic error budgets are aligning with streamlined 510(k) pathways for wearable diagnostic devices.
Industry Challenges
- Mixed-signal design talent scarcity:Experienced analog IC architects capable of microvolt-level noise optimization are concentrated among a handful of design centers.
- Multi-regulatory SKU fragmentation:Divergent REACH, GB standards, and FDA electromagnetic compatibility requirements are multiplying qualification test matrices without volume scaling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sensor Signal Conditioner (SSC) Ics Market |
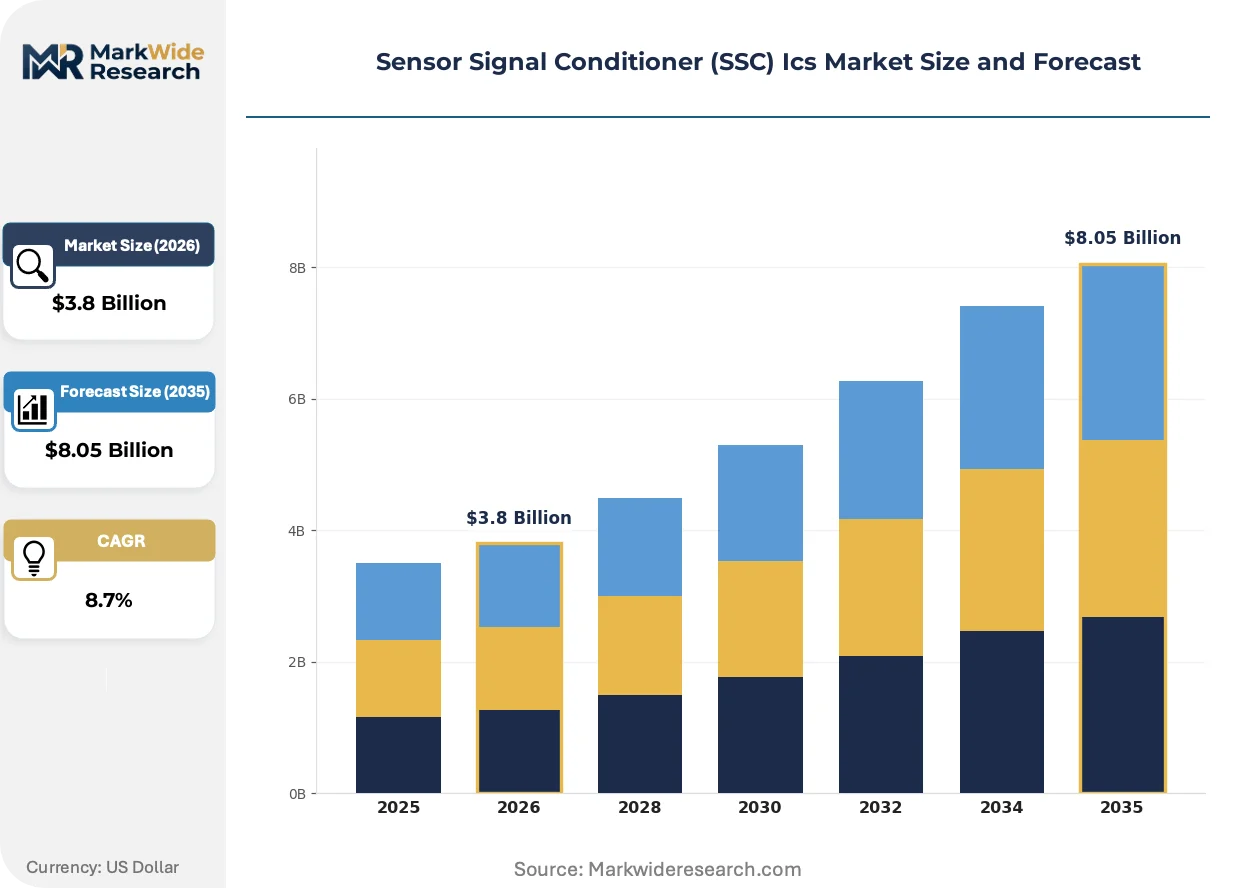
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analog, Digital, Hybrid, Wireless Technology: Voltage Mode, Current Mode, Temperature Compensation, Adaptive Application: Industrial Automation, Medical Devices, Automotive Sensors, Environmental Monitoring End User: Manufacturers, OEMs, Research Institutions, System Integrators |
| Companies Covered | Texas Instruments, Analog Devices, Renesas Electronics Corporation, Infineon Technologies, NXP Semiconductors, STMicroelectronics, Microchip Technology, Maxim Integrated, iC-Haus GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sensor Signal Conditioner (SSC) Ics Market Evolving Landscape
SSC architectures are converging around digitally assisted analog cores that embed calibration intelligence while preserving the noise performance of pure analog front ends. This convergence is compressing traditional boundaries between discrete signal conditioning and system-on-chip integration.
Digital calibration engines with embedded temperature sensors and EEPROM-stored correction coefficients are hybridizing with conventional chopper-stabilized amplifiers. Medical device manufacturers are adopting these hybrid architectures fastest, driven by FDA traceability requirements for deterministic error budgets in continuous glucose monitors and infusion pumps. The technology is compressing the traditional separation between front-end analog conditioning and downstream digital compensation.
REACH substance restrictions on halogenated flame retardants are forcing substrate and molding compound reformulations that extend qualification cycles by six to nine months. European automotive semiconductor clusters around Munich and Ingolstadt are absorbing these delays through captive testing infrastructure. High-reliability industrial grades bound for European export markets are most affected, with vendors maintaining parallel legacy and compliant material flows.
Automotive OEM procurement departments are consolidating SSC sourcing through direct tier-one partnerships rather than distributed distributor channels. Tier-one sensor module suppliers are capturing expanded value-add scope, displacing traditional broadline distribution for high-volume wheel-speed and position sensing applications. Germany's automotive semiconductor procurement concentration exemplifies this shift, with Ingolstadt-based OEMs negotiating multi-year die supply agreements directly with analog IC designers.
Sensor Signal Conditioner (SSC) Ics Market Segmentation
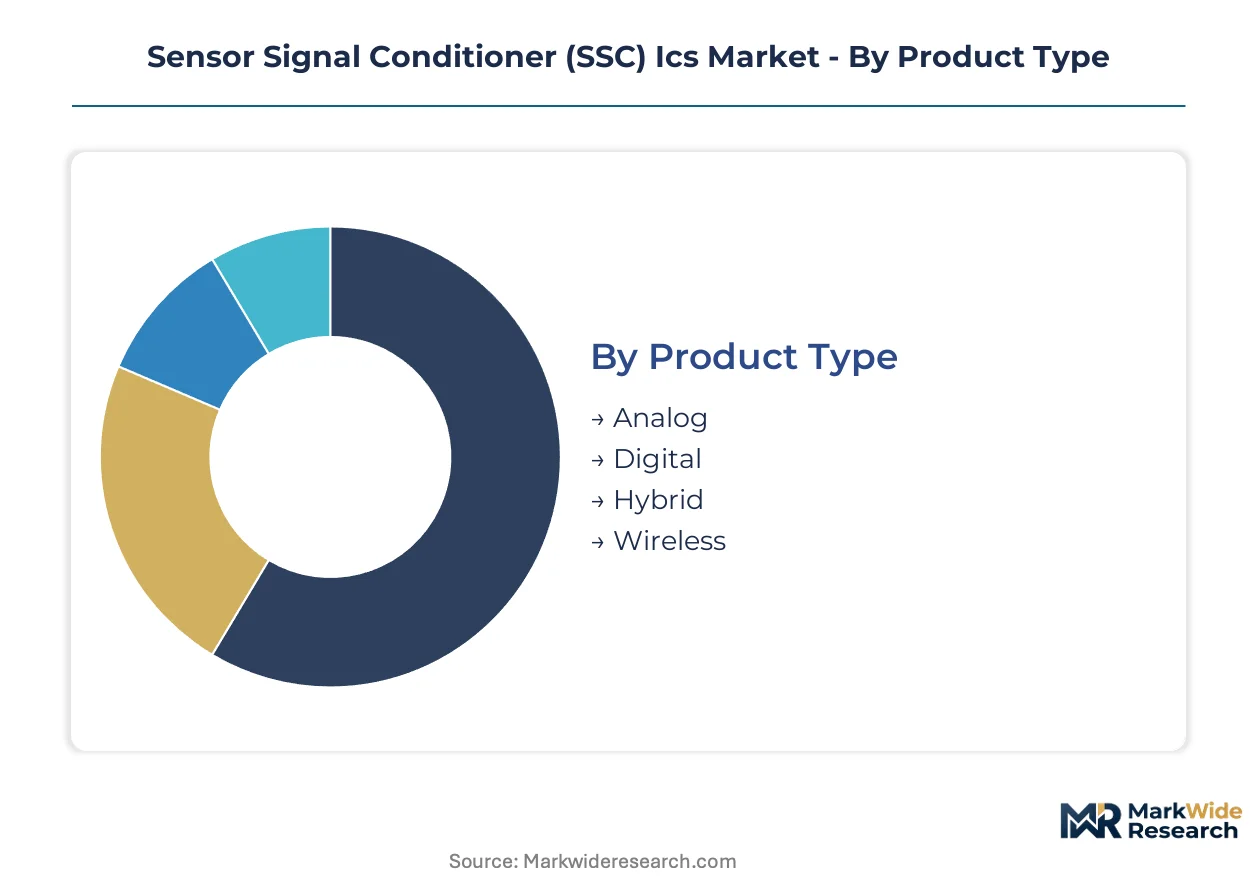
SSC IC segmentation reflects divergent paths between mature analog architectures and digitally assisted hybrid cores. Procurement patterns split sharply across automotive, medical, and industrial automation verticals with distinct noise, drift, and calibration requirements.
Product Type:
Mature analog variants anchor established industrial loops while digital and hybrid architectures accelerate in regulated medical environments.
- Analog:Chopper-stabilized amplifiers with microvolt-level input-referred noise dominate temperature and pressure measurement chains in process industries. Demand concentrates in Germany's automotive semiconductor cluster around Munich and Ingolstadt for wheel-speed sensing modules requiring sub-microvolt offset drift.
- Digital:Embedded calibration engines with EEPROM-stored correction coefficients serve FDA-traceable medical devices including continuous glucose monitors and infusion pumps. Deterministic error budgets and pre-certification alignment are accelerating procurement from wearable diagnostic OEMs.
- Hybrid:Digitally assisted analog cores preserve front-end noise performance while embedding intelligence for multi-sensor fusion.
- Wireless:Integrated RF transceivers with on-chip conditioning enable distributed environmental monitoring nodes.
Analog handles the majority of throughput; Digital is the fastest mover on share.
Technology:
Voltage-mode dominance in automotive sensing contrasts with adaptive architectures gaining traction in distributed air-quality networks.
- Voltage Mode:Differential amplifier stages with rail-to-rail output swing capture consolidated socket opportunities as OEMs integrate sensor fusion electronics into corner modules. Procurement runs through direct tier-one partnerships rather than distributor channels for high-volume wheel-speed applications.
- Current Mode:Transimpedance architectures excel in photodiode interface circuits for industrial spectroscopy.
- Temperature Compensation:On-chip PTAT references and polynomial correction circuits stabilize offset drift across battery management thermal envelopes in electric powertrains.
- Adaptive:Real-time drift correction algorithms with machine-learned coefficients are opening sockets in sub-ppm stability air-quality networks deployed across European urban monitoring grids.
Voltage Mode maintains the largest installed base; Adaptive is climbing the fastest on application expansion.
Application:
Automotive electrification and medical device regulation are reshaping demand concentration away from traditional industrial automation.
- Automotive Sensors:Battery management systems operating across wider thermal envelopes than internal combustion platforms demand redesigned offset specifications and compensation circuits. REACH-compliant substrate reformulations from European packaging houses are qualifying halogen-free molding compounds for high-reliability grades.
- Medical Devices:FDA electromagnetic compatibility requirements and traceability mandates favor hybrid architectures with deterministic error budgets in infusion pumps and diagnostic wearables.
- Industrial Automation:Mature-node analog capacity constraints at TSMC and GlobalFoundries are limiting multi-source strategies for temperature-loop products facing palladium and gold wire bonding cost pressure.
- Environmental Monitoring:Distributed node deployments require adaptive temperature compensation for sub-ppm drift stability in air-quality sensing networks.
Automotive Sensors commands the dominant revenue position; Medical Devices is gaining share fastest on regulatory tailwinds.
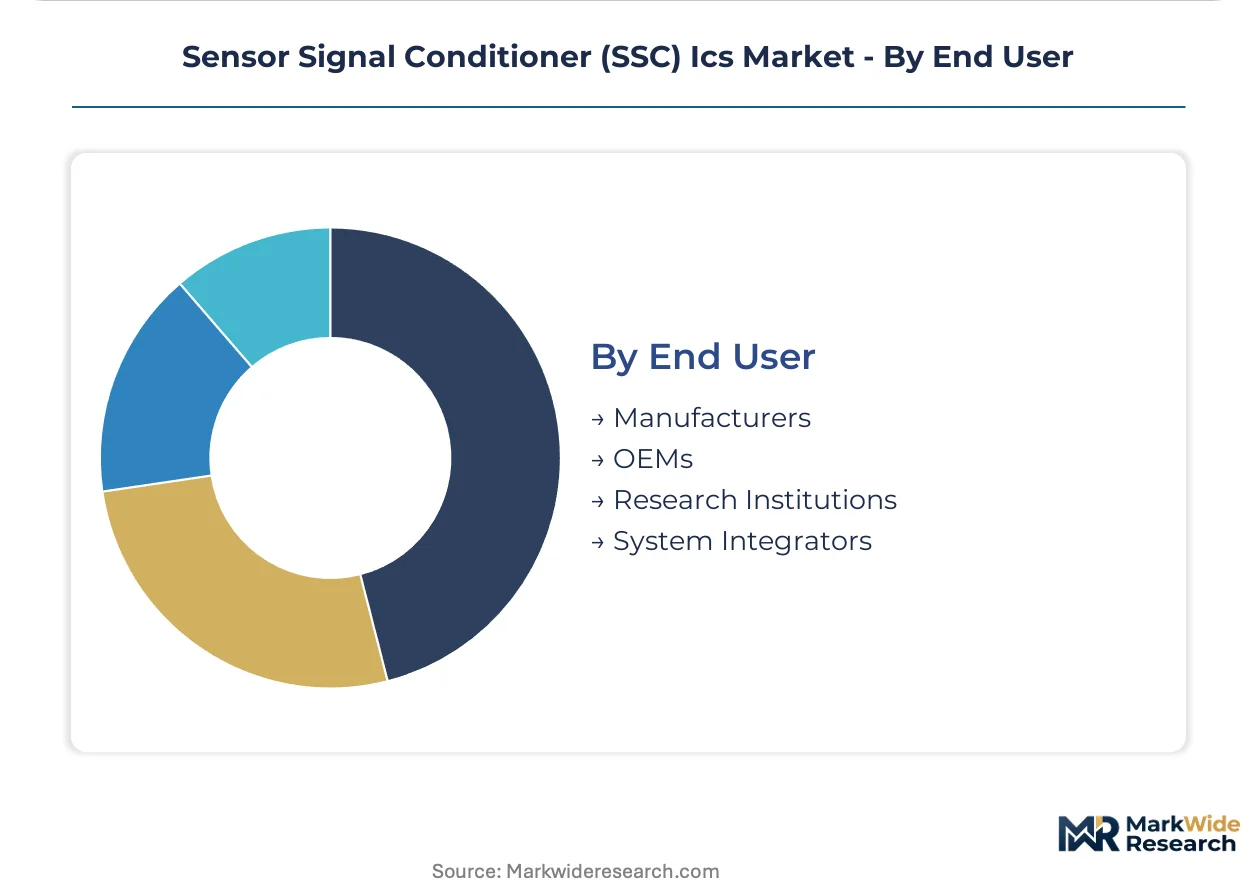
End User:
Tier-one consolidation in automotive contrasts with fragmented procurement across research and system integration channels.
- OEMs:Direct multi-year die supply agreements with analog IC designers are displacing traditional distribution for high-volume sensing applications. Ingolstadt-based automotive OEMs exemplify this consolidation through captive procurement negotiations.
- Manufacturers:Industrial automation OEMs in China are benefiting from domestic 300-mm analog capacity additions shortening lead times for precision SSC wafers.
- System Integrators:Module-level procurement with embedded calibration engines serves smart-manufacturing equipment in India's textile and pharmaceutical sectors under PLI scheme incentives.
- Research Institutions:Low-volume custom specifications for experimental sensor platforms face extended qualification cycles from REACH substance restriction compliance.
OEMs drive the highest absolute volume; System Integrators are expanding most quickly on regional manufacturing incentives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH compliance and the EU Green Deal anchor European demand concentration, while automotive electrification and domestic fab expansion reshape procurement patterns across Germany, China, the United States, Japan, and India.
Germany
Automotive sensor deployment in electric powertrains accelerates SSC IC procurement for battery management systems. ECHA substance restrictions under REACH force halogen-free molding compound reformulations that extend qualification cycles. Munich and Ingolstadt anchor Europe's densest automotive semiconductor cluster, with OEMs negotiating direct multi-year die supply agreements.
China
Domestic 300-mm analog capacity additions shorten lead times for precision SSC wafers serving industrial automation OEMs. MIIT directives and GB standards impose local certification layers for SSC ICs incorporated into smart-manufacturing equipment. Yangtze River Delta fabrication complexes narrow the geographic supply gap for precision analog ICs previously sourced from offshore foundries.
United States
FDA electromagnetic compatibility requirements and EPA substance restriction rules shape exportable medical and environmental sensor interface architectures. Richardson, Texas hosts expanded 300-mm fab capacity sustaining cost leadership in high-volume SSC lines. Greater Boston and Silicon Valley design centers concentrate mixed-signal talent for microvolt-level noise optimization.
Japan
METI industrial policy supports automotive MCU platform integration that embeds SSC functions and reduces board-level component count. JIS standards and PMDA medical device regulations favor deterministic error budgets in diagnostic equipment. Kansai and Nagoya manufacturing corridors supply tier-one sensor module vendors with high-reliability grades.
India
PLI scheme incentives attract SSC module packaging investments for smart-manufacturing equipment serving domestic textile and pharmaceutical sectors. BIS certification requirements add compliance layers for industrial environmental sensor interfaces. Maharashtra and Karnataka absorb expanded system integrator procurement with embedded calibration engines.
Sensor Signal Conditioner (SSC) Ics Market Competitive Landscape
Capability concentration sits with one tier; scale advantage sits with another. The vendor base organizes around three distinct strata: diversified analog giants with captive fab networks, automotive-focused semiconductor platforms with embedded integration roadmaps, and precision specialists serving regulated medical and industrial niches. Competitive positioning hardens through M&A consolidation of mixed-signal design teams and strategic foundry partnerships that secure mature-node analog capacity.
Among diversified analog suppliers, Texas Instruments and Analog Devices exemplify scale-driven archetypes with broad signal-conditioning portfolios. Renesas Electronics Corporation occupies a position within the automotive-integrated tier, representing the MCU-embedded SSC convergence path. These three anchors illustrate how procurement consolidation favors vendors with either captive manufacturing depth or platform-level integration capabilities.
| Leading Market Players |
|---|
| Texas Instruments |
| Analog Devices |
| Renesas Electronics Corporation |
| Infineon Technologies |
| NXP Semiconductors |
| STMicroelectronics |
| Microchip Technology |
| Maxim Integrated |
| iC-Haus GmbH |
| Others |
Value Network & Pricing Analysis
TSMC and GlobalFoundries mature-node analog concentration in Taiwan and the United States anchors upstream supply, concentrating margin capture among automotive OEMs in Germany's Ingolstadt cluster and medical device manufacturers demanding FDA-traceable deterministic error budgets.
Pricing Analysis
Geographic price spreads between European REACH-compliant grades and standard industrial variants reflect six-to-nine month qualification cycle premiums absorbed by Munich-based packaging houses. Three-tier pricing structure across automotive-grade, medical-grade, and industrial-grade certification levels segments buyer tiers, with industrial automation OEMs in China exhibiting highest price sensitivity due to domestic 300-mm fab capacity expansion. Pricing pressure stems from palladium and gold wire bonding volatility compressing gross margins on temperature-loop products, while automotive OEMs negotiating direct multi-year die supply agreements show lowest sensitivity due to captive volume commitments.
Supply Chain Analysis
Tariff exposure between United States and China semiconductor equipment restrictions dominates supply chain risk assessment for SSC IC vendors dependent on dual-source wafer strategies. Manufacturing concentrates in Taiwan, South Korea, and the United States for precision analog fabrication, with raw material dependencies on high-purity silicon substrates, halogen-free molding compounds, and precious metal interconnects. Single-source vulnerability persists for proprietary iMEMS co-integration processes limiting second-source availability for medical device manufacturers. Distribution runs through direct tier-one partnerships displacing traditional broadline channels for high-volume automotive sensing applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment through REACH compliance and FDA traceability requirements creates substantial switching costs that defend incumbent positions against emerging challengers lacking qualified material flows and deterministic error budget architectures.
For Market Incumbents: Harden defensive moats by deepening backward integration into halogen-free substrate qualification at captive European testing infrastructure and securing multi-year die supply agreements with Ingolstadt-based automotive OEMs before emerging analog suppliers complete REACH-compliant reformulations. Threat substitution from digitally assisted hybrid architectures demands accelerated R&D in embedded calibration engines to preserve socket position in FDA-traceable medical devices. For New Entrants and Emerging Players: India's PLI scheme electronics incentives represent the most penetrable geographic entry point, offering local packaging investment subsidies for smart-manufacturing equipment serving domestic textile and pharmaceutical sectors underserved by established European and East Asian suppliers. White-space targets include adaptive temperature compensation architectures for distributed air-quality networks requiring sub-ppm drift stability, and hybrid SSC modules for wearable diagnostic OEMs seeking streamlined 510(k) pre-certification pathways. Go-to-market execution should anchor on system integrator partnerships rather than direct OEM negotiations. For Investors and Strategic Acquirers: Capital is best deployed toward precision analog specialists with captive mixed-signal design teams capable of microvolt-level noise optimization and existing FDA electromagnetic compatibility qualification. Long-term viability across the analysis window favors vendors with proven REACH-compliant material flows and automotive MCU platform integration roadmaps. Acquisition screening should prioritize targets with embedded iMEMS processes or halogen-free molding compound pre-qualification. The signal to watch is OEM procurement department consolidation away from distributor channels toward direct tier-one partnerships, indicating preferred supplier status crystallization.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Material Pre-Qualification | European packaging houses with halogen-free molding compound validation capture six-to-nine month lead time advantages over lagging competitors. |
| Direct Tier-One Partnership Consolidation | Automotive OEM procurement departments in Germany's Ingolstadt cluster displace distributor channels through multi-year die supply agreements. |
| Embedded Calibration Engine Development | Hybrid architectures with deterministic error budgets align with FDA pre-certification pathways for continuous glucose monitor and infusion pump sockets. |
| Domestic 300-mm Fab Capacity Expansion | China's Yangtze River Delta fabrication complexes shorten lead times for precision SSC wafers serving industrial automation OEMs. |
| iMEMS Co-Integration Investment | Proprietary processes limit second-source availability and defend margin position in medical device applications requiring traceability. |
Research Methodology
Operator-level perspectives from analog IC design architects, automotive Tier 1 supplier procurement managers, medical device regulatory affairs leads, and semiconductor packaging engineers anchored the qualitative base for this analysis. Primary fieldwork combined structured interviews with secondary validation across SEC 10-K filings, ECHA REACH substance restriction updates, FDA 510(k) premarket notification databases, and MIIT GB standards directives. Bottom-up wafer demand modeling and top-down automotive sensor deployment forecasts were triangulated to cross-verify volume assumptions.
Scenario-bracketing around electric powertrain adoption curves and REACH compliance timelines framed the analytical approach across the projection horizon. Segmentation dimensions modeled include product type analog-digital-hybrid split, technology voltage-mode versus adaptive compensation architectures, application vertical automotive-medical-industrial-environmental, and end-user procurement channel concentration. CAGRs were derived from installed base erosion rates and new socket creation in battery management systems and wearable diagnostics. Industry-specific forecast inputs incorporated palladium price volatility indices and European packaging house qualification cycle data.
Practitioners should monitor REACH substance restriction expansion beyond halogenated flame retardants, FDA digital health pre-certification pathway revisions, and TSMC mature-node analog capacity allocation shifts for early signals requiring forecast adjustment. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Europe Optical Sensors Market
Sensors and Controls
Turbomachinery Control Systems Market
Sensors and Controls
Smart Thermometer Market
Sensors and Controls
Optical Chemical Sensor Market
Sensors and Controls
Silicon-Based Fingerprint Sensors Market
Sensors and Controls
Smart Pressure Sensors Market
Sensors and Controls
United States Chemical Sensors Market
Sensors and Controls
Absolute Encoders Market
Sensors and Controls
Thermometer Market
Sensors and Controls
Ingestible Sensor Market
Sensors and Controls
Electrochemical Sensor Market
Sensors and Controls
North America Temperature Sensor Market
Sensors and Controls
Meteorological Equipment Market
Sensors and Controls
Force Sensor Market
Sensors and Controls
Global Sensors Market
Sensors and Controls
Middle East and Africa MEMS and Sensors Market