
 Global Wireless Brain Sensors Market | 2026-2036
Global Wireless Brain Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Global Wireless Brain Sensors Market Foresight
Modular sensor-headset bundling is decoupling hardware from software subscription tiers, forcing buyers to evaluate total cost of ownership across multi-year contracts. EMOTIV leverages direct-to-researcher distribution to sustain margin control in cognitive assessment deployments. Medtronic anchors hospital system sales through its established neurosurgical device relationships, while Neuroelectrics competes on channel flexibility with smaller research institutions.
Wireless brain sensors are portable electrophysiological devices that acquire neural signals—typically in the 0.5-100 Hz frequency range for EEG—through scalp or intracranial electrodes and transmit data via radio protocols to processing units. These instruments serve clinical diagnostics, neuroscientific research, and emerging human-machine interface applications by eliminating tethered laboratory constraints. EEG sensors dominate current shipment volumes due to mature manufacturing economics and broad indication coverage, while fNIRS sensors represent the fastest-expanding category as functional neuroimaging demand spreads beyond academic centers into sports science labs and cognitive therapy practices. Brain-computer interface applications command premium pricing tiers because regulatory validation requirements and specialized signal-processing firmware create defendable margin pools.
The FDA breakthrough device program compresses premarket review timelines for novel neural sensing platforms, while the EU MDR recasts wireless neurodiagnostics as Class IIa or IIb devices with intensified clinical evidence requirements. Japan's PMDA maintains distinct software-as-medical-device guidance that shapes firmware update protocols for Bluetooth-enabled headsets sold into Japanese neurorehabilitation centers. Stakeholders must monitor divergence between FDA's risk-based digital health enforcement discretion and EMA's emerging neurotechnology qualification pathway to avoid duplicative validation spend.
Market Dynamics
Modular sensor-headset architectures are fragmenting procurement decisions across hardware, firmware, and analytics layers, forcing buyers to negotiate multi-year total cost of ownership rather than upfront equipment pricing. This structural decoupling is compressing margins for integrated device manufacturers while creating entry points for specialized signal-processing software vendors.
Growth Catalysts
- DARPA neurotechnology funding:US defense research programs concentrate capital for non-invasive neural sensing platforms, accelerating validation timelines for wearable EEG systems in military and civilian dual-use applications.
- EU MDR Class IIa/IIb reclassification:Intensified clinical evidence requirements for wireless neurodiagnostics are professionalizing manufacturing standards, filtering out low-quality entrants and consolidating procurement toward validated suppliers.
- fNIRS manufacturing scale-up:Functional near-infrared spectroscopy production economics are improving as sports science labs and cognitive therapy practices expand demand beyond academic research centers.
Market Restraints
- Specialized electrode material costs:Silver-silver chloride and dry polymer electrode substrates face price volatility from precious metals markets, compressing hardware margins at volume shipment tiers.
- Bluetooth protocol fragmentation:Regional spectrum allocation differences between FCC, CE, and PMDA jurisdictions force firmware branching, increasing validation overhead for globally distributed headsets.
- EEG-fNIRS substitution pressure:Functional neuroimaging modalities compete for the same research and clinical budgets, with fNIRS gaining ground in motion-tolerant applications where EEG artifact rejection proves costly.
Strategic Opportunities
- Japanese neurorehabilitation centers:PMDA software-as-medical-device guidance creates first-mover advantage for vendors establishing firmware update protocols compliant with Japanese Bluetooth-enabled device standards.
- Brain-computer interface premium tier:Regulatory validation requirements and specialized signal-processing firmware create defendable margin pools distinct from commoditized research-grade EEG hardware.
- Direct-to-researcher distribution:Channel disintermediation bypasses traditional neurosurgical device sales networks, enabling margin control and faster iteration cycles for cognitive assessment deployments.
Industry Challenges
- Signal processing talent scarcity:Firmware engineers with expertise in real-time neural artifact rejection algorithms command premium compensation, constraining R&D expansion at mid-cap device developers.
- Multi-jurisdiction certification timelines:Parallel FDA breakthrough device and EU MDR conformity assessment pathways require duplicative clinical evidence generation, delaying commercial launch windows.
- Legacy hospital IT integration:Wireless brain sensor data streams must interface with established electronic health record architectures, creating implementation friction in hospital system sales cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Wireless Brain Sensors Market |
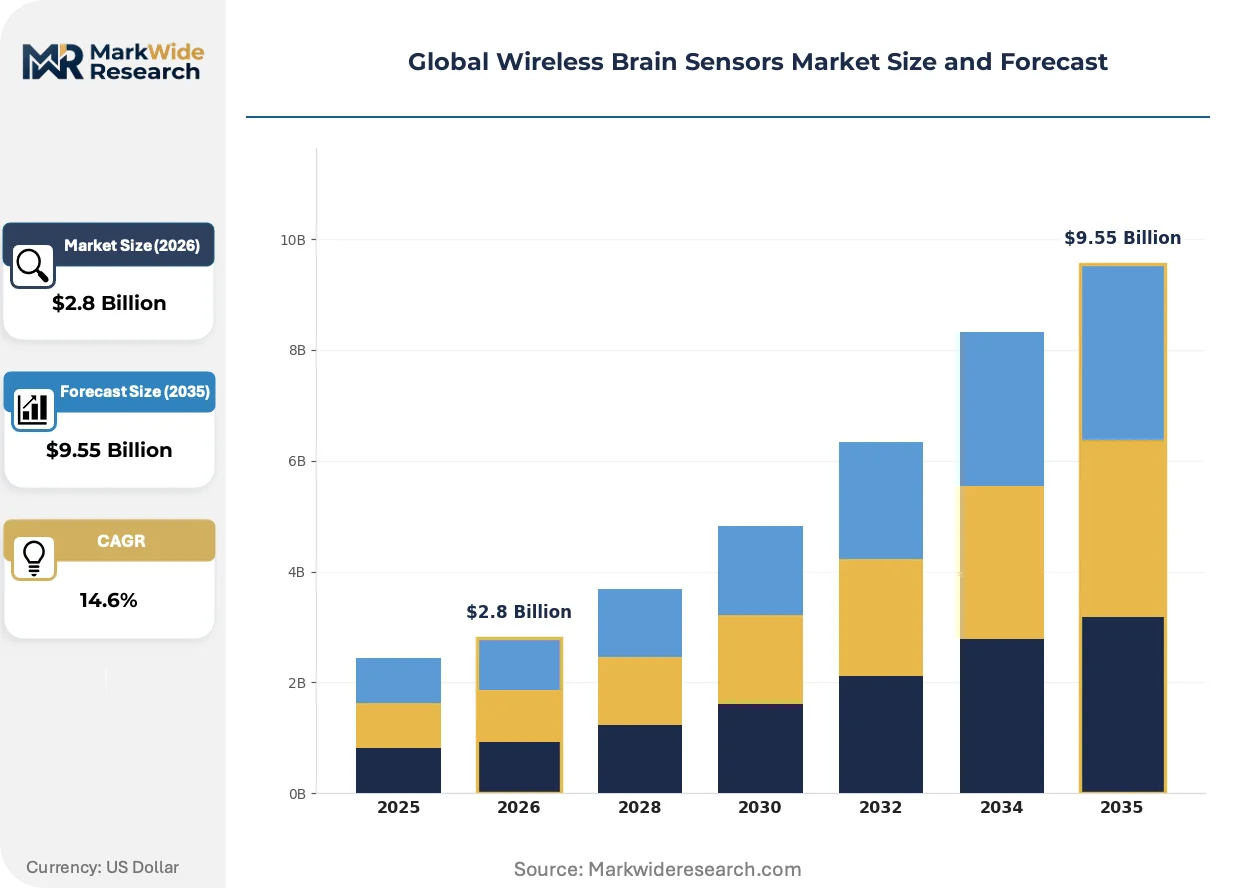
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $9.55 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: EEG Sensors, MEG Sensors, fNIRS Sensors, ECoG Sensors Technology: Bluetooth, Wi-Fi, Zigbee, LoRaWAN, Ultra-Wideband Application: Neurofeedback Training, Cognitive Assessment, Brain-Computer Interface, Sleep Monitoring, Epilepsy Detection End User: Research Institutions, Neurorehabilitation Centers, Cognitive Therapists, Sports Science Labs |
| Companies Covered | EMOTIV, Advanced Brain Monitoring, Inc., NeuroSky, Neuroelectrics, Neuronetrix Solutions, LLC, Medtronic, Natus Medical Incorporated, Koninklijke Philips N.V., Cadwell Industries, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Wireless Brain Sensors Market Shifts & Advancements
Dry electrode arrays and onboard edge computing are compressing the traditional laboratory-to-field boundary for neural signal acquisition, enabling ambulatory monitoring scenarios previously constrained by gel-based preparation requirements and tethered amplification.
Soft polymer dry electrodes with micro-needle architectures are eliminating conductive gel preparation steps while maintaining impedance stability across extended wear periods. Sports science programs at Australian and German universities are deploying these systems for field-based cognitive load monitoring during athletic performance. This hardware evolution is decentralizing neural data collection from centralized neuroimaging suites into distributed training facilities and home-based rehabilitation settings.
EMA's emerging neurotechnology qualification pathway is diverging from FDA's risk-based digital health enforcement discretion, creating regulatory friction for vendors pursuing parallel US-European market entry. The pathway mandates adaptive trial designs for novel neural sensing platforms, extending premarket validation timelines. Brain-computer interface developers are responding by sequencing regulatory submissions to prioritize the jurisdiction with clearer predicate device precedents.
Research institutions are unbundling hardware procurement from analytics subscriptions, negotiating multi-year software licenses independent of sensor refresh cycles. This purchasing pattern disrupts traditional bundled device-and-software contracts that anchored hospital system sales. The shift is most pronounced in German and Dutch neurorehabilitation centers, where reimbursement framework evolution creates budgetary incentives to optimize total cost of ownership across extended deployment horizons.
Global Wireless Brain Sensors Market Segmentation
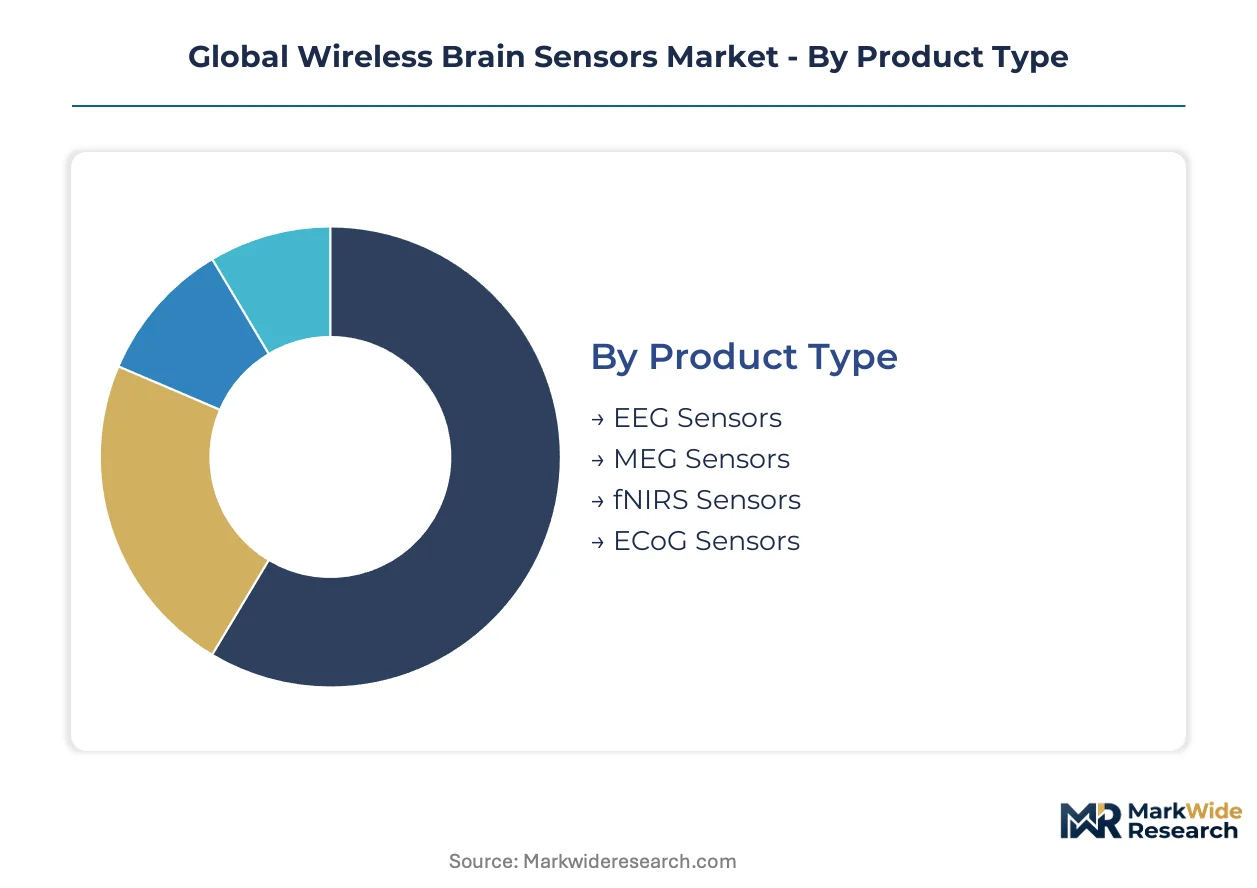
Wireless brain sensors fragment across hardware architectures, radio protocols, clinical applications, and institutional buyer types. Procurement patterns diverge sharply between research-grade flexibility demands and clinical-grade validation requirements.
Product Type:
Standardized electrode arrays compete with modular, application-specific configurations across this hardware layer.
- EEG Sensors:Scalp-mounted electrodes acquire cortical electrical activity in the 0.5-100 Hz range through dry polymer or silver-silver chloride substrates. Demand concentrates in US research institutions where DARPA-funded programs validate wearable systems for dual-use cognitive monitoring. Manufacturing scale and mature regulatory predicates position this segment as the volume anchor.
- fNIRS Sensors:Functional near-infrared spectroscopy emitters and detectors measure hemodynamic response through optical absorption at multiple wavelengths. German neurorehabilitation centers are expanding procurement as reimbursement frameworks evolve to cover functional neuroimaging for motor recovery assessment. This modality gains ground in motion-tolerant applications where EEG artifact rejection proves costly.
- MEG Sensors:Magnetoencephalography systems detect magnetic fields generated by neural currents through superconducting quantum interference devices. Academic medical centers in Japan and the Netherlands maintain limited deployments for pre-surgical epilepsy mapping.
- ECoG Sensors:Electrocorticography grids require craniotomy placement for high-resolution intracranial recording. Epilepsy surgery programs at select US and German hospitals represent the constrained addressable market.
Leading the category by volume: EEG Sensors. Expanding most quickly: fNIRS Sensors.
Technology:
Radio protocol selection trades off bandwidth, power consumption, and regulatory clearance complexity across jurisdictions.
- Bluetooth:The 2.4 GHz ISM band protocol dominates headset deployments through mature silicon economics and smartphone interoperability. FDA breakthrough device submissions for brain-computer interfaces overwhelmingly specify Bluetooth Low Energy for tether-free patient mobility.
- Wi-Fi:Higher throughput enables real-time streaming of multi-channel neural data to cloud analytics platforms. Research institutions in Australia and South Korea deploy Wi-Fi-enabled arrays for distributed laboratory architectures where local edge computing is unavailable.
- Zigbee:Mesh networking topology suits multi-node sensor arrays with low duty-cycle requirements. Industrial research consortia in Germany evaluate Zigbee for factory-floor cognitive load monitoring of equipment operators.
- LoRaWAN:Sub-GHz long-range protocols enable rural and ambulatory deployments beyond hospital Wi-Fi coverage. Pilot programs in Scandinavian telemedicine initiatives test LoRaWAN for home-based epilepsy monitoring.
- Ultra-Wideband:Centimeter-precision spatial localization combined with high data rates supports immersive virtual reality neurofeedback systems. Premium-tier brain-computer interface developers in the US and Switzerland specify UWB for low-latency closed-loop applications.
Dominating procurement decisions: Bluetooth. Steepest expansion trajectory: Ultra-Wideband.
Application:
Clinical validation requirements and reimbursement status create tiered margin pools across use cases.
- Brain-Computer Interface:Signal-processing firmware for neural decoding commands premium pricing tiers. FDA breakthrough device designation compresses premarket timelines for developers targeting motor-impaired patient populations.
- Cognitive Assessment:Standardized protocols for attention, memory, and executive function evaluation drive volume in educational and occupational health settings. Direct-to-researcher distribution models bypass traditional neurosurgical sales networks.
- Neurofeedback Training:Real-time operant conditioning of brain activity supports anxiety, ADHD, and peak performance applications. Sports science labs in Germany and Australia deploy dry electrode systems for field-based cognitive load monitoring.
- Sleep Monitoring:Polysomnography alternatives face reimbursement compression in US sleep clinic consolidation. Consumer-grade wearable integration threatens research-grade hardware margins.
- Epilepsy Detection:Seizure forecasting algorithms require long-term ambulatory validation. EU MDR Class IIb reclassification intensifies clinical evidence requirements for wireless diagnostic claims.
Commanding highest unit margins: Brain-Computer Interface. Gaining share fastest: Neurofeedback Training.
End User:
Budget authority and procurement sophistication vary dramatically across institutional buyer types.
- Research Institutions:Principal investigators negotiate unbundled hardware and software contracts with multi-year refresh cycles. German and Dutch centers optimize total cost of ownership across extended deployment horizons.
- Neurorehabilitation Centers:Reimbursement framework evolution in Germany creates budgetary incentives for functional neuroimaging procurement. PMDA software-as-medical-device guidance shapes firmware update protocols for Japanese facilities.
- Cognitive Therapists:Solo and small-group practices prioritize plug-and-play systems with minimal electrode preparation. Channel flexibility from specialized vendors competes with established neurosurgical device relationships.
- Sports Science Labs:Australian and German university programs deploy dry electrode arrays for athletic performance monitoring. Motion-tolerant hardware specifications override clinical-grade signal fidelity requirements.
Generating largest contract values: Research Institutions. Expanding procurement fastest: Neurorehabilitation Centers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Shenzhen and Shanghai concentrate component manufacturing for wireless neural sensing hardware, while research parks in Massachusetts and Bavaria drive algorithm development clusters.
United States
DARPA neurotechnology funding and NIH brain initiative grants concentrate capital in Boston and San Diego research corridors. FDA breakthrough device designation accelerates premarket review timelines for wearable EEG developers targeting motor-impaired populations. The San Francisco Bay Area anchors venture-backed brain-computer interface startups commercializing non-invasive neural decoding platforms.
Germany
Neurorehabilitation centers in Munich and Heidelberg expand procurement of functional neuroimaging systems as statutory health insurance frameworks evolve reimbursement coverage. EU MDR Class IIa reclassification intensifies clinical evidence requirements, filtering procurement toward validated suppliers. The Tübingen-Stuttgart corridor hosts university spinouts commercializing dry electrode arrays for sports science applications.
Japan
PMDA software-as-medical-device guidance shapes firmware update protocols for Bluetooth-enabled headsets deployed in Tokyo and Osaka neurorehabilitation facilities. METI funding for aging-in-place technologies accelerates home-based neural monitoring pilot programs. The Kansai region concentrates academic medical centers maintaining limited magnetoencephalography deployments for pre-surgical epilepsy mapping.
Australia
Sports science programs at Melbourne and Sydney universities deploy dry electrode systems for field-based cognitive load monitoring during athletic performance. TGA regulatory pathways for software-enabled medical devices influence validation strategies for vendors targeting Asia-Pacific distribution. The Australian Institute of Sport in Canberra coordinates multi-site trials validating ambulatory neural sensing for elite athlete training protocols.
Switzerland
Swissmedic's emerging neurotechnology qualification pathway attracts brain-computer interface developers sequencing regulatory submissions to prioritize jurisdictions with clearer predicate precedents. ETH Zurich and University of Geneva spinouts commercialize ultra-wideband-enabled closed-loop neurofeedback systems. The Lake Geneva cluster concentrates precision engineering capabilities for micro-fabricated neural electrode substrates.
Global Wireless Brain Sensors Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across fragmented procurement channels. Hospital system sales concentrate around established neurosurgical device relationships, while research institutions disintermediate traditional distribution through direct vendor negotiations. Three archetypes dominate: integrated medical device conglomerates anchoring clinical validation pathways; neuroscience-focused specialists controlling cognitive assessment segments; and component suppliers capturing modular hardware layers. Competitive intensity centers on M&A activity consolidating signal-processing software capabilities and strategic partnerships securing electrode material supply chains.
Within the diversified medical technology tier, Medtronic leverages neurosurgical device relationships to anchor hospital system procurement, while Koninklijke Philips N.V. occupies a position spanning diagnostic imaging integration. EMOTIV exemplifies the pure-play specialist archetype, representing channel disintermediation strategies that bypass traditional sales networks for direct researcher engagement. Neuroelectrics sits within the flexible research-tier segment, competing on unbundled hardware-software contracts that accommodate smaller institutional budgets.
| Leading Market Players |
|---|
| EMOTIV |
| Advanced Brain Monitoring, Inc. |
| NeuroSky |
| Neuroelectrics |
| Neuronetrix Solutions, LLC |
| Medtronic |
| Natus Medical Incorporated |
| Koninklijke Philips N.V. |
| Cadwell Industries, Inc. |
| Others |
Supply & Pricing Matrix
Brain-computer interface premium tiers commanding validation-intensive margins diverge sharply from commoditized research-grade EEG hardware, with FDA breakthrough pathway investments and silver-silver chloride electrode volatility jointly shaping procurement economics and supplier geographic concentration. This bifurcation concentrates margin pools among firmware-integrated vendors while compressing hardware-only manufacturers into volume-dependent, spot-market exposure.
Pricing Analysis
Short lead-time premiums for EU MDR-validated Class IIb devices sustain pricing power against spot-market research-grade alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and firmware integration depth. Cost compression in research-grade EEG stems from dry electrode manufacturing scale-up in Chinese component hubs. Academic buyers exhibit highest price sensitivity; neurorehabilitation centers with evolving German reimbursement frameworks demonstrate lowest.
Supply Chain Analysis
Regional distribution centers in Shenzhen and Shanghai anchor component sourcing for electrode substrates and Bluetooth silicon, with secondary hubs in South Korea and Japan for specialized fNIRS emitters. Silver-silver chloride and dry polymer electrode materials draw from precious metals markets and polymer chemical feedstocks. Single-source vulnerability concentrates in superconducting quantum interference devices for MEG sensors. Distribution runs through direct-to-researcher channels and established neurosurgical device sales networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized signal-processing firmware talent scarcity props pricing across brain-computer interface tiers, constraining R&D expansion and sustaining incumbent margin pools.
For Market Incumbents: Hedge against fNIRS substitution pressure by securing dry electrode array supply agreements with Australian and German sports science deployment partners. Deepen backward integration into silver-silver chloride substrate production to offset precious metals volatility. Prioritize FDA breakthrough device pathway investments to compress premarket timelines against emerging ultra-wideband competitors. For New Entrants and Emerging Players: FDA breakthrough device designation in the United States opens a window for motor-impaired population targeting ahead of EU MDR adaptive trial mandates. Japanese neurorehabilitation centers present the most penetrable geography given PMDA software-as-medical-device guidance gaps. Pursue direct-to-researcher distribution to bypass Medtronic-anchored hospital sales networks. For Investors and Strategic Acquirers: Re-rating potential sits with signal-processing software specialists given DARPA neurotechnology funding acceleration and NIH brain initiative grant concentration. Five-to-ten year viability favors firmware-integrated platforms over hardware-only commoditization exposure. Monitor EU MDR conformity assessment timeline divergence from FDA breakthrough pathway as inflection signal for regulatory sequencing arbitrage.| Strategic Initiative | Industry Significance |
|---|---|
| Firmware-Integrated Platform Development | Signal-processing specialization creates defendable margin pools distinct from commoditized EEG hardware. |
| Direct-to-Researcher Distribution Buildout | Channel disintermediation bypasses traditional neurosurgical sales networks for faster iteration cycles. |
| EU MDR Class IIb Certification Investment | Clinical evidence requirements filter procurement toward validated suppliers in German neurorehabilitation expansion. |
| Silver-Silver Chloride Supply Security | Precious metals price volatility hedging protects hardware margins at volume shipment tiers. |
| PMDA Software-as-Medical-Device Compliance | Firmware update protocol alignment captures first-mover advantage in Japanese Bluetooth-enabled device markets. |
Research Methodology
Independent corroboration across device manufacturer executives, neurorehabilitation center procurement leads, biomedical engineering researchers, and GPO contracts managers underwrites the qualitative findings. Secondary validation draws from FDA 510(k) and breakthrough device filings, EU MDR conformity assessment databases, PMDA software-as-medical-device guidance documents, and hospital procurement system records. Bottom-up shipment modeling and top-down funding flow analysis triangulate volume estimates.
Rate-of-change decomposition across hardware architecture, radio protocol, clinical application, and institutional buyer type segments informs the analytical framework. CAGRs derive from installed base evolution and replacement cycle assumptions. fNIRS manufacturing scale-up trajectories and DARPA program funding disbursement schedules serve as industry-specific forecast inputs across the projection horizon.
The model assumes a particular technology adoption path; alternative pathways for dry electrode arrays displacing gel-based systems would alter the outlook. Forecasts reflect assumptions regarding reimbursement framework evolution in Germany and FDA breakthrough pathway throughput capacity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Multi-Axis Sensor Market
Sensors and Controls
APAC Chemical Sensors Market
Sensors and Controls
Global Multi-Turn Potentiometer Market
Sensors and Controls
Global Level Sensors Market
Sensors and Controls
Inductive Proximity Sensors Market
Sensors and Controls
Wireless Temperature Sensor Market
Sensors and Controls
Magnetometer Sensor Market
Sensors and Controls
Thermistor Temperature Sensor Market
Sensors and Controls
MEMS Microphones Market
Sensors and Controls
CO Gas Sensors Market
Sensors and Controls
Middle East and Africa Wearable Sensors Market
Sensors and Controls
Laser Sensor Market
Sensors and Controls
3D Sensors Market
Sensors and Controls
Potentiometer Market
Sensors and Controls
Reed Sensor Market
Sensors and Controls
Flow Sensor Market