
 Chemical Sensors Market | 2026-2036
Chemical Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Chemical Sensors Market Intelligence
Expertise in materials science and data analytics is rotating the core skill set away from traditional analytical chemistry for sensor innovation. Honeywell International leverages its deep expertise in industrial automation to integrate sensors into complex control systems. Siemens specializes in sensor solutions for process industries, while MSA Safety differentiates with a focus on gas detection for worker safety applications.
A chemical sensor is a device that transforms chemical information into an analytically useful signal for detection and quantification. These devices often function via electrochemical reactions at an electrode surface or shifts in a material's optical properties. Electrochemical sensors represent the largest product segment, driven by their extensive use in industrial safety applications. Demand for optical sensors is accelerating, particularly for high-sensitivity environmental monitoring and food quality analysis.
Regulatory frameworks such as the US Environmental Protection Agency's air quality standards and the EU's REACH directive directly mandate sensor deployment for compliance. China's Ministry of Ecology and Environment (MEE) further creates demand through strict industrial emissions monitoring rules. The critical strategic decision for manufacturers involves balancing investment between high-volume commodity sensors and specialized systems for niche applications like pharmaceutical analysis.
Market Dynamics
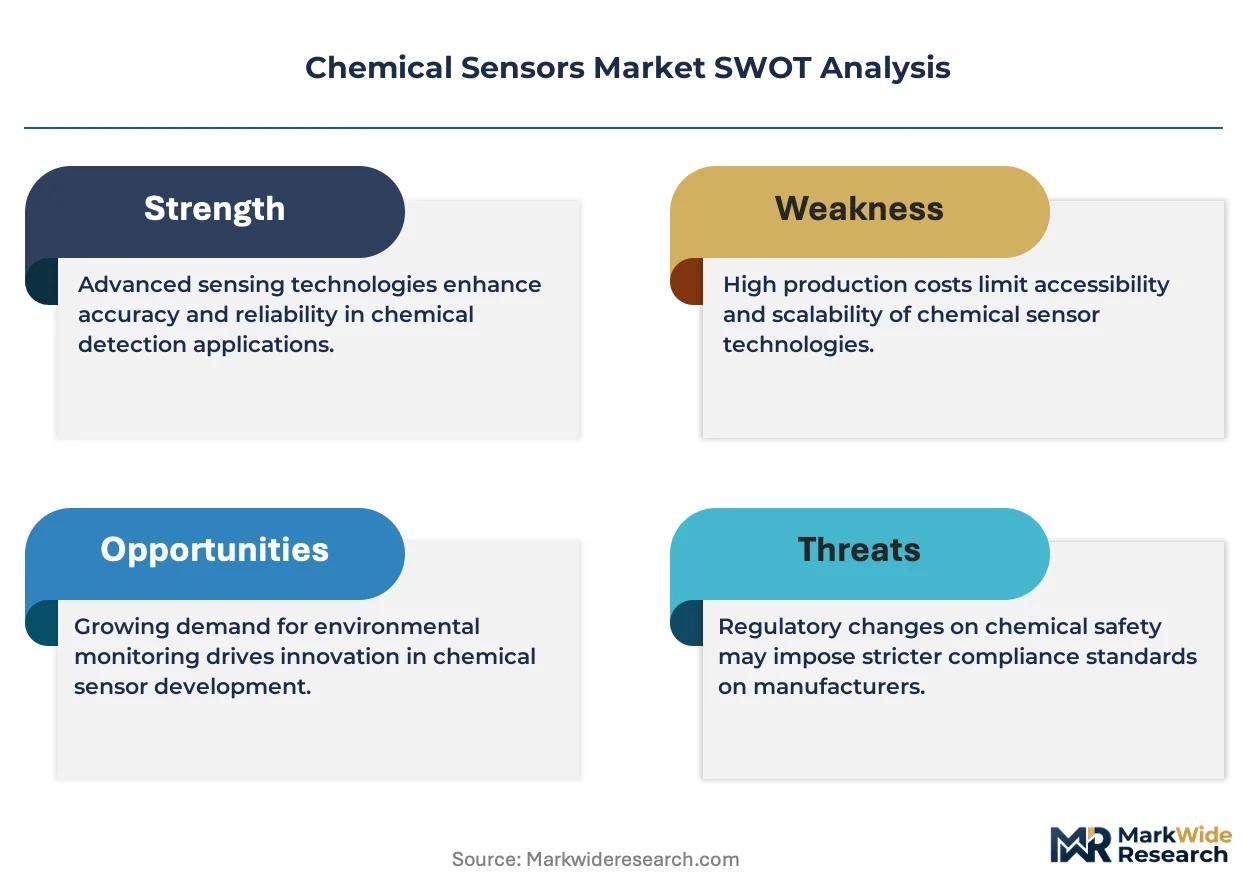
Intensifying regulatory pressure for environmental monitoring and industrial safety serves as the central force shaping the chemical sensor market. Mandates from bodies like the US EPA and frameworks such as the EU Green Deal are compelling investment in advanced detection capabilities.
Growth Catalysts
- Industrial Safety Mandates:Worker safety regulations, particularly for gas detection in oil and gas, mining, and chemical production, create a steady, non-discretionary demand base for electrochemical sensors designed to monitor toxic and combustible gases.
- Process Analytical Technology (PAT):The pharmaceutical and food and beverage industries are increasingly deploying inline optical and electrochemical sensors to achieve real-time quality control, optimizing production yields and ensuring regulatory compliance with manufacturing standards.
- National Environmental Initiatives:Government-led programs, such as China's efforts to curb industrial pollution and India's smart cities mission, are generating large-scale public and private sector demand for air and water quality monitoring networks.
Market Restraints
- High Input Material Costs:The price volatility of noble metals like platinum and palladium, which are critical materials for high-performance catalytic and electrochemical sensors, creates margin pressure and complicates long-term cost planning for manufacturers.
- Sensor Drift and Calibration Needs:Many sensors exhibit performance drift over time, requiring frequent and costly recalibration to maintain accuracy. This factor increases the total cost of ownership and is a significant operational burden in large-scale deployments.
- Competition from Analytical Instruments:In high-precision laboratory and research applications, benchtop analytical instruments like gas chromatographs and mass spectrometers offer superior sensitivity and selectivity, limiting the addressable market for sensors in certain high-value niches.
Strategic Opportunities
- Smart Agriculture Applications:The integration of chemical sensors into precision farming systems presents a significant opportunity for monitoring soil nutrient levels, pH, and moisture, as well as detecting pesticide residues to optimize crop health and yields.
- AI and Machine Learning Integration:Combining sensor data streams with AI algorithms enables predictive analytics for equipment failure, real-time process optimization in smart factories, and advanced environmental modeling, creating new value-added service revenues.
- Wearable Health Monitoring:Miniaturized biosensors integrated into wearable devices offer a pathway for non-invasive, continuous monitoring of biomarkers in sweat or interstitial fluid, opening new avenues in personalized medicine and consumer wellness.
Industry Challenges
- Interdisciplinary Talent Scarcity:A persistent skills gap exists for professionals who possess a hybrid expertise in materials science, electrochemistry, software engineering, and data analytics, which is now essential for next-generation sensor innovation.
- Legacy System Integration:Integrating modern, digital sensors with older, analog-based industrial control systems (ICS) and SCADA infrastructure presents significant technical challenges, often requiring costly middleware or system overhauls for end-users.
- Data Security and Privacy:As sensors become increasingly networked and connected to the cloud, ensuring the security of sensitive data from industrial processes or personal health monitoring against cyber threats becomes a critical and complex challenge.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chemical Sensors Market |
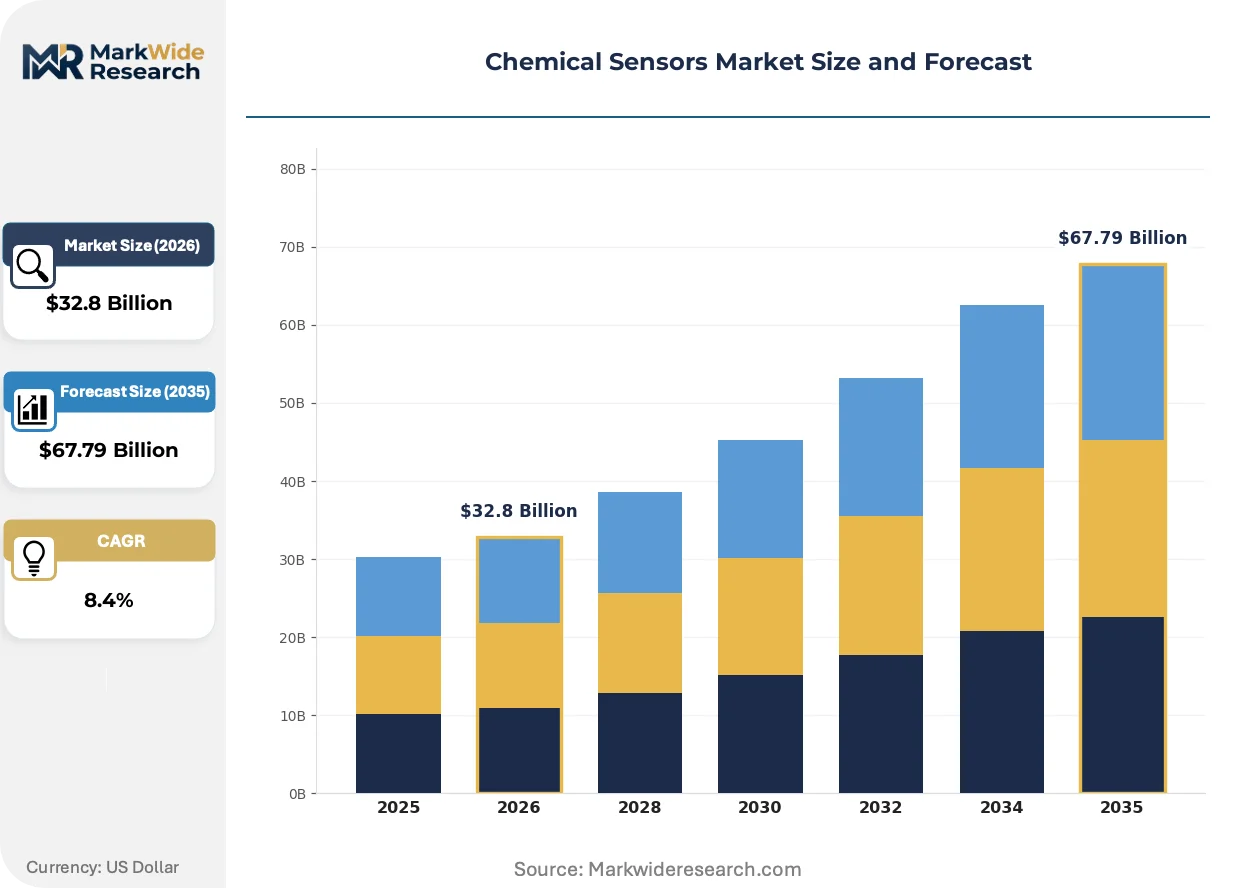
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $67.79 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electrochemical Sensors, Optical Sensors, Catalytic Sensors, Thermal Sensors, Acoustic Sensors Technology: Semiconductor Sensors, Nanomaterial Sensors, Polymer Sensors, Piezoelectric Sensors, Colorimetric Sensors Application: Environmental Monitoring, Food Quality Analysis, Pharmaceutical Analysis, Industrial Safety, Hazardous Gas Detection End User: Research Laboratories, Agricultural Monitoring, Water Treatment Facilities, Chemical Manufacturing, Educational Institutes |
| Companies Covered | Thermo Fisher Scientific, Honeywell International, ABB, Siemens, General Electric, Emerson Electric, Bayer, MSA Safety, Pepperl+Fuchs Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chemical Sensors Market Strategic Shifts & Innovations
The market's evolution is defined by a pivot from discrete component sales toward integrated, intelligent sensing systems. This shift is driven by advancements in miniaturization, data analytics, and a demand for more holistic, real-time chemical information across industries.
MEMS-based sensors leverage microfabrication techniques to place mechanical and electronic components onto a silicon chip. The medical and consumer electronics sectors are adopting these miniaturized devices for applications like portable diagnostics and indoor air quality monitoring. This miniaturization is decomposing the traditional market structure, which was built on larger industrial devices, into a high-volume, chip-level business model.
Europe's REACH regulation mandates comprehensive chemical safety assessments for substances manufactured or imported into the EU. This policy directly compels industries to deploy sensors for monitoring process environments and worker exposure to demonstrate compliance. The electrochemical and optical sensor segments are responding by developing more durable and chemical-specific products for continuous monitoring within manufacturing facilities.
A notable shift in purchasing behavior is the move from acquiring standalone hardware to procuring integrated sensing-as-a-service platforms. This model displaces the traditional transactional sale by bundling sensor deployment with data management, analytics dashboards, and ongoing maintenance. This trend is most visible in the environmental monitoring sector, where municipal clients favor subscription-based services for managing city-wide air and water quality networks.
Chemical Sensors Market Segmentation
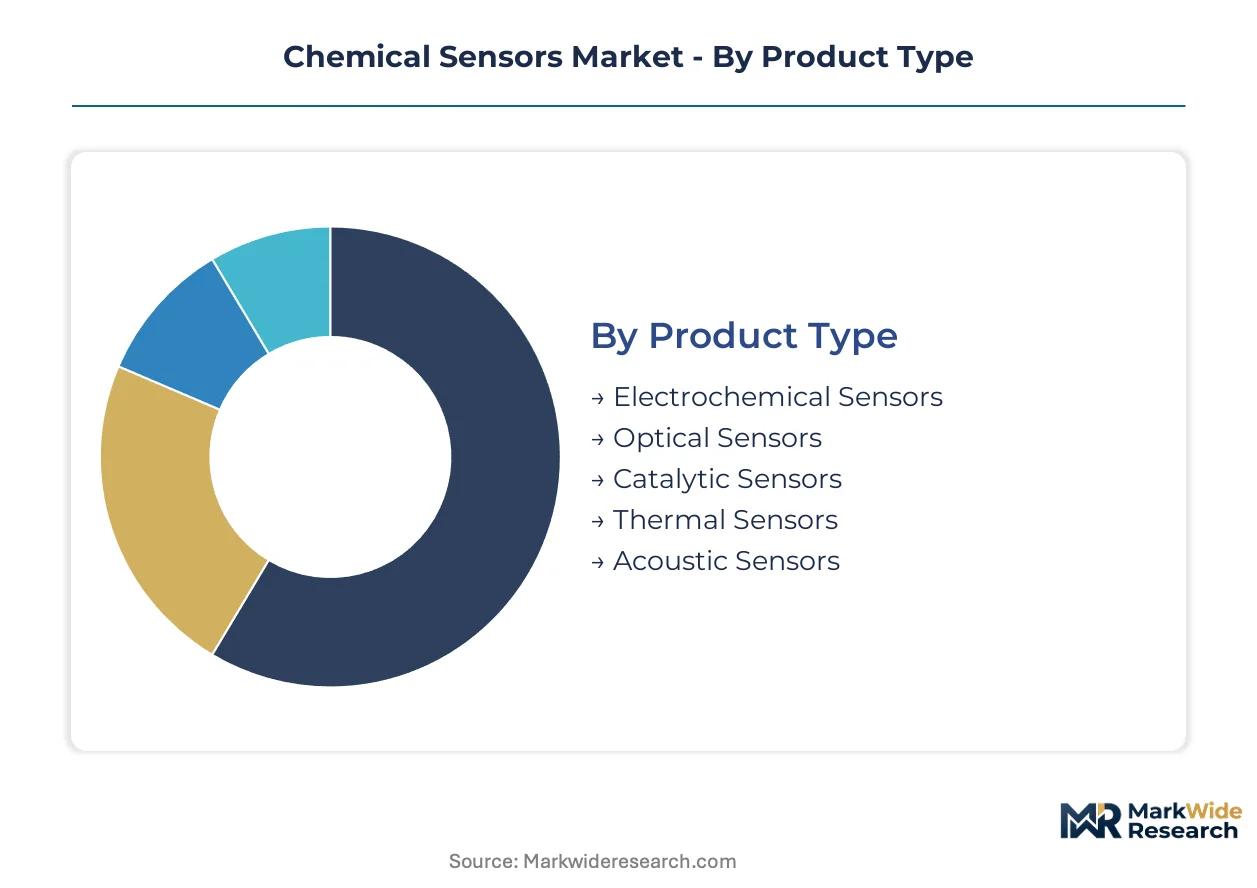
The chemical sensors market segments into distinct categories based on product type, underlying technology, specific application areas, and the end-user industries that deploy these devices. Understanding these classifications provides clarity on where innovation is concentrated and how market demand is distributed across various industrial and environmental sectors.
Product Type:
Product type segmentation reveals how different sensor mechanisms are adopted across various global markets, with some types seeing more widespread international adoption than others.
- Electrochemical Sensors:These devices operate by measuring electrical signals generated from chemical reactions at an electrode surface, making them highly effective for gas detection. Demand for electrochemical sensors is consistently high in industrial safety applications across North America and Europe due to stringent worker protection regulations.
- Optical Sensors:Optical sensors detect chemical changes by monitoring shifts in a material's light absorption, reflection, or emission properties, offering high sensitivity and selectivity. These sensors are experiencing accelerating demand in environmental monitoring networks and food quality analysis, particularly in China and India, driven by national quality initiatives.
- Catalytic Sensors:Catalytic sensors utilize a heated catalytic bead to detect combustible gases, providing a reliable response to a broad range of hydrocarbons. These are primarily employed in hazardous area monitoring within the oil and gas sector.
- Thermal Sensors:Thermal sensors measure heat changes associated with chemical reactions, offering a robust solution for specific exothermic or endothermic processes. Industrial process control systems often integrate these for temperature-sensitive chemical reactions.
- Acoustic Sensors:Acoustic sensors detect chemical presence by measuring changes in sound wave propagation properties due to chemical interactions. These devices find specialized use in detecting airborne particulates and certain volatile organic compounds.
Electrochemical Sensors commands the established base. The steepest expansion runs through Optical Sensors.
Technology:
The technological underpinnings of chemical sensors often dictate their cost profile, with advanced materials typically commanding higher prices due to research and development investments and specialized manufacturing processes.
- Nanomaterial Sensors:These sensors leverage the unique properties of nanoparticles, nanotubes, and nanowires to achieve enhanced sensitivity and miniaturization, making them suitable for detecting trace amounts of analytes. Integration into portable and wearable devices is driving significant interest in consumer electronics and health monitoring.
- Semiconductor Sensors:Semiconductor sensors utilize changes in electrical conductivity of a semiconductor material upon exposure to specific gases or liquids, providing cost-effective and compact detection solutions. These are widely deployed in indoor air quality monitors and automotive exhaust systems.
- Polymer Sensors:Polymer sensors incorporate chemically sensitive polymer films that change properties upon analyte absorption, offering flexibility in design and application. These are frequently used for detecting organic vapors and humidity levels.
- Piezoelectric Sensors:Piezoelectric sensors detect chemicals by measuring mass changes on a crystal surface, which alters its resonant frequency. These find niche applications in high-precision laboratory instruments and environmental research.
- Colorimetric Sensors:Colorimetric sensors rely on a visual color change in a reagent upon chemical interaction, providing a simple and rapid detection method. These are common in point-of-care diagnostics and water quality test kits.
Nanomaterial Sensors caters to high-volume industrial needs. Semiconductor Sensors is gaining share fastest in specialized applications.
Application:
The diverse applications for chemical sensors highlight their utility across critical sectors, from safeguarding human health to preserving environmental quality, often driven by specific functional requirements.
- Environmental Monitoring:This application involves deploying sensors to measure pollutants in air, water, and soil, ensuring compliance with regulatory standards and safeguarding ecosystems. Regulations from the US EPA and the EU Green Deal compel widespread sensor deployment for this purpose.
- Industrial Safety:Chemical sensors are crucial for detecting toxic, flammable, and explosive gases in industrial environments, protecting workers and preventing catastrophic incidents. Worker safety mandates in chemical production and mining directly drive this segment.
- Food Quality Analysis:Sensors in this segment assess freshness, detect contaminants, and verify authenticity in food products, ensuring consumer safety and reducing spoilage. Real-time quality control in food processing facilities increasingly relies on these sensors.
- Pharmaceutical Analysis:This application uses sensors for quality control, process monitoring, and drug discovery within the pharmaceutical industry, ensuring product purity and efficacy. Process Analytical Technology (PAT) initiatives are expanding sensor use in this sector.
- Hazardous Gas Detection:Specialized sensors identify and quantify specific dangerous gases like carbon monoxide, hydrogen sulfide, and methane, providing early warnings in residential, commercial, and industrial settings. This is a critical subset of industrial safety and environmental monitoring.
Demand for Environmental Monitoring remains consistently high due to regulatory pressures. Industrial Safety is experiencing rapid uptake in new industrial verticals.
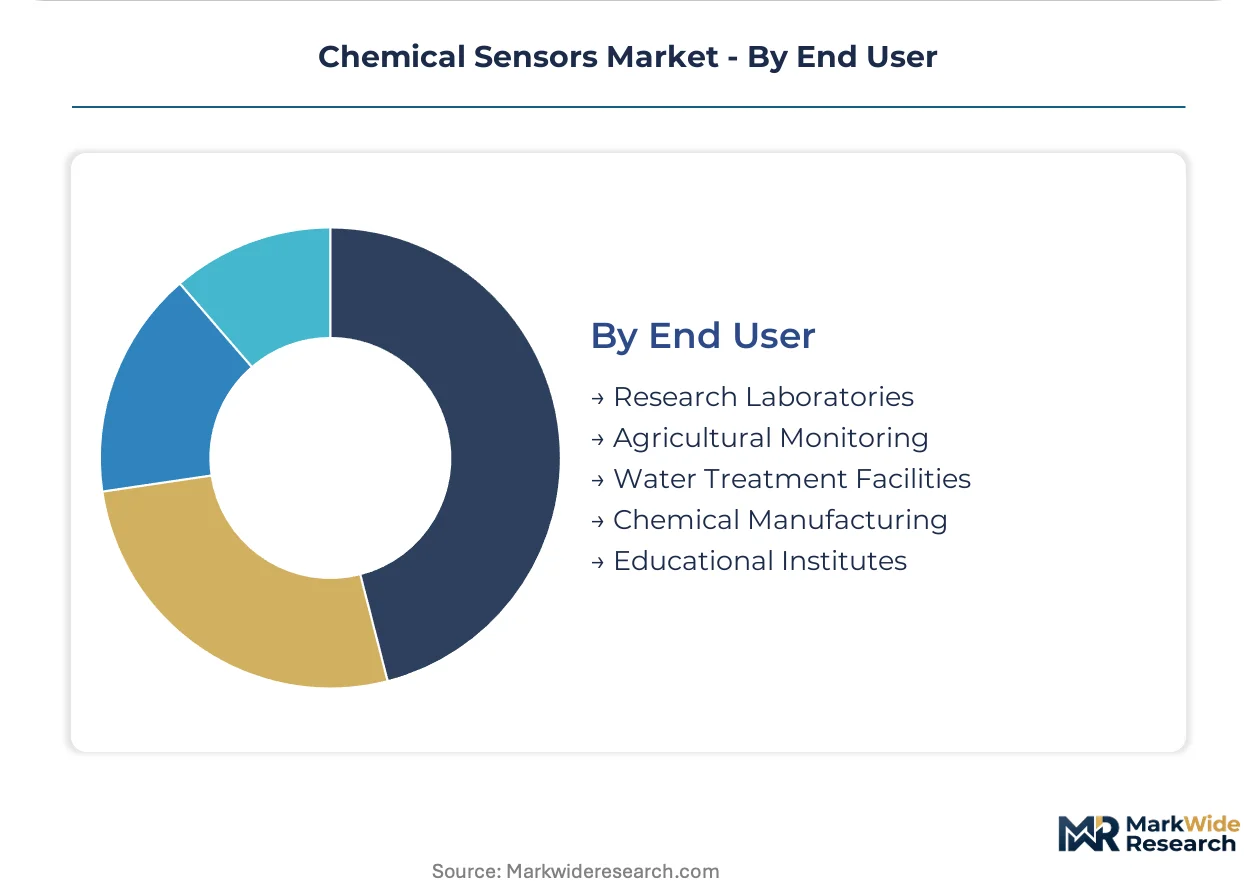
End User:
End-user segmentation illustrates the varied organizational contexts in which chemical sensors are utilized, ranging from academic institutions to large-scale industrial operations, each with unique requirements and purchasing behaviors.
- Chemical Manufacturing:This sector utilizes chemical sensors extensively for process control, safety monitoring, and emissions compliance within its complex production facilities. Honeywell International integrates sensors into control systems for this end-user group.
- Water Treatment Facilities:These facilities deploy sensors for continuous monitoring of water quality parameters, detecting contaminants, and optimizing treatment processes to ensure public health and environmental protection. Government-led smart cities initiatives in India drive demand for these sensors.
- Research Laboratories:Laboratories use highly sensitive and precise chemical sensors for analytical research, method development, and material characterization. These environments often require specialized, high-precision instruments.
- Agricultural Monitoring:Sensors in agriculture assess soil nutrient levels, pH, moisture content, and detect pesticide residues, optimizing crop yields and promoting sustainable farming practices. Precision farming systems are increasingly integrating these devices.
- Educational Institutes:Academic institutions employ chemical sensors for teaching purposes, student experiments, and fundamental scientific research in chemistry, environmental science, and engineering departments. These typically require robust and easy-to-use sensor platforms.
Chemical Manufacturing forms a foundational demand segment. Water Treatment Facilities represents a growth frontier driven by new mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US Environmental Protection Agency (EPA) anchors significant demand for chemical sensors across North America, driven by stringent environmental monitoring and industrial safety regulations. Diverse national policies and industrial concentrations shape market dynamics across key global economies. Governments worldwide prioritize advanced detection capabilities for public health and economic stability.
United States
Demand for chemical sensors in the United States stems from robust industrial safety mandates and comprehensive environmental protection requirements. The US EPA’s air and water quality standards compel widespread sensor deployment in manufacturing and utilities. The Gulf Coast region, with its dense concentration of chemical and petrochemical industries, drives substantial procurement of electrochemical sensors for gas detection.
China
China's Ministry of Ecology and Environment (MEE) initiatives heavily influence the chemical sensors market, particularly for industrial pollution control and environmental monitoring. National quality initiatives also accelerate demand for optical sensors in food safety analysis. The Yangtze River Delta industrial zones represent a major hub for large-scale sensor network installations addressing emissions and water quality.
Germany
Germany's chemical sensor market benefits from strong process industry applications and advanced industrial automation needs. The EU's REACH directive mandates continuous monitoring of chemical substances, driving sensor deployment in manufacturing facilities. Bavaria's industrial automation sector integrates specialized chemical sensors into complex control systems for precision manufacturing.
India
India's smart cities mission and national environmental initiatives are generating substantial demand for air and water quality monitoring networks. Water treatment facilities increasingly deploy chemical sensors to ensure public health and optimize processes. The industrial growth in Maharashtra, particularly around Mumbai and Pune, fuels the need for sensors in diverse manufacturing and utility applications.
Japan
Japan's demand for chemical sensors arises from its high-precision manufacturing sectors and advanced research laboratories. The Ministry of Economy, Trade and Industry (METI) supports technological innovation, promoting sensor integration into new industrial applications. The Kanto region, encompassing Tokyo, serves as a hub for both sensor innovation and deployment in its extensive technology and automotive industries.
Chemical Sensors Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, defining the competitive structure of the chemical sensors market. This tiered landscape includes diversified industrial conglomerates, specialized safety solution providers, and emerging technology innovators. Strategic partnerships between sensor manufacturers and data analytics firms are common, alongside technology licensing agreements to accelerate innovation.
Integrated leaders such as Honeywell International and Thermo Fisher Scientific exemplify broad portfolio coverage, spanning industrial automation to laboratory instrumentation. These companies leverage extensive distribution networks and deep industry expertise across multiple end-user segments. Specialized solution providers like MSA Safety focus on niche applications, particularly gas detection for worker safety, differentiating through specific performance and compliance features. These archetypes collectively shape product development and market penetration strategies.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Honeywell International |
| ABB |
| Siemens |
| General Electric |
| Emerson Electric |
| Bayer |
| MSA Safety |
| Pepperl+Fuchs Group |
| Others |
Cost & Logistics Intelligence
Long-term supply agreements for specialized chemical sensors lock in both supply access and price visibility for critical industrial and environmental applications. These contracts provide stability amidst fluctuating raw material costs, particularly for noble metals.
Pricing Analysis
Geographic price spreads for chemical sensors reflect regional regulatory stringency and local manufacturing costs. Pricing stratifies across premium, standard, and economy tiers, influenced by sensor performance levels and specific regulatory certifications required for deployment. Margin pressure stems from the price volatility of noble metals like platinum and palladium, critical for high-performance electrochemical sensors. Industrial safety applications and environmental monitoring exhibit lower price sensitivity due to mandatory compliance, while consumer-grade applications are more price-elastic.
Supply Chain Analysis
Strategic stockpiling for critical noble metals mitigates supply disruptions for high-performance chemical sensors, contrasting with just-in-time approaches for more common components. Supply concentration for advanced sensor manufacturing centers in countries like Germany and Japan, while raw material extraction for noble metals often originates from a few key global sources. The market relies on specific inputs such as platinum, palladium, and specialized polymers. Commodity price volatility for these critical materials presents a significant structural risk. Distribution runs through a mix of direct sales to large industrial end-users and specialized integrators, with a growing shift towards sensing-as-a-service models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The chemical sensors market is in an early-cycle expansion phase, driven by escalating regulatory mandates for environmental monitoring and industrial safety. This tailwind accelerates the penetration of advanced detection capabilities across diverse industries.
For Market Incumbents:
Shield core market share by deepening vertical integration into critical material supply, such as noble metals, to counter input cost volatility. Invest heavily in AI and machine learning integration to enhance existing sensor data analytics, mitigating the threat from specialized data analytics firms. Expand service-as-a-service offerings for environmental monitoring clients, leveraging established distribution networks to defend against new entrants focused solely on hardware sales.
For New Entrants and Emerging Players:
Advanced environmental modeling and predictive maintenance platforms represent a service-layer gap where incumbents under-serve. Target smart agriculture applications by developing miniaturized, low-cost sensors for soil nutrient analysis and pesticide detection. Focus on a subscription-based sensing-as-a-service model, particularly for emerging economies like India, offering bundled hardware, data analytics, and ongoing maintenance. This approach enables rapid penetration in under-served, compliance-driven markets.
For Investors and Strategic Acquirers:
Specialized sensor technology firms with strong intellectual property in nanomaterials or advanced optical sensing present attractive acquisition targets for long-term viability. These companies offer critical capabilities for next-generation applications in personalized medicine and smart factories. Seek firms that possess a hybrid expertise in materials science and data analytics, addressing the industry's talent scarcity. The signal to watch is accelerating adoption rates of miniaturized biosensors in consumer wearables.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in AI-powered Predictive Analytics Platforms | Honeywell International can enhance process optimization and equipment failure prediction for industrial clients. |
| Develop Miniaturized Biosensor Arrays | MSA Safety can expand into wearable health monitoring applications, leveraging its expertise in gas detection. |
| Expand Sensing-as-a-Service Offerings | Siemens can capture recurring revenue streams from municipal environmental monitoring networks in Europe. |
| Secure Long-term Supply for Noble Metals | Chemical sensor manufacturers can stabilize input costs and ensure production continuity for high-performance sensors. |
| Pursue Partnerships for System Integration | Companies can overcome legacy system integration challenges for industrial control systems in manufacturing. |
Research Approach
The analysis maps electrochemical, optical, and catalytic sensor sub-sectors, each validated through primary interviews with plant managers, R&D directors, and procurement leads. This involved bottom-up data collection and top-down market sizing, triangulating insights from secondary sources like US EPA reports, EU Green Deal policy documents, and China's MEE publications. Customs data and company financial filings further informed market dynamics.
Market outputs were validated against external benchmarks from leading industrial automation and environmental regulatory bodies, ensuring consistency across the analysis window. The analytical framework modeled segmentation by product type, technology, application, and end-user industry. Compound Annual Growth Rates were derived from historical data trends and projected adoption rates for new sensor technologies like nanomaterials. Regulatory mandates for industrial safety and environmental compliance served as key forecast inputs.
Underlying assumptions cover stable regulatory enforcement and continued technological advancement, with deviation risk concentrated in unforeseen geopolitical events or raw material supply shocks. Forecasts reflect these assumptions. Revision becomes warranted when major policy shifts or disruptive material science breakthroughs cross thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
MEMS Pressure Sensors Market
Sensors and Controls
US Wireless Sensors Market
Sensors and Controls
Nano Positioning System Market
Sensors and Controls
Europe Vibration Sensors Market
Sensors and Controls
Instrumented Load Shackle Market
Sensors and Controls
Hydrogen Pressure Sensor Market
Sensors and Controls
Global Smartphone Sensors Market
Sensors and Controls
Non-Glass Capacitive Sensors Market
Sensors and Controls
Tooth Mounted Sensor Market
Sensors and Controls
Automation Control Components and Devices Market
Sensors and Controls
Capacitive Tactile Sensor Market
Sensors and Controls
Parking Sensors Market
Sensors and Controls
Sensor Based Sorting System Market
Sensors and Controls
Smartphone Biometric Sensors Market
Sensors and Controls
MEMS for Mobile Devices Market
Sensors and Controls
Asia-Pacific Industrial Control System Market