
 Hydrogen Pressure Sensor Market | 2026-2036
Hydrogen Pressure Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Hydrogen Pressure Sensor Market Foresight
Aftermarket calibration services is reshaping margin distribution across the hydrogen sensor value chain. Sensata Technologies leverages its automotive heritage to dominate OEM fuel cell programs. TE Connectivity anchors its position through aerospace-grade qualification protocols. WIKA competes on precision manufacturing scale for high-pressure hydrogen storage systems.
A hydrogen pressure sensor measures hydrogen gas pressure in environments demanding extreme chemical compatibility, typically employing 316L stainless steel wetted parts and hermetic sealing rated to 700 bar or beyond for gaseous hydrogen containment. Smart Sensors command premium positioning through embedded diagnostics and digital IO-Link outputs that reduce field wiring complexity. Piezoelectric technology leads in dynamic engine testing applications where microsecond response times matter. Strain Gauge designs occupy the mature utility segment for stationary storage tank monitoring.
ISO 19880 governs gaseous hydrogen fueling station sensor performance, while the EU AI Act and Machinery Directive shape embedded software validation for smart sensor variants. Japan's METI hydrogen roadmap and South Korea's Hydrogen Economy Policy enforce domestic certification thresholds that filter market access. Stakeholders must monitor evolving pressure-cycle fatigue standards as hydrogen blending into natural gas networks creates new operating envelopes.
Market Dynamics
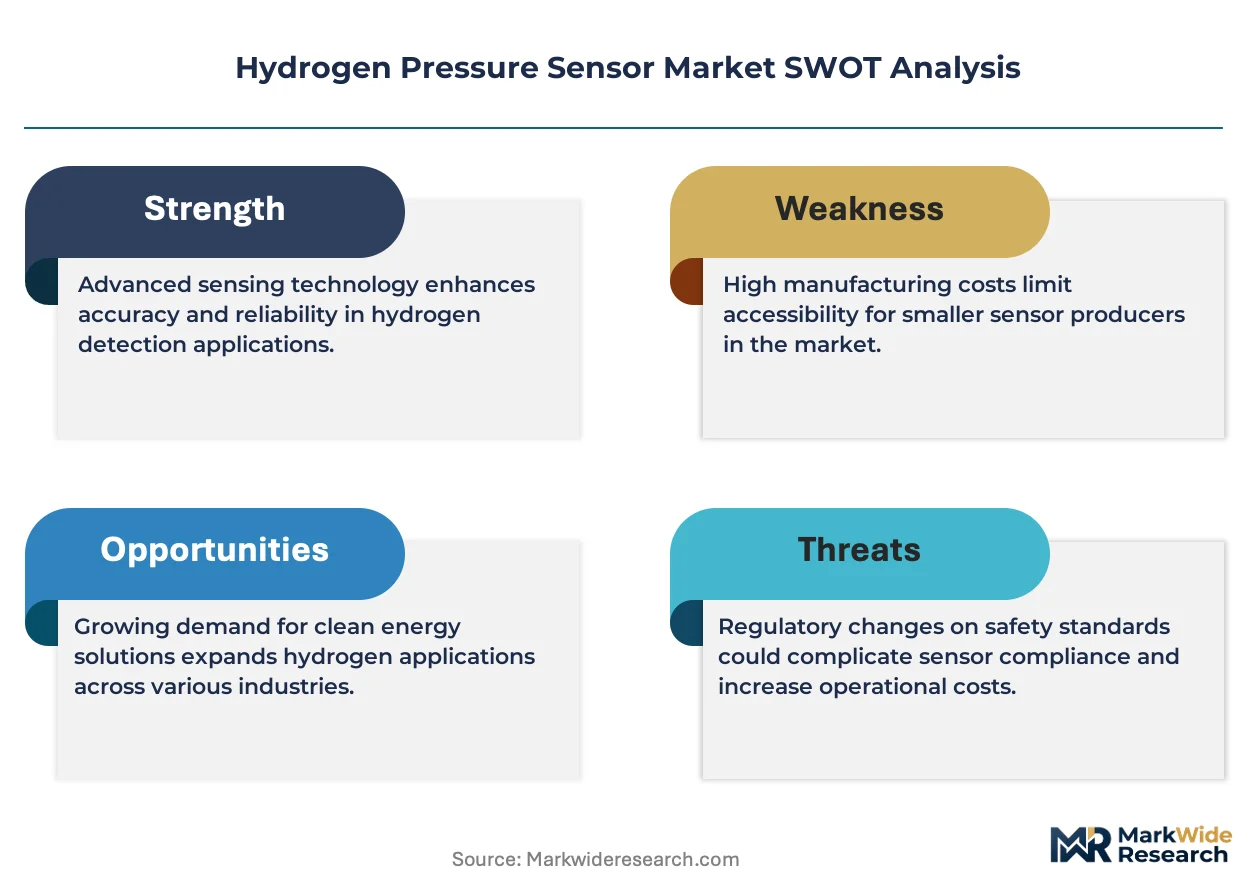
The hydrogen pressure sensor market pivots on the collision between ISO 19880 safety mandates and the engineering complexity of 700-bar hydrogen containment systems. Sensor suppliers must simultaneously certify for automotive fuel cell programs and stationary storage infrastructure, creating divergent qualification pathways that fragment R&D investment.
Growth Catalysts
- Automotive fuel cell deployment:OEM hydrogen vehicle programs in Germany, Japan, and South Korea are pulling high-pressure sensor volumes into serialized production. Tier-1 suppliers are locking in multi-year supply agreements for 350-bar and 700-bar variants.
- ISO 19880 enforcement:Gaseous hydrogen fueling station certification requirements are mandating sensor replacement cycles and diagnostic traceability. Station operators must upgrade legacy installations to meet pressure-cycle monitoring standards.
- Metal hydride storage scaling:Solid-state hydrogen storage systems for material handling equipment and backup power are creating demand for precision low-pressure sensors with hermetic sealing.
Market Restraints
- 316L stainless steel cost volatility:Wetted parts fabrication depends on aerospace-grade alloy supply chains concentrated in European and Japanese mills. Price swings in nickel and chromium feedstocks compress sensor gross margins unpredictably.
- Hydrogen embrittlement testing bottlenecks:Accelerated life validation for high-pressure cycling requires specialized chambers with 12-18 month queue times at accredited laboratories. Certification delays throttle product launch velocity.
- Electrochemical sensor substitution:Thin-film hydrogen leak detection systems are capturing safety-monitoring applications that pressure sensors previously dominated in enclosed spaces.
Strategic Opportunities
- India hydrogen hub development:The country's National Hydrogen Mission is funding pilot fueling corridors connecting refining clusters to port infrastructure. Early sensor deployment in these corridors establishes reference installations for scaling.
- Smart sensor retrofit programs:IO-Link enabled diagnostics allow aftermarket upgrade of analog sensors in existing storage facilities. Service revenue streams attach to hardware refresh cycles.
- Ammonia cracking integration:Hydrogen pressure sensors positioned between ammonia reformers and fuel cell inlets capture emerging maritime and off-grid power applications.
Industry Challenges
- Hydrogen-specific calibration expertise scarcity:Field technicians trained on natural gas or industrial gas sensors require re-certification for hydrogen permeability and embrittlement behavior. Training program development lags hardware deployment.
- Cross-standard harmonization friction:Japan's METI certification, South Korea's KGS approval, and EU CE marking under the Machinery Directive impose overlapping but non-identical test protocols. Multi-region product variants inflate SKU complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydrogen Pressure Sensor Market |
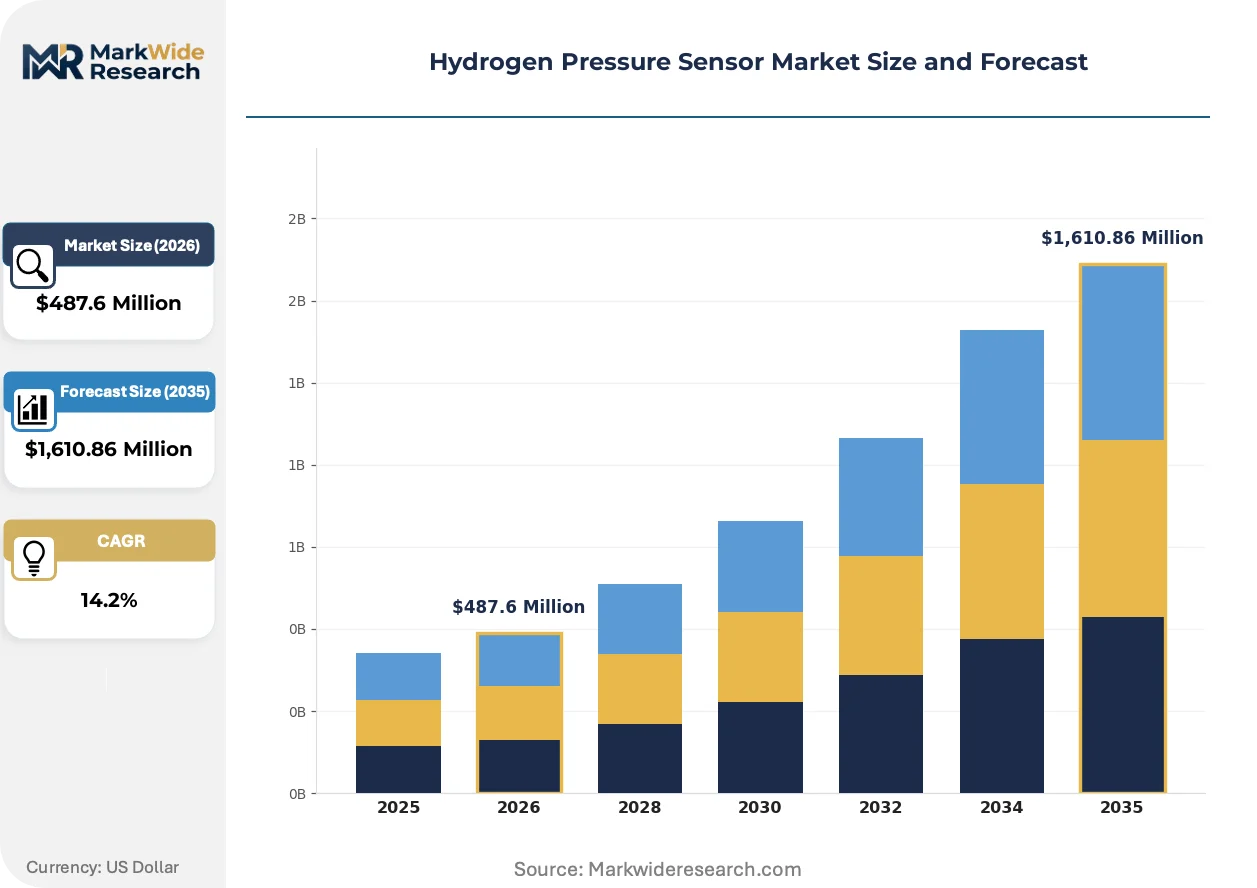
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,610.86 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gauge Sensors, Absolute Sensors, Differential Sensors, Smart Sensors Technology: Piezoelectric, Optical, Capacitive, Strain Gauge End User: Aerospace, Automotive, Chemical, Energy Application: Fuel Cells, Storage Systems, Engine Testing, Pressure Monitoring |
| Companies Covered | Sensata Technologies, Amphenol, TE Connectivity, Baker Hughes (Druck), Vaisala, Honeywell Analytics, NAGANO KEIKI, H2scan, WIKA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydrogen Pressure Sensor Market Shifts & Advancements
Silicon carbide MEMS pressure elements are penetrating hydrogen applications previously reserved for bulk metal diaphragm designs. This material transition is compressing sensor form factors while extending operational temperature ranges.
Optical fiber Bragg grating pressure transducers eliminate electrical spark risk in Zone 0 hydrogen environments. Offshore energy operators and subterranean storage facilities are adopting these designs for intrinsic safety compliance. The technology is rendering obsolete conventional strain gauge configurations in confined-space monitoring.
The EU AI Act's risk classification system is capturing smart hydrogen sensors with embedded diagnostic algorithms. Manufacturers must now document training data provenance and algorithmic transparency for CE marking. Automotive OEMs are responding by segregating sensor hardware from edge computing modules to isolate software validation scope.
Aftermarket calibration services are unbundling from original equipment sales. Industrial gas distributors and specialized metrology firms are capturing recurring revenue through mobile calibration units deployed at hydrogen storage sites. Germany's TÜV-certified service network is expanding fastest, followed by Japan's accredited laboratory partnerships with METI-approved inspection bodies.
Hydrogen Pressure Sensor Market Segmentation
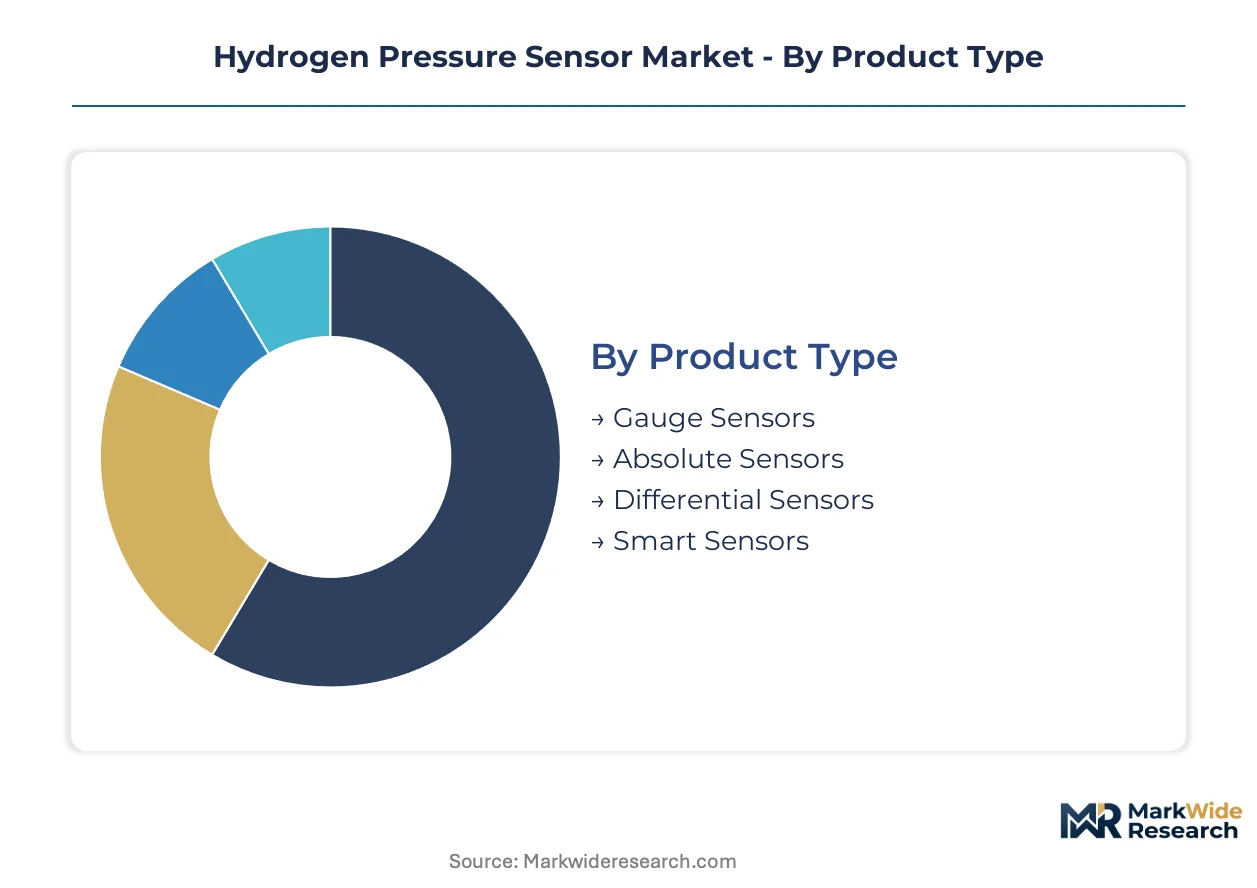
Sensor selection in hydrogen environments hinges on pressure range, chemical compatibility, and diagnostic requirements. Each segment category reflects distinct engineering trade-offs between precision, durability, and integration complexity across fuel cell and storage applications.
Product Type:
Pressure reference methodology spans vented gauge designs to fully compensated smart systems, mapping to cost tiers and functional sophistication.
- Smart Sensors:Embedded diagnostics with IO-Link digital outputs enable predictive maintenance and reduce wiring complexity. Demand concentrates in Germany's fueling station networks where ISO 19880 mandates continuous pressure-cycle traceability and remote monitoring capabilities.
- Absolute Sensors:Sealed reference cavities measure pressure against vacuum, critical for high-altitude fuel cell aircraft and aerospace ground support equipment. Japan's METI hydrogen aviation initiatives are pulling absolute sensor volumes into qualification programs for regional turboprop retrofits.
- Gauge Sensors:Vented atmospheric reference designs dominate stationary storage tank monitoring where cost sensitivity exceeds precision requirements.
- Differential Sensors:Dual-port configurations track pressure drop across filtration and purification stages in hydrogen conditioning skids.
Established volume favors Gauge Sensors; emerging adoption favors Smart Sensors.
Technology:
Transduction physics determines response speed, temperature tolerance, and intrinsic safety certification pathways.
- Strain Gauge:Bonded foil or thin-film resistive elements on metal diaphragms deliver proven stability for stationary storage. South Korea's KGS-certified tank farms specify strain gauge designs for 700-bar containment monitoring where long-term drift specifications dominate selection criteria.
- Piezoelectric:Quartz or ceramic crystal elements generate charge signals with microsecond response times. Engine testing laboratories in Stuttgart and Nagoya specify piezoelectric transducers for combustion analysis and fuel cell stack characterization where dynamic pressure resolution matters.
- Optical:Fiber Bragg grating designs eliminate electrical ignition risk in Zone 0 hydrogen atmospheres.
- Capacitive:Diaphragm displacement modulating electrode gap achieves high sensitivity for low-pressure metal hydride storage systems.
Strain Gauge captures current installed base; Piezoelectric is climbing the fastest in test and measurement applications.
End User:
Industry verticals impose divergent qualification protocols, from aerospace DO-160 to automotive IATF 16949.
- Automotive:OEM fuel cell vehicle programs require 350-bar and 700-bar sensors with AEC-Q200 automotive qualification. Germany's KBA type approval process and Japan's Ministry of Land, Infrastructure, Transport and Tourism certification are gating serial production for Hyundai, Toyota, and BMW platforms.
- Energy:Utility-scale hydrogen storage and blending into natural gas networks demand extended temperature ranges and pressure-cycle fatigue resistance. Netherlands and Germany's hydrogen backbone projects are specifying energy-grade sensors for salt cavern and pipeline injection monitoring.
- Aerospace:Aircraft fuel cell propulsion and ground handling equipment require DO-160G environmental qualification and hermetic sealing.
- Chemical:Refinery hydrogen production and ammonia cracking processes utilize sensors rated for process contamination and high-purity requirements.
Automotive drives current procurement volumes; Energy is gaining share fastest as infrastructure scales.
Application:
Functional deployment contexts range from electrochemical conversion to mechanical containment verification.
- Storage Systems:Tank level monitoring, pressure relief verification, and cascade filling control for gaseous and liquid hydrogen containment. Germany's NOW-funded H2Mobility stations and Japan's ENEOS retail network are deploying storage-integrated sensor arrays with redundant safety channels.
- Fuel Cells:Anode and cathode pressure regulation, humidity management, and purge control in proton exchange membrane stacks. South Korea's Hydrogen Economy Policy is accelerating fuel cell sensor demand for stationary power and maritime propulsion systems.
- Pressure Monitoring:Distributed sensing for pipeline integrity, compressor stations, and distribution manifold health.
- Engine Testing:Dynamic measurement in combustion research, fuel cell stack development, and component validation rigs.
Storage Systems anchor near-term revenue; Fuel Cells represent the steepest expansion trajectory as vehicle deployment accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in South Korea and Japan demonstrate the lowest price elasticity, absorbing premiums for 700-bar certification and METI-compliant diagnostics. German purchasers negotiate aggressively on volume contracts for fueling station networks. Indian procurement remains highly cost-sensitive, prioritizing gauge sensors over smart configurations in pilot corridors.
Germany
Automotive OEM hydrogen programs at BMW and Mercedes-Benz pull high-pressure sensor volumes into serialized production. The KBA type-approval process and NOW-funded H2Mobility station rollout enforce ISO 19880 compliance timelines. Stuttgart's testing laboratories and Hamburg's port hydrogen hub concentrate demand for piezoelectric dynamic measurement equipment.
Japan
ENEOS retail network expansion and fuel cell aviation initiatives under METI's hydrogen roadmap accelerate absolute sensor demand. The Ministry of Land, Infrastructure, Transport and Tourism certification gates serial production for Toyota platforms. Nagoya's engine testing clusters and Tokyo Bay fueling corridors anchor precision sensor deployment.
South Korea
Hyundai's fuel cell vehicle programs and stationary power mandates under the Hydrogen Economy Policy drive 350-bar and 700-bar procurement. KGS approval requirements filter market access for storage tank monitoring systems. Ulsan's petrochemical hydrogen backbone and Busan's maritime propulsion projects concentrate infrastructure-grade sensor demand.
United States
California's LCFS credit markets and DOE hydrogen hub awards stimulate fueling station sensor deployment. OSHA process safety management and EPA risk management plan requirements shape stationary storage specifications. Houston's refinery hydrogen production and the Pacific Northwest's electrolyzer manufacturing clusters anchor industrial demand.
India
The National Hydrogen Mission funds pilot fueling corridors connecting Gujarat refining clusters to port infrastructure. BIS certification timelines and PLI scheme incentives for electrolyzer manufacturing reshape procurement priorities. Reliance Industries' Jamnagar complex and Tamil Nadu's automotive component belt concentrate early reference installations.
Hydrogen Pressure Sensor Market Competitive Landscape
Capability concentration sits with aerospace-qualified specialists; scale advantage sits with automotive-tier suppliers with serialized production infrastructure. The market structures around three tiers: heritage automotive sensor houses, precision instrumentation conglomerates, and hydrogen-specific technology ventures. Consolidation pressure intensifies as ISO 19880 diagnostic requirements force firmware development investments that favor balance-sheet depth. Dominant competitive moves include strategic partnerships for hydrogen embrittlement testing access and geographic expansion into India's emerging hub corridors.
Within the automotive-heritage tier, Sensata Technologies and TE Connectivity exemplify players leveraging AEC-Q200 qualification pathways and OEM fuel cell program relationships. Sensata anchors its position through serialized supply agreements with German and South Korean vehicle platforms. TE Connectivity occupies a position emphasizing aerospace-grade protocols that transfer into high-pressure containment applications. Among precision instrumentation specialists, WIKA represents the manufacturing-scale archetype targeting stationary storage and fueling infrastructure. These three companies collectively illustrate how competitive positioning fragments across vehicle-integrated versus infrastructure-deployed sensor demand.
| Leading Market Players |
|---|
| Sensata Technologies |
| Amphenol |
| TE Connectivity |
| Baker Hughes (Druck) |
| Vaisala |
| Honeywell Analytics |
| NAGANO KEIKI |
| H2scan |
| WIKA |
| Others |
Supply & Pricing Matrix
Stuttgart's precision engineering cluster anchors European sensor diaphragm manufacturing, with capacity utilization at specialized 316L stainless steel mills directly conditioning pricing power for downstream hydrogen pressure sensor assemblers. German automotive OEM procurement teams leverage multi-year fuel cell program commitments to compress supplier margins, while Japanese and South Korean buyers absorb premiums for METI-compliant and KGS-certified variants.
Pricing Analysis
Aftermarket calibration services generate lifetime value exceeding original hardware sales for established sensor networks. Pricing stratifies across automotive-grade AEC-Q200 certification, industrial infrastructure tiers, and aerospace DO-160G qualification levels. Cost compression in gauge sensor segments intensifies as Indian National Hydrogen Mission corridors prioritize basic pressure monitoring over smart diagnostics. Fleet operators and fueling station consortia demonstrate lowest price elasticity, while pilot project developers in emerging hydrogen hubs exhibit acute cost sensitivity.
Supply Chain Analysis
Nickel and chromium feedstock availability from European and Japanese specialty alloy mills anchors wetted parts fabrication. Sensor assembly draws from German automotive-tier electronics, Japanese precision ceramics for piezoelectric elements, and Chinese MEMS foundry capacity for silicon carbide pressure elements. Single-source vulnerability concentrates in accredited hydrogen embrittlement testing chambers with 12-18 month queue times. Distribution runs through Tier-1 automotive supplier networks for OEM programs and industrial gas distributor channels for stationary storage deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
IO-Link interoperability standardization is transforming hydrogen pressure sensors into platform-connected edge devices, with embedded diagnostic algorithms creating ecosystem lock-in comparable to industrial automation protocols. This shift rewards firmware-capable suppliers while marginalizing analog-only hardware specialists.
For Market Incumbents: Harden certification portfolios against ISO 19880 diagnostic mandates by accelerating firmware development investments that smaller competitors cannot match. Secure captive access to hydrogen embrittlement testing capacity through laboratory partnerships or in-house chamber acquisition. Deepen relationships with German KBA and Japan's Ministry of Land, Infrastructure, Transport and Tourism approval bodies to extend type-approval advantages.
For New Entrants and Emerging Players: Establish a beachhead in India's pilot fueling corridors where BIS certification timelines and PLI scheme incentives create entry windows before incumbent footprint solidifies. Target aftermarket calibration service contracts for existing analog sensor installations rather than competing directly for OEM serial production slots. Pursue partnerships with industrial gas distributors seeking to unbundle metrology capabilities from hardware sales.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors precision instrumentation conglomerates with manufacturing scale and existing hydrogen-adjacent process sensor portfolios. The 5-10 year viability window rewards acquisition targets combining MEMS fabrication expertise with automotive qualification infrastructure. Monitor KGS and METI certification approval velocity as the signal indicating whether Korean or Japanese market access is tightening or loosening for external suppliers.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO 19880 Diagnostic Certification | Embedded algorithm validation gates fueling station deployment under EU AI Act risk classification. |
| Silicon Carbide MEMS Transition | Material shift compresses form factors while extending temperature ranges beyond metal diaphragm limits. |
| Hydrogen Embrittlement Testing Access | Laboratory queue bottlenecks throttle product launch velocity for unaccredited suppliers. |
| IO-Link Platform Integration | Digital output standardization creates predictive maintenance revenue attachment to hardware sales. |
| India Corridor Reference Installation | Early deployment in National Hydrogen Mission pilots establishes scaling credibility for subsequent rounds. |
Research Methodology
Initial hypotheses were tested against primary input from sensor platform engineers at automotive Tier-1 suppliers, fueling station procurement managers under Germany's H2Mobility program, and calibration service technicians at TÜV-accredited laboratories, then refined through secondary validation against SEC filings from listed instrumentation conglomerates, METI hydrogen roadmap progress reports, and KGS certification registry databases. Bottom-up unit demand estimates from fuel cell vehicle production schedules and stationary storage deployment pipelines were triangulated against top-down market sizing derived from alloy feedstock consumption patterns in hydrogen-grade 316L stainless steel.
Demand-supply-balance modeling across the analysis window incorporated pressure range segmentation, technology transduction physics, and end-use qualification tier as core dimensions. CAGRs were computed from fitted growth curves anchored to hydrogen infrastructure investment trajectories in Germany, Japan, and South Korea. Forecast inputs included OEM fuel cell vehicle platform ramp schedules, ISO 19880 enforcement timelines for fueling station retrofit cycles, and metal hydride storage scaling curves for material handling equipment applications.
Sensitivities concentrate around hydrogen embrittlement testing capacity expansion, nickel alloy price volatility, and regulatory harmonization friction between Japan's METI, South Korea's KGS, and EU CE marking under the Machinery Directive. Cross-checking against vehicle production database benchmarks and electrolyzer manufacturing capacity announcements is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Absolute Encoders Market
Sensors and Controls
Photonic Sensors and Detectors Market
Sensors and Controls
Quantum Dot Sensor Market
Sensors and Controls
Wireless Flow Sensors Market
Sensors and Controls
Odor Sensor Market
Sensors and Controls
Multi-Axis Sensor Market
Sensors and Controls
Temperature Controller Market
Sensors and Controls
APAC Nano Sensors Market
Sensors and Controls
Europe Gas Sensors Market
Sensors and Controls
Time of Flight (Tof) Sensor Market
Sensors and Controls
PM2.5 Sensors Market
Sensors and Controls
Solid Flow Rate Valve Control Market
Sensors and Controls
US Distributed Acoustic Sensing Market
Sensors and Controls
High-Performance IMU Market
Sensors and Controls
Industrial Combustion Control Components and Systems Market
Sensors and Controls
Mass Flow Controller Market