
 Global Thermocouple Temperature Sensors Market | 2026-2036
Global Thermocouple Temperature Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Global Thermocouple Temperature Sensors Market Foresight
Aftermarket calibration and sensor refurbishment revenue is reshaping margin distribution across the value chain. Emerson Electric Co leverages its distributed service network to capture recurring calibration contracts in process industries. WIKA Alexander Wiegand SE & Co. KG anchors European demand through its metrology-certified refurbishment centers. TE Connectivity competes in North America by extending its authorized service partner program for industrial thermocouple replacement cycles.
A thermocouple temperature sensor consists of two dissimilar metal conductors joined at a measurement junction, generating a voltage proportional to temperature differential across the Seebeck effect, with common type K pairs using chromel-alumel alloys rated from -200°C to +1260°C. These devices serve as primary temperature transducers in process control loops where direct electrical signal output enables PLC integration without intermediate conversion stages. Grounded junction configurations dominate high-vibration manufacturing environments due to faster thermal response, while wireless technology segments are expanding fastest in distributed HVAC monitoring architectures where retrofit cabling costs constrain wired alternatives. The analog technology base remains mature across aerospace turbine testing applications where millisecond-level signal latency requirements persist.
FDA food safety regulations mandate continuous temperature monitoring with traceable sensor calibration in commercial food processing facilities, directly expanding replacement demand for validated thermocouple assemblies. EPA emissions monitoring standards under 40 CFR Part 60 require certified high-temperature sensors in stack gas measurement systems, shaping product certification requirements for industrial suppliers. NIST traceability protocols and IEC 60584 tolerance classes define interchangeability standards that determine market access for component manufacturers across jurisdictions. Stakeholders must evaluate sensor lifecycle cost models against emerging solid-state alternatives as wireless digital architectures gradually displace traditional analog loop configurations in non-critical temperature monitoring roles.
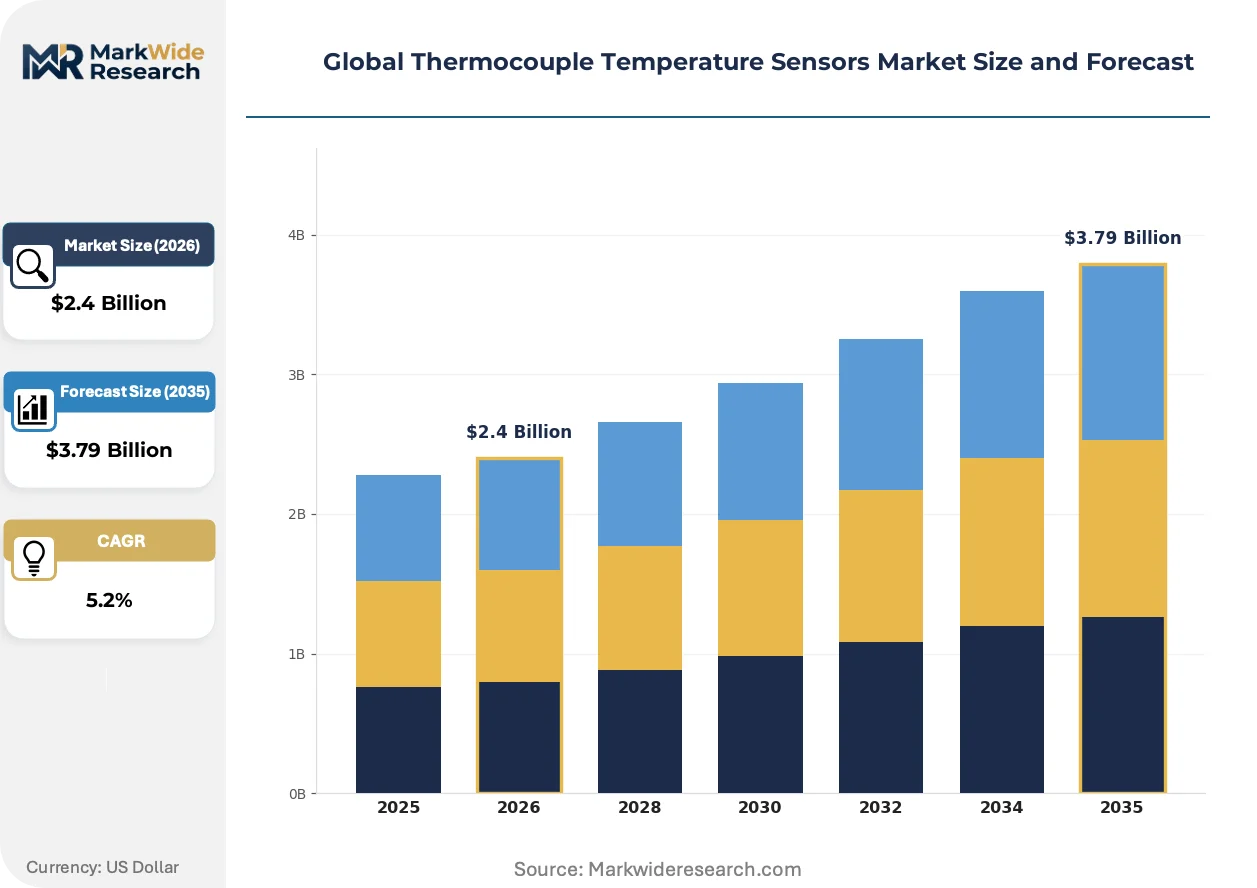
Market Dynamics
Industrial automation deployment is compressing sensor replacement cycles while tightening calibration protocols across food processing and stack gas monitoring applications. IEC 60584 tolerance classes and NIST traceability mandates now determine supplier market access.
Growth Catalysts
- Food Safety Mandates:FDA regulations require continuous temperature monitoring with validated sensor calibration in commercial food processing facilities, expanding replacement demand for certified thermocouple assemblies.
- Emissions Compliance:EPA standards under 40 CFR Part 60 mandate certified high-temperature sensors in stack gas measurement systems, shaping industrial procurement specifications.
- Smart Factory Expansion:China's industrial corridors are integrating wireless sensor networks into process control loops, accelerating digital architecture adoption.
Market Restraints
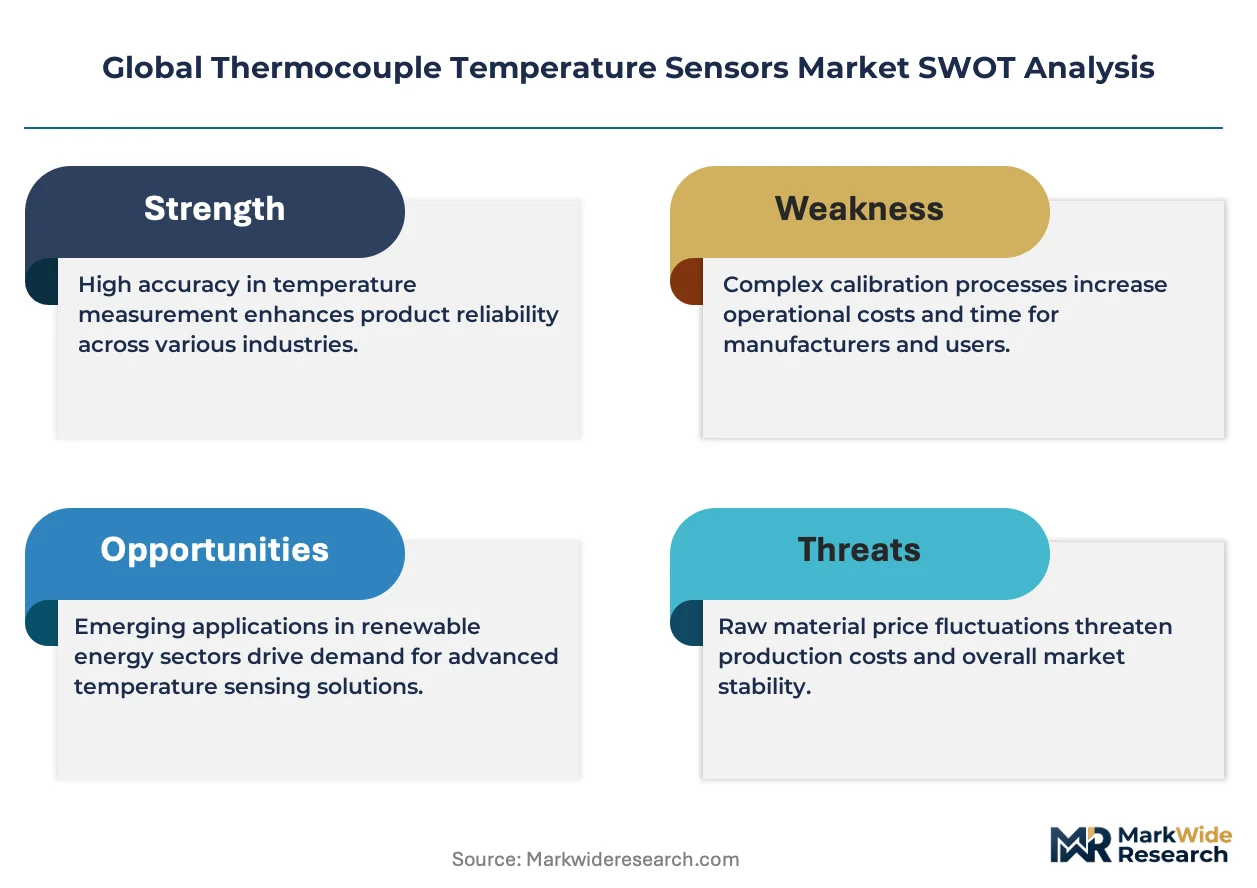
- Input Cost Volatility:Chromel-alumel alloy prices fluctuate with nickel and chromium commodity markets, squeezing margins for Type K thermocouple manufacturers.
- Supply Concentration Risk:Precision wire drawing capabilities concentrate in Germany's instrumentation cluster, creating single-source dependencies for aerospace-grade conductors.
- Solid-State Substitution:RTD and infrared sensors are capturing non-critical monitoring roles where millisecond latency requirements do not apply.
Strategic Opportunities
- Aftermarket Services:Metrology-certified refurbishment centers in Europe are capturing recurring calibration contracts as industrial users extend sensor lifecycles.
- HVAC Retrofit Demand:Wireless technology segments are expanding fastest in distributed building monitoring where retrofit cabling costs constrain wired alternatives.
- EU Green Deal Alignment:F-Gas Regulation phase-down is driving demand for leak detection thermocouples in refrigeration system monitoring across member states.
Industry Challenges
- Metrology Talent Scarcity:Certified calibration technicians with NIST-traceable competency are in short supply across North American service networks.
- Legacy System Integration:Analog signal conditioning requirements in aerospace turbine testing resist digital architecture migration due to millisecond-level latency specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Thermocouple Temperature Sensors Market |
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.79 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Grounded, Ungrounded, Exposed, Non-Exposed Technology: Analog, Digital, Wireless, Infrared Application: Manufacturing, HVAC, Aerospace, Food Processing End User: Industrial, Commercial, Residential, Research |
| Companies Covered | Honeywell International Inc, Emerson Electric Co, Omega Engineering, TE Connectivity, ABB Ltd, WIKA Alexander Wiegand SE & Co. KG, Endress+Hauser Group, Danfoss A/S, KEYENCE CORPORATION, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Thermocouple Temperature Sensors Market Shifts & Advancements
Digital architectures are virtualizing traditional signal pathways while regulatory compliance requirements harden certification standards. Three developments are restructuring competitive positioning across component and service segments.
Wireless transmitter modules with integrated cold junction compensation are virtualizing the analog loop infrastructure that historically dominated distributed temperature monitoring. Food processing facilities in Germany are adopting these architectures fastest, eliminating conduit installation costs while maintaining IEC 60584 compliance. The technology is virtualizing maintenance workflows by enabling cloud-based calibration tracking and predictive replacement scheduling.
REACH substance restrictions are tightening material disclosure requirements for chromel-alumel alloys used in Type K thermocouples. European suppliers must now document full chemical composition across the supply chain to maintain CE marking eligibility. Industrial buyers in the region are responding by consolidating procurement around suppliers with established material traceability systems.
Service unbundling is separating hardware supply from calibration contracts in process industry procurement. End-users in North American oil and gas sectors now source sensors and metrology services through distinct vendor relationships, compressing traditional bundled pricing models. This pattern is most visible in Texas and Louisiana refining corridors where specialized calibration providers compete against manufacturer service networks.
Global Thermocouple Temperature Sensors Market Segmentation
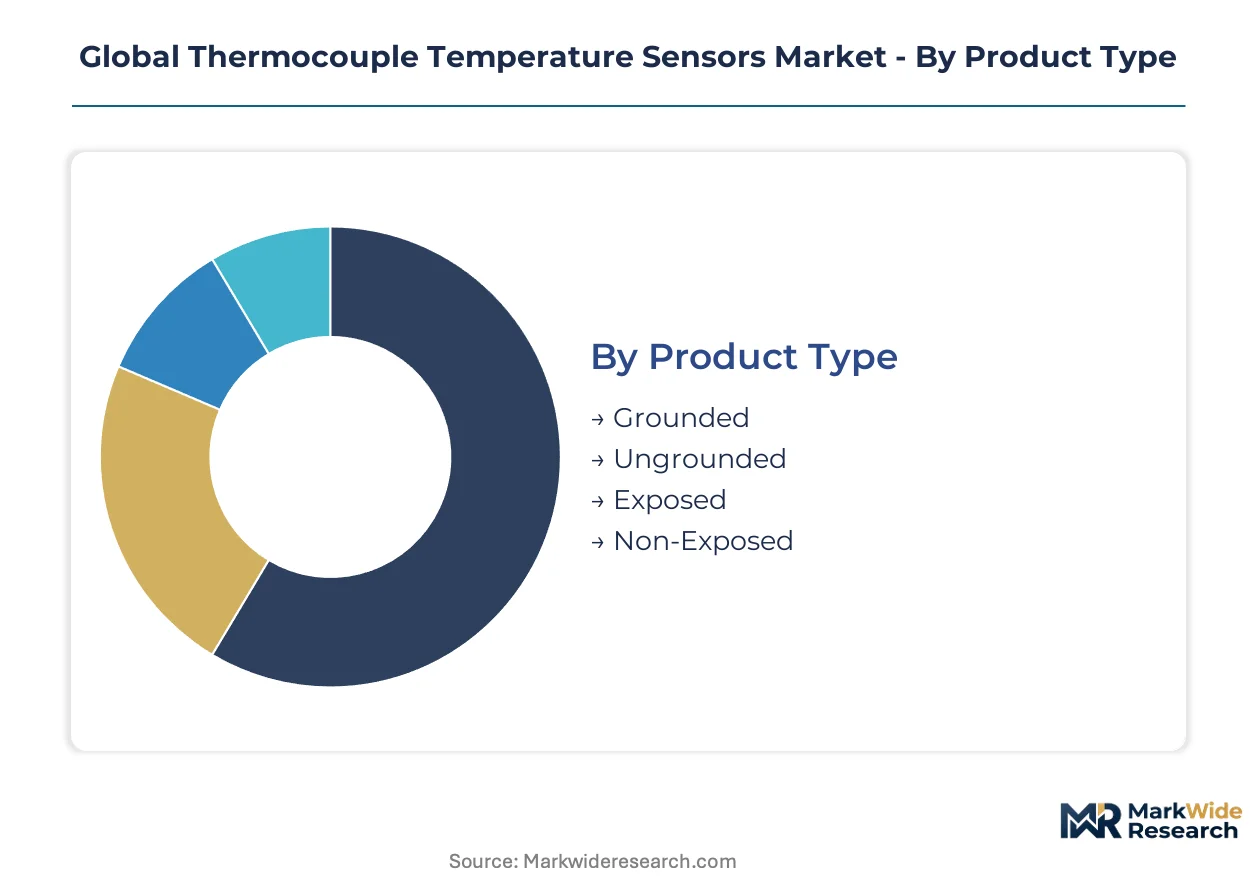
Thermocouple architectures diverge sharply across vibration tolerance, signal latency, and retrofit cost constraints. Procurement patterns split between mission-critical process loops demanding grounded junctions and distributed building systems prioritizing wireless deployment flexibility.
Product Type:
Grounded junctions dominate high-vibration manufacturing environments where thermal response speed outweighs electrical isolation requirements.
- Grounded:The measuring junction bonds directly to the protective sheath, delivering sub-second thermal response for turbine testing and forging operations. German precision instrumentation clusters specify these configurations for automotive powertrain validation labs where vibration resistance prevents signal drift.
- Ungrounded:Electrical isolation between junction and sheath protects against ground loop interference in multi-sensor PLC networks. Chinese smart factory corridors deploy these for chemical reactor monitoring where stray currents threaten measurement integrity.
- Exposed:Direct immersion designs sacrifice mechanical protection for maximum thermal sensitivity in laboratory calibration standards.
- Non-Exposed:Sheathed configurations balance response time with durability for general industrial maintenance applications.
The dominant share belongs to Grounded configurations, while Ungrounded variants are closing the gap fastest in digital process control architectures.
Technology:
Signal conditioning requirements fragment procurement between legacy analog loops and cloud-connected digital architectures.
- Analog:Millisecond-level latency specifications in aerospace turbine testing preserve demand for direct voltage output without ADC conversion stages. FAA certification protocols for engine test cells mandate these signal pathways where digital jitter introduces unacceptable measurement uncertainty.
- Wireless:Battery-powered transmitter modules with integrated cold junction compensation eliminate conduit costs in HVAC retrofit projects. Germany's food processing facilities adopt these fastest for refrigerated warehouse monitoring where IEC 60584 compliance must coexist with installation flexibility.
- Digital:Bus-addressable sensors streamline calibration tracking through embedded memory storing NIST-traceable coefficients.
- Infrared:Non-contact alternatives capture surface temperature in hazardous zones where thermocouple immersion risks contamination or mechanical failure.
Wireless deployments are expanding most quickly in building automation, though analog retains entrenched positions in aerospace validation.
Application:
Regulatory compliance intensity varies dramatically across FDA-mandated food safety and EPA emissions monitoring versus discretionary HVAC efficiency upgrades.
- Food Processing:Continuous temperature validation requirements under FDA regulations drive replacement demand for calibrated assemblies with documented traceability chains. Commercial bakeries and protein processing facilities in the US Midwest maintain quarterly recertification schedules.
- Aerospace:Turbine blade testing protocols require Type K chromel-alumel pairs rated to 1260°C with grounded junctions for thermal shock characterization. California propulsion test centers specify these for next-generation engine development programs.
- Manufacturing:Heat treatment furnaces and metal forming operations deploy standardized thermocouple assemblies for process uniformity.
- HVAC:Distributed building management systems prioritize cost-per-point economics over calibration rigor for comfort control loops.
Food Processing commands the dominant procurement volume, while Aerospace specifications drive premium pricing tiers through certification overhead.
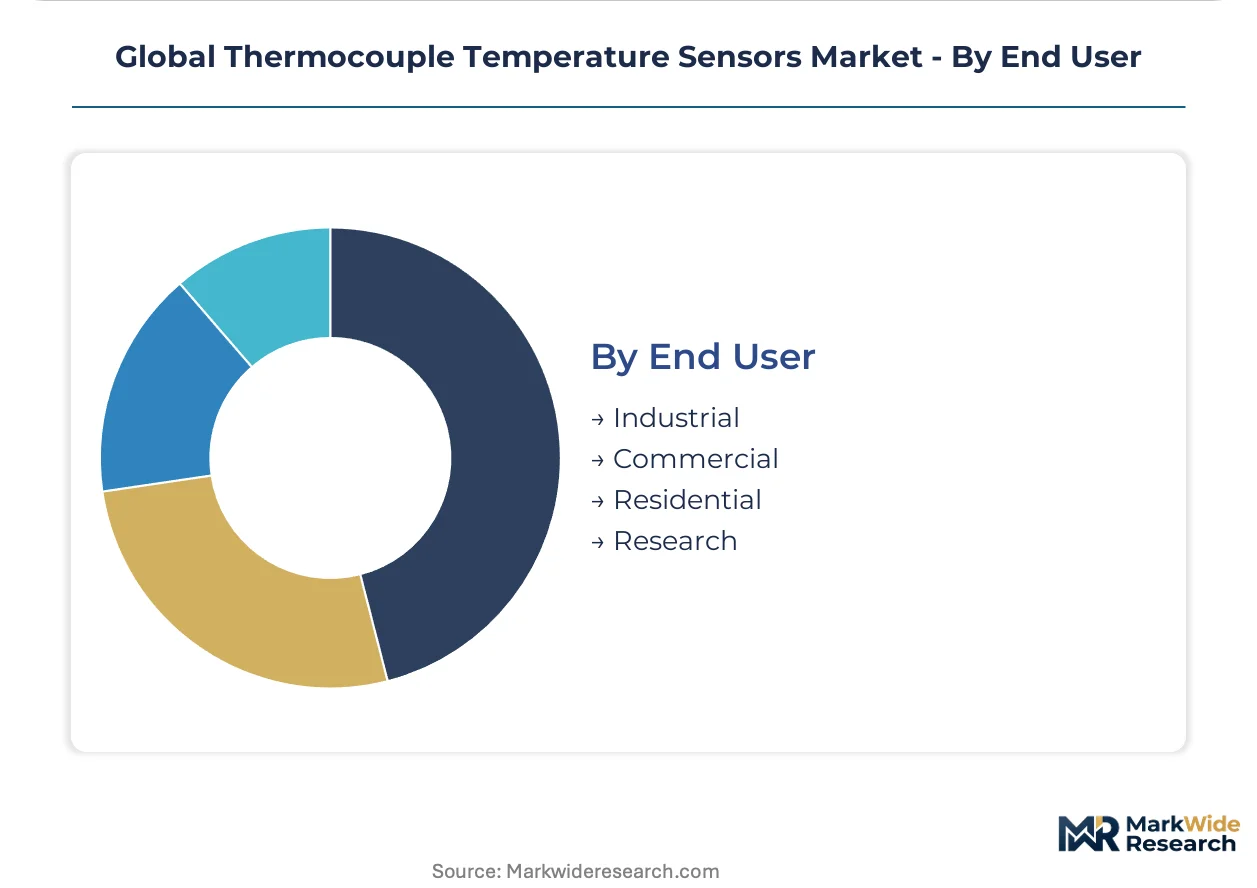
End User:
Budget authority and technical staffing determine whether organizations source validated sensor assemblies or commodity replacements.
- Industrial:Process manufacturers with in-house metrology labs negotiate calibration service contracts separately from hardware procurement. Texas and Louisiana refining corridors unbundle these relationships, sourcing sensors through distributors while retaining specialized calibration providers.
- Research:National laboratories and university engineering departments specify custom mineral-insulated constructions for extreme environment characterization. Oak Ridge National Laboratory maintains dedicated procurement channels for irradiation-resistant thermocouple designs.
- Commercial:Facility managers prioritize interchangeability and rapid availability over tolerance class optimization.
- Residential:Consumer-grade applications rely on integrated thermostat sensors with limited calibration requirements.
Industrial end users absorb the dominant revenue share, while Research institutions are climbing fastest in average transaction value through specialized engineering requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany's precision instrumentation cluster demonstrate lowest price elasticity, accepting premium calibration overhead, while China's smart factory corridors drive volume procurement with compressed margins. Demand fragmentation across regulatory jurisdictions creates divergent procurement specifications.
United States
EPA emissions monitoring standards under 40 CFR Part 60 and FDA food safety mandates generate dual regulatory pull for certified thermocouple assemblies. The FAA maintains millisecond-level latency requirements for aerospace turbine testing protocols. California propulsion test centers anchor West Coast demand for Type K chromel-alumel pairs in next-generation engine development.
Germany
REACH substance restrictions and CE marking requirements tighten material disclosure for chromel-alumel alloys used in Type K configurations. The EU Green Deal's F-Gas Regulation phase-down expands leak detection thermocouple demand in refrigeration monitoring. Precision instrumentation clusters in Bavaria specify grounded junctions for automotive powertrain validation labs.
China
MIIT smart factory deployment and dual carbon goals accelerate wireless sensor network integration into process control loops. GB standards and SAMR certification protocols shape domestic procurement specifications. Yangtze River Delta manufacturing corridors deploy ungrounded configurations for chemical reactor monitoring where stray currents threaten measurement integrity.
Japan
METI industrial automation incentives and JIS tolerance class standards determine supplier market access for component manufacturers. PMDA pharmaceutical manufacturing guidelines mandate continuous temperature validation with traceable sensor calibration. Kanto region electronics fabs anchor demand for mineral-insulated constructions in semiconductor process equipment.
India
BIS certification requirements and FSSAI food safety regulations expand replacement demand for validated thermocouple assemblies in commercial processing facilities. The PLI scheme for manufacturing incentivizes domestic sensor assembly capacity. Gujarat's chemical processing corridors and Maharashtra's pharmaceutical clusters drive industrial procurement volume.
Global Thermocouple Temperature Sensors Market Competitive Landscape
Full-line industrial conglomerates and specialized metrology houses split the market between bundled service contracts and unbundled hardware procurement. The vendor base concentrates around three strategic archetypes: diversified process automation suppliers with distributed service networks, European precision instrumentation specialists with metrology-certified refurbishment centers, and connectivity-focused component manufacturers extending authorized partner programs. Dominant competitive moves include geographic expansion through calibration service network density and technology licensing for wireless transmitter modules with integrated cold junction compensation.
Within the diversified automation tier, Emerson Electric Co and ABB Ltd occupy positions spanning hardware supply through recurring calibration contract capture. Among European precision specialists, WIKA Alexander Wiegand SE & Co. KG anchors metrology-certified service capabilities. TE Connectivity represents the connectivity-focused archetype with North American industrial replacement cycle positioning. These three exemplify divergent strategic paths: service network scale, regional metrology authority, and authorized partner program extension.
| Leading Market Players |
|---|
| Honeywell International Inc |
| Emerson Electric Co |
| Omega Engineering |
| TE Connectivity |
| ABB Ltd |
| WIKA Alexander Wiegand SE & Co. KG |
| Endress+Hauser Group |
| Danfoss A/S |
| KEYENCE CORPORATION |
| Others |
Supply & Pricing Matrix
Undercapacity in Germany's precision wire drawing facilities is driving order backlogs and selective supplier prioritization, compressing margins for aerospace-grade thermocouple manufacturers while amplifying pricing power for metrology-certified European specialists.
Pricing Analysis
Aftermarket calibration contracts capture the dominant lifetime value tier across the thermocouple value chain. Hardware procurement stratifies across premium IEC 60584 Class 1 certified assemblies, standard industrial-grade replacements, and economy ungrounded configurations for HVAC retrofits. Price differentiation rests on NIST traceability documentation and regional calibration network density. Cost compression in standard-grade Type K pairs is intensifying because chromel-alumel alloy input volatility squeezes spot-market suppliers. Research institutions demonstrate lowest price sensitivity, while commercial facility managers prioritize interchangeability and rapid availability over tolerance optimization.
Supply Chain Analysis
Export-control restrictions on precision mineral-insulated cable manufacturing equipment limit technology transfer to emerging sensor assembly hubs. Germany, China, and Japan anchor global supply for aerospace-grade conductors and ceramic insulator components. Raw material dependencies draw from nickel and chromium commodity markets, alumina ceramic substrates, and platinum-rhodium alloy feedstocks. Single-source vulnerability concentrates in Bavaria's precision instrumentation cluster where specialized wire drawing capabilities lack qualified secondary sources. Distribution runs through authorized service partner networks for industrial replacement cycles and direct OEM supply agreements for aerospace validation programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The thermocouple temperature sensors market functions as a regulatory-entrenchment defensive moat where NIST traceability mandates and IEC 60584 certification requirements create structural barriers to unqualified competitors.
For Market Incumbents: Harden calibration service network density in Texas and Louisiana refining corridors where end-users unbundle hardware and metrology procurement. Deepen backward integration into chromel-alumel alloy supply through captive wire drawing capacity or long-term offtake agreements with German precision metal suppliers. Solid-state RTD and infrared substitution threats demand accelerated wireless transmitter module development with integrated cold junction compensation. For New Entrants and Emerging Players: India's Gujarat chemical processing and Maharashtra pharmaceutical clusters offer underpenetrated white-space for validated thermocouple assemblies with BIS certification. Wireless HVAC retrofit architectures in China's Yangtze River Delta smart factory corridors present fastest penetration potential where installation flexibility outweighs calibration rigor. Partner with established European metrology houses for NIST-traceable coefficient documentation rather than building captive calibration infrastructure. For Investors and Strategic Acquirers: Capital is best deployed toward metrology-certified refurbishment center operators with recurring calibration contract books in FDA-regulated food processing and EPA-mandated emissions monitoring verticals. Long-term viability across the analysis window favors service-unbundled business models over hardware-centric commodity positioning. Monitor F-Gas Regulation phase-down acceleration across EU member states as inflection signal for refrigeration leak detection thermocouple demand expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Calibration Service Network Expansion | Emerson Electric's distributed service footprint captures recurring EPA and FDA-mandated recertification contracts in process industries. |
| Wireless Transmitter Module Development | Integrated cold junction compensation architectures eliminate conduit installation costs in Germany's food processing refrigerated warehouse retrofits. |
| Backward Integration into Alloy Supply | Captive chromel-alumel wire drawing capacity insulates margins from nickel and chromium commodity volatility affecting Type K manufacturers. |
| Metrology-Certified Refurbishment Center Buildout | WIKA's European service hubs anchor regional demand through CE-marked refurbishment with full REACH substance documentation. |
| Authorized Service Partner Program Extension | TE Connectivity's North American industrial replacement cycle positioning leverages distributor relationships for rapid availability. |
Research Methodology
Operator-level perspectives from plant engineers, maintenance directors, OEM procurement teams, and aftermarket service heads anchored the qualitative base for this thermocouple temperature sensors analysis. Primary interview insights combined with secondary validation from IEC 60584 calibration standard documentation, EPA 40 CFR Part 60 emissions monitoring filings, FDA food safety inspection records, and SEC 10-K disclosures from listed industrial automation suppliers. Bottom-up sensor unit demand modeling triangulated against top-down process industry capital expenditure patterns.
Scenario-bracketing around regulatory enforcement intensity and smart factory deployment pace structured the analytical framework across the projection horizon. Segmentation dimensions modeled include junction configuration type, signal conditioning technology, application vertical, and end-user budget authority tier. CAGRs derived from installed base replacement cycle analysis and wireless architecture adoption curve modeling. Industry-specific forecast inputs incorporated REACH substance restriction phase-in schedules and MIIT smart factory integration targets.
Practitioners should monitor EPA enforcement variance across state implementation plans and EU F-Gas Regulation acceleration timelines for early signals of demand inflection. Forecasts reflect documented assumptions regarding calibration technician workforce availability and nickel commodity price bands. Material shifts in IEC 60584 tolerance class adoption or solid-state sensor cost-performance ratios would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Inductive and LVDT Sensors Market
Sensors and Controls
APAC Pressure Sensors Market
Sensors and Controls
Ultrasound Sensors Market
Sensors and Controls
Sensor Development Kit Market
Sensors and Controls
Doppler Lidar Market
Sensors and Controls
Speech Intelligibility Devices Market
Sensors and Controls
Active Vibration Control Market
Sensors and Controls
Global Temperature Sensors Market
Sensors and Controls
Variable Reluctance Sensor Market
Sensors and Controls
Ultrasonic Sensors Market
Sensors and Controls
Global Tilt Sensor Market
Sensors and Controls
United States (US) Industrial Sensors Market
Sensors and Controls
Automotive Cabin Air Quality Sensors Market
Sensors and Controls
Global Multi-Turn Potentiometer Market
Sensors and Controls
Fingerprint Module Market
Sensors and Controls
Distance Measurement Sensor Market