
 Blue-Green Algae Sensors Market | 2026-2036
Blue-Green Algae Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Blue-Green Algae Sensors Market Insights
The municipal procurement channel is rewriting how environmental instrumentation reaches end users across North America and Asia-Pacific. Hydrolab leverages its long-standing relationships with U.S. water utilities to sustain repeat instrumentation contracts. Shanghai Boqu Instrument competes aggressively on cost while extending its service network across provincial environmental bureaus in China. bbe Moldaenke GmbH differentiates through specialized fluorescence detection modules that occupy premium positions in European research installations.
Blue-green algae sensors detect cyanobacteria populations through optical, electrochemical, or fluorescence-based methods, typically resolving chlorophyll-a and phycocyanin concentrations at parts-per-billion thresholds to trigger early warnings for toxic blooms. Their primary purpose is to prevent public exposure to microcystins and other cyanotoxins in drinking water, recreational waters, and aquaculture systems. Portable sensors lead current unit shipments due to lower capital barriers for smaller municipalities and field research teams, while in-situ monitors capture the fastest expansion as continuous monitoring mandates spread across watershed districts. Optical sensors dominate the technology mix, though fluorescence detection commands higher margins from customers requiring species-level discrimination between harmful and benign algal strains.
The EPA sets enforceable cyanotoxin thresholds under the Safe Drinking Water Act, while China's MEE enforces surface water quality standards that include algae-related parameters across major river basins. ISO 10260 provides standardized chlorophyll-a measurement protocols that manufacturers must address for cross-border equipment acceptance. Stakeholders should monitor how regulatory deadlines for real-time source water monitoring reshape capital allocation between portable and fixed-installation sensor platforms.
Market Dynamics
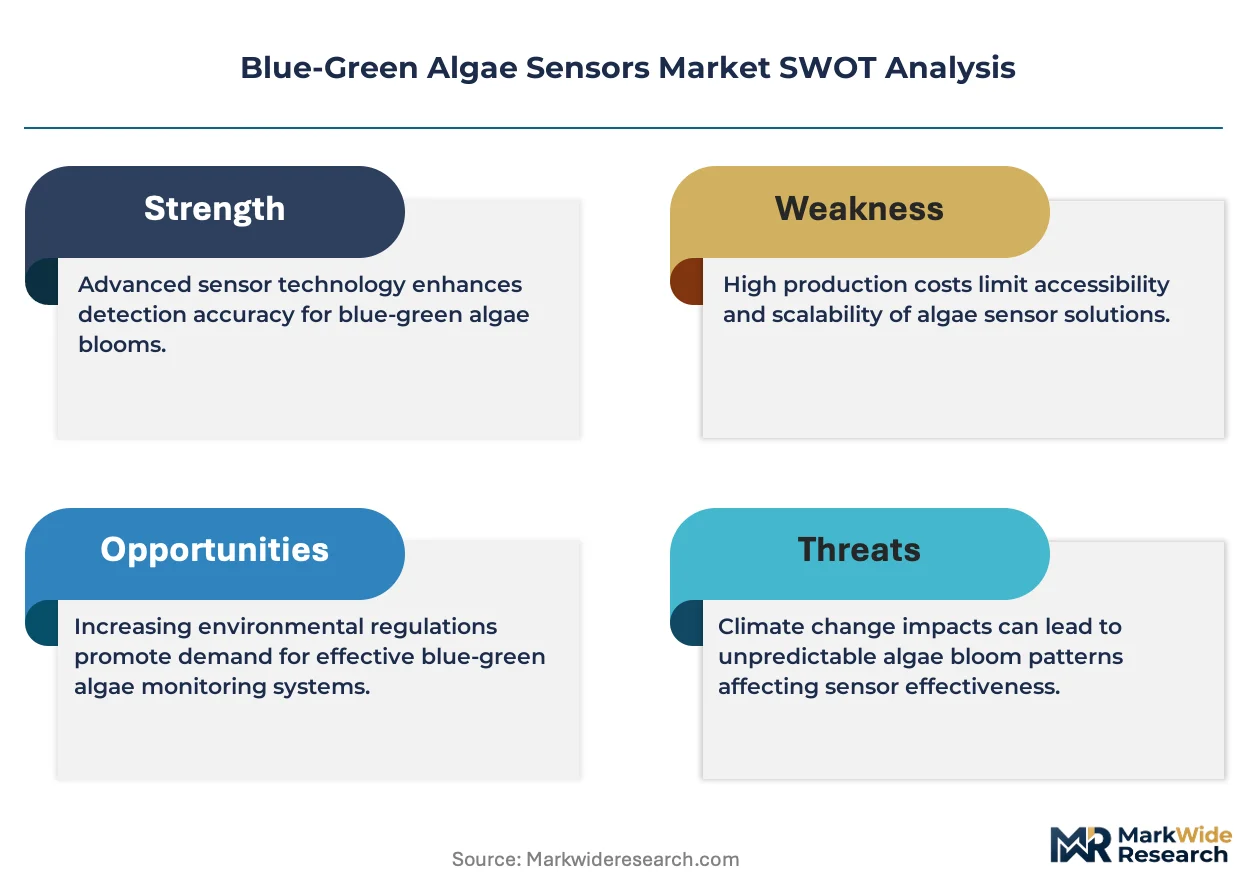
Municipal water utilities face mounting pressure to deploy continuous cyanotoxin monitoring infrastructure as regulatory thresholds tighten and public liability exposure escalates from harmful algal bloom events.
Growth Catalysts
- EPA cyanotoxin health advisories:Revised microcystin and cylindrospermopsin limits under the Safe Drinking Water Act compel utilities to upgrade from periodic sampling to real-time detection systems.
- Fluorescence spectroscopy:Advances in phycocyanin-specific excitation wavelengths enable species-level discrimination between toxic Microcystis and benign Anabaena strains, justifying premium sensor deployments.
- Yangtze River basin enforcement:China's MEE surface water quality standards now incorporate algae-related parameters across provincial monitoring networks, expanding instrumentation mandates.
Market Restraints
- Optical component supply concentration:High-precision photomultiplier tubes and narrow-band interference filters depend on limited German and Japanese specialty manufacturers, creating procurement bottlenecks.
- Calibration complexity:Chlorophyll-a reference standards require freeze-dried phytoplankton cultures from certified biological resource centers, extending deployment timelines.
- Electrochemical sensor drift:Dissolved oxygen interference and biofouling on electrode surfaces degrade measurement stability in eutrophic waters, limiting unattended operational periods.
Strategic Opportunities
- India's Ganga rejuvenation program:National Mission for Clean Ganga allocations for water quality monitoring create untapped demand for portable algal biomass sensors at tributary confluence points.
- IoT-5G convergence:Low-latency cellular networks enable edge-computing sensor arrays that transmit bloom alerts directly to public health dashboards without SCADA integration.
- Aquaculture insurance underwriting:Parametric policies for fish kill losses now require verified algal density thresholds, creating subscription-based sensor-as-a-service revenue models.
Industry Challenges
- Interoperability with legacy SCADA:Municipal utilities operate decades-old control systems with proprietary protocols, forcing costly middleware development for sensor integration.
- Field technician training gaps:Fluorescence calibration procedures and quality assurance protocols exceed the skill base of typical water treatment plant operators, requiring dedicated instrumentation specialists.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Blue-Green Algae Sensors Market |
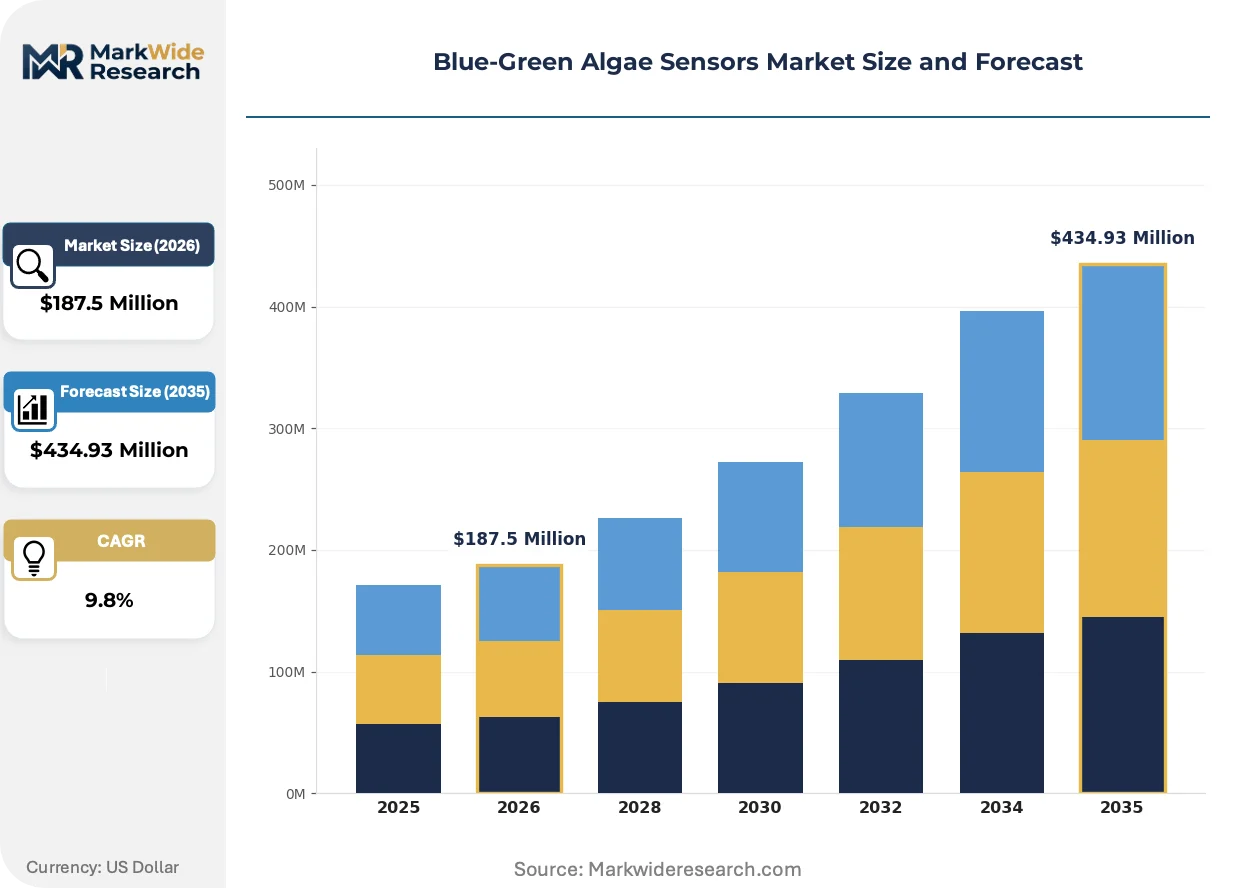
| Market Size in 2026 | $187.5 Million |
| Market Size in 2035 | $434.93 Million |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Sensors, In-Situ Monitors, Lab Analysis Kits, Satellite Sensors Technology: Optical Sensors, Electrochemical Sensors, Fluorescence Detection, Biological Sensors Application: Water Quality Monitoring, Wastewater Treatment, Research & Development, Aquaculture End User: Environmental Agencies, Research Institutions, Aquaculture Farms, Municipalities |
| Companies Covered | Hydrolab, Shanghai Boqu Instrument, Suzhou Delfino Environmental Technology, GI Instruments Québec Inc., GL Environment, Aquaread, In-Situ Inc., Eureka Water Probes, bbe Moldaenke GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Blue-Green Algae Sensors Market Trends and Innovations
Real-time water quality instrumentation is pivoting from laboratory-dependent workflows to autonomous field-deployable systems that compress detection-to-decision cycles from days to minutes.
Hyperspectral imaging is digitizing algal population assessment through continuous spectral signature capture across 200-plus wavelength bands. Research installations and advanced treatment plants in the Great Lakes basin are piloting these systems to map bloom spatial heterogeneity. The technology is digitizing how utilities allocate treatment chemical dosing by replacing grab-sample spot measurements with dynamic concentration gradient mapping.
REACH authorization requirements for mercury-containing devices are accelerating LED-based excitation source adoption in fluorescence sensors. European manufacturers must phase out traditional mercury-vapor lamps by 2026, compressing redesign cycles for portable field instruments. The regulatory pressure is reshaping component sourcing strategies, with Asian suppliers capturing increased share of solid-state UV emitter production.
Subscription-based monitoring services are displacing capital equipment purchases among smaller watershed districts and private lake associations. Hydrological consulting firms deploy owned sensor fleets, charging per-sample or per-alert fees rather than selling hardware outright. This model is expanding fastest in the United States among recreational water managers lacking in-house technical capacity for instrument maintenance and data interpretation.
Blue-Green Algae Sensors Market Segmentation
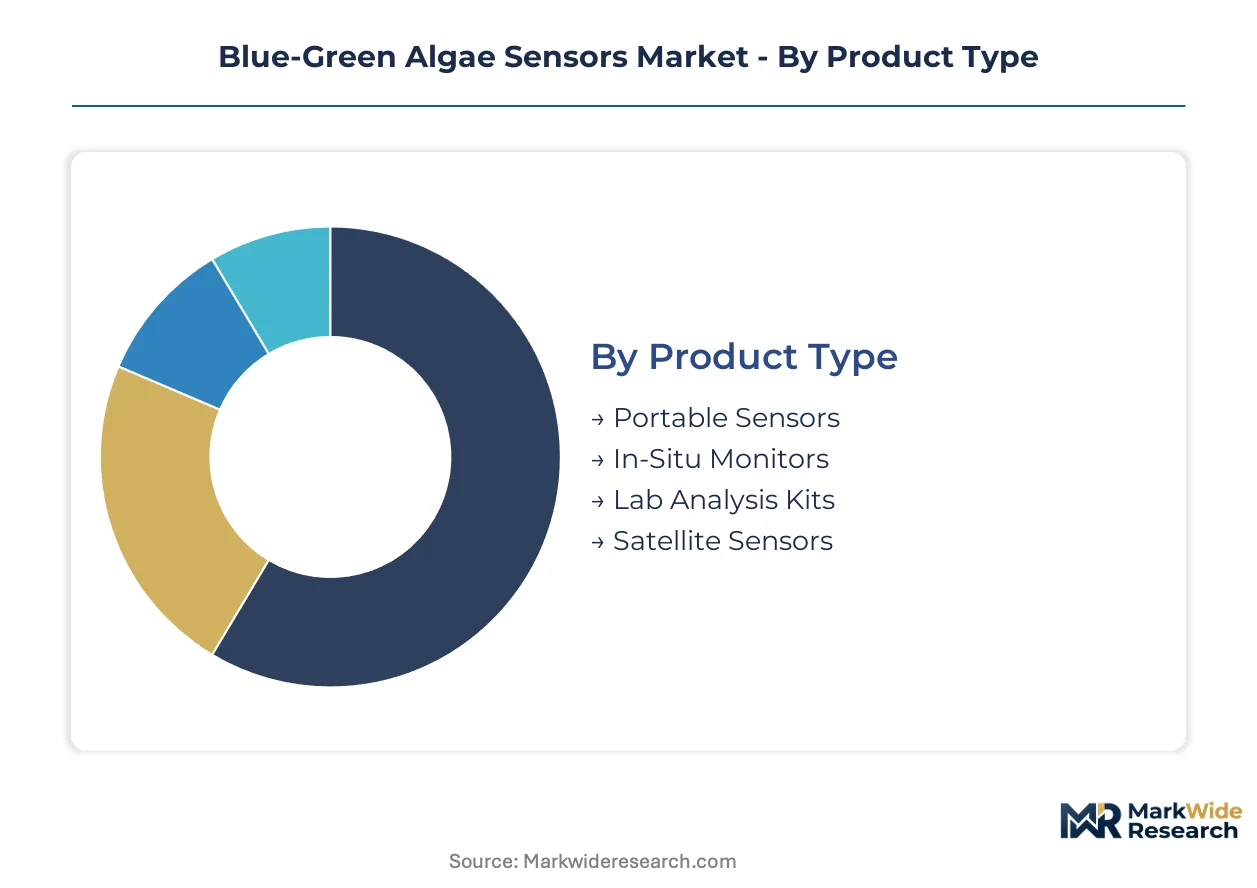
Blue-green algae sensors serve distinct operational contexts—from rapid field response to continuous watershed surveillance—each demanding different performance specifications, durability thresholds, and data transmission architectures. Segmentation reveals how procurement priorities diverge between regulatory compliance mandates and research precision requirements.
Product Type:
The maturity spectrum spans decades-old portable instruments to emerging satellite-based detection platforms still validating operational parameters.
- Portable Sensors:Handheld units integrate optical or fluorescence probes with battery-powered data loggers for rapid deployment at bloom outbreak sites. Municipal utilities across the Great Lakes basin favor these for spot-checking intake points without permanent infrastructure investment.
- In-Situ Monitors:Fixed installations with autonomous power and telemetry enable continuous chlorophyll-a and phycocyanin tracking at reservoir depths. China's Yangtze River delta provincial bureaus are expanding these deployments to meet MEE real-time reporting mandates.
- Lab Analysis Kits:Benchtop systems with standardized extraction protocols serve regulatory compliance laboratories requiring certified reference methods.
- Satellite Sensors:Hyperspectral imagers on orbital platforms provide basin-scale bloom mapping, though spatial resolution limits utility for localized source water protection.
Portable sensors retain volume leadership; in-situ monitors hold the steepest expansion curve.
Technology:
Cost tiers separate commodity optical approaches from premium fluorescence systems commanding specialized procurement budgets.
- Optical Sensors:Turbidity-compensated absorbance measurements at 665nm and 750nm wavelengths deliver chlorophyll-a estimates at lowest capital cost. These dominate municipal procurement where species discrimination is secondary to biomass threshold detection.
- Fluorescence Detection:Phycocyanin-specific excitation at 620nm enables toxic Microcystis identification versus benign strains, justifying premium pricing for utilities facing liability exposure from cyanotoxin events. European research installations specify these for species-level ecological studies.
- Electrochemical Sensors:Dissolved oxygen and pH electrode arrays proxy algal metabolic activity, though biofouling limits unattended operation in eutrophic conditions.
- Biological Sensors:Whole-cell biosensors and molecular probes remain experimental, with limited commercial availability outside specialized research contracts.
Optical sensors dominate unit shipments; fluorescence detection captures margin expansion.
Application:
Customer type segmentation reveals divergent technical requirements between regulatory enforcement and production agriculture.
- Water Quality Monitoring:Source water protection programs drive the largest instrumentation volumes, with EPA cyanotoxin health advisories compelling real-time infrastructure upgrades across U.S. watershed districts.
- Aquaculture:Fish farm operators deploy dissolved oxygen and algal density sensors to predict harmful bloom events before stock mortality, with insurance underwriters now mandating verified monitoring for parametric policy eligibility.
- Wastewater Treatment:Nutrient removal facilities monitor effluent algae loads to demonstrate compliance with total maximum daily load permits.
- Research & Development:Academic and government laboratories specify multi-parameter fluorometers for ecological process studies with publication-grade data quality requirements.
Water quality monitoring anchors procurement volume; aquaculture applications are climbing fastest.
End User:
Supply concentration varies sharply between centralized government procurement and fragmented private farm purchasing.
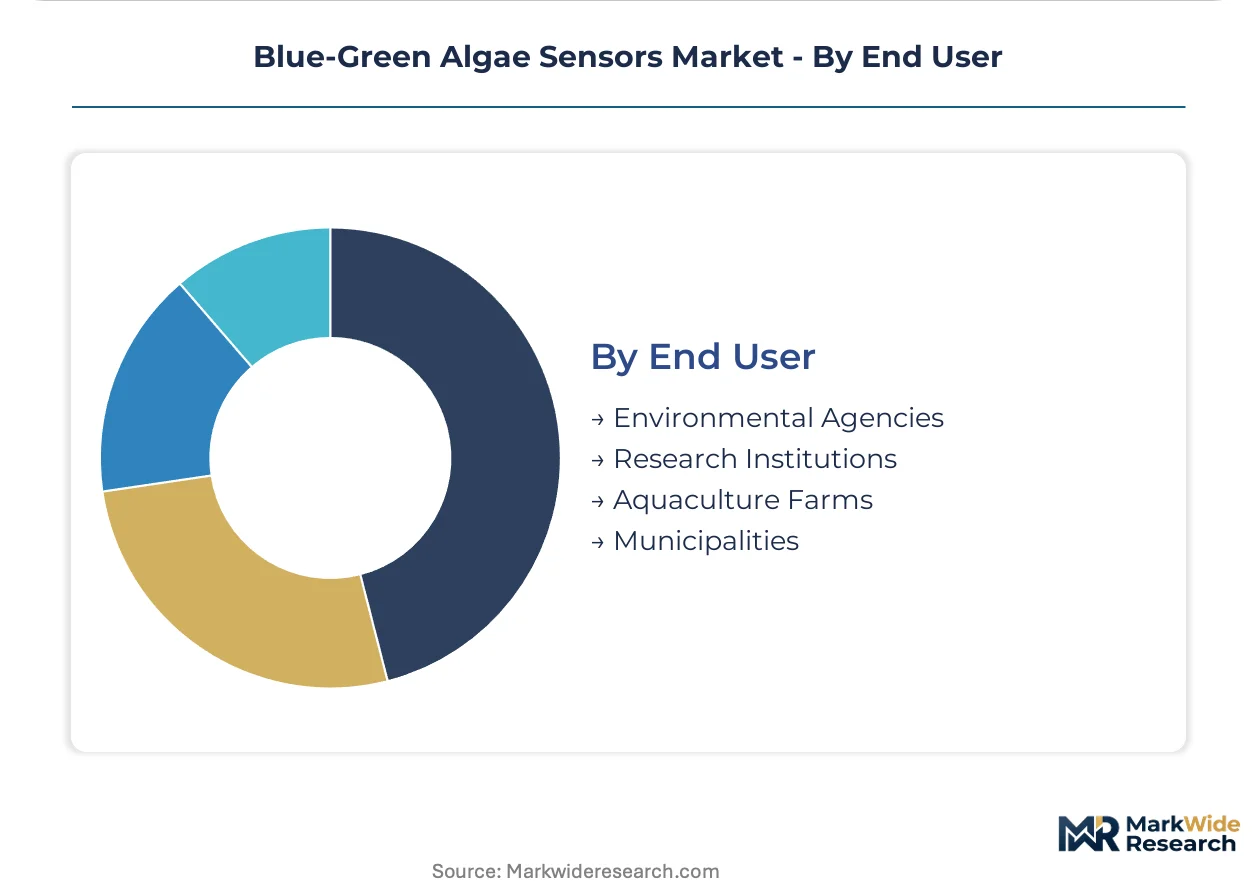
- Municipalities:Water utilities consolidate demand through formal bidding processes, favoring established vendors with SCADA integration capabilities and multi-year service contracts.
- Environmental Agencies:State and provincial regulators deploy sensor networks for watershed surveillance, with China's MEE surface water standards directly mandating provincial monitoring infrastructure expansion.
- Aquaculture Farms:Private operators prioritize low-cost portable units with minimal calibration requirements, creating price-sensitive demand concentrated in coastal production zones.
- Research Institutions:Universities and government laboratories specify premium fluorescence systems with published validation studies, accepting longer procurement cycles for precision instrumentation.
Municipalities represent the largest addressable base; aquaculture farms are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Great Lakes-St. Lawrence Seaway anchors North American demand for cyanobacteria monitoring infrastructure, while China's Yangtze River Delta waterways drive Asia-Pacific procurement volumes.
United States
EPA cyanotoxin health advisories under the Safe Drinking Water Act compel municipal utilities across the Great Lakes basin to upgrade from periodic sampling to real-time detection systems. Toledo, Ohio and Green Bay, Wisconsin represent concentrated deployment zones where harmful algal bloom events have triggered capital allocation toward in-situ monitoring arrays.
China
MEE surface water quality standards now incorporate algae-related parameters across provincial monitoring networks in the Yangtze River delta. Shanghai and Jiangsu province environmental bureaus are expanding instrumentation mandates, with Suzhou and Nanjing emerging as procurement hubs for fluorescence-based detection systems.
Germany
REACH authorization requirements for mercury-containing devices accelerate LED-based excitation source adoption in fluorescence sensors. Bavarian and Baden-Württemberg research installations specify premium detection modules for species-level ecological studies, with Munich and Stuttgart hosting validation centers for chlorophyll-a reference protocols.
Canada
Health Canada guidelines for cyanobacterial toxins in drinking water drive provincial utility procurement across Ontario and Quebec. Lake Erie watershed monitoring programs concentrate sensor deployments near Windsor and the Niagara Peninsula, where cross-border bloom events necessitate coordinated detection infrastructure.
India
The National Mission for Clean Ganga allocates funding for water quality monitoring at tributary confluence points. Uttar Pradesh and Bihar state pollution control boards are piloting portable algal biomass sensors, with Varanasi and Patna representing initial deployment sites for field-verified cyanobacteria detection.
Blue-Green Algae Sensors Market Competitive Landscape
On the supply side, the industry is bifurcated between established water instrumentation conglomerates and specialized optical sensor developers. The vendor landscape organizes into three strategic archetypes: full-suite water quality platform providers, fluorescence detection specialists, and cost-optimized regional fabricators. Dominant competitive moves include SCADA integration capability building and multi-year municipal service contracting.
Within the premium-tier vector, bbe Moldaenke GmbH exemplifies specialized fluorescence detection expertise, while Hydrolab represents the established utility relationship archetype. Shanghai Boqu Instrument occupies a position among cost-competitive regional fabricators extending service networks across provincial environmental bureaus.
| Leading Market Players |
|---|
| Hydrolab |
| Shanghai Boqu Instrument |
| Suzhou Delfino Environmental Technology |
| GI Instruments Québec Inc. |
| GL Environment |
| Aquaread |
| In-Situ Inc. |
| Eureka Water Probes |
| bbe Moldaenke GmbH |
| Others |
Pricing and Supply Chain Analysis
German and Japanese specialty manufacturers of high-precision photomultiplier tubes and narrow-band interference filters concentrate upstream supply, concentrating margin capture in fluorescence detection modules while commoditizing optical sensor tiers downstream.
Pricing Analysis
Volume-discount tiering separates municipal procurement contracts from spot purchases by aquaculture farms and research laboratories. Three-tier pricing structure across premium fluorescence systems, standard optical units, and economy portable probes reflects certification grade and SCADA integration complexity. Cost compression in economy tiers is intensifying because Shanghai Boqu Instrument and regional Chinese fabricators expand service networks. Aquaculture farms exhibit highest price sensitivity due to uninsured operational risk, while European research installations accept premium positioning for species-level discrimination capabilities.
Supply Chain Analysis
Export-control restrictions on high-precision optical components limit flows of German-manufactured photomultiplier tubes and Japanese narrow-band interference filters to Chinese sensor assemblers. Component sourcing concentrates in Germany, Japan, and China for excitation sources, optical benches, and telemetry modules. Raw material dependencies include rare-earth phosphors for LED excitation, fused silica for optical windows, and marine-grade aluminum for probe housings. Single-source vulnerability in photomultiplier tube supply creates procurement bottlenecks. Distribution runs through municipal bidding channels, hydrological consulting firms, and direct OEM sales to research institutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Municipal procurement consolidation across U.S. Great Lakes utilities and Yangtze River delta bureaus is shifting buyer power toward formal bidding processes, squeezing margin pools for sensor vendors lacking multi-year service contracts.
For Market Incumbents: Build switching-cost moats through SCADA integration certification and captive calibration service contracts. Incumbents should deepen backward integration into LED excitation source production to offset REACH-driven mercury lamp phaseouts. Threats from low-cost Chinese entrants in portable segments require defensive capacity positioning in fluorescence detection modules where technical complexity sustains premium pricing. For New Entrants and Emerging Players: Build out portable sensor-as-a-service offerings targeting India's National Mission for Clean Ganga tributary monitoring points where procurement capacity is nascent. White-space targets include parametric aquaculture insurance underwriting partnerships and IoT-5G edge-computing arrays for recreational water managers. Go-to-market angle should emphasize subscription-based per-alert pricing rather than capital equipment sales. For Investors and Strategic Acquirers: Capital is best deployed toward fluorescence detection specialists with validated chlorophyll-a reference protocols and established relationships with European research installations. Long-term viability centers on regulatory enforcement durability across EPA cyanotoxin mandates and China's MEE surface water standards. Signal to watch is provincial monitoring infrastructure budget allocation velocity in secondary Chinese river basins.| Strategic Initiative | Industry Significance |
|---|---|
| LED Excitation Source Transition | REACH mercury lamp phaseouts by 2026 force component redesign cycles for portable field instruments. |
| SCADA Integration Certification | Municipal utilities demand middleware compatibility with decades-old control systems and proprietary protocols. |
| Subscription Service Model Deployment | Hydrological consulting firms displace capital sales with per-sample fees among watershed districts lacking technical capacity. |
| Hyperspectral Imaging Pilot Expansion | Great Lakes utilities digitize bloom spatial heterogeneity for dynamic treatment chemical dosing allocation. |
| Provincial Bureau Service Network Extension | China's MEE mandates drive instrumentation procurement across Jiangsu and Shanghai environmental monitoring hubs. |
Research Methodology
The analysis maps portable sensors, in-situ monitors, lab analysis kits, and satellite detection platforms, each validated through municipal water utility procurement officers, provincial environmental bureau technical directors, aquaculture farm operators, and fluorescence calibration specialists. Primary interviews with watershed district managers and hydrological consulting firm principals combined with secondary validation from EPA cyanotoxin health advisory filings, China's MEE surface water quality standards, ISO 10260 chlorophyll-a protocols, and municipal bidding records. Bottom-up unit shipment estimates triangulate against top-down infrastructure spending allocations across the Great Lakes and Yangtze River delta regions.
Assumption sets held regulatory enforcement timelines and technology substitution curves fixed while varying provincial budget allocation velocities and aquaculture insurance underwriting adoption rates. Segmentation dimensions modeled include product type, detection technology, application context, and end-user procurement channel across the projection horizon. CAGRs derive from infrastructure mandate compliance schedules and replacement cycle analysis. Industry-specific forecast inputs incorporate fluorescence detection module cost curves and LED excitation source manufacturing scale trajectories.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese cost-optimized fabricators or hyperspectral imaging platform entrants would shift outcomes. Material shifts in EPA cyanotoxin threshold enforcement intensity or China's MEE provincial delegation of monitoring authority would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
North America Occupancy Sensors Market
Sensors and Controls
Body Worn Antenna Market
Sensors and Controls
Smart Flow Meter Market
Sensors and Controls
Wired Occupancy Sensors Market
Sensors and Controls
Tooth Mounted Sensor Market
Sensors and Controls
APAC Proximity Sensors Market
Sensors and Controls
Capacitive Pressure Sensor Market
Sensors and Controls
Piezoelectric MEMS Resonators Market
Sensors and Controls
Inline Viscosity Sensor Market
Sensors and Controls
Hydrogen Pressure Sensor Market
Sensors and Controls
Odor Sensor Market
Sensors and Controls
United States Sensor Market
Sensors and Controls
Window Sensors Market
Sensors and Controls
Fingerprint Module Market
Sensors and Controls
Middle East and Africa Touch Sensor Market
Sensors and Controls
HVAC Sensor Market