
 Toy Drones Market | 2026-2036
Toy Drones Market Size, Share, and Industry Trends Forecast 2026-2036
Toy Drones Market Analytics
Subscription-based leasing and asset-light rental models for consumer drone fleets is reshaping competitive dynamics in the toy drones sector. DJI leverages its Shenzhen manufacturing base to sustain cost advantages across quadcopter lines. Syma Toys anchors volume production through deep integration with Guangdong component suppliers. Parrot differentiates via European design positioning and educational software bundling.
Toy drones are unmanned aerial vehicles weighing under 250 grams, typically constructed from ABS plastic or expanded polypropylene foam, incorporating brushless motors, lithium-polymer batteries, and gyroscopic stabilization systems for recreational flight. Quadcopters dominate unit volume due to mechanical simplicity and stability, while gliders capture niche margin pools among hobbyist collectors seeking unpowered flight authenticity. Educational application drones are expanding fastest as schools integrate UAV modules into STEM curricula, with remote control systems remaining the primary interface despite smartphone app penetration among teen demographics.
FAA registration requirements for drones exceeding 0.55 pounds and the EU's CE marking under delegated regulation 2019/945 constrain product design and channel access for manufacturers serving Western markets. China's SAMR enforces GB standard compliance for domestic sales while MIIT oversees radio transmission certifications that affect controller frequencies. Stakeholders must monitor evolving low-altitude airspace classifications and battery transport regulations as jurisdictions refine consumer UAV governance frameworks.
Market Dynamics
STEM curriculum mandates across US middle schools and EU secondary education systems are accelerating educational drone procurement, compressing sales cycles from seasonal retail peaks to institutional purchasing calendars tied to academic budgets.
Growth Catalysts
- Educational Procurement Mandates:US state-level STEM funding initiatives and EU Erasmus+ digital education allocations are institutionalizing UAV modules in secondary school technology curricula, creating recurring annual demand cycles distinct from holiday retail patterns.
- FAA Part 107 Certification Pathways:The FAA's remote pilot certification framework for sub-250g operations is legitimizing youth drone programs as career pipeline investments, driving parental purchases of training-grade equipment over disposable toy alternatives.
- Shenzhen Component Ecosystem Density:Guangdong Province's concentrated brushless motor, lithium-polymer battery, and flight controller manufacturing clusters enable rapid prototype-to-production cycles for new entrants, lowering capital barriers for specialized educational drone developers.
Market Restraints
- Lithium-Polymer Battery Supply Concentration:Cathode material processing and cell manufacturing concentrate in China's Yangtze River Delta and Pearl River Delta regions, exposing non-Chinese assemblers to raw material allocation disruptions and export licensing volatility.
- EU CE Marking Compliance Burden:Delegated Regulation 2019/945 mandates electromagnetic compatibility testing, radio equipment conformity assessment, and technical documentation retention that extends product development timelines by 4-8 months for European market entry.
- Altitude-Restricted Flight Zones:Municipal geofencing implementations around airports, stadiums, and government facilities in the US, EU, and China are compressing usable recreational airspace, reducing perceived utility value among casual consumers.
Strategic Opportunities
- Underpenetrated Indian Education Sector:India's National Education Policy 2020 emphasis on experiential learning and Atal Tinkering Lab expansion creates institutional procurement channels for coding-integrated drone kits, with BIS certification requirements still evolving relative to mature Western frameworks.
- Subscription Fleet Leasing Models:Asset-light rental programs for school districts and summer camp operators reduce upfront capital barriers while generating recurring revenue streams and captive aftermarket parts demand.
- AI-Enabled Autonomous Flight Convergence:Integration of computer vision modules and edge computing chipsets is enabling self-navigating educational drones that reduce instructor supervision requirements, expanding deployability in resource-constrained learning environments.
Industry Challenges
- Flight Instructor Certification Bottlenecks:Scarcity of FAA-certified remote pilots with pedagogical training limits scalable deployment of school-based drone programs, constraining revenue realization from institutional sales pipelines.
- Cross-Border Radio Frequency Harmonization:Divergent MIIT, FCC, and ETSI spectrum allocations for 2.4GHz and 5.8GHz control links force hardware variant proliferation, fragmenting production runs and complicating inventory management for multi-region vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Toy Drones Market |
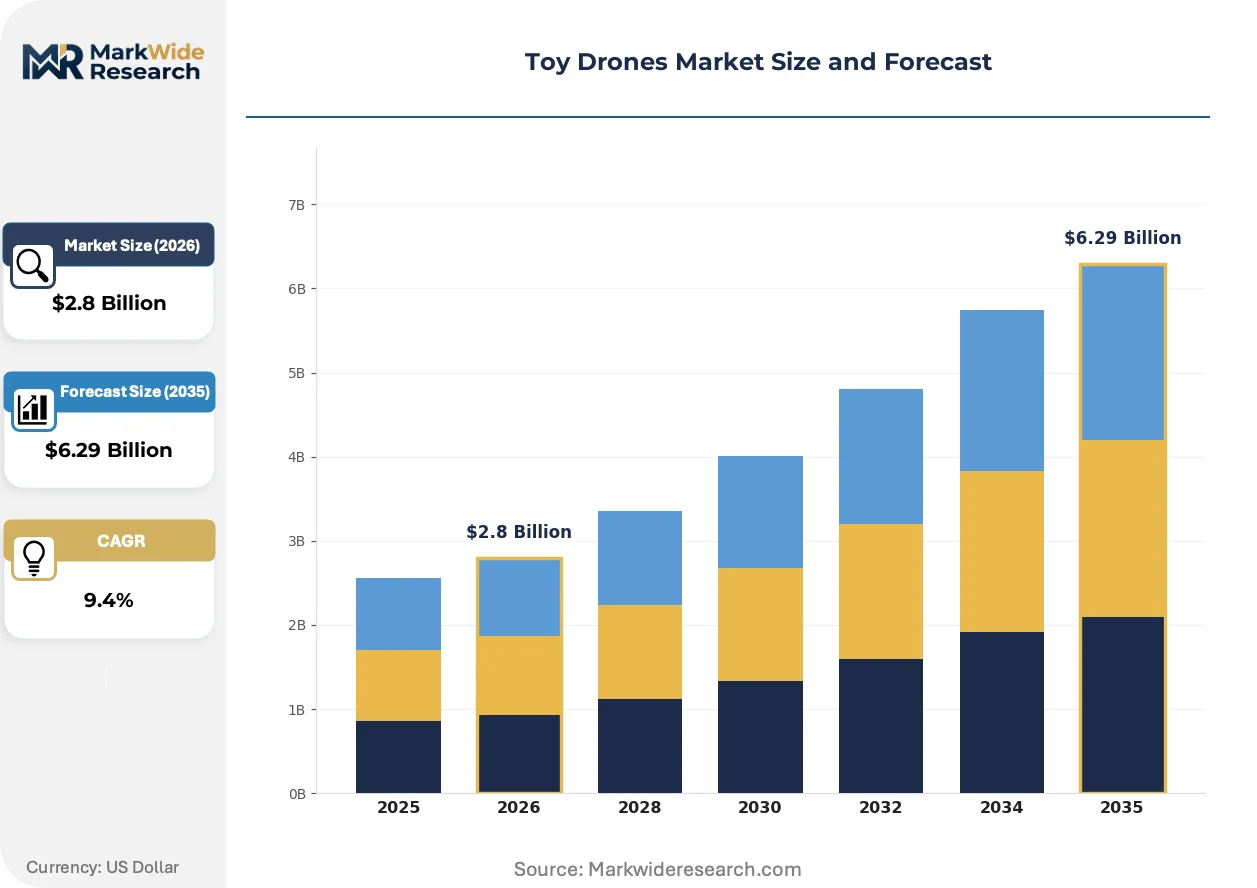
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $6.29 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Quadcopters, Helicopters, Airplanes, Gliders Age Group: Children, Teens, Adults, All Ages Application: Recreational, Educational, Sports, Competitions Control Type: Remote Control, Smartphone Apps, Gesture Control, Voice Control |
| Companies Covered | Syma Toys, Yuneec International, DJI, UDIRC, Guangdong Syma Model Aircraft Industrial, Parrot, Autel Robotics, Heygelo, Hubsan, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Toy Drones Market Evolving Landscape
Flight control architectures and powertrain configurations are diverging sharply between recreational simplicity and educational programmability, creating distinct technical roadmaps that reshape supplier relationships and margin structures.
Brushless motor systems are replacing brushed DC architectures in mid-tier toy drones. Hobbyist collectors and STEM educators are adopting these configurations for extended duty cycles and repairability. The technology is migrating from premium racing quadcopters into sub-$150 educational platforms, compressing the performance gap between toy and prosumer categories.
China's SAMR is tightening GB standard enforcement for lithium-polymer battery thermal runaway containment in domestically sold UAVs. Manufacturers must now submit cell-level abuse testing documentation and integrate redundant protection circuits. Domestic brands are absorbing compliance costs through in-house battery pack assembly, while export-oriented assemblers face dual certification burdens for home and Western markets.
Institutional buyers are consolidating vendor relationships through multi-year curriculum licensing agreements. School districts in Texas, California, and Ontario are replacing transactional hardware purchases with bundled content subscriptions that include lesson plans, educator training, and fleet management software. This pattern is most pronounced in North American public education procurement, where technology coordinators prioritize vendor accountability over unit cost minimization.
Toy Drones Market Segmentation
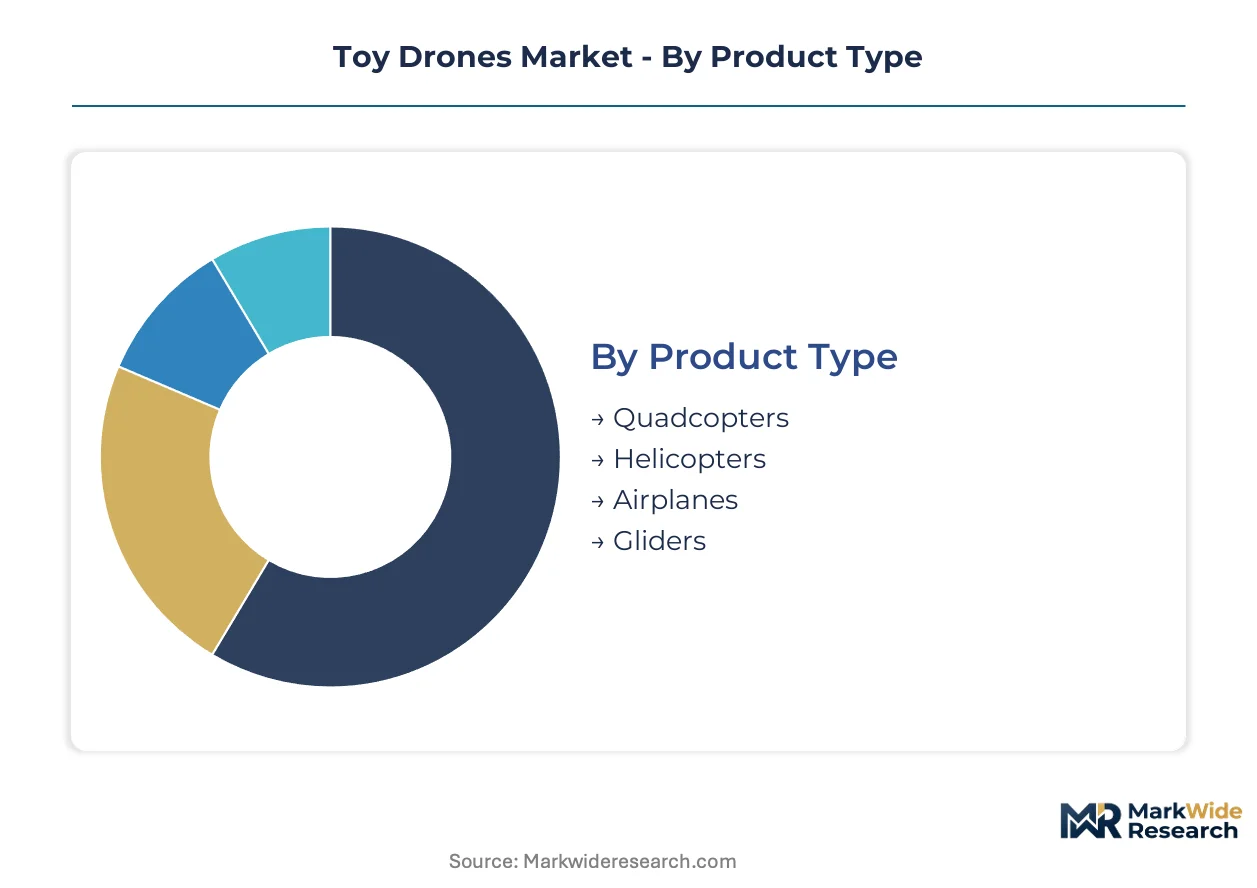
Segmentation in toy drones separates volume-driven recreational units from margin-rich educational platforms with divergent technical requirements and procurement cycles. Manufacturers must configure distinct supply chains for ABS plastic toy-grade output versus repairable brushless motor systems serving institutional buyers.
Product Type:
Mechanical architecture determines material selection, motor specification, and flight stability characteristics across price tiers.
- Quadcopters:Four-rotor configurations with gyroscopic stabilization dominate unit economics through mechanical simplicity and crash tolerance. Demand concentrates in mass-market retail channels serving children and casual hobbyists, with Shenzhen's component ecosystem enabling sub-$50 entry points.
- Helicopters:Single-rotor designs with tail rotor anti-torque systems demand precise balancing and collective pitch control. Enthusiast collectors in Japan and Germany sustain niche demand for scale-model fidelity and aerobatic performance.
- Airplanes:Fixed-wing foam constructions prioritize flight duration over maneuverability, appealing to outdoor recreational users in Australia and Canada with expansive open spaces.
- Gliders:Unpowered flight platforms with expanded polypropylene fuselages capture hobbyist margins through thermal soaring authenticity.
Quadcopters command the established base. The steepest expansion runs through gliders as STEM programs adopt unpowered flight physics modules.
Age Group:
Developmental capability and purchasing authority split the market between gift-buying parents and self-directed adolescent or adult enthusiasts.
- Children:Users under 12 years operate simplified three-channel controls with altitude hold and propeller guards. Procurement flows through holiday retail peaks in the US and EU, with durability ranking above performance in parental selection criteria.
- Teens:Adolescent operators aged 13-17 transition to programmable platforms with smartphone app integration. FAA Part 107 awareness campaigns in Texas and California schools are accelerating training-grade purchases over disposable alternatives.
- Adults:Hobbyist collectors and competitive racers drive brushless motor adoption and aftermarket parts ecosystems.
- All Ages:Cross-generational positioning emphasizes family bonding and intergenerational skill transfer in marketing narratives.
Children anchor volume throughput. Teens are climbing the fastest as career pathway framing legitimizes parental investment in certification-prep equipment.
Application:
Use case specificity determines sensor integration, software bundling, and channel strategy for institutional versus consumer endpoints.
- Recreational:Backyard and park flight without structured objectives. Chinese domestic consumption and US big-box retail sustain this segment through seasonal inventory cycles.
- Educational:Curriculum-integrated UAV modules with coding interfaces and lesson plan licensing. US state STEM mandates and EU Erasmus+ allocations are institutionalizing procurement through academic budget calendars.
- Sports:First-person-view racing and freestyle aerobatics with high-thrust-to-weight ratios. Australian and UK racing leagues are formalizing competitive structures with standardized timing systems.
- Competitions:Skill-based contests with judged maneuver sequences and technical documentation requirements.
Recreational applications retain the volume base. Educational deployment is gaining share fastest as school districts consolidate vendor relationships around multi-year curriculum subscriptions.
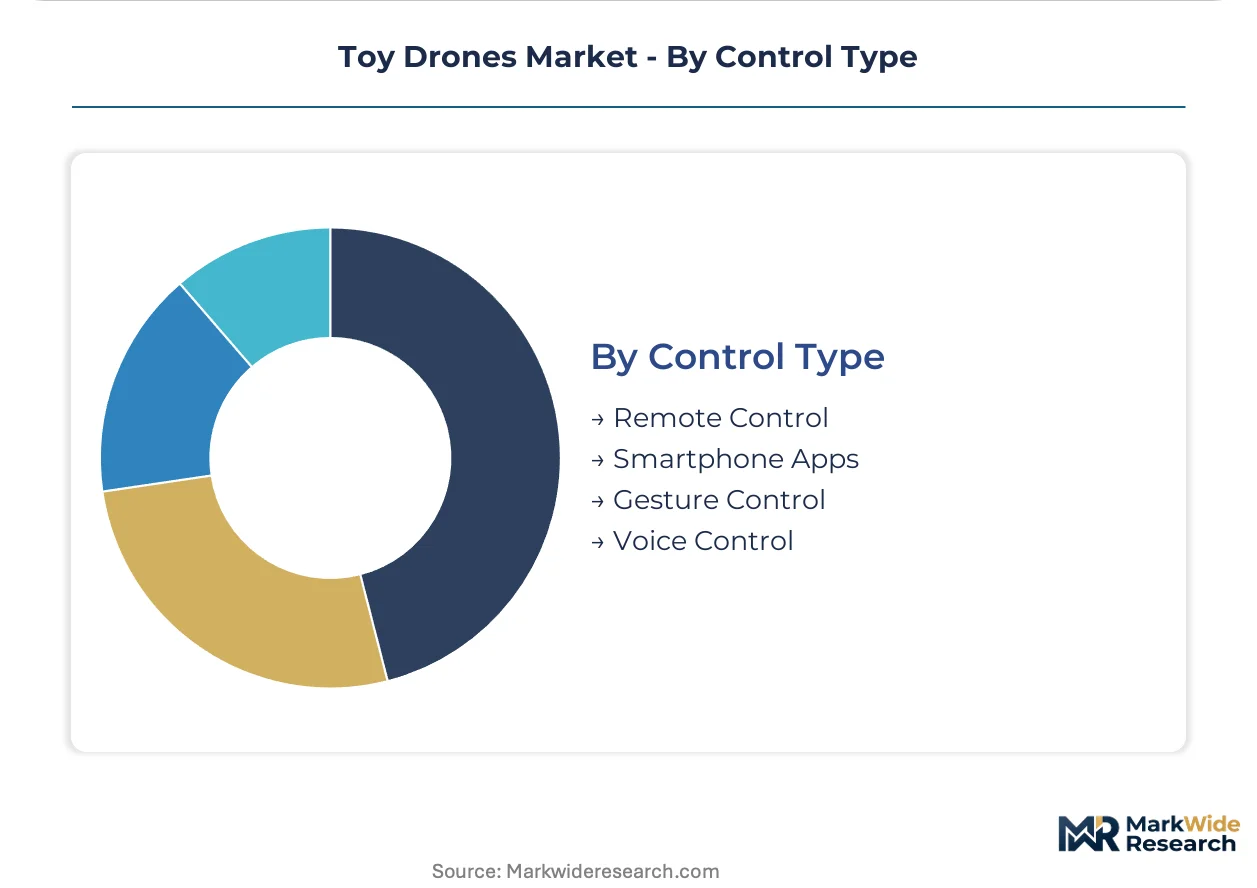
Control Type:
Interface modality shapes hardware cost structure, radio certification complexity, and user learning curve steepness.
- Remote Control:Dedicated 2.4GHz transmitters with physical sticks dominate institutional training environments. FAA-certified flight instructors in Florida and Arizona prefer tactile feedback for student progression assessment.
- Smartphone Apps:WiFi or Bluetooth-linked interfaces reduce hardware BOM costs but introduce latency constraints. Teen demographics in South Korea and urban China show highest adoption of touchscreen piloting.
- Gesture Control:Hand-motion sensors enable intuitive operation for young children without controller literacy.
- Voice Control:Natural language command interfaces remain experimental, with limited commercial deployment outside demonstration units.
Remote control systems hold the installed base. Smartphone app interfaces are expanding most quickly as OEMs eliminate bundled transmitters to hit price points in emerging markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FAA Part 107 certification pathways and EU Erasmus+ digital education allocations are institutionalizing drone procurement across Western education systems, while China's MIIT radio transmission standards and India's evolving BIS framework reshape supplier access in Asia.
United States
Texas and California school districts are consolidating vendor relationships around multi-year curriculum subscriptions with bundled educator training. FAA Part 107 remote pilot certification campaigns in Florida and Arizona are legitimizing youth drone programs as career pipeline investments. The Southeast manufacturing corridor around Atlanta hosts assembly operations serving institutional procurement channels.
China
Shenzhen's component ecosystem supplies brushless motors, lithium-polymer batteries, and flight controllers to global toy drone assemblers. MIIT enforces radio transmission certifications affecting controller frequencies for domestic sales. The Pearl River Delta manufacturing clusters enable rapid prototype-to-production cycles for educational drone developers.
Germany
Scale-model helicopter collectors in Bavaria and Baden-Württemberg sustain niche demand for aerobatic fidelity and thermal soaring authenticity. CE marking under Delegated Regulation 2019/945 mandates electromagnetic compatibility testing that extends product development timelines. The Eindhoven-adjacent distribution network channels certified units into EU education procurement frameworks.
India
Atal Tinkering Lab expansion under the National Education Policy 2020 creates institutional procurement channels for coding-integrated drone kits. BIS certification requirements remain less prescriptive than Western frameworks, reducing compliance burdens for mid-tier entrants. Maharashtra and Karnataka state education boards are piloting UAV modules in secondary technology curricula.
United Kingdom
FPV racing leagues in England and Scotland are formalizing competitive structures with standardized timing systems. The Civil Aviation Authority's altitude-restricted flight zones around airports and stadiums compress usable recreational airspace. London-based educational technology distributors are bundling lesson plan licensing with hardware procurement for academy trusts.
Toy Drones Market Competitive Landscape
On the supply side, the industry is bifurcating between Shenzhen-anchored volume manufacturers and European design-positioned specialists serving institutional procurement channels. Three archetypes dominate: vertically integrated component-to-assembly operators, curriculum-licensing platform bundlers, and racing-specialist performance houses. Competitive moves concentrate on backward integration into battery pack assembly and geographic expansion through distributor consolidation.
Among Shenzhen-based fabricators, DJI and Syma Toys exemplify the vertically integrated volume archetype, leveraging Guangdong Province component density to compress production cycles. Parrot occupies a position within the European design-specialist tier, bundling educational software with hardware platforms to capture institutional procurement mandates. These three anchors illustrate the geographic and strategic segmentation shaping vendor selection criteria across North American and European education buyers.
| Leading Market Players |
|---|
| Syma Toys |
| Yuneec International |
| DJI |
| UDIRC |
| Guangdong Syma Model Aircraft Industrial |
| Parrot |
| Autel Robotics |
| Heygelo |
| Hubsan |
| Others |
Value Network & Pricing Analysis
The Shenzhen-Hong Kong logistics corridor's freight cost volatility transmits directly into toy drone pricing power, compressing margins for Guangdong-dependent assemblers while amplifying differentiation premiums for CE-certified European entrants serving institutional procurement channels.
Pricing Analysis
Certification level creates the primary spread between disposable toy-grade units and training-platform pricing, with CE marking under Delegated Regulation 2019/945 and FAA Part 107 compliance separating premium institutional tiers from mass-market alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects brushless motor specification, battery thermal containment standards, and curriculum software bundling. Pricing pressure stems from lithium-polymer cathode material allocation volatility in China's Yangtze River Delta. School districts exhibit lowest price sensitivity, prioritizing vendor accountability and educator training over unit cost minimization.
Supply Chain Analysis
Tariff exposure between China and Western markets dominates supply chain risk calculus for toy drone assemblers, with Section 301 duties on radio equipment and battery packs forcing hardware variant proliferation. Manufacturing concentrates in China's Guangdong Province, South Korea's battery cell facilities, and Taiwan's semiconductor packaging operations. Brushless motors, lithium-polymer cells, and flight controller chipsets constitute critical input dependencies. Distribution runs through educational technology distributors in Texas and California, big-box retail in the US Midwest, and direct-to-school procurement channels in Ontario and Bavaria.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
STEM curriculum mandates are accelerating institutional procurement cycles, creating a high-growth disruption window as FAA certification pathways legitimize youth drone programs as career pipeline investments.
For Market Incumbents: Build curriculum licensing moats through multi-year school district subscriptions bundling hardware, lesson plans, and educator training. DJI and Syma Toys should deepen backward integration into battery pack assembly to absorb SAMR thermal runaway compliance costs. Parrot must defend European positioning by accelerating CE marking documentation to compress 4-8 month approval timelines. Threat response requires countering Shenzhen-based cost advantages through software differentiation and institutional channel control. For New Entrants and Emerging Players: Build out white-space presence in India's Atal Tinkering Lab procurement channels before BIS certification frameworks mature to Western complexity. Maharashtra and Karnataka state education boards offer penetrable entry points with coding-integrated drone kits. Subscription fleet leasing models for resource-constrained schools reduce upfront capital barriers while generating recurring revenue. Target summer camp operators and informal STEM education providers with asset-light rental programs. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors educational platform bundlers over pure hardware fabricators, as institutional buyers consolidate vendor relationships around curriculum-integrated solutions. Long-term viability rests on software recurring revenue attachment rates rather than transactional hardware margins. Acquisition target archetype: regional distributors with captive school district relationships and existing educator training infrastructure. Signal to watch: FAA-certified flight instructor pipeline expansion rates in Florida and Arizona as scalable deployment constraint indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Curriculum Licensing Agreement | Texas school districts consolidate multi-year subscriptions bundling lesson plans with fleet management software. |
| Backward Integration into Battery Assembly | In-house pack production absorbs SAMR thermal runaway documentation burdens for dual-market certification. |
| Educator Training Certification Program | FAA-certified instructor pipelines in Arizona and Florida remove scalable deployment bottlenecks for institutional sales. |
| Regional Distributor Acquisition | London-based EdTech distributors with academy trust relationships accelerate European education procurement access. |
| AI-Enabled Autonomous Flight Module Launch | Computer vision integration reduces instructor supervision requirements in resource-constrained Indian learning environments. |
Research Methodology
Cross-validation between primary interviews with flight instructors, school technology coordinators, and educational procurement officers anchors the qualitative findings against secondary validation from FAA certification databases, EU delegated regulation filings, and customs trade records. Bottom-up triangulation across Shenzhen component supplier disclosures and top-down reconciliation with institutional budget allocation data from Texas Education Agency and Ontario Ministry of Education sources ensures methodological rigor.
Calibration against historical procurement cycle patterns and regulatory implementation timelines shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include product architecture, age group developmental capability, application specificity, and control interface modality. CAGRs derive from installed base expansion rates in educational institutions and replacement cycle compression in recreational channels. Forecast inputs incorporate MIIT radio frequency allocation changes and evolving BIS certification trajectory assumptions.
Stress conditions across lithium-polymer supply allocation, CE marking timeline extensions, and FAA instructor certification bottlenecks were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding STEM funding continuity and regulatory harmonization progress. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
UAV
Unmanned Aerial Vehicle Fuel Cell Market
UAV
Europe Tethered Drone Market
UAV
Drone Powered Business Solutions Market
UAV
Unmanned Combat Aerial Vehicle Market
UAV
North America Drone Software Market
UAV
Nano Drones Market
UAV
Small Drone Market
UAV
Global Stratospheric UAV Payload Technology Market
UAV
Home Security Drone Market
UAV
Enterprise Drone Management Solutions Market
UAV
Autonomous Aircraft Cameras Market
UAV
Asia-Pacific Drones Market
UAV
FPV Drone Goggles Market
UAV
Asia Pacific Commercial Drone Market
UAV
Drones Market
UAV
US Commercial Drone Market