
 Micro Drone Market | 2026-2036
Micro Drone Market Size, Share, and Industry Trends Forecast 2026-2036
Micro Drone Market Analysis
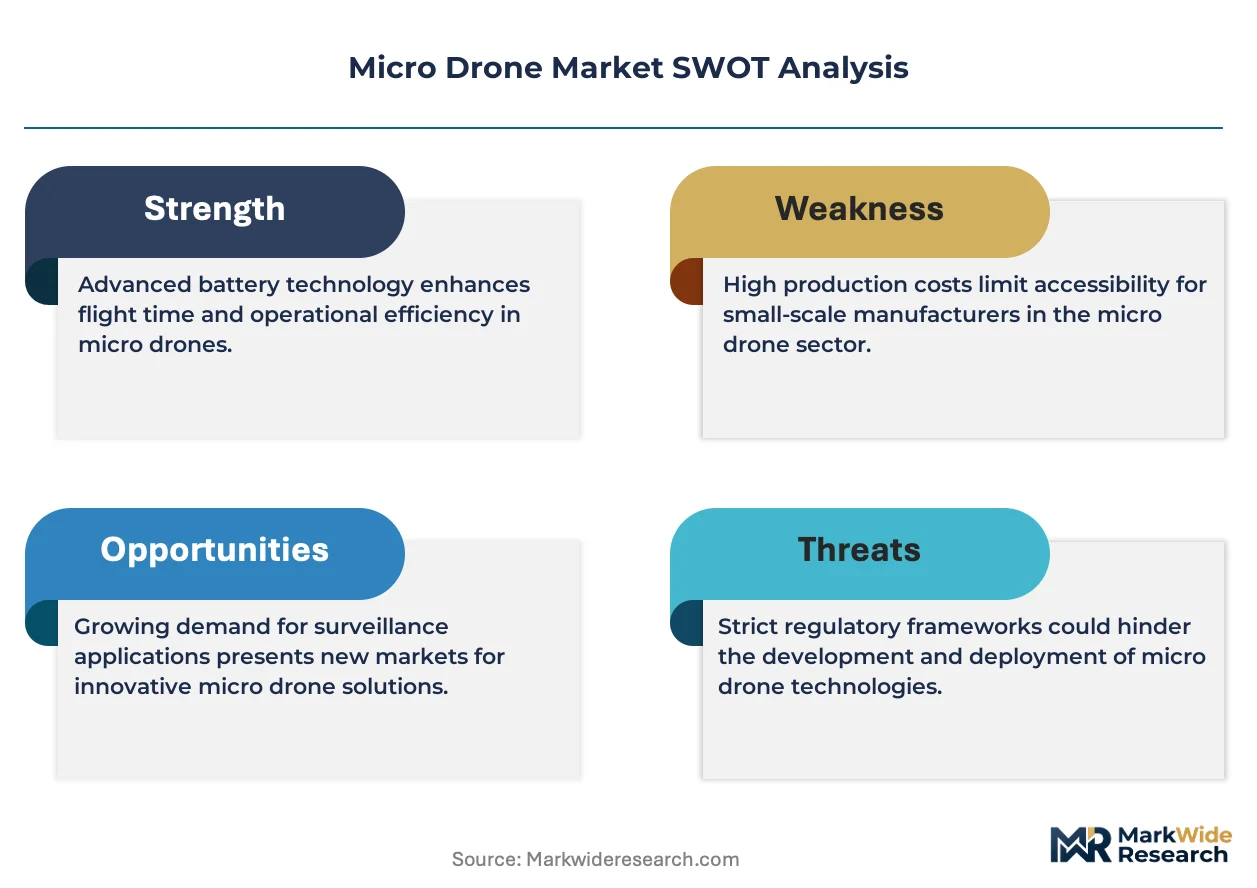
FAA Remote ID implementation is recalibrating engineering budgets for every manufacturer targeting the United States. DJI sustains its supply chain leverage through captive production of flight controllers and camera gimbals in Shenzhen. Skydio differentiates through autonomous navigation stacks purpose-built for defense and public safety contracts. AeroVironment anchors its position in military microsystems with decades of Pentagon program integration.
A micro drone denotes an unmanned aerial vehicle weighing under two kilograms, typically constructed from carbon fiber-reinforced polymers or injection-molded thermoplastics, and powered by brushless DC motors driving fixed-pitch or variable-pitch rotors. These systems execute close-range reconnaissance, precision agriculture spraying, and confined-space infrastructure inspection where manned access proves impractical or hazardous. Rotary-wing configurations dominate unit shipments due to vertical takeoff agility and hover stability in GPS-denied environments, while fixed-wing variants capture longer-endurance missions in mapping and corridor surveillance. AI-enabled technology represents the fastest-expanding segment as edge inference chips shrink power draw while expanding real-time object classification for search and rescue operations.
FAA Part 107 and Remote ID rules in the United States, EASA drone regulation frameworks across European member states, and China's CAAC low-altitude flight management standards collectively determine where manufacturers can sell, what capabilities they must embed, and how operators must certify. These compliance architectures favor incumbents with dedicated regulatory affairs teams and punish smaller entrants lacking certification bandwidth. Stakeholders must track which jurisdictions will mandate beyond-visual-line-of-sight protocols next, as this single regulatory shift would restructure competitive advantage across the entire supplier tier.
Market Dynamics
Shenzhen's component ecosystem is compressing development cycles for flight controllers and brushless motor assemblies, forcing Western manufacturers to choose between compliance engineering investments and supply chain reconfiguration.
Growth Catalysts
- FAA Remote ID mandate:United States operators must broadcast identification and location data, creating immediate retrofit demand across existing fleets and mandating embedded modules in new production.
- Urban warfare doctrine:NATO defense agencies are standardizing palm-sized reconnaissance units for building-clearing operations, institutionalizing micro drone procurement within military acquisition frameworks.
- Carbon fiber-reinforced polymers:Advanced thermoplastic manufacturing is slashing airframe weight while maintaining crash resilience, extending flight endurance for rotary-wing configurations.
Market Restraints
- Lithium-polymer battery supply:Cathode material costs fluctuate with cobalt and nickel spot markets, exposing assemblers to input volatility that contract manufacturers cannot easily hedge.
- Shenzhen supply concentration:Flight controller silicon, ESC boards, and compact gimbal motors originate from a single manufacturing corridor, creating single-point vulnerability for non-Chinese brands.
- Brushless motor thermal limits:Power density constraints prevent sustained high-thrust operation in hot climates, restricting payload capacity for precision agriculture applications.
Strategic Opportunities
- India low-altitude airspace:DGFT import liberalization and BIS certification streamlining are opening defense and infrastructure inspection verticals previously blocked by regulatory friction.
- Edge AI inference chips:Convergence of neuromorphic processors with millimeter-wave radar is enabling real-time obstacle classification without ground station dependency.
- EU Green Deal procurement rules:Public sector tenders now weight lifecycle carbon footprint, advantaging manufacturers with repairable designs and recycled polymer airframes.
Industry Challenges
- Flight control firmware certification:EASA's Specific Category requirements demand formal verification of autonomous navigation stacks, extending engineering timelines by twelve to eighteen months.
- RF engineer scarcity:Competence in antenna design for GPS-denied environments concentrates among defense contractors, constraining commercial product development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Micro Drone Market |
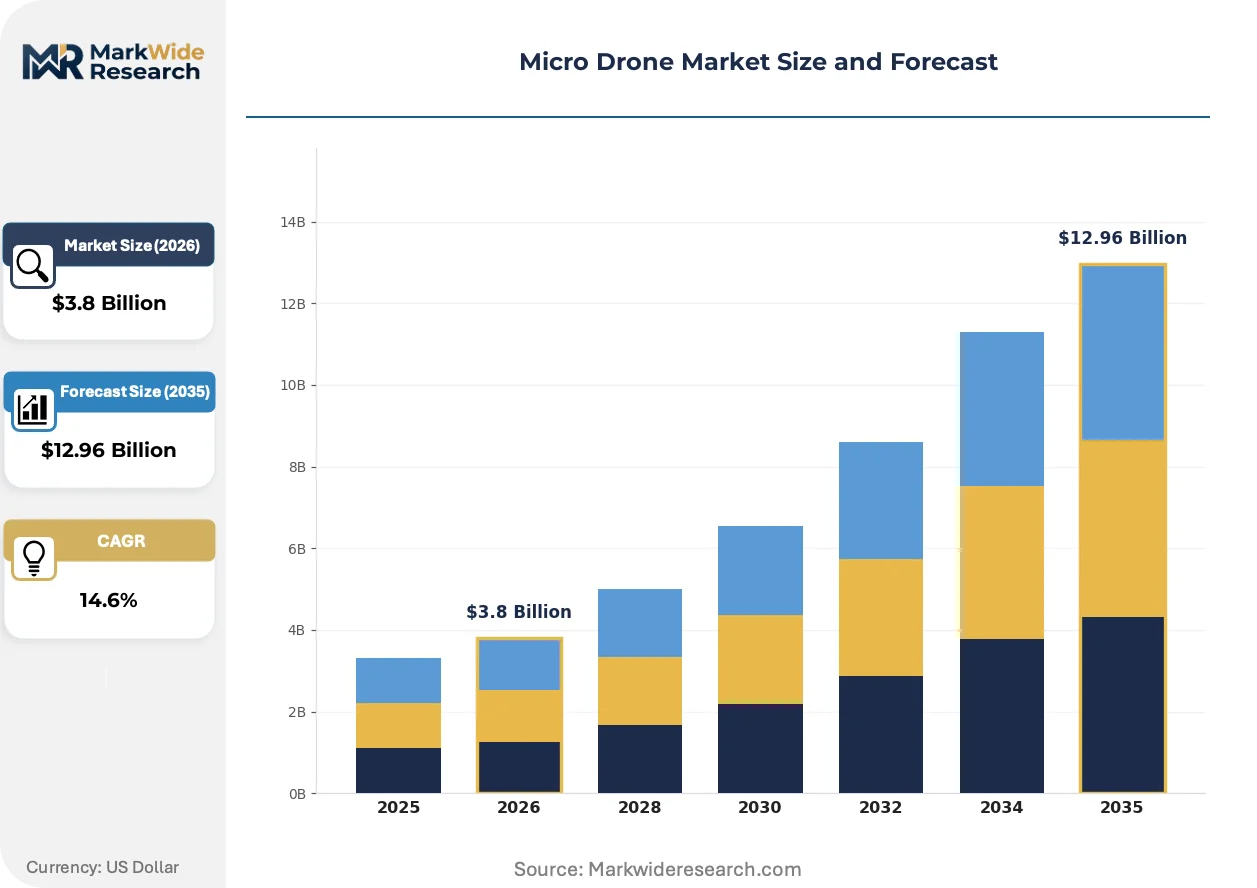
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.96 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed-wing, Rotary-wing, Hybrid, Mini Quadcopter End User: Agriculture, Surveillance, Delivery, Entertainment Application: Mapping, Infrastructure Inspection, Photography, Search & Rescue Technology: GPS-based, AI-enabled, LiDAR, FPV |
| Companies Covered | AeroVironment, Yuneec, DJI, JOUAV, EHang, Skydio, XAG, Freefly Systems, Parrot Drone SAS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Micro Drone Market Emerging Trajectories
Autonomous navigation stacks are migrating from cloud dependency to onboard processing, compressing latency for collision avoidance and enabling operations in electromagnetic-contested environments.
Neuromorphic vision sensors paired with event-based cameras are rewriting the economics of real-time object tracking. Search and rescue teams in Alpine regions are adopting these systems for low-light canyon operations. The technology is compressing the performance gap between military-grade and commercial platforms.
EU AI Act risk classification rules are redefining liability for autonomous flight systems. Manufacturers must now document algorithmic decision pathways for high-risk applications including crowd monitoring. German industrial inspection providers are restructuring service contracts to isolate algorithmic liability from hardware failure coverage.
Defense procurement officers are consolidating vendor relationships around full-stack autonomy providers, displacing hardware-agnostic software integrators. French and British military tenders now specify combined airframe-navigation payloads rather than separable components. This preference shift is squeezing modular suppliers out of tier-one contract eligibility.
Micro Drone Market Segmentation
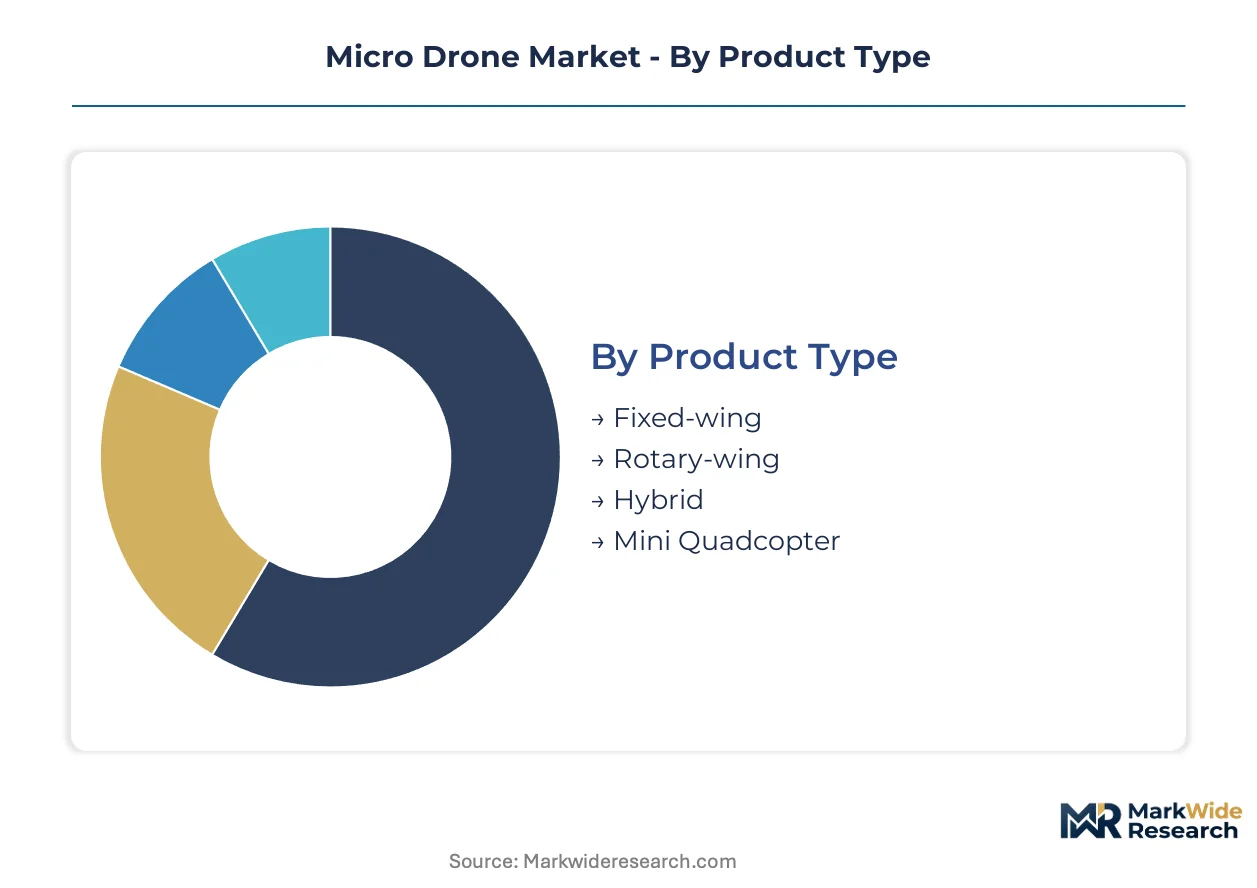
Micro drone procurement cycles diverge sharply by operational environment, with defense and enterprise buyers replacing fleets every 18-24 months while consumer segments stretch intervals to 36 months. Upgrade decisions hinge on payload capacity gains, battery chemistry improvements, and regulatory compliance mandates rather than airframe wear.
Product Type:
Replacement cycles vary dramatically across configurations, with commercial operators retiring rotary-wing units faster than fixed-wing platforms due to motor fatigue in hover-intensive missions.
- Rotary-wing:Vertical takeoff capability and hover stability dominate urban reconnaissance and confined-space inspection. NATO defense agencies in Germany, France, and the United Kingdom are standardizing palm-sized rotary units for building-clearing operations, compressing procurement timelines.
- Fixed-wing:Extended endurance suits corridor surveillance and large-area mapping where runway or hand-launch access exists. Precision agriculture operators in Australia's wheat belt favor these configurations for thousand-hectare coverage missions.
- Hybrid:Combines VTOL agility with cruise efficiency for infrastructure networks spanning varied terrain. Utility inspectors in Norway's fjord regions deploy these for pylon-to-pylon transitions.
- Mini Quadcopter:Consumer-grade entry point with limited payload and range. Recreational demand concentrates in Japan and South Korea where registration thresholds exclude heavier units.
Rotary-wing sits at the top of the volume ranking, with Hybrid climbing the fastest as bridge applications multiply.
End User:
Customer sophistication determines specification intensity, with defense and agricultural buyers demanding formal verification while entertainment purchasers prioritize cost minimization.
- Surveillance:Real-time video streaming with encrypted downlinks for law enforcement and border control. India's Central Reserve Police Force is expanding procurement under relaxed DGFT import rules.
- Agriculture:Variable-rate spraying and multispectral crop monitoring drive payload integration. Brazilian soybean operators are retrofitting existing fleets with CAAN-approved chemical dispersal systems.
- Delivery:Last-mile logistics trials by postal services and healthcare networks. Swissmedic-regulated medical transport corridors in Switzerland's Alpine valleys are advancing beyond-visual-line-of-sight waivers.
- Entertainment:Aerial cinematography and light shows for events and film production. Dubai's MOHAP-licensed operators dominate Middle East spectacle deployments.
Surveillance commands the highest specification tier, with Agriculture expanding most quickly as subsidy programs activate.
Application:
Mission-criticality shapes durability requirements, with search and rescue and infrastructure inspection demanding fault-tolerant designs absent in photography segments.
- Search & Rescue:Thermal imaging and low-light navigation for alpine and maritime environments. Alpine rescue teams in Austria and Italy are adopting neuromorphic vision sensors for canyon operations.
- Infrastructure Inspection:Close-proximity flight around power lines, wind turbines, and bridges. German network operators now weight lifecycle carbon footprint under EU Green Deal procurement rules.
- Mapping:Photogrammetry and orthomosaic generation for construction and mining. South African platinum belt surveyors integrate LiDAR payloads for volumetric stockpile measurement.
- Photography:Commercial and artistic aerial imaging with stabilized gimbal systems. Wedding and real estate segments in California drive refresh demand for 4K video capabilities.
Infrastructure Inspection leads contract value, with Search & Rescue gaining share fastest as sensor miniaturization advances.
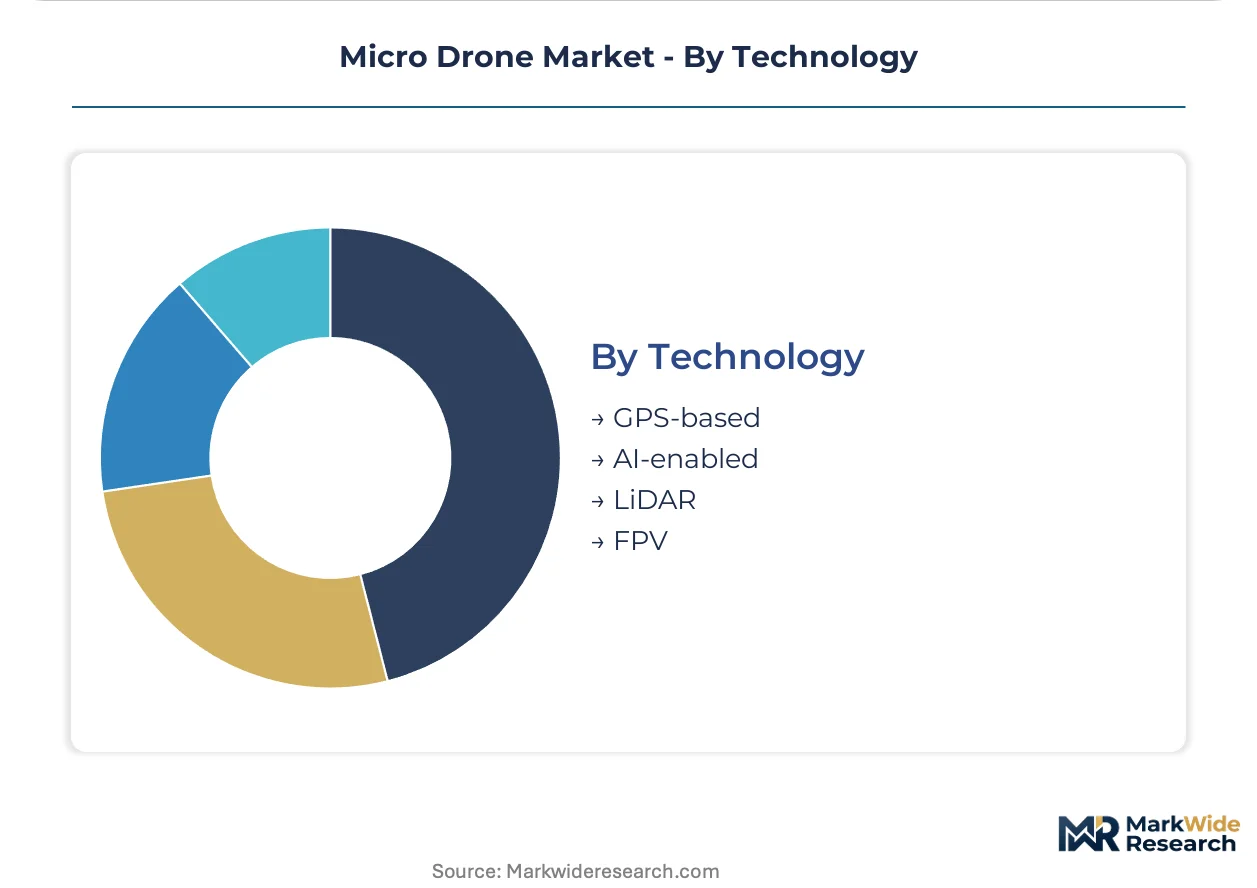
Technology:
Autonomy levels determine regulatory friction, with AI-enabled and beyond-visual-line-of-sight systems facing extended certification timelines under EASA and FAA frameworks.
- AI-enabled:Edge inference for real-time object classification and collision avoidance. Edge AI inference chips from neuromorphic processor vendors are shrinking power draw while expanding capability.
- GPS-based:Standard navigation for visual-line-of-sight operations in open environments. FAA Part 107 compliance dominates United States commercial deployments.
- LiDAR:Precision ranging for mapping and obstacle detection in GPS-denied settings. Underground mining operators in Western Australia deploy these for stope surveying.
- FPV:First-person view racing and acrobatic cinematography with low-latency video links. Amateur racing leagues in Poland and the Czech Republic drive component innovation.
GPS-based retains installed base dominance, with AI-enabled tracing the steepest expansion trajectory as defense procurement consolidates around full-stack autonomy.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineers specializing in flight control firmware and RF antenna design concentrate in defense corridors around Washington DC, Toulouse, and Tel Aviv, anchoring regional capability clusters that shape procurement patterns.
United States
Defense procurement officers at the Pentagon and Special Operations Command drive demand for palm-sized reconnaissance units. FAA Remote ID mandates compress compliance timelines for manufacturers targeting commercial operators. Austin and Boston harbor autonomy software clusters where former defense contractors commercialize navigation stacks.
China
Shenzhen's hardware ecosystem dominates flight controller silicon and brushless motor assembly, supplying component density unmatched elsewhere. CAAC low-altitude flight management standards determine which capabilities manufacturers must embed for domestic certification. DJI anchors production in Nanshan District, where vertical integration spans flight controllers through camera gimbals.
Germany
Bundeswehr urban warfare doctrine institutionalizes micro drone procurement for building-clearing operations. EASA Specific Category requirements demand formal verification of autonomous navigation stacks, extending engineering timelines. Munich and Stuttgart host industrial inspection providers restructuring contracts around EU AI Act liability rules.
Israel
Israel Defense Forces operational experience in dense urban environments drives specification intensity for GPS-denied navigation. The country's national defense regulator mandates encrypted downlinks for surveillance deployments. Tel Aviv's autonomy engineering cluster supplies navigation firmware to NATO procurement frameworks.
India
Central Reserve Police Force expansion under relaxed DGFT import rules accelerates surveillance platform procurement. BIS certification streamlining opens defense and infrastructure inspection verticals previously blocked by regulatory friction. Bengaluru's drone startups concentrate on precision agriculture retrofit kits for soybean operators in Maharashtra.
Micro Drone Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across a tiered supplier base. The market structure concentrates around three strategic archetypes: full-stack autonomy providers capturing defense contracts, component-integrated hardware manufacturers serving commercial segments, and modular software integrators facing displacement. Competitive moves center on backward integration into flight controller silicon and strategic partnerships for regulatory certification bandwidth.
Within the full-stack autonomy tier, Skydio and AeroVironment exemplify defense-focused positioning through Pentagon program integration. DJI anchors the component-integrated hardware archetype through captive production in Shenzhen's manufacturing corridor. These three companies occupy distinct competitive positions: American specialists in autonomous navigation, legacy military contractors, and Chinese vertically integrated manufacturers.
| Leading Market Players |
|---|
| AeroVironment |
| Yuneec |
| DJI |
| JOUAV |
| EHang |
| Skydio |
| XAG |
| Freefly Systems |
| Parrot Drone SAS |
| Others |
Supply Flow & Price Mechanics
Cobalt and nickel spot market volatility cascades through lithium-polymer battery procurement into three distinct pricing tiers for micro drone assemblers. Defense contractors absorbing cathode cost swings through long-term offtake agreements separate from commercial operators exposed to spot pricing.
Pricing Analysis
Bundled hardware-software service packages diverge from bare airframe transactions across the procurement landscape. Three-tier pricing structure across premium, standard, and economy levels separates NATO-certified defense units from enterprise inspection platforms and consumer-grade mini quadcopters. Price differentiation hinges on EASA Specific Category firmware verification and embedded Remote ID module inclusion. Pricing pressure stems from Shenzhen component cost compression forcing Western manufacturers into compliance engineering trade-offs. Agricultural cooperatives in Brazil exhibit highest price sensitivity while Pentagon program officers prioritize capability over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from defense procurement officers mandate qualified alternatives for flight controller silicon and brushless motor assemblies. Component supply concentrates in China, South Korea, and Taiwan for ESC boards, edge AI inference chips, and compact gimbal motors. Raw material dependencies encompass cobalt cathodes, carbon fiber-reinforced polymers, and rare-earth magnets for rotor assemblies. Single-source vulnerability concentrates in Shenzhen's Nanshan District flight controller ecosystem. Distribution runs through direct defense contracting channels, regional system integrators, and e-commerce platforms for consumer segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in edge AI inference chip integration and defense full-stack autonomy contracts, with carbon fiber thermoplastic cost curves enabling premium-tier positioning.
For Market Incumbents: Extend firmware certification bandwidth to capture EASA Specific Category and FAA Remote ID compliance premiums before smaller competitors exhaust engineering resources. Backward integration into flight controller silicon reduces exposure to Shenzhen supply concentration. Anchor defense relationships through combined airframe-navigation payloads rather than modular component sales. For New Entrants and Emerging Players: Begin with India's DGFT-liberalized defense and infrastructure inspection verticals where BIS certification streamlining has lowered regulatory barriers. Precision agriculture retrofit kits for Brazilian soybean operators represent the most penetrable application segment. Partner with established autonomy software clusters in Austin or Boston for navigation stack licensing rather than ground-up development. For Investors and Strategic Acquirers: Asymmetric upside sits with neuromorphic vision sensor developers pairing event-based cameras with millimeter-wave radar for GPS-denied navigation. Long-term viability favors full-stack autonomy providers over hardware-agnostic software integrators facing displacement from defense procurement consolidation. Watch for beyond-visual-line-of-sight regulatory waivers in Swissmedic-regulated Alpine corridors as inflection signal for commercial autonomy scaling.| Strategic Initiative | Industry Significance |
|---|---|
| Edge AI Inference Chip Integration | Shrinks power draw for real-time obstacle classification in GPS-denied environments. |
| Defense Full-Stack Autonomy Partnership | Captures Pentagon program integration requirements displacing modular suppliers. |
| CAAC Low-Altitude Certification Pathway | Unlocks domestic China market access for flight control firmware vendors. |
| EU Green Deal Procurement Alignment | Meets German network operator lifecycle carbon footprint weighting for repairable designs. |
| Neuromorphic Vision Sensor Development | Enables Alpine search and rescue low-light canyon operations compressing military-commercial performance gaps. |
Methodological Framework
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each defense procurement corridor and manufacturing cluster. Primary interviews with flight control firmware engineers, Pentagon program integration officers, EASA certification specialists, and Shenzhen component suppliers combined with secondary validation. Sources include FAA Part 107 enforcement databases, EASA Specific Category approval registries, DGFT import liberalization notifications, and customs records from India's Central Reserve Police Force procurement. Bottom-up unit shipment modeling triangulates against top-down defense budget allocation analysis.
Granularity-level modeling disaggregates rotary-wing, fixed-wing, hybrid, and mini quadcopter configurations across surveillance, agriculture, delivery, and entertainment end uses. Technology segmentation captures AI-enabled, GPS-based, LiDAR, and FPV autonomy levels. CAGRs derive from fitted growth curves applied to defense procurement cycle data and commercial fleet replacement intervals. Forecast inputs incorporate cobalt-nickel price elasticity for battery cost trajectories and EASA firmware verification timeline distributions.
Several conditions sit outside the modeled scope, including sudden CAAC low-altitude flight management standard revisions and NATO urban warfare doctrine shifts. Forecasts reflect assumptions on Remote ID compliance adoption curves and neuromorphic sensor cost-down trajectories. Deviation in beyond-visual-line-of-sight regulatory mandate timing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
UAV
Global Electric Drone Market
UAV
Asia-Pacific Drone Light Shows Market
UAV
Counter-UAS Market
UAV
Fixed Wing Military Drones Market
UAV
Europe Tactical UAV Market
UAV
Drone-In-A-Box Market
UAV
Rc Helicopter Market
UAV
Global Drone Software Market
UAV
Global Aerial Survey Services Market
UAV
Drones Market
UAV
Global Renewable Drones Market
UAV
Commercial Drone-Enabled Services Market
UAV
UAV Payload Market
UAV
Passenger Drones Market
UAV
North America Tactical UAV Market
UAV
Nano Drones Market