
 United States Drone Services Market | 2026-2036
United States Drone Services Market Size, Share, and Industry Trends Forecast 2026-2036
United States Drone Services Market Outlook
FAA Part 107 remote pilot certification is unwinding barriers to commercial entry while elevating operational standards for legitimate providers. Skydio, Inc. leverages autonomous flight algorithms to dominate infrastructure inspection workflows for utility and telecommunications clients. PrecisionHawk anchors its position through specialized agricultural analytics that integrate multispectral imaging with prescription mapping software. DroneDeploy, Inc. competes across multiple verticals with a cloud-based mission planning platform that standardizes data collection protocols.
United States drone services encompass remotely piloted and autonomous aerial systems operated by third-party providers to capture data, transport goods, or perform physical tasks for commercial and government clients. These services typically employ aircraft weighing less than 55 pounds, flying at altitudes up to 400 feet above ground level, with flight durations ranging from 20 minutes to several hours depending on powertrain configuration and payload requirements. Aerial Photography and Inspection within the Service Type dimension command established revenue pools, while Mapping services exhibit accelerated growth as lidar and photogrammetry costs decline. Delivery drones represent an emerging Technology segment where regulatory clearance timelines, rather than technical capability, currently constrain market expansion.
FAA rulemaking on beyond-visual-line-of-sight operations, alongside FAA Reauthorization Act mandates and state-level privacy statutes, shapes where and how providers can deploy assets commercially. The Department of Transportation coordinates with the FAA on urban air mobility integration, while the Department of Homeland Security influences counter-drone restrictions that affect service provider equipment choices. Stakeholders must monitor the interplay between federal preemption efforts and municipal zoning ordinances, as fragmented local governance threatens to complicate nationwide service scaling.
Market Dynamics
FAA Part 107 certification expansion and pending beyond-visual-line-of-sight rulemaking are compressing operational barriers while elevating compliance thresholds for commercial drone service providers.
Growth Catalysts
- Variable-rate application systems:Precision agriculture operators across the Midwest Corn Belt deploy autonomous spraying drones that reduce chemical inputs by targeting specific crop zones. USDA conservation incentive programs subsidize adoption for qualifying farms.
- Battery energy density improvements:Solid-state lithium-polymer configurations extend flight endurance to 45-90 minutes for multirotor platforms. Commercial inspection firms leverage this capability for extended infrastructure surveys.
- Texas energy corridor demand:Oil and gas pipeline operators require frequent aerial monitoring across Permian Basin infrastructure. Third-party drone contractors capture recurring inspection contracts from midstream operators.
Market Restraints
- Lithium supply concentration:Battery cell manufacturing concentrates in East Asian facilities, exposing US drone operators to input cost volatility and supply chain disruptions.
- Visual-line-of-sight limitation:FAA Part 107 mandates require pilots maintain unaided visual contact with aircraft, constraining operational radius for rural agricultural and linear infrastructure missions.
- Counter-drone equipment restrictions:Department of Homeland Security regulations limit service provider access to jamming and detection systems, creating vulnerability to rogue aircraft interference.
Strategic Opportunities
- Urban air mobility corridors:Department of Transportation designated testing zones in Dallas-Fort Worth and Los Angeles enable early-mover positioning for medical supply and parcel delivery networks.
- LiDAR-photogrammetry convergence:Surveying firms integrate simultaneous localization and mapping with multispectral imaging to capture topographic and vegetation data in single flights.
- State-level agricultural subsidies:North Dakota and California crop insurance programs increasingly mandate drone-collected data for precision claims processing, creating captive demand pools.
Industry Challenges
- Remote pilot certification backlog:FAA testing center capacity constraints extend Part 107 credentialing timelines to 6-8 weeks, throttling workforce expansion for seasonal agricultural operators.
- Legacy system integration:Enterprise clients demand API compatibility with existing GIS and asset management platforms, requiring custom middleware development from service providers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Drone Services Market |
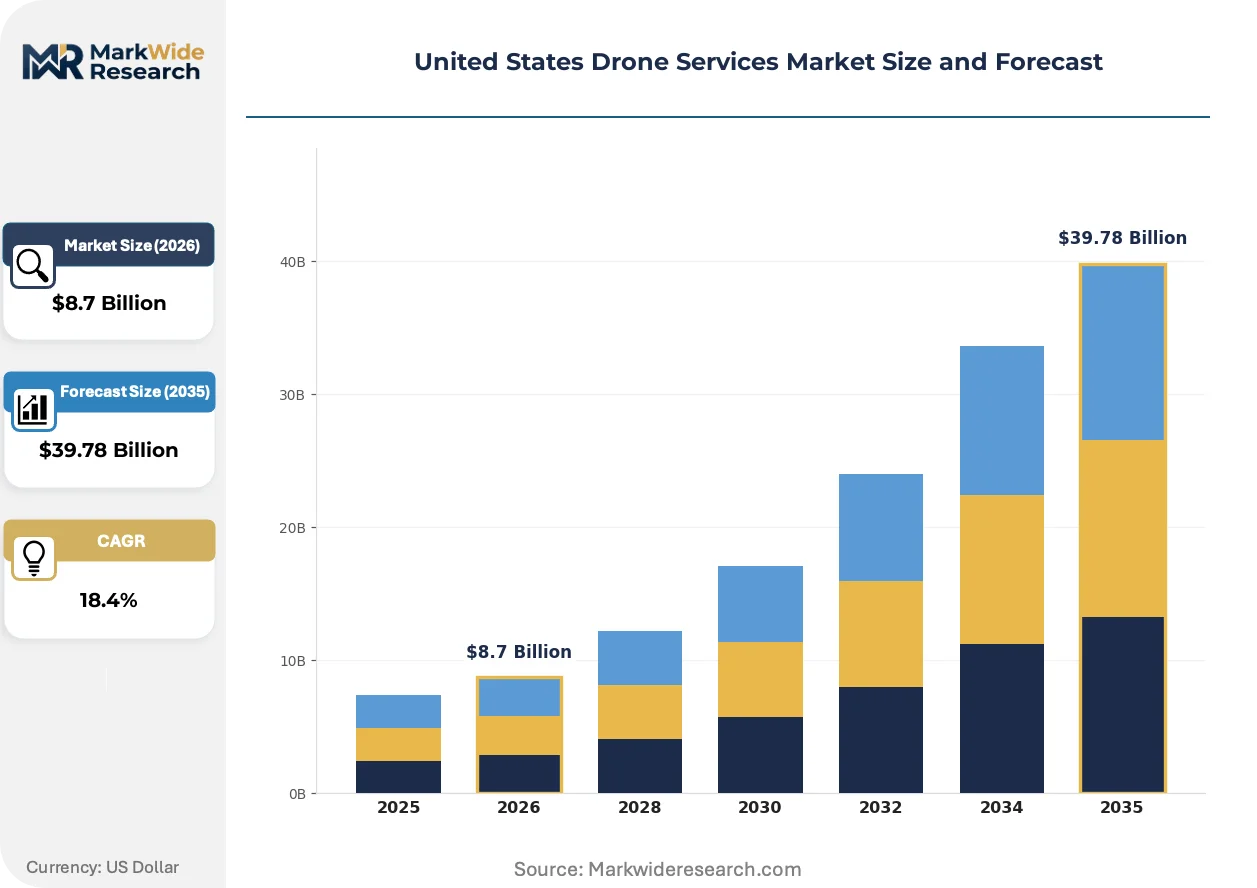
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $39.78 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Agriculture, Construction, Delivery, Surveillance Service Type: Aerial Photography, Inspection, Mapping, Monitoring End User: Public Sector, Real Estate, Media, Energy Technology: Fixed-Wing, Multi-Rotor, Hybrid, Delivery Drones |
| Companies Covered | DroneDeploy, Inc., PrecisionHawk, Skydio, Inc., AgEagle Aerial Systems Inc., Cyberhawk Innovations Limited, Zipline International Inc., Wing Aviation LLC, Phoenix Drone Services LLC, SkySpecs, Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Drone Services Market Strategic Shifts
Autonomous flight algorithms and sensor miniaturization are compressing the cost-performance frontier for commercial aerial data collection, while regulatory frameworks lag technical capability.
Edge computing architectures are fragmenting traditional ground-station processing models. Onboard NVIDIA Jetson modules now execute real-time object detection for power line fault identification. Utility inspection firms deploy these systems across Texas and California transmission networks. The shift reduces data transmission costs and enables immediate anomaly flagging without cloud dependency.
FAA Reauthorization Act mandates for UAS Traffic Management integration are forcing operational protocol changes. Commercial operators must adopt Remote ID broadcast standards and coordinate with Low Altitude Authorization and Notification Capability systems. Agricultural and energy infrastructure segments face the steepest compliance adaptation curves as 2024 implementation deadlines approach.
Asset owner procurement patterns favor multi-year service contracts over per-flight arrangements. Oil and gas midstream operators in North Dakota consolidate vendor relationships to capture volume discounts and standardized reporting formats. This concentration pressures smaller regional drone contractors to specialize or exit.
United States Drone Services Market Segmentation
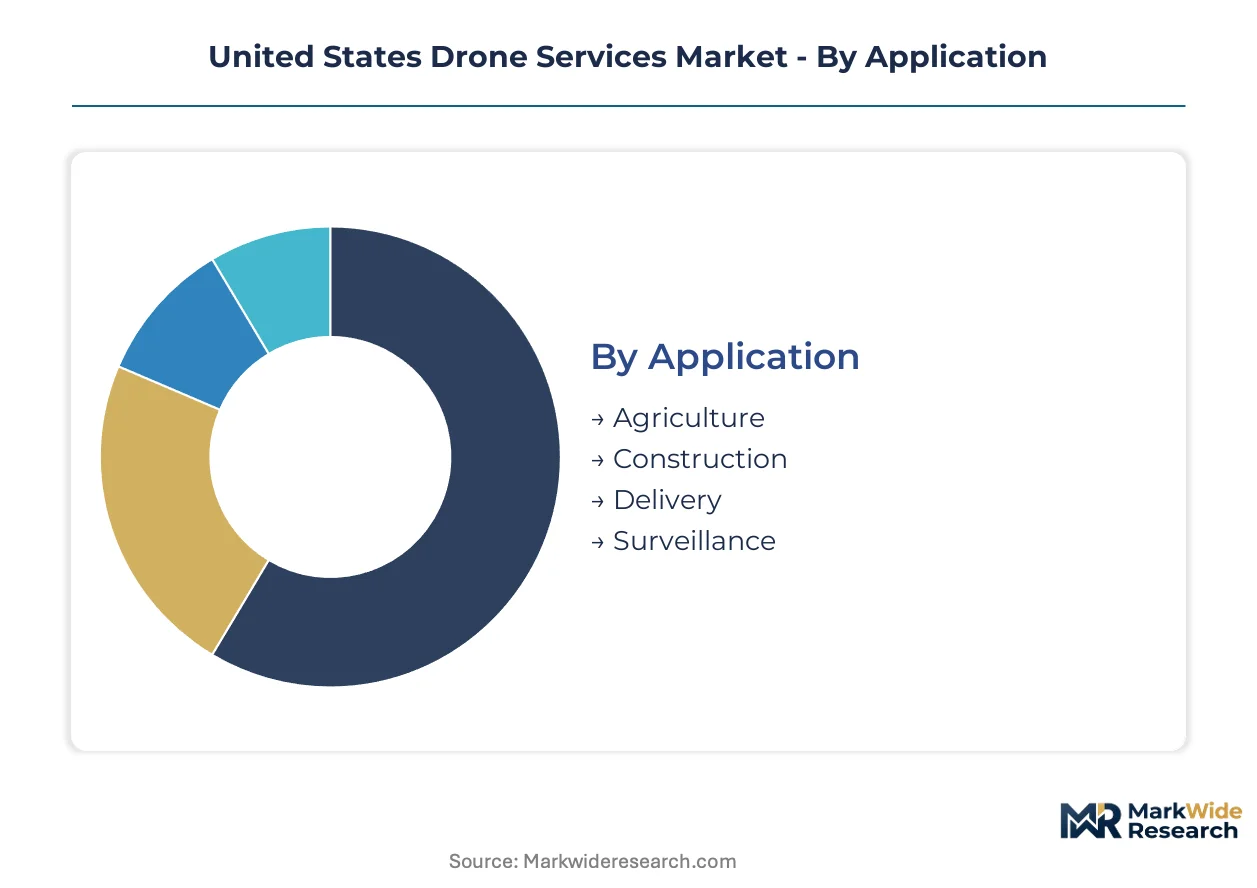
Segmentation in the United States drone services market reveals how FAA regulatory frameworks differentially constrain or enable specific operational configurations. Each category maps distinct compliance burdens to addressable revenue pools across commercial verticals.
Application:
FAA Part 107 waivers and pending beyond-visual-line-of-sight rulemaking create asymmetric operational latitude across use cases.
- Agriculture:Variable-rate application systems dominate Midwest Corn Belt operations. USDA conservation incentive programs subsidize autonomous spraying drones that reduce chemical inputs through zone-specific targeting. Demand concentrates in North Dakota and Iowa where crop insurance programs increasingly mandate drone-collected data for precision claims processing.
- Construction:Progress monitoring and volumetric surveying drive adoption across commercial real estate developments. Site managers deploy photogrammetry for earthwork quantity verification and schedule compliance documentation. California and Texas metropolitan construction corridors generate dense contractor networks.
- Delivery:Regulatory clearance timelines constrain expansion despite technical readiness. Department of Transportation designated urban air mobility corridors in Dallas-Fort Worth enable limited medical supply pilot programs.
- Surveillance:Law enforcement and private security operators face stringent municipal zoning restrictions that fragment deployment authority.
Agriculture handles the majority of throughput; Delivery is the fastest mover on share pending FAA operational approvals.
Service Type:
Data processing intensity and deliverable formats segment providers by capability investment requirements.
- Aerial Photography:Established revenue pool serving real estate marketing and media production. Standardized deliverables reduce barrier to entry for independent operators. Demand clusters in California and Florida residential markets.
- Inspection:Infrastructure integrity assessment commands premium pricing for specialized sensor configurations. Texas Permian Basin oil and gas operators require frequent pipeline monitoring across expansive linear assets. Recurring multi-year contracts dominate procurement patterns.
- Mapping:LiDAR-photogrammetry convergence accelerates growth as hardware costs decline. Surveying firms integrate simultaneous localization and mapping with multispectral imaging for topographic and vegetation capture in single flights.
- Monitoring:Continuous data streams for environmental compliance and asset condition tracking. Agricultural and energy segments drive adoption through subscription-based service models.
Inspection captures the highest contract values; Mapping is expanding most quickly on technology cost curves.
End User:
Procurement sophistication and budget cycle predictability differentiate customer segments.
- Public Sector:Federal and state agencies operate under Federal Acquisition Regulation compliance requirements. Emergency management and transportation departments deploy drones for disaster response and infrastructure inventory. Budget authorization cycles extend sales timelines.
- Real Estate:Commercial and residential property marketing drives recurring photography demand. Brokerage networks standardize aerial imagery requirements across listing portfolios. Seasonal patterns align with regional construction activity.
- Media:Broadcast and film production operators prioritize cinematic quality and rapid turnaround. Freelance pilot networks serve project-based demand with variable pricing structures.
- Energy:Midstream oil and gas operators consolidate vendor relationships for volume discounts. North Dakota and Texas transmission utilities require thermal imaging for predictive maintenance programs.
Energy commands the longest contract durations; Public Sector is climbing the fastest on infrastructure modernization mandates.
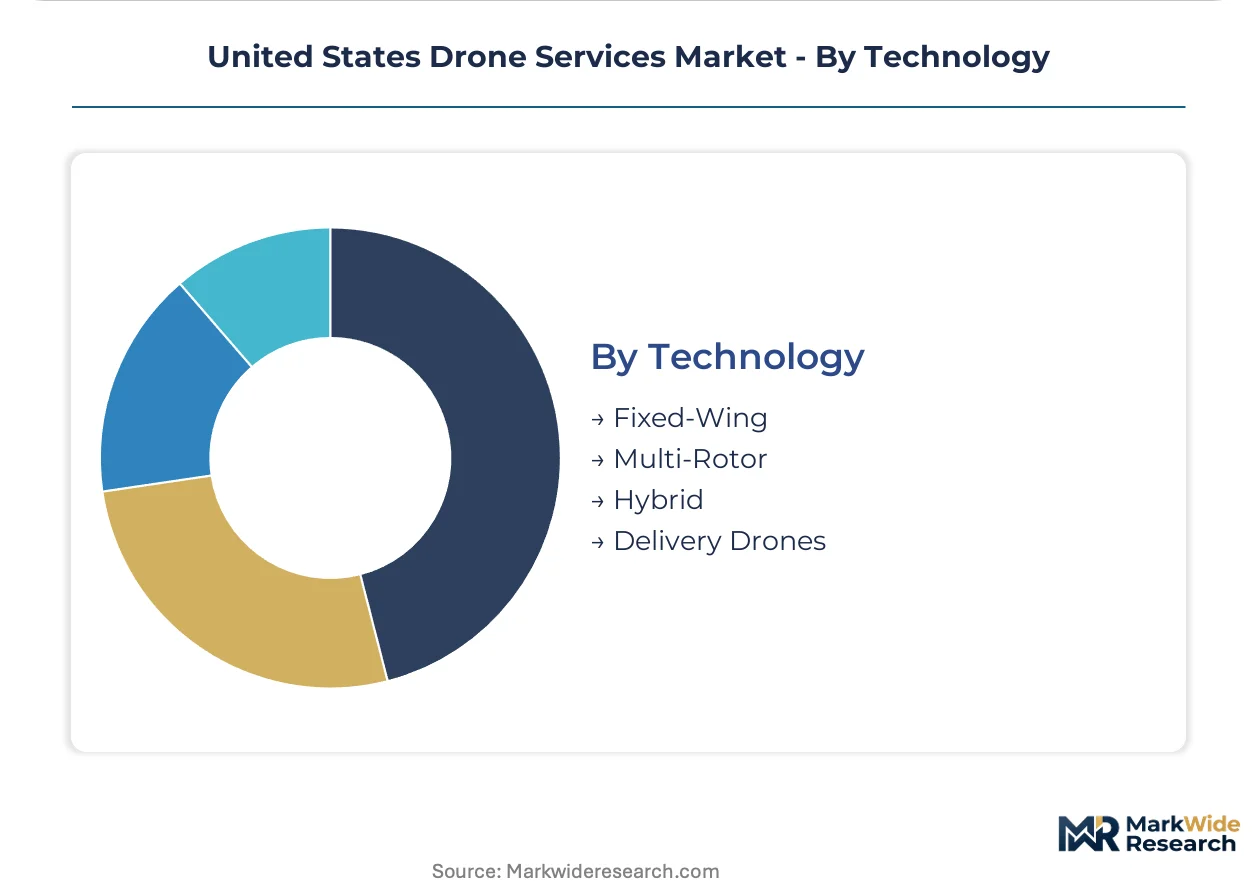
Technology:
Airframe configuration determines payload capacity, endurance, and regulatory classification thresholds.
- Fixed-Wing:Extended endurance platforms serve large-area agricultural and mapping missions. FAA Part 107 weight and altitude restrictions apply uniformly regardless of powertrain configuration.
- Multi-Rotor:Vertical takeoff capability dominates inspection and photography workflows where maneuverability outweighs range requirements. Solid-state lithium-polymer battery improvements extend flight duration to 45-90 minutes for commercial survey operations.
- Hybrid:Combined powertrain architectures attempt to merge endurance advantages with operational flexibility. Technical complexity elevates maintenance requirements and pilot training burdens.
- Delivery Drones:Purpose-built logistics platforms await beyond-visual-line-of-sight regulatory clarity. Payload weight restrictions and airspace deconfliction protocols remain unresolved.
Multi-Rotor handles the majority of commercial flight hours; Delivery Drones are gaining share fastest contingent on FAA rulemaking timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Permian Basin pipeline network anchors Texas as the dominant demand center for linear infrastructure inspection. California's metropolitan construction corridors and agricultural valleys generate dense contractor networks. Midwest grain handling facilities and North Dakota Bakken oil fields complete the continental distribution of service demand.
Texas
Oil and gas midstream operators across the Permian Basin require frequent aerial monitoring of pipeline integrity and flare stack conditions. FAA Part 107 waivers for energy corridor operations enable extended flight windows across rural counties. Houston and Midland host concentrated contractor networks serving ExxonMobil and Kinder Morgan infrastructure assets.
California
Commercial real estate developments in Los Angeles and the Bay Area drive progress monitoring and volumetric surveying contracts. State-level agricultural subsidies for precision farming create captive demand in the Central Valley. Sacramento regulatory frameworks on privacy and municipal zoning fragment deployment authority for surveillance applications.
North Dakota
Bakken shale operators consolidate vendor relationships for thermal imaging of well pads and transmission infrastructure. USDA crop insurance programs mandate drone-collected data for precision claims processing across wheat and soybean operations. Fargo and Bismarck anchor contractor networks serving both energy and agricultural segments.
Midwest Corn Belt
Iowa and Illinois grain handling facilities deploy variable-rate application systems for zone-specific chemical targeting. FAA testing center capacity constraints in Chicago and Des Moines extend Part 107 credentialing timelines during planting seasons. Des Moines and Cedar Rapids host agricultural analytics specialists integrating multispectral imaging with prescription mapping.
Florida
Residential real estate marketing in Miami and Orlando generates standardized aerial photography demand across brokerage networks. Hurricane response and disaster recovery operations create surge demand for emergency management deployments. Tampa and Jacksonville host inspection specialists serving coastal infrastructure and utility restoration contracts.
United States Drone Services Market Competitive Environment
Listed leaders compete with private specialists across platform autonomy and vertical software integration. The vendor base fragments between hardware manufacturers, software platforms, and pure-play service operators. Three archetypes dominate: autonomous flight specialists, agricultural analytics integrators, and cloud-based mission planning platforms. Consolidation pressures emerge as energy midstream operators demand multi-year service contracts with standardized reporting formats.
Within the autonomous flight tier, Skydio, Inc. and SkySpecs, Inc. exemplify hardware-software integration approaches. PrecisionHawk and DroneDeploy, Inc. occupy positions bridging analytics and platform standardization. These four entities represent the competitive core where FAA regulatory clarity on beyond-visual-line-of-sight operations will determine scale advantages.
| Leading Market Players |
|---|
| DroneDeploy, Inc. |
| PrecisionHawk |
| Skydio, Inc. |
| AgEagle Aerial Systems Inc. |
| Cyberhawk Innovations Limited |
| Zipline International Inc. |
| Wing Aviation LLC |
| Phoenix Drone Services LLC |
| SkySpecs, Inc. |
| Others |
Value Chain & Pricing Dynamics
Battery pack manufacturing scale economies in Shenzhen and Seoul concentrate cost leverage among East Asian cell producers, compressing price floors for US-based drone operators while elevating working capital requirements for domestic fleet operators seeking volume discounts.
Pricing Analysis
Volume-discount tiering structures separate enterprise multi-year contracts from per-flight arrangements and seasonal agricultural subscriptions. Pricing stratifies across FAA Part 107 certified operators, waiver-holding specialists, and uncertified independents based on compliance documentation and insurance coverage depth. Cost compression in the agricultural spraying segment intensifies as Midwest cooperatives consolidate vendor relationships. Energy infrastructure buyers exhibit lowest price sensitivity due to regulatory compliance mandates, while real estate marketing clients drive hardest bargain pressure.
Supply Chain Analysis
Inbound logistics costs through Long Beach and Savannah container terminals expose US operators to lithium-polymer cell delivery delays from Shenzhen, Dongguan, and Incheon production hubs. Solid-state battery development draws from cobalt cathode chemistries, carbon fiber airframe composites, and NVIDIA edge-computing modules. Single-source vulnerability concentrates in rare earth magnet suppliers for brushless motors. Distribution runs through direct OEM relationships for enterprise fleets and regional distributor networks for agricultural contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where FAA certification backlogs and Part 107 waiver scarcity create regulatory entrenchment that protects established operators from rapid competitive displacement.
For Market Incumbents: Consolidate through exclusive multi-year service contracts with Permian Basin midstream operators and North Dakota Bakken utilities, locking out emerging competitors. Acquire specialized agricultural analytics firms in Iowa and Illinois to capture USDA conservation incentive program flows. Counter the threat of autonomous flight algorithm commoditization by deepening vertical integration into prescription mapping software.
For New Entrants and Emerging Players: FAA Part 107 fast-track programs in Dallas-Fort Worth and Phoenix testing centers compress credentialing timelines for seasonal agricultural deployment. Target Florida hurricane response and disaster recovery segments where emergency procurement bypasses standard vendor qualification. Penetrate California Central Valley crop insurance data collection where state mandates create captive demand. Lead with thermal imaging specialization for utility predictive maintenance to differentiate from generalist competitors.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among energy infrastructure inspection specialists with multi-year master service agreements. Long-term viability centers on software-defined autonomy platforms rather than hardware-dependent service operators. Target acquisition archetypes include agricultural analytics integrators with proprietary prescription mapping engines. Watch FAA beyond-visual-line-of-sight rulemaking timelines as the critical inflection signal for delivery drone network scaling.
| Strategic Initiative | Industry Significance |
|---|---|
| Beyond-Visual-Line-of-Sight Certification Investment | Unlocks rural agricultural and linear infrastructure missions currently constrained by FAA Part 107 visual contact mandates. |
| Agricultural Analytics Platform Integration | Captures USDA conservation incentive flows through prescription mapping software tied to variable-rate application systems. |
| Energy Corridor Exclusive Contracting | Secures recurring revenue from Permian Basin and Bakken operators requiring thermal imaging for predictive maintenance. |
| Edge Computing Hardware Partnership | Enables real-time anomaly detection for utility inspection without cloud dependency, reducing data transmission costs. |
| Urban Air Mobility Corridor Positioning | Establishes early-mover presence in Department of Transportation designated testing zones for medical supply delivery networks. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of FAA regulatory filings, USDA conservation program documentation, and state-level agricultural subsidy records. Primary interviews engaged fleet operations managers at Texas energy infrastructure contractors, Part 107 certification instructors in Midwest testing centers, and precision agriculture specialists in North Dakota. Secondary validation drew from FERC infrastructure inspection reports, EIA energy corridor development data, and SEC filings of publicly traded drone technology providers. Bottom-up service provider capacity estimates triangulated against top-down addressable market calculations across application segments.
Segmentation dimensions modeled include application type, service configuration, end-user procurement sophistication, and airframe technology architecture across the projection horizon. CAGRs derived from historical adoption curves in agricultural spraying and infrastructure inspection, adjusted for regulatory implementation timelines. Forecast inputs incorporated battery energy density improvement trajectories and FAA rulemaking schedule assumptions for beyond-visual-line-of-sight operations.
Underlying assumptions cover stable lithium supply chain conditions and incremental FAA regulatory liberalization, with deviation risk concentrated in counter-drone equipment restriction tightening and visual-line-of-sight mandate persistence. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
UAV
Ultra-Long Endurance Drone Market
UAV
Stratospheric Flying Drone Market
UAV
Racing Drone Market
UAV
Drone Flight Controller System Market
UAV
Global Drone Services Market
UAV
Global Drone Sensor Market
UAV
GCC Drone Pilot Training Market
UAV
Latin America Small UAV Market
UAV
Europe Drones Market
UAV
Commercial UAV Market
UAV
Global Stratospheric UAV Payload Technology Market
UAV
Unmanned Aerial Vehicle Fuel Cell Market
UAV
Drone Payload Market
UAV
Tactical UAV Market
UAV
Drone-Based Consulting Services Market
UAV
Middle-East and Africa Drones Market