
 Europe Tethered Drone Market | 2026-2036
Europe Tethered Drone Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Tethered Drone Market Insights
MIL-STD compliance tier is redrawing competitive boundaries in European tethered drone procurement. Elistair leverages its French manufacturing base to anchor supply for defense and security agencies across Western Europe. Azur Drones dominates harbor and border surveillance deployments with persistent-flight platforms rated for maritime corrosion. Hoverfly Technologies specializes in tethered power systems for public safety agencies seeking uninterrupted aerial overwatch.
A tethered drone consists of an unmanned aerial vehicle connected to a ground station via a physical cable supplying continuous power and data transmission, typically operating at altitudes below 150 meters with flight endurance measured in hours rather than minutes. The tether eliminates battery swap cycles, enabling persistent intelligence, surveillance, and reconnaissance missions for military and law enforcement operators. Multirotor tethered drones lead European procurement volumes due to vertical takeoff flexibility in constrained urban environments, while hybrid tethered drones represent the fastest-expanding segment as operators seek extended endurance without sacrificing payload capacity. Mesh networking technology commands premium positioning in defense applications where jam-resistant communication links determine mission viability.
CE marking under the EU Drone Regulation frames airworthiness requirements for tethered operations in shared airspace, while EASA's specific-category certification pathway shapes product development timelines for manufacturers targeting cross-border deployments. France's DGAC operational waivers and Germany's BSI cybersecurity standards for critical infrastructure protection further segment market access conditions across national boundaries. Stakeholders must weigh national certification reciprocity against the cost of maintaining multiple regulatory compliance portfolios as European defense procurement moves toward greater interoperability standards.
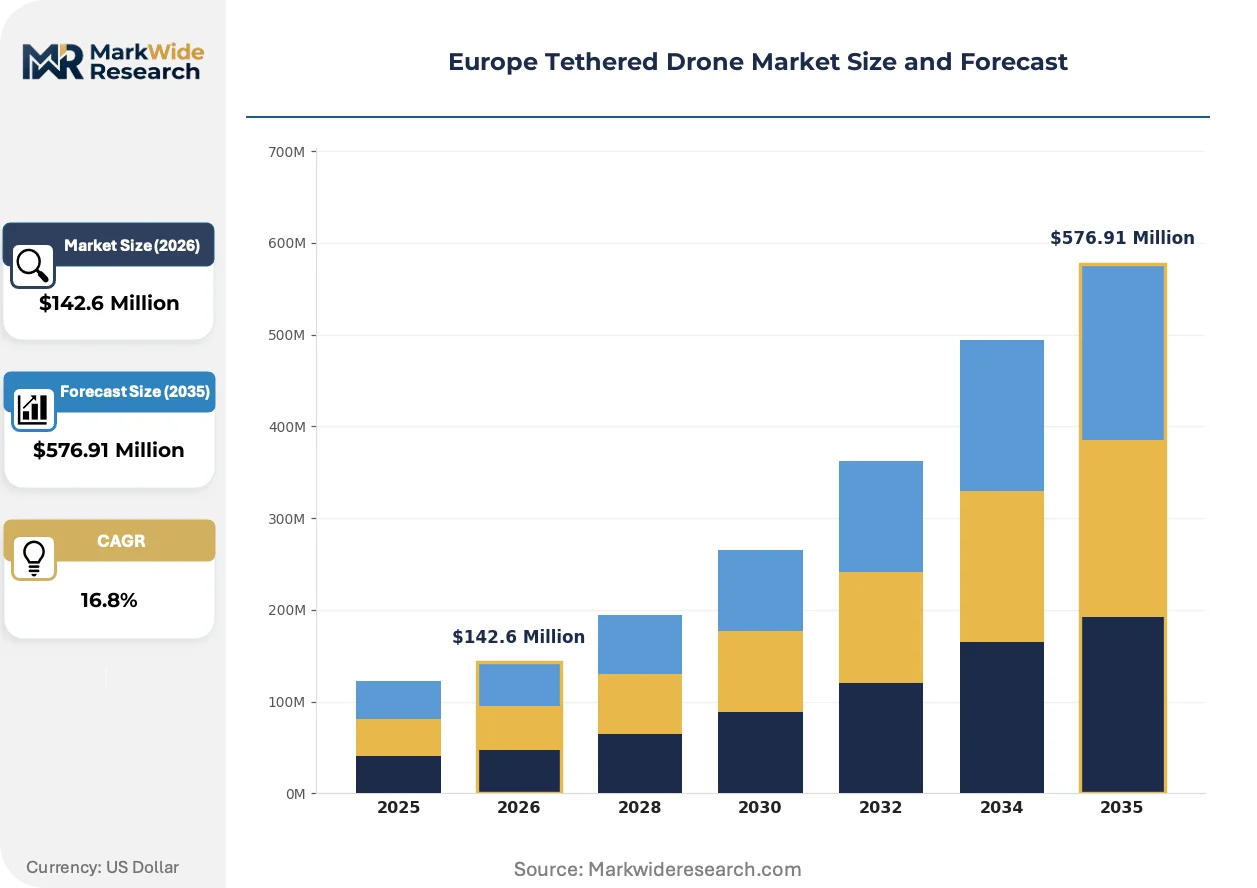
Market Dynamics
MIL-STD compliance requirements are fragmenting vendor qualification pathways across European defense procurement, forcing manufacturers to maintain parallel certification portfolios for national military buyers while EASA's specific-category framework governs cross-border commercial deployments.
Growth Catalysts
- EU Green Deal battery-waste mandates:Electric tethered systems gain preference over disposable battery platforms in public sector tenders, redirecting procurement budgets toward persistent-flight architectures.
- France's defense corridor concentration:DGAC operational waivers for beyond-visual-line-of-sight flights accelerate military ISR platform deployments along the nation's eastern border regions.
- Mesh networking integration:Jam-resistant communication protocols are becoming mandatory in defense specifications, elevating technical requirements for vendors serving NATO-aligned operators.
Market Restraints
- Copper conductor cost volatility:Tether cable manufacturing depends on copper pricing swings that compress hardware margins during procurement contract negotiations.
- Single-source fiber optic supply:High-bandwidth data tethers rely on specialized optical fiber production concentrated in Asian manufacturing hubs, creating import dependency risks.
- CE marking reciprocity gaps:Divergent national interpretations of EU Drone Regulation airworthiness standards delay product launches in secondary European markets.
Strategic Opportunities
- Poland's eastern flank surveillance gap:NATO infrastructure investments are creating demand corridors for persistent aerial monitoring along border zones with Belarus and Kaliningrad.
- Emergency response service unbundling:Fire departments and search-and-rescue units are separating drone-as-a-service contracts from traditional aviation equipment procurement.
- Hybrid hydrogen-electric convergence:Fuel cell backup systems combined with tethered primary power are extending mission endurance for critical infrastructure protection roles.
Industry Challenges
- Embedded systems cybersecurity certification:Germany's BSI standards for critical infrastructure protection require specialized engineering talent scarce in European labor markets.
- Legacy radar integration complexity:Tethered platforms must interface with existing air traffic management architectures designed for conventional aircraft transponder signatures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Tethered Drone Market |
| Market Size in 2026 | $142.6 Million |
| Market Size in 2035 | $576.91 Million |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Tethered Drones, Hybrid Tethered Drones, Fixed-Wing Tethered Drones, Multirotor Tethered Drones End User: Military, Law Enforcement, Agriculture, Security Application: Surveillance, Communication, Firefighting, Search and Rescue Technology: Wi-Fi, 4G LTE, 5G, Mesh Networking |
| Companies Covered | Azur Drones, Teledyne FLIR, Elistair, Hoverfly Technologies, Yuneec, Fotokite, UAVTEK, Sky Technologies, Novadem, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Tethered Drone Market Trends and Innovations
Power conversion electronics and fiber-optic data transmission are converging to reshape tethered platform specifications, compressing the performance gap between lightweight commercial units and military-grade persistent surveillance systems.
Silicon carbide power semiconductors are replacing traditional silicon-based voltage converters in ground station tether management systems. Defense integrators in France and Germany are specifying these components for reduced thermal signature and higher conversion efficiency. The technology is miniaturizing ground station footprints, enabling mobile deployment configurations previously restricted to fixed-site installations.
REACH chemical restrictions on halogenated flame retardants are forcing cable sheath reformulations for tether insulation materials. Manufacturers serving European markets must validate alternative compounds without degrading electromagnetic shielding performance. Maritime surveillance platforms operating in North Sea conditions face the most acute compliance pressure due to combined salt spray and abrasion resistance requirements.
Long-term leasing arrangements are displacing capital purchase models among municipal public safety agencies. French departmental governments and German state police forces are consolidating fleet management under specialized drone service operators. This restructuring concentrates buying power with intermediaries who negotiate multi-year performance contracts rather than discrete hardware acquisitions.
Europe Tethered Drone Market Segmentation
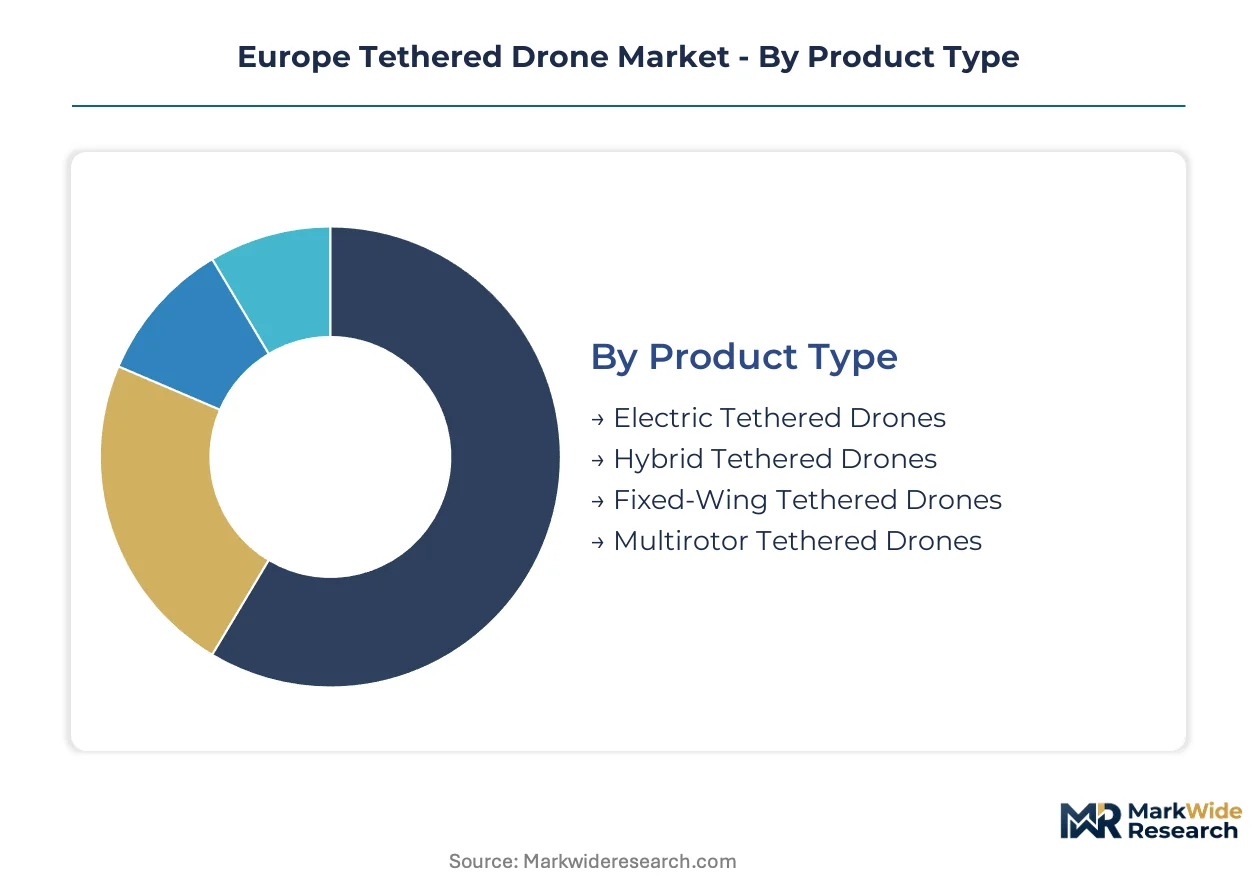
Segmentation in the European tethered drone market reflects divergent certification pathways and operational requirements across defense, public safety, and commercial verticals. EASA's specific-category framework and national military standards create distinct procurement silos that reward specialized product configurations.
Product Type:
EASA airworthiness certification tiers and MIL-STD compliance requirements split manufacturing strategies between commercial and defense-grade platforms.
- Multirotor Tethered Drones:Vertical takeoff capability enables deployment from confined urban spaces and vehicle-mounted ground stations. French DGAC operational waivers for beyond-visual-line-of-sight flights concentrate procurement along eastern border defense corridors where maneuverability in restricted terrain dominates specifications.
- Hybrid Tethered Drones:Dual-power architectures combine tethered primary supply with onboard battery or fuel cell backup for mission continuity during cable severance. German public safety agencies in North Rhine-Westphalia and Bavaria specify these platforms for critical infrastructure protection roles requiring guaranteed persistence.
- Electric Tethered Drones:Pure tethered power eliminates battery swap logistics for continuous surveillance missions.
- Fixed-Wing Tethered Drones:Aerodynamic efficiency supports extended endurance for maritime and perimeter monitoring applications.
Established volume favors multirotor configurations; emerging adoption favors hybrid architectures.
End User:
Procurement authority fragmentation across national defense ministries, interior departments, and agricultural agencies shapes contract structures and technical specifications.
- Military:Persistent intelligence, surveillance, and reconnaissance missions demand jam-resistant communications and electromagnetic-hardened components. NATO interoperability standards and France's defense procurement agency specifications drive platform requirements for eastern flank monitoring operations.
- Law Enforcement:Crowd monitoring and tactical overwatch applications prioritize rapid deployment from standard police vehicles. German state police forces in Baden-Württemberg and Hesse are consolidating fleet management under multi-year service contracts rather than capital purchases.
- Security:Private sector guarding and facility protection represents emerging commercial demand.
- Agriculture:Crop monitoring and livestock surveillance applications remain nascent due to cost thresholds.
Defense procurement concentrates purchasing power; municipal unbundling of drone services accelerates law enforcement adoption curves.
Application:
Mission duration requirements and payload specifications differentiate platform sizing across operational scenarios.
- Surveillance:Continuous optical and thermal monitoring for border, harbor, and critical infrastructure protection. Azur Drones dominates French maritime deployments with corrosion-rated platforms operating in North Sea conditions.
- Communication:Aerial network relay and emergency cellular restoration extend coverage in disaster zones or remote terrain.
- Search and Rescue:Thermal detection and loudspeaker coordination support alpine and coastal emergency response.
- Firefighting:Persistent overwatch for wildfire progression mapping and hotspot identification.
Surveillance applications anchor current revenue; communication relay functions gain share fastest as mesh networking integration matures.
Technology:
Data transmission protocols determine mission viability in contested electromagnetic environments and bandwidth-intensive operations.
- Mesh Networking:Self-healing, jam-resistant topologies mandatory in NATO-aligned defense specifications. Elistair integrates these protocols for French military and security agency deployments requiring communication continuity under electronic warfare conditions.
- 5G:Ultra-reliable low-latency links enable real-time high-definition video streaming and command responsiveness.
- 4G LTE:Established commercial coverage supports public safety operations in urban and suburban environments.
- Wi-Fi:Short-range, high-bandwidth connectivity for localized deployments with established ground infrastructure.
Mesh networking commands defense premiums; 5G integration represents the steepest expansion trajectory as public safety agencies modernize command systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense buyers in France and Germany demonstrate low price elasticity for MIL-STD-compliant platforms, while municipal public safety agencies across Southern Europe exhibit acute budget sensitivity that favors leasing over capital acquisition.
France
DGAC operational waivers for beyond-visual-line-of-sight flights accelerate military ISR deployments along eastern border corridors. The EU Green Deal's battery-waste mandates redirect procurement toward electric tethered architectures. Defense technology clusters in Île-de-France and Provence-Alpes-Côte d'Azur concentrate manufacturing capability for NATO-aligned persistent surveillance systems.
Germany
BSI cybersecurity standards for critical infrastructure protection create specialized engineering demand that outstrips domestic labor supply. Federal interior ministry funding consolidates state police fleet management under multi-year service contracts. North Rhine-Westphalia and Bavaria anchor public safety technology procurement for hybrid tethered platforms with mission-continuity backup.
United Kingdom
Maritime surveillance requirements in North Sea and English Channel conditions drive corrosion-resistant platform specifications. Civil Aviation Authority integration with NATO interoperability standards shapes defense procurement timelines. Technology development concentrates in Greater London and Southeast England for mesh networking integration.
Poland
NATO infrastructure investments along the Belarus and Kaliningrad borders generate demand corridors for persistent aerial monitoring. National defense procurement agency specifications align with emerging EU defense fund eligibility criteria. Industrial activity clusters in Warsaw and Krakow metropolitan areas for border surveillance system integration.
Italy
Mountain rescue and alpine emergency response applications prioritize rapid-deployment multirotor configurations for thermal detection missions. ANAC civil aviation regulatory harmonization with EASA specific-category frameworks accelerates product certification timelines. Northern industrial regions in Lombardy and Piedmont concentrate system integration capability for public safety agencies.
Europe Tethered Drone Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the European tethered drone market. The vendor base separates into defense-integrated specialists with MIL-STD certification portfolios and commercial-scale manufacturers serving municipal public safety leasing markets. Three archetypes dominate: French defense corridor incumbents with DGAC waiver relationships, German-engineered cybersecurity-compliant platforms, and Nordic design-origin specialists in maritime corrosion resistance. Competitive dynamics center on strategic partnerships with national procurement agencies and geographic expansion through EASA specific-category certification reciprocity.
Among France-based specialists, Elistair and Azur Drones exemplify divergent positioning archetypes within the same national market. Elistair occupies a position aligned with defense and security agency supply relationships, while Azur Drones represents maritime surveillance specialization with corrosion-rated platform configurations. Hoverfly Technologies, with US-origin naming convention, sits within the public safety technology tier serving municipal agencies seeking uninterrupted aerial overwatch capability. These three anchors illustrate how geographic proximity to procurement authorities and regulatory waiver pathways shape competitive positioning more than scale economies alone.
| Leading Market Players |
|---|
| Azur Drones |
| Teledyne FLIR |
| Elistair |
| Hoverfly Technologies |
| Yuneec |
| Fotokite |
| UAVTEK |
| Sky Technologies |
| Novadem |
| Others |
Pricing and Supply Chain Analysis
Ninety-day inventory cycles for fiber-optic tether cables concentrate procurement leverage with French and German defense integrators, compressing hardware margins for manufacturers while elevating long-term service contract premiums. This lead-time structure rewards vendors with DGAC waiver relationships and BSI cybersecurity certification portfolios, locking out speculative entrants from price-sensitive municipal segments.
Pricing Analysis
After-sales service contracts and multi-year performance agreements drive lifetime value for tethered drone vendors, displacing transactional hardware sales in European public safety procurement. Three-tier pricing structure across MIL-STD-certified defense platforms, CE-marked commercial systems, and economy-tier municipal leasing separates Elistair's premium positioning from Hoverfly Technologies' service-based models. Cost compression in copper conductor procurement is intensifying because of commodity price volatility, squeezing margins on fixed-price defense contracts. German state police forces exhibit acute price sensitivity, while French military buyers demonstrate low elasticity for jam-resistant mesh networking integration.
Supply Chain Analysis
Inventory cycles stretching to ninety days for specialized fiber-optic tethers expose European assemblers to single-source dependencies concentrated in Asian manufacturing hubs. Ground station production draws from German silicon carbide semiconductor fabrication, French electromagnetic shielding componentry, and Italian precision mechanical assemblies. Single-source vulnerability in halogen-free cable sheath compounds under REACH chemical restrictions threatens maritime platform deliveries. Distribution runs through defense procurement agencies in France and Germany, with emerging channel consolidation among drone-as-a-service operators serving municipal law enforcement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through German state police fleet consolidation and French departmental government leasing unification, fragmenting vendor pricing power across fragmented municipal procurement.
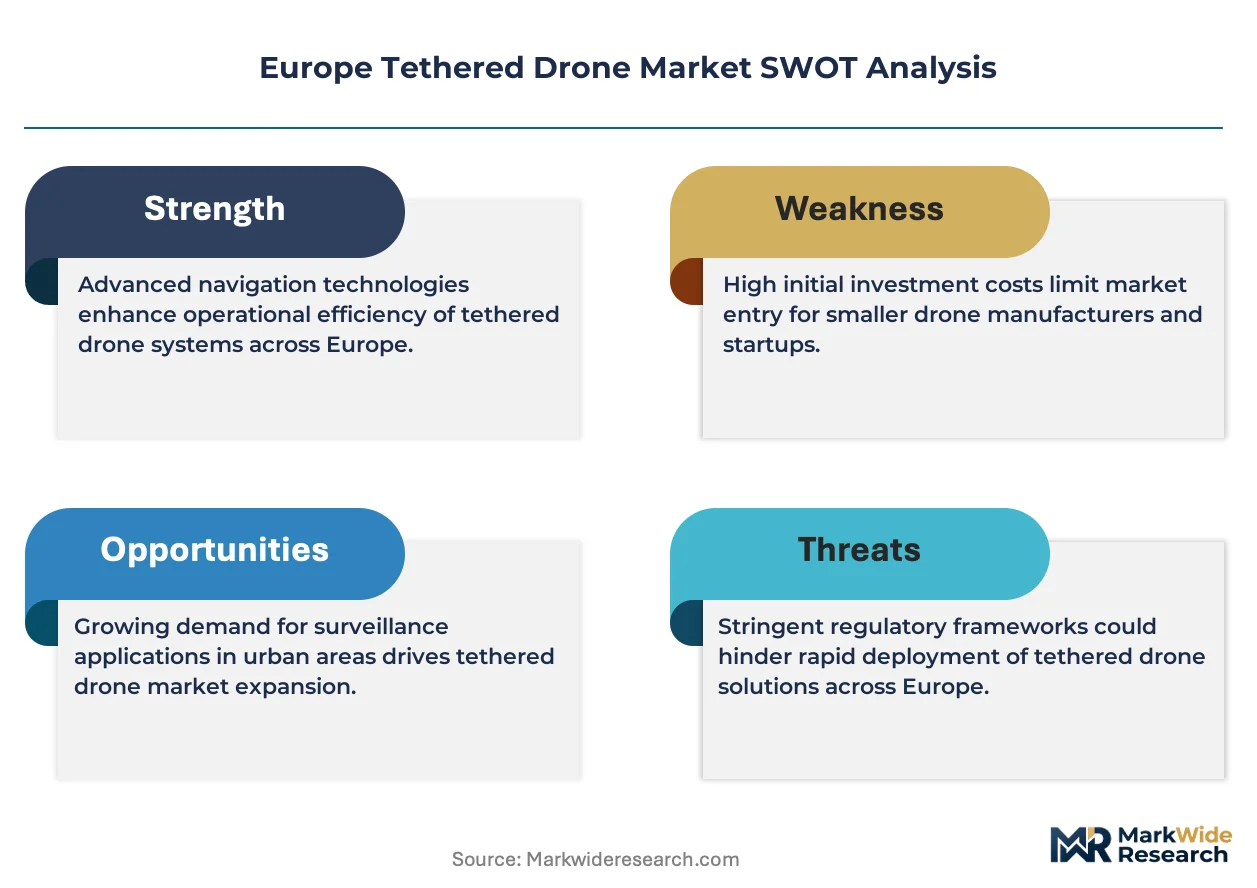
For Market Incumbents: Consolidate DGAC waiver relationships and BSI cybersecurity certification portfolios to defend against emerging Nordic maritime specialists. Deepen backward integration into silicon carbide power semiconductor sourcing to offset copper cost volatility. Lock in multi-year performance contracts with French defense procurement agencies before EU defense fund eligibility criteria harden. For New Entrants and Emerging Players: Anchor in Poland's eastern flank surveillance gap where NATO infrastructure investments outpace established vendor certification timelines. Target Italian alpine rescue services with rapid-deployment multirotor configurations for thermal detection missions. Pursue EASA specific-category certification reciprocity as the primary go-to-market pathway for cross-border commercial scaling. For Investors and Strategic Acquirers: Long-term, this sits as a defense-integrated infrastructure play because persistent aerial surveillance demand is tethered to NATO eastern flank monitoring commitments and EU Green Deal battery-waste mandates. Acquisition targets should display hybrid hydrogen-electric convergence capability and mesh networking integration expertise. Watch for Polish national defense procurement agency specification alignment with EU defense fund criteria as the inflection signal for demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| EASA Specific-Category Certification | Enables cross-border deployments for French manufacturers targeting German public safety markets. |
| Mesh Networking Integration | Meets NATO jam-resistant communication mandates for eastern flank surveillance contracts. |
| Hybrid Power Architecture Development | Addresses German BSI mission-continuity requirements for critical infrastructure protection. |
| Multi-Year Service Contract Structuring | Aligns with French departmental government fleet consolidation under specialized operators. |
| REACH-Compliant Cable Reformulation | Satisfies chemical restrictions for North Sea maritime surveillance platform deployments. |
Research Methodology
The analysis maps multirotor configurations, hybrid architectures, mesh networking protocols, and fiber-optic transmission systems, each validated through defense procurement officers, public safety fleet managers, EASA certification specialists, and tether cable manufacturing engineers. Primary interviews with French DGAC waiver holders and German BSI compliance consultants combined with secondary validation from EASA regulatory filings, NATO interoperability standards documentation, EU defense procurement databases, and customs trade data for copper conductor imports. Bottom-up platform deployment estimates and top-down defense budget allocation analysis provided cross-verification.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation modeling incorporated product type, end-user procurement authority, application mission duration, and technology protocol requirements. CAGRs were derived from defense expenditure trajectory analysis and public safety leasing contract velocity. Industry-specific forecast inputs included DGAC operational waiver issuance rates and BSI cybersecurity certification completion timelines.
Decision-makers should treat outputs as directional under assumptions of sustained NATO eastern flank investment and stable EASA regulatory reciprocity; material deviation would warrant model refresh. Forecasts reflect these base conditions alongside copper price band assumptions and fiber-optic supply continuity. Revision becomes warranted when DGAC waiver processing delays or REACH chemical restriction enforcement intensity crosses thresholds affecting platform certification timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
UAV
Drone Motors Market
UAV
Europe Commercial Drones Market
UAV
Drone Inspection Service Market
UAV
UAV GNSS Antenna Market
UAV
Fixed-Wing VTOL UAV Market
UAV
Commercial Drone-Enabled Services Market
UAV
Counter Drone System Market
UAV
Small UAV Market
UAV
Electric Unmanned Aerial Vehicle Market
UAV
Global Aerial Imaging Market
UAV
FPV Drone Goggles Market
UAV
Racing Drone Market
UAV
Drone Camera Market
UAV
Firefighting Drone Market
UAV
Global Aerial Survey Services Market
UAV
Ultra Micro Drone Market