
 Drone Data Management Market | 2026-2036
Drone Data Management Market Size, Share, and Industry Trends Forecast 2026-2036
Drone Data Management Market Insights
Edge-native data pipelines is rewriting how drone-captured information reaches decision-makers, compressing latency from hours to seconds for field-critical workflows. DroneDeploy leverages cloud-to-edge orchestration to sustain dominance in construction mapping workflows. Pix4D anchors its position through photogrammetry engines that process multispectral imagery at scale. Skydio competes on autonomous flight intelligence that reduces operator skill barriers for infrastructure inspection.
Drone data management encompasses the ingestion, processing, storage, and analytical transformation of aerial sensor outputs—principally RGB, LiDAR, thermal, and multispectral data—into structured intelligence for operational planning and asset monitoring. The discipline relies on photogrammetric reconstruction algorithms generating sub-centimeter ground sample distances and real-time kinematic positioning for georectification accuracy. Analytics platforms lead value capture by converting raw flight data into predictive maintenance and yield-optimization models. Cloud-based deployments expand fastest among precision farming operators requiring seasonal elasticity, while on-premises systems retain traction with defense and critical infrastructure clients governed by data sovereignty mandates.
The FAA's Part 107 framework and the EU's U-space drone regulations shape operator certification thresholds and beyond-visual-line-of-sight permissions, directly governing fleet scalability and software compliance requirements. ISO 21384-3 unmanned aircraft systems standards further codify data quality and flight safety protocols for cross-border commercial operations. Stakeholders must monitor evolving national airspace integration timelines and align platform architectures with emerging remote identification mandates.
Market Dynamics
Edge computing architectures are compressing data processing latency from hours to seconds, forcing platform vendors to rearchitect cloud-native pipelines for field-deployable inference. This shift rewards operators with distributed compute footprints while penalizing pure-cloud providers serving time-critical inspection workflows.
Growth Catalysts
- FAA Part 107 Certification:Standardized remote pilot competency requirements in the United States have lowered enterprise liability thresholds and accelerated fleet deployment across infrastructure and agriculture sectors.
- Photogrammetry Automation:Real-time kinematic positioning and sub-centimeter ground sample distance algorithms now enable survey-grade outputs without ground control points, expanding addressable use cases.
- Construction Sector Demand:Manual site surveys face displacement by drone-captured orthomosaics and digital elevation models, creating persistent software subscription pull-through.
Market Restraints
- LiDAR Sensor Cost Concentration:High-precision ranging modules remain concentrated among specialized photonics suppliers, compressing hardware margins for integrated platform vendors.
- Data Sovereignty Mandates:Defense and critical infrastructure clients in Germany and France require on-premises deployments, fragmenting vendor architectures and raising compliance overhead.
- Battery Energy Density Limits:Lithium-polymer chemistry constraints cap flight endurance below 45 minutes for multirotor platforms, restricting single-mission coverage area.
Strategic Opportunities
- Brazil Agriculture Expansion:Precision farming penetration remains below 15% in Mato Grosso and Goiás soybean belts, creating whitespace for seasonal elasticity pricing models.
- EU U-Space Integration:Beyond-visual-line-of-sight permissions under harmonized airspace rules will unlock automated corridor inspection contracts across German and French rail networks.
- Multispectral-Thermal Fusion:Converged sensor payloads enable crop stress detection and photovoltaic defect identification from single flights, expanding per-acre value capture.
Industry Challenges
- Remote Pilot Talent Scarcity:FAA-certified operators number under 300,000 for commercial demand projected to exceed 500,000 by mid-decade, inflating wage premiums and training backlogs.
- Legacy GIS Integration Friction:Enterprise asset management systems from Esri and Bentley require custom API middleware, extending deployment timelines and professional services dependency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drone Data Management Market |
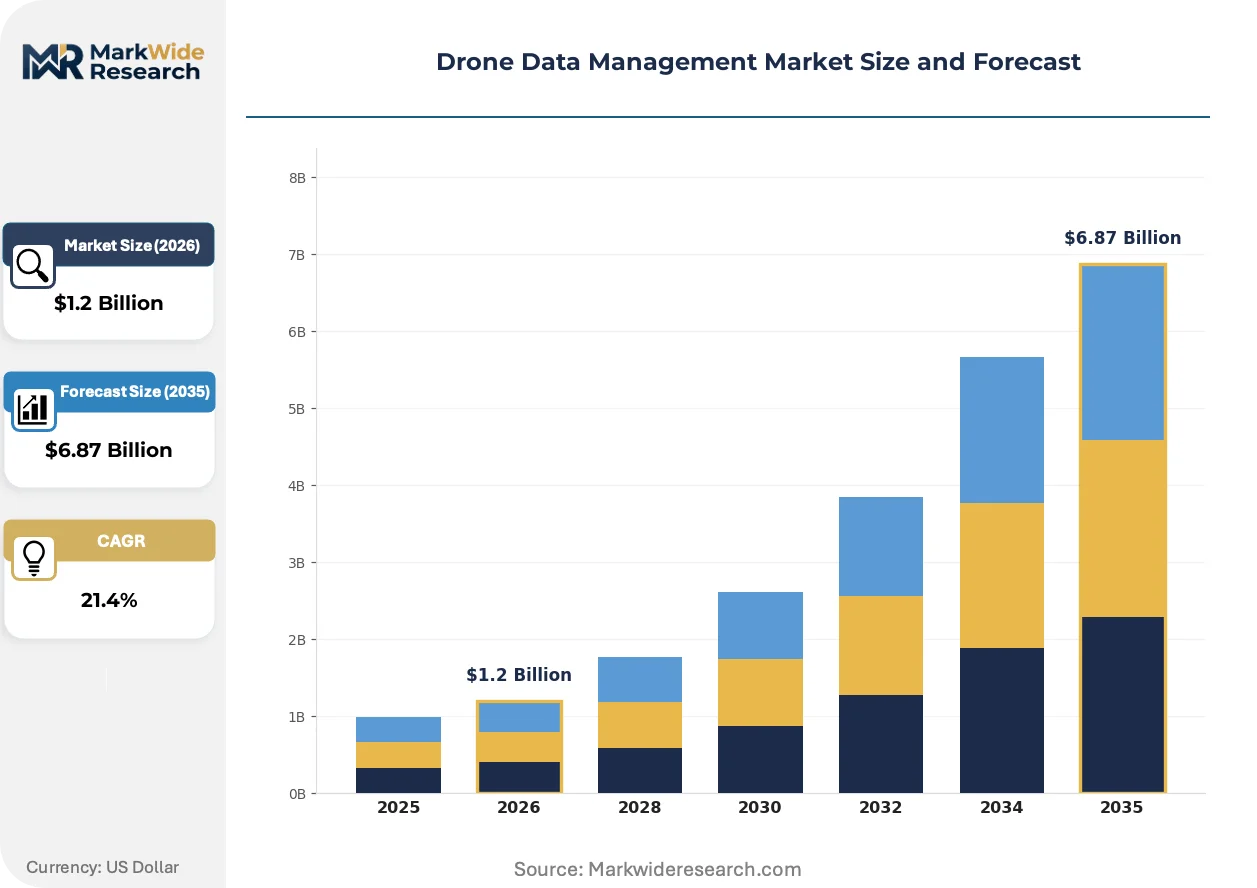
| Market Size in 2026 | $1.2 Billion |
| Market Size in 2035 | $6.87 Billion |
| CAGR (2026 – 2036) | 21.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Data Processing Software, Data Storage Solutions, Analytics Platforms, Visualization Tools, Data Security Systems Use Case: Mapping, Infrastructure Inspection, Agricultural Monitoring, Disaster Management, Environmental Surveying End User: Surveyors, Precision Farming Operators, Construction Firms, Emergency Responders, Environmental Agencies Deployment: Cloud-Based, On-Premises, Hybrid, Edge Computing Platforms, SaaS Solutions |
| Companies Covered | DroneDeploy, PrecisionHawk, Pix4D, Kespry, SZ DJI Technology, Esri, Skydio, DELAIR, Skycatch, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drone Data Management Market Trends and Innovations
Real-time inference at the point of capture is displacing batch processing workflows, compressing decision cycles from days to minutes for field operations. This architectural shift redefines competitive advantage around latency rather than storage economics.
Edge-native AI accelerators are digitizing raw sensor streams into actionable intelligence aboard the aircraft. Mining operators in Western Australia now deploy NVIDIA Jetson modules for instant haul road defect flagging. This capability is digitizing the traditional surveyor-to-engineer handoff, eliminating ground station bottlenecks.
The EU's U-space regulatory framework mandates remote identification and geofencing for all commercial operations above 250 grams. Airspace management service providers must certify detect-and-avoid systems under EASA oversight. German energy utilities are pre-emptively retrofitting inspection fleets to comply with 2026 conformance deadlines.
Subscription pricing for photogrammetry processing is displacing perpetual license models among mid-sized surveying firms. Channel partners in the United States now bundle hardware financing with software tiers to reduce upfront capital barriers. This shift concentrates most visibly among California and Texas construction contractors managing seasonal project volatility.
Drone Data Management Market Segmentation
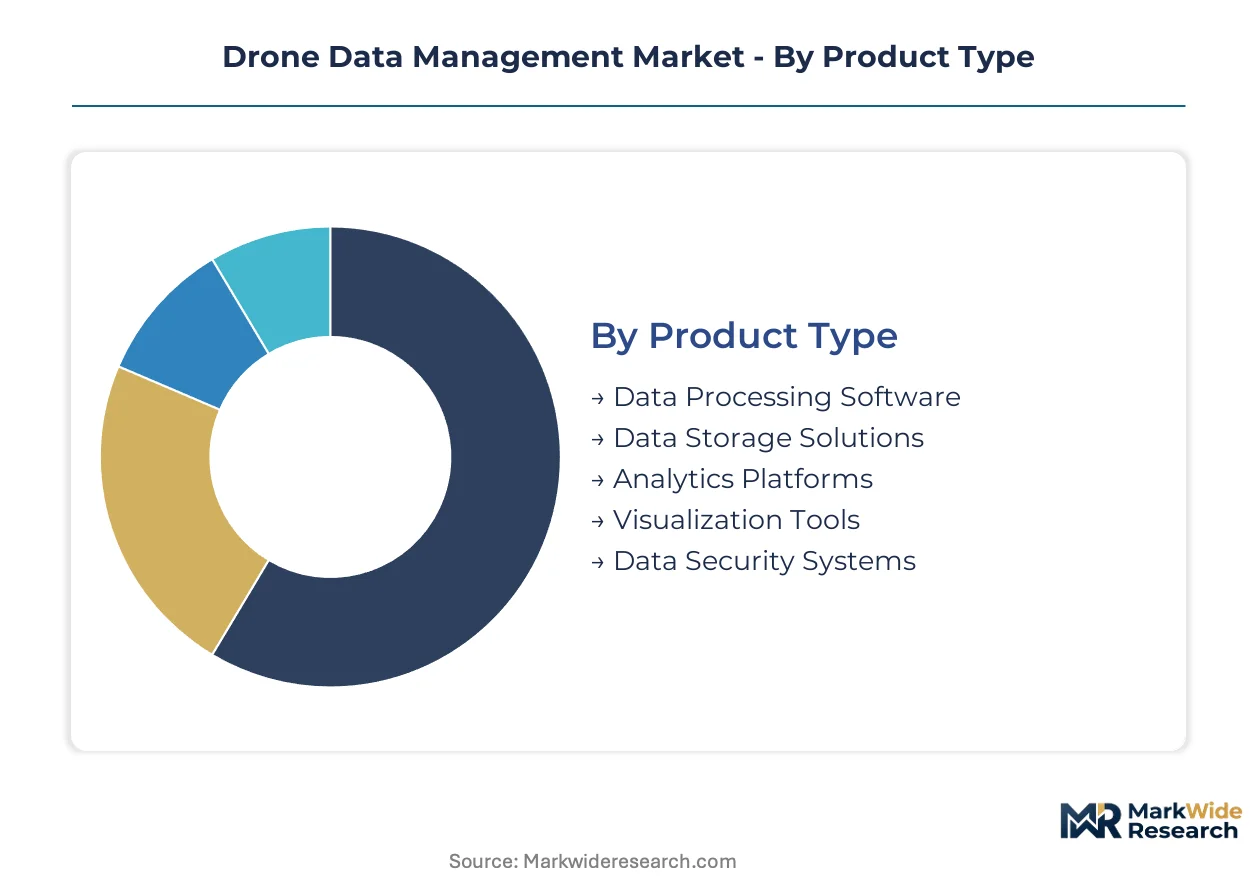
Drone data management platforms must align software architecture with distinct operational tempos across inspection, agriculture, and emergency response workflows. Segmentation reveals where latency requirements, compliance mandates, and sensor complexity create divergent purchasing criteria.
Product Type:
Software modules span the data lifecycle from ingestion through actionable intelligence, with cost tiers reflecting computational intensity and integration depth.
- Data Processing Software:Photogrammetric engines reconstruct RGB and LiDAR streams into orthomosaics and point clouds. Surveyors in Texas and California drive demand for sub-centimeter ground sample distance outputs without ground control points.
- Analytics Platforms:Machine learning pipelines convert multispectral and thermal data into predictive maintenance and yield-optimization models. Precision farming operators in the United States and Brazil concentrate purchasing for seasonal crop stress detection.
- Data Storage Solutions:Tiered architectures accommodate petabyte-scale flight archives with retrieval latency requirements varying by use case. Defense clients mandate on-premises vaults under data sovereignty protocols.
- Visualization Tools:3D mesh rendering and temporal comparison interfaces enable stakeholder communication across distributed project teams.
- Data Security Systems:Encryption-at-rest and access governance modules address FAA remote identification compliance and EU U-space data protection mandates.
The dominant share belongs to Data Processing Software, while Analytics Platforms is gaining share fastest as operators prioritize inference over raw storage.
Use Case:
Application maturity varies sharply by regulatory clarity and return-on-calculation visibility.
- Mapping:Orthomosaic and digital elevation model generation for construction progress monitoring and cadastral survey. German and French infrastructure contractors now specify survey-grade outputs in procurement tenders.
- Infrastructure Inspection:Automated defect detection across transmission lines, pipelines, and transport corridors. EU U-space beyond-visual-line-of-sight permissions will unlock automated rail network contracts.
- Agricultural Monitoring:Multispectral crop health indices and variable-rate prescription maps. Brazilian Mato Grosso soybean operators represent underpenetrated whitespace below 15% adoption.
- Disaster Management:Rapid damage assessment and search-and-rescue coordination for emergency responders.
- Environmental Surveying:Erosion tracking, wetland delineation, and carbon stock estimation for regulatory compliance.
Infrastructure Inspection commands the largest current deployment base, though Agricultural Monitoring shows the steepest expansion trajectory as Brazil and India accelerate precision farming adoption.
End User:
Customer archetypes diverge by technical sophistication, fleet scale, and integration requirements with legacy enterprise systems.
- Construction Firms:General contractors and project developers replacing manual site surveys with drone-captured progress documentation. United States federal infrastructure spending amplifies procurement velocity.
- Surveyors:Licensed geomatics professionals requiring survey-grade accuracy and audit trails for legal boundary determination.
- Precision Farming Operators:Large-scale agricultural enterprises managing seasonal elasticity and per-acre value capture through yield optimization.
- Emergency Responders:Fire departments and search-and-rescue units prioritizing real-time situational awareness over archival precision.
- Environmental Agencies:Government and nonprofit entities conducting longitudinal ecosystem monitoring under regulatory mandates.
Construction Firms hold the leading position by revenue, with Precision Farming Operators expanding most quickly through Brazil and India market development.
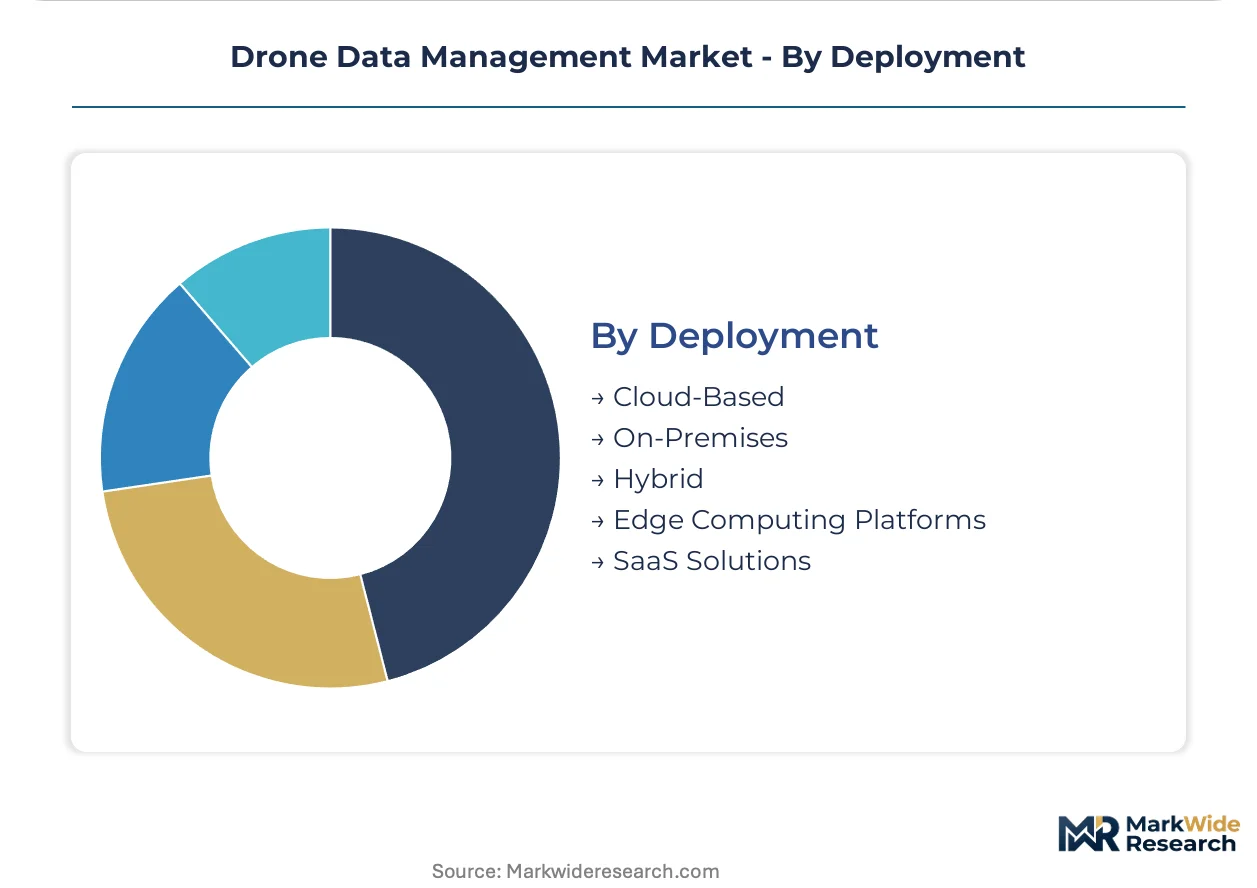
Deployment:
Infrastructure configuration reflects data sovereignty requirements, mission latency constraints, and capital versus operating expenditure preferences.
- Cloud-Based:Elastic compute and storage for seasonal agriculture workloads and distributed project collaboration. United States precision farming operators dominate consumption.
- Edge Computing Platforms:NVIDIA Jetson and similar accelerators enabling real-time inference aboard aircraft or field gateways. Mining operators in Western Australia deploy for instant haul road defect flagging.
- On-Premises:Air-gapped systems for defense and critical infrastructure clients governed by German and French data sovereignty mandates.
- Hybrid:Tiered architectures balancing sensitive processing on-premises with scalable analytics in cloud environments.
- SaaS Solutions:Subscription photogrammetry processing displacing perpetual licenses among mid-sized United States surveying firms.
Cloud-Based deployment retains the largest installed base, while Edge Computing Platforms is climbing the fastest as latency requirements compress from hours to seconds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Precision agriculture operators in the United States, infrastructure contractors in Germany, and mining enterprises in Australia represent the dominant buyer archetypes shaping regional demand patterns. Each geography concentrates purchasing around distinct regulatory timelines and operational tempo requirements.
United States
Federal infrastructure spending and precision agriculture investments drive concentrated software procurement. The FAA's Part 107 certification framework standardizes remote pilot competency thresholds, lowering enterprise liability barriers. Texas and California construction contractors now specify drone-captured orthomosaics in procurement tenders for federal highway projects.
Germany
Rail network operators and energy utilities prioritize automated corridor inspection contracts under advancing U-space permissions. The country's national aviation regulator mandates detect-and-avoid system certification for beyond-visual-line-of-sight operations. Bavaria-based infrastructure contractors are pre-emptively retrofitting fleets to meet 2026 conformance deadlines for remote identification.
Brazil
Mato Grosso and Goiás soybean belt operators represent underpenetrated whitespace with precision farming adoption below 15%. The national agricultural regulator supports seasonal elasticity pricing models through rural credit expansion programs. São Paulo-based agritech distributors now bundle hardware financing with software subscriptions to reduce upfront capital barriers.
Australia
Western Australia mining operators deploy edge-native AI accelerators for instant haul road defect flagging. The country's civil aviation safety authority governs commercial remote pilot licensing and airspace integration timelines. Perth-based resource extraction companies are digitizing traditional surveyor-to-engineer handoffs through field-deployable inference systems.
France
Critical infrastructure clients require on-premises deployments under data sovereignty protocols governing defense and nuclear asset monitoring. The national data protection regulator enforces encryption-at-rest mandates for aerial sensor archives. Île-de-France energy utilities are fragmenting vendor architectures to satisfy compliance overhead for air-gapped systems.
Drone Data Management Market Competitive Landscape
Channel-controlling players compete with product-specialist players for procurement relationships with fleet-scale operators. The vendor base organizes around three strategic archetypes: cloud-native platform orchestrators, photogrammetry engine specialists, and autonomous flight intelligence providers. Dominant competitive moves include strategic partnerships with hardware manufacturers and portfolio diversification into edge computing accelerators.
Within the cloud-to-edge orchestration tier, DroneDeploy and Skycatch represent platform vendors compressing latency for construction mapping workflows. Pix4D anchors the photogrammetry specialist segment through multispectral processing engines. Skydio occupies a position among autonomous flight intelligence providers reducing operator skill barriers for infrastructure inspection contracts.
| Leading Market Players |
|---|
| DroneDeploy |
| PrecisionHawk |
| Pix4D |
| Kespry |
| SZ DJI Technology |
| Esri |
| Skydio |
| DELAIR |
| Skycatch |
| Others |
Pricing and Supply Chain Analysis
Single-source dependency on NVIDIA Jetson modules for edge-native AI accelerators determines both three-tier pricing spreads across premium-mid-economy levels and supply chain configuration favoring US and Taiwanese component flows. LiDAR sensor cost concentration among specialized photonics suppliers compresses hardware margins and forces subscription pricing adoption among mid-sized surveying firms.
Pricing Analysis
Cost-plus contracts with lithium-polymer battery indexation dominate hardware procurement for multirotor platform vendors. Three-tier pricing structure across premium, standard, and economy levels segments by photogrammetry engine certification grade and seasonal elasticity requirements. Pricing pressure stems from Brazilian agritech distributors bundling hardware financing with software subscriptions to reduce upfront capital barriers. Precision farming operators in Mato Grosso exhibit highest price sensitivity, while defense clients governed by data sovereignty mandates show lowest sensitivity due to compliance-driven procurement.
Supply Chain Analysis
Export-control restrictions under US Commerce Department regulations limit NVIDIA GPU flows to Chinese drone manufacturers, fragmenting global component sourcing. Supply concentration centers on Taiwan for semiconductor fabrication, China for lithium-polymer cell production, and Germany for precision optics. Raw material dependencies include rare-earth magnets for motor assemblies, gallium arsenide for photonics, and cobalt for battery cathodes. Single-source vulnerability runs through Taiwanese foundry capacity for AI accelerator chips. Distribution runs through São Paulo-based agritech distributors for Brazilian agriculture, California channel partners for US construction contractors, and direct enterprise sales for defense clients.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
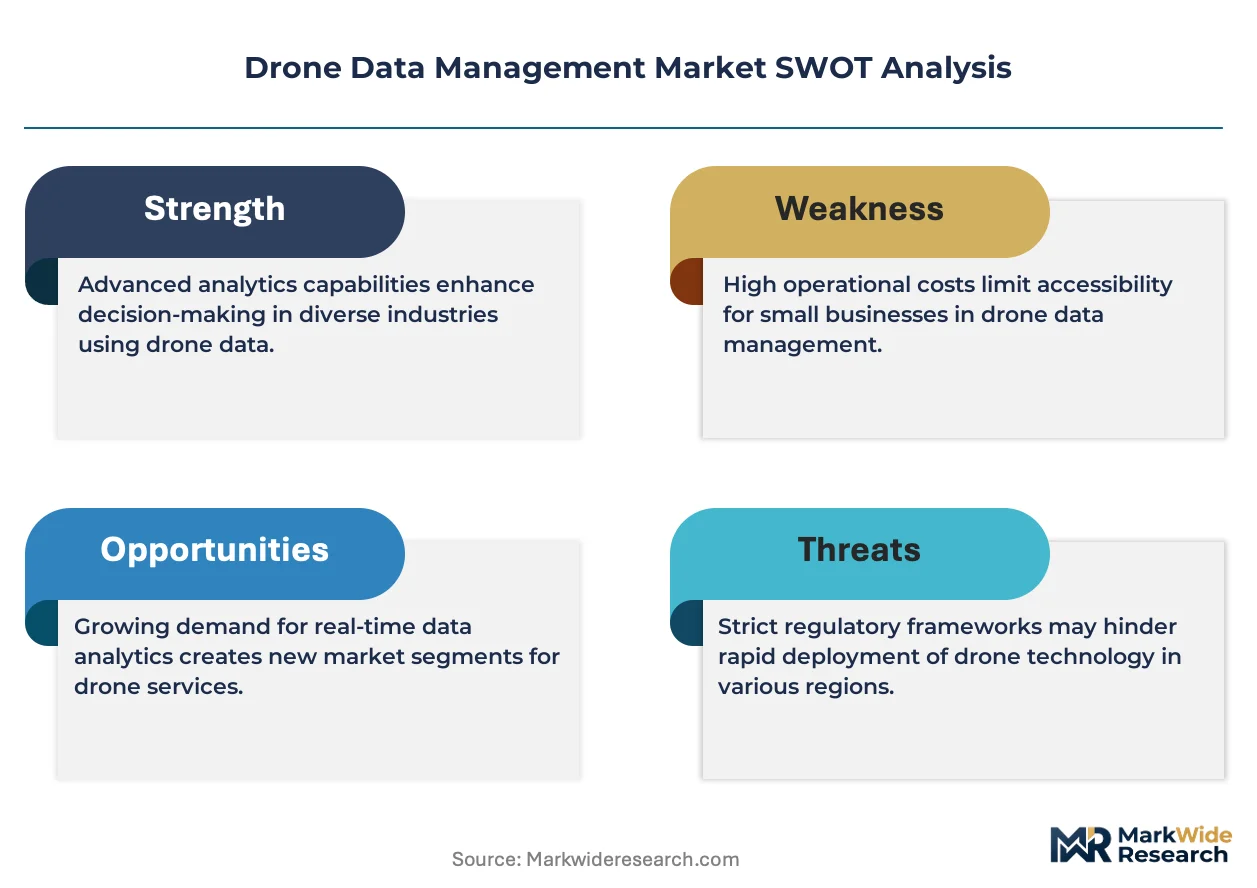
Drone data management is approaching a platform-economics inflection as edge-to-cloud orchestration interoperability becomes the primary procurement criterion for fleet-scale operators. The EU's U-space regulatory framework is accelerating ecosystem consolidation around certified detect-and-avoid system providers.
For Market Incumbents: Build switching-cost moats through deep API integration with Esri and Bentley enterprise asset management systems. Incumbents should preemptively retrofit inspection fleets for 2026 EU U-space remote identification conformance deadlines while acquiring edge computing accelerator specialists to defend against pure-cloud vendor displacement. Certification investment in ISO 21384-3 unmanned aircraft systems standards creates procurement gatekeeping power. For New Entrants and Emerging Players: Build out seasonal elasticity pricing models for Brazilian Mato Grosso and Goiás soybean belt operators where precision farming penetration remains below 15%. New entrants should target underpenetrated whitespace in multispectral-thermal fusion sensor payloads for photovoltaic defect identification. Go-to-market execution favors bundling hardware financing with software subscriptions through São Paulo agritech distributor partnerships. For Investors and Strategic Acquirers: Edge-native AI accelerator specialists with NVIDIA Jetson deployment track record in Western Australian mining operations represent priority acquisition targets. Long-term viability hinges on airspace integration regulatory clarity and beyond-visual-line-of-sight permission scalability. The signal to monitor is FAA Part 107 remote pilot certification velocity against commercial operator demand projections.| Strategic Initiative | Industry Significance |
|---|---|
| Edge Computing Platform Integration | NVIDIA Jetson deployment compresses inference latency from hours to seconds for mining operators. |
| Regulatory Certification Pathway | EASA detect-and-avoid system certification unlocks automated German rail network inspection contracts. |
| Strategic Partnership | API middleware development with Esri reduces legacy GIS integration friction for construction firms. |
| Geographic Expansion | Seasonal elasticity pricing models capture Brazilian Mato Grosso soybean belt whitespace below 15% penetration. |
| Acquisition of Specialist Firm | Photogrammetry engine specialists with sub-centimeter ground sample distance algorithms anchor survey-grade outputs. |
Research Methodology
Desk research of FAA regulatory filings, EU U-space implementation documents, and SEC 10-K disclosures from publicly traded platform vendors preceded structured interviews with remote pilot training directors, construction procurement managers, precision farming operations leads, and photogrammetry software engineers. Primary fieldwork combined with secondary validation across customs data for drone component imports, EASA certification registries, and agricultural extension service adoption surveys. Bottom-up fleet deployment estimates and top-down software subscription revenue analysis were triangulated for segmentation calibration.
Assumptions held fixed include lithium-polymer battery energy density constraints, FAA Part 107 certification requirements, and EU U-space 2026 conformance deadlines; variables tested include Brazilian rural credit expansion velocity, German detect-and-avoid system certification timelines, and edge computing hardware cost curves. The analytical framework modeled deployment scale by end-user segment, processing intensity tier, and regional regulatory cluster across the projection horizon. CAGRs were derived from logistic diffusion curves fitted to precision farming adoption patterns and infrastructure inspection automation rates, with inputs including federal highway spending appropriations and soybean commodity price cycles.
Stress conditions across Brazilian currency volatility, EU U-space implementation delays, and NVIDIA semiconductor supply constraints were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions and risk factor weightings. Material shifts in FAA beyond-visual-line-of-sight permission timelines or German data sovereignty enforcement intensity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
UAV
Commercial Drone-Enabled Services Market
UAV
Drone Lens Market
UAV
Rc Helicopter Market
UAV
Electric Glider Market
UAV
UAV Payload Market
UAV
Aerial Smart Weapons Market
UAV
Drone Inspection Service Market
UAV
Drone Tracking Antenna Market
UAV
Drone Telematics Market
UAV
UAV Payload and Subsystems Market
UAV
North America Drone Software Market
UAV
UAV Market
UAV
Drone Identification System Market
UAV
UAV Sense-And-Avoid Systems Market
UAV
Nano Drones Market
UAV
Industrial Drones Market