
 Global Drone Services Market | 2026-2036
Global Drone Services Market Size, Share, and Industry Trends Forecast 2026-2036
Global Drone Services Market Analysis
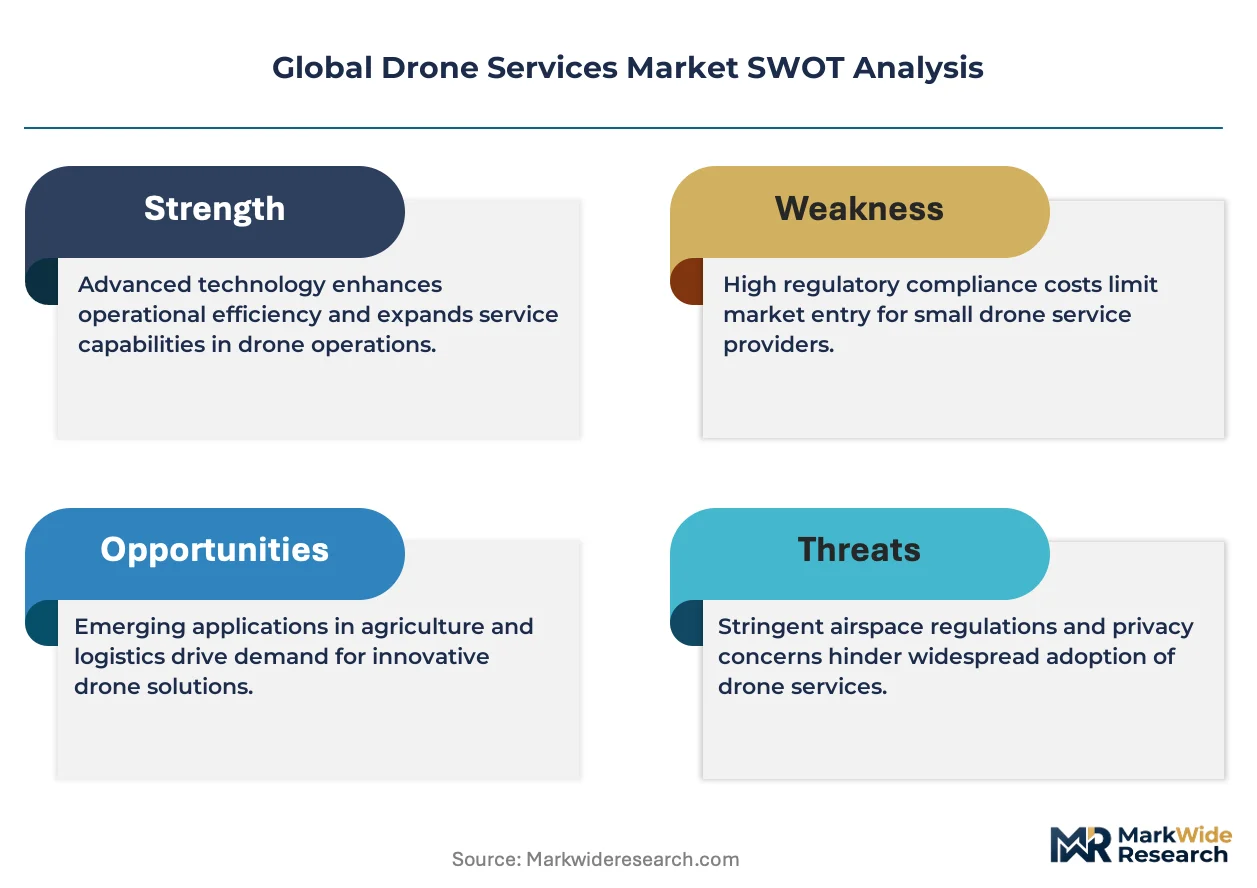
The capital-intensity divergence between fleet-owning operators and software-centric platforms is redrawing competitive boundaries in drone services. Aerodyne Group Limited leverages its asset-heavy model across energy and telecommunications infrastructure, sustaining regional dominance through localized maintenance hubs. DroneDeploy, Inc. competes purely through cloud-based analytics, anchoring its position with subscription revenue rather than aircraft depreciation.
Drone services encompass the commercial provision of unmanned aerial vehicle operations, data acquisition, and analytic deliverables performed by third-party providers rather than end users, typically utilizing platforms with sub-25-kilogram maximum takeoff weight and integrated multispectral or LiDAR sensor payloads. The primary purpose spans remote sensing, physical asset inspection, and autonomous cargo transport across industries requiring spatial data or aerial access without manned aviation economics. Inspection services command mature margin pools in oil and gas and power transmission verticals, while delivery services represent the fastest-growing application dimension as regulatory frameworks accommodate urban air mobility trials. Multi-rotor systems dominate current service revenue due to versatility and lower pilot training thresholds, though fixed-wing platforms retain structural advantages in large-area surveying and agricultural mapping where endurance exceeds two hours.
FAA Part 107 and the EU U-space regulatory framework govern operational certification and airspace integration across the two largest addressable markets, with EASA standards additionally shaping product design requirements for CE-marked unmanned systems. China's CAAC drone registration mandates and Brazil's ANAC remote pilot licensing rules illustrate how national aviation authorities are segmenting risk categories to accelerate commercial deployment without compromising manned aviation safety. Stakeholders must monitor evolving beyond-visual-line-of-sight waiver volumes and urban air mobility corridor designations as leading indicators of where serviceable addressable demand will materialize first.
Market Dynamics
The regulatory divergence between FAA Part 107 waivers and EU U-space implementation timelines is fragmenting service deployment schedules, forcing operators to maintain parallel compliance architectures while awaiting harmonized beyond-visual-line-of-sight standards.
Growth Catalysts
- BVLOS waiver expansion:FAA Part 107 exemption volumes for beyond-visual-line-of-sight operations are accelerating utility infrastructure inspection contracts across Texas and California transmission corridors.
- Variable-rate spraying adoption:Brazilian soybean operators are deploying multispectral-equipped fleets for precision agriculture, reducing chemical input costs through targeted application maps.
- Urban air mobility corridor designation:EU U-space framework development in Paris and Rome is enabling last-mile delivery pilot programs with dedicated low-altitude transit lanes.
Market Restraints
- Sensor payload cost volatility:LiDAR unit pricing fluctuates with semiconductor foundry capacity, compressing margins for surveying operators dependent on high-resolution terrain mapping.
- Pilot certification bottlenecks:FAA Part 107 practical examination wait times exceed eight weeks in metropolitan training centers, throttling fleet expansion velocity.
- Fixed-wing endurance limitations:Multi-rotor dominance in service revenue reflects structural barriers to large-area agricultural mapping where flight duration requirements exceed battery chemistry constraints.
Strategic Opportunities
- Indian agricultural underpenetration:Punjab and Haryana wheat belts lack commercial drone service density, presenting first-mover advantages for crop health monitoring subscription models.
- 5G network digital twin convergence:Telecommunications infrastructure operators are integrating drone-acquired LiDAR with network planning software, creating recurring data refresh contracts.
- Australian mining automation mandates:Site safety regulations in Western Australia are accelerating autonomous pit inspection deployments without on-ground personnel exposure.
Industry Challenges
- Maintenance technician scarcity:Localized repair hub staffing lags fleet growth in remote oil and gas inspection territories, extending aircraft downtime intervals.
- EU CE marking timeline compression:EASA design standard compliance for sub-25-kilogram platforms requires extended certification cycles, delaying new sensor payload integration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Drone Services Market |
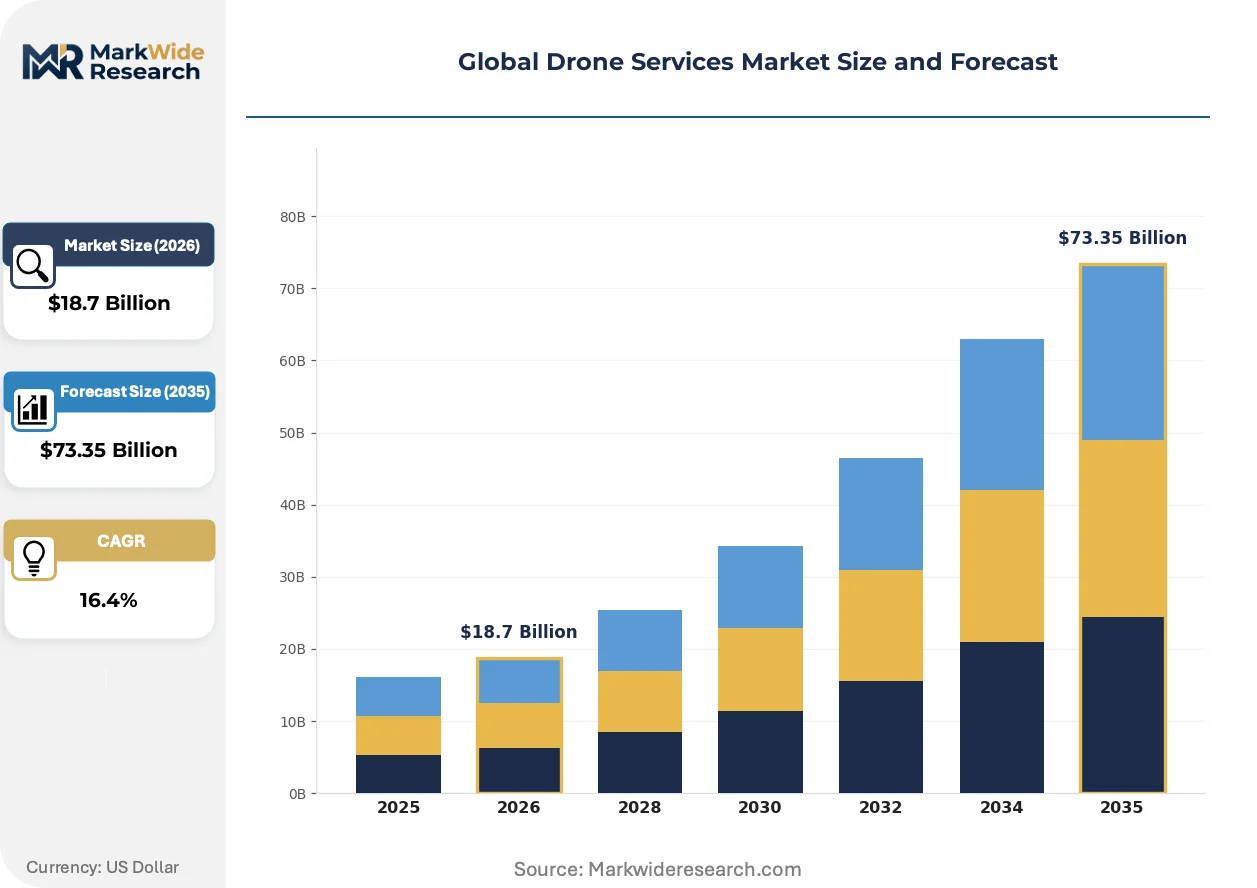
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $73.35 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Aerial Photography, Delivery Services, Surveying, Inspection Application: Agriculture, Construction, Logistics, Emergency Response End User: Agriculture Producers, Construction Companies, Government Agencies, Enterprises Technology: Fixed Wing, Multi-Rotor, Hybrid, Last-Mile Delivery |
| Companies Covered | Aerodyne Group Limited, Terra Drone Corporation, Cyberhawk Innovations Limited, DroneDeploy, Inc., Sky-Futures Ltd., PrecisionHawk, AgEagle Aerial Systems Inc., Zipline, Wing Aviation LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Drone Services Market Emerging Trajectories
Edge computing architectures are relocating analytic processing from ground stations to onboard hardware, compressing data delivery latency while reshaping cloud platform competitive positioning.
Artificial intelligence-based defect detection is decomposing traditional manual image review workflows in power transmission inspection. Duke Energy and Pacific Gas and Electric are deploying neural networks trained on insulator degradation patterns, reducing analyst headcount requirements while accelerating maintenance scheduling decisions. This capability compression is enabling fixed-price inspection contracts that undercut time-and-materials legacy pricing.
EU U-space regulatory framework implementation is mandating remote identification and geofencing capabilities for all commercial operations above 250 grams. EASA technical standards require broadcast module integration by January 2026, forcing fleet retrofit investments or accelerated replacement cycles. German and French operators are consolidating around compliant platform manufacturers to avoid airspace access restrictions.
Subscription-based data delivery is displacing per-flight pricing in agricultural verticals. Brazilian cotton cooperatives now demand season-long crop health dashboards with weekly refresh guarantees, transferring weather and flight scheduling risk to service providers. This model concentrates buyer power among large farming syndicates while squeezing smaller regional operators unable to guarantee fleet availability.
Global Drone Services Market Segmentation
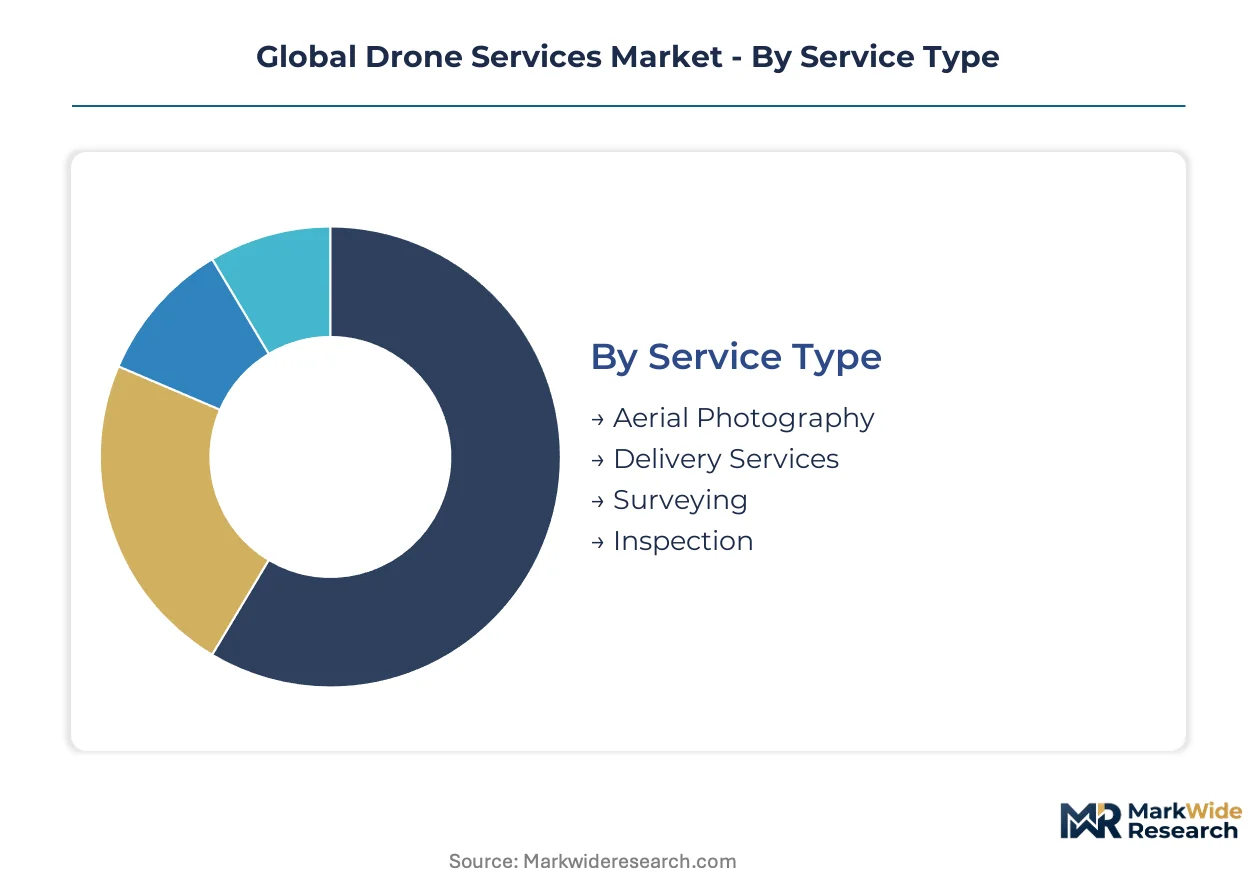
Service providers structure offerings around flight duration requirements, sensor payload specifications, and regulatory complexity tiers. Geographic deployment patterns vary sharply across segments, with inspection services clustering near industrial corridors while delivery trials concentrate in urban air mobility corridors.
Service Type:
Domestic demand dominates aerial photography and inspection, whereas delivery services require cross-border regulatory harmonization to achieve scale.
- Inspection:Oil and gas operators in Texas and California transmission corridors drive recurring contracts for thermal and visual asset assessment. FAA Part 107 waiver volumes for beyond-visual-line-of-sight operations are accelerating utility infrastructure deployment schedules.
- Delivery Services:Urban air mobility trials in Paris and Rome leverage dedicated low-altitude transit lanes under EU U-space frameworks. Last-mile cargo transport represents the steepest expansion trajectory as regulatory frameworks accommodate autonomous urban operations.
- Aerial Photography:Real estate marketing and event documentation sustain localized operator networks across metropolitan Australia.
- Surveying:Brazilian soybean belt operators deploy multispectral-equipped fleets for precision terrain mapping and boundary verification.
Inspection holds the largest share; momentum sits with delivery services.
Application:
Cost tier stratification separates capital-intensive agricultural fleets from asset-light emergency response deployments.
- Agriculture:Variable-rate spraying adoption in Brazil and Australia reduces chemical input costs through targeted application maps derived from multispectral crop health data. Brazilian cotton cooperatives now demand season-long dashboards with weekly refresh guarantees.
- Construction:Progress monitoring and earthwork volume calculations anchor recurring data refresh contracts with major infrastructure developers.
- Logistics:Warehouse inventory cycle counting and yard management applications are gaining share fastest among enterprise supply chain operators.
- Emergency Response:Search-and-rescue and post-disaster damage assessment rely on rapid-deployment multi-rotor systems with minimal pilot certification barriers.
Agriculture commands mature revenue pools; logistics is climbing the fastest.
End User:
Volume concentration sits with large farming syndicates and utility operators, while government procurement runs through structured tender processes.
- Agriculture Producers:Punjab and Haryana wheat belts in India lack commercial service density, presenting first-mover advantages for subscription-based crop health monitoring.
- Enterprises:Telecommunications infrastructure operators integrate drone-acquired LiDAR with 5G network planning software.
- Government Agencies:Western Australian mining safety regulations mandate autonomous pit inspection deployments without on-ground personnel exposure.
- Construction Companies:Earthwork contractors and commercial developers utilize progress documentation for milestone-based payment verification.
Agriculture producers represent the dominant customer base; enterprises are gaining share fastest.
Technology:
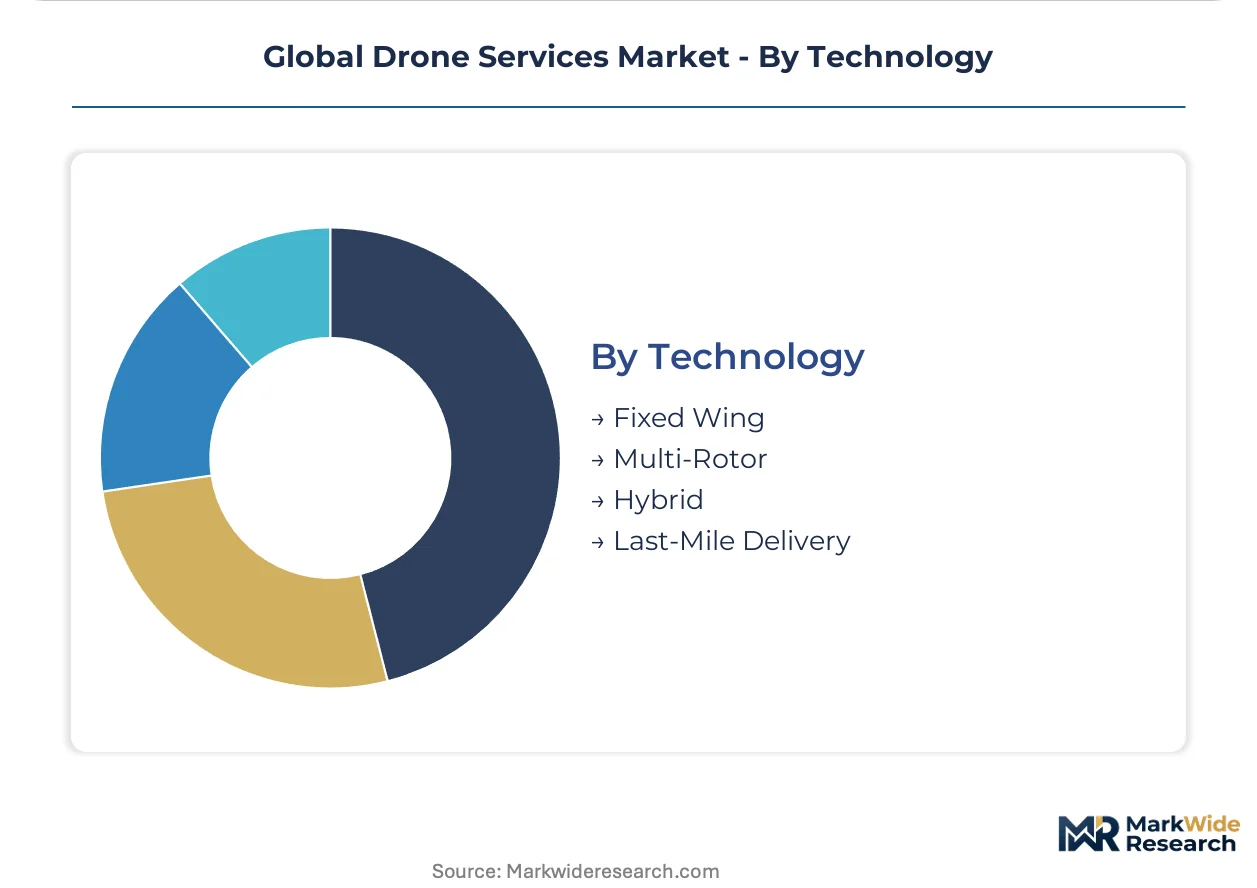
Supply concentration favors multi-rotor manufacturers serving inspection and photography, while hybrid platforms remain import-dependent for agricultural endurance applications.
- Multi-Rotor:Dominates current service revenue due to versatility and lower FAA Part 107 pilot training thresholds. Quad- and hexacopter configurations support sub-25-kilogram payloads with integrated multispectral or LiDAR sensors.
- Fixed Wing:Retains structural advantages in large-area surveying where flight duration requirements exceed two hours. Battery chemistry constraints limit multi-rotor competitiveness in agricultural mapping scale.
- Hybrid:Vertical takeoff and landing combined with fixed-wing endurance addresses regulatory constraints in remote inspection territories with limited runway access.
- Last-Mile Delivery:Purpose-built cargo drones with automated payload handling integrate with EU U-space remote identification and geofencing mandates.
Multi-rotor systems hold the largest share; hybrid platforms are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Service export intensity from established drone service markets is accelerating as regulatory harmonization lags behind commercial demand growth. Import dependence for specialized sensor payloads and compliant aircraft platforms is reshaping procurement patterns across emerging operational territories.
United States
Utility infrastructure inspection contracts across Texas and California transmission corridors are generating recurring revenue pools for fleet-owning operators. FAA Part 107 waiver volumes for beyond-visual-line-of-sight operations are accelerating deployment schedules without requiring full regulatory reform. Houston and Dallas-Fort Worth clusters concentrate energy sector service providers near downstream refining and midstream pipeline networks.
Brazil
Soybean belt operators in Mato Grosso and Goiás are deploying multispectral-equipped fleets for variable-rate spraying and crop health monitoring. ANAC remote pilot licensing rules segment risk categories to accelerate commercial deployment while preserving manned aviation safety protocols. São Paulo state anchors the national service provider ecosystem through proximity to agricultural financing and equipment distribution networks.
Germany
Industrial inspection demand from Ruhr Valley chemical complexes and Bavarian automotive manufacturing facilities sustains specialized operator networks. EASA design standards for CE-marked unmanned systems shape product requirements for sub-25-kilogram platforms entering EU markets. Frankfurt-Rhine-Main corridor operators are consolidating around compliant manufacturers to avoid U-space airspace access restrictions.
Australia
Western Australian mining safety regulations mandate autonomous pit inspection deployments without on-ground personnel exposure. CASA drone registration mandates enforce operational accountability across remote resource extraction territories. Perth and Kalgoorlie service hubs concentrate maintenance technician capacity for fly-in-fly-out inspection schedules.
India
Punjab and Haryana wheat belts lack commercial drone service density, presenting first-mover advantages for subscription-based crop health monitoring models. DGFT import regulations and PLI scheme incentives are reshaping domestic platform assembly and sensor payload availability. Karnataka and Telangana technology corridors are incubating software-centric analytics platforms for agricultural data interpretation.
Global Drone Services Market Vendor Landscape
Concentration sits with fleet-owning infrastructure specialists and asset-light software platforms rather than integrated manufacturing-service hybrids. The vendor base separates into three strategic archetypes: regional maintenance hub operators sustaining localized presence through aircraft availability guarantees, cloud-based analytics providers monetizing subscription data layers without hardware depreciation exposure, and purpose-built delivery specialists securing urban air mobility corridor access. Competitive moves center on sensor payload integration partnerships and geographic expansion through regulatory waiver accumulation rather than manufacturing scale.
Within the asset-heavy infrastructure tier, Aerodyne Group Limited and Terra Drone Corporation exemplify regional dominance through localized maintenance capacity and energy sector contract concentration. Cyberhawk Innovations Limited occupies a position among inspection specialists with oil and gas vertical focus. DroneDeploy, Inc. anchors the software-centric archetype through cloud-based analytics subscription models without fleet ownership exposure. Zipline and Wing Aviation LLC represent the purpose-built delivery vector with urban air mobility corridor access strategies.
| Leading Market Players |
|---|
| Aerodyne Group Limited |
| Terra Drone Corporation |
| Cyberhawk Innovations Limited |
| DroneDeploy, Inc. |
| Sky-Futures Ltd. |
| PrecisionHawk |
| AgEagle Aerial Systems Inc. |
| Zipline |
| Wing Aviation LLC |
| Others |
Supply Flow & Price Mechanics
Ninety-day sensor payload procurement cycles concentrate pricing power with LiDAR and multispectral module distributors in Germany and Japan, forcing fleet operators to absorb cost volatility or push through surcharges to utility and agricultural end users. This lead-time compression rewards operators with backward-integrated maintenance networks who can extend airframe lifecycles while competitors face accelerated replacement schedules.
Pricing Analysis
Configured-to-order pricing for BVLOS-capable platforms with integrated thermal and LiDAR sensors commands substantial premiums over standard visual-inspection packages. Subscription-based data delivery dominates agricultural verticals, while project-based contracting persists in oil and gas inspection where site complexity varies. Price differentiation hinges on FAA Part 107 waiver status and sensor resolution tiers. Pricing pressure stems from Brazilian and Australian fleet oversupply in commodity crop monitoring. Smallholder cooperatives exhibit acute price sensitivity; energy majors prioritize reliability guarantees over unit economics.
Supply Chain Analysis
Inventory cycles for sub-25-kilogram airframes and CE-marked avionics stretch across twelve-to-sixteen week horizons, tethering delivery schedules to Shenzhen and Taipei manufacturing clusters. Semiconductor foundry capacity constraints feed into flight controller and remote identification module availability. Single-source vulnerability concentrates in high-resolution LiDAR units from select German and Canadian suppliers. Distribution runs through regional maintenance hubs in Houston, São Paulo, and Perth that consolidate spare inventory for fly-in-fly-out inspection schedules.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified remote pilot availability lags fleet expansion velocity across every major operational territory, creating a binding constraint that separates scalable operators from stranded asset bases. This scarcity dynamic rewards early movers who secure training pipeline partnerships before regulatory waiver volumes accelerate further.
For Market Incumbents: Shield recurring revenue pools in Texas and California transmission corridors by deepening technician training pipelines and securing exclusive airspace access through municipal U-space partnerships. Consolidate around EASA-compliant platform manufacturers before CE marking deadlines force fleet retrofit investments. Vertical integration into localized repair hubs defends margin position against asset-light analytics competitors.
For New Entrants and Emerging Players: Lead with software-centric crop health dashboards targeting Punjab and Haryana wheat belts where commercial service density remains minimal. Subscription models with weekly refresh guarantees transfer weather and scheduling risk while concentrating buyer power among farming syndicates. Partner with Indian PLI scheme beneficiaries for domestic platform assembly to circumvent DGFT import friction.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-arbitrage play because BVLOS waiver accumulation and U-space corridor access constitute defensible moats that compound with operational scale. Target acquisition profiles emphasize fleet-owning operators with energy sector contract concentration and established maintenance hub networks. The signal to watch is FAA exemption volume acceleration in metropolitan utility corridors.
| Strategic Initiative | Industry Significance |
|---|---|
| BVLOS Waiver Accumulation | Secures airspace access for Texas and California transmission corridor contracts ahead of harmonized standards. |
| Sensor Payload Integration Partnership | Accelerates EASA compliance timelines while differentiating analytics offerings for 5G network digital twin applications. |
| Localized Maintenance Hub Expansion | Reduces aircraft downtime intervals in Western Australian mining territories with fly-in-fly-out inspection schedules. |
| Subscription Model Transition | Transfers weather and flight scheduling risk to providers while locking in Brazilian cotton cooperative demand. |
| Remote Pilot Training Pipeline | Addresses FAA Part 107 examination bottlenecks that throttle fleet expansion velocity in metropolitan centers. |
Methodological Framework
The analysis maps inspection, delivery, surveying, and agricultural application segments, each validated through primary interviews with fleet operations directors, FAA certification consultants, utility procurement managers, and agricultural cooperative technology officers. Secondary sources include EASA technical standard filings, ANAC remote pilot licensing records, FAA Part 107 waiver databases, and customs trade data for unmanned aircraft component flows. Bottom-up service provider capacity estimates triangulate against top-down addressable demand calculations across transmission corridor, mining, and precision agriculture verticals.
Consistency checks validate volume and value outputs against external benchmarks including utility infrastructure inspection contract disclosures, telecommunications network planning software integration announcements, and agricultural equipment financing records. Segmentation dimensions encompass service type, application vertical, end user archetype, and platform technology category across the projection horizon. CAGRs derive from fitted growth curves calibrated to regulatory waiver velocity, pilot certification throughput, and sensor payload cost trajectories. Forecast inputs incorporate EU U-space implementation timelines and Indian PLI scheme uptake rates.
Underlying assumptions cover sustained FAA and EASA regulatory momentum, with deviation risk concentrated in beyond-visual-line-of-sight standardization delays and semiconductor foundry capacity constraints affecting LiDAR availability. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
UAV
Small Drone Market
UAV
Bubble Drone Market
UAV
Asia-Pacific Drones Market
UAV
Latin America Small UAV Market
UAV
Miniature Drone Market
UAV
North America Drone Services Market
UAV
Drone Powered Business Solutions Market
UAV
Solar-Powered UAV Market
UAV
UAV Simulator Market
UAV
Drone Identification System Market
UAV
Middle-East and Africa Drones Market
UAV
UAV Navigation Systems Market
UAV
Fixed-Wing VTOL UAV Market
UAV
Rc Helicopter Market
UAV
Asia Pacific Small UAV Market
UAV
Counter-UAS Market