
 Drone Flight Controller System Market | 2026-2036
Drone Flight Controller System Market Size, Share, and Industry Trends Forecast 2026-2036
Drone Flight Controller System Market Analysis
The capital-intensity divergence between in-house semiconductor fabrication and outsourced controller assembly is unwinding competitive stability across the sector. DJI leverages captive chip design and manufacturing scale to dominate consumer and prosumer tiers. Skydio sustains advanced autonomy software development through defense contracting channels. Freefly Systems anchors its position in high-end cinematography with specialized stabilization firmware.
A drone flight controller system comprises embedded computing hardware, sensor fusion algorithms, and real-time control loops that process IMU data at frequencies exceeding 400 Hz to stabilize multirotor and fixed-wing platforms. Integrated Systems command premium positioning by bundling GPS, LiDAR, and vision-based processing on single boards, while Software Solutions attract agricultural and surveying end users seeking modular upgrades without hardware replacement. Hardware Kits retain share among defense and aerospace buyers requiring custom airframe integration.
The FAA's Part 107 framework and Remote ID final rule shape product compliance costs and market access timelines for US-bound manufacturers, while EASA's drone regulation framework and CE marking requirements govern European type certification. China's MIIT enforces GB standards on radio transmission modules that constrain export-ready controller designs. Stakeholders must monitor divergence between FAA, EASA, and MIIT cybersecurity mandates as these will determine which controller architectures achieve cross-border deployment eligibility.
Market Dynamics
Controller architecture is splitting between integrated system-on-chip designs for mass-market units and modular federated computing for defense-grade platforms, with certification requirements driving this hardware divergence.
Growth Catalysts
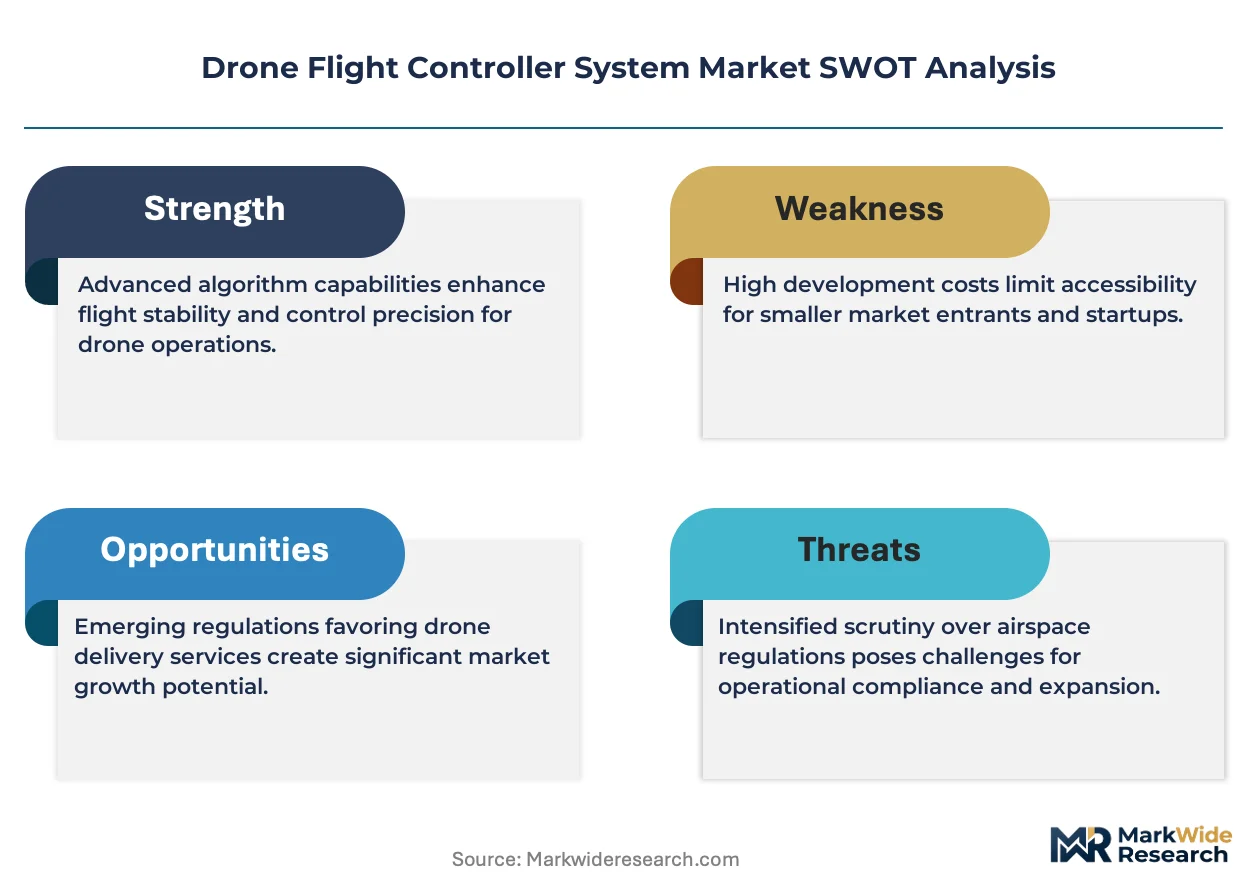
- Remote ID Mandates:FAA and EASA enforcement timelines are forcing fleet operators to upgrade legacy controllers, creating replacement demand across commercial operator bases in the US and Europe.
- Autonomous Spraying Adoption:Precision agriculture operators in Brazil are expanding drone fleet deployments for crop protection, driving controller volume through OEM partnerships with local agricultural equipment distributors.
- Sensor Fusion Advancement:Real-time integration of LiDAR, thermal imaging, and RTK-GPS at 400+ Hz processing rates is enabling new inspection applications in energy infrastructure and maritime logistics.
Market Restraints
- Semiconductor Supply Concentration:Captive chip fabrication capacity concentrates among Shenzhen-based vertically integrated manufacturers, constraining second-tier controller vendors' access to advanced process nodes.
- Radio Module Compliance Costs:China's MIIT GB standards on transmission modules require redesign cycles for export-bound controllers, extending product development timelines by 8-14 months.
- Pilot Skill Requirements:FAA Part 107 certification thresholds limit operator pool expansion, capping addressable market growth in commercial cinematography and real estate verticals.
Strategic Opportunities
- Defense Contracting Channels:Advanced autonomy software development funded through military R&D programs offers revenue stability independent of consumer market cyclicality.
- Modular Software Solutions:Agricultural end-users in Australia and Canada are adopting firmware-upgrade pathways that extend hardware lifecycles without full controller replacement.
- Cybersecurity Certification Pre-Positioning:Early alignment with diverging FAA, EASA, and MIIT cybersecurity mandates will determine which architectures achieve cross-border deployment eligibility.
Industry Challenges
- Embedded Systems Talent Scarcity:Real-time control loop engineering expertise concentrates among defense-aerospace talent pools, inflating compensation costs for commercial controller developers.
- Multi-Jurisdiction Certification Parallelism:Simultaneous pursuit of FAA, EASA, and MIIT type approvals fragments engineering resources and extends time-to-revenue for new platform launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drone Flight Controller System Market |
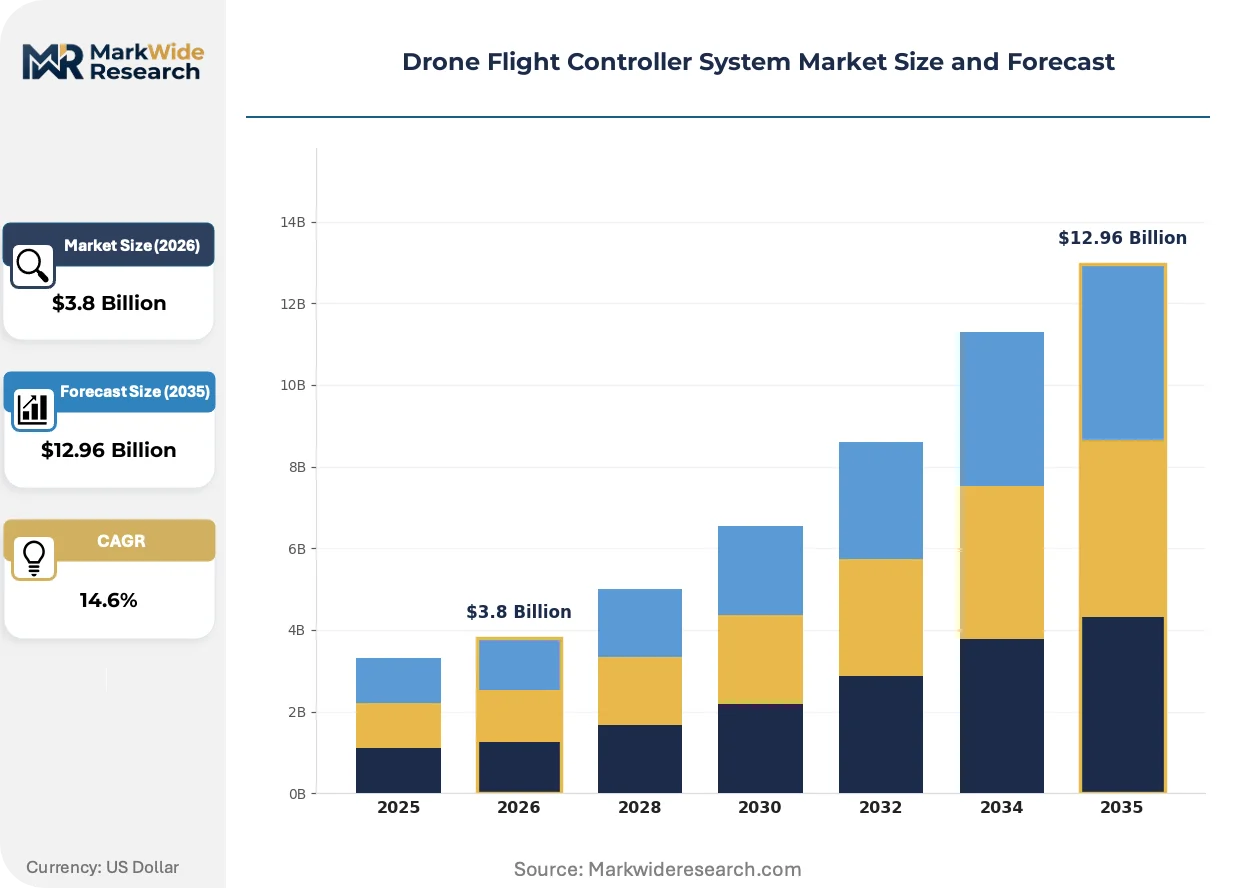
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.96 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone Controllers, Integrated Systems, Software Solutions, Hardware Kits Technology: GPS, IMU, LiDAR, Vision-based Systems End User: Aerospace, Agriculture, Defense, Surveying Application: Mapping, Surveillance, Delivery, Inspection |
| Companies Covered | Embention, Freefly Systems, DJI, ACSL, Parrot, Skydio, JOUAV, Draganfly, Autel Robotics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drone Flight Controller System Market Emerging Trajectories
Flight controller technology is splitting along performance tiers, with regulatory mandates and end-use specialization driving divergent hardware-software architectures rather than unified platform strategies.
Vision-based navigation stacks are bifurcating controller market structure. High-frame-rate stereo vision processing enables GPS-denied operation in urban canyons and indoor environments. Cinematography and infrastructure inspection operators are adopting these systems fastest. This capability compression is eliminating the price-performance gap between premium autopilot modules and mid-tier integrated controllers.
EASA's drone regulation framework and corresponding CE marking requirements are tightening hardware traceability obligations. Component-level documentation mandates now extend through firmware version control and sensor calibration chains. European commercial operators are responding by consolidating supplier relationships toward vertically integrated controller manufacturers with established notified body partnerships.
Service unbundling is altering controller procurement economics. Agricultural and surveying end-users are separating hardware acquisition from software licensing and maintenance contracts. Australian precision farming cooperatives now source flight controllers through equipment financing structures while subscribing to autonomy feature sets annually. This shift compresses upfront capital requirements but extends vendor revenue recognition timelines.
Drone Flight Controller System Market Segmentation
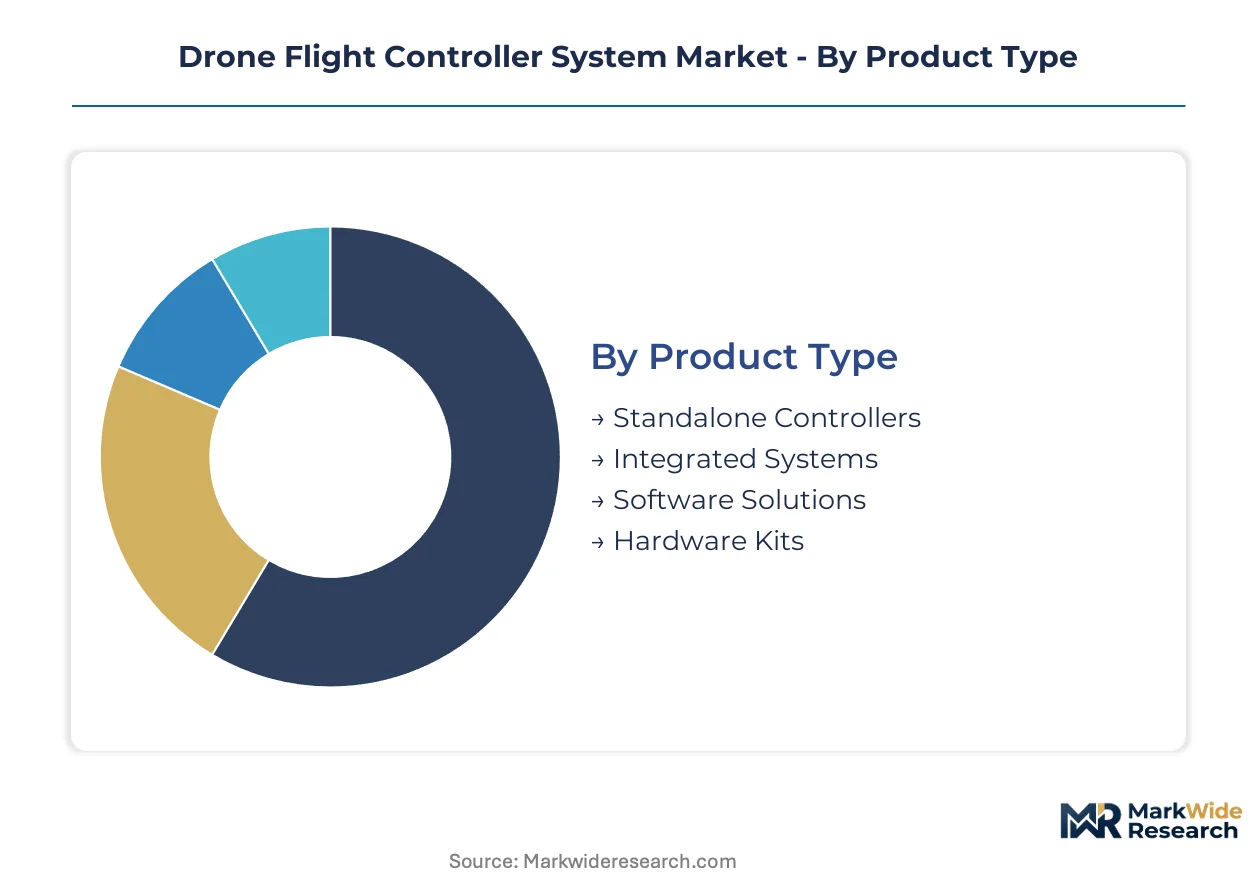
Flight controller procurement patterns diverge sharply between defense contractors seeking custom hardware integration and agricultural distributors pushing modular software upgrades. Understanding these channel dynamics reveals which architectures capture margin versus volume across the forecast window.
Product Type:
Integrated Systems and Software Solutions flow through OEM partnerships with agricultural equipment distributors, while Standalone Controllers and Hardware Kits reach defense contractors through direct technical sales channels.
- Integrated Systems:Single-board designs bundle GPS, LiDAR, and vision processing at 400+ Hz loop frequencies. Demand concentrates among precision agriculture operators in Brazil expanding autonomous spraying fleets, driven by OEM partnerships with local equipment distributors.
- Software Solutions:Modular firmware enables feature upgrades without hardware replacement. Australian and Canadian agricultural cooperatives are adopting subscription-based licensing through equipment financing structures, extending vendor revenue timelines.
- Standalone Controllers:Discrete processing units for custom airframe integration by defense contractors.
- Hardware Kits:Component-level assemblies for aerospace manufacturers requiring full traceability documentation.
By volume, Software Solutions leads. By growth pace, Integrated Systems is climbing the fastest.
Technology:
Cost tiering separates premium sensor fusion stacks from commodity positioning modules, with certification grade determining which technologies deploy in regulated airspace.
- Vision-based Systems:High-frame-rate stereo processing enables GPS-denied navigation in urban canyons and indoor environments. Cinematography operators in Los Angeles and infrastructure inspectors across German energy networks are adopting these capabilities fastest.
- LiDAR:Real-time point-cloud integration at 400+ Hz enables centimeter-precision altitude hold for maritime logistics and wind turbine inspection applications.
- GPS:Standard positioning module for open-sky commercial operations.
- IMU:Inertial measurement units providing baseline attitude stabilization across all price tiers.
By installed base, GPS dominates. By capability expansion, Vision-based Systems is gaining share fastest.
End User:
Application maturity varies by sector, with defense and agriculture commanding premium pricing while surveying standardizes on mid-tier configurations.
- Agriculture:Precision farming operators in Brazil, Australia, and Canada drive controller volume through seasonal fleet expansion cycles. Autonomous spraying adoption is accelerating replacement demand for legacy manual-flight hardware.
- Defense:Military R&D programs fund advanced autonomy software development, offering revenue stability independent of consumer market cyclicality. Custom integration requirements sustain Hardware Kit procurement.
- Aerospace:Commercial drone manufacturers seeking certified subsystems for type-approved platforms.
- Surveying:Geospatial service providers standardizing on RTK-GPS integrated controllers for cadastral and construction monitoring work.
By unit shipments, Agriculture leads. By margin capture, Defense is expanding most quickly.
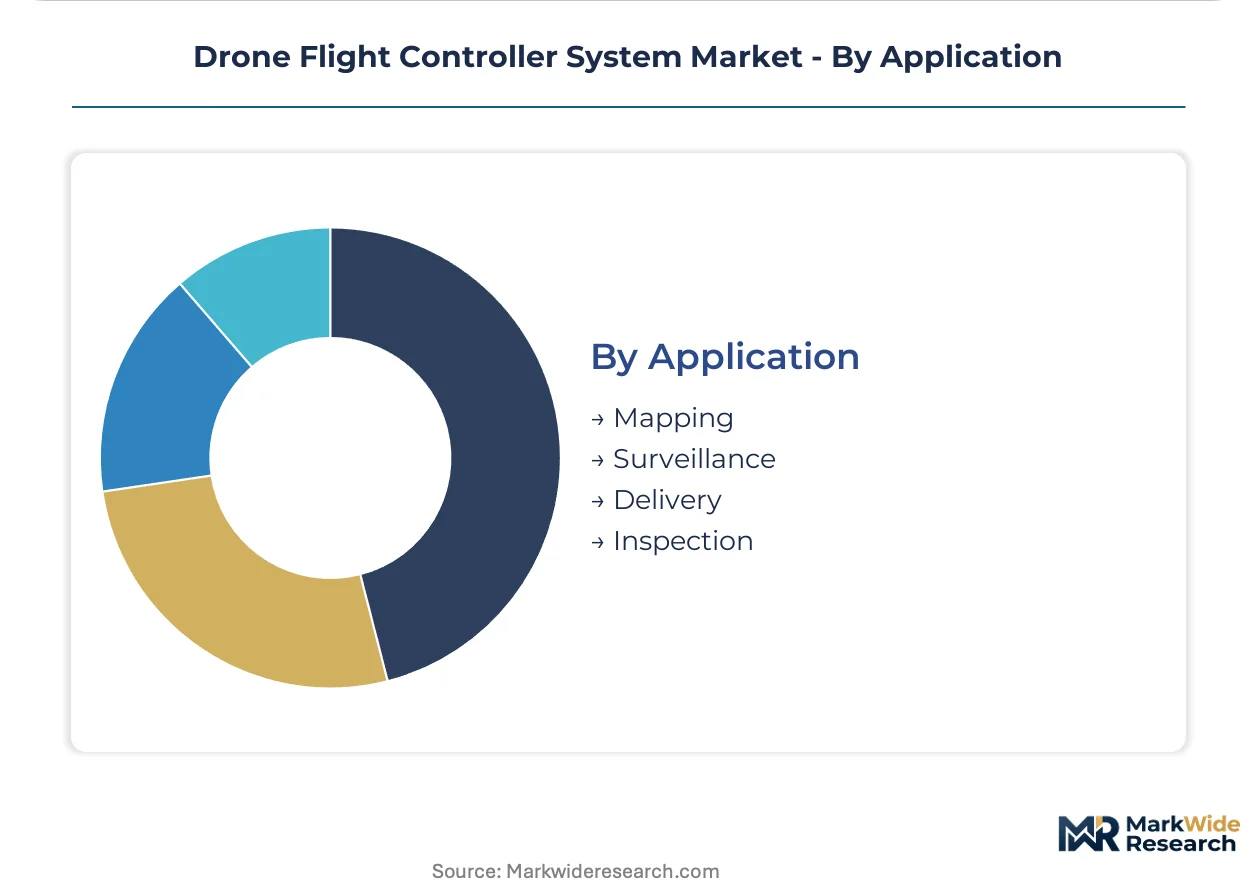
Application:
Geographic deployment patterns concentrate Inspection and Surveillance in regulated Western markets while Mapping and Delivery face airspace access constraints.
- Inspection:Energy infrastructure and maritime logistics operators across the US Gulf Coast and North Sea deploy LiDAR-integrated controllers for automated asset monitoring. FAA and EASA Beyond Visual Line of Sight waivers are tightening hardware certification requirements.
- Surveillance:Security and border control applications in the US and Saudi Arabia drive demand for encrypted datalink controllers with hardened cybersecurity architectures.
- Mapping:Surveying contractors in Australia and Canada utilizing RTK-corrected photogrammetry for mining and construction projects.
- Delivery:Last-mile logistics trials constrained by urban airspace congestion and Remote ID compliance timelines in US and European cities.
By current deployment scale, Inspection leads. By regulatory enablement trajectory, Surveillance shows the steepest expansion path.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazilian agricultural buyers exhibit the highest price elasticity in controller procurement, while defense contractors in the United States and Germany absorb substantial premiums for hardened architectures. China's vertically integrated manufacturers capture margin through captive semiconductor fabrication.
United States
Defense contractors and cinematography studios drive differentiated demand tiers. FAA Remote ID mandates and Part 107 certification frameworks force fleet operator hardware refresh cycles. Los Angeles anchors commercial production while defense procurement concentrates around Washington DC corridor and Texas aerospace clusters.
Germany
Industrial inspection operators across the Ruhr energy corridor and Bavarian manufacturing zones prioritize LiDAR-integrated controllers. EASA drone regulation framework and CE marking requirements tighten component traceability obligations. Munich and Stuttgart host system integrators serving German and Austrian cross-border operators.
China
Mass-market manufacturing scale and captive chip fabrication define competitive positioning. MIIT GB standards on radio transmission modules constrain export-ready designs. Shenzhen's Guangdong province concentrates vertically integrated controller production serving domestic and Southeast Asian agricultural drone OEMs.
Brazil
Precision agriculture operators in Mato Grosso and São Paulo states expand autonomous spraying fleet purchases most aggressively. ANVISA agrochemical application regulations intersect with DECEA airspace coordination requirements. Campinas and Ribeirão Preto host distributor partnerships linking Asian controller manufacturers to local equipment financing networks.
Australia
Surveying cooperatives and mining logistics operators adopt modular software licensing to extend hardware lifecycles. CASA regulations on Beyond Visual Line of Sight operations shape controller capability requirements. Perth and Brisbane concentrate energy infrastructure inspection demand while Victorian agricultural zones drive seasonal replacement cycles.
Drone Flight Controller System Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with captive semiconductor fabrication separating the two groups. Shenzhen-based manufacturers leverage in-house chip design to dominate volume tiers, while defense-focused developers sustain premium positioning through military R&D channels. Three archetypes define the field: vertically integrated mass-market suppliers, defense-contracting autonomy specialists, and cinematography stabilization experts. Competitive moves concentrate on strategic partnerships with agricultural equipment distributors and early cybersecurity certification alignment across FAA, EASA, and MIIT frameworks.
Within the integrated manufacturing tier, DJI exemplifies captive supply chain dominance, while Skydio occupies a position representing defense-funded autonomy development. Freefly Systems anchors the high-end cinematography specialization archetype.
| Leading Market Players |
|---|
| Embention |
| Freefly Systems |
| DJI |
| ACSL |
| Parrot |
| Skydio |
| JOUAV |
| Draganfly |
| Autel Robotics |
| Others |
Supply Flow & Price Mechanics
Semiconductor process node migration from legacy 28nm to advanced 7nm fabrication is simultaneously redrawing supply geography toward Shenzhen and compressing controller ASPs for mid-tier agricultural OEMs. This substitution dynamic concentrates pricing power among captive foundry operators while forcing second-tier vendors toward modular software licensing to preserve margin.
Pricing Analysis
After-sales firmware subscriptions and annual maintenance contracts now drive lifetime value capture across precision agriculture deployments. Three-tier pricing structure across premium, standard, and economy levels separates defense-grade hardened controllers from prosumer integrated boards and commodity GPS modules. Cost compression in the standard tier is intensifying because Brazilian equipment distributors demand volume discounts for fleet purchases. Agricultural cooperatives in Australia exhibit highest price sensitivity, while German energy infrastructure operators absorb premium LiDAR-integrated configurations without elasticity.
Supply Chain Analysis
TSMC wafer allocation bottlenecks in Taiwan constrain advanced controller SoC availability for non-captive vendors. Shenzhen, South Korea, and Japan concentrate semiconductor fabrication and MEMS sensor production. Raw material dependencies span silicon wafers, gallium arsenide RF components, and rare-earth magnet motors. Single-source vulnerability in 7nm foundry capacity exposes second-tier controller developers to allocation priority shifts. Distribution runs through agricultural equipment financing networks in Brazil and direct technical sales channels for defense contractors in the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against software-defined controller substitution, where modular firmware providers displace integrated hardware vendors in agricultural and surveying verticals.
For Market Incumbents: Compound certification advantages by accelerating FAA, EASA, and MIIT cybersecurity pre-approval timelines before divergence hardens. Deepen backward integration into MEMS sensor packaging to offset foundry allocation risk. Lock agricultural distributor relationships through equipment financing partnerships in Brazil and Australia to forestall modular software entrants. For New Entrants and Emerging Players: Firmware-upgrade service gaps in Australian and Canadian precision farming cooperatives offer white-space entry without competing against Shenzhen manufacturing scale. Target mid-tier cinematography operators in Los Angeles seeking GPS-denied vision navigation at prosumer price points. Pursue OEM co-development agreements with regional agricultural equipment distributors rather than direct hardware sales. For Investors and Strategic Acquirers: Capital is best deployed toward defense-contracting autonomy specialists with established military R&D revenue streams and export-controlled technology barriers. Long-term viability across the analysis window favors architectures capable of cross-border deployment under diverging FAA-EASA-MIIT cybersecurity mandates. Monitor EASA CE marking timeline acceleration as inflection indicator for European market access consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Cybersecurity Certification Pre-Positioning | Early alignment with FAA, EASA, and MIIT mandates determines cross-border deployment eligibility. |
| Backward Integration into MEMS Sensors | In-house sensor packaging reduces dependency on Shenzhen-based component suppliers. |
| Equipment Financing Partnership | Brazilian distributor alliances compress customer upfront capital requirements and extend revenue recognition. |
| Defense R&D Contracting Channel | Military autonomy funding provides revenue stability independent of consumer market cyclicality. |
| Modular Firmware Platform Launch | Subscription licensing extends hardware lifecycles for Australian agricultural cooperatives. |
Methodological Framework
Desk research of FAA regulatory filings, EASA type certification databases, and MIIT GB standard publications preceded structured interviews with flight controller hardware engineers, agricultural equipment procurement managers, defense autonomy program officers, and precision farming cooperative operators. Primary fieldwork across Shenzhen manufacturing clusters, Campinas distributor networks, and Stuttgart system integrators was cross-validated against customs trade records and semiconductor foundry utilization disclosures. Bottom-up controller shipment estimates and top-down OEM revenue triangulation anchored market sizing.
Variance decomposition across product type, technology tier, end-use vertical, and geographic regulatory cluster shaped the analytical framework. CAGRs were derived from segment-level growth rate reconciliation against aggregate market expansion. Modeled inputs included Remote ID mandate enforcement timelines, autonomous spraying fleet expansion rates in Brazil, and defense R&D program funding trajectories.
Underlying assumptions cover sustained FAA-EASA regulatory divergence, stable semiconductor foundry allocation priorities, and Brazilian agricultural credit availability, with deviation risk concentrated in cybersecurity mandate synchronization and China export control expansion. Practitioners should keep alternative scenarios live as cross-border certification reciprocity frameworks evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
UAV
UAV Payload Market
UAV
Enterprise Drone Management Solutions Market
UAV
Drone Tracking Antenna Market
UAV
Home Security Drone Market
UAV
Europe Commercial Drones Market
UAV
UAV Drones Market
UAV
Global Drone Sensor Market
UAV
UAV Payload and Subsystems Market
UAV
Middle-East and Africa Drones Market
UAV
Drone Roof Inspection Market
UAV
Ultra-Long Endurance Drone Market
UAV
Fixed Wing Military Drones Market
UAV
Aerial Smart Weapons Market
UAV
Europe Drones Market
UAV
Rotary Blade UAV Drones Market
UAV
Global VTOL UAV Market