
 Asia-Pacific Tethered Drone Market | 2026-2036
Asia-Pacific Tethered Drone Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Tethered Drone Market Insights
A shortage of certified UAV maintenance technicians is collapsing deployment timelines for defense and emergency services operators across the region. Elistair Sas leverages its proprietary micro-tether technology to sustain premium positioning in persistent surveillance applications. Mistral Solutions Pvt. Ltd. anchors its competitive stance through deep integration with Indian defense procurement channels. Skyshot Pte Ltd differentiates by dominating urban deployment configurations across Southeast Asian smart city programs.
Tethered drones are unmanned aerial systems physically connected to a ground station via a reinforced fiber-optic or power-conducting cable, enabling indefinite flight endurance with continuous data transmission and electrical supply. The cable typically spans 50–400 meters depending on operational altitude requirements, with fiber-optic cores supporting real-time high-bandwidth sensor feeds. Military end users currently occupy the largest revenue pool given sustained border surveillance and base perimeter monitoring contracts. Electric technology leads deployment volumes due to lower acoustic signatures and simplified logistics, though hybrid systems are gaining traction where extended payload capacity matters. Surveillance applications generate the densest margin concentration owing to integration complexity and recurring software licensing structures.
Japan's METI enforces radio equipment certification standards that tethered drone manufacturers must satisfy for domestic commercial deployment. India's DGFT export-import classifications and CEA electrical safety mandates shape product configuration requirements for equipment entering government tenders. Australia's CASA operational framework governs beyond-visual-line-of-sight permissions that directly determine viable use cases in offshore energy and rural firefighting. Stakeholders must weigh regulatory divergence against platform standardization economics when configuring regional product portfolios.
Market Dynamics
Defense procurement channels across Southeast Asia are consolidating vendor qualification requirements, compressing supplier lists and privileging platforms with pre-certified electromagnetic compatibility and indigenous data sovereignty architectures.
Growth Catalysts
- India's CEA Electrical Safety Mandates:Stringent certification requirements for grid-connected aerial systems are filtering out uncertified imports and creating protected demand corridors for compliant domestic assemblers.
- Border Infrastructure Modernization:Persistent aerial surveillance requirements along contested Himalayan and maritime boundaries are generating multi-year procurement frameworks with built-in technology refresh clauses.
- Fiber-Optic Tether Materials:Advances in tensile-strength-to-weight ratios for optical power-composite cables are extending operational ceilings beyond 300 meters while maintaining real-time data throughput.
Market Restraints
- Copper and Optical Fiber Input Volatility:Raw material cost swings for tether conductor cores are compressing gross margins for hardware manufacturers locked into fixed-price government tenders.
- Certified Technician Scarcity:The shortage of DGCA-authorized maintenance personnel in India and CASA-certified operators in Australia is extending deployment lead times by four to eight weeks.
- Radio Frequency Interference Constraints:Dense urban electromagnetic environments in Tokyo, Seoul, and Singapore are limiting viable operating zones for non-shielded control links.
Strategic Opportunities
- Philippines Maritime Patrol Expansion:Archipelagic territorial enforcement requirements across the Sulu and Celebes Seas are creating demand for shipborne tethered systems with salt-corrosion-resistant architectures.
- Japan's METI Energy Efficiency Directives:Carbon-neutral procurement preferences are accelerating electric propulsion adoption and creating subsidy-accessible retrofit markets for legacy diesel-hybrid platforms.
- Smart City Integration Partnerships:Municipal data fusion requirements in Bangkok, Jakarta, and Ho Chi Minh City are opening recurring-revenue service contracts for traffic and crowd monitoring deployments.
Industry Challenges
- Cross-Border Certification Fragmentation:Divergent electromagnetic compatibility testing protocols between Australia's RCM marking, Japan's TELEC certification, and India's BIS registration are forcing redundant engineering cycles.
- Legacy Defense Procurement Inertia:Established tender processes favoring rotor-wing manned helicopters are delaying unmanned platform adoption despite superior endurance economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Tethered Drone Market |
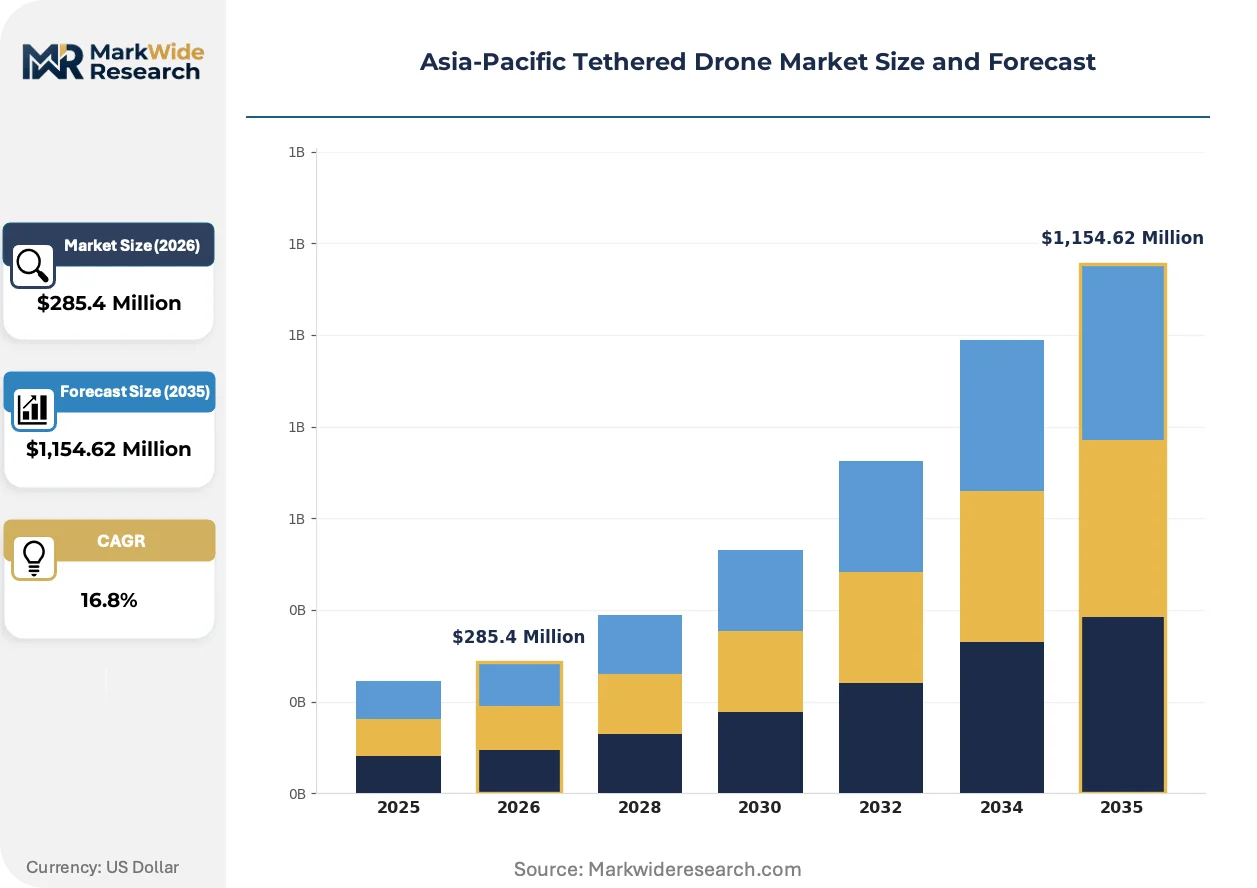
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $1,154.62 Million |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Surveillance, Security, Communication, Weather Monitoring End User: Military, Government, Commercial, Emergency Services Deployment: Onshore, Offshore, Urban, Rural Technology: Electric, Hybrid, Fuel Cell, Others |
| Companies Covered | Sky Sapience Ltd., Elistair Sas, Yuneec International Co. Ltd, Flyfocus sp. z o.o, Exail Technologies, Mistral Solutions Pvt. Ltd., Hoverfly Technology Inc., Novadem, Skyshot Pte Ltd, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Tethered Drone Market Trends and Innovations
Platform architecture decisions are pivoting toward modular payload interfaces and open-source ground control software, enabling rapid reconfiguration across surveillance, communications relay, and environmental monitoring missions without airframe redesign.
Silicon carbide power electronics is supplanting traditional silicon-based motor controllers in electric propulsion systems. Japanese and South Korean defense integrators are specifying these components for reduced thermal signature and extended duty cycles. The shift is compressing supplier margins on legacy controller architectures while opening premium pricing tiers for wide-bandgap semiconductor integration.
Japan's METI radio equipment certification standards now mandate interference resilience testing for tethered drones operating in shared spectrum bands. Manufacturers must demonstrate coexistence with existing cellular and broadcast infrastructure. Commercial deployment timelines in Japanese urban centers are extending by three to six months as vendors recertify platforms under the revised technical conformity assessment procedures.
Buyer organizations are unbundling hardware acquisition from persistent service contracts. Australian offshore energy operators and Indian paramilitary units are separating capital equipment purchases from multi-year maintenance and software licensing agreements. This bifurcation is most visible in Australia's Pilbara region and India's northeastern border infrastructure projects, where operators prioritize operational expenditure flexibility over upfront platform ownership.
Asia-Pacific Tethered Drone Market Segmentation
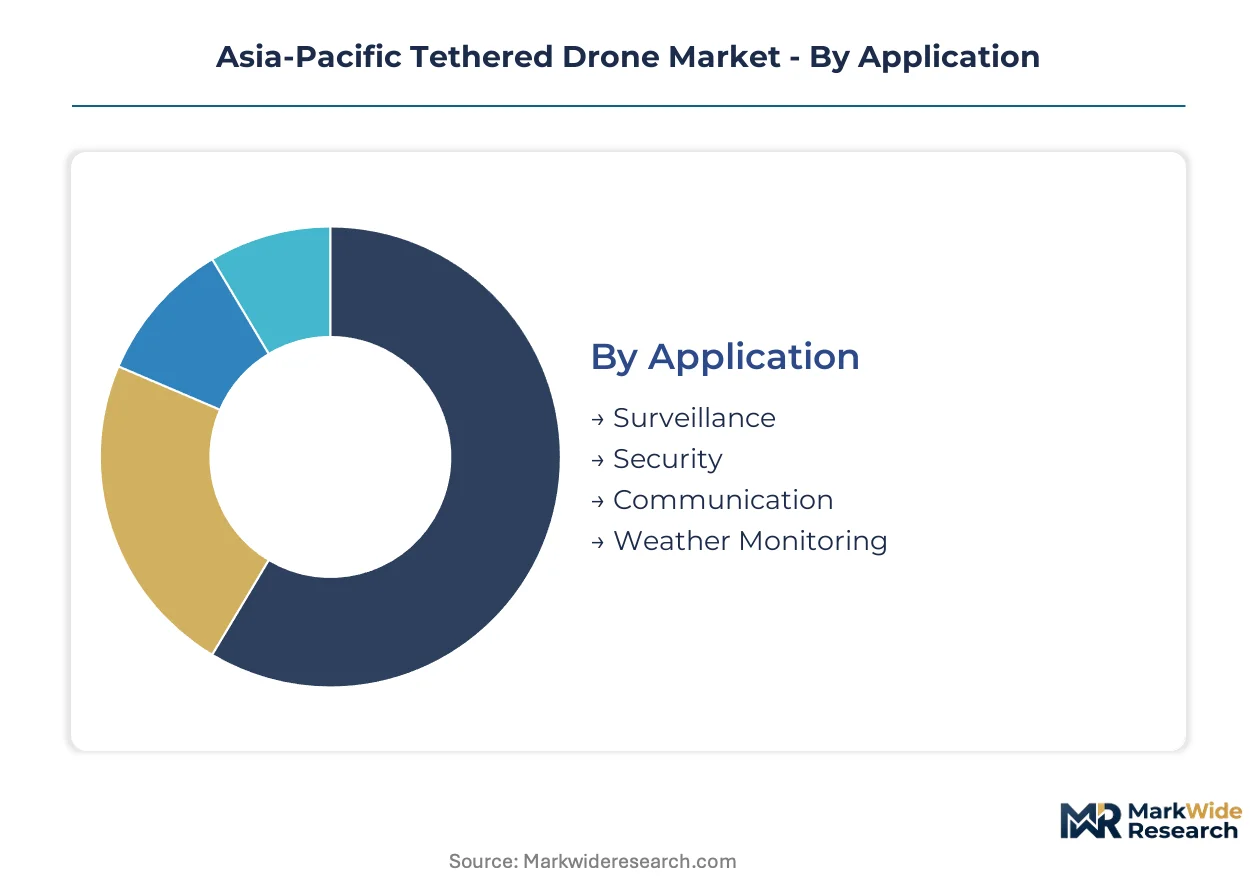
Tethered drone procurement patterns diverge sharply across operational contexts, with defense and energy operators prioritizing endurance specifications while municipal buyers emphasize rapid deployment logistics. Understanding these segment boundaries clarifies where technology investments concentrate and which certification requirements dominate vendor selection.
Application:
Margin pools concentrate in applications requiring complex sensor fusion and recurring software licensing rather than hardware-only deployments.
- Surveillance:Persistent aerial observation systems integrate electro-optical, infrared, and signals intelligence payloads through fiber-optic tether links. Border security infrastructure across India's Himalayan frontier and Australia's northern maritime approaches generates sustained demand for platforms with multi-spectral imaging and real-time data streaming capabilities.
- Security:Perimeter monitoring and event protection deployments leverage rapid-setup tethered systems for crowd analytics and access control. Smart city programs in Bangkok and Jakarta are specifying these configurations for traffic flow optimization and public safety coordination.
- Communication:Aerial relay platforms extend cellular and tactical radio coverage in disaster-affected or remote terrain. Compact form factors suit emergency response teams requiring immediate network restoration.
- Weather Monitoring:Atmospheric sampling payloads measure temperature, humidity, and particulate concentrations at altitude gradients. Research institutions and agricultural operators deploy these for localized meteorological modeling.
The dominant share belongs to Surveillance, while Communication is closing the gap fastest as disaster resilience budgets expand across archipelagic Southeast Asia.
End User:
Procurement scale and contract duration vary dramatically by buyer type, with military tenders spanning five-to-seven year frameworks against annual municipal renewals.
- Military:Defense ministries specify electromagnetic-hardened platforms with indigenous data sovereignty architectures for base perimeter and forward operating post monitoring. Australia's CASA beyond-visual-line-of-sight permissions and India's CEA electrical safety mandates shape technical compliance requirements.
- Government:Civil infrastructure agencies deploy tethered systems for border management, environmental enforcement, and critical facility protection. Japan's METI radio equipment certification standards filter vendor qualification lists for domestic procurement channels.
- Commercial:Energy, construction, and media sectors adopt leased-service models prioritizing operational expenditure flexibility over capital ownership. Offshore operators in Australia's Pilbara region favor unbundled hardware and maintenance agreements.
- Emergency Services:Firefighting and search-and-rescue units require rapid-deployment systems with simplified operator interfaces. Rural brigades across Australia's bushfire-prone regions and India's northeastern states are expanding aerial observation capabilities.
Military contracts command the largest revenue concentration, though Commercial adoption is expanding most quickly as energy operators retrofit legacy inspection workflows.
Deployment:
Environmental exposure severity determines material specifications and maintenance intervals more than altitude requirements alone.
- Onshore:Fixed installations at military installations, critical infrastructure sites, and research stations prioritize reliability metrics and minimal ground crew requirements. Salt-corrosion-resistant architectures are becoming standard even for coastal land-based positions.
- Offshore:Shipborne and platform-mounted systems face combined salt spray, vibration, and space constraints. The Philippines' maritime patrol expansion across the Sulu and Celebes Seas is generating demand for compact, rapidly stowable configurations.
- Urban:Dense electromagnetic environments in Tokyo, Seoul, and Singapore demand shielded control links and interference-resilient designs. METI certification timelines extend deployment schedules by three to six months.
- Rural:Extended logistics chains and limited technical support infrastructure favor simplified mechanical designs with field-replaceable components. India's DGCA-authorized technician shortage extends rural deployment lead times significantly.
Onshore installations retain the largest installed base, while Offshore applications are gaining share fastest as archipelagic territorial enforcement requirements intensify.
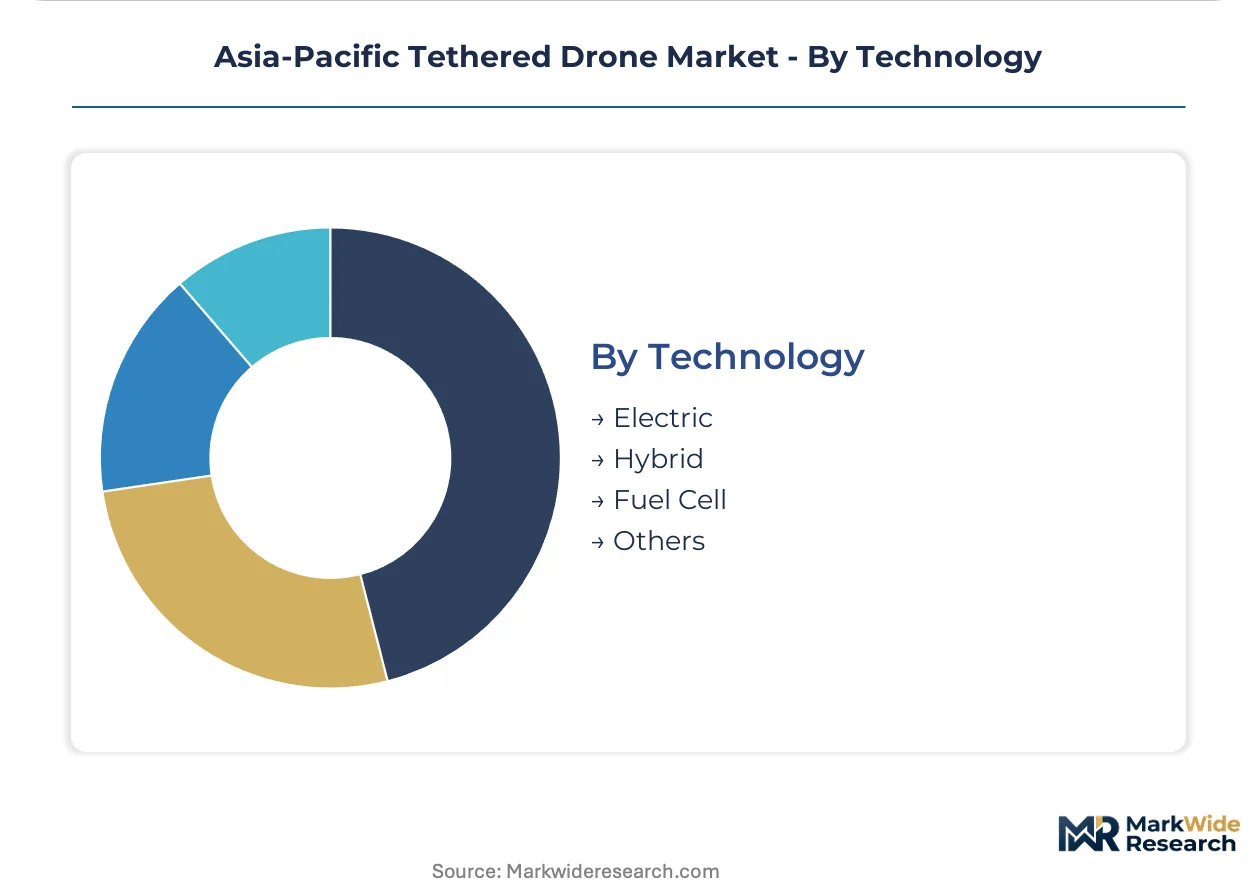
Technology:
Power system selection trades acoustic signature against payload capacity and endurance, with regulatory carbon mandates accelerating electric platform preference.
- Electric:Battery-powered propulsion with ground-station electrical supply through power-conducting tethers enables indefinite flight with minimal thermal and acoustic signatures. Japan's METI energy efficiency directives and China's dual carbon goals are filtering procurement specifications toward zero-emission platforms.
- Hybrid:Combined battery and combustion systems extend payload lift capacity for heavy sensor packages and adverse weather operations. Legacy diesel-hybrid platforms face retrofit pressure as subsidy-accessible electric alternatives mature.
- Fuel Cell:Hydrogen proton-exchange-membrane systems offer extended endurance without combustion noise, though ground logistics complexity limits current deployment. South Korean defense integrators are specifying these for reduced thermal signature requirements.
- Others:Emerging power architectures including tethered solar augmentation and wireless power transmission remain experimental, with limited operational certification.
Electric systems dominate current deployment volumes, while Hybrid configurations are climbing the fastest as operators seek payload flexibility without full platform replacement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's MIIT equipment certification standards anchor procurement specifications across the Asia-Pacific tethered drone landscape, filtering vendor qualification lists and shaping platform configuration requirements for defense and commercial operators throughout the region.
China
Dual carbon goals and border surveillance modernization along the Himalayan frontier are driving electric propulsion adoption. MIIT radio transmission equipment regulations mandate electromagnetic compatibility testing for urban deployment. Shenzhen and Chengdu industrial clusters concentrate domestic platform assembly for government tender channels.
Japan
METI energy efficiency directives are accelerating zero-emission platform procurement across smart city programs. Revised radio equipment certification standards now require interference resilience testing in shared spectrum bands. Tokyo and Osaka metropolitan areas are extending commercial deployment timelines by three to six months during recertification cycles.
India
CEA electrical safety mandates and DGFT export-import classifications are filtering uncertified imports from government tenders. Himalayan border infrastructure projects and northeastern maritime surveillance requirements are generating multi-year procurement frameworks. Bengaluru and Hyderabad defense technology corridors are anchoring domestic assembly capacity for compliant systems.
Australia
CASA beyond-visual-line-of-sight permissions are determining viable use cases across offshore energy and rural firefighting operations. The Pilbara region's iron ore operators are unbundling hardware acquisition from multi-year maintenance agreements. Perth and Brisbane are concentrating shipborne system integration for maritime patrol requirements.
South Korea
Defense integrators are specifying silicon carbide power electronics for reduced thermal signatures in extended duty cycles. MFDS equipment safety frameworks and national carbon neutrality targets are shaping procurement specifications. Seoul and Busan industrial zones are concentrating wide-bandgap semiconductor integration for next-generation platforms.
Asia-Pacific Tethered Drone Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the Asia-Pacific tethered drone market. European specialists with proprietary tether systems occupy premium positioning in persistent surveillance applications, while Asia-based integrators leverage defense procurement channel relationships and domestic certification advantages. The competitive landscape fragments across three strategic archetypes: micro-tether technology specialists, defense channel-anchored integrators, and urban deployment configuration leaders. Consolidation pressures are intensifying through electromagnetic compatibility pre-certification requirements and indigenous data sovereignty mandates.
Among the technology specialists, Elistair Sas exemplifies the proprietary micro-tether archetype, while Mistral Solutions Pvt. Ltd. occupies a position within the defense channel-integrated tier. Skyshot Pte Ltd represents the urban deployment configuration specialist archetype, anchoring smart city integration partnerships across Southeast Asian municipal programs.
| Leading Market Players |
|---|
| Sky Sapience Ltd. |
| Elistair Sas |
| Yuneec International Co. Ltd |
| Flyfocus sp. z o.o |
| Exail Technologies |
| Mistral Solutions Pvt. Ltd. |
| Hoverfly Technology Inc. |
| Novadem |
| Skyshot Pte Ltd |
| Others |
Pricing and Supply Chain Analysis
Silicon carbide power electronics displacing silicon-based motor controllers simultaneously redraws component sourcing maps toward Japanese and South Korean semiconductor fabs and compresses legacy controller pricing power. This substitution dynamic concentrates premium tier margins around wide-bandgap semiconductor integration while forcing cost discipline on conventional architectures.
Pricing Analysis
Geographic price spreads between Japanese METI-certified platforms and uncertified imports span three performance tiers. Pricing stratifies across electromagnetic-hardened defense specifications, interference-resilient urban configurations, and basic commercial surveillance packages. Cost compression in the commercial tier intensifies because Australian and Indian energy operators unbundle hardware from service contracts. Government buyers in India's defense procurement channels show lowest price sensitivity, while municipal smart city programs in Southeast Asia prioritize operational expenditure flexibility.
Supply Chain Analysis
China and Japan anchor fiber-optic tether cable production, with Shenzhen and Chengdu industrial clusters concentrating domestic platform assembly. Manufacturing draws from copper conductor stock, optical fiber cores, and silicon carbide wafers as critical inputs. Single-source vulnerability around certified electromagnetic compatibility testing laboratories creates procurement bottlenecks for vendors seeking multi-country approvals. Distribution runs through defense procurement channels, direct municipal contracting, and leased-service arrangements with offshore energy operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific tethered drone market rewards specialized capabilities that remain scarce across electromagnetic compatibility certification, fiber-optic tether engineering, and DGCA-authorized maintenance networks. Organizations possessing these assets command disproportionate positioning in procurement channels that filter for pre-certified platforms.
For Market Incumbents: Compound certification advantages by securing indigenous data sovereignty architectures ahead of Southeast Asian defense procurement consolidation. Pre-certify platforms under Japan's revised METI interference resilience standards and Australia's CASA beyond-visual-line-of-sight frameworks. Vertical integration into fiber-optic tether manufacturing insulates margin structures from copper and optical fiber input volatility. For New Entrants and Emerging Players: Differentiate on rapid-deployment logistics for rural firefighting and emergency response segments where technician scarcity extends incumbent lead times. The Philippines' maritime patrol expansion across archipelagic waters represents the most penetrable defense adjacent market. Pursue shipborne system integration partnerships with Perth and Brisbane marine engineering clusters as the primary go-to-market angle. For Investors and Strategic Acquirers: The market sits at a vendor consolidation phase that favors electromagnetic compatibility pre-certified specialists with established defense channel relationships. Long-term viability over the next decade rests on platform standardization economics overcoming cross-border certification fragmentation. Watch for India's CEA electrical safety mandate enforcement intensity as the inflection signal determining protected demand corridor durability.| Strategic Initiative | Industry Significance |
|---|---|
| Electromagnetic Compatibility Pre-Certification | Secures vendor list placement ahead of Southeast Asian defense procurement consolidation. |
| Fiber-Optic Tether Manufacturing Integration | Captures margin pool compression from raw material input volatility in copper and optical fiber markets. |
| Shipborne System Architecture Development | Positions for Philippines maritime patrol expansion across salt-corrosion-exposed archipelagic operations. |
| Smart City Service Contract Structuring | Captures recurring revenue from Bangkok and Jakarta municipal data fusion requirements. |
| Silicon Carbide Power Electronics Adoption | Meets Japanese and South Korean defense integrator specifications for reduced thermal signature. |
Research Methodology
Operator-level perspectives from defense procurement officers, CASA-certified drone operators, electromagnetic compatibility testing engineers, and offshore energy inspection coordinators anchored the qualitative base. These interviews triangulated against secondary sources including MIIT equipment certification filings, METI technical conformity assessment procedures, CASA operational framework bulletins, and DGFT export-import classification records. Bottom-up platform deployment estimates and top-down defense budget allocation analysis converged through iterative validation.
Sensitivity analysis tested forecast robustness across alternative regulatory enforcement scenarios and raw material cost trajectories over the projection horizon. Segmentation modeling incorporated application type, end user category, deployment environment, and propulsion technology dimensions. CAGRs derived from logistic adoption curve fitting against historical procurement cycle data, with India's border infrastructure modernization timelines and Japan's carbon-neutral procurement preferences as specific demand drivers.
Decision-makers should treat outputs as directional under sustained defense budget commitment and certification standard stability assumptions; material deviation would warrant model refresh. Specific risks include abrupt electromagnetic compatibility protocol divergence, certified technician training pipeline collapse, and fiber-optic tether supply disruption. Recalibration cycles align with material shifts in national carbon mandate enforcement and defense procurement framework renewals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
UAV
North America Drone Software Market
UAV
UAV Payload Market
UAV
Inspection Drones in Confined Space Market
UAV
Drone Powered Business Solutions Market
UAV
Tactical UAV Market
UAV
Europe Drones Market
UAV
Asia-Pacific Drone Light Shows Market
UAV
Europe Drone Light Shows Market
UAV
Rc Helicopter Market
UAV
Home Security Drone Market
UAV
Multirotor Drones Market
UAV
Global Drone Sensor Market
UAV
Drone Inspection Service Market
UAV
Ultra Micro Drone Market
UAV
Ultra-Long Endurance Drone Market
UAV
North America Small UAV Market