
 Asia-Pacific Digital Battlefield Market | 2026-2036
Asia-Pacific Digital Battlefield Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Digital Battlefield Market Analytics
Naval force modernization is decoupling from legacy platform upgrades across Asia-Pacific defense budgets. Lockheed Martin leverages its integrated warfare systems portfolio to anchor contracts with Australia's AUKUS-aligned submarine program. Thales competes through sovereign radar and electronic warfare specialization in Singapore and South Korea. Elbit Systems extends its battlefield management footprint via localized production partnerships in India and Vietnam.
The Asia-Pacific digital battlefield encompasses networked military technologies integrating real-time data fusion, secure communications, and sensor-to-shooter architectures operating across electromagnetic contested environments. These systems process multi-source intelligence streams to compress decision cycles from minutes to seconds for joint force commanders. Command Systems currently dominate procurement budgets as legacy C2 networks face obsolescence against peer adversary electronic threats. Cloud Computing deployment models are expanding fastest where nations prioritize resilient, distributed architectures over single-point vulnerability, though On-Premises solutions retain preference for nuclear command and nuclear-adjacent operations. AI-enabled Analytics Solutions command premium pricing where defense ministries fund predictive maintenance and autonomous targeting validation pipelines.
Australia's Defence Strategic Review, Japan's METI cybersecurity frameworks for critical infrastructure, and India's CEA data localization mandates for military cloud contracts collectively reshape vendor qualification pathways across the region. Compliance with these overlapping regimes now functions as a market access gate rather than post-award formality. Stakeholders must weigh sovereign partnership requirements against intellectual property exposure when structuring joint ventures with national champions.
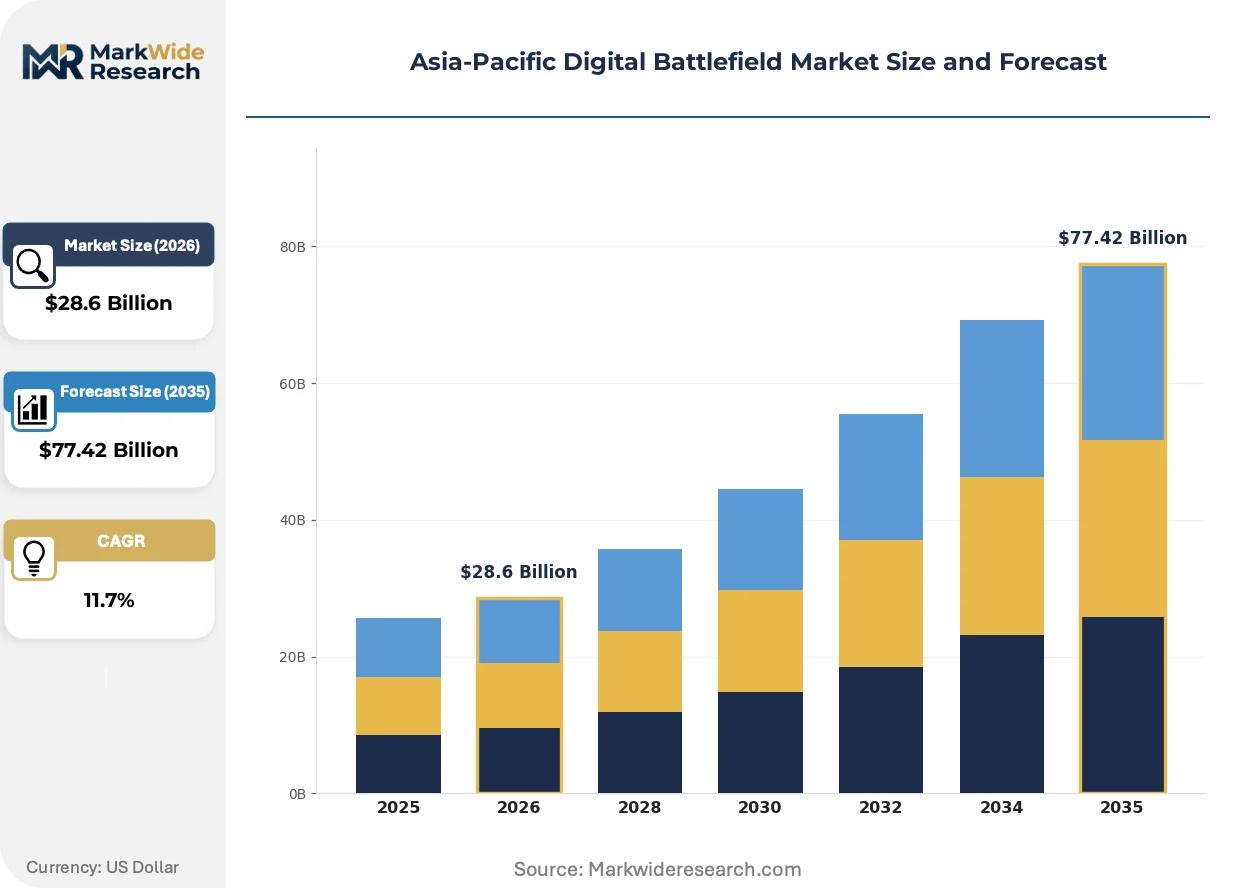
Market Dynamics
China's MIIT cybersecurity standards for military-grade cloud infrastructure are forcing foreign vendors to restructure local partnerships or exit sovereign defense contracts entirely. This regulatory tightening compresses vendor qualification timelines while elevating compliance costs across networked command system procurements.
Growth Catalysts
- AUKUS-aligned submarine programs:Australia's sovereign defense modernization is accelerating procurement of integrated warfare systems with strict data residency requirements. Foreign contractors must establish domestic production facilities to bid on command and control networks.
- Japan's METI cybersecurity frameworks:Critical infrastructure protection mandates for Self-Defense Forces digital transformation are expanding addressable market for secure communications vendors. Compliance certification now functions as a de facto pre-qualification for defense ministry tenders.
- Sensor-to-shooter architectures:Real-time data fusion technologies are compressing decision cycles from minutes to seconds across Southeast Asian naval modernization programs. Joint force commanders demand interoperable battle management systems linking aerial, surface, and subsurface platforms.
Market Restraints
- Rare earth magnet supply concentration:Permanent magnet dependencies for precision-guided munitions guidance systems concentrate in Chinese processing facilities. Export licensing unpredictability disrupts long-term procurement planning for regional defense agencies.
- Legacy C2 network obsolescence:Decades-old command infrastructure in Indonesia, Malaysia, and Thailand requires complete replacement rather than incremental upgrade. Budget allocation rigidities prevent rapid migration to networked architectures.
- Dual-use technology transfer restrictions:Wassenaar Arrangement controls and national export regimes block commercial AI and quantum encryption vendors from defense-adjacent contracts. Indigenous capability gaps persist in high-assurance cryptographic modules.
Strategic Opportunities
- Vietnam's coastal defense digitization:Underpenetrated procurement budgets for maritime domain awareness systems create first-mover advantages for vendors establishing localized maintenance partnerships. The country's CEA data localization mandates favor joint ventures with domestic technology champions.
- AI-enabled predictive maintenance:Convergence of machine learning analytics with satellite-linked equipment health monitoring is opening premium-priced service contracts. Indian defense maintenance depots are piloting autonomous fault detection for armored vehicle fleets.
- South Korea's KF-21 fighter program:Indigenous next-generation combat aircraft development is generating demand for sovereign electronic warfare and radar systems. Technology transfer requirements are accelerating knowledge localization for active electronically scanned array production.
Industry Challenges
- Cleared workforce scarcity:Security-cleared software engineers and systems integrators with defense project experience command premium compensation across Australia, Japan, and Singapore. Talent poaching between prime contractors disrupts program timelines.
- Multi-domain integration complexity:Synchronizing legacy platform data buses with modern IP-based networks requires custom middleware development for each national customer. Non-recurring engineering costs erode margins on fixed-price development contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Digital Battlefield Market |
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $77.42 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Simulations, Training Tools, Command Systems, Analytics Solutions Technology: AI, Augmented Reality, Virtual Reality, Cloud Computing End User: Military, Defense Contractors, Government Agencies, Security Firms Deployment: On-Premises, Cloud-Based, Hybrid, Mobile Solutions |
| Companies Covered | Lockheed Martin Corporation, Northrop Grumman Corporation, BAE Systems, RTX Corporation, Thales Group, General Dynamics Corporation, L3Harris Technologies, Elbit Systems, Airbus, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Digital Battlefield Market Evolving Landscape
Electromagnetic spectrum contestation is driving investment in adaptive waveforms and cognitive radio systems across Asia-Pacific defense research programs. Battlefield network architects prioritize resilience over raw bandwidth in procurement specifications.
Software-defined radio platforms with modular waveform loading are unifying previously stovepiped communications channels across air, land, and maritime domains. Japan's Self-Defense Forces are fielding these systems in phased deployments through 2028. The technology is unifying procurement specifications that previously required separate radios for each service branch, compressing vendor qualification pools to firms with full-spectrum software certification.
India's CEA data localization mandates for military cloud contracts are forcing foreign hyperscale providers to establish sovereign infrastructure with domestic equity partners. Defense ministry auditors now require cryptographic key management within national territory. Prime contractors are responding by segmenting cloud architectures between classified on-premises stacks and unclassified edge processing nodes.
Fixed-price development contracts with milestone-based payment terms are displacing cost-plus arrangements for digital battlefield system procurements. Australia's Defence Strategic Review institutionalized this shift for acquisitions above defined thresholds. Singapore's Defence Science and Technology Agency has adopted similar commercial terms for command system modernizations, transferring program risk to integrators while retaining technical oversight authority.
Asia-Pacific Digital Battlefield Market Segmentation
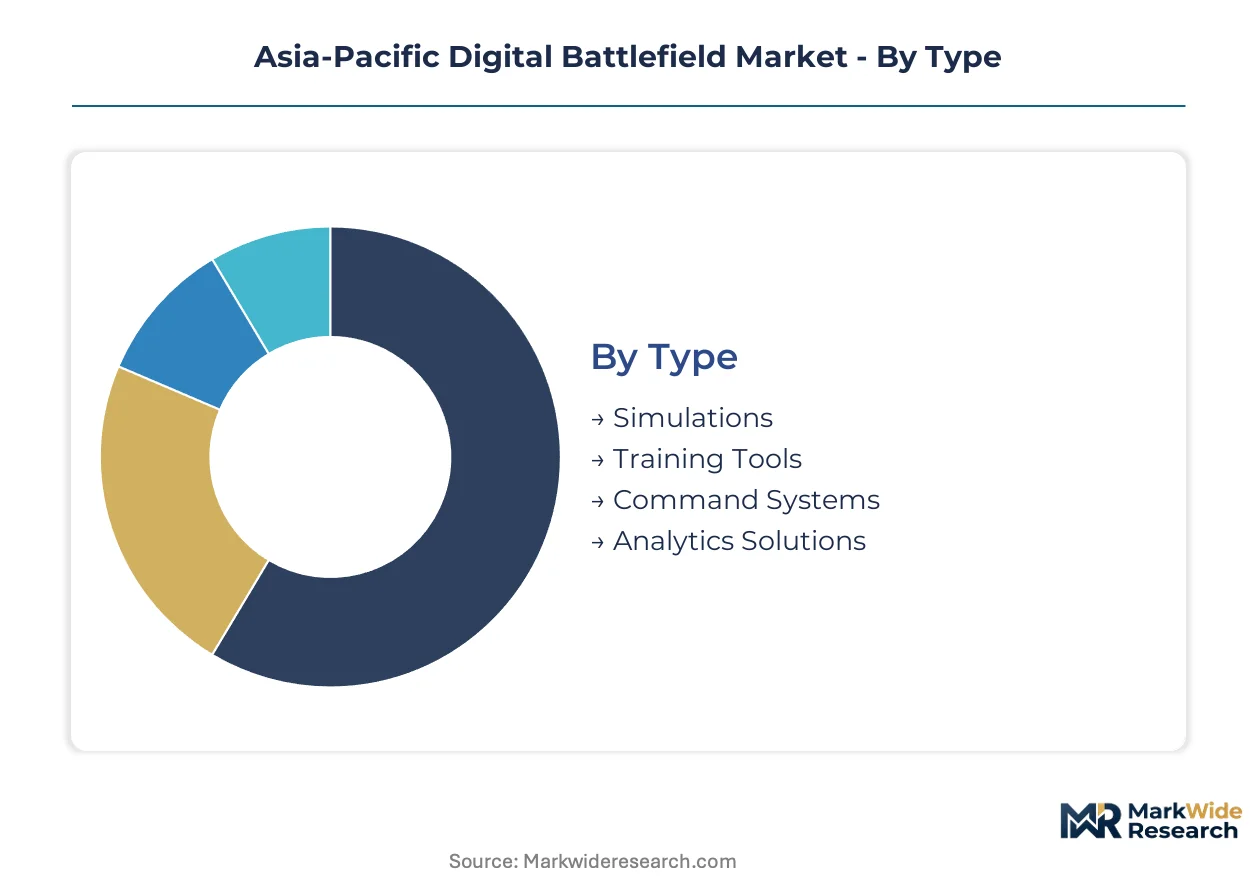
Procurement patterns across Asia-Pacific defense ministries diverge sharply by operational maturity and sovereign data requirements. Segment-level investment priorities reflect these structural differences in threat perception and industrial policy.
Type:
Defense agencies allocate budgets based on legacy infrastructure replacement urgency versus capability gap closure timelines.
- Command Systems:Networked C2 architectures integrating multi-source intelligence streams for joint force coordination. Australia's AUKUS-aligned submarine program and Japan's Self-Defense Forces digital transformation are concentrating procurement here, driven by electromagnetic spectrum contestation against peer adversaries.
- Analytics Solutions:AI-enabled predictive platforms processing equipment health monitoring and autonomous targeting validation. Indian defense maintenance depots pilot these for armored vehicle fleet optimization, with premium pricing justified by operational availability gains.
- Simulations:Synthetic training environments for combined arms exercises with live-virtual-constructive integration.
- Training Tools:Individual and collective skill development systems for platform-specific operator certification.
Command Systems leads volumes today; Analytics Solutions is gaining share fastest.
Technology:
Adoption velocity correlates with national data localization mandates and cleared workforce availability.
- Cloud Computing:Distributed architectures with sovereign infrastructure requirements under India's CEA data localization mandates and China's MIIT cybersecurity standards. Foreign hyperscale providers establish domestic equity partnerships to access defense ministry tenders.
- AI:Machine learning pipelines for predictive maintenance and sensor-to-shooter decision compression. Southeast Asian naval modernization programs prioritize real-time data fusion capabilities here.
- Augmented Reality:Heads-up displays for maintenance technicians and tactical situational awareness overlays.
- Virtual Reality:Immersive mission rehearsal environments for pre-deployment familiarization.
Cloud Computing dominates current procurement cycles; AI commands the steepest expansion trajectory.
End User:
Contracting authority and security clearance thresholds determine vendor qualification pathways.
- Military:Uniformed services with sovereign procurement authority and strict technical specifications. Australia's Defence Strategic Review institutionalized fixed-price development terms for acquisitions above defined thresholds.
- Defense Contractors:Prime integrators and subsystem suppliers managing technology transfer requirements. South Korea's KF-21 fighter program generates demand through active electronically scanned array localization mandates.
- Government Agencies:Civilian defense ministries and national security coordinating bodies.
- Security Firms:Private sector entities with limited access to classified program elements.
Military accounts anchor revenue concentration; Defense Contractors are expanding most quickly.
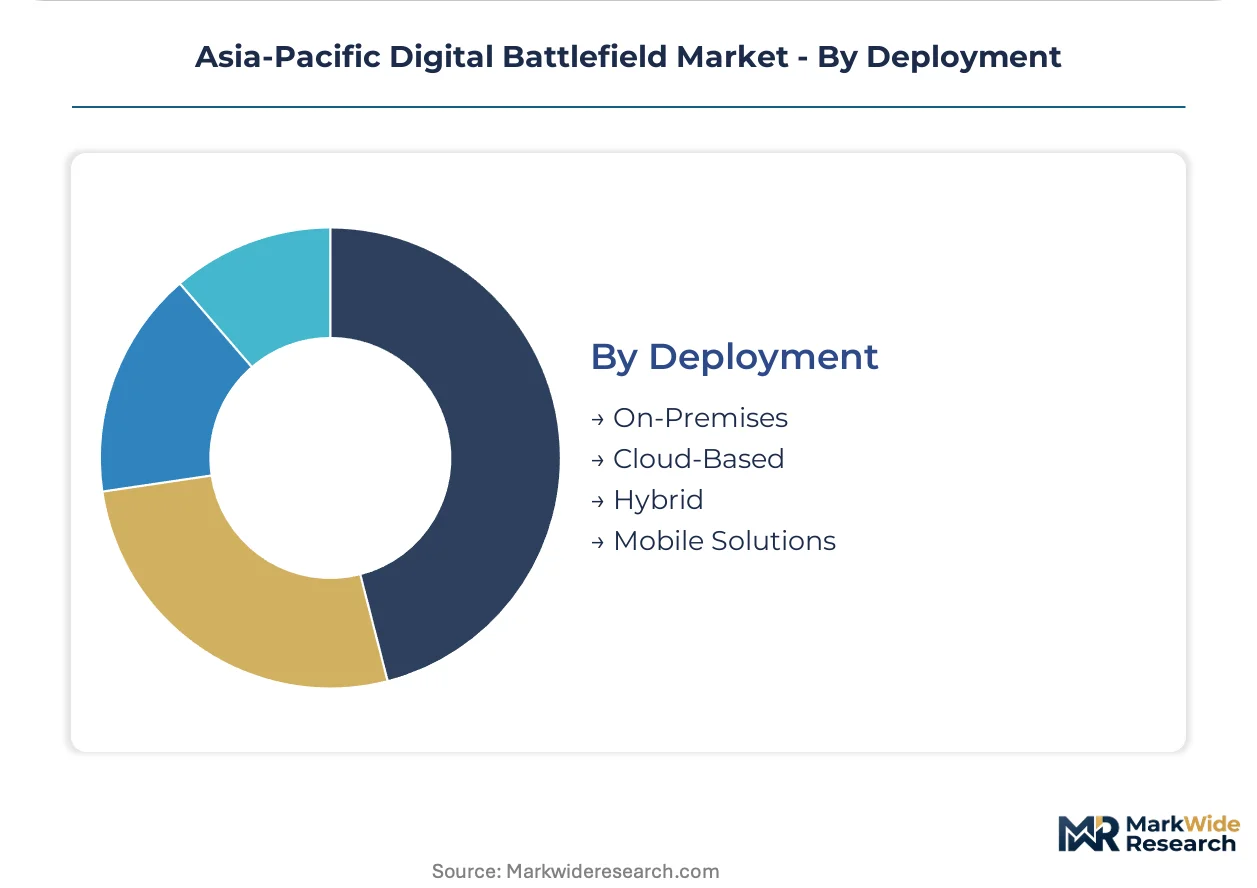
Deployment:
Security classification levels and network resilience requirements shape architecture selection.
- On-Premises:Air-gapped infrastructure for nuclear command and nuclear-adjacent operations retaining preference where single-point vulnerability is unacceptable. Japan's Self-Defense Forces maintain these for highest-assurance communications.
- Hybrid:Segmented architectures separating classified on-premises stacks from unclassified edge processing. Prime contractors respond to defense ministry auditor requirements for cryptographic key management within national territory.
- Cloud-Based:Fully distributed models for unclassified logistics and administrative functions.
- Mobile Solutions:Tactical edge computing for dismounted units and forward-deployed platforms.
On-Premises retains preference for highest-assurance applications; Hybrid deployment is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canberra anchors defense procurement concentration through Australia's AUKUS-aligned submarine program and sovereign modernization mandates. Regional procurement patterns diverge sharply between established alliance partners and emerging digitization programs.
Australia
AUKUS submarine integration drives integrated warfare system procurement with strict data residency requirements. The Defence Strategic Review institutionalized fixed-price development terms above defined acquisition thresholds. Foreign contractors establish domestic production facilities in South Australia and Western Australia to bid on command and control networks.
Japan
Self-Defense Forces digital transformation expands secure communications procurement under METI cybersecurity frameworks. Critical infrastructure protection mandates now function as de facto pre-qualification for defense ministry tenders. Industrial concentration in the Kanto region around Tokyo supports phased software-defined radio deployments through 2028.
India
CEA data localization mandates force foreign hyperscale providers into sovereign infrastructure joint ventures for military cloud contracts. Defense maintenance depots pilot AI-enabled predictive maintenance for armored vehicle fleet optimization. Karnataka's Bangalore cluster hosts cryptographic module development for indigenous capability gaps.
South Korea
KF-21 fighter program generates demand for sovereign electronic warfare and active electronically scanned array localization. Technology transfer requirements accelerate knowledge transfer for radar system production. The Seoul Capital Area concentrates defense electronics manufacturing with government-mandated domestic equity partnerships.
Vietnam
Coastal defense digitization creates procurement opportunities for maritime domain awareness systems with localized maintenance requirements. CEA data localization mandates favor joint ventures with domestic technology champions. Underpenetrated budgets in the Red River Delta and Mekong Delta regions attract first-mover vendor establishment.
Asia-Pacific Digital Battlefield Market Competitive Landscape
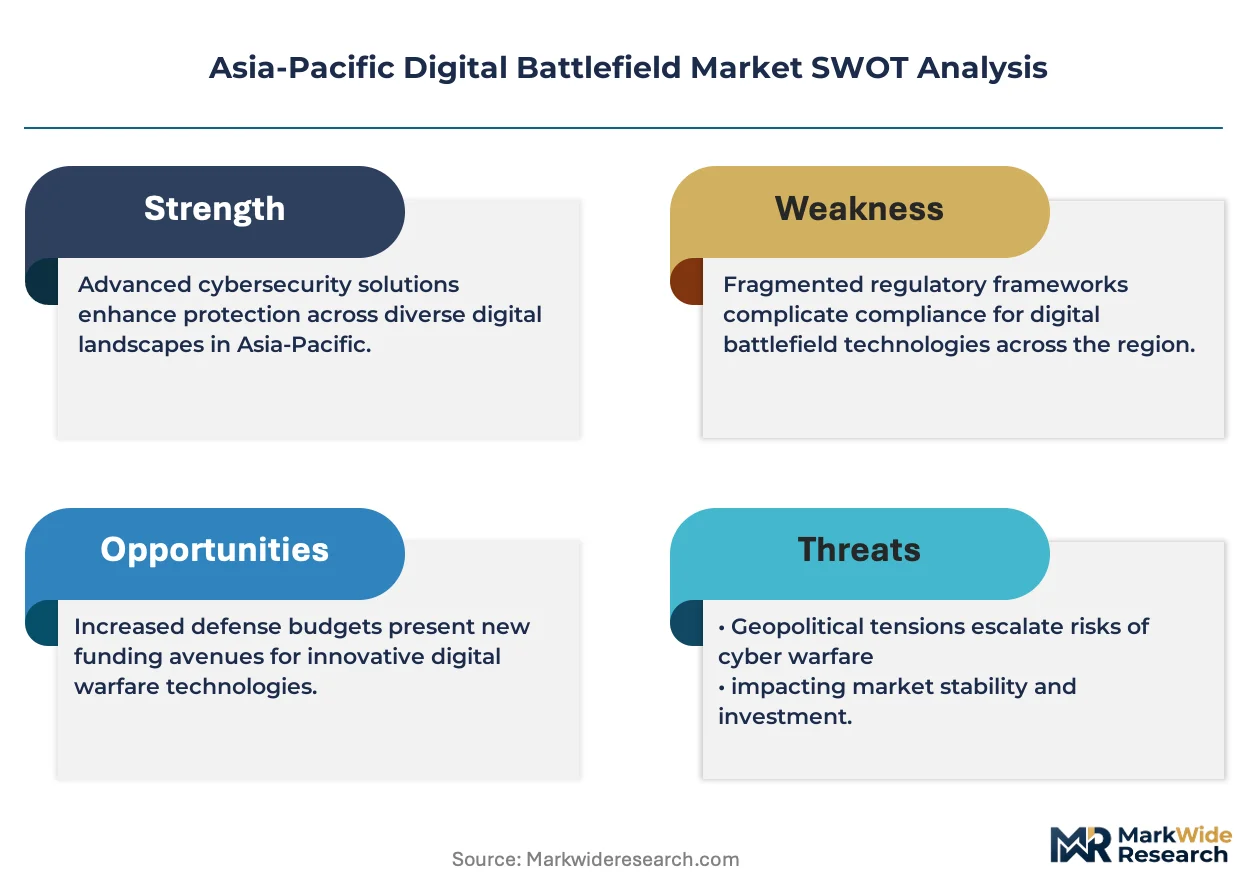
Strategic partnerships dominate the current landscape as foreign primes restructure local relationships to satisfy sovereign compliance requirements. The vendor base organizes around three archetypes: integrated warfare system providers with full-spectrum portfolios, radar and electronic warfare specialists with regional sovereign partnerships, and battlefield management vendors leveraging localized production arrangements. Prime contractors pursue M&A activity to acquire cleared workforce capabilities, while technology licensing agreements proliferate to satisfy data localization mandates without full joint venture exposure.
Within the integrated warfare tier, Lockheed Martin and Northrop Grumman represent the archetype of alliance-aligned primes anchoring major platform programs through domestic facility establishment. Among European-headquartered specialists, BAE Systems and Thales Group exemplify sovereign radar and electronic warfare positioning through regional specialization in Singapore and South Korea. At the localized production end, Elbit Systems occupies a position demonstrating battlefield management expansion via manufacturing partnerships in India and Vietnam.
| Leading Market Players |
|---|
| Lockheed Martin Corporation |
| Northrop Grumman Corporation |
| BAE Systems |
| RTX Corporation |
| Thales Group |
| General Dynamics Corporation |
| L3Harris Technologies |
| Elbit Systems |
| Airbus |
| Others |
Value Network & Pricing Analysis
Sovereign-backed defense primes with captive production facilities in Australia, Japan, and South Korea anchor supply-side discipline, translating cleared workforce scarcity and data localization mandates into sustained pricing power for mission-critical command systems. Their ownership structure insulates long-term contract margins from commodity volatility while forcing foreign entrants into cost-absorbing joint venture arrangements.
Pricing Analysis
Direct-to-defense-ministry channels bypass distributor markups entirely, with prime contractors capturing full value through fixed-price development terms institutionalized under Australia's Defence Strategic Review. Three-tier pricing structure across sovereign-compliant, alliance-aligned, and commercial-adaptable system tiers reflects certification grade and domestic content requirements. Cost compression in commercial-adaptable tiers intensifies because foreign hyperscale providers must absorb infrastructure localization costs. Government agencies exhibit highest price sensitivity where budget allocation rigidities persist, while nuclear-adjacent operations show least sensitivity given single-source vulnerability constraints.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from Australia's AUKUS submarine program and South Korea's KF-21 fighter development, with prime contractors maintaining captive engineering teams in Adelaide and Seoul. Rare earth magnet processing concentrates in China, precision semiconductor fabrication in Taiwan and South Korea, and cryptographic module assembly in India and Japan. Single-source vulnerability in Chinese rare earth export licensing disrupts guidance system procurement timelines. Distribution runs through sovereign-cleared facility networks with mandatory domestic equity partnerships under India's CEA and China's MIIT frameworks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific digital battlefield represents a late-cycle quality story as electromagnetic spectrum contestation shifts procurement specifications toward resilient, adaptive architectures with premium pricing endurance.
For Market Incumbents: Anchor integrated warfare system portfolios through domestic facility establishment in South Australia and Western Australia to satisfy AUKUS data residency requirements. Deepen backward integration into sovereign radar and electronic warfare production via technology transfer partnerships in South Korea and Singapore, defending against emerging localized primes with cleared workforce advantages. For New Entrants and Emerging Players: Launch via joint venture structures with Vietnam's domestic technology champions to access coastal defense digitization budgets under CEA localization mandates. Target maritime domain awareness systems in underpenetrated Mekong Delta procurement channels, leveraging localized maintenance partnerships as the primary go-to-market angle against established regional primes. For Investors and Strategic Acquirers: Valuations sit cheapest among battlefield management software specialists with AI-enabled predictive maintenance pipelines and security-cleared engineering teams. Long-term viability across the projection horizon hinges on compliance adaptability to overlapping sovereign frameworks. Acquisition target archetype: mid-cap vendors with established MIIT or CEA certification pathways. Monitor rare earth export licensing unpredictability as the signal to watch for supply chain stress inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Infrastructure Partnership | Foreign hyperscale providers establish domestic equity joint ventures to satisfy India's CEA data localization mandates for military contracts. |
| Cleared Workforce Acquisition | Prime contractors acquire security-cleared software engineering teams in Australia and Japan to compress program timeline risks. |
| Software-Defined Radio Certification | Vendors pursue full-spectrum software certification to unify previously stovepiped communications channels across Japan's Self-Defense Forces. |
| Localized Production Facility Establishment | Foreign primes build domestic manufacturing presence in South Australia to bid on AUKUS-aligned submarine command networks. |
| AI Predictive Maintenance Service Contract | Analytics vendors secure premium-priced recurring revenue through satellite-linked equipment health monitoring for Indian armored vehicle fleets. |
Research Methodology
Bottom-up defense ministry procurement tracking reconciled against top-down prime contractor revenue segmentation forms the analytical core of this study. Primary interviews with program managers at Australia's Defence Strategic Review implementation office, Japan's Acquisition Technology and Logistics Agency procurement officers, India's Defence Research and Development Organisation project directors, and South Korea's Defense Acquisition Program Administration contract specialists combined with secondary validation against MIIT cybersecurity standard filings, CEA data localization circulars, METI critical infrastructure protection frameworks, and AUKUS implementation pathway disclosures. Top-down triangulation against customs trade data for rare earth magnet flows and hyperscale provider sovereign infrastructure investment disclosures completed the demand-supply reconciliation.
Historical trendline analysis of command system procurement cycles across Australia's sovereign modernization programs, Japan's Self-Defense Forces digital transformation phases, and India's indigenization mandates informed the projection framework. Segmentation modeling spanned deployment architecture, technology adoption velocity, end-user contracting authority, and regional regulatory cluster alignment. CAGRs derived from fitted trend extrapolation against policy-mandated procurement acceleration timelines, with specific inputs including electromagnetic spectrum contestation investment curves and cleared workforce supply constraints.
Forecast precision tightens around the base case; tail outcomes carry wider variance under rare earth export licensing disruption or accelerated data localization mandate expansion. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Defense and Military Systems and Equipment
Military Load Carriage System Market
Defense and Military Systems and Equipment
Mine Clearance System Market
Defense and Military Systems and Equipment
Middle East and Africa Defense Market
Defense and Military Systems and Equipment
Military High Altitude Radio Jamming System Market
Defense and Military Systems and Equipment
Global Digital Battlefield Market
Defense and Military Systems and Equipment
Saudi Arabia Defense Market
Defense and Military Systems and Equipment
Military Helmet and Helmet Mounted Display Systems Market
Defense and Military Systems and Equipment
Explosive Ordnance Disposal Market
Defense and Military Systems and Equipment
Global Battlefield Management System Market
Defense and Military Systems and Equipment
Mission Management System Market
Defense and Military Systems and Equipment
Land-Based Smart Weapons Market
Defense and Military Systems and Equipment
Global Military Laser Rangefinder Market
Defense and Military Systems and Equipment
Battle Management System (BMS) Market
Defense and Military Systems and Equipment
Smart War Weapon Market
Defense and Military Systems and Equipment
India Defense Market
Defense and Military Systems and Equipment
Military Helmet and Helmet Mounted Displays Market