
 Short-Range Delivery Drone Market | 2026-2036
Short-Range Delivery Drone Market Size, Share, and Industry Trends Forecast 2026-2036
Short-Range Delivery Drone Market Insights
Chinese lithium-polymer battery pack production is hardening as the dominant supply constraint for frame manufacturers worldwide. Wingcopter leverages its German engineering base to sustain premium positioning in medical-grade hybrid VTOL systems. Zipline International anchors East African last-mile networks through autonomous control platforms purpose-built for blood product distribution. Amazon.com competes on manufacturing scale, operating dedicated development centers for rotor-optimized quadcopter designs.
Short-range delivery drones are unmanned aerial vehicles engineered for payload transport under approximately ten kilometers, typically utilizing multi-rotor or hybrid lift configurations with maximum takeoff weights below twenty-five kilograms and battery-driven propulsion systems rated for fifteen to thirty minutes of flight endurance. Their primary commercial purpose centers on bypassing ground infrastructure bottlenecks through direct point-to-point aerial logistics. Hybrid VTOL configurations dominate capital deployment where runway absence demands combined vertical lift and fixed-wing cruise efficiency. AI-based routing systems represent the fastest-expanding technology segment as operators prioritize dynamic rerouting around restricted airspace and weather anomalies. Food delivery applications remain margin-constrained due to per-unit economics, while medical supplies transport commands premium pricing through cold-chain certification requirements and regulatory urgency.
The FAA's Part 107 and Part 135 frameworks govern commercial operations in the United States, mandating pilot certification and air carrier standards that filter out undercapitalized entrants. EASA's Specific Category regulations under EU 2019/947 establish comparable barriers across European member states, with drone operator certificates required for beyond-visual-line-of-sight medical missions. China's CAAC maintains separate certification tracks through the Unmanned Aircraft Flight Management Regulation, creating fragmented market access conditions for multinational platform providers. Stakeholders must monitor evolving detect-and-avoid mandates as regulators weigh integration with crewed aviation corridors.
Market Dynamics
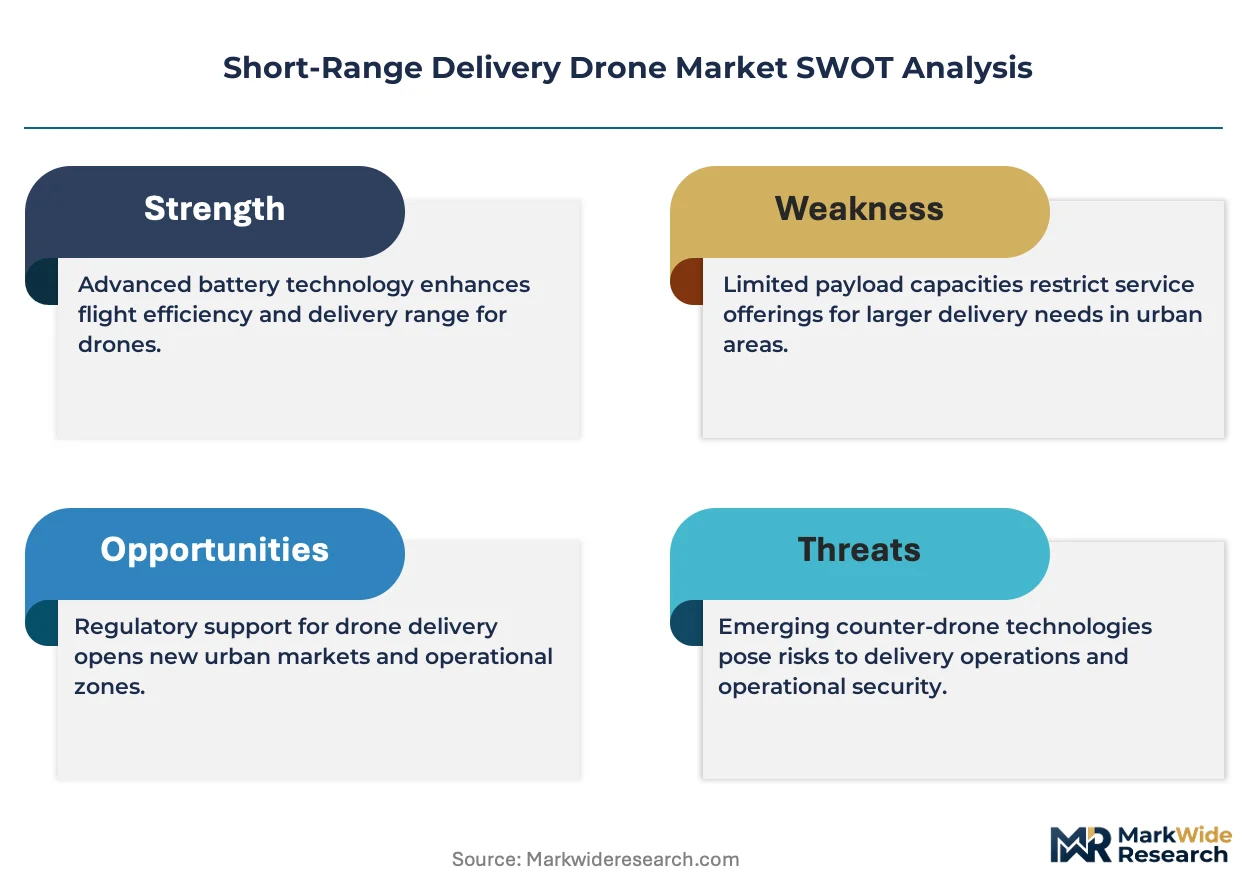
Hybrid VTOL architecture is displacing pure multi-rotor designs as operators demand extended range without sacrificing vertical landing precision in dense urban corridors.
Growth Catalysts
- Part 135 Air Carrier Certification:The FAA's framework in the United States creates compliant operational pathways for beyond-visual-line-of-sight medical deliveries, filtering out undercapitalized competitors and concentrating revenue among certified operators.
- Cold-Chain Certification Requirements:Pharmaceutical distributors now mandate temperature-validated transport for biologics and vaccines, creating premium pricing tiers that justify fleet investment over ground-based alternatives.
- Chinese Lithium-Polymer Production Scale:Battery pack manufacturing concentration in Shenzhen and Dongguan supply chains is reducing unit costs for frame assemblers worldwide, compressing hardware procurement cycles.
Market Restraints
- Detect-and-Avoid Mandate Uncertainty:Pending FAA requirements for crewed aviation corridor integration impose capital-intensive sensor payloads that inflate per-unit economics before revenue generation begins.
- Single-Source Battery Dependency:Cathode precursor refining concentrates in Jiangsu province, exposing frame manufacturers to export control volatility and forced production pauses.
- Fixed-Wing Glide Limitations:Hybrid VTOL systems sacrifice payload capacity for cruise efficiency, constraining blood product volumes per flight below what ground vehicles achieve.
Strategic Opportunities
- EASA Specific Category Expansion:EU 2019/947 regulatory harmonization across member states enables cross-border medical corridor networks that German operators can leverage into adjacent markets.
- AI-Based Dynamic Routing Convergence:Integration of real-time weather telemetry with restricted airspace databases is compressing flight planning cycles and reducing human oversight requirements.
- Last-Mile Pharmacy Networks:Urban retail pharmacy chains in France and Spain are piloting automated prescription fulfillment that bypasses centralized distribution centers entirely.
Industry Challenges
- Remote Pilot Certification Bottlenecks:FAA Part 107 training pipelines produce qualified operators slower than fleet expansion rates, forcing wage inflation for experienced controllers.
- Airframe-Autopilot Integration Complexity:Proprietary flight control software from legacy vendors resists interoperability with third-party sense-and-avoid hardware, extending certification timelines.
- Ground Infrastructure Capex Requirements:Vertiport construction and charging station deployment demand municipal permitting coordination that delays operational launch by 18-24 months in most jurisdictions.
Report Scope
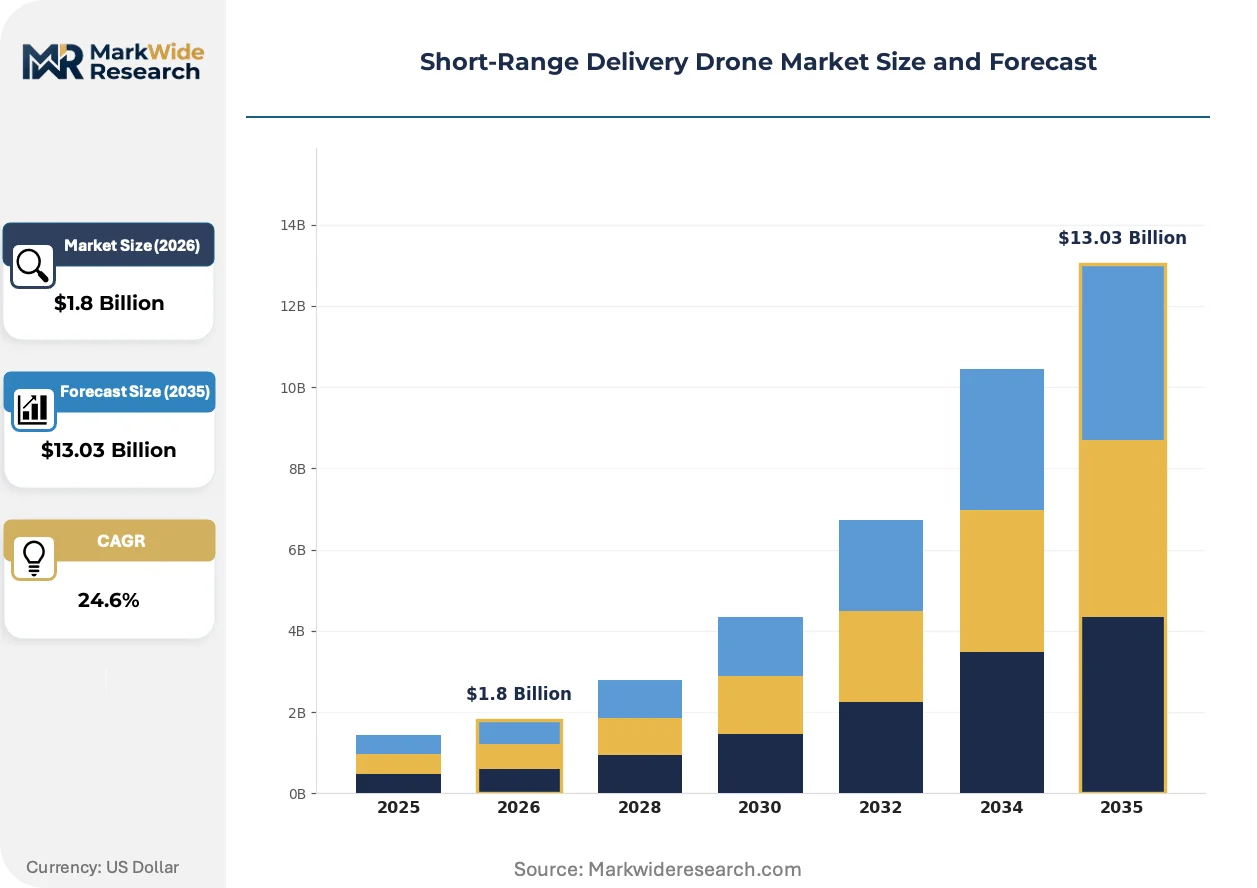
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Short-Range Delivery Drone Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $13.03 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Quadcopter, Hexacopter, Fixed-Wing, Hybrid VTOL, Octocopter Technology: GPS Navigation, Obstacle Avoidance, AI-Based Routing, Autonomous Control, Real-Time Tracking Use Case: Food Delivery, Parcel Delivery, Medical Supplies Transport, E-Commerce Shipments, Document Courier End User: Courier Services, Pharmaceutical Providers, Food Chains, Retailers, Logistics Companies |
| Companies Covered | Wingcopter, Wing Aviation LLC, Zipline International Inc., UPS Flight Forward Inc., Amazon.com Inc., Alphabet Inc., Matternet Inc., Flytrex Aviation Ltd., United Parcel Service Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Short-Range Delivery Drone Market Trends and Innovations
Autonomous control platforms are compressing operator labor models while sense-and-avoid sensor fusion is rewriting airspace access rules. Battery chemistry evolution and procurement pattern shifts complete the transformation arc.
Solid-state lithium-metal cells are electrifying energy density benchmarks for sub-25kg platforms. German medical operators are adopting these packs ahead of food delivery segments due to cold-chain reliability requirements. The technology is electrifying route planning assumptions by extending practical range beyond current lithium-polymer limits without weight penalties.
EASA's drone operator certificate requirements under EU 2019/947 are tightening pilot oversight mandates for beyond-visual-line-of-sight missions. Operators must now demonstrate redundant command links and automated contingency protocols to maintain certification. Medical transport providers in Germany and the Netherlands are responding by consolidating flight operations centers to pool compliance expertise.
Pharmaceutical procurement departments are consolidating vendor relationships around integrated fleet-management contracts rather than per-delivery pricing. This behavior shift compresses margin transparency for pure hardware suppliers while rewarding operators with vertical service capabilities. The pattern is most visible in French hospital network tenders, where total-cost-of-ownership models now dominate evaluation criteria.
Short-Range Delivery Drone Market Segmentation
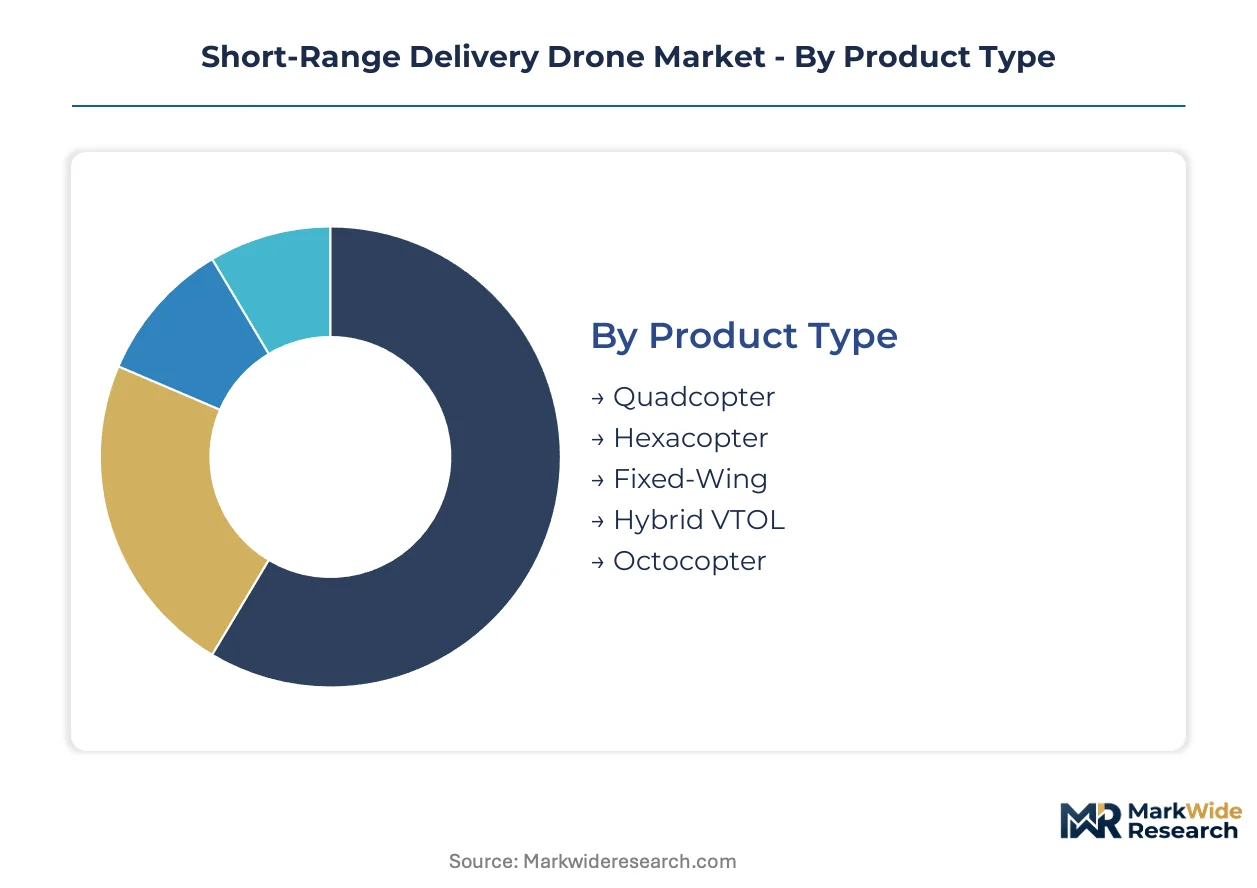
Short-range delivery drone procurement patterns diverge sharply across product architectures, autonomy levels, and end-use requirements. Pharmaceutical cold-chain mandates and FAA Part 135 certification pathways are compressing vendor selection criteria around integrated system performance rather than standalone hardware specifications.
Product Type:
Standalone airframe configurations dominate fleet procurement where operators lack in-house integration capabilities, while embedded autopilot-airframe pairings concentrate among certified medical carriers.
- Hybrid VTOL:Combines multi-rotor vertical lift with fixed-wing cruise efficiency through tilt-rotor or lift-plus-cruise architectures. German pharmaceutical networks under EASA Specific Category certification are standardizing on these platforms for blood product corridors exceeding eight kilometers.
- Quadcopter:Four-rotor configuration with direct-drive electric motors and simplified flight control algorithms. Food delivery operators in dense urban cores prioritize these units for sub-three-kilogram payloads where endurance requirements stay below twenty minutes.
- Hexacopter:Six-rotor redundancy architecture tolerating single-motor failure without payload loss. Survey and inspection contractors embed these into mixed-service fleets for missions demanding hover stability in moderate wind conditions.
- Fixed-Wing:Conventional aerodynamic surfaces requiring runway or catapult launch infrastructure. Rural parcel networks in Australia and Canada deploy these for maximum range efficiency where landing zone access exists.
- Octocopter:Eight-rotor heavy-lift configuration supporting payloads above ten kilograms with enhanced redundancy margins. Industrial logistics pilots in the United Arab Emirates test these for construction material transport in controlled airspace zones.
Hybrid VTOL leads volumes today; octocopter configurations are gaining share fastest in heavy-lift testing programs.
Technology:
Cost-tier stratification separates commodity navigation stacks from premium autonomy suites requiring regulatory validation investment.
- AI-Based Routing:Machine learning algorithms ingest real-time weather telemetry, restricted airspace boundaries, and battery state-of-charge to optimize flight paths dynamically. Medical operators in the Netherlands consolidate operations centers around these capabilities to satisfy EASA redundant command-link mandates.
- Autonomous Control:Full beyond-visual-line-of-sight operation without continuous human pilot intervention, contingent on detect-and-avoid sensor certification. Zipline International's East African blood distribution networks anchor demand here through purpose-built platforms.
- GPS Navigation:Standard satellite positioning with WAAS or EGNOS augmentation for meter-level accuracy. Entry-level food delivery fleets in Spain and France rely on these systems where regulatory frameworks still mandate visual-line-of-sight operation.
- Obstacle Avoidance:Lidar, radar, or stereo vision sensor fusion for unplanned object detection and evasion. Urban corridor operators in Singapore and Dubai prioritize this technology for dense built-environment penetration.
- Real-Time Tracking:Continuous telemetry transmission to ground control stations for fleet coordination and regulatory compliance logging. Pharmaceutical distributors mandate this capability for chain-of-custody documentation across temperature-validated shipments.
GPS Navigation anchors installed base volumes; AI-Based Routing is climbing the fastest as BVLOS certification expands.
Use Case:
Application-specific margin structures separate premium-certified medical transport from commoditized consumer delivery segments.
- Medical Supplies Transport:Temperature-validated payload compartments with real-time thermal monitoring and contingency protocol automation. Cold-chain certification requirements from pharmaceutical procurement departments concentrate demand among vertically integrated operators with vertical service capabilities.
- Food Delivery:Rapid-turnaround thermal bags with consumer-facing arrival notifications and photo-verification drop protocols. Per-unit economics constrain fleet investment as delivery fees compress below autonomous operation cost thresholds in most European markets.
- Parcel Delivery:Standardized container interfaces compatible with existing last-mile sorting infrastructure. National postal operators in Germany and France pilot these services for rural route supplementation where ground vehicle costs exceed aerial alternatives.
- E-Commerce Shipments:Direct-to-consumer fulfillment bypassing centralized distribution centers through micro-fulfillment node networks. Amazon.com operates dedicated development centers optimizing rotor configurations for this segment's weight distribution patterns.
- Document Courier:Secure tamper-evident payload bays for legal, financial, and governmental document transmission. Banking networks in Switzerland and Luxembourg maintain niche demand for same-day notarized instrument delivery.
Medical Supplies Transport commands premium pricing tiers; E-Commerce Shipments show steepest expansion trajectory as micro-fulfillment networks proliferate.
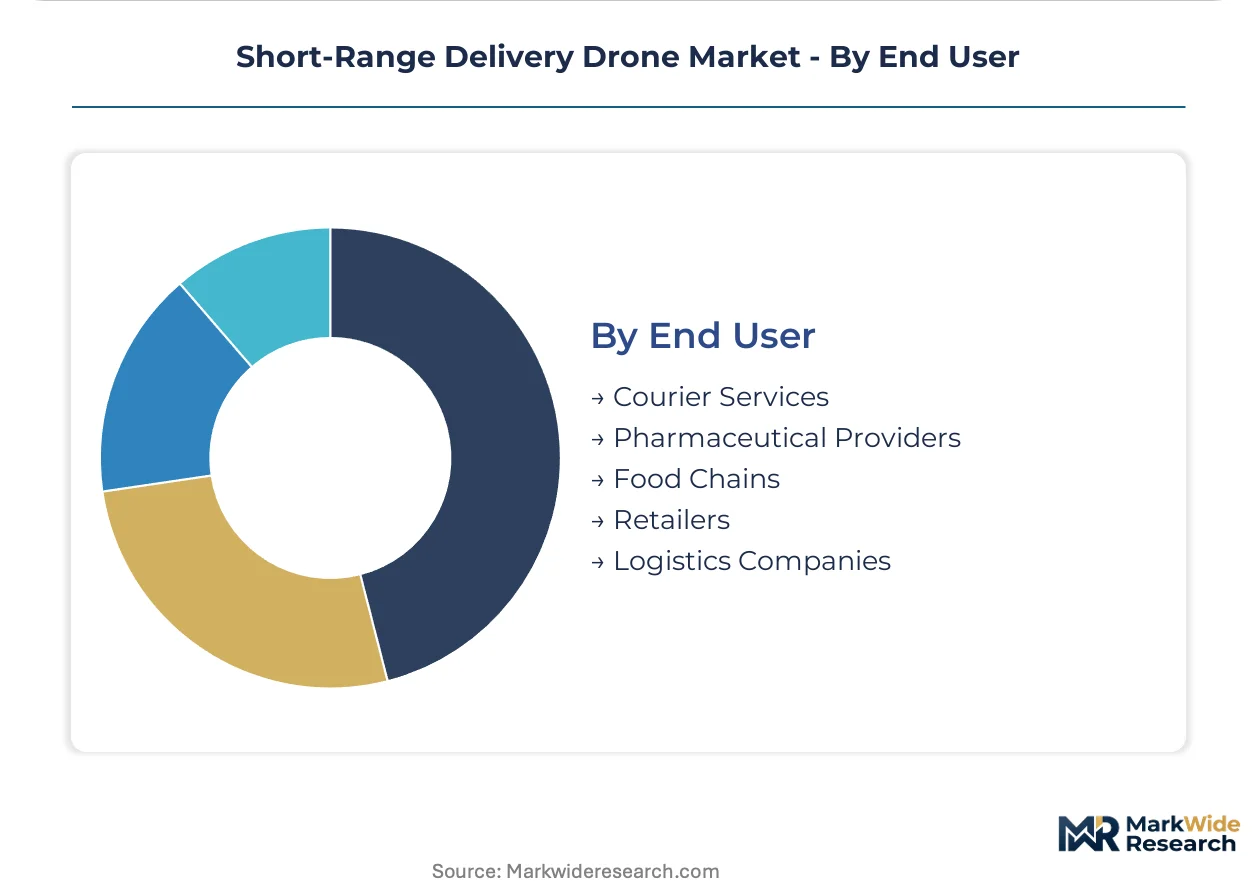
End User:
Customer-type maturity separates consolidated fleet-management contractors from fragmented pilot-program operators.
- Pharmaceutical Providers:Integrated cold-chain logistics departments consolidating vendor relationships around total-cost-of-ownership contracts rather than per-delivery pricing. French hospital network tenders increasingly exclude pure hardware suppliers lacking vertical service capabilities.
- Logistics Companies:Parcel integrators seeking aerial augmentation for last-mile cost reduction in low-density delivery zones. DHL and UPS maintain experimental programs concentrated in suburban corridors with favorable municipal permitting environments.
- Courier Services:Independent operators bidding on time-critical document and small-package delivery contracts. FAA Part 107 certification bottlenecks constrain fleet expansion rates below demand growth, forcing wage inflation for qualified remote pilots.
- Food Chains:Quick-service restaurant operators testing automated fulfillment for digital order channels. Margin constraints limit deployment to premium urban markets with concentrated demand density and favorable vertiport access.
- Retailers:Pharmacy and convenience store chains piloting automated prescription fulfillment from local inventory. Urban retail networks in France and Spain bypass centralized distribution entirely through direct-to-consumer aerial delivery.
Pharmaceutical Providers dominate contract value; Retailers are expanding most quickly as pharmacy automation pilots multiply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping fleet deployment as operators migrate toward jurisdictions with clarified beyond-visual-line-of-sight pathways and lower certification latency. Cost-of-compliance gaps between the United States and European Union are concentrating medical-grade platform investment in Germany and the Netherlands.
United States
Pharmaceutical distributors in North Carolina and California are expanding pilot programs for blood product transport between hospital networks. The FAA's Part 135 air carrier certification framework filters operational entrants through capital-intensive compliance requirements. Wing Aviation LLC and UPS Flight Forward Inc. anchor certified operations in suburban Dallas and Raleigh-Durham corridors.
Germany
EASA Specific Category certification under EU 2019/947 enables cross-border medical corridor networks spanning the Rhine-Ruhr and Bavarian regions. Wingcopter leverages its Darmstadt engineering base to sustain premium positioning in temperature-validated transport systems. The Frankfurt-Rhine-Main metropolitan cluster hosts consolidated flight operations centers pooling redundant command-link expertise.
China
Shenzhen and Dongguan manufacturing clusters dominate lithium-polymer battery pack production for frame assemblers worldwide. The CAAC's Unmanned Aircraft Flight Management Regulation maintains separate certification tracks that fragment market access for multinational operators. Domestic logistics platforms are piloting last-mile delivery in Guangzhou and Hangzhou urban cores.
United Arab Emirates
Dubai's vertiport infrastructure investments are compressing operational launch timelines for courier services in dense urban corridors. The General Civil Aviation Authority's detect-and-avoid mandates are accelerating sensor payload integration timelines. Amazon.com Inc. operates dedicated development centers optimizing rotor configurations for Gulf-state micro-fulfillment networks.
Australia
Rural parcel networks in Queensland and Western Australia deploy fixed-wing configurations for maximum range efficiency where landing zone access exists. The Civil Aviation Safety Authority's remote pilot certification requirements constrain fleet expansion below demand growth in remote mining corridors. Perth-based operators are consolidating around total-cost-of-ownership contracts for document courier services.
Short-Range Delivery Drone Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialized medical certification and heavy-lift testing programs. The vendor base stratifies across three maturity tiers: vertically integrated service operators, pure hardware manufacturers, and logistics incumbents with captive aerial divisions. Three strategic archetypes dominate: German engineering-centric platforms, East African autonomous network anchors, and scale-driven e-commerce fulfillment specialists. Competitive moves concentrate on EASA certification pre-positioning and municipal vertiport partnership lock-ups.
Among German-based platform developers, Wingcopter GmbH exemplifies the medical-grade hybrid VTOL archetype through its EASA regulatory relationships and Darmstadt headquarters concentration. Zipline International Inc. anchors the autonomous control tier with purpose-built platforms for blood distribution networks. Amazon.com Inc. occupies the scale-driven position through dedicated rotor-optimization development centers and manufacturing integration.
| Leading Market Players |
|---|
| Wingcopter |
| Wing Aviation LLC |
| Zipline International Inc. |
| UPS Flight Forward Inc. |
| Amazon.com Inc. |
| Alphabet Inc. |
| Matternet Inc. |
| Flytrex Aviation Ltd. |
| United Parcel Service Inc. |
| Others |
Pricing and Supply Chain Analysis
EASA cold-chain certification mandates for beyond-visual-line-of-sight medical deliveries gate qualified supply to vertically integrated operators while sustaining premium-tier pricing for temperature-validated transport systems. Pharmaceutical procurement departments now consolidate vendor relationships around total-cost-of-ownership contracts that reward fleet-management capabilities over standalone hardware sales.
Pricing Analysis
Distributor margins compress as frame manufacturers bypass intermediaries to serve certified operators directly. Pricing stratifies across premium medical-grade systems, standard commercial platforms, and economy food-delivery configurations. Cost compression in the food-delivery tier intensifies because per-unit economics constrain fleet investment below autonomous operation thresholds. Courier services exhibit highest price sensitivity while pharmaceutical providers absorb premium pricing for cold-chain reliability.
Supply Chain Analysis
Skilled aerospace engineering labor availability in southern Germany and the Netherlands sustains precision manufacturing for EASA-certified platforms. Shenzhen and Dongguan battery pack production draws from Jiangsu province cathode refining, creating single-source vulnerability to export control volatility. Distribution runs through integrated fleet-management contracts rather than component spot markets, concentrating procurement power among operators with vertical service capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in short-range delivery drones rests on solid-state battery cost-down curves and pharmaceutical procurement's shift toward premium-certified service tiers.
For Market Incumbents: Cement EASA regulatory relationships through redundant command-link infrastructure investments that emerging entrants cannot replicate quickly. Deepen backward integration into battery pack assembly to reduce exposure to Chinese cathode precursor volatility. Prioritize municipal vertiport partnership lock-ups in Frankfurt-Rhine-Main and Raleigh-Durham corridors before competitors secure operational launch windows. For New Entrants and Emerging Players: Capture last-mile pharmacy automation pilots in French and Spanish urban retail networks where incumbent presence remains thin. Target document courier services in Swiss and Luxembourg banking corridors where niche premium pricing sustains smaller fleet scales. Lead with autonomous control platform specialization rather than hardware manufacturing to compress capital requirements. For Investors and Strategic Acquirers: Roll-up economics work for mid-scale medical operators because EASA certification bottlenecks create scarcity value for existing certificate holders. Five-to-ten-year viability hinges on detect-and-avoid regulatory harmonization enabling cross-border corridor networks. Watch FAA Part 135 certification velocity as the inflection signal—accelerated approval timelines would dilute scarcity premia for early certified operators.| Strategic Initiative | Industry Significance |
|---|---|
| EASA Specific Category Pre-Certification | Positions operators for EU cross-border medical corridor expansion before regulatory harmonization completes. |
| Vertiport Infrastructure Partnerships | Municipal permitting coordination in Dallas and Dubai compresses operational launch timelines by 18-24 months. |
| Solid-State Battery Integration | German medical operators adopt lithium-metal cells ahead of food segments for cold-chain reliability extension. |
| AI Routing Platform Development | Netherlands operations centers consolidate around dynamic rerouting to satisfy redundant command-link mandates. |
| Pharmaceutical Fleet-Management Contracts | French hospital network tenders increasingly exclude pure hardware suppliers lacking vertical service capabilities. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with drone operations executives, EASA certification consultants, pharmaceutical procurement directors, and municipal aviation planners with secondary validation against FAA certification databases, EASA regulatory filings, customs battery trade records, and hospital network tender documents. Bottom-up fleet deployment estimates triangulated against top-down addressable logistics spend calculations.
Segment-weighting across product architecture, autonomy level, and end-use application drove volume and value allocation throughout the projection horizon. Modeled dimensions included hybrid VTOL versus multi-rotor configurations, GPS versus AI-based routing technology tiers, and medical versus food versus parcel use cases. CAGRs derived from logistic intensity trends and regulatory pathway clarity assessments, with battery energy density evolution and pilot certification pipeline velocity as key forecast inputs.
Underlying measurement precision varies by segment; medical transport and EASA-certified operations carry tighter precision than emerging food-delivery pilots where regulatory frameworks remain unsettled. Forecasts reflect assumptions about detect-and-avoid mandate timelines and cathode supply chain stability. Material deviation in FAA Part 135 approval velocity or Chinese export control enforcement warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
UAV
UAV GNSS Antenna Market
UAV
Global Smartphone Controlled Drone Market
UAV
Tethered Drones Market
UAV
UAV Simulator Software Market
UAV
Europe Drone Light Shows Market
UAV
Unmanned Aerial Vehicle Fuel Cell Market
UAV
North America Drone Services Market
UAV
GCC Drone Pilot Training Market
UAV
Global Stratospheric UAV Payload Technology Market
UAV
Drone Roof Inspection Market
UAV
Rc Helicopter Market
UAV
Unmanned Combat Aerial Vehicle Market
UAV
Global Drone Inspection and Monitoring Market
UAV
Drone Payload Market
UAV
Asia-Pacific Drone Light Shows Market
UAV
Global Smart Commercial Drones Market