
 Middle-East and Africa Small UAV Market | 2026-2036
Middle-East and Africa Small UAV Market Size, Share, and Industry Trends Forecast 2026-2036
Middle-East and Africa Small UAV Market Foresight
Defense ministries across the Gulf Cooperation Council states are bifurcating procurement budgets between sovereign capability-building and off-the-shelf platform acquisition. Elbit Systems leverages its Hermes family production lines in Israel to sustain regional dominance in medium-altitude tactical systems. Baykar Makina Sanayi ve Ticaret A.S. competes aggressively on unit economics, while EDGE Group PJSC anchors Emirati industrial policy through in-house unmanned platform development.
Small unmanned aerial vehicles in the Middle-East and Africa span fixed-wing, rotorcraft, hybrid, and nano configurations with maximum takeoff weights below 150 kilograms and endurance profiles ranging from 45 minutes to 12 hours, serving military ISR, commercial logistics, and critical infrastructure monitoring missions. Rotorcraft platforms dominate current procurement volumes due to vertical takeoff flexibility in desert and urban operating environments, while hybrid architectures represent the fastest-growing product category as operators seek to combine endurance with landing versatility. Surveillance applications command the largest installed base across the region, though delivery services exhibit the steepest adoption trajectory as logistics operators pilot last-mile automation in controlled airspace corridors.
The General Civil Aviation Authority of the UAE, South Africa's Civil Aviation Authority, and Israel's Civil Aviation Authority each enforce distinct certification pathways that fragment product homologation requirements and extend time-to-market for multi-country operators. Military procurement further channels through national offset programs and local content mandates that reshape supplier selection criteria. Stakeholders must monitor the divergence between civilian open-sky frameworks and sovereign defense procurement protocols to align platform development roadmaps with addressable demand pools.
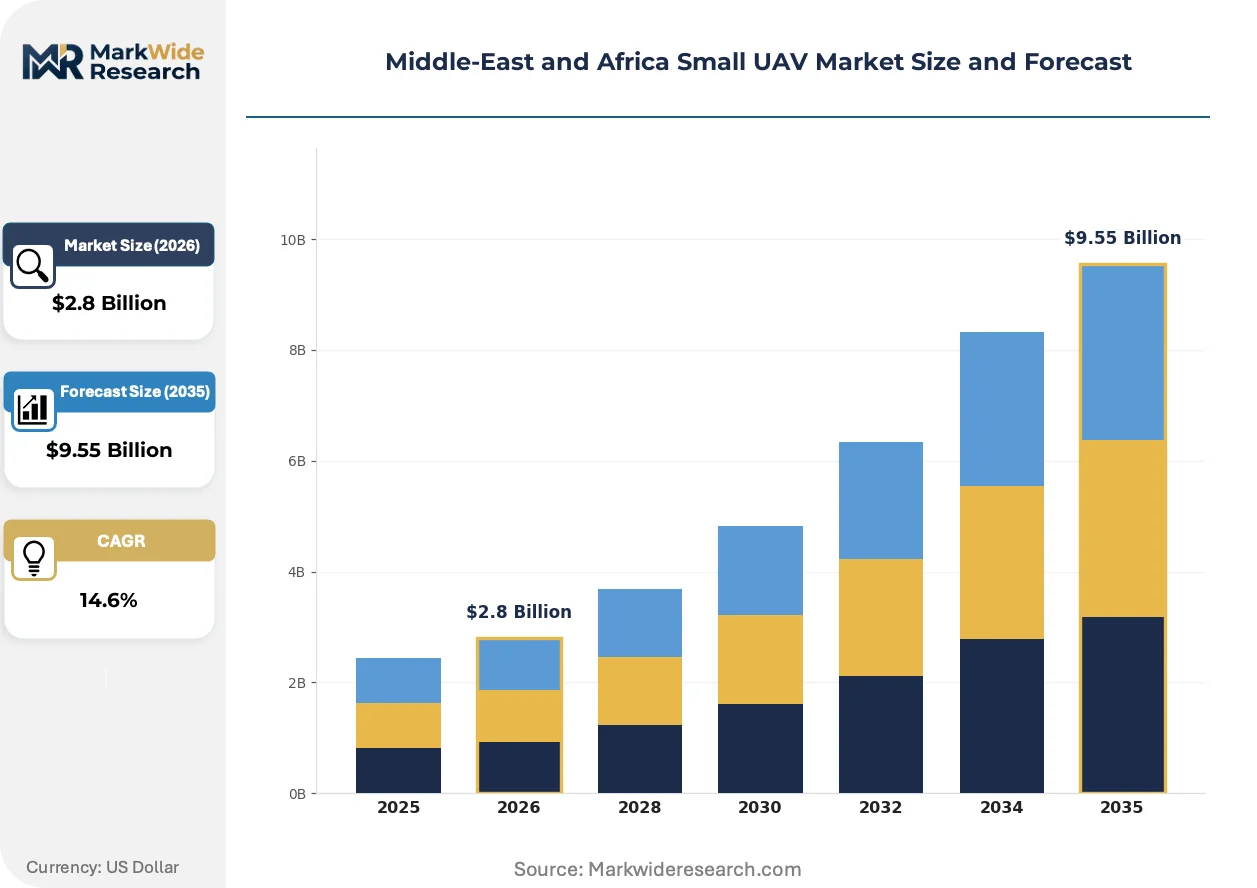
Market Dynamics
Gulf defense ministries are bifurcating procurement between sovereign capability-building and off-the-shelf acquisition, while civilian regulators in South Africa and the UAE open controlled airspace corridors that split market development along parallel military-commercial tracks.
Growth Catalysts
- BVLOS Certification Frameworks:South Africa's Civil Aviation Authority and the UAE's General Civil Aviation Authority have introduced beyond-visual-line-of-sight operating certificates that unlock commercial logistics routes and infrastructure inspection missions.
- Tactical ISR Modernization:Defense ministries across Saudi Arabia, the UAE, and Qatar are accelerating replacement of manned reconnaissance platforms with small unmanned systems for border surveillance and counter-insurgency operations.
- Desert Operating Requirements:Extreme temperature profiles and sand ingestion risks in North African and Gulf environments are driving procurement toward hardened propulsion and sealed avionics architectures.
Market Restraints
- Fragmented Airspace Governance:The divergence between Israel's Civil Aviation Authority certification pathways and GCC regulatory frameworks extends product homologation timelines and multiplies compliance costs for regional operators.
- Import Dependency for Critical Subsystems:Regional production of gyro-stabilized gimbals, encrypted datalinks, and miniaturized thermal sensors remains concentrated in Israeli and Turkish supply chains, exposing buyers to export control volatility.
- Lithium-Polymer Supply Concentration:Battery cell manufacturing for endurance-optimized platforms relies on East Asian suppliers, with shipping disruptions through the Red Sea and Suez Canal creating input cost volatility and delivery uncertainty.
Strategic Opportunities
- Nigerian Agricultural Spraying:Cotton and cocoa cooperatives in Ogun and Oyo states are piloting rotorcraft platforms for precision pesticide application, representing an underpenetrated commercial vertical outside Gulf defense demand.
- EDGE Group Offset Mandates:Emirati local content requirements and technology transfer clauses in defense procurement are creating captive demand for in-country assembly and subsystem integration partnerships.
- Hybrid Architecture Convergence:Fixed-wing endurance combined with multi-rotor landing flexibility is opening mission profiles for pipeline monitoring across Saudi Arabia's Rub' al Khali and offshore platform inspection in Qatar's North Field.
Industry Challenges
- Autonomy Software Certification:National aviation regulators lack harmonized standards for detect-and-avoid algorithms and geofencing reliability, forcing developers to run parallel validation programs for each operating territory.
- RF Spectrum Allocation Contention:Military C-band occupation and commercial 5G expansion in dense urban corridors across Dubai and Tel Aviv are compressing available bandwidth for command-and-control links.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle-East and Africa Small UAV Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $9.55 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed-Wing, Rotorcraft, Hybrid, Nano UAV Application: Agricultural Monitoring, Surveillance, Infrastructure Inspection, Delivery Services Technology: Remote Sensing, GPS Navigation, Communication Systems, Imaging Systems End User: Government, Commercial, Military, Civil |
| Companies Covered | Elbit Systems, Israel Aerospace Industries, DJI, Northrop Grumman Corporation, Textron Systems, Baykar Makina Sanayi ve Ticaret A.S., EDGE Group PJSC, General Atomics, AeroVironment Inc., Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle-East and Africa Small UAV Market Shifts & Advancements
Platform architectures and operating models across the Middle-East and Africa are diverging as defense buyers prioritize sovereign supply chains while commercial operators exploit newly liberalized airspace frameworks.
Swarming coordination protocols and distributed autonomy architectures are fragmenting traditional single-platform procurement models. Israeli and Turkish system integrators are deploying mesh-networked formations of 5-20 kilogram platforms for electronic warfare and saturation reconnaissance missions. This topology is compressing unit cost structures while multiplying sensor coverage per sortie, forcing legacy platform specialists to reconfigure production lines for interoperable node architectures.
The UAE's General Civil Aviation Authority has established segregated drone delivery corridors above Dubai's arterial road network, creating the region's first dedicated low-altitude commercial airway system. This regulatory infrastructure is attracting logistics operators to establish permanent deployment hubs and maintenance stations. E-commerce and pharmaceutical cold-chain distributors are now the fastest-growing civilian buyer segment, displacing ad-hoc surveying contracts as the primary commercial revenue stream.
Defense procurement offices in Riyadh and Abu Dhabi are unbundling traditional platform-plus-support contracts into separate airframe, payload, and sustainment awards. Tier-2 system integrators are capturing maintenance and training revenue previously retained by original equipment manufacturers. This disaggregation is most visible in tactical reconnaissance programs, where Emirati firms now compete for multi-year service contracts independent of initial platform selection.
Middle-East and Africa Small UAV Market Segmentation
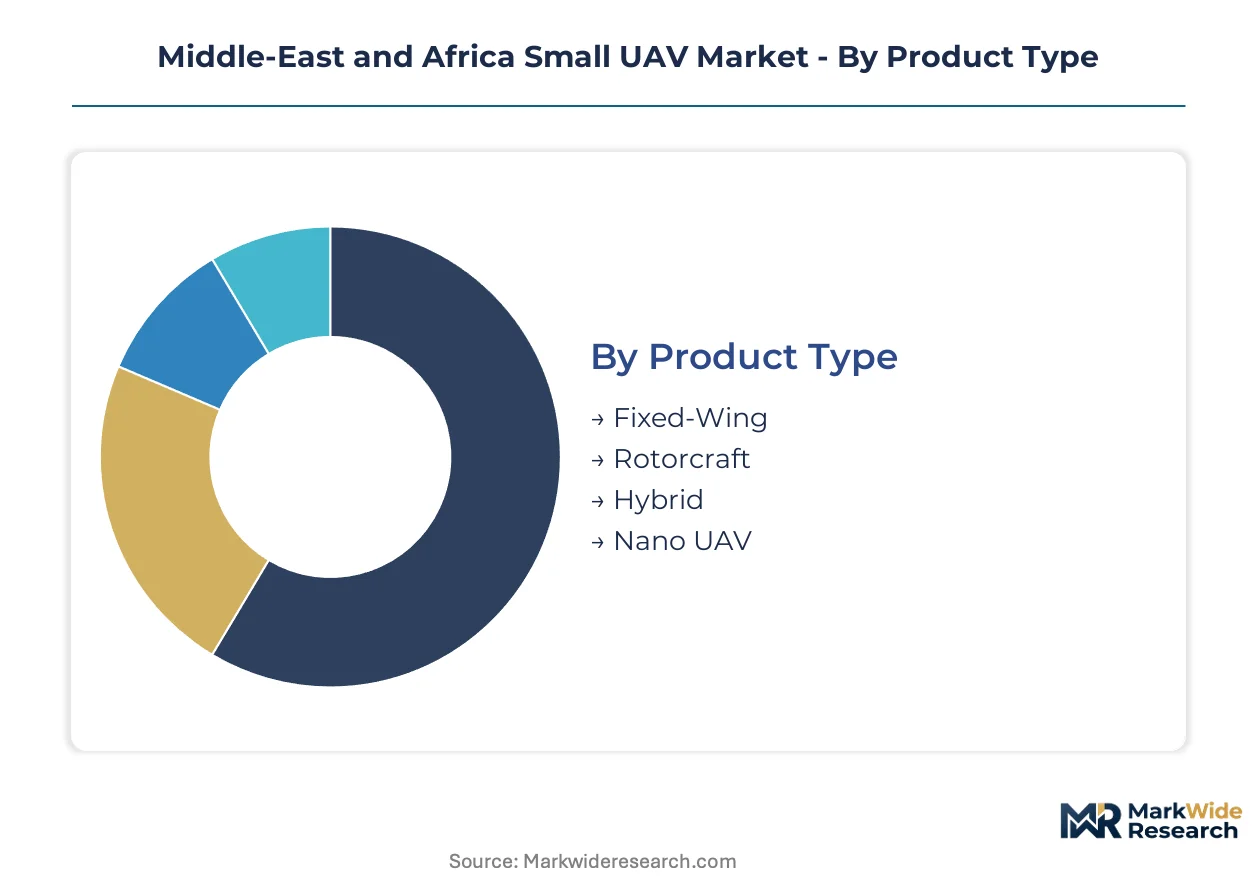
Segmentation in the Middle-East and Africa Small UAV Market reveals how procurement priorities diverge between sovereign defense programs and emerging commercial corridors. Understanding where margin pools concentrate across product architectures and end-use verticals enables suppliers to align development roadmaps with addressable demand.
Product Type:
Margin pools concentrate in platforms that balance endurance with operational flexibility in desert and urban environments.
- Fixed-Wing:Aerodynamic designs maximize range and endurance for pipeline monitoring across Saudi Arabia's Rub' al Khali and border surveillance missions. Procurement volumes concentrate in defense ministries seeking cost-efficient alternatives to manned reconnaissance.
- Rotorcraft:Vertical takeoff capability dominates current procurement across GCC defense ministries and Dubai's delivery corridor operators. Sand ingestion risks and extreme temperature profiles are driving demand toward hardened propulsion architectures with sealed avionics enclosures.
- Hybrid:VTOL transition systems combine fixed-wing endurance with multi-rotor landing precision for offshore platform inspection in Qatar's North Field.
- Nano UAV:Sub-2-kilogram platforms serve urban reconnaissance and confined-space inspection where acoustic signature minimization matters.
The dominant share belongs to Rotorcraft, while Hybrid is closing the gap fastest.
Application:
Volume concentrates in missions where regulatory clarity has unlocked repeatable deployment economics.
- Surveillance:Border monitoring and critical infrastructure protection command the largest installed base across GCC defense ministries. Israeli and Turkish system integrators compete for tactical ISR modernization programs replacing manned reconnaissance platforms.
- Delivery Services:Dubai's segregated drone corridors above arterial road networks attract pharmaceutical cold-chain and e-commerce distributors. The UAE's General Civil Aviation Authority certification framework creates deployment predictability unavailable elsewhere in the region.
- Agricultural Monitoring:Cotton and cocoa cooperatives in Nigeria's Ogun and Oyo states pilot precision spraying applications outside Gulf defense demand.
- Infrastructure Inspection:Power transmission and desalination facility operators adopt rotorcraft platforms for maintenance scheduling in Saudi Arabia and the UAE.
Surveillance retains the largest revenue pool, though Delivery Services is expanding most quickly.
Technology:
Cost structures fragment based on subsystem import dependency and local integration capabilities.
- Imaging Systems:Gyro-stabilized gimbals and miniaturized thermal sensors remain concentrated in Israeli and Turkish supply chains, exposing buyers to export control volatility.
- Communication Systems:Encrypted datalinks face RF spectrum contention between military C-band occupation and commercial 5G expansion in Dubai and Tel Aviv.
- GPS Navigation:Precision positioning infrastructure supports geofencing reliability for beyond-visual-line-of-sight operations in South Africa and the UAE.
- Remote Sensing:Multispectral payloads enable agricultural yield optimization and environmental monitoring across North African deployment zones.
Imaging Systems commands premium pricing, while Communication Systems is gaining share fastest as bandwidth constraints drive upgrade cycles.
End User:
Procurement authority determines contract structure and local content requirements.
- Military:GCC defense ministries unbundle platform-plus-support contracts into separate airframe, payload, and sustainment awards. Emirati firms now compete for multi-year service contracts independent of initial platform selection.
- Government:Civil aviation authorities and interior ministries procure for border management and emergency response with distinct certification pathways from defense procurement.
- Commercial:Logistics operators and agricultural cooperatives drive civilian adoption where BVLOS frameworks exist in South Africa and the UAE.
- Civil:Research institutions and humanitarian organizations deploy platforms for environmental monitoring and disaster assessment with constrained procurement budgets.
Military retains the dominant procurement volume, though Commercial is climbing the fastest as airspace liberalization spreads.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Supply concentrates in Israeli and Turkish production corridors, with system integrators leveraging hardened avionics expertise to capture GCC defense procurement. Regional demand splits between sovereign capability mandates in the Gulf and emerging commercial corridors in Southern Africa.
United Arab Emirates
Abu Dhabi's surveillance modernization programs and Dubai's drone delivery corridors anchor regional procurement volumes. The General Civil Aviation Authority has established segregated low-altitude airways above arterial road networks. EDGE Group PJSC drives in-house platform development from Emirati industrial zones, capturing offset-mandated contracts.
Saudi Arabia
Border surveillance and Rub' al Khali pipeline monitoring missions drive fixed-wing and hybrid platform demand. The General Authority for Military Industries enforces local content requirements that reshape supplier selection criteria. Riyadh-based defense offices unbundle traditional platform-plus-support contracts into separate airframe and sustainment awards.
Israel
Tactical ISR modernization programs sustain medium-altitude system production from established defense corridors. The Civil Aviation Authority enforces certification pathways that diverge from GCC frameworks, extending homologation timelines. Israeli system integrators deploy mesh-networked formations for electronic warfare missions from coastal production clusters.
South Africa
Beyond-visual-line-of-sight operating certificates unlock commercial logistics routes and infrastructure inspection missions outside Gulf defense demand. The Civil Aviation Authority's regulatory framework creates deployment predictability for agricultural and mining applications. Johannesburg and Cape Town operators pilot precision spraying for cotton cooperatives in Ogun and Oyo states.
Turkey
Baykar Makina Sanayi ve Ticaret A.S. competes aggressively on unit economics across GCC tactical reconnaissance tenders. The Presidency of Defense Industries channels export authorization through sovereign technology transfer protocols. Ankara-based production lines supply encrypted datalinks and miniaturized thermal sensors to regional buyers.
Middle-East and Africa Small UAV Market Competitive Landscape
Concentration sits with Israeli and Turkish defense integrators who anchor medium-altitude tactical systems, while Emirati industrial policy cultivates domestic champions through offset mandates and sovereign assembly requirements. The vendor base stratifies across three archetypes: established defense primes with hardened avionics legacies, state-backed national champions capturing local content contracts, and commercial rotorcraft specialists exploiting liberalized airspace corridors. Competitive moves center on unbundling traditional platform-plus-support contracts and securing multi-year sustainment awards independent of initial system selection.
Within the defense prime tier, Elbit Systems and Israel Aerospace Industries exemplify hardened avionics specialists leveraging desert-proven production lines. Baykar Makina Sanayi ve Ticaret A.S. occupies a position as a unit-economics challenger competing across GCC procurement cycles. EDGE Group PJSC anchors the state-backed national champion archetype, capturing Emirati offset-mandated contracts through in-house unmanned platform development.
| Leading Market Players |
|---|
| Elbit Systems |
| Israel Aerospace Industries |
| DJI |
| Northrop Grumman Corporation |
| Textron Systems |
| Baykar Makina Sanayi ve Ticaret A.S. |
| EDGE Group PJSC |
| General Atomics |
| AeroVironment Inc. |
| Others |
Supply & Pricing Matrix
Ninety-day inventory cycles for lithium-polymer battery cells from East Asian suppliers compress pricing power for regional assemblers while amplifying cost volatility when Red Sea shipping disruptions extend lead times. This inventory exposure shapes how UAE-based system integrators negotiate multi-year service contracts with GCC defense ministries.
Pricing Analysis
The General Civil Aviation Authority's BVLOS certification tiers dictate the pricing tier structure across commercial deployments. Three-tier pricing structure across premium, standard, and economy levels separates sovereign-grade encrypted datalinks from commercial rotorcraft kits and entry-level surveying platforms. Price differentiation hinges on certification grade and local content ratios mandated by Emirati offset programs. Cost compression in the economy tier is intensifying because Turkish manufacturers compete aggressively on unit economics for tactical reconnaissance tenders. Agricultural cooperatives in Nigeria exhibit the highest price sensitivity, while Saudi defense procurement offices prioritize performance over unit cost.
Supply Chain Analysis
Just-in-time preferences dominate commercial logistics operators in Dubai's delivery corridors, whereas defense integrators maintain strategic stockpiles of hardened avionics components against export control volatility. Component manufacturing concentrates in Israel, Turkey, and the UAE, with gyro-stabilized gimbals and miniaturized thermal sensors drawing from Israeli production clusters. Supply chain risk centers on single-source vulnerability for encrypted datalinks subject to sovereign technology transfer protocols. Distribution runs through direct defense procurement channels in Riyadh and Abu Dhabi alongside commercial system integrators serving South African agricultural markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a service-attach opportunity where multi-year sustainment contracts and training packages expand faster than hardware unit sales. Recurring revenue from BVLOS-certified maintenance stations in Dubai's drone corridors now exceeds initial platform margins for commercial operators.
For Market Incumbents: Secure multi-year sustainment awards independent of initial platform selection by unbundling traditional contracts into separate airframe and service components. Lock in exclusive maintenance partnerships with the General Civil Aviation Authority's certified corridor operators. Baykar Makina Sanayi ve Ticaret A.S.'s unit-economics aggression threatens margin pools in tactical reconnaissance tenders. Vertical integration into sealed avionics manufacturing insulates against sand-ingestion warranty claims in desert deployments.
For New Entrants and Emerging Players: Differentiate on hybrid VTOL architectures for Qatar's North Field offshore inspection missions where fixed-wing endurance and multi-rotor precision converge. Nigerian agricultural spraying in Ogun and Oyo states represents the most penetrable commercial vertical outside Gulf defense demand. Partner with South Africa's Civil Aviation Authority to establish BVLOS-certified training academies for regional operator certification.
For Investors and Strategic Acquirers: Carve-out targets emerge from defense primes divesting non-core maintenance divisions as procurement offices unbundle platform-plus-support contracts. Long-term viability hinges on capturing recurring service revenue streams that compound across fleet deployments. Tier-2 system integrators with established sovereign offset partnerships in the UAE present the most attractive acquisition archetype. Watch for inflection when Saudi Arabia's General Authority for Military Industries tightens local content thresholds above current levels.
| Strategic Initiative | Industry Significance |
|---|---|
| BVLOS Certification Investment | Unlocks commercial deployment corridors under the General Civil Aviation Authority's segregated airways framework. |
| Local Content Partnership | Satisfies Emirati offset mandates and Saudi General Authority for Military Industries procurement criteria. |
| Hybrid Architecture Development | Captures Qatar's North Field offshore inspection and Saudi Rub' al Khali pipeline monitoring demand. |
| Encrypted Datalink Supply Agreement | Secures sovereign technology transfer protocols from Turkish defense export authorization channels. |
| Multi-Year Sustainment Contract | Generates recurring revenue independent of initial platform selection in unbundled procurement structures. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with defense procurement officers at GCC ministries, commercial logistics operators in Dubai's drone corridors, and agricultural cooperative managers in Nigeria's Ogun state. Secondary validation drew from customs filings tracking lithium-polymer battery imports, General Civil Aviation Authority certification registries, and EDGE Group PJSC offset disclosure documents. Bottom-up fleet deployment estimates triangulated against top-down defense budget allocations.
Across the analysis window, the forecasting framework modeled platform architecture splits, application verticals, technology subsystems, and end-user procurement authority segments. CAGRs were derived from deployment velocity curves and replacement cycle assumptions for tactical reconnaissance platforms. Industry-specific inputs included BVLOS certification penetration rates and sovereign offset compliance ratios in Emirati defense tenders.
Material uncertainties — export control restrictions on encrypted datalinks, Red Sea shipping disruptions affecting battery supply, and regulatory divergence between Israeli and GCC aviation authorities — sit outside the modeled envelope. Forecasts reflect assumptions about sustained defense modernization budgets and commercial airspace liberalization trajectories. Revision becomes warranted when local content thresholds in Saudi procurement guidelines cross thresholds that reshape supplier qualification criteria.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
UAV
Global Aerial Survey Services Market
UAV
Micro Drone Market
UAV
Asia-Pacific Drone Light Shows Market
UAV
Firefighting Drone Market
UAV
Drone Wireless Charging Station Market
UAV
North America Drones Market
UAV
Racing Drone Market
UAV
UAV Drones Market
UAV
Drones Market
UAV
Drone-Based Consulting Services Market
UAV
Tethered Drones Market
UAV
FPV Drone Goggles Market
UAV
Small UAV Market
UAV
Bubble Drone Market
UAV
Aerial Smart Weapons Market
UAV
Drone Tracking Antenna Market