
 Global Hydrocyclone Market | 2026-2036
Global Hydrocyclone Market Size, Share, and Industry Trends Forecast 2026-2036
Global Hydrocyclone Market Outlook
Oil and gas water treatment is consolidating as the fastest-growing end-use vertical for hydrocyclone systems, displacing traditional gravity-based separation in produced water applications. Weir Group leverages its engineering heritage in abrasive materials to dominate high-wear mining installations across South America. TechnipFMC competes through subsea and offshore integration expertise, anchoring its position in deepwater separation packages. FLSmidth specializes in minerals processing workflows, extending its reach into copper and iron ore concentrators where hydrocyclone clusters manage classification duty.
A hydrocyclone is a stationary mechanical separator that uses centrifugal force generated by tangential fluid injection to classify, dewater, or deslime particulate suspensions, with typical operating pressures ranging from 10 to 150 psi depending on cut size requirements. The device contains no moving parts, relying instead on geometric design parameters including vortex finder diameter, spigot aperture, and cone angle to determine separation efficiency. Polyurethane segments lead in abrasion-resistant mining applications where liner longevity determines total cost of ownership, while metal construction dominates high-temperature chemical processing streams where thermal deformation resistance is critical. Water treatment installations represent the fastest-growing end user category, driven by produced water reinjection standards and industrial wastewater reuse mandates that demand reliable solids removal ahead of membrane systems.
EPA discharge limits under the Clean Water Act and REACH substance restrictions shape material selection and liner chemistry for hydrocyclone manufacturers serving North American and European buyers. China's MEE enforces stricter tailings pond standards that accelerate replacement of aging separation trains with higher-efficiency hydrocyclone arrays. Stakeholders must monitor evolving water reuse regulations and assess whether composite material advances can displace incumbent polyurethane and metal configurations in corrosive service environments.
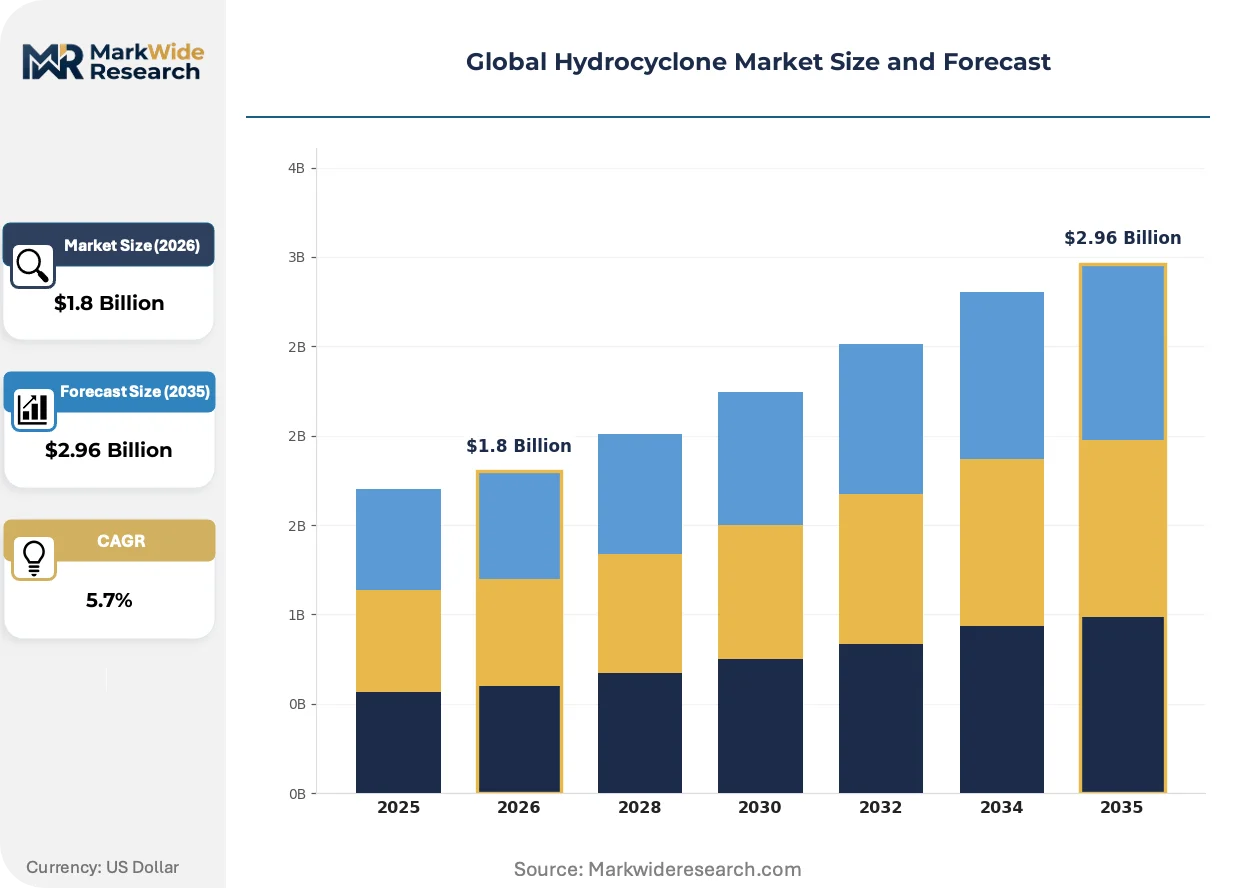
Market Dynamics
Water treatment infrastructure operators are accelerating hydrocyclone replacements ahead of membrane filtration stages, driven by tightening discharge limits that penalize suspended solids carryover into reinjection streams.
Growth Catalysts
- EPA Clean Water Act enforcement:Produced water reinjection standards in the Permian Basin mandate pre-filtration solids removal, forcing operators to upgrade gravity separators with hydrocyclone arrays.
- Copper concentrator expansion:Chilean mining corridors are installing hydrocyclone clusters to handle finer grind sizes in ore flotation circuits.
- Polyurethane liner chemistry:Abrasion-resistant formulations now extend replacement intervals in high-silica slurries, reducing total cost of ownership for desert mining operations.
Market Restraints
- Steel and alloy input volatility:Metal-bodied hydrocyclones for chemical processing face margin pressure from nickel price swings.
- Spigot and vortex finder supply concentration:Precision-machined cone components rely on a narrow German and Japanese supplier base.
- Gravity separator retrofit economics:Existing API separators in mature oilfields create sunk-cost resistance to hydrocyclone adoption.
Strategic Opportunities
- India's coal washery modernization:The country's PLI scheme for mining equipment creates procurement pull for dense medium cyclone upgrades.
- Lithium brine clarification:Salares in Argentina and Chile need solids control ahead of evaporation ponds.
- EU Green Deal water reuse mandates:Industrial clusters in Belgium and the Netherlands face compulsory closed-loop cooling systems.
Industry Challenges
- Cfd modeling talent scarcity:Computational fluid dynamics specialists who can optimize vortex finder geometry remain concentrated in academic and large OEM circles.
- Legacy DCS integration:Hydrocyclone pressure and density sensors must interface with decades-old distributed control systems in petrochemical complexes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Hydrocyclone Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyurethane, Rubber, Metal, Composite End User: Mining, Oil & Gas, Water Treatment, Chemical Processing Installation: Onshore, Offshore, Underground, Above Ground Size: Small, Medium, Large, Extra Large |
| Companies Covered | Schlumberger, TechnipFMC, Weir Group, KSB, Exterran, FLSmidth, Siemens, Multotec Group, Metso Outotec, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Hydrocyclone Market Strategic Shifts
Computational optimization and materials science are compressing hydrocyclone design cycles while regulatory stringency forces tighter integration with downstream membrane trains.
Ceramic matrix composite liners are integrating into high-temperature hydrocyclone applications above 150 degrees Celsius where polyurethane degrades. Chemical processors in Germany and Japan are piloting these configurations in acid leach circuits. The shift is integrating hydrocyclone separation deeper into process flows previously reserved for filtration centrifuges.
REACH substance restrictions on isocyanate-based polyurethane precursors are forcing liner manufacturers to reformulate curing chemistries. The industrial consequence is extended qualification timelines for new mining installations. Australian and Chilean operators are responding by stockpiling approved liner inventories ahead of supplier recertification deadlines.
After-sales service unbundling is separating hydrocyclone maintenance contracts from original equipment purchases. Mining contractors in Western Australia now procure spigot replacement services through third-party specialists rather than OEM service arms. This pattern is most visible in iron ore operations where equipment utilization rates exceed 90 percent and downtime costs dominate vendor selection.
Global Hydrocyclone Market Segmentation
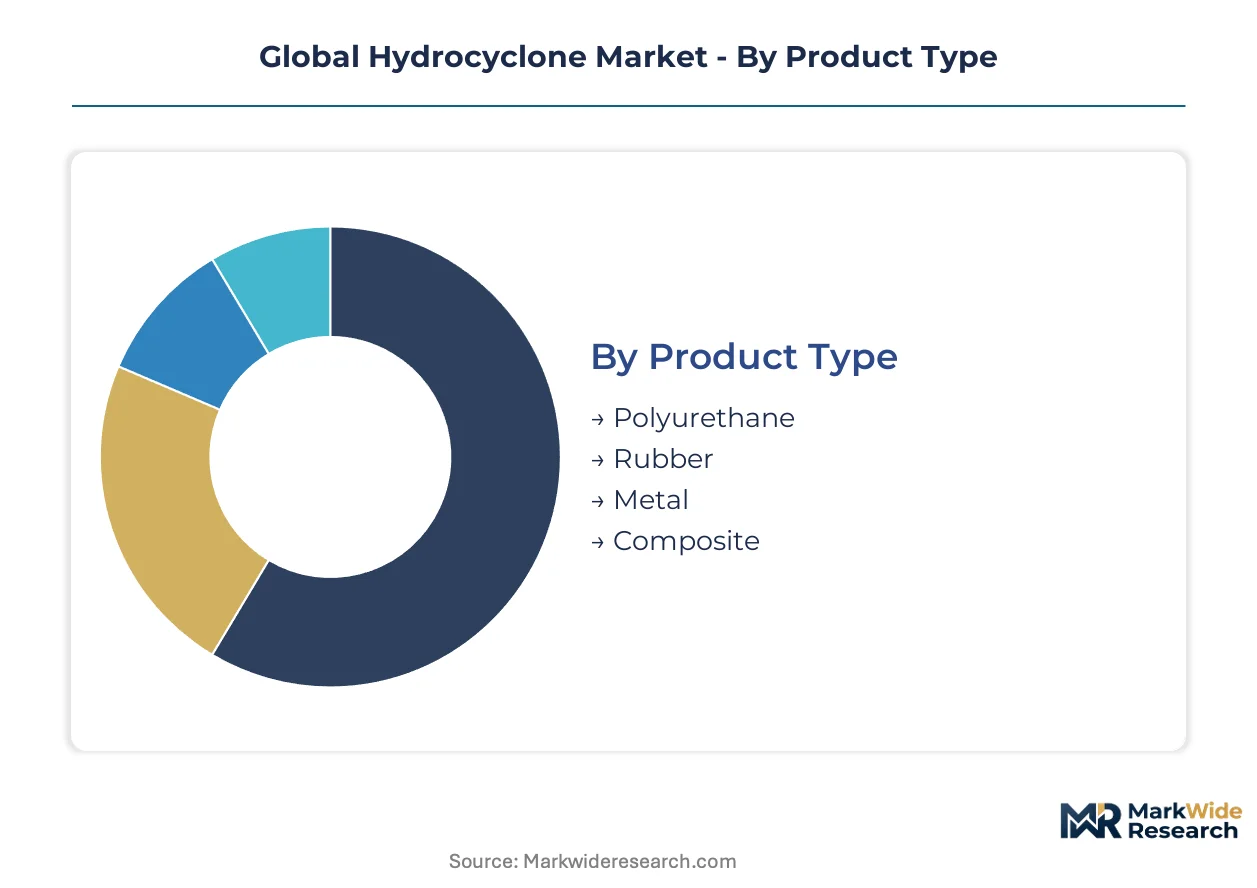
Hydrocyclone procurement patterns diverge sharply across material specifications and operational contexts, with replacement cycles and regulatory compliance timelines driving upgrade decisions more than greenfield installations.
Product Type:
Material selection dictates replacement intervals and total cost of ownership, with abrasive service conditions and chemical exposure profiles determining upgrade urgency across installed bases.
- Polyurethane:Elastomeric liners dominate high-silica mining slurries where abrasion resistance determines service life. Australian iron ore operators and Chilean copper concentrators specify polyurethane segments for hydrocyclone clusters handling grind classification, with liner chemistry now reformulating under REACH isocyanate restrictions.
- Metal:Steel and alloy constructions withstand thermal deformation above 150 degrees Celsius in chemical processing streams. Nickel price volatility compresses margins for metal-bodied units serving acid leach circuits, though thermal resistance keeps this specification locked into high-temperature applications.
- Rubber:Natural and synthetic rubber compounds serve moderate-abrasion duties in water treatment and light mining applications where cost sensitivity outweighs extreme wear resistance.
- Composite:Ceramic matrix and polymer-ceramic hybrids are piloting in German and Japanese chemical plants for corrosive high-temperature service, displacing traditional metal configurations in select acid environments.
Polyurethane sits at the top of the volume ranking, with Composite climbing the fastest as qualification timelines accelerate for high-temperature chemical service.
End User:
Application-specific discharge standards and process integration requirements shape procurement specifications, with water treatment mandates now outpacing traditional mining demand cycles.
- Mining:Copper concentrators in Chile and iron ore operations in Western Australia deploy hydrocyclone clusters for closed-circuit grinding classification. Finer grind size requirements in flotation circuits are forcing upgrades to higher-efficiency cone geometries.
- Water Treatment:Produced water reinjection standards under EPA Clean Water Act enforcement are displacing gravity separators in Permian Basin installations. Pre-membrane solids removal mandates are accelerating hydrocyclone adoption ahead of filtration trains.
- Oil & Gas:Offshore platforms and subsea separation packages specify compact hydrocyclone arrays for produced water treatment, with deepwater integration requirements favoring specialized engineering partnerships.
- Chemical Processing:Acid leach circuits and high-temperature process streams demand corrosion-resistant configurations, with ceramic liner pilots expanding the addressable application set.
Mining sits at the top of the volume ranking, with Water Treatment expanding most quickly as discharge regulations tighten across North American shale plays.
Installation:
Physical deployment context determines structural specifications and maintenance accessibility, with offshore and underground constraints driving specialized engineering requirements.
- Onshore:Standard above-ground installations dominate mining and water treatment applications, with modular skid-mounted packages enabling rapid deployment and relocation.
- Offshore:Platform and subsea installations require compact, corrosion-resistant configurations with remote monitoring capabilities for unmanned operations.
- Underground:Space-constrained mine sites demand low-profile hydrocyclone arrays with simplified maintenance access for liner replacement in confined environments.
- Above Ground:Elevated structures and mezzanine installations in chemical plants and coal washeries require reinforced support framing and spill containment integration.
Onshore sits at the top of the volume ranking, with Offshore gaining share fastest as deepwater production expands and platform water treatment standards tighten.
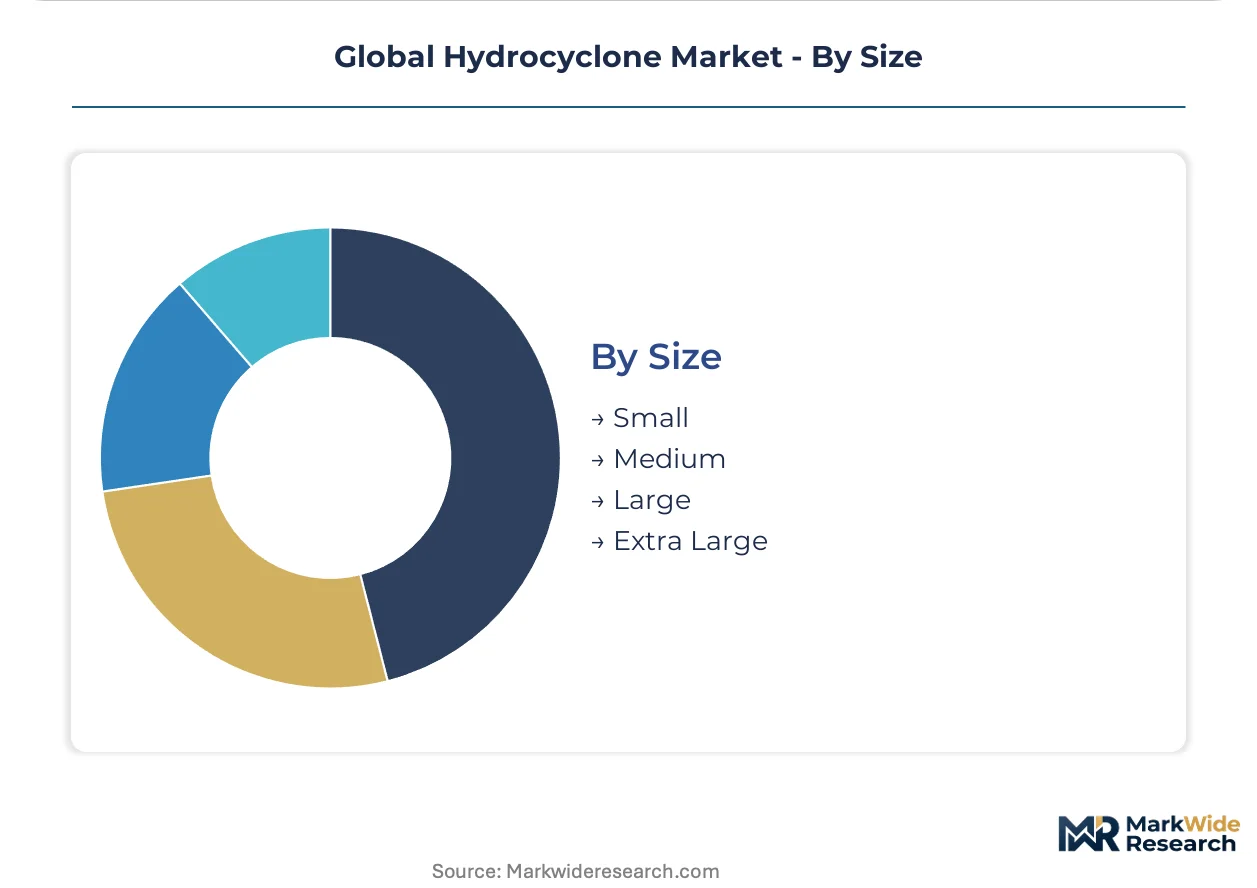
Size:
Throughput requirements and cut size specifications determine diameter selection, with clustering strategies and single-unit economics varying across operational scales.
- Large:High-capacity units handle bulk solids classification in major mining concentrators, with single-unit throughput minimizing cluster complexity for primary grinding circuits.
- Medium:Mid-range diameters balance capital efficiency and operational flexibility across coal washeries and industrial water treatment facilities.
- Small:Compact units serve pilot plants, laboratory applications, and precision classification duties in specialty mineral processing.
- Extra Large:Specialized diameters address extreme throughput requirements in iron ore and copper operations, with custom engineering for site-specific slurry characteristics.
Large sits at the top of the volume ranking, with Small climbing the fastest as modular distributed treatment systems expand in industrial water reuse applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting hydrocyclone procurement toward jurisdictions where tailings compliance costs diverge most sharply. Australian and Chilean mining operators absorb stricter EPA-equivalent standards, while Chinese fabricators exploit cost gaps in liner chemistry reformulation.
Australia
Iron ore concentrators in the Pilbara region deploy hydrocyclone clusters for closed-circuit grinding classification. The country's EPA enforces stringent tailings storage facility guidelines that accelerate replacement of legacy separation trains. Perth-based engineering contractors now specify polyurethane-lined units with extended wear intervals for desert mining conditions.
Chile
Copper flotation circuits in the Atacama Desert demand finer particle classification ahead of solvent extraction. The Ministry of Mining implements progressive tailings dam closure mandates under Law 20.551. Antofagasta and Calama processing corridors are retrofitting hydrocyclone arrays to meet 2025 solids containment deadlines.
China
Mineral processing corridors in Hebei and Shandong provinces drive dense medium cyclone demand for coal washery modernization. The Ministry of Ecology and Environment enforces stricter tailings pond liner standards under revised GB specifications. Tangshan steel slag recovery plants are installing ceramic-composite hydrocyclones for high-temperature slurry handling.
United States
Permian Basin produced water treatment operators replace gravity separators with hydrocyclone arrays ahead of membrane filtration. EPA Clean Water Act enforcement under Section 402 mandates pre-reinjection solids removal below 15 ppm. Midland and Odessa service companies are contracting compact skid-mounted packages for rapid field deployment.
Germany
Chemical processors in the Ruhr industrial cluster pilot ceramic matrix composite liners for acid leach circuits above 150 degrees Celsius. REACH restrictions on isocyanate-based polyurethane precursors force reformulation of elastomeric hydrocyclone components. Leverkusen and Ludwigshafen specialty chemical plants qualify alternative liner chemistries ahead of 2026 recertification deadlines.
Global Hydrocyclone Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with mining procurement favoring established engineering heritage while water treatment opens to modular system integrators. The vendor base concentrates around three strategic archetypes: diversified industrial conglomerates with minerals processing divisions, pure-play separation equipment specialists, and regional fabrication houses serving replacement part demand. M&A activity targets aftermarket service networks, while capacity expansion focuses on polyurethane liner molding facilities in mining-intensive geographies.
Among diversified engineering groups, Weir Group and FLSmidth occupy positions anchored in abrasive materials handling and minerals workflow integration respectively. TechnipFMC represents the subsea and offshore specialization archetype, with deepwater separation package expertise distinguishing its competitive position. These three entities exemplify how engineering heritage in specific operational contexts—mining concentrators, flotation circuits, and platform water treatment—shapes hydrocyclone market segmentation rather than product-level differentiation alone.
| Leading Market Players |
|---|
| Schlumberger |
| TechnipFMC |
| Weir Group |
| KSB |
| Exterran |
| FLSmidth |
| Siemens |
| Multotec Group |
| Metso Outotec |
| Others |
Value Chain & Pricing Dynamics
Ceramic matrix composite liner adoption in German and Japanese chemical plants is compressing cost economics for high-temperature service while simultaneously fragmenting supplier concentration away from traditional polyurethane molding centers. This materials transition forces hydrocyclone manufacturers to dual-source liner chemistries under REACH recertification timelines, reshaping both procurement premiums and geographic supply footprints.
Pricing Analysis
Distributor margins on replacement spigots and vortex finders absorb 15-25 percent of end-user pricing in mining-intensive corridors, with direct-to-OEM volume discounts compressing this spread for cluster procurement above fifty units. Three-tier pricing structure across premium polyurethane formulations, standard rubber compounds, and economy metal-bodied units reflects certification grade and liner longevity guarantees. Cost compression in standard-grade segments is intensifying because Chinese fabricators are qualifying REACH-compliant alternatives ahead of European recertification deadlines. Junior mining contractors in Western Australia exhibit highest price sensitivity, while major copper concentrators in Chile prioritize wear-interval guarantees over unit economics.
Supply Chain Analysis
REACH compliance certification for isocyanate-free polyurethane precursors gates supplier qualification timelines, concentrating approved liner production in Germany, Australia, and select Chinese facilities with pre-certified chemistry pipelines. Raw material feeds draw from nickel alloy foundries in Japan, high-purity alumina ceramic suppliers in Germany, and elastomer polymer streams anchored in Basf and Covestro production networks. Single-source vulnerability concentrates in precision-machined cone components from German and Japanese specialty tooling houses. Distribution runs through mining equipment distributors in Perth and Antofagasta, OEM direct sales for offshore packages, and third-party aftermarket specialists unbundling maintenance contracts in Western Australia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Hydrocyclone Market functions as a stable compounder where regulatory tailwinds on tailings management and produced water standards generate replacement-cycle visibility across decade-long asset lifespans.
For Market Incumbents: Anticipate margin erosion from Chinese liner suppliers achieving REACH equivalency certification by securing backward integration into ceramic matrix composite feedstocks and expanding captive polyurethane molding capacity in Chilean mining corridors. Defend position by embedding pressure and density sensors into legacy DCS architectures, converting equipment sales into recurring instrumentation service contracts. For New Entrants and Emerging Players: Begin with lithium brine clarification arrays in Argentine salares, where evaporation pond solids control demands outpace established vendor coverage and qualification timelines favor nimble engineering partnerships. Target modular skid-mounted packages for Permian Basin water treatment operators seeking rapid deployment ahead of EPA enforcement deadlines, leveraging third-party spigot replacement networks to bypass OEM service infrastructure. For Investors and Strategic Acquirers: Valuations sit cheapest among regional fabrication houses with captive aftermarket service networks in Australian iron ore districts, where utilization rates above ninety percent generate predictable replacement part demand. Five-to-ten year viability rests on exposure to water treatment verticals rather than pure mining cyclicality. Watch for inflection where ceramic liner qualification timelines compress below eighteen months, signaling materials transition acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ceramic Matrix Composites | Captures margin from high-temperature chemical processing applications above 150 degrees Celsius. |
| Long-term Service Contract Unbundling | Separates spigot replacement from OEM sales, matching Western Australian contractor preferences. |
| Joint Venture with Lithium Brine Developers | Positions hydrocyclone arrays ahead of evaporation pond construction in Argentine salares. |
| Capacity Expansion in Chilean Mining Corridors | Localizes polyurethane liner production for copper concentrator clusters under Law 20.551 deadlines. |
| Technology Licensing for Subsea Compact Arrays | Transfers deepwater separation expertise to platform operators facing produced water tightening. |
Study Parameters
Multiple input streams — structured interviews with minerals processing engineers, water treatment procurement leads, and aftermarket service specialists; trade data from Australian Bureau of Statistics and Chilean customs records; and OEM technical documentation — were reconciled through bottom-up installation tracking and top-down market sizing. Primary fieldwork captured replacement cycle dynamics in Pilbara iron ore concentrators and Permian Basin produced water facilities. Secondary validation drew from EPA enforcement guidance, REACH substance restriction updates, and patent filings on vortex finder geometry optimization.
Data-stream reconciliation across product type, end user, installation context, and regional regulatory cluster dimensions anchored volume and value projections throughout the forecast period. CAGRs were derived from segment-level replacement rates and greenfield installation pipelines. Industry-specific inputs included copper grind size trends in Chilean flotation circuits, ceramic liner pilot expansion in German chemical plants, and produced water reinjection standard enforcement trajectories across North American shale plays.
Caveats apply where nickel price volatility, REACH recertification delays, or CFD modeling talent scarcity could materially shift the outlook for high-efficiency cone adoption. Forecasts reflect assumptions on regulatory enforcement consistency and materials qualification timelines. A model refresh is warranted upon material change in EPA Clean Water Act interpretation or ceramic matrix composite liner failure rates in acid leach service.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Mixed Flow Pump Market
Pumps and Control Devices
Steam Jet Ejector Market
Pumps and Control Devices
Wind Powered Water Pumps Market
Pumps and Control Devices
Fire Pump Test Meters Market
Pumps and Control Devices
Single-Use Pump Market
Pumps and Control Devices
Radial Flow Pump Market
Pumps and Control Devices
Global Solar-Powered Pump Market
Pumps and Control Devices
Brine Tanks Market
Pumps and Control Devices
Global Mobile Hydraulic Pump Market
Pumps and Control Devices
Global Diaphragm Pump Market
Pumps and Control Devices
Dewatering Pumps Market
Pumps and Control Devices
Global Solar Water Pump Systems Market
Pumps and Control Devices
Industrial Oil Filter Machine Market
Pumps and Control Devices
Global Vacuum Pump Market
Pumps and Control Devices
Self-Priming Centrifugal Pump Market
Pumps and Control Devices
Spiral Classifier Market