
 Residential Pumps Market | 2026-2036
Residential Pumps Market Size, Share, and Industry Trends Forecast 2026-2036
Residential Pumps Market Analytics
Homeowners replacing aging private well systems is rotating demand toward higher-efficiency electric and solar pump configurations. Grundfos leverages its variable-speed drive technology to capture premium replacement cycles in European markets. Xylem anchors North American distribution through extensive dealer networks serving rural residential water supply. KSB competes on cast-iron construction durability for diaphragm pump segments in Central European heating applications.
Residential pumps are electromechanical devices engineered to move water or fluid media through pressurized distribution networks, typically operating at heads between 10 and 100 meters and constructed from cast iron, stainless steel, or engineered thermoplastics to resist corrosion and cavitation. Centrifugal pumps dominate volume due to simple impeller geometry and lower manufacturing cost, while submersible configurations command margin premiums in deep-well applications where seal integrity determines service life. Solar-powered technology represents the fastest-expanding segment as photovoltaic module cost declines enable off-grid residential water supply in regions with unreliable grid infrastructure.
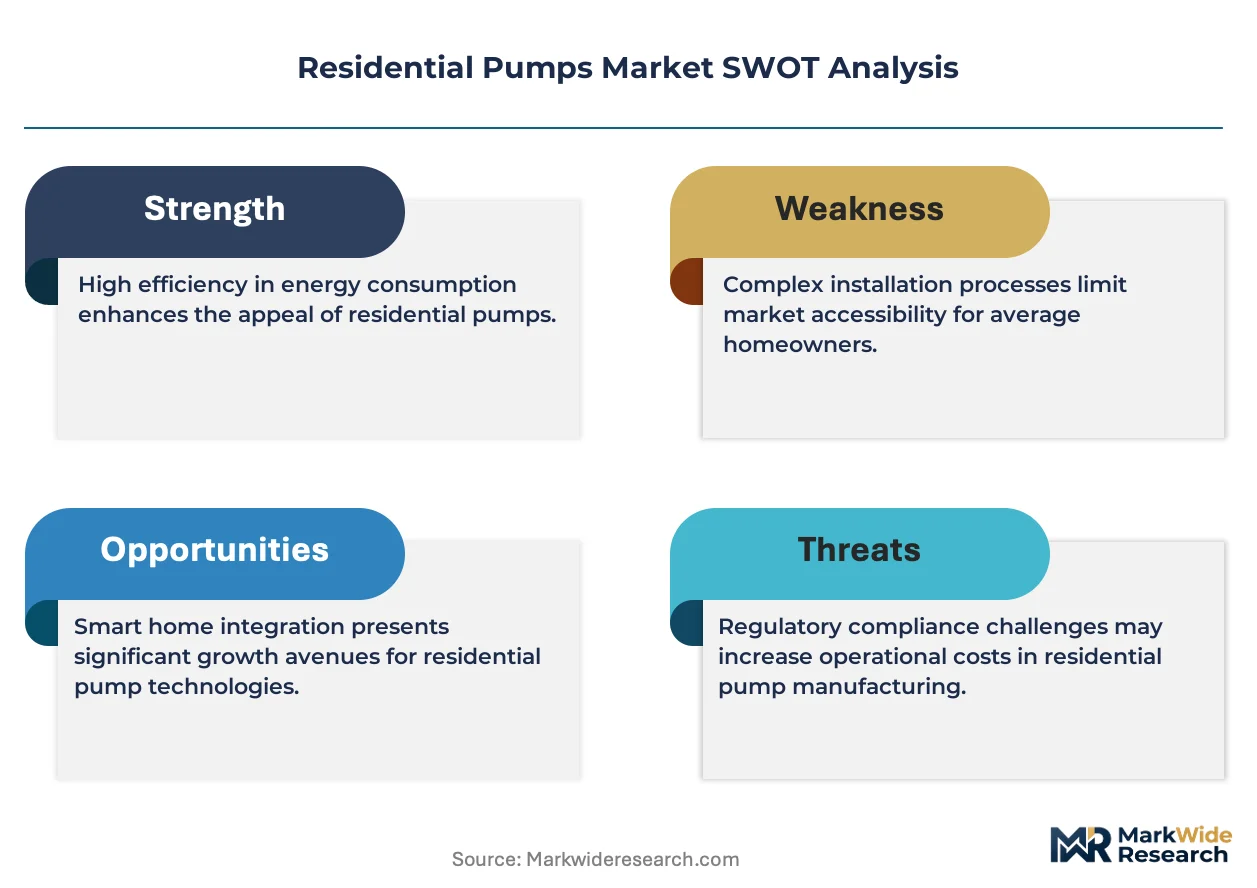
EPA WaterSense certification requirements in the United States and EU Ecodesign regulations administered by national market surveillance authorities mandate minimum hydraulic efficiency thresholds that disqualify legacy single-speed designs from new installation. China's GB standards for pump energy efficiency, enforced by SAMR provincial inspections, create compliance barriers for imported equipment lacking local test laboratory documentation. Stakeholders must monitor evolving multi-jurisdictional efficiency labeling convergence to determine whether regional product customization or unified global platform strategies offer superior returns on compliance investment.
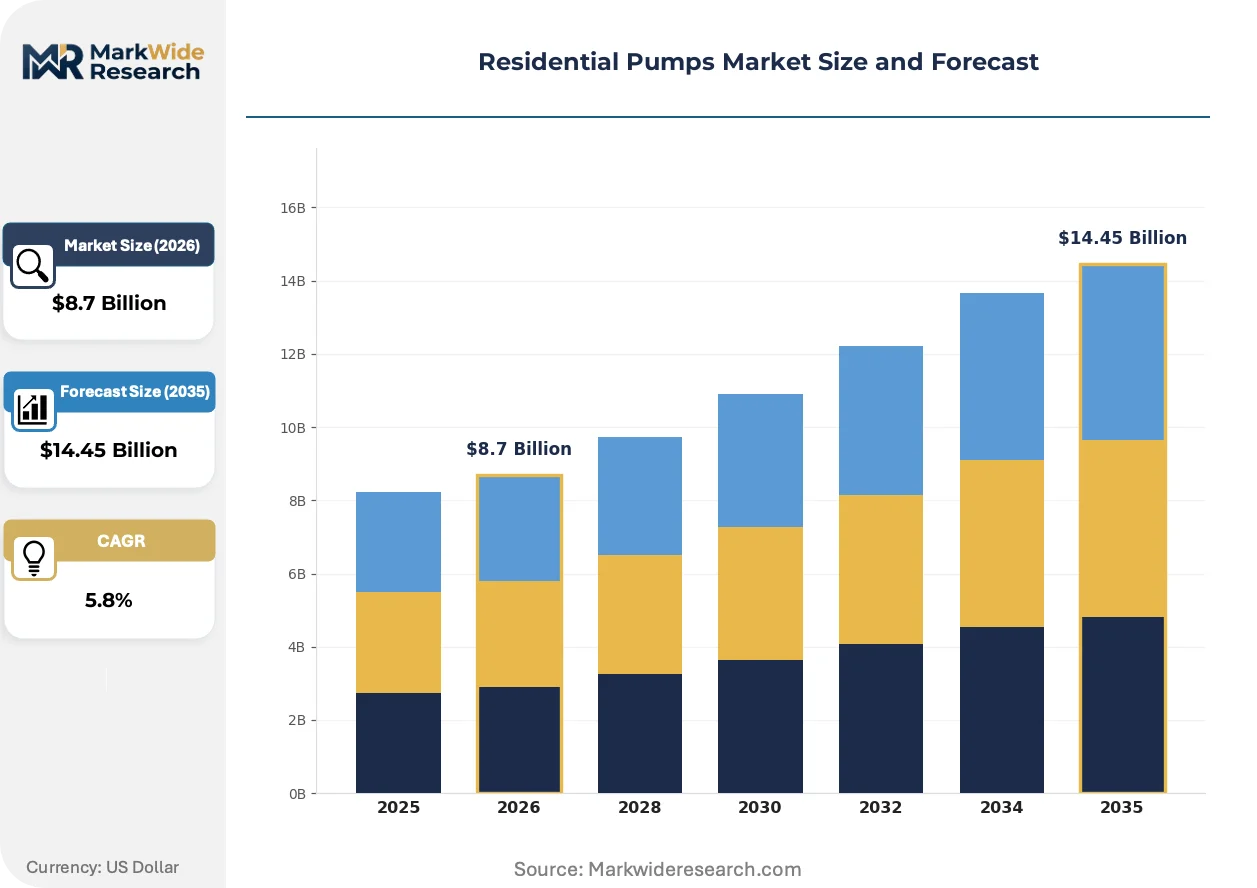
Market Dynamics
Variable-speed drive technology is fragmenting the installed base of single-speed pumps as homeowners prioritize energy cost reduction over upfront capital savings. Regulatory mandates across multiple jurisdictions are disqualifying legacy designs from new installations, compressing replacement cycles and elevating certification documentation to a competitive gate.
Growth Catalysts
- EPA WaterSense Certification:United States federal efficiency thresholds mandate minimum hydraulic performance standards that rotate demand toward premium variable-speed configurations in new residential construction.
- Photovoltaic Cost Decline:Solar-powered pump technology enables off-grid water supply in regions with unreliable electrical infrastructure, expanding addressable markets beyond grid-connected households.
- Tier-Two Chinese Urbanization:Municipal water pressure inconsistencies in rapidly expanding Chinese cities drive diaphragm and booster pump installation in mid-rise residential developments.
Market Restraints
- Cast Iron Input Volatility:Foundry-grade pig iron price swings compress margin stability for manufacturers dependent on traditional pump housing materials.
- Test Laboratory Concentration:SAMR-accredited certification facilities in China create bottleneck risk for imported equipment lacking local documentation.
- Seal Integrity Limitations:Submersible pump service life remains constrained by elastomer degradation in high-mineral groundwater environments.
Strategic Opportunities
- Rural Electrification Gaps:Solar-DC pump convergence targets off-grid residential water access in sub-Saharan African and South Asian markets with unreliable grid infrastructure.
- EU Ecodesign Expansion:Extended product scope under ecodesign regulations creates compliance-driven replacement demand for circulator pumps in Central European heating retrofits.
- Direct-to-Installer Channels:Digital procurement platforms disintermediate traditional wholesale distribution, capturing margin from contractor-specified replacement cycles.
Industry Challenges
- Variable-Speed Programming Expertise:Installer skill gaps in drive parameter configuration delay commissioning and elevate callback rates for smart pump deployments.
- Multi-Jurisdictional Labeling Convergence:Divergent efficiency test protocols between EPA WaterSense, EU Ecodesign, and China's GB standards force product customization or platform fragmentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Residential Pumps Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Submersible, Centrifugal, Diaphragm, Positive Displacement Application: Water Supply, Irrigation, Drainage, Heating Technology: Electric, Solar, Hydraulic, Pneumatic End User: Homeowners, Contractors, Plumbers, Facilities Managers |
| Companies Covered | Xylem, Sulzer, Flowserve Corporation, KSB, Danfoss, Wilo SE, Weir Group, Grundfos, EBARA Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Residential Pumps Market Evolving Landscape
Digital control architectures are displacing electromechanical pressure switches as the primary interface between pump and distribution network. This shift compresses mechanical component counts while elevating firmware and sensor integration to core competitive capabilities.
Permanent magnet synchronous motor technology is fragmenting the fractional horsepower pump segment. These motors deliver 10-15 efficiency points above induction equivalents. European HVAC contractors specify them for circulator retrofits to meet EU Ecodesign minimums. The technology is compressing demand for traditional wound-rotor designs in premium replacement cycles.
EPA WaterSense specifications now mandate on-demand hot water circulation controls that limit energy waste from continuous pump operation. The regulation forces manufacturers to integrate temperature sensors and programmable timers into residential circulator offerings. North American plumbing contractors report specification lock-in for certified models in new construction permitting.
Homeowner specification behavior is rotating toward total-cost-of-ownership calculations that weight electricity consumption over purchase price. Rural well owners in drought-affected US states prioritize variable-speed drives that match output to demand rather than constant-pressure alternatives. This pattern concentrates in agricultural-exurban interface zones where water tables fluctuate seasonally.
Residential Pumps Market Segmentation
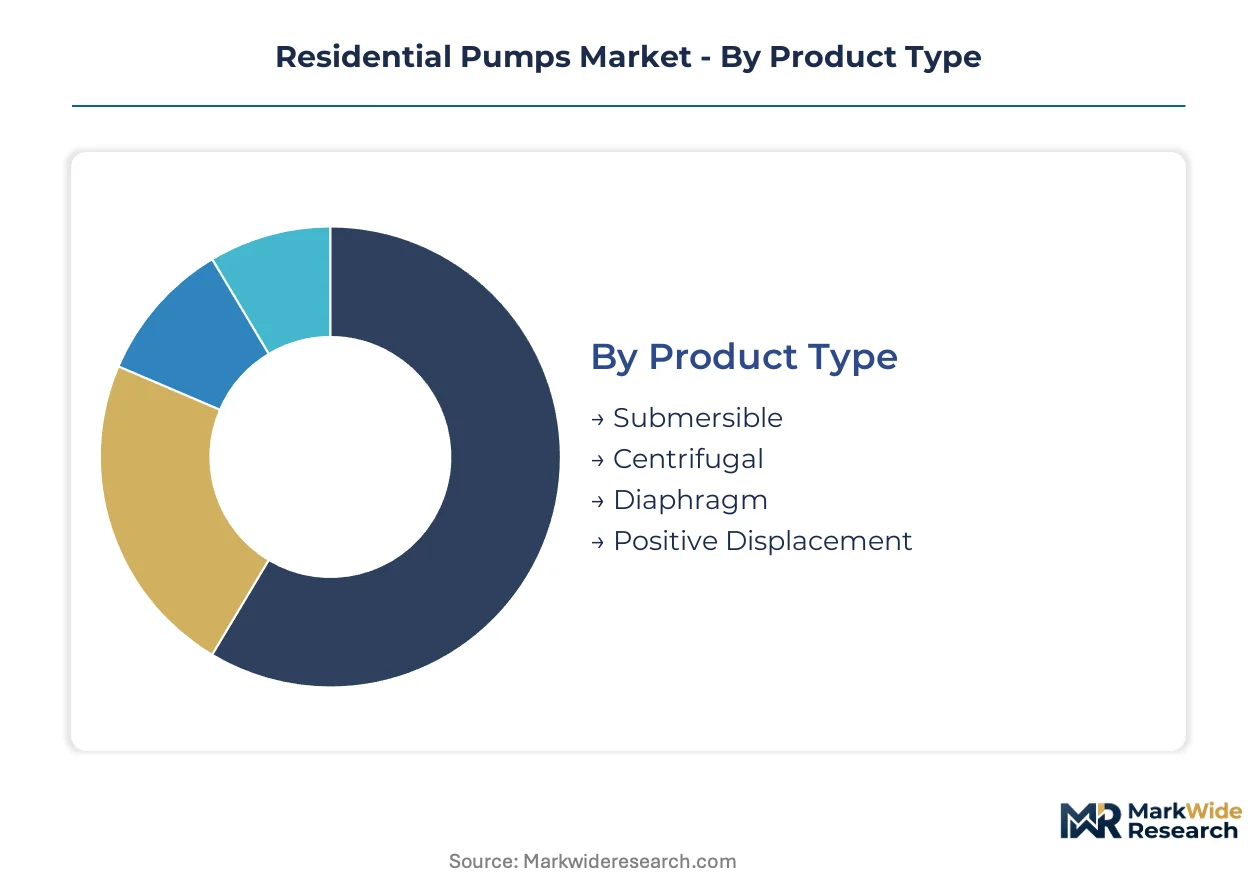
Segmentation in residential pumps reveals distinct procurement patterns across installation contexts and buyer sophistication levels. Contractors prioritize specification reliability over upfront cost, while direct homeowner purchases concentrate on retail-accessible configurations with simplified commissioning requirements.
Product Type:
Submersible and centrifugal configurations dominate export volumes to water-stressed regions, while diaphragm and positive displacement pumps serve concentrated domestic heating and pressure-boosting applications.
- Submersible:Seal-integrated motor designs operate below water level in boreholes and cisterns, eliminating suction lift limitations. Demand concentrates in rural American states with aging private well infrastructure, where seal integrity determines replacement frequency in high-mineral groundwater conditions.
- Centrifugal:Radial flow impeller geometry enables simple manufacturing and maintenance access. Chinese tier-two cities absorb volume for municipal pressure supplementation in mid-rise residential construction, driven by infrastructure lag behind building completion rates.
- Diaphragm:Positive displacement action delivers precise flow control for hydronic heating circuits and chemical dosing applications.
- Positive Displacement:Rotary and reciprocating mechanisms maintain consistent output regardless of system pressure variations in high-viscosity fluid handling.
Centrifugal configurations hold the largest share; momentum sits with submersible technology as deep-well access expands in water-scarce regions.
Application:
Water supply applications command premium pricing through certification requirements, while heating and drainage segments compete on installation simplicity and contractor familiarity.
- Water Supply:Pressure boosting and well extraction systems deliver potable water to residential distribution networks. EPA WaterSense certification mandates in the United States rotate specification toward variable-speed configurations that reduce energy consumption across fluctuating demand profiles.
- Irrigation:Landscape and agricultural-adjacent residential pumping matches output to seasonal water table variations. Solar-DC convergence enables off-grid installation in sub-Saharan African and South Asian markets with unreliable electrical infrastructure, expanding addressable households beyond grid coverage.
- Drainage:Sump and sewage ejector configurations protect below-grade spaces from groundwater intrusion and wastewater backup.
- Heating:Circulator pumps integrate with hydronic distribution systems for space heating and domestic hot water recirculation.
Water supply applications generate the highest absolute revenue; irrigation is expanding most quickly through solar technology cost reductions.
Technology:
Electric configurations retain manufacturing scale advantages, while solar technology fragments procurement patterns through distributed generation integration.
- Electric:Grid-connected induction and permanent magnet motor designs serve established infrastructure markets. EU Ecodesign regulations administered by national market surveillance authorities mandate minimum hydraulic efficiency thresholds that disqualify legacy single-speed designs from new installation in Central European residential construction.
- Solar:Photovoltaic-powered DC pumps eliminate grid dependency for water access in remote locations. China's GB standards for pump energy efficiency, enforced by SAMR provincial inspections, create compliance documentation requirements that favor domestic manufacturers with established test laboratory relationships.
- Hydraulic:Fluid power transmission enables explosion-safe operation and precise speed control in specialized industrial-adjacent residential applications.
- Pneumatic:Compressed air drive systems provide intrinsic safety in volatile atmosphere environments and temporary construction dewatering.
Electric technology maintains dominant installed base; solar configurations show steepest expansion trajectory through photovoltaic module cost decline.
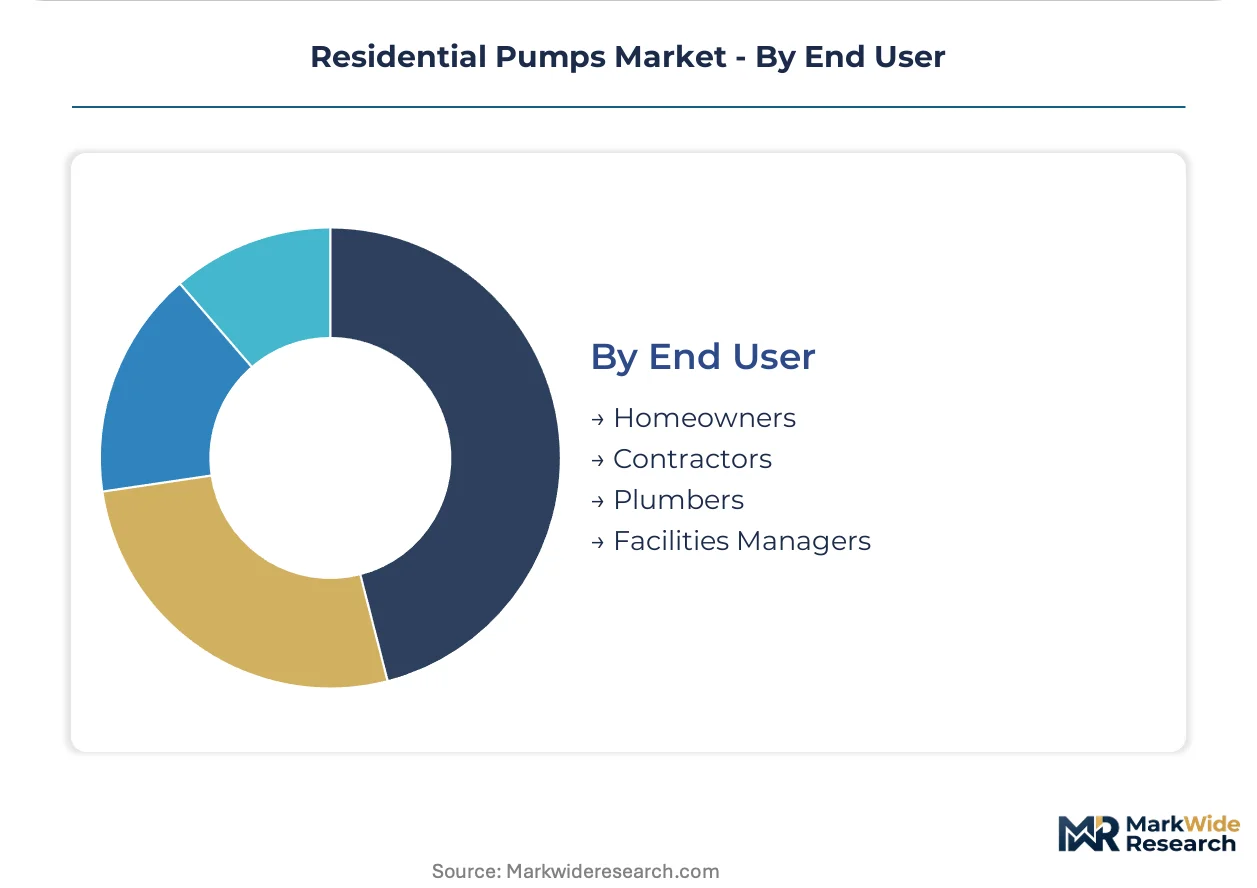
End User:
Contractor and plumber channels concentrate specification authority, while direct homeowner purchases respond to retail availability and total-cost-of-ownership messaging.
- Homeowners:Direct purchasers prioritize visible energy savings and warranty terms over technical specifications. Digital procurement platforms disintermediate traditional wholesale distribution, capturing margin from replacement cycles initiated by consumer research rather than contractor recommendation.
- Contractors:Installation firms specify equipment based on commissioning reliability and callback risk minimization. Skill gaps in variable-speed drive parameter configuration delay project completion and elevate service costs for smart pump deployments in premium residential segments.
- Plumbers:Trade specialists influence replacement decisions through existing relationship networks and emergency service availability.
- Facilities Managers:Multi-unit residential maintenance professionals standardize procurement across property portfolios to reduce spare parts complexity and technician training requirements.
Contractor channels command the largest specification influence; direct homeowner procurement is gaining share fastest through digital platform penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Mississippi River navigation system underwrites North American distribution logistics for pump manufacturers serving agricultural-exurban well replacement cycles. China's high-speed rail network connects Yangtze River Delta production clusters to interior tier-two cities where municipal pressure inconsistencies drive booster pump installation.
United States
Rural electrification gaps in the Great Plains and Southwest rotate demand toward solar-DC configurations for off-grid well access. EPA WaterSense certification mandates in new residential construction disqualify legacy single-speed designs from federal procurement. Texas and Florida concentrate replacement activity where aging private well infrastructure intersects with drought-stressed water tables.
China
Tier-two cities in Sichuan and Hunan provinces absorb centrifugal pump volume as residential construction outpaces municipal infrastructure deployment. SAMR provincial inspections enforce GB energy efficiency standards that create documentation barriers for imported equipment lacking local test laboratory relationships. The Yangtze River Delta manufacturing corridor anchors domestic production capacity for diaphragm pump exports to Central Asian markets.
Germany
EU Ecodesign regulations administered by national market surveillance authorities mandate minimum hydraulic efficiency thresholds for circulator pumps in hydronic heating retrofits. The Ruhr industrial basin hosts foundry capacity for cast-iron pump housings serving Central European replacement cycles. Bavaria's HVAC contractor networks specify permanent magnet synchronous motor technology to meet tightening efficiency minimums.
India
Agricultural-exurban interface zones in Maharashtra and Gujarat drive demand for variable-speed submersible pumps matching output to seasonal water table fluctuations. The country's national pump efficiency regulator enforces star-rating labeling requirements that rotate procurement toward certified configurations. The Delhi-Mumbai Industrial Corridor concentrates distribution infrastructure for solar-powered irrigation pumps targeting off-grid rural electrification gaps.
Brazil
São Paulo's municipal water utility expansion programs drive diaphragm pump installation for pressure boosting in peripheral residential developments. ANVISA-equivalent efficiency protocols for electromechanical equipment create compliance documentation requirements favoring established import channels. The Southeast industrial triangle anchors assembly operations for thermoplastic pump components serving Mercosur distribution networks.
Residential Pumps Market Competitive Landscape
Concentration sits with diversified industrial conglomerates possessing captive foundry capacity and established certification documentation across multiple jurisdictions. The vendor base stratifies between scale-driven manufacturers serving commodity replacement cycles and technology specialists capturing premium efficiency mandates. Two archetypes dominate: integrated pump-motor producers controlling permanent magnet synchronous motor supply chains, and distribution-heavy operators anchoring contractor specification networks. Competitive moves center on test laboratory accreditation expansion to clear multi-jurisdictional compliance barriers, and backward integration into permanent magnet motor manufacturing to capture efficiency regulation premiums.
Among European-based diversified industrials, Grundfos and KSB occupy positions exemplifying integrated technology-platform strategies. Xylem anchors North American market access through extensive dealer network relationships. Wilo SE represents the specialist archetype concentrating on circulator pump efficiency leadership for EU Ecodesign compliance markets.
| Leading Market Players |
|---|
| Xylem |
| Sulzer |
| Flowserve Corporation |
| KSB |
| Danfoss |
| Wilo SE |
| Weir Group |
| Grundfos |
| EBARA Corporation |
| Others |
Value Network & Pricing Analysis
Ninety-day foundry lead times for cast-iron pump housings concentrate procurement leverage with Yangtze River Delta manufacturers, compressing margin flexibility for European and North American assemblers dependent on containerized component flows. This inventory-to-pricing dynamic elevates working capital requirements for distributors serving seasonal replacement cycles in drought-affected American states.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates EPA WaterSense-certified variable-speed configurations from legacy single-speed designs and unbranded import alternatives. Price differentiation rests on certification grade and permanent magnet motor integration, with premium tiers commanding substantial markups for energy efficiency documentation. Cost compression in economy segments is intensifying because Chinese domestic manufacturers exploit GB standard test laboratory relationships to bypass import compliance costs. Rural well owners in agricultural-exurban zones exhibit highest price sensitivity, while HVAC contractors specifying EU Ecodesign-compliant circulators demonstrate lowest elasticity.
Supply Chain Analysis
Strategic stockpile preferences dominate cast-iron input procurement, with major foundries maintaining elevated pig iron inventories to buffer against commodity price volatility. Manufacturing concentration centers on China, Germany, and Italy, with the Yangtze River Delta and Ruhr industrial basin anchoring casting capacity for pump housings and impeller components. Raw material dependencies draw from foundry-grade pig iron, neodymium permanent magnets, and fluoropolymer seal elastomers. Single-source vulnerability concentrates in SAMR-accredited test laboratory access for Chinese market entry. Distribution runs through wholesale plumbing networks and direct-to-installer digital platforms serving contractor specification channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue streams including predictive maintenance subscriptions and extended warranty programs are expanding faster than hardware unit sales, transforming residential pump economics toward recurring-revenue models. This shift elevates firmware-update capabilities and remote diagnostic infrastructure to competitive necessities.
For Market Incumbents: Secure permanent magnet synchronous motor supply chains through backward integration or long-term offtake agreements with rare-earth processors, insulating against efficiency regulation premiums. Fortify EPA WaterSense and EU Ecodesign certification documentation across product platforms to disqualify emerging competitors lacking multi-jurisdictional test laboratory relationships. Defensive positioning must address solar-DC pump specialists targeting rural electrification gaps with photovoltaic-integrated offerings. For New Entrants and Emerging Players: Anchor in sub-Saharan African and South Asian off-grid markets where unreliable grid infrastructure creates addressable demand beyond established electric pump distribution networks. Target solar-powered irrigation configurations for agricultural-exurban households in Maharashtra and Gujarat, exploiting variable-speed programming expertise gaps among incumbent installer networks. Direct-to-installer digital procurement platforms offer the most penetrable go-to-market angle, disintermediating legacy wholesale relationships. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates seeking to divest non-core pump divisions lacking integrated motor technology or digital service capabilities. Long-term viability across the analysis window favors manufacturers controlling permanent magnet motor supply chains and predictive maintenance software stacks. The signal to watch is SAMR accreditation expansion among mid-tier test laboratories, which would lower compliance barriers and intensify price competition in Chinese tier-two city markets.| Strategic Initiative | Industry Significance |
|---|---|
| Permanent Magnet Motor Integration | Captures EU Ecodesign efficiency premiums and displaces legacy induction motor suppliers. |
| Digital Platform Expansion | Direct-to-installer channels disintermediate wholesale distributors and capture replacement cycle margins. |
| Solar-DC Product Line Development | Photovoltaic cost declines enable off-grid market penetration in sub-Saharan Africa and South Asia. |
| Multi-Jurisdictional Certification Investment | EPA WaterSense, EU Ecodesign, and GB standard documentation creates competitive moats against import competitors. |
| Predictive Maintenance Service Launch | Remote diagnostic subscriptions transform hardware transactions into recurring revenue relationships. |
Research Methodology
The analysis maps submersible, centrifugal, diaphragm, and solar-DC pump configurations, each validated through maintenance directors at multi-unit residential properties, plumbing contractor specification leads, and aftermarket service heads at industrial distributors. Primary interviews with plant engineers at foundry operations and procurement teams at OEM pump assemblers combined with secondary validation from customs trade records, EPA WaterSense certification databases, and SAMR inspection disclosures. Bottom-up unit shipment estimates triangulated against top-down energy efficiency regulation impact assessments.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon, with modeled segmentation spanning pump type, application context, technology architecture, and end-user procurement channel. CAGRs were derived from replacement cycle acceleration patterns and regulatory mandate implementation timelines. Industry-specific forecast inputs incorporated photovoltaic module cost decline curves and municipal infrastructure lag indicators in Chinese tier-two cities.
Decision-makers should treat outputs as directional under assumptions of steady regulatory enforcement intensity and no abrupt rare-earth supply disruption; material deviation would warrant model refresh. Revision becomes warranted when SAMR accreditation expansion or permanent magnet motor technology substitution crosses thresholds that alter competitive cost structures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Axial Flow Pump Market
Pumps and Control Devices
Latin America Positive Displacement Pumps Market
Pumps and Control Devices
Europe, Middle-East and Africa Diaphragm Pump Market
Pumps and Control Devices
Water Intake Screens Market
Pumps and Control Devices
Regenerative Turbine Pump Market
Pumps and Control Devices
Split Casing Pump Market
Pumps and Control Devices
Energy-Saving Canned Motor Pump Market
Pumps and Control Devices
Europe Positive Displacement Pumps Market
Pumps and Control Devices
Water Pump Market
Pumps and Control Devices
Volute Pump Market
Pumps and Control Devices
Industrial Pump Control Panels Market
Pumps and Control Devices
Asia Pacific Submersible Pump Market
Pumps and Control Devices
North America Submersible Pumps Market
Pumps and Control Devices
US Industrial Pump Market
Pumps and Control Devices
Air Breathing Hose Market
Pumps and Control Devices
Horizontal Pumping Systems (HPS) Market