
 Vane Pump Market | 2026-2036
Vane Pump Market Size, Share, and Industry Trends Forecast 2026-2036
Vane Pump Market Analysis
REACH compliance is broadening the cost-of-entry calculus for vane pump suppliers serving European industrial channels. Eaton Corporation plc leverages its integrated hydraulics portfolio to sustain specification wins in mobile construction equipment. Bosch Rexroth AG anchors its position through captive manufacturing of precision-machined vanes and port plates. Parker Hannifin Corporation differentiates via distributed service networks that control aftermarket attachment rates across North American fleet operators.
A vane pump is a positive-displacement rotary machine that uses sliding vanes mounted in an eccentric rotor to trap and transport fluid; typical operating pressures range from 7 to 175 bar with displacements from 2 to 400 cm³/rev, serving primarily to convert mechanical energy into controlled hydraulic power for motion and force transmission. Hydraulic vane pumps occupy the dominant volume position owing to their established cost-efficiency in medium-pressure circuits, while rotary vane configurations are gaining traction in vacuum and pneumatic handling systems where oil-free operation matters. Fuel dispensing applications retain stable replacement demand from retail petroleum infrastructure, though pressure boosting installations in process industries represent the margin-accretive growth vector.
The EPA regulates hydraulic fluid spill containment and disposal protocols for mobile equipment operating in US jurisdictions, while ISO 4406 cleanliness standards shape filtration specifications that determine vane life and warranty terms. EMA's machinery safety directives in Europe mandate pressure-relief integration and noise-emission thresholds that redirect R&D spending toward optimized cam-ring profiles and composite vane materials. Stakeholders must weigh energy-efficiency certification requirements against the capital cost of next-generation variable-displacement architectures when refreshing product roadmaps.
Market Dynamics
Energy-efficiency mandates under the EU Green Deal are compressing specification cycles for hydraulic power components across European industrial machinery fleets, forcing accelerated R&D investment in variable-displacement architectures and composite material vane systems.
Growth Catalysts
- REACH compliance expansion:Chemical safety registration requirements for hydraulic fluids are filtering supplier bases toward certified fluid formulators, consolidating procurement relationships for compliant vane pump OEMs serving EU industrial channels.
- Construction equipment fleet renewal:Medium-pressure hydraulic circuits in excavators and wheel loaders continue specifying vane pumps for cost-efficiency, with Germany's precision manufacturing corridor around Stuttgart anchoring demand concentration.
- Rotary vane vacuum systems:Oil-free pneumatic handling configurations are displacing lubricated alternatives in food packaging and semiconductor cleanroom environments where contamination control dictates equipment selection.
Market Restraints
- Aluminum alloy input volatility:Housing and port plate castings face price pressure from primary metal supply constraints, compressing margin buffers for mid-tier pump assemblers without backward integration into foundry operations.
- Cam-ring grinding capacity concentration:Precision surface finishing for hardened steel cam rings concentrates among specialized German and Japanese machine shops, creating bottleneck risk for volume ramp-ups.
- Gear pump substitution in low-pressure circuits:External gear configurations capture specification wins below 70 bar where cost sensitivity outweighs vane pump noise and efficiency advantages.
Strategic Opportunities
- Process industry pressure boosting:Margin-accretive installations in chemical and pharmaceutical continuous processing offer displacement growth beyond replacement-cycle petroleum dispensing applications.
- EU Green Deal efficiency certification:Energy labeling mandates for industrial fluid power systems create specification preference for variable-displacement vane architectures that can demonstrate measurable power consumption reduction.
- Composite vane material convergence:Carbon-fiber reinforced polymer and advanced engineering thermoplastic formulations enable dry-running capability, opening pneumatic and vacuum handling segments previously closed to lubricated pump technologies.
Industry Challenges
- ISO 4406 cleanliness certification timelines:Fluid contamination control standards require extended validation protocols for filtration-integrated pump systems, delaying product launch schedules and freezing working capital in pre-certified inventory.
- Precision grinding skill scarcity:Cam-ring profile geometry and vane slot machining demand specialized metrology and CNC programming expertise that outpaces vocational training pipeline output in traditional manufacturing regions.
- Legacy hydraulic system integration:Variable-displacement vane pumps must interface with existing fixed-displacement circuit architectures without triggering resonance or control instability, complicating retrofit specification engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vane Pump Market |
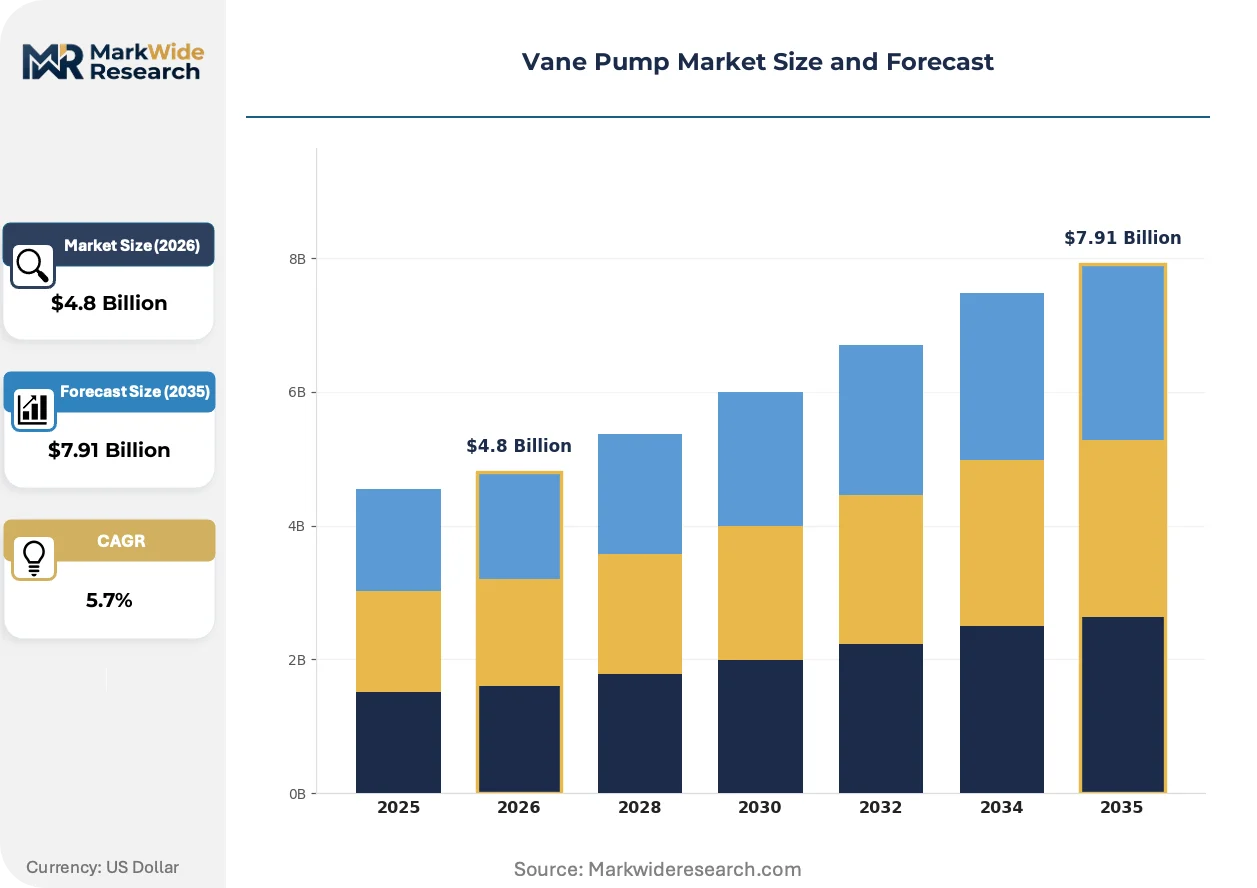
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic Vane, Pneumatic Vane, Rotary Vane, Custom Vane End User: Construction, Automotive, Aerospace, Marine Application: Fluid Transfer, Fuel Dispensing, Pressure Boosting, Lubrication Installation Type: Stationary, Mobile, Integrated, Modular |
| Companies Covered | Eaton Corporation plc, Parker Hannifin Corporation, Bosch Rexroth AG, Danfoss A/S, Moog Inc., Kawasaki Heavy Industries Ltd., Atos Spa, Permco Inc., Bucher Hydraulics GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vane Pump Market Emerging Trajectories
Electrification of mobile equipment powertrains is bifurcating hydraulic system design, with battery-electric architectures demanding higher-efficiency pumps and conventional diesel-electric hybrids maintaining legacy specifications.
Electro-hydraulic variable-displacement control is electrifying pump response characteristics through integrated solenoid valve manifolds and sensor feedback loops. Construction equipment OEMs in Germany and Japan are adopting these architectures for precision boom and bucket control. The technology is electrifying competitive differentiation around energy recovery and load-sensing efficiency metrics that determine battery pack sizing in electric excavators.
The EPA's hydraulic fluid spill containment protocols for mobile equipment are tightening disposal and secondary containment requirements across US jurisdictions. Equipment fleets face operational compliance costs that favor sealed, integrated pump-reservoir units over open-circuit configurations. Mobile construction applications in California and the Pacific Northwest are responding with specification shifts toward cartridge-style vane pumps that minimize connection points and leak pathways.
Service unbundling is fragmenting traditional distributor relationships as fleet operators separate parts procurement from technical support. Independent hydraulic repair shops in the US Midwest and German Ruhr industrial belt are capturing aftermarket volume through specialized vane replacement and cam-ring regrinding capabilities. This pattern concentrates most visibly among North American municipal equipment fleets with captive maintenance workshops seeking direct component sourcing.
Vane Pump Market Segmentation
Vane pump architectures fragment across pressure regimes, contamination sensitivity, and motion control precision requirements. Each segment carries distinct specification cycles, certification burdens, and margin structures that reshape supplier positioning.
Product Type:
Hydraulic vane configurations command the volume tier through established cost positioning in medium-pressure circuits. Rotary and pneumatic variants occupy premium positioning where oil-free operation commands specification preference.
- Hydraulic Vane:Sliding vane assemblies in eccentric rotors handle 7-175 bar operating pressures with displacements from 2-400 cm³/rev. Construction equipment fleets across Germany's Stuttgart manufacturing corridor specify these for boom and bucket circuits where cost-efficiency outweighs absolute efficiency.
- Rotary Vane:Oil-free dry-running architectures using carbon-fiber reinforced polymer vanes penetrate food packaging and semiconductor cleanroom environments. Contamination control mandates in EU pharmaceutical processing drive displacement of lubricated alternatives.
- Pneumatic Vane:Vacuum handling systems for automated material transfer operate below atmospheric pressure with minimal maintenance intervals.
- Custom Vane:Application-specific geometries for aerospace fuel systems and cryogenic fluid transfer carry extended validation timelines.
Mature deployment sits with hydraulic vane in construction and industrial machinery. Newer deployment is concentrated in rotary vane for cleanroom and food-grade pneumatic handling.
End User:
Construction equipment procurement patterns favor standardized medium-pressure architectures with distributed service networks. Aerospace and marine segments demand application-specific engineering with captive aftermarket control.
- Construction:Excavator and wheel loader OEMs specify cartridge-style vane pumps for EPA spill containment compliance. California fleet operators drive specification shifts toward sealed integrated pump-reservoir units.
- Automotive:Transmission lubrication and power steering circuits require compact displacements with NVH-optimized cam-ring profiles.
- Aerospace:Fuel system redundancy and fire-safety certification dominate procurement criteria for commercial aviation platforms.
- Marine:Corrosion-resistant housings and seawater compatibility filtration integrate with propulsion hydraulic systems.
Procurement centralization clusters with construction through fleet-scale purchasing agreements. Fragmented specification engineering characterizes aerospace and marine end users.
Application:
Fluid transfer and lubrication applications sustain replacement-cycle revenue with established technical standards. Pressure boosting installations in continuous process industries carry margin-accretive growth potential.
- Fluid Transfer:General-purpose hydraulic power circuits in industrial machinery specify fixed-displacement vane pumps for cost-sensitive motion control.
- Fuel Dispensing:Retail petroleum infrastructure generates stable aftermarket demand with standardized sealing and corrosion specifications.
- Pressure Boosting:Chemical and pharmaceutical continuous processing demands variable-displacement architectures with energy-efficiency certification under EU Green Deal mandates.
- Lubrication:Machine tool coolant and bearing oil circulation systems prioritize contamination tolerance and extended service intervals.
Replacement-cycle economics dominate fuel dispensing and lubrication. Pressure boosting in process industries represents the steepest expansion trajectory for variable-displacement architectures.
Installation Type:
Stationary industrial installations optimize for efficiency certification and integrated filtration. Mobile equipment specifications prioritize leak containment and connection-point reduction.
- Stationary:Factory-automated hydraulic power units incorporate ISO 4406 cleanliness monitoring with predictive maintenance sensor integration.
- Mobile:Construction and agricultural equipment adopt cartridge-style vane pumps to minimize EPA-regulated spill pathways and secondary containment requirements.
- Integrated:Pump-reservoir-manifold assemblies reduce assembly labor and leak points for OEMs with captive hydraulic system design.
- Modular:Field-replaceable cartridge architectures enable independent hydraulic repair shops to capture aftermarket volume through specialized vane replacement capabilities.
Volume concentration rests with stationary installations in precision manufacturing corridors. Modular configurations are gaining share fastest among municipal equipment fleets with captive maintenance workshops.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's precision manufacturing corridor around Stuttgart operates as the dominant tax-incentive zone for vane pump demand, with EU Green Deal efficiency mandates compressing specification cycles across European industrial machinery fleets.
United States
Construction equipment fleet renewal and EPA spill containment protocols drive specification shifts toward cartridge-style vane pumps. California and Pacific Northwest fleet operators favor sealed integrated pump-reservoir units to minimize leak pathways. Independent hydraulic repair shops in the US Midwest capture aftermarket volume through specialized vane replacement capabilities.
Germany
Stuttgart's precision manufacturing corridor anchors demand concentration for medium-pressure hydraulic circuits in excavators and wheel loaders. EMA machinery safety directives mandate pressure-relief integration and noise-emission thresholds that redirect R&D spending toward optimized cam-ring profiles. Variable-displacement architectures with EU Green Deal efficiency certification gain specification preference in process industries.
Japan
Electro-hydraulic variable-displacement control architectures penetrate construction equipment OEMs seeking precision boom and bucket control. METI industrial efficiency standards shape energy recovery and load-sensing efficiency metrics that determine battery pack sizing in electric excavators. Specialized machine shops in industrial regions concentrate precision surface finishing capacity for hardened steel cam rings.
China
Dual carbon goals and MIIT industrial efficiency mandates accelerate displacement of fixed-displacement architectures in process industry applications. Yangtze River Delta manufacturing clusters absorb volume demand for hydraulic power components serving domestic construction equipment production. National standards for hydraulic fluid cleanliness shape filtration specifications that determine vane life and warranty terms.
India
PLI scheme incentives for construction equipment manufacturing concentrate component sourcing relationships in emerging industrial corridors. BIS standards for hydraulic system safety and efficiency create certification barriers for imported pump assemblies. Domestic fleet operators in Gujarat and Maharashtra prioritize cost-efficient medium-pressure vane configurations for excavator and wheel loader procurement.
Vane Pump Market Vendor Landscape
German producers anchor one tier; US specialists hold specification relationships with North American fleet operators. Japanese fabricators concentrate precision grinding capacity for cam-ring geometries. The vendor base organizes around three strategic archetypes: integrated hydraulics conglomerates with captive component manufacturing, precision-machining specialists controlling critical surface-finishing bottlenecks, and distributed service networks capturing aftermarket attachment rates. Competitive moves concentrate on backward integration into foundry operations for housing castings and strategic partnerships for composite vane material development.
Among diversified hydraulics conglomerates, Eaton Corporation plc and Parker Hannifin Corporation occupy positions representing integrated portfolio breadth and distributed service network scale respectively. Bosch Rexroth AG exemplifies the precision-manufacturing archetype through its captive production of critical machined components. These three entities represent distinct competitive vectors: specification capture through system integration, aftermarket control through geographic coverage, and component-level precision through in-house machining capability.
| Leading Market Players |
|---|
| Eaton Corporation plc |
| Parker Hannifin Corporation |
| Bosch Rexroth AG |
| Danfoss A/S |
| Moog Inc. |
| Kawasaki Heavy Industries Ltd. |
| Atos Spa |
| Permco Inc. |
| Bucher Hydraulics GmbH |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap specialists in Germany's Baden-Württemberg region anchor premium pricing through captive cam-ring grinding capacity, while price discipline erodes among Asian assemblers dependent on spot aluminum alloy markets and outsourced precision machining.
Pricing Analysis
Short lead-time premiums for precision-ground cam rings command 15-25% markups over standard-delivery contracts in Stuttgart's manufacturing corridor. Three-tier pricing structure across premium, standard, and economy levels separates EU Green Deal-certified variable-displacement architectures from fixed-displacement commodity units. Price differentiation hinges on ISO 4406 cleanliness certification tier and backward integration into foundry operations. Cost compression in economy-tier hydraulic vane pumps is intensifying because aluminum alloy input volatility compresses margin buffers for non-integrated assemblers. Fleet operators in India's Gujarat corridor exhibit highest price sensitivity, while German precision manufacturers demonstrate lowest sensitivity due to specification-locked procurement relationships.
Supply Chain Analysis
Workforce scarcity for CNC grinding and precision metrology constrains volume ramp capacity in Germany, Japan, and the US Upper Midwest manufacturing belts. Geographic supply concentration centers on Germany for cam-ring finishing, China for aluminum housing castings, and Japan for electro-hydraulic control manifolds. Raw material dependencies draw from primary aluminum alloys, hardened bearing steel for cam rings, and carbon-fiber reinforced polymers for dry-running vane systems. Single-source vulnerability in specialized German and Japanese machine shops for precision surface finishing creates bottleneck risk during demand surges. Distribution runs through captive OEM supply agreements for construction equipment fleets, with aftermarket volume fragmenting toward independent hydraulic repair shops in the US Midwest and German Ruhr industrial belt.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The vane pump market sits in a technology-transition phase as electro-hydraulic variable-displacement architectures displace fixed-displacement legacy systems in battery-electric construction equipment.
For Market Incumbents: Hedge specification exposure by deepening captive production of precision-machined vanes and port plates before REACH compliance consolidation filters supplier bases. Defend against gear pump substitution in sub-70 bar circuits through ISO 4406 cleanliness certification investment that extends warranty terms and locks fleet procurement relationships. Prioritize R&D allocation toward composite vane material development for dry-running vacuum applications displacing lubricated alternatives in EU pharmaceutical processing. For New Entrants and Emerging Players: The price-point gap between premium German-engineered variable-displacement units and economy-tier Chinese fixed-displacement pumps offers white-space targeting for mid-tier certified alternatives. Municipal equipment fleets with captive maintenance workshops in North America represent the most penetrable segment for modular cartridge architectures enabling independent repair shop aftermarket capture. Go-to-market execution should anchor on direct component sourcing relationships that bypass traditional distributor technical support bundling. For Investors and Strategic Acquirers: EU Green Deal efficiency certification mandates for industrial fluid power systems are the leading indicator that variable-displacement vane pump specialists will command sustained valuation premiums over fixed-displacement commodity producers. Long-term viability across the analysis window favors precision-machining specialists with captive cam-ring grinding capacity and backward integration into aluminum foundry operations. Acquisition target archetype: mid-tier German or Japanese fabricators with stranded precision grinding assets and underutilized composite material R&D pipelines. Signal to monitor: EPA spill containment protocol tightening in California and Pacific Northwest jurisdictions accelerating specification shifts toward sealed integrated pump-reservoir units.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Foundry Operations | Captive aluminum housing production insulates margin buffers from primary metal price volatility. |
| Composite Vane Material Development Partnership | Carbon-fiber reinforced polymer formulations unlock dry-running capability for food packaging cleanrooms. |
| ISO 4406 Cleanliness Certification Investment | Filtration-integrated pump systems extend warranty terms and lock fleet procurement relationships. |
| Electro-Hydraulic Control Architecture Launch | Solenoid valve manifolds with sensor feedback loops capture specification wins in electric excavators. |
| Modular Cartridge Architecture Expansion | Field-replaceable designs enable independent hydraulic repair shops to capture municipal fleet aftermarket volume. |
Methodological Framework
Independent corroboration across OEM procurement executives, aftermarket service heads at fleet operators, precision-machining specialists, and hydraulic fluid formulators underwrites the qualitative findings in this study. Primary interviews with plant engineers at construction equipment manufacturers, maintenance directors at municipal fleet workshops, and technical R&D directors at component suppliers were cross-validated against secondary sources including SEC 10-K filings from diversified hydraulics conglomerates, ECHA REACH registration databases, EPA spill containment enforcement records, and EU Green Deal efficiency certification registries. Bottom-up demand modeling triangulates against top-down industrial machinery production forecasts.
Rate-of-change decomposition across the projection horizon segments volume and value trajectories by product architecture, pressure regime, end-use industry, installation type, and regional regulatory cluster. The analytical framework models displacement growth in process industry pressure boosting against replacement-cycle economics in fuel dispensing infrastructure. CAGRs derive from regression analysis of historical specification cycle compression under efficiency mandates, calibrated to aluminum alloy price elasticity and precision grinding capacity utilization assumptions. Industry-specific forecast inputs incorporate battery-electric construction equipment penetration curves and MIIT industrial efficiency mandate compliance timelines.
Inputs from ECHA REACH databases and EPA enforcement records were available through the study window; gaps in real-time cam-ring grinding capacity utilization data introduce uncertainty bands around volume ramp assumptions. Forecasts reflect documented assumptions regarding EU Green Deal implementation pacing and battery-electric mobile equipment adoption curves. Material deviation in aluminum alloy supply constraints, precision machining skill pipeline output, or REACH compliance enforcement intensity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Subsea Pumps Market
Pumps and Control Devices
Worm Pumps Market
Pumps and Control Devices
Horizontal Pumping Systems (HPS) Market
Pumps and Control Devices
Cryogenic Pump Market
Pumps and Control Devices
Water Intake Screens Market
Pumps and Control Devices
Sealless Magnetic Drive Pump Market
Pumps and Control Devices
Subsea Pump System Market
Pumps and Control Devices
Pump Tubes Market
Pumps and Control Devices
Droplet Separator Market
Pumps and Control Devices
Peristaltic Pumps Market
Pumps and Control Devices
Ultra High Pressure Water Pump Market
Pumps and Control Devices
Twin Screw Pumps Market
Pumps and Control Devices
North America Dispensing Pumps Market
Pumps and Control Devices
Marine Pump Market
Pumps and Control Devices
Domestic Booster Pump Market
Pumps and Control Devices
Europe, Middle-East and Africa Diaphragm Pump Market