
 Fertilizer Injection Pumps Market | 2026-2036
Fertilizer Injection Pumps Market Size, Share, and Industry Trends Forecast 2026-2036
Fertilizer Injection Pumps Market Foresight
The gap between precision-capable injection systems and basic commodity pumps is consolidating around variable rate technology and remote monitoring integration. John Blue Company leverages its diaphragm pump specialization to anchor the North American dealer channel. DOSATRON competes through water-powered proportional dosing that eliminates electrical dependency in remote field conditions.
Fertilizer injection pumps are positive-displacement or centrifugal devices engineered to meter liquid or dissolved nutrients into irrigation lines at controlled ratios, typically operating at pressures between 20 and 150 PSI with flow accuracies within two percent. Diaphragm pumps dominate the installed base for their chemical compatibility and self-priming capability, while electric pumps with remote monitoring represent the fastest-expanding margin pool as farm operators seek real-time dosage verification. Piston pumps sustain demand in high-pressure greenhouse environments where pulsation dampening technology protects delicate root-zone delivery.
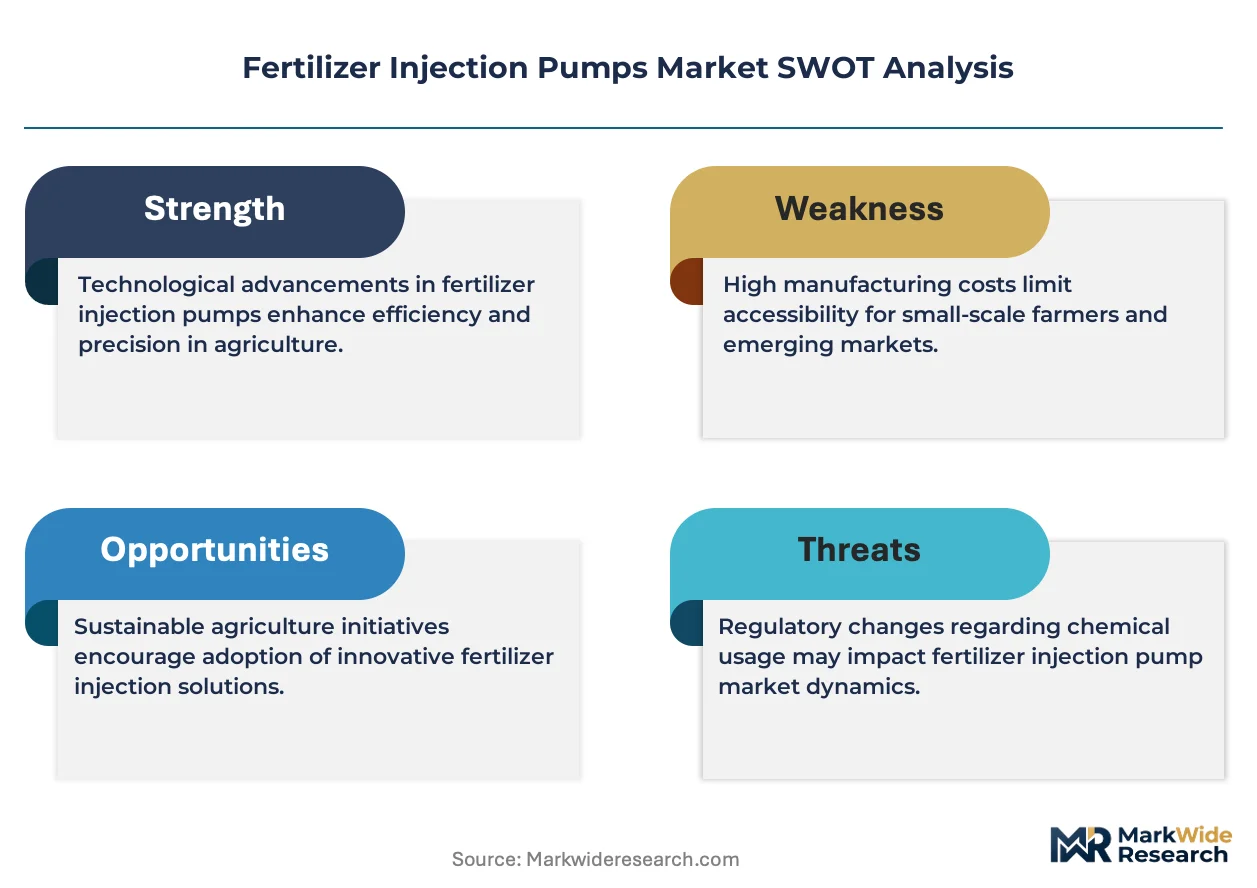
EPA NPDES permits and state-level nutrient management plans in the US constrain discharge thresholds, pushing growers toward closed-loop fertigation with continuous flow verification. The EU F-Gas Regulation and REACH chemical standards shape material selection for seals and housings in European equipment imports. Stakeholders must weigh capital outlay for precision-enabled systems against tightening enforcement timelines for agricultural runoff compliance.
Market Dynamics
Precision agriculture adoption is compressing the competitive landscape around variable-rate dosing systems, with EPA discharge mandates and California's Central Valley water quality enforcement accelerating replacement cycles for legacy equipment.
Growth Catalysts
- Variable Rate Technology:Precision dosing systems enable growers to match nutrient delivery to soil-zone variability, reducing input waste while satisfying nutrient management plan requirements.
- Brazil's Cerrado Expansion:Large-scale soybean and corn operations are retrofitting center-pivot systems with proportional injection equipment to support double-cropping intensity.
- EPA NPDES Permitting:Tightening agricultural runoff thresholds under federal discharge permits are mandating continuous flow verification and closed-loop fertigation infrastructure.
Market Restraints
- Seal Material Costs:Fluoroelastomer and PTFE compound prices fluctuate with petrochemical feedstock volatility, compressing margin on chemical-compatible diaphragm pump assemblies.
- Electronics Supply Concentration:Remote monitoring chipsets and IoT sensor modules concentrate in East Asian contract manufacturers, exposing lead time risk for smart pump configurations.
- High-Pressure Piston Limitations:Pulsation dampening requirements in greenhouse environments add cost and maintenance burden versus diaphragm alternatives.
Strategic Opportunities
- Water-Powered Proportional Dosing:Elimination of electrical dependency opens remote field installations in regions with unreliable grid infrastructure or solar-only power.
- EU F-Gas Material Compliance:REACH and F-Gas Regulation standards for seal and housing materials create premium positioning for certified equipment in European import markets.
- Dealer Channel Digitization:Remote diagnostics integration enables aftermarket service revenue streams and predictive maintenance subscriptions through agricultural equipment distributors.
Industry Challenges
- Precision Agriculture Technician Shortage:Installation and calibration of variable-rate systems requires specialized hydraulics and sensor integration skills that outpace vocational training pipeline output.
- Legacy Irrigation Integration:Retrofitting analog center-pivot and drip systems with digital dosing controls demands custom manifold fabrication and pressure-balancing engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fertilizer Injection Pumps Market |
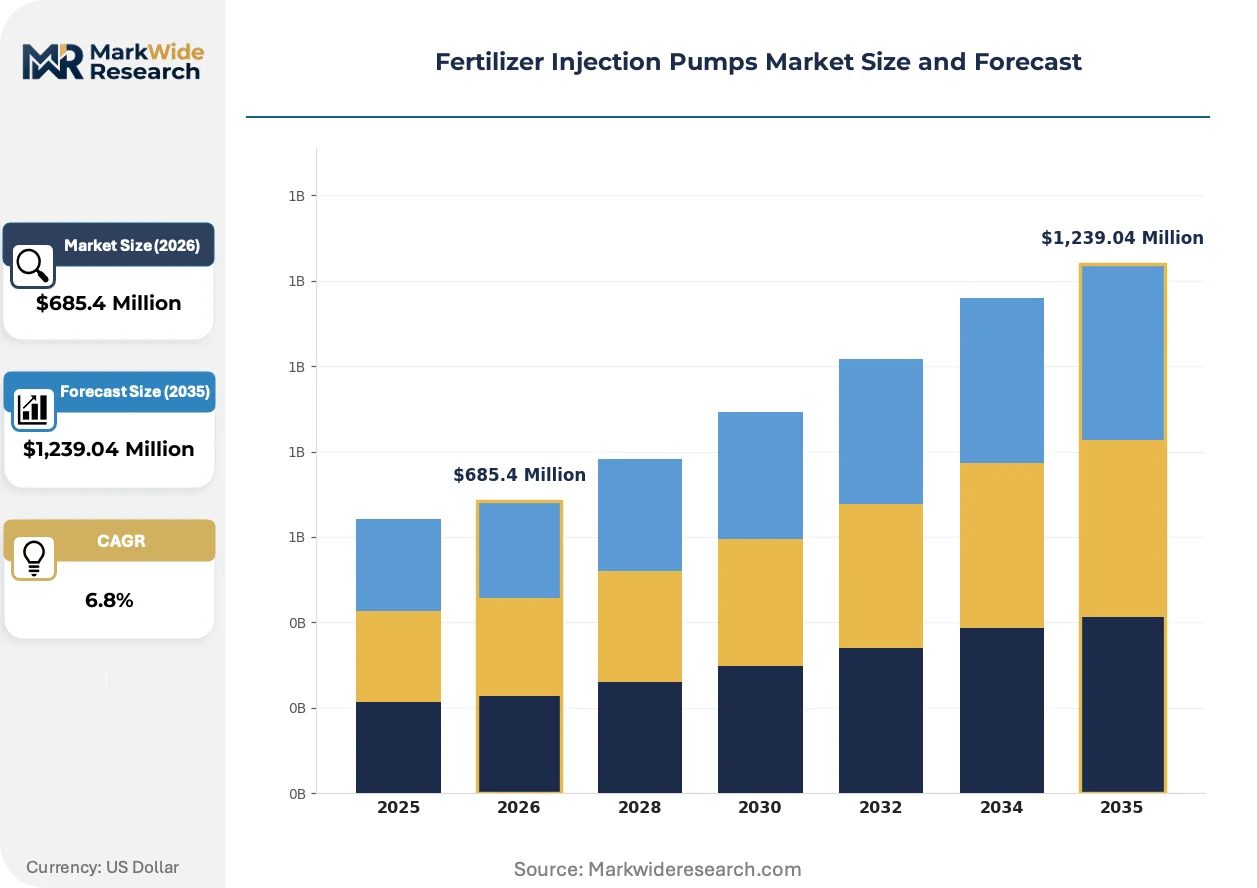
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,239.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diaphragm Pumps, Piston Pumps, Electric Pumps, Hydraulic Pumps Application: Agriculture, Horticulture, Greenhouse, Turf Management Technology: Variable Rate Technology, Continuous Flow, Pulsation Dampening, Remote Monitoring End User: Farmers, Agricultural Cooperatives, Landscape Contractors, Commercial Growers |
| Companies Covered | John Blue Company, DOSATRON, Inject-O-Meter Manufacturing, Ace Pump Corporation, Hebei Lvzhixin Agricultural Equipment Technology, Kothari Group, Ningbo ECOWis Plastic & Electric, Zexel, Amiad Water Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fertilizer Injection Pumps Market Shifts & Advancements
Electrification of dosing control and real-time verification systems is restructuring competitive advantage around data-enabled service models rather than hardware durability alone.
Electric diaphragm pumps with integrated flow sensors and cellular telemetry are overtaking basic mechanical dosing units in commercial vegetable operations. California's Central Valley growers are specifying these systems to satisfy Regional Water Quality Control Board audit requirements. The shift is compressing margins on commodity pump categories while expanding software and verification service revenue pools.
EPA NPDES permit renewal timelines are tightening discharge monitoring and reporting obligations for concentrated animal feeding operations and large produce farms. This regulatory pressure is accelerating capital allocation toward closed-loop fertigation with continuous dosage logging. Greenhouse and hydroponic facilities face the steepest compliance cost escalation due to their year-round discharge profiles.
Service unbundling is fragmenting traditional equipment-plus-installation procurement into separate hardware, calibration, and verification contracting. Large-scale operations in Brazil's Mato Grosso and Goiás states are sourcing pumps through agricultural input distributors while engaging third-party agronomists for dosing protocol design. This split separates capital expenditure from operational expertise, pressuring manufacturers to defend position through aftermarket digital services rather than initial equipment margins.
Fertilizer Injection Pumps Market Segmentation
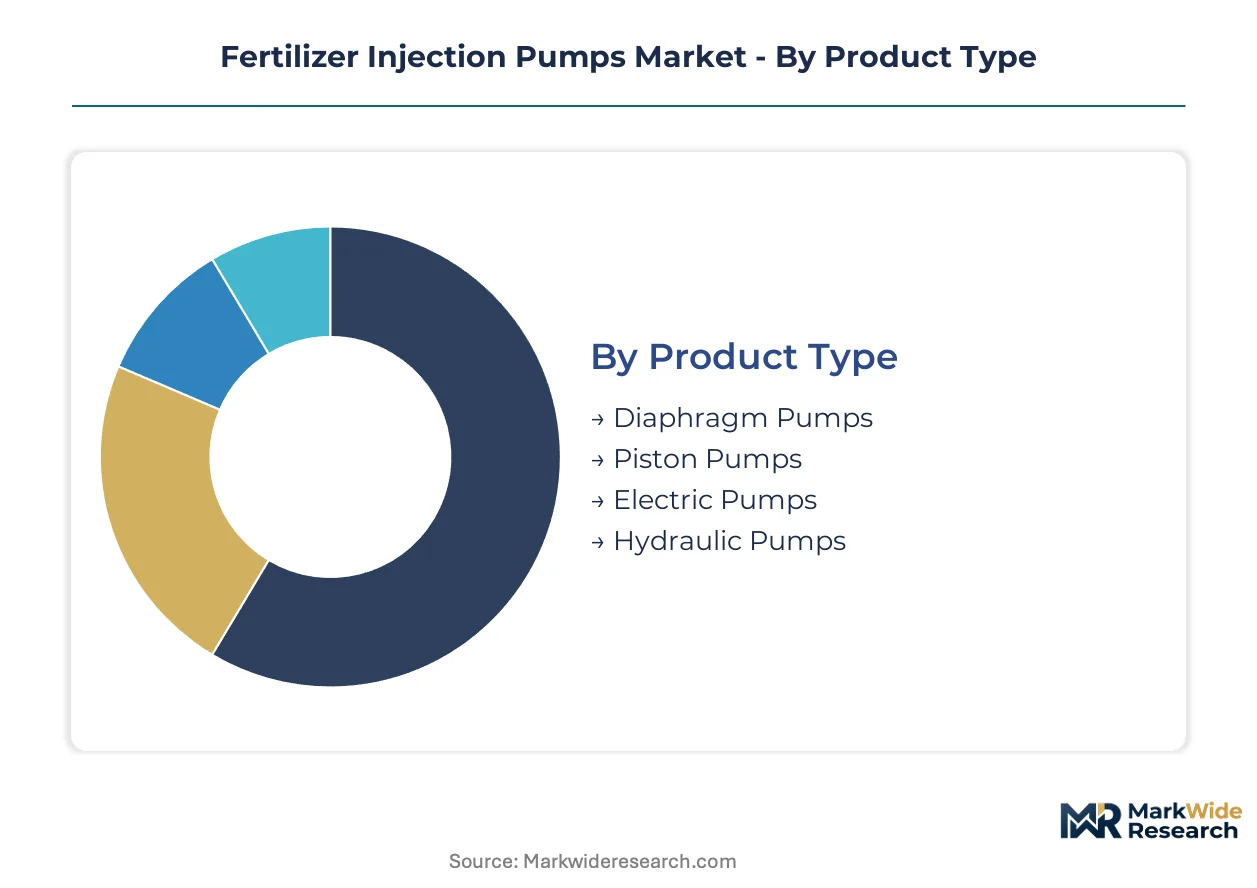
Segmentation in fertilizer injection pumps reveals how equipment specifications diverge across pressure requirements, chemical compatibility needs, and precision agriculture maturity. Understanding these splits enables targeted positioning against regulatory compliance timelines and regional cropping intensities.
Product Type:
Diaphragm pumps anchor the volume base while electric configurations command the premium tier.
- Diaphragm Pumps:Self-priming positive-displacement units with fluoropolymer diaphragms handle corrosive liquid fertilizers and suspended solutions without seal degradation. Demand concentrates in Brazil's Cerrado soybean operations where chemical compatibility and field reliability outweigh precision requirements. EPA NPDES permit holders favor these units for closed-loop systems with basic flow verification.
- Electric Pumps:Integrated variable-frequency drives and flow sensors enable real-time dosage telemetry for audit compliance. California Central Valley vegetable growers specify these systems to satisfy Regional Water Quality Control Board discharge monitoring mandates. Remote diagnostics capability separates premium pricing from commodity diaphragm alternatives.
- Piston Pumps:High-pressure reciprocating designs deliver precise metering for greenhouse drip irrigation with minimal pulsation.
- Hydraulic Pumps:Water-powered proportional dosing eliminates electrical dependency in remote field installations with unreliable grid infrastructure.
Today's leader: Diaphragm Pumps. Tomorrow's challenger: Electric Pumps.
Application:
Commercial cropping intensity determines specification tier, with year-round operations justifying precision capital outlay.
- Agriculture:Large-scale row-crop operations in Brazil's Mato Grosso and Goiás states retrofit center-pivot systems with proportional injection equipment to support soybean-corn double-cropping sequences. Variable-rate dosing reduces input waste across soil-zone variability while satisfying nutrient management plan requirements.
- Greenhouse:Controlled-environment agriculture demands pulsation-dampened delivery to protect delicate root-zone irrigation with continuous discharge profiles triggering the steepest compliance cost escalation under EPA permitting.
- Horticulture:Specialty crop producers balance precision needs against smaller scale through modular injection skids.
- Turf Management:Golf courses and sports fields prioritize uniform coverage over variable-rate capability in high-frequency maintenance cycles.
Agriculture commands installed base volume. Greenhouse drives margin expansion through compliance-linked precision requirements.
Technology:
Hardware-software integration depth separates commodity dosing from value-captured service models.
- Variable Rate Technology:GPS-correlated nutrient application maps enable zone-specific dosing protocols calibrated to soil sampling grids. Large-scale operations engage third-party agronomists for protocol design while sourcing hardware through agricultural input distributors.
- Remote Monitoring:Cellular telemetry modules transmit flow verification data to cloud dashboards for regulatory audit trails. The electronics supply concentration in East Asian contract manufacturers exposes lead time risk for smart pump configurations.
- Continuous Flow:Mechanical proportional dosing maintains steady injection ratios without electronic dependency for basic compliance.
- Pulsation Dampening:Accumulator and flow-smoothing engineering protects delicate greenhouse emitters from pressure spikes.
Variable Rate Technology anchors current replacement cycles. Remote Monitoring captures recurring service revenue streams.
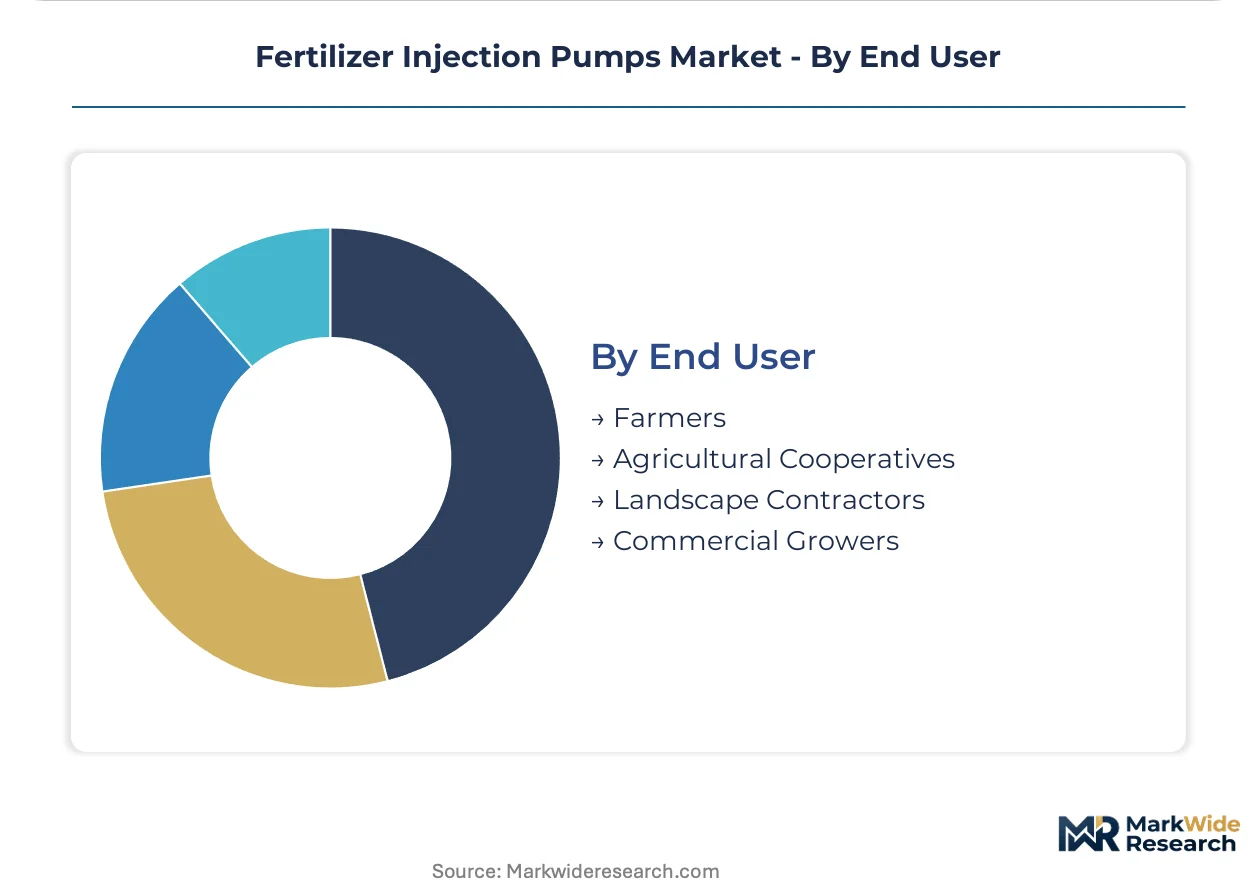
End User:
Capital scale and technical staffing separate self-sufficient operators from distributor-dependent buyers.
- Commercial Growers:California Central Valley vegetable operations specify electric diaphragm pumps with integrated telemetry to satisfy Regional Water Quality Control Board audit requirements. In-house agronomy teams manage calibration and protocol adjustment without third-party dependency.
- Agricultural Cooperatives:Pooled procurement power enables volume discounts on precision-enabled systems shared across member farms with standardized cropping programs.
- Farmers:Owner-operators balance capital constraints against compliance timelines through phased retrofit strategies.
- Landscape Contractors:Mobile fertigation services prioritize portable hydraulic pumps for rapid deployment across multiple client sites.
Commercial Growers lead precision adoption. Agricultural Cooperatives concentrate volume procurement leverage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's Cerrado region commands larger-scale retrofit investments than California's Central Valley, though both anchor regional demand clusters with divergent regulatory timelines and infrastructure maturity.
United States
California Central Valley vegetable growers specify electric diaphragm pumps with integrated telemetry to satisfy Regional Water Quality Control Board audit requirements. EPA NPDES permit renewal timelines tighten discharge monitoring obligations for concentrated animal feeding operations. Fresno and Kern counties concentrate precision-enabled system deployments for year-round compliance-linked replacement cycles.
Brazil
Mato Grosso and Goiás states retrofit center-pivot systems with proportional injection equipment to support soybean-corn double-cropping sequences. ANVISA chemical compatibility standards and state-level environmental licensing shape equipment import specifications. The Cerrado biome anchors large-scale fertigation infrastructure expansion as commercial operators scale nutrient management plan compliance.
China
Shandong Peninsula greenhouse clusters adopt pulsation-dampened piston pumps for high-value protected vegetable production. MEE water quality standards and provincial agricultural non-point source pollution controls tighten discharge thresholds in intensive cropping zones. Yangtze River Delta horticulture operations pilot remote monitoring integration for audit-ready dosage verification.
Germany
Baden-Württemberg specialty crop producers specify REACH-certified seal materials for diaphragm pump assemblies handling corrosive liquid fertilizers. EU F-Gas Regulation and ECHA chemical standards constrain material selection for European equipment certification. Bavaria's precision agriculture equipment distributors integrate predictive maintenance subscriptions for aftermarket service revenue capture.
Australia
Murray-Darling Basin irrigators balance variable-rate dosing adoption against basin plan water recovery targets and salinity management protocols. ISO agricultural water management standards and state-level irrigation modernization programs accelerate legacy system replacement. Queensland broadacre operations concentrate water-powered proportional dosing deployments for grid-independent remote field installations.
Fertilizer Injection Pumps Market Competitive Landscape
Top-tier vendors anchor the precision-enabled electric pump segment, while mid-scale fabricators compete on chemical compatibility and field reliability for commodity diaphragm applications. The competitive structure stratifies across three archetypes: specialized diaphragm pump manufacturers with established dealer networks, water-powered proportional dosing specialists targeting off-grid installations, and diversified irrigation equipment suppliers bundling injection systems with center-pivot packages. Dominant competitive moves include geographic expansion through agricultural input distributor partnerships and technology licensing for remote monitoring module integration.
Within the North American specialist tier, John Blue Company and Inject-O-Meter Manufacturing exemplify diaphragm pump specialization with established channel presence. DOSATRON occupies a position representing water-powered proportional dosing archetypes that eliminate electrical dependency. Hebei Lvzhixin Agricultural Equipment Technology and Ningbo ECOWis Plastic & Electric sit within the Asia-Pacific fabrication cluster serving cost-optimized export demand. Amiad Water Systems represents diversified irrigation equipment suppliers with filtration-adjacent positioning.
| Leading Market Players |
|---|
| John Blue Company |
| DOSATRON |
| Inject-O-Meter Manufacturing |
| Ace Pump Corporation |
| Hebei Lvzhixin Agricultural Equipment Technology |
| Kothari Group |
| Ningbo ECOWis Plastic & Electric |
| Zexel |
| Amiad Water Systems |
| Others |
Supply & Pricing Matrix
EPA NPDES permit compliance gates qualified supply and premium-tier pricing access, as California Central Valley growers specify electric diaphragm pumps with integrated telemetry to satisfy Regional Water Quality Control Board audit requirements. The regulatory enforcement timeline separates certified equipment manufacturers commanding service-bundled pricing from commodity diaphragm pump fabricators competing on field reliability alone.
Pricing Analysis
Capacity additions in China's Shandong Peninsula are reshaping price floors for pulsation-dampened piston pump assemblies serving greenhouse clusters. Three-tier pricing structure across premium, standard, and economy levels differentiates by certification grade and remote monitoring integration, with California commercial growers least price-sensitive due to compliance-linked replacement cycles. Cost compression in commodity diaphragm categories intensifies because Brazilian soybean operators prioritize chemical compatibility over precision features.
Supply Chain Analysis
ANVISA chemical compatibility standards and Brazil's state-level environmental licensing are reshaping sourcing for fluoropolymer seal materials and corrosion-resistant housings. Manufacturing concentrates in China, Germany, and the United States, with raw material dependencies spanning fluoroelastomer compounds, PTFE formulations, and precision-machined pump heads. Single-source vulnerability in East Asian electronics for remote monitoring chipsets exposes lead time risk. Distribution runs through agricultural equipment distributors and input supply cooperatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a margin-expansion story as software-enabled verification services displace commodity hardware pricing, with electric pump configurations capturing recurring revenue streams from compliance-linked audit requirements.
For Market Incumbents: Deepen aftermarket service integration through predictive maintenance subscriptions and remote diagnostics platforms to defend against water-powered proportional dosing specialists targeting off-grid installations. Anchor dealer channel digitization in Brazil's Mato Grosso and Goiás states to capture retrofit demand from double-cropping expansion. Invest in REACH-certified seal material vertical integration to secure European import positioning.
For New Entrants and Emerging Players: Water-powered proportional dosing technology offers a technology-first wedge into Queensland broadacre operations and remote Cerrado field installations with unreliable grid infrastructure. Target agricultural cooperatives with pooled procurement power through volume-tiered pricing and shared calibration service models. Engage third-party agronomists for protocol design partnerships to separate capital expenditure from operational expertise.
For Investors and Strategic Acquirers: Roll-up economics work for specialized diaphragm pump manufacturers with established North American dealer networks because precision agriculture technician shortages create captive installation and calibration revenue streams. Acquire targets with EPA NPDES compliance-linked customer bases and telemetry-enabled product portfolios. Watch for inflection in Brazil's ANVISA enforcement timelines accelerating import specification upgrades.
| Strategic Initiative | Industry Significance |
|---|---|
| Dealer Channel Digitization | Remote diagnostics integration captures predictive maintenance subscriptions through California Central Valley distributors. |
| Backward Integration into Seal Materials | In-house fluoropolymer compound production secures margin against petrochemical feedstock volatility. |
| Water-Powered Proportional Dosing Expansion | Electrical elimination opens Queensland broadacre and remote Brazilian field installations. |
| REACH Certification Investment | ECHA-compliant seal materials enable premium positioning in German specialty crop import markets. |
| Telemetry Module Partnership | Cellular flow verification integration satisfies Regional Water Quality Control Board audit requirements. |
Research Methodology
Coverage spans North America, South America, Europe, and Asia-Pacific, with primary inputs from each region combining interviews with irrigation equipment distributors, precision agriculture technicians, commercial grower operations managers, and aftermarket service heads with secondary validation. Sources include EPA NPDES permit databases, ANVISA chemical compatibility filings, EU ECHA REACH registrations, and customs trade data for pump assembly imports. Bottom-up equipment deployment estimates triangulate against top-down agricultural input spending patterns.
Rate-of-change decomposition separates volume growth from value migration across the projection horizon, modeling segmentation dimensions including pump technology type, application intensity, precision agriculture maturity, and regional regulatory enforcement stage. CAGRs derive from equipment replacement cycle analysis and compliance-linked capital allocation patterns, with forecast inputs spanning center-pivot retrofit rates in Brazil's Cerrado and greenhouse expansion in China's Shandong Peninsula.
The model holds under steady regulatory enforcement timelines; deviation in EPA NPDES permit renewal acceleration or ANVISA import specification tightening would shift replacement cycle assumptions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Global Pumps Market
Pumps and Control Devices
Liquid Dispensing Pump Market
Pumps and Control Devices
Global Positive Displacement (PD) Pumps Market
Pumps and Control Devices
Liquid Ring Vacuum Pump Market
Pumps and Control Devices
Water Pump Market
Pumps and Control Devices
Metering Pump Market
Pumps and Control Devices
Chemical Pump Market
Pumps and Control Devices
Sealless Magnetic Drive Pump Market
Pumps and Control Devices
Regenerative Turbine Pump Market
Pumps and Control Devices
Subsea Pumps Market
Pumps and Control Devices
Rotary Vane Vacuum Pump Market
Pumps and Control Devices
Water Intake Screens Market
Pumps and Control Devices
Progressive Cavity Pump (PCP) Market
Pumps and Control Devices
Fire Pump Test Meters Market
Pumps and Control Devices
Bubble Membrane Disc Diffuser Market
Pumps and Control Devices
Global Diaphragm Pump Market