
 Oil and Gas Pumps Market | 2026-2036
Oil and Gas Pumps Market Size, Share, and Industry Trends Forecast 2026-2036
Oil and Gas Pumps Market Analysis
Aftermarket service revenue is fragmenting across regional service networks and original equipment channels. Flowserve Corporation extends its captive parts logistics through dedicated field service hubs in major production corridors. Baker Hughes Company leverages digital monitoring subscriptions to anchor recurring revenue streams alongside hardware sales. KSB SE & Co. KGaA competes through backward integration into precision casting for critical impeller geometries.
Oil and gas pumps are engineered fluid-handling machines designed to transmit hydrocarbons, produced water, and injection fluids across wellheads, gathering systems, and processing facilities at pressures ranging from atmospheric to above 10,000 psi. Centrifugal pumps dominate high-flow, moderate-head applications in pipeline transfer and booster stations where efficiency curves determine operating economics. Positive displacement pumps sustain niche positions in high-viscosity crude handling and chemical injection systems where precise volumetric delivery outweighs energy efficiency metrics.
API standards, ISO 13709, and NACE material requirements govern corrosion-resistant alloy selection for sour service environments and dictate qualification protocols for offshore installations. EPA methane regulations and BSEE well control mandates are tightening seal reliability standards and driving demand for zero-emission pump designs in environmentally sensitive production zones. Stakeholders must weigh capital intensity against lifecycle service contracts as procurement criteria shift from upfront cost to total cost of ownership.
Market Dynamics
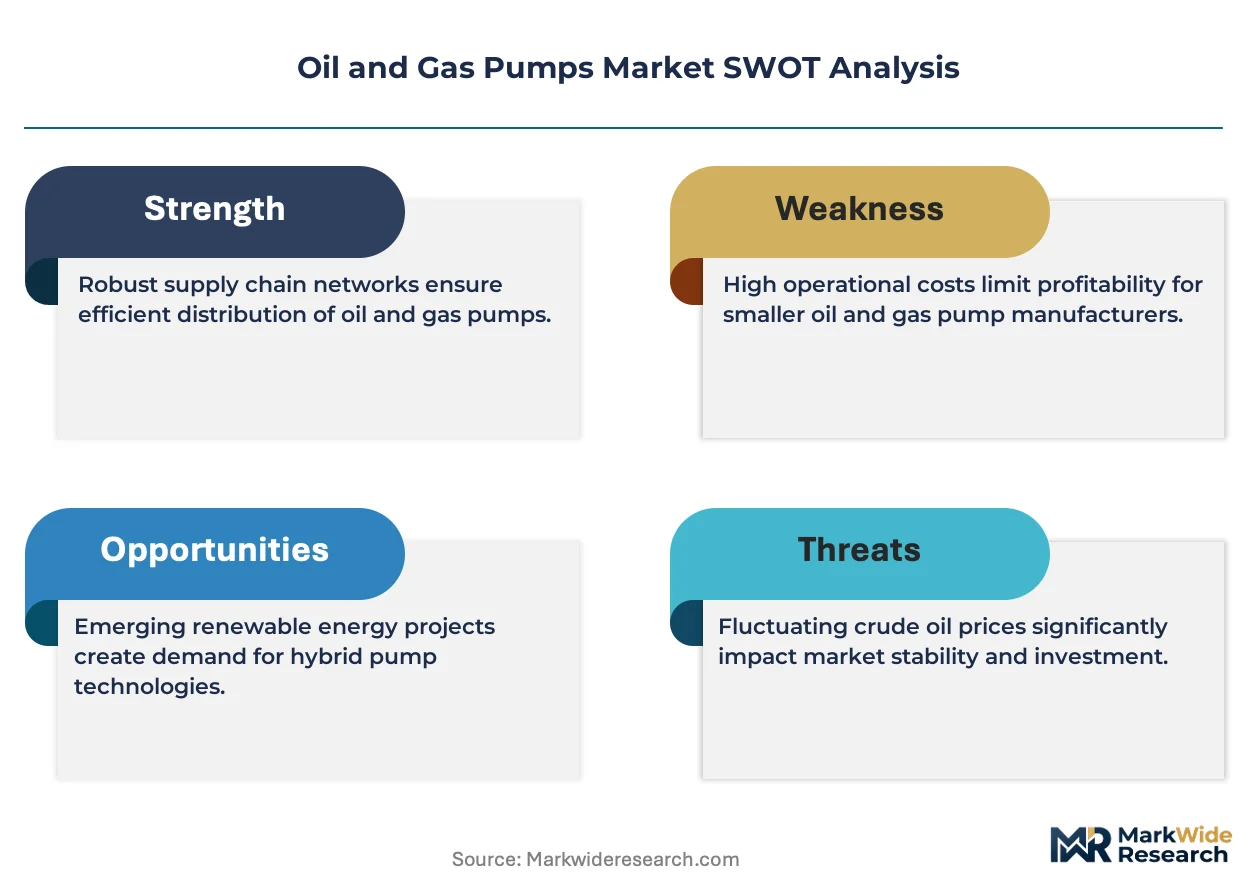
Offshore operators are compressing replacement cycles as saltwater corrosion degrades pump integrity faster than historical baselines, forcing capital reallocation toward corrosion-resistant alloys and predictive maintenance infrastructure.
Growth Catalysts
- EPA methane regulations:Zero-emission seal mandates in US production zones are accelerating demand for magnetic drive and canned motor pump architectures.
- Permian Basin drilling intensity:Sustained rig activity in West Texas and southeastern New Mexico sustains above-average spare parts consumption and field service demand.
- API 610 material certification:Tightened alloy traceability requirements are locking in premium supplier relationships and raising barriers to commodity entrants.
Market Restraints
- Nickel alloy cost volatility:Super duplex and Inconel price swings compress margin predictability for sour service pump manufacturers.
- Subsea equipment supplier concentration:Limited qualified foundries for high-pressure impeller castings create single-source vulnerabilities in Norway and Brazil offshore clusters.
- Positive displacement efficiency ceiling:Progressing cavity pumps face thermodynamic limits above 500 horsepower that centrifugal designs circumvent.
Strategic Opportunities
- Digital twin integration:Real-time vibration and temperature monitoring fused with physics-based modeling enables predictive failure windows and service contract anchoring.
- CCUS injection applications:Carbon capture projects in Texas and Alberta require high-pressure reciprocating pumps for supercritical CO2 handling at 2,000+ psi.
- Hydrogen blending infrastructure:Pipeline retrofit programs in Germany and the Netherlands create demand for modified centrifugal seals rated for embrittlement-resistant service.
Industry Challenges
- Weld procedure qualification bottlenecks:ASME Section IX and API 1104 certification delays for exotic alloy repairs extend field downtime in remote offshore locations.
- Legacy SCADA integration friction:Brownfield installations with 1990s control architectures resist seamless connectivity with cloud-based pump monitoring platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oil and Gas Pumps Market |
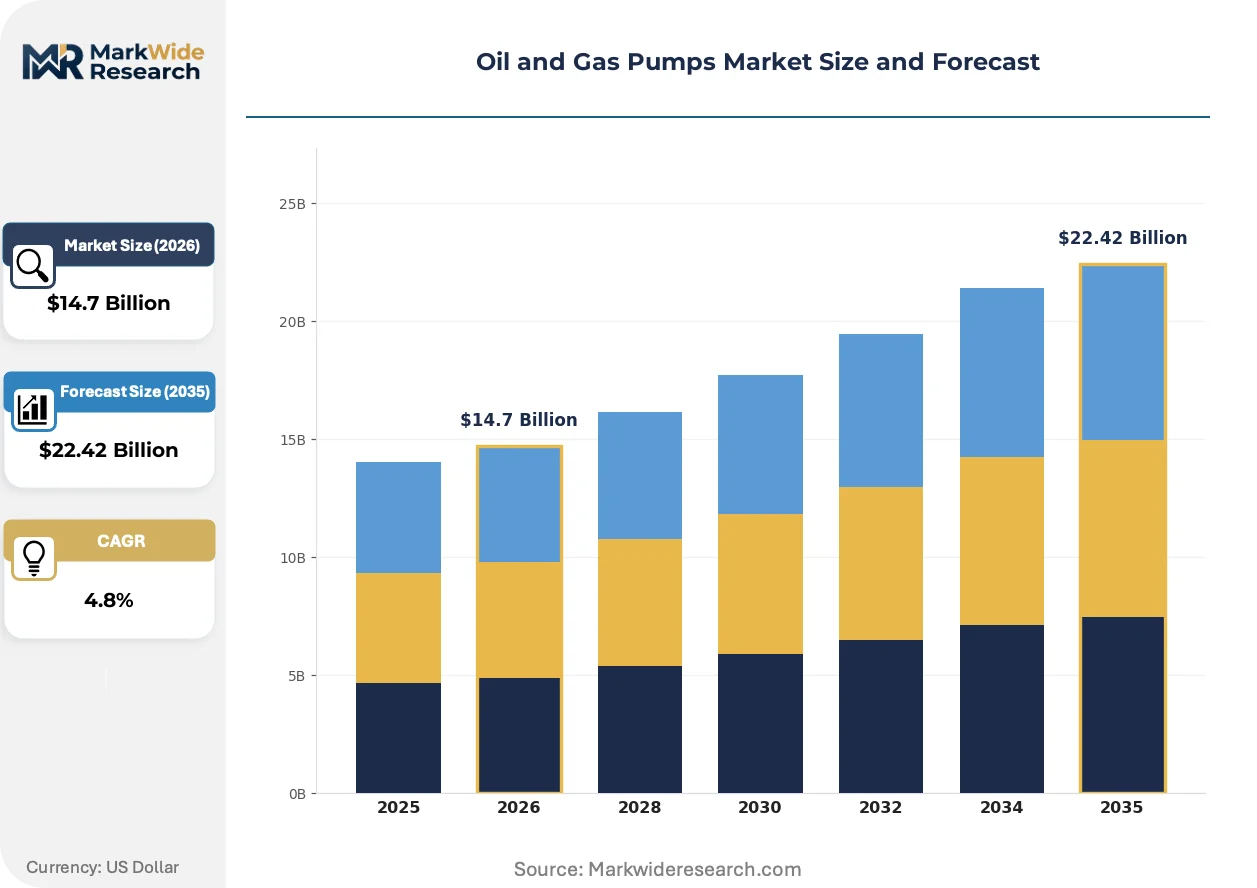
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $22.42 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Centrifugal Pumps, Positive Displacement Pumps, Submersible Pumps, Diaphragm Pumps Technology: Electric, Hydraulic, Pneumatic, Mechanical Installation: Onshore, Offshore, Mobile, Fixed End User: Exploration, Production, Refining, Distribution |
| Companies Covered | Xylem Inc., NETZSCH Pumps & Systems, Flowserve Corporation, Weir Group Plc, ITT Inc., Sulzer Ltd., Alfa Laval AB, Baker Hughes Company, KSB SE & Co. KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oil and Gas Pumps Market Emerging Trajectories
Additive manufacturing of impeller geometries is collapsing lead times for custom hydraulic profiles while enabling internal channel designs impossible with conventional five-axis machining.
Topology-optimized titanium impellers produced via electron beam melting are rendering obsolete traditionally cast stainless steel components in high-solids produced water applications. North Sea operators are qualifying these parts for 10,000-hour run intervals. The shift is compressing spare parts inventory requirements and relocating value capture toward design software and powder metallurgy suppliers.
BSEE well control mandates are tightening blowout preventer integration standards with subsea boosting systems, forcing pump OEMs to recertify hydraulic interfaces under API 16D protocols. Gulf of Mexico producers face 18-month recertification timelines that delay field development schedules. Equipment suppliers are responding by pre-qualifying integrated pump-BOP skids to accelerate permitting.
Aftermarket service unbundling is fragmenting traditional OEM revenue streams as independent repair shops capture 40% of mechanical seal replacement work in mature US onshore basins. Digital parts catalogs and 3D scanning for reverse engineering are displacing manufacturer-controlled spare parts monopolies. The Permian Basin exhibits the most advanced independent service network density globally.
Oil and Gas Pumps Market Segmentation
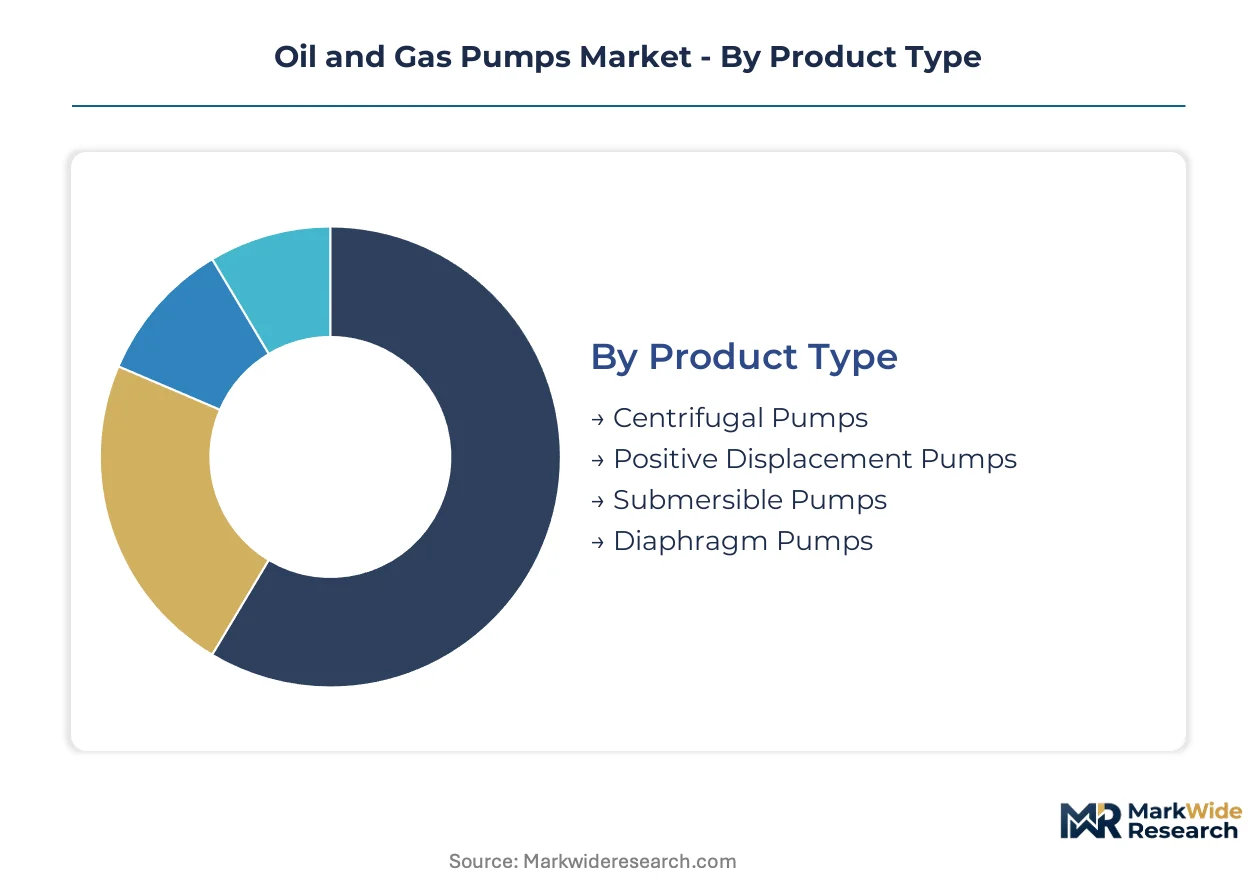
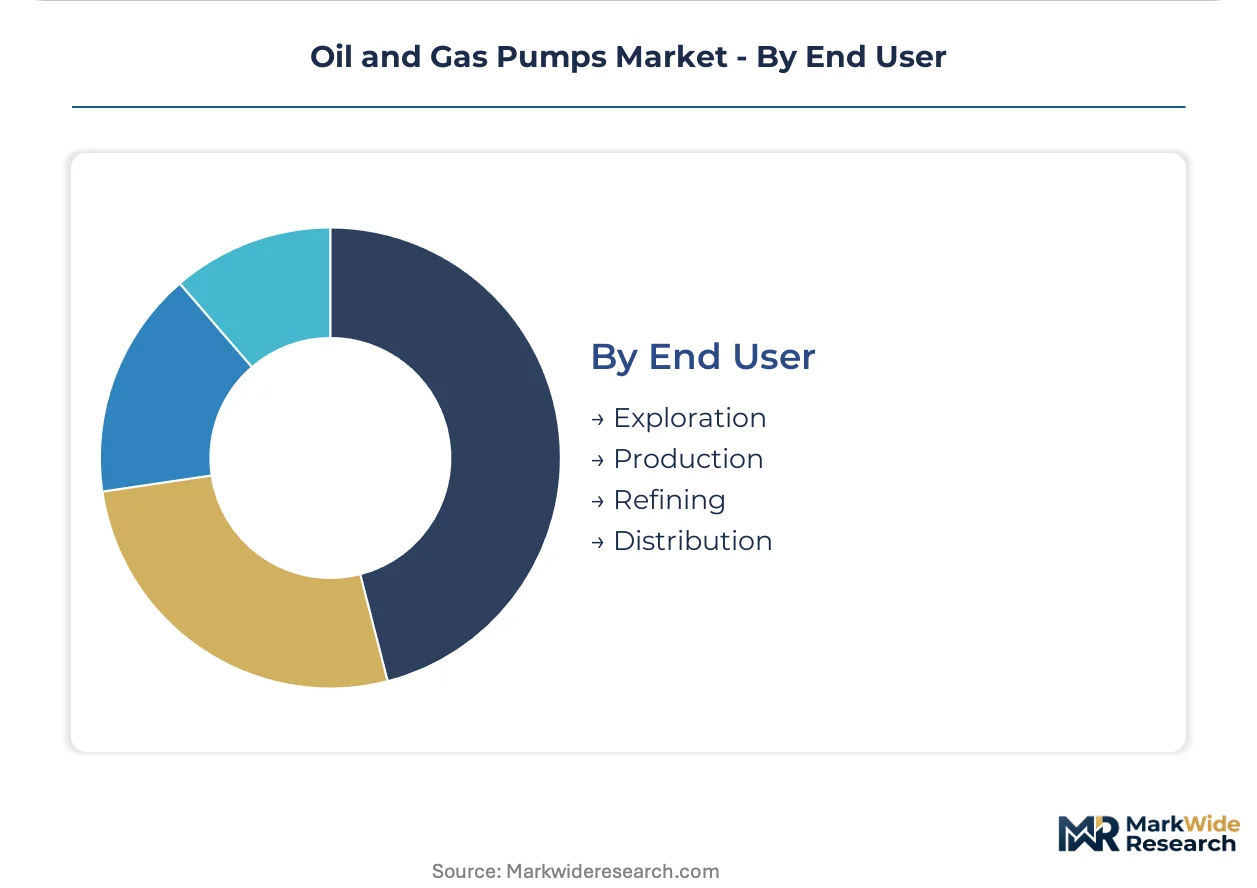
Pump specification requirements diverge sharply across upstream, midstream, and downstream hydrocarbon handling stages. Material certification standards and duty cycle intensity create distinct procurement patterns that segment supplier relationships and service contract structures.
Product Type:
Mature centrifugal designs dominate high-volume transfer applications while emerging submersible architectures reshape subsea production economics.
- Centrifugal Pumps:Radial and mixed-flow impeller configurations handle 500-50,000 barrels per day in pipeline booster stations across the Permian Basin. API 610 compliance mandates govern material traceability for these units in sour service environments where hydrogen sulfide concentrations exceed 100 ppm.
- Positive Displacement Pumps:Reciprocating and rotary designs deliver precise volumetric flow for high-viscosity crude above 1,000 centipoise and chemical injection skids. Operators in West Texas deploy these units for polymer flooding applications where shear-sensitive fluid handling prevents emulsion degradation.
- Submersible Pumps:Electric submersible pump systems operate at depths exceeding 10,000 feet in Gulf of Mexico deepwater fields. Modular motor-protector-seal configurations allow rapid replacement without full well intervention.
- Diaphragm Pumps:Air-operated double-diaphragm architectures handle abrasive produced water with solids content above 500 ppm. These sealless designs satisfy EPA methane regulations in zero-emission production zones.
Centrifugal pumps retain volume leadership; submersible pumps hold the steepest expansion curve.
Technology:
Cost tiers separate premium electric drive systems from commodity mechanical alternatives across field development budgets.
- Electric:Variable frequency drive integration enables 15-30% energy recovery through regenerative braking in high-head applications. Permian Basin operators specify NEMA Premium efficiency motors above 250 horsepower to qualify for IRA clean energy tax credits.
- Hydraulic:Power fluid systems transmit torque through pressurized crude or synthetic oil in subsea trees and downhole safety valves. Norwegian North Sea installations favor these architectures for blowout preventer integration under BSEE protocols.
- Pneumatic:Compressed air drive suits explosive atmosphere classifications in tank farm loading racks and offshore platform sump drainage. These systems eliminate ignition sources in Zone 1 hazardous locations.
- Mechanical:Direct shaft coupling from diesel or gas turbine prime movers persists in remote locations without grid connectivity. West Texas well pads deploy these configurations where electrification infrastructure remains uneconomic.
Electric technology commands the premium tier; pneumatic systems anchor the economy segment.
Installation:
Application context determines capital intensity and regulatory burden across fixed infrastructure versus mobile deployment.
- Onshore:Permanent pump stations along interstate pipelines in Texas and New Mexico incorporate NACE MR0175-compliant materials for sour gas compression. These installations support 20-year asset lifecycles with scheduled turnarounds every five years.
- Offshore:Platform-mounted and subsea boosting systems face ASME Section VIII pressure vessel certification and Coast Guard fire safety inspection. Gulf of Mexico producers compress replacement cycles as saltwater corrosion accelerates equipment degradation.
- Mobile:Skid-mounted frac pumps and well testing units relocate between pads on 18-wheeler transport frames. Rapid deployment specifications prioritize weight reduction over absolute efficiency metrics.
- Fixed:Refinery process pumps in Port Arthur and Baytown complexes operate under OSHA Process Safety Management and EPA Risk Management Plan mandates. These installations require documented mechanical integrity programs with vibration monitoring thresholds.
Fixed installations dominate capital allocation; mobile configurations expand most quickly.
End User:
Customer type segmentation reveals divergent procurement sophistication between integrated majors and independent operators.
- Exploration:Mud pump systems circulate drilling fluid at 3,000+ psi in wildcat drilling programs. West Texas independents specify triplex positive displacement units with ceramic liners for extended duty in abrasive formations.
- Production:Artificial lift and gathering system pumps handle multiphase flow with gas volume fractions exceeding 90%. Subsea boosting installations in the Gulf of Mexico require API 17D subsea production system certification.
- Refining:Hydrotreater feed pumps and delayed coker charge pumps operate above 500°F in sulfur recovery units. These applications demand API 610 11th edition compliance with full nozzle load calculations.
- Distribution:Pipeline mainline and terminal transfer pumps move refined products under FERC tariff regulations. Colonial Pipeline specifications govern procurement for 5,500-mile product distribution networks.
Production segment retains volume leadership; distribution holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in the United States exhibit the lowest price elasticity, absorbing premium alloys and predictive service contracts, while operators in Brazil and India prioritize upfront cost minimization over lifecycle economics.
United States
Permian Basin drilling intensity sustains above-average spare parts consumption across West Texas and southeastern New Mexico. EPA methane regulations and BSEE well control mandates tighten seal reliability standards for zero-emission pump designs. Houston anchors the largest concentration of pump OEM headquarters and dedicated field service hubs.
China
Domestic refining capacity expansion drives demand for high-pressure hydrotreater feed pumps in Shandong and Jiangsu provinces. GB standards and MIIT industrial efficiency mandates accelerate NEMA-equivalent motor adoption. The Yangtze River Delta clusters precision casting foundries serving both domestic and export markets.
Germany
Hydrogen blending infrastructure retrofits create demand for embrittlement-resistant centrifugal seals in pipeline networks. EU Green Deal and REACH material compliance govern alloy selection for sour service applications. The Ruhr industrial corridor hosts specialized repair shops capturing aftermarket share from traditional OEM channels.
Brazil
Pre-salt deepwater development sustains subsea boosting system demand despite capital budget volatility. ANVISA and environmental licensing delays extend procurement cycles for offshore installations. The Campos Basin concentrates equipment deployment where local content requirements favor joint ventures with international suppliers.
Saudi Arabia
Gas production expansion and CCUS injection pilot projects drive high-pressure reciprocating pump procurement. SFDA and national industrial localization programs mandate in-country value capture for major equipment. The Eastern Province hosts the densest concentration of oilfield service infrastructure outside North America.
Oil and Gas Pumps Market Vendor Landscape
Vertically integrated conglomerates and specialized component fabricators split the market across distinct value capture zones. Consolidation pressures concentrate at the premium alloy and subsea system tiers where API certification barriers limit new entry. Three archetypes dominate: full-system integrators with captive service networks, precision casting specialists controlling critical impeller geometries, and digital-enabled aftermarket disruptors unbundling traditional OEM revenue streams. Competitive moves center on backward integration into exotic material supply and predictive maintenance platform deployment.
Among diversified industrial conglomerates, Flowserve Corporation and Baker Hughes Company exemplify full-system integrators anchoring recurring revenue through digital monitoring subscriptions and field service logistics. KSB SE & Co. KGaA occupies a position within the precision manufacturing tier, representing specialists who compete through upstream control over critical casting processes. These three entities illustrate how competitive positioning diverges between service-anchored platforms and manufacturing-centric architectures.
| Leading Market Players |
|---|
| Xylem Inc. |
| NETZSCH Pumps & Systems |
| Flowserve Corporation |
| Weir Group Plc |
| ITT Inc. |
| Sulzer Ltd. |
| Alfa Laval AB |
| Baker Hughes Company |
| KSB SE & Co. KGaA |
| Others |
Supply Flow & Price Mechanics
Houston-to-Permian Basin dedicated flatbed corridors carry super duplex impeller castings at freight premiums that compound nickel alloy cost volatility, concentrating pricing power among foundries with captive logistics while forcing pump OEMs to pass through tiered service contract premiums to operators with lowest price elasticity.
Pricing Analysis
Aftermarket service revenue tiers anchored by predictive maintenance subscriptions and extended parts availability contracts now capture lifetime value exceeding original equipment margins. Three-tier pricing structure across API-certified premium, standard alloy, and refurbished economy levels segments buyers by sour service exposure and regulatory scrutiny. Cost compression in standard centrifugal tiers intensifies as independent repair shops capture mechanical seal replacement volumes. Integrated majors with capital discipline programs exhibit lowest price sensitivity; independent Permian operators prioritize upfront hardware minimization.
Supply Chain Analysis
Contract-manufacturing concentration for high-pressure impeller castings rests with qualified foundries in Norway, Brazil, and the US Gulf Coast where ASME Section IX weld procedure certification creates single-source bottlenecks. Super duplex stainless steel, Inconel alloys, and precision titanium powder feedstock draw from nickel mining corridors in Indonesia and refined metal processors in Germany. Tariff exposure on exotic alloy imports from non-FTA sources threatens margin stability for sour service pump fabricators. Distribution runs through OEM captive parts networks, independent aftermarket distributors, and digital parts catalog platforms displacing traditional channel control.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital monitoring subscriptions and predictive maintenance service layers expand faster than hardware shipments, reframing pump procurement as recurring-revenue attachment opportunities rather than capital equipment transactions.
For Market Incumbents: Insulate premium positioning by backward integration into precision casting for critical impeller geometries, locking in API 610 material traceability certification that commodity entrants cannot replicate. Anchor recurring revenue through field service hub density in the Permian Basin and Gulf of Mexico corridors where replacement cycle compression sustains parts demand. Counter independent aftermarket disruption by pre-qualifying integrated pump-BOP skids under API 16D protocols, extending recertification timelines that delay competitor permitting.
For New Entrants and Emerging Players: Build out digital twin integration capabilities targeting brownfield installations with legacy SCADA architectures resistant to cloud-based connectivity, capturing predictive failure window contracts that OEMs underserve. Target mobile frac pump and well testing unit segments where rapid deployment specifications prioritize weight reduction over absolute efficiency, bypassing entrenched centrifugal pump incumbents. Lead with additive manufacturing of titanium impellers for high-solids produced water applications, collapsing lead times that traditional foundries cannot match.
For Investors and Strategic Acquirers: EPA methane regulation implementation reshapes the acquisition landscape toward zero-emission seal technologies and magnetic drive architectures qualifying for IRA clean energy tax credits. Five-to-ten year viability favors precision casting specialists with captive alloy supply and digital-enabled aftermarket platforms unbundling traditional OEM revenue streams. Watch BSEE well control mandate enforcement velocity as the signal indicating subsea boosting system recertification demand inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Casting | Captures API 610 material traceability certification barriers that lock out commodity competitors. |
| Predictive Maintenance Platform Deployment | Anchors recurring revenue through real-time vibration monitoring fused with physics-based failure modeling. |
| Additive Manufacturing Qualification | Collapses impeller lead times for North Sea operators qualifying electron beam melted titanium components. |
| Zero-Emission Seal Architecture Development | Positions for EPA methane regulation compliance in Permian Basin zero-emission production zones. |
| Integrated Pump-BOP Skid Pre-Certification | Accelerates Gulf of Mexico permitting timelines under BSEE API 16D protocol requirements. |
Methodological Framework
The analysis maps centrifugal, positive displacement, submersible, and diaphragm pump architectures, each validated through maintenance directors at Permian Basin operators, aftermarket service heads at Gulf of Mexico platforms, OEM procurement teams, and plant engineers at Port Arthur refineries. Primary fieldwork combined with secondary validation from API certification databases, BSEE incident reports, EPA regulatory filings, and customs trade data on nickel alloy imports. Bottom-up unit economics triangulate against top-down hydrocarbon production forecasts across the analysis window.
Fixed assumptions include sustained Permian drilling intensity, progressive EPA methane regulation enforcement, and API 610 11th edition material certification permanence; varied conditions span nickel alloy price volatility bands, CCUS injection project development velocity, and hydrogen blending infrastructure retrofit adoption curves. Segmentation dimensions modeled include pump type, drive technology, installation context, and end-use stage across upstream through downstream hydrocarbon handling. CAGRs derive from production volume forecasts, replacement cycle compression rates, and service contract attachment trend analysis.
Stress conditions across nickel alloy cost spikes, BSEE recertification timeline extensions, and independent aftermarket share capture were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on regulatory enforcement velocity and technology adoption curves. Cross-checking against EIA hydrocarbon production forecasts and FERC pipeline tariff filings is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Vertical Inline Pumps Market
Pumps and Control Devices
Global Heavy Duty Pumps Market
Pumps and Control Devices
Commercial Booster Pumps Market
Pumps and Control Devices
Global Hydrocyclone Market
Pumps and Control Devices
Asia-Pacific Cryogenic Pump Market
Pumps and Control Devices
Solar Pump Inverter Market
Pumps and Control Devices
Air Breathing Hose Market
Pumps and Control Devices
Regenerative Turbine Pump Market
Pumps and Control Devices
Europe Water Pump Market
Pumps and Control Devices
Glycol Pumps Market
Pumps and Control Devices
Mist Sprayer Pumps Market
Pumps and Control Devices
Plunger Pumps Market
Pumps and Control Devices
Electrohydraulic Pumps Market
Pumps and Control Devices
Global Reciprocating Pumps Market
Pumps and Control Devices
Middle East and Africa Centrifugal Pumps Market
Pumps and Control Devices
Flow Back Equipment Market