
 Slurry Pumps Market | 2026-2036
Slurry Pumps Market Size, Share, and Industry Trends Forecast 2026-2036
Slurry Pumps Market Analysis
EU Green Deal industrial emissions benchmarks are repositioning slurry pump procurement toward energy-efficient designs. The Weir Group Plc leverages its vertical integration in wear-resistant alloys to dominate aftermarket services. Metso sustains technology leadership in high-pressure grinding circuit pumps through proprietary impeller geometries. KSB Group anchors its position in European wastewater sludge handling with localized manufacturing in Germany.
Slurry pumps are centrifugal or positive-displacement machines engineered to transport abrasive solid-liquid mixtures, typically operating at heads exceeding 100 meters with wear liners rated for Mohs hardness above 7. Horizontal configurations lead mining installations due to simpler maintenance access and higher throughput capacity, while submersible types are gaining share in deep-pit dewatering where suction lift constraints eliminate surface-mounted alternatives. Polyurethane-lined wetted parts command margin premiums in phosphate and sand slurry service where rubber degrades chemically.
EPA effluent limitation guidelines and REACH substance restrictions on chromium alloys are tightening material compliance for pump castings exported to North America and Europe. China's MEE enforces particulate discharge thresholds at mineral processing plants, compelling domestic operators to replace legacy pump fleets. ISO 5199 and API 610 testing protocols serve as de facto market access filters for suppliers serving international EPC contractors. Stakeholders must weigh capex recovery timelines against accelerating regulatory phase-outs of high-energy-intensity pump classes.
Market Dynamics
Slurry pump procurement decisions now pivot on tailings dam integrity mandates and energy efficiency benchmarking, with mining operators recalibrating capex toward wear-resistant materials and predictive maintenance architectures.
Growth Catalysts
- EPA effluent limitation guidelines:US mining operators face mandatory pump upgrades to reduce suspended solids discharge, triggering replacement cycles in copper and coal processing facilities.
- Copper concentrate throughput expansion:Chilean and Peruvian smelter operators are commissioning higher-capacity tailings transport infrastructure to match record extraction rates.
- Polyurethane liner technology:Advanced elastomer formulations rated for pH extremes below 4 and above 12 are displacing rubber in phosphate fertilizer and oil sands applications.
Market Restraints
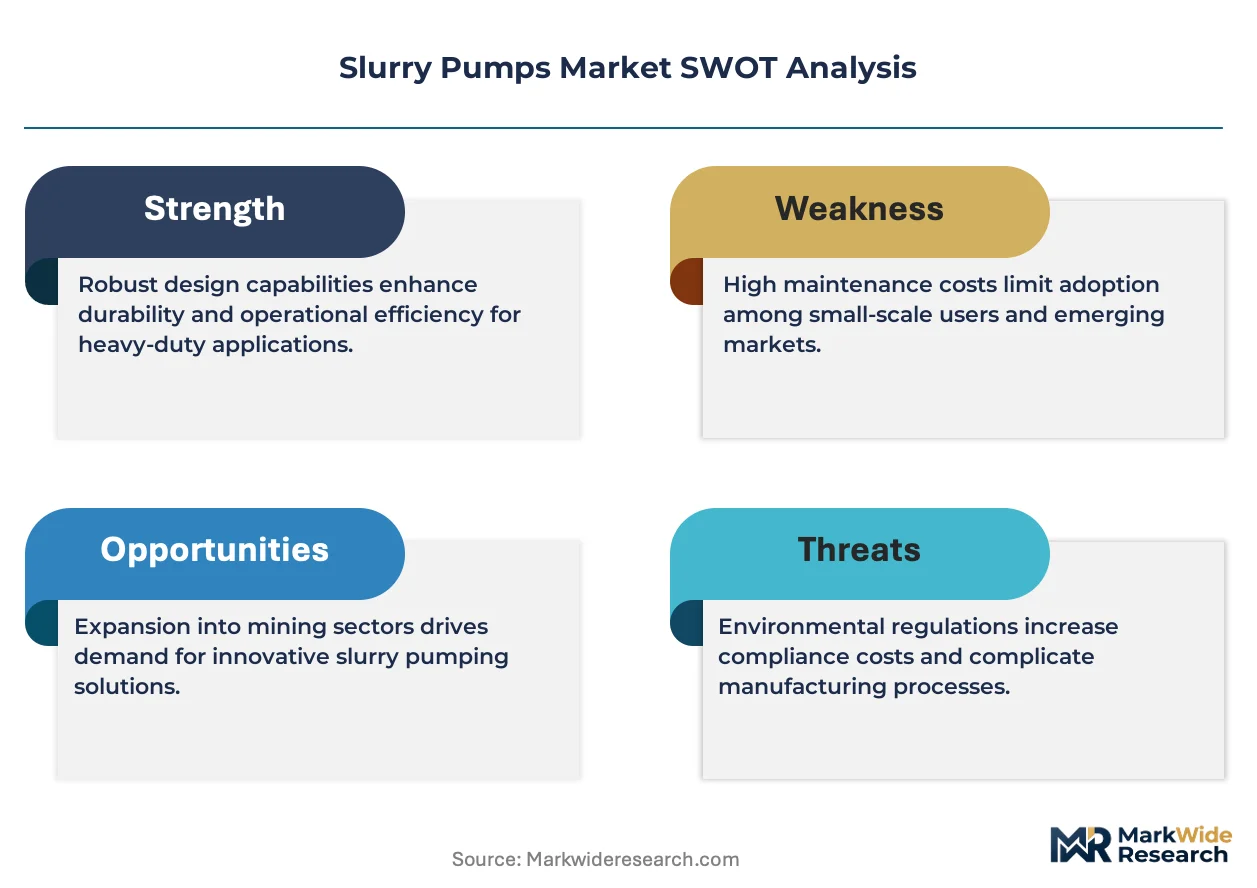
- High-alloy steel price volatility:Nickel and chromium feedstock costs swing 15-40% quarterly, compressing margin stability for casting-dependent manufacturers.
- REACH substance restrictions:ECHA authorization requirements for hexavalent chromium compounds extend compliance timelines for European pump exporters by 8-14 months.
- Centrifugal pump head limitations:Single-stage designs cap at 150 meters for abrasive slurries, forcing multi-stage configurations that multiply maintenance complexity.
Strategic Opportunities
- Deep-pit dewatering submersibles:Australian iron ore operators below 200-meter extraction depths require pressure-compensated motor housings currently served by limited supplier bases.
- EU Green Deal industrial emissions benchmarks:Carbon-intensity scoring in public procurement tenders favors variable-frequency drive retrofits and high-efficiency hydraulic designs.
- Digital twin integration:Real-time wear monitoring fused with predictive algorithms enables outcome-based service contracts displacing traditional spare parts revenue models.
Industry Challenges
- API 610 and ISO 5199 certification timelines:Third-party validation for high-pressure mining pumps extends 6-9 months, delaying project commissioning for EPC contractors.
- Abrasion-resistant welding specialization:Qualified technicians for hardfacing impeller vane repairs are concentrated in Germany and Japan, creating service bottlenecks in remote mining districts.
- Legacy control system integration:SCADA architectures from the 1990s lack protocol compatibility with modern vibration sensors, forcing costly middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Slurry Pumps Market |
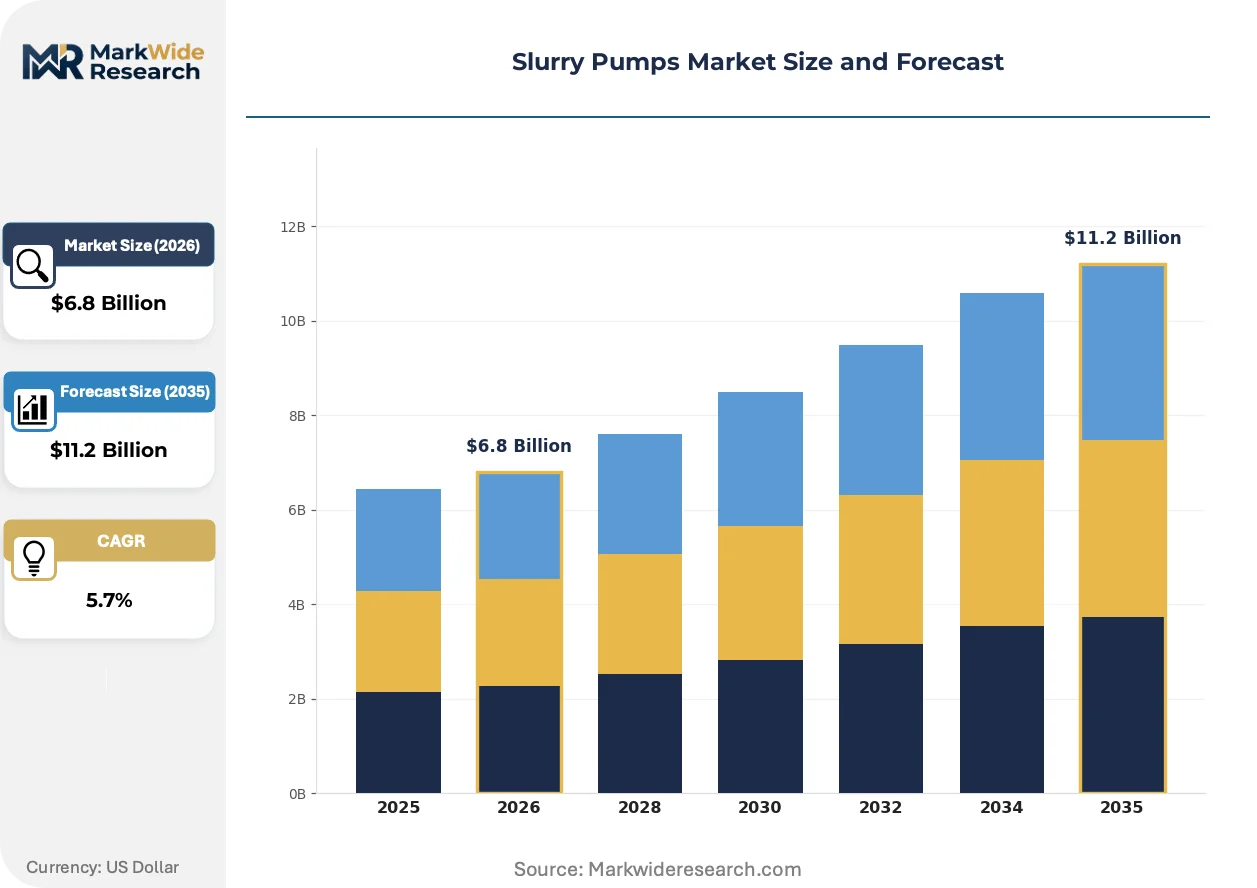
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Vertical, Horizontal, Submersible, Peristaltic Material: Cast Iron, Stainless Steel, Polyurethane, Rubber Application: Mining, Wastewater Treatment, Agriculture, Chemical Processing Installation: Fixed, Mobile, Temporary, Permanent |
| Companies Covered | The Weir Group Plc, Metso, Flowserve Corporation, ITT Goulds Pumps, Xylem Inc., KSB Group, FLSmidth, Schurco Slurry, DAE Pumps, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Slurry Pumps Market Emerging Trajectories
Digitalization of pump performance monitoring and materials science advances in ceramic-metal matrix composites are restructuring competitive advantage around total cost of ownership rather than upfront equipment pricing.
Ceramic-impregnated tungsten carbide coatings are expanding into high-pressure grinding circuit pumps where traditional elastomer liners fail within 800 operating hours. Anglo American and Vale are piloting these surfaces at concentrate transfer stations in Brazil and South Africa. The technology is compressing maintenance intervals from quarterly to semi-annual schedules while enabling 20% higher rotational speeds.
EU F-Gas Regulation phase-down schedules are forcing refrigerant-dependent pump cooling systems toward glycol-based closed loops. Metso and Weir are redesigning bearing housing thermal management for European mining installations. The shift most affects submersible dewatering pumps in German potash and Polish copper operations where ambient groundwater temperatures exceed 35°C.
After-sales service unbundling is fragmenting traditional OEM revenue streams as third-party maintenance specialists capture 30-40% of wear parts replacement in mature mining districts. Independent service providers in Western Australia and Alberta are building regional inventory pools that compress parts availability from 6 weeks to 72 hours. This pattern is most visible in iron ore and oil sands clusters where operator consolidation has concentrated bargaining power.
Slurry Pumps Market Segmentation
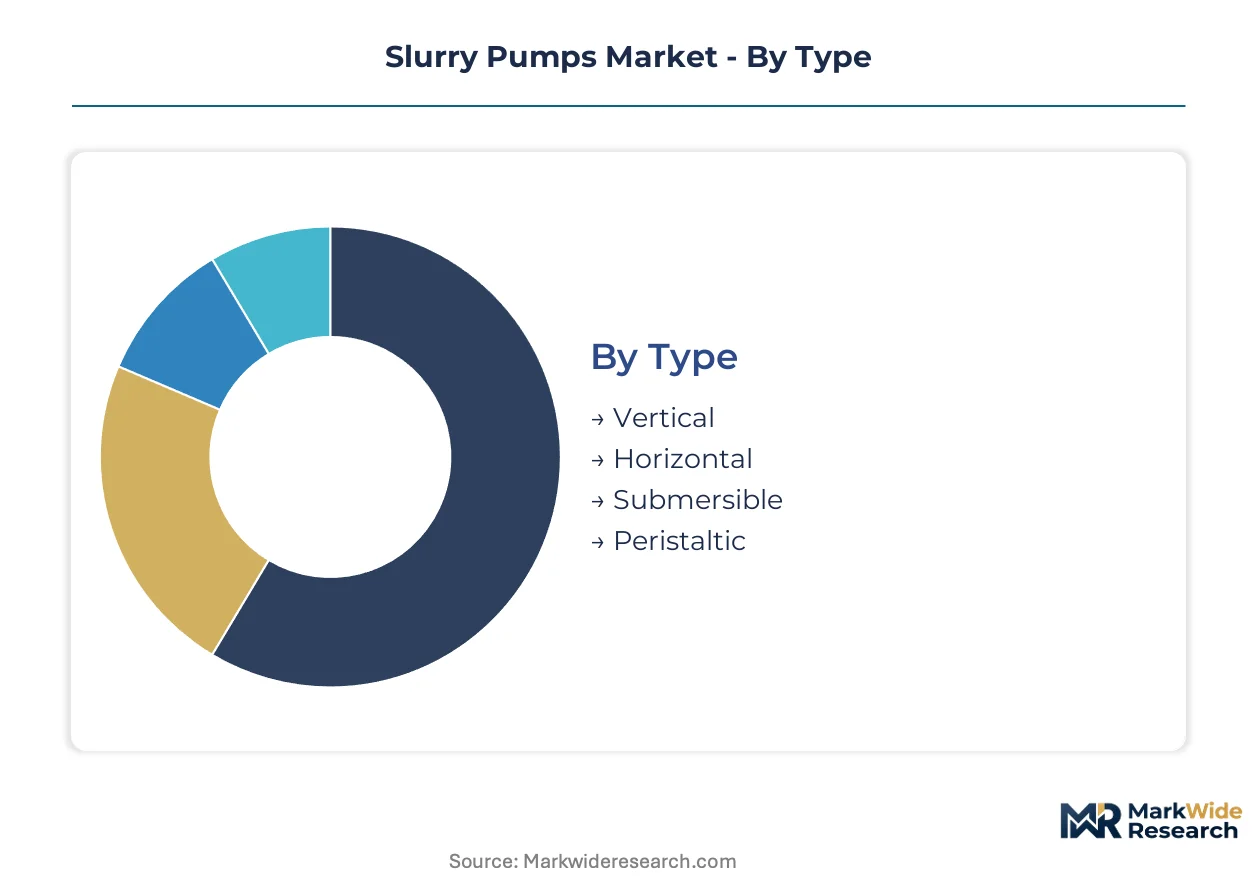
Slurry pump procurement varies sharply by operational intensity, abrasive severity, and regulatory exposure. Buyers prioritize different performance vectors—wear resistance, energy efficiency, or mobility—depending on their specific extraction or processing environment.
Type:
Horizontal configurations dominate high-throughput mining installations where maintenance access drives total cost of ownership calculations.
- Vertical:Space-constrained processing plants favor vertical cantilever designs that eliminate submerged bearings. Chilean copper concentrators specify these for tailings thickener underflow where floor space premiums exceed equipment cost differentials.
- Horizontal:Split-case horizontal pumps handle 80% of iron ore slurry volumes in Western Australia. Split-casing permits impeller replacement without disturbing suction or discharge piping, compressing maintenance windows from days to hours.
- Submersible:Pressure-compensated motor housings enable operation below 200-meter suction lift limits in deep-pit dewatering.
- Peristaltic:Hose-based positive displacement suits shear-sensitive chemical slurries and precise dosing applications.
Horizontal pumps lead volumes today; submersible types are gaining share fastest in deep extraction zones.
Material:
Material selection hinges on Mohs hardness of transported solids and chemical exposure rather than initial procurement cost.
- Cast Iron:Standard for low-abrasion wastewater and agricultural applications where pH remains neutral. German municipal utilities specify EN-GJL-250 grades for grit chamber pumps, accepting shorter lifecycles against lower capital outlay.
- Stainless Steel:Duplex and super-duplex alloys resist chloride-induced pitting in offshore oil sands and marine dredging. Norwegian North Sea operators mandate SAF 2205 for produced water reinjection pumps.
- Polyurethane:Advanced formulations rated for pH extremes displace rubber in phosphate fertilizer processing.
- Rubber:Natural and synthetic elastomers retain cost advantage in moderately abrasive sand and gravel slurries.
Cast iron leads volumes today; polyurethane is expanding most quickly in chemically aggressive service.
Application:
End-use concentration determines specification stringency, with mining operators imposing the most demanding wear life and availability requirements.
- Mining:Copper, iron ore, and oil sands extraction account for the majority of high-pressure, high-abrasion installations. Vale's S11D complex in Brazil runs 300kW+ pumps on 24-hour continuous duty cycles with 99.5% availability mandates.
- Wastewater Treatment:Primary sludge and thickened waste activated sludge handling prioritizes clog resistance and dry-run tolerance. KSB's Amarex KRT series dominates European municipal retrofits under EU Urban Wastewater Treatment Directive compliance schedules.
- Agriculture:Irrigation and manure handling systems favor portable, lower-head centrifugal units.
- Chemical Processing:Corrosion-resistant alloys and mechanical seals containing aggressive acids and caustics.
Mining leads volumes today; wastewater treatment is climbing the fastest on regulatory upgrade cycles.
Installation:
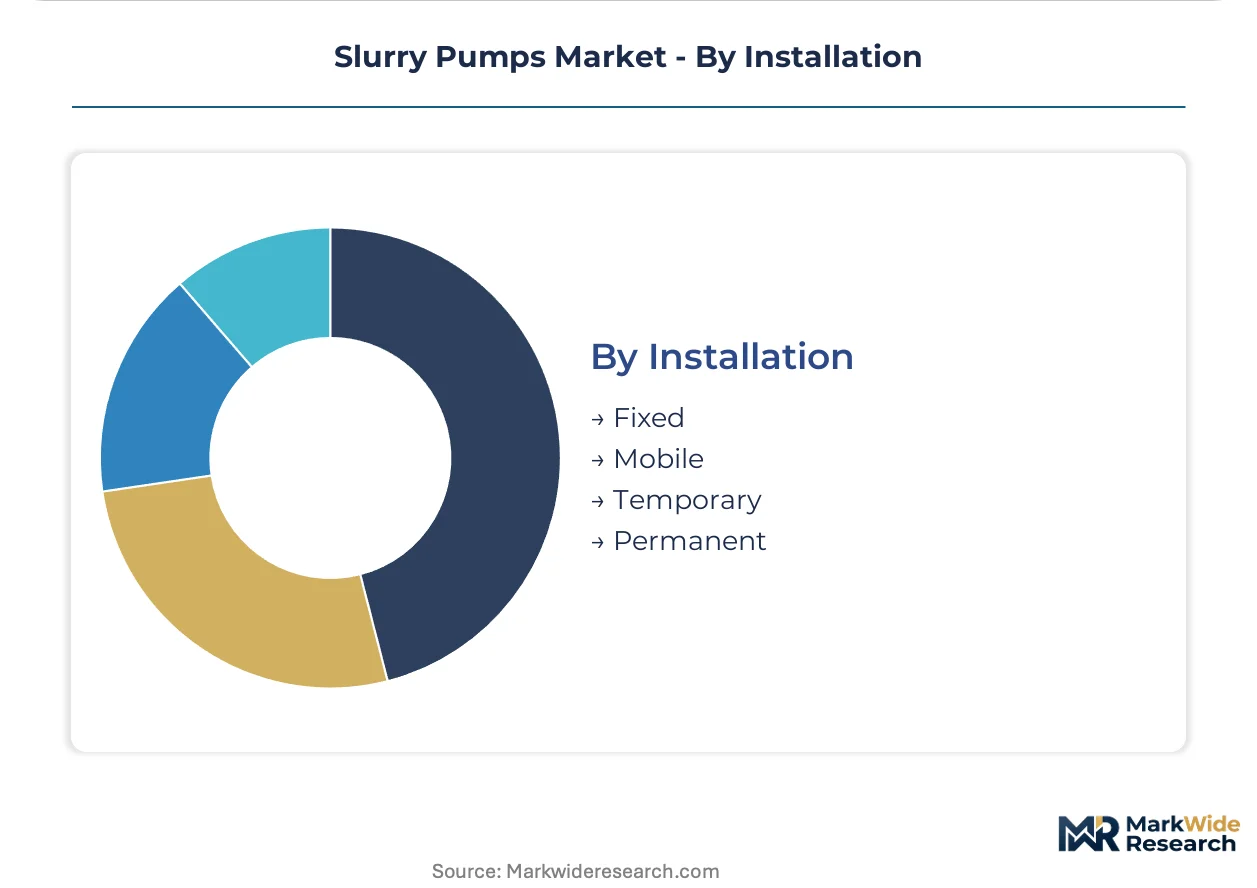
Mobility requirements separate capital-intensive permanent infrastructure from rental and contingency deployment models.
- Fixed:Anchored installations with dedicated foundations and hard-piped connections characterize major concentrator and tailings facilities. BHP's South Flank iron ore project commissioned 40+ fixed horizontal pumps with 25-year design life.
- Mobile:Skid-mounted and trailer-deployed units serve exploration drilling, construction dewatering, and emergency flood response. Australian hire fleets maintain 500+ mobile diesel-driven pumps for wet-season contingency.
- Temporary:Short-term rental agreements bridge commissioning gaps or seasonal demand spikes.
- Permanent:Engineered installations with integrated control systems and predictive maintenance architectures.
Fixed installations lead volumes today; mobile configurations are gaining share fastest in contract mining and rental markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized welding technicians for hardfacing repairs cluster in Germany and Japan, creating service bottlenecks for remote mining districts worldwide. Equipment procurement patterns track ore body geography and tailings dam integrity mandates.
United States
Copper and coal processing facilities drive replacement cycles under EPA effluent limitation guidelines. The agency mandates suspended solids reductions that force pump upgrades. Arizona and Utah copper concentrators commission higher-efficiency tailings transport systems.
Chile
Record copper extraction rates require expanded tailings infrastructure at smelter complexes. Stricter seismic stability standards for dam construction elevate specification stringency. The Atacama Desert mining corridor anchors concentrator pump demand.
Australia
Iron ore operators below 200-meter extraction depths require pressure-compensated submersible motor housings. Western Australia's Pilbara region runs split-case horizontal pumps on 24-hour continuous duty cycles. The state's hire fleets maintain 500+ mobile diesel-driven units for wet-season contingency.
Germany
Potash operations and municipal wastewater utilities specify vertical cantilever designs for space-constrained thickener underflow. EU F-Gas Regulation phase-downs force glycol-based bearing housing cooling retrofits. North Rhine-Westphalia's industrial pump manufacturing base supplies European retrofit markets.
Canada
Oil sands producers demand polyurethane-lined wetted parts for pH extremes that degrade rubber. Alberta's tailings management infrastructure expands to match bitumen extraction growth. Regional independent service providers compress parts availability from six weeks to 72 hours.
Slurry Pumps Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the slurry pump value chain. Foundry-dependent manufacturers absorb nickel and chromium price volatility while specialized engineering houses license hydraulic designs. Three archetypes dominate: vertically integrated alloy producers controlling wear-resistant material supply, regional fabrication specialists serving single-commodity mining districts, and digital service platforms unbundling aftermarket maintenance. Consolidation pressures concentrate among casting-dependent players seeking feedstock cost stability, while technology licensing agreements proliferate among hydraulic design specialists.
Within the integrated alloy tier, The Weir Group Plc and Metso occupy positions anchored by captive wear-resistant material production. KSB Group exemplifies the regional engineering house model with localized European manufacturing. These three represent divergent strategic postures: alloy integration versus hydraulic specialization versus geographic density.
| Leading Market Players |
|---|
| The Weir Group Plc |
| Metso |
| Flowserve Corporation |
| ITT Goulds Pumps |
| Xylem Inc. |
| KSB Group |
| FLSmidth |
| Schurco Slurry |
| DAE Pumps |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up aftermarket specialists have consolidated regional service networks across Western Australia and Alberta, compressing parts availability timelines while exerting downward pressure on OEM spare parts pricing through inventory pooling and independent sourcing channels.
Pricing Analysis
The bundled-vs-unbundled service split distinguishes capital equipment sales from lifecycle service contracts. Three-tier pricing structure across premium, standard, and economy levels separates API 610-certified high-pressure units from ISO 5199-compliant mid-tier pumps and uncertified economy alternatives. Price differentiation rests on certification grade and after-sales service bundling. Cost compression in the economy tier is intensifying because independent service providers capture 30-40% of wear parts replacement in mature mining districts. Contract mining operators exhibit highest price sensitivity; major concentrator projects with 25-year design life mandates show lowest sensitivity to upfront equipment premiums.
Supply Chain Analysis
Qualified hardfacing technicians for impeller vane repairs concentrate in Germany and Japan, creating service bottlenecks that extend maintenance windows in remote Chilean and Peruvian mining districts. Foundry-dependent manufacturing draws from nickel and chromium feedstock sources anchored in South Africa, Kazakhstan, and Indonesia. Supply chain risk centers on quarterly nickel and chromium price swings of 15-40% that compress margin stability for casting-dependent producers. Distribution runs through EPC contractor procurement channels for major projects and independent aftermarket specialists for wear parts replacement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through digital service unbundling, where predictive maintenance architectures enable outcome-based contracts that displace traditional spare parts revenue models at premium pricing.
For Market Incumbents: To counter independent aftermarket specialists capturing regional wear parts markets, backward integration into captive wear-resistant alloy production secures feedstock cost stability against nickel and chromium volatility. Incumbents should deepen digital twin integration capabilities to anchor outcome-based service contracts that resist third-party disintermediation in Australian iron ore and Canadian oil sands clusters. For New Entrants and Emerging Players: Deep-pit dewatering operators below 200-meter extraction depths represent an underserved buyer archetype currently served by limited supplier bases for pressure-compensated submersible motor housings. New entrants should target mobile pump rental fleets in Australian wet-season contingency markets through skid-mounted diesel-driven configurations with 72-hour parts availability guarantees via regional inventory pooling partnerships. For Investors and Strategic Acquirers: Valuations sit cheapest among foundry-dependent mid-caps exposed to raw material price volatility without captive alloy supply. Long-term viability favors targets with installed base density in regulatory upgrade cycles under EPA effluent guidelines and EU Green Deal benchmarks. The signal to watch is acceleration of REACH authorization timelines for hexavalent chromium compounds that would extend compliance-driven replacement demand.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Twin Integration | Real-time wear monitoring fused with predictive algorithms enables outcome-based service contracts displacing traditional spare parts models. |
| Backward Integration into Wear-Resistant Alloys | Captive supply of nickel-chromium feedstocks insulates margin stability against quarterly raw material price swings. |
| Regional Inventory Pooling | Independent service providers in Western Australia and Alberta compress parts availability from six weeks to 72 hours. |
| Pressure-Compensated Submersible Development | Australian iron ore operators below 200-meter extraction depths require motor housings currently served by limited supplier bases. |
| Glycol-Based Cooling Retrofit | EU F-Gas Regulation phase-downs force bearing housing thermal management redesigns for German potash and Polish copper operations. |
Methodological Framework
Direct dialogue with maintenance directors at copper concentrators, aftermarket service heads in Australian hire fleets, EPC contractor procurement teams, and plant engineers in Canadian oil sands operations grounded qualitative insights. Secondary validation drew from EPA effluent limitation guidelines, EU ECHA authorization databases, ISO 5199 and API 610 testing protocol documentation, and SEC filings of publicly traded pump manufacturers. Bottom-up and top-down triangulation cross-validated equipment shipment data against end-use installation records.
Bottom-up modeling aggregated unit economics across horizontal, vertical, submersible, and peristaltic configurations by material grade and application intensity. Top-down validation tracked mining capex cycles, wastewater treatment regulatory compliance schedules, and tailings infrastructure investment flows across the analysis window. Segmentation dimensions included pump type, material specification, end-use application, and installation mobility. CAGRs were derived from regression analysis of historical equipment replacement cycles and regulatory-driven upgrade timelines.
Underlying measurement precision varies by segment; mining procurement data carries tighter precision than municipal wastewater estimates. Forecasts reflect assumptions about EPA guideline enforcement consistency, REACH authorization timelines, and copper concentrate throughput expansion rates. Material deviation in nickel-chromium feedstock pricing or tailings dam integrity mandate acceleration warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Wind Powered Water Pumps Market
Pumps and Control Devices
Radial Piston Pumps Market
Pumps and Control Devices
Europe, Middle-East and Africa Diaphragm Pump Market
Pumps and Control Devices
Pressure Washer Pump Oil Market
Pumps and Control Devices
Rotating Equipment Market
Pumps and Control Devices
Pressure Pumping Market
Pumps and Control Devices
Global Hydraulic Submersible Pump Market
Pumps and Control Devices
Global Diaphragm Pump Market
Pumps and Control Devices
Electrostatic Spraying System Market
Pumps and Control Devices
Asia-Pacific Cryogenic Pump Market
Pumps and Control Devices
Oil and Gas Pumps Market
Pumps and Control Devices
Sanitary Pumps Market
Pumps and Control Devices
Water Intake Screens Market
Pumps and Control Devices
Axial Flow Pump Market
Pumps and Control Devices
Global High Pressure Pumps Market
Pumps and Control Devices
North America Submersible Pumps Market