
 Global Leak Detection Solutions Market | 2026-2036
Global Leak Detection Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Global Leak Detection Solutions Market Foresight
A capital-intensity divergence between integrated conglomerates and sensor specialists is rotating competitive dynamics across the leak detection landscape. Honeywell International Inc. leverages its distributed control system footprint to bundle fixed acoustic installations with process automation contracts. Emerson Electric Co. sustains technology leadership in ultrasonic detection through sustained R&D allocation toward pipeline-specific algorithms. Siemens Energy anchors European hydrogen infrastructure projects with electromagnetic sensor arrays designed for pressurized gas networks.
Leak detection solutions encompass sensor hardware, analytics software, and communication protocols engineered to identify fluid or gas escape points across pressurized systems, with acoustic sensors detecting pressure-wave anomalies at frequencies between 20 Hz and 100 kHz and thermal imaging cameras resolving temperature differentials as small as 0.05°C to visualize volatile organic compound releases. Optical sensors dominate capital expenditure in pipeline monitoring due to fiber-optic cable integration with distributed temperature sensing, while wireless networks represent the fastest-expanding deployment mode as battery-powered nodes reduce trenching costs in remote terrain. Cloud-based platforms concentrate recurring revenue streams by centralizing multi-site alert management for facility managers and utility providers.
The EPA enforces methane monitoring under New Source Performance Standards, compelling energy producers to deploy continuous emission detection rather than periodic surveys. EMA guidelines on industrial safety and the EU F-Gas Regulation restrict fluorinated greenhouse gas leaks, shaping product certification requirements for HVAC and refrigeration applications. Stakeholders must monitor evolving hydrogen-specific standards from ISO working groups as molecular leak rates differ fundamentally from natural gas, demanding recalibrated sensor sensitivity thresholds and revised maintenance protocols.
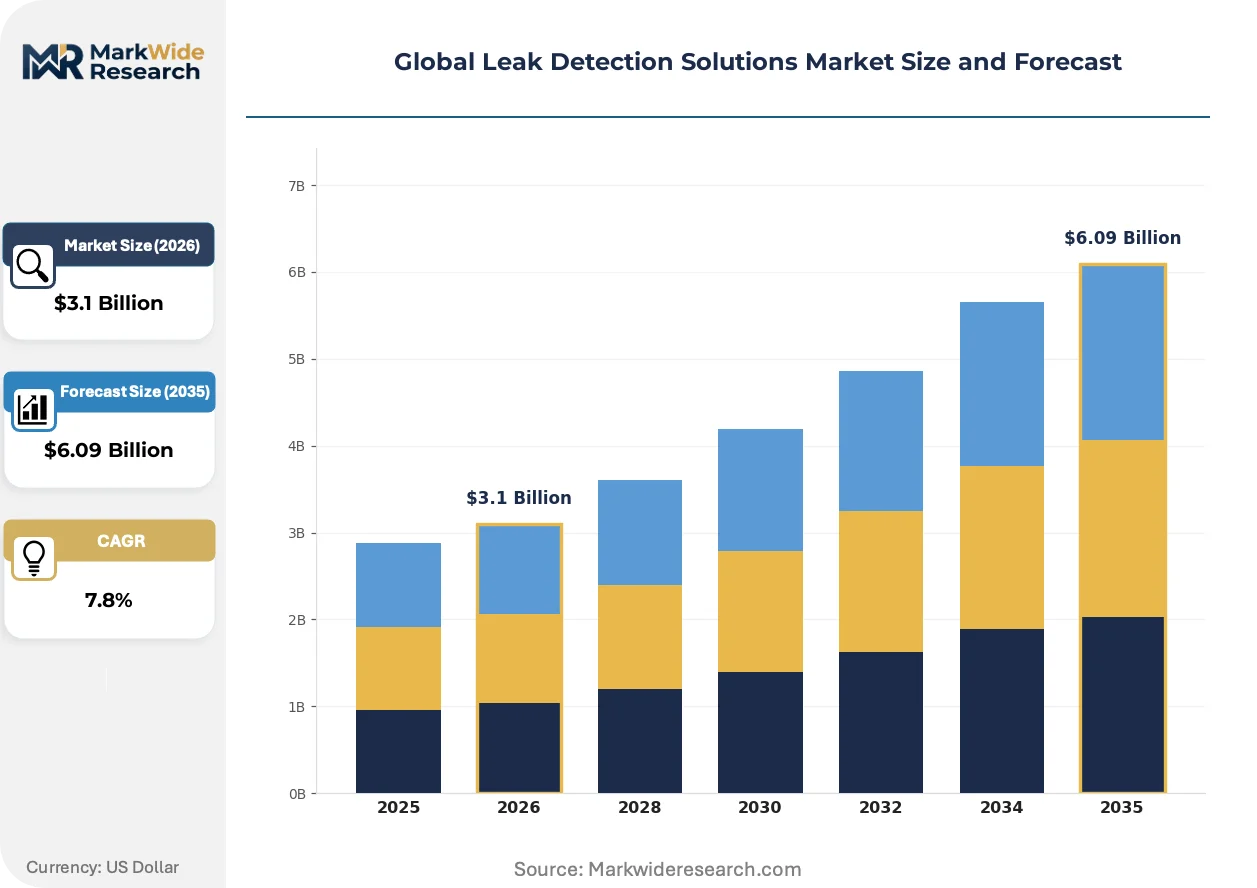
Market Dynamics
The shift from periodic manual surveys to continuous automated monitoring is compressing procurement cycles and forcing sensor vendors to bundle analytics software with hardware deployments. Pipeline operators now demand real-time data streams rather than quarterly inspection reports.
Growth Catalysts
- EPA Methane Rules:New Source Performance Standards mandate continuous emission monitoring at upstream and midstream facilities, compelling infrastructure upgrades across US oil and gas networks.
- Hydrogen Pipeline Buildout:Germany's national hydrogen backbone requires specialized detection systems calibrated for hydrogen's rapid molecular dispersion rates.
- Fiber-Optic Integration:Distributed temperature sensing cables enable kilometer-scale coverage with single installations, reducing per-mile monitoring costs for long-distance pipelines.
Market Restraints
- Sensor Calibration Costs:Hydrogen-specific sensitivity thresholds demand frequent recalibration protocols that inflate total cost of ownership versus natural gas systems.
- Wireless Node Battery Life:Remote terrain deployments face power management constraints as acoustic sensors in sub-zero climates drain cells faster than projected replacement cycles.
- Legacy System Integration:SCADA retrofitting at aging pipeline facilities requires custom protocol bridges that extend deployment timelines and compress vendor margins.
Strategic Opportunities
- EU F-Gas Regulation:HVAC and refrigeration certification requirements create aftermarket demand for portable leak detectors with fluorinated gas specificity.
- Cloud Platform Centralization:Multi-site alert management systems enable recurring revenue streams from utility providers managing distributed infrastructure portfolios.
- India Industrial Safety Mandates:Chemical processing clusters near Gujarat and Maharashtra are adopting optical gas imaging for volatile organic compound monitoring.
Industry Challenges
- ISO Hydrogen Standards Gap:Pending working group recommendations on molecular leak rate thresholds leave sensor manufacturers without unified certification benchmarks.
- Acoustic Signal Processing Talent:Pipeline-specific algorithm development requires rare combinations of petroleum engineering and digital signal processing expertise.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Leak Detection Solutions Market |
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $6.09 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Acoustic Sensors, Optical Sensors, Ultrasonic Detectors, Thermal Imaging, Electromagnetic Sensors, Chemical Sensors Deployment Mode: Fixed Systems, Portable Devices, Wireless Networks, Cloud-Based Platforms, Hybrid Systems, On-Premises Installations Use Case: Pipeline Monitoring, HVAC Systems, Water Supply Networks, Fuel Storage, Chemical Processing, Fire Suppression Systems Customer Type: Energy Producers, Facility Managers, Environmental Agencies, Maintenance Contractors, Utility Providers, Manufacturing Plants |
| Companies Covered | Honeywell International Inc., Emerson Electric Co., Siemens Energy, Schneider Electric, ABB, Teledyne FLIR LLC, Aeris Technologies Inc., Bridger Photonics, Pentair, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Leak Detection Solutions Market Shifts & Advancements
Detection modality convergence is blurring hardware categories as vendors combine thermal, acoustic, and optical sensing in single platforms. Buyers now evaluate integrated systems rather than standalone sensor specifications.
Artificial intelligence inference at the edge is fragmenting traditional centralized analytics architectures. Machine learning models now run on battery-powered nodes to reduce latency for critical leak alerts. Midstream pipeline operators in Texas and Alberta are piloting these distributed intelligence networks. The shift compresses response times from minutes to seconds for rupture events.
The EU F-Gas Regulation is tightening enforcement timelines for fluorinated greenhouse gas monitoring across refrigeration and air conditioning sectors. Equipment owners must document continuous compliance rather than annual leak checks. HVAC service contractors in Germany and France are upgrading to portable optical detectors to meet inspection density requirements.
Buying committees now specify performance-based service agreements that penalize false-positive rates rather than purchasing hardware outright. Facility managers at petrochemical complexes prefer subscriptions covering sensor maintenance, calibration, and cloud analytics. This procurement evolution is most advanced in Netherlands and Belgium where integrated energy clusters prioritize operational expenditure models.
Global Leak Detection Solutions Market Segmentation
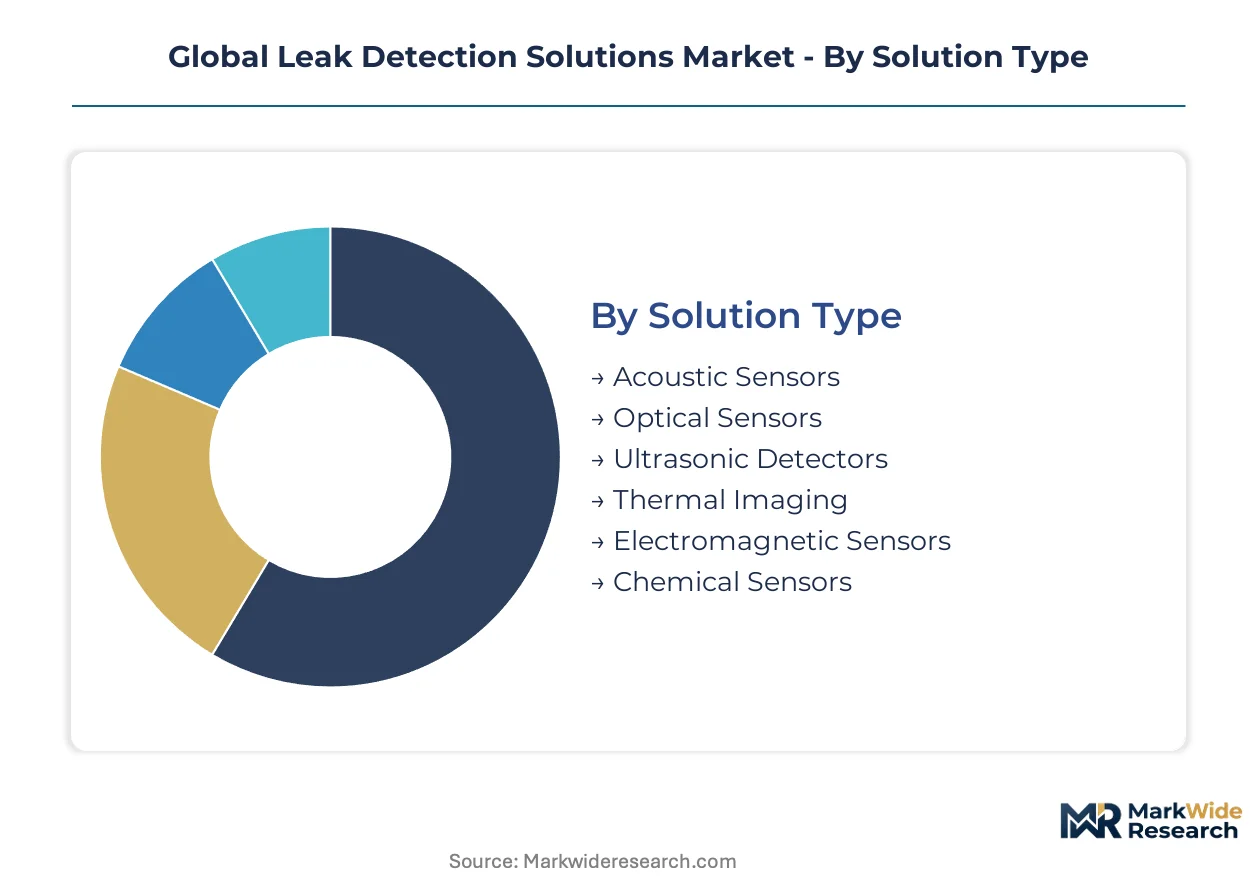
Leak detection solutions fragment across four intersecting dimensions that determine procurement priorities. Solution type dictates capital intensity and calibration protocols. Deployment mode shapes total cost of ownership across remote versus urban infrastructure. Use case and customer type together determine whether buyers prioritize regulatory compliance or operational risk reduction.
Solution Type:
Acoustic and optical sensors dominate export-led demand from German hydrogen infrastructure and US shale networks, while electromagnetic and chemical sensors concentrate in domestic European HVAC retrofit markets.
- Acoustic Sensors:Pressure-wave detection systems operating between 20 Hz and 100 kHz identify rupture events through vibration signature analysis. Demand concentrates in Texas and Alberta midstream corridors where pipeline operators require sub-second rupture response times under EPA methane monitoring mandates.
- Optical Sensors:Fiber-optic distributed temperature sensing cables deliver kilometer-scale coverage with 0.05°C resolution for volatile organic compound visualization. Germany's national hydrogen backbone drives specialized procurement as operators adapt sensitivity thresholds for hydrogen's rapid molecular dispersion.
- Ultrasonic Detectors:High-frequency emission detection for pressurized gas systems, primarily deployed in Japanese industrial clusters under METI safety guidelines.
- Thermal Imaging:Infrared cameras resolving temperature differentials for fugitive emission detection, expanding in Indian chemical processing zones near Gujarat.
- Electromagnetic Sensors:Field distortion detection arrays for metallic pipeline networks, concentrated in European hydrogen distribution pilots.
- Chemical Sensors:Compound-specific detection for fluorinated gases under EU F-Gas Regulation compliance frameworks.
Optical sensors hold the largest share; momentum sits with acoustic sensors.
Deployment Mode:
Fixed and hybrid systems command premium pricing in capital-intensive pipeline infrastructure, while portable devices and wireless networks penetrate cost-sensitive maintenance contractor segments.
- Fixed Systems:Permanent installations integrated with SCADA architectures for continuous monitoring of upstream facilities. Energy producers in US shale basins deploy these under EPA New Source Performance Standards requiring automated emission detection rather than periodic surveys.
- Portable Devices:Handheld optical and acoustic units for field inspection workflows. HVAC service contractors in France and Germany upgrade fleets to meet EU F-Gas Regulation inspection density requirements for fluorinated greenhouse gas documentation.
- Wireless Networks:Battery-powered node arrays eliminating trenching costs in remote terrain. Sub-zero climate deployments in Canadian oil sands face accelerated battery drain constraints.
- Cloud-Based Platforms:Centralized alert management systems generating recurring revenue from utility providers managing distributed infrastructure portfolios.
- Hybrid Systems:Combined fixed and portable architectures for petrochemical complexes prioritizing operational expenditure models.
- On-Premises Installations:Local data processing for facilities with cybersecurity restrictions or latency-sensitive critical alerts.
Fixed systems anchor revenue concentration; cloud-based platforms are climbing the fastest.
Use Case:
Pipeline monitoring and chemical processing concentrate in export-oriented energy economies, while HVAC systems and water supply networks fragment across domestic municipal procurement.
- Pipeline Monitoring:Long-distance hydrocarbon and hydrogen transport infrastructure requiring continuous emission detection. US midstream operators deploy fiber-optic sensing across Permian Basin gathering systems to satisfy EPA methane rules.
- HVAC Systems:Refrigeration and air conditioning leak detection for fluorinated gas compliance. European equipment owners must document continuous monitoring rather than annual leak checks under tightening EU F-Gas Regulation enforcement.
- Water Supply Networks:Municipal distribution system integrity monitoring, concentrated in aging infrastructure replacement cycles.
- Fuel Storage:Tank farm and terminal emission control for environmental agency reporting requirements.
- Chemical Processing:Volatile organic compound detection at Indian clusters near Maharashtra adopting optical gas imaging for regulatory compliance.
- Fire Suppression Systems:Clean agent leak monitoring for data center and critical facility protection.
Pipeline monitoring dominates value capture; HVAC systems are gaining share fastest.
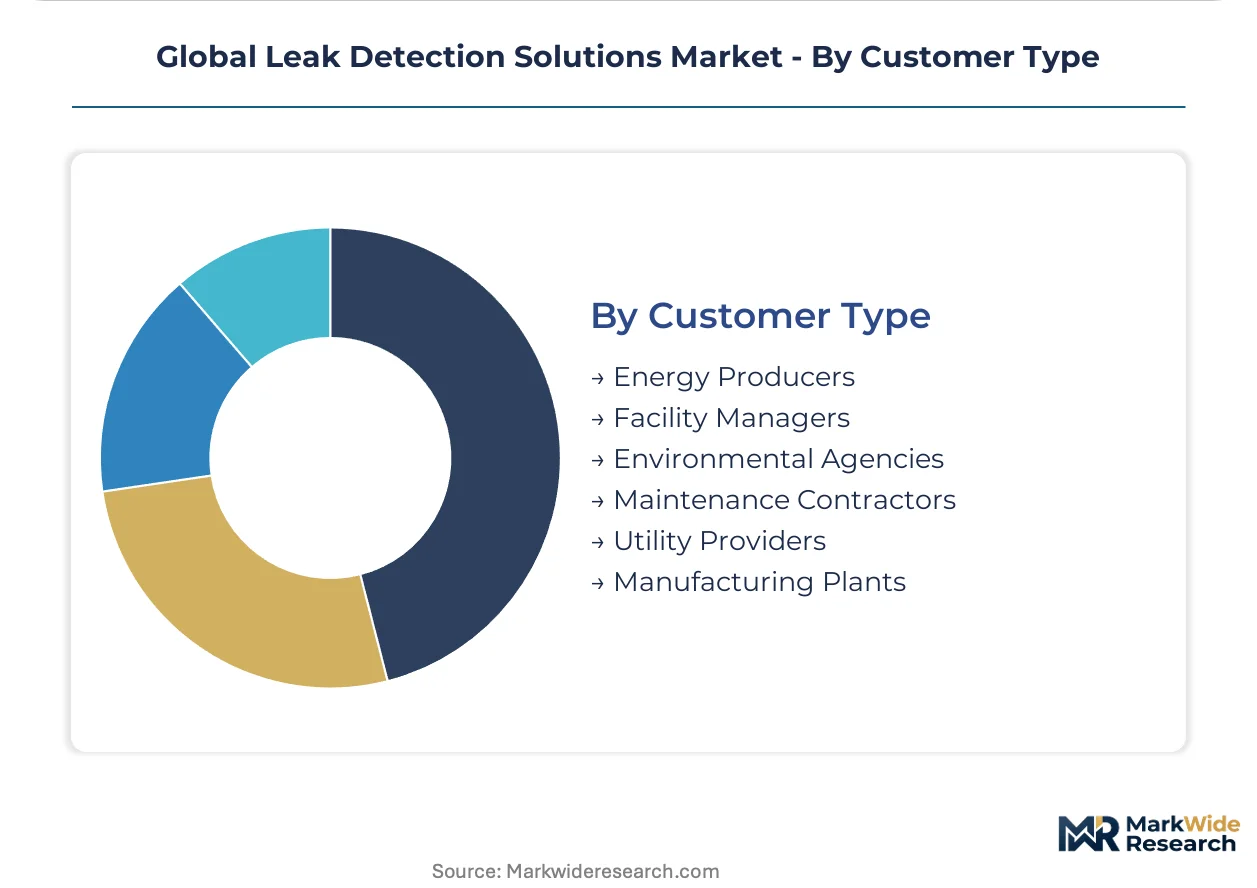
Customer Type:
Energy producers and utility providers drive large-scale integrated procurement, while environmental agencies and maintenance contractors fragment demand across compliance-focused spot purchases.
- Energy Producers:Upstream and midstream oil and gas operators mandating infrastructure upgrades under EPA methane emission rules. Continuous monitoring deployment compresses procurement cycles from quarterly inspections to real-time system procurement.
- Facility Managers:Petrochemical complex operators in Netherlands and Belgium preferring performance-based service agreements covering sensor maintenance, calibration, and cloud analytics.
- Environmental Agencies:Regulatory enforcement bodies specifying certification requirements for third-party verification services.
- Maintenance Contractors:HVAC and refrigeration service providers upgrading to portable optical detectors for EU F-Gas inspection density compliance.
- Utility Providers:Multi-site infrastructure managers subscribing to centralized alert management platforms for distributed portfolio oversight.
- Manufacturing Plants:Process industry operators integrating leak detection with distributed control system architectures.
Energy producers command the largest procurement volumes; facility managers are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany demonstrate the lowest price elasticity as hydrogen infrastructure mandates override procurement budgets, while Indian chemical processors exhibit acute cost sensitivity that compresses vendor margins on optical gas imaging systems.
United States
Midstream operators across the Permian Basin and Texas shale corridors drive fixed acoustic sensor deployments under EPA methane monitoring mandates. New Source Performance Standards compel continuous emission detection at upstream facilities, eliminating periodic survey compliance models. Houston-headquartered energy producers bundle leak detection with SCADA upgrade cycles.
Germany
The national hydrogen backbone buildout commands specialized electromagnetic sensor arrays calibrated for molecular dispersion rates. EU F-Gas Regulation enforcement tightens certification requirements for HVAC and refrigeration leak detection equipment. Industrial clusters in North Rhine-Westphalia pilot pressurized gas network monitoring for hydrogen distribution infrastructure.
India
Chemical processing facilities near Gujarat and Maharashtra adopt portable optical detectors for volatile organic compound compliance under tightening industrial safety mandates. The Central Electricity Authority guidelines shape certification requirements for utility-scale deployment. Cost-conscious procurement favors wireless battery-powered nodes over fiber-optic trenching in remote terrain.
Canada
Oil sands operators in Alberta face accelerated battery drain constraints for wireless acoustic sensors in sub-zero climates. Federal methane regulations align with EPA stringency, compelling midstream infrastructure upgrades. Calgary-based pipeline operators test distributed intelligence networks to compress rupture response times.
Japan
METI safety guidelines drive ultrasonic detector deployment in industrial clusters around Nagoya and Osaka. High-frequency emission detection systems concentrate in petrochemical and semiconductor manufacturing facilities. Domestic vendors supply pressurized gas monitoring equipment with precision calibration protocols for cleanroom environments.
Global Leak Detection Solutions Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with conglomerates leveraging control system footprints to bundle hardware-software contracts while pure-play sensor vendors compete on calibration precision and niche detection modalities. The market structure rewards backward integration into fiber-optic cable manufacturing and cloud analytics platforms. Three archetypes dominate: diversified industrial conglomerates with process automation legacies, specialist sensor manufacturers with petroleum engineering expertise, and emerging optical technology firms with gas imaging intellectual property. Competitive moves concentrate on strategic partnerships for hydrogen-specific certification and geographic expansion through regional system integrators.
Within the integrated conglomerate tier, Honeywell International Inc. and Emerson Electric Co. occupy positions that exemplify control system bundling strategies, while Siemens Energy anchors European hydrogen infrastructure archetypes through electromagnetic specialization. These three entities represent contrasting geographic footprints—American industrial diversification, American ultrasonic leadership, and German energy infrastructure focus—without exclusive claims to technology superiority or market share dominance.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Emerson Electric Co. |
| Siemens Energy |
| Schneider Electric |
| ABB |
| Teledyne FLIR LLC |
| Aeris Technologies Inc. |
| Bridger Photonics |
| Pentair |
| Others |
Supply & Pricing Matrix
Long-term service contracts with embedded calibration schedules lock in both sensor hardware supply and predictable lifetime revenue visibility for vendors serving EPA-mandated methane monitoring programs. This contract structure concentrates pricing power with integrated conglomerates while forcing specialist sensor manufacturers to compete on aftermarket service attach rates.
Pricing Analysis
Aftermarket service and recalibration revenue streams drive lifetime customer value beyond initial hardware deployment. Three-tier pricing structure across premium, standard, and economy levels stratifies by sensor modality complexity and certification grade for hydrogen-specific applications. Cost compression in wireless node segments intensifies as battery chemistry suppliers face raw material volatility. Indian chemical processors exhibit acute price sensitivity, while German hydrogen infrastructure buyers demonstrate minimal elasticity under regulatory mandate pressure.
Supply Chain Analysis
Inventory lead times for fiber-optic sensing cables stretch to six months as specialized coating facilities in Germany, Japan, and the United States operate at capacity. Component sourcing draws from precision photonics foundries in Taiwan, rare-earth magnet suppliers in China, and semiconductor fabrication in South Korea. Single-source vulnerability concentrates in distributed temperature sensing cable manufacturing. Distribution runs through regional system integrators who bundle installation with SCADA protocol bridging services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EPA methane rule disruption compresses procurement cycles from quarterly inspections to real-time system deployment, creating structural openings for vendors with cloud-native analytics platforms.
For Market Incumbents: Fortify control system bundling advantages by deepening backward integration into fiber-optic cable manufacturing and expanding calibration service networks across Permian Basin shale corridors. Emerging optical technology firms with gas imaging intellectual property threaten premium positioning in volatile organic compound detection. Certification investment for ISO hydrogen working group standards represents the critical defensive lever. For New Entrants and Emerging Players: Cloud-based multi-site alert management platforms offer the most penetrable service-layer gap where Honeywell and Emerson under-serve mid-tier utility providers. Wireless battery-powered node arrays for remote Canadian oil sands terrain present white-space opportunity with reduced trenching value propositions. Go-to-market through Alberta-based regional system integrators bypasses direct incumbent channel conflict. For Investors and Strategic Acquirers: Specialist sensor manufacturers with petroleum engineering algorithm expertise and established EPA compliance track records represent the highest-conviction acquisition archetype. Long-term viability hinges on hydrogen infrastructure certification positioning as molecular leak rate standards crystallize. Watch for ISO working group finalization timelines as the definitive inflection signal for sensor sensitivity recalibration demand spikes.| Strategic Initiative | Industry Significance |
|---|---|
| Hydrogen-Specific Certification Investment | Positions vendors for Germany's national hydrogen backbone procurement cycles under pending ISO standards. |
| Cloud Platform Integration Partnership | Enables recurring revenue capture from utility providers managing distributed pipeline portfolios. |
| Regional System Integrator Acquisition | Accelerates deployment velocity for SCADA retrofitting at aging US midstream facilities. |
| Fiber-Optic Cable Manufacturing Scale-Up | Reduces lead time vulnerability for kilometer-scale distributed temperature sensing deployments. |
| Edge AI Inference Development | Compresses rupture response times from minutes to seconds for Texas and Alberta operators. |
Research Methodology
Operator-level perspectives from pipeline integrity managers, SCADA engineers, environmental compliance officers, and HVAC service contractors anchored the qualitative base. Primary interview data combined with secondary validation from EPA enforcement databases, FERC pipeline safety filings, EU ECHA regulatory updates, and German hydrogen infrastructure project announcements. Bottom-up sensor deployment modeling and top-down energy infrastructure capex analysis provided triangulation across market sizing estimates.
Sensitivity analysis tested forecast robustness across alternative hydrogen adoption timelines and methane regulation enforcement intensities. Segmentation modeling spanned solution type, deployment mode, use case, and customer archetype dimensions across the projection horizon. CAGR derivation incorporated pipeline mileage expansion rates, EPA compliance deadline clustering, and hydrogen molecular dispersion calibration protocol adoption curves.
Underlying assumptions cover continuous monitoring mandate permanence and ISO hydrogen standard finalization, with deviation risk concentrated in regulatory enforcement variability and battery chemistry supply disruptions. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Automatic Water Level Controller Market
Pumps and Control Devices
API 610 Pumps Market
Pumps and Control Devices
Global Hydraulic Gear Pump Market
Pumps and Control Devices
Oil and Gas Actuators Market
Pumps and Control Devices
Radial Split Pump Market
Pumps and Control Devices
Europe Positive Displacement Pumps Market
Pumps and Control Devices
Radial Piston Pumps Market
Pumps and Control Devices
Bubble Membrane Disc Diffuser Market
Pumps and Control Devices
Marine Pump Market
Pumps and Control Devices
Electrostatic Coalescers Market
Pumps and Control Devices
Industrial Pumps Market
Pumps and Control Devices
Southeast Asia Submersible Pumps Market
Pumps and Control Devices
Cryogenic Process Pumps Market
Pumps and Control Devices
Asia-Pacific Peristaltic Pumps Market
Pumps and Control Devices
Global Lobe Pumps Market
Pumps and Control Devices
Progressive Cavity Pump (PCP) Market