
 Concrete Wind Tower Market | 2026-2036
Concrete Wind Tower Market Size, Share, and Industry Trends Forecast 2026-2036
Concrete Wind Tower Market Outlook
Steel reinforcement is consolidating its cost advantage over traditional tubular steel in multi-megawatt tower designs. Arcosa Wind Towers leverages vertical integration across concrete batching and steel cage fabrication to control input costs. CS Wind Corporation anchors its position through manufacturing scale in Asia-Pacific supply nodes. Max Bögl Wind specializes in hybrid tower systems that extend hub heights beyond conventional steel limits.
Concrete wind towers are reinforced concrete structures, typically 80-140 meters tall, manufactured through slip-form or precast segment methods to support nacelle assemblies in utility-scale wind farms. Precast concrete technology dominates current installations due to transport modularity and quality control, while lightweight concrete formulations represent the fastest-growing technology segment as developers pursue taller hub heights without crane capacity constraints. Hybrid product types command premium positioning by combining steel base sections with concrete upper towers, whereas monopole designs retain cost leadership in onshore markets with standard hub heights below 120 meters.
The EU Green Deal and F-Gas Regulation shape material specifications by penalizing high-carbon concrete mixes and rewarding recycled aggregate content, while national building codes in Germany and Denmark enforce seismic and fatigue standards for tower structural certification. ISO 14025 environmental product declarations increasingly gate market access for European utility procurements. Stakeholders must monitor evolving carbon-border adjustment mechanisms and precast manufacturing automation investments that will determine cost competitiveness against steel alternatives in offshore deployment scenarios.
Market Dynamics
Steel price volatility and embodied-carbon accounting are compressing procurement timelines for precast concrete alternatives, forcing utilities to lock multi-year supply contracts before carbon-border adjustments take full effect.
Growth Catalysts
- EU Green Deal carbon-border adjustments:Germany's F-Gas Regulation penalizes high-carbon concrete mixes, accelerating specification shifts toward recycled aggregate formulations in North Sea offshore tenders.
- Hub height extension demand:Utility-scale developers in Denmark require tower systems exceeding 140 meters to access higher wind speeds, where hybrid concrete-steel designs outperform tubular steel on fatigue resistance.
- Precast manufacturing automation:Robotic cage welding and automated segment casting are compressing production cycle times at Vestas and Siemens Gamesa supplier clusters.
Market Restraints
- Reinforcement steel cost volatility:Rebar price swings of 40% within single quarters destabilize project economics for fixed-price EPC contracts.
- Transport radius constraints:Precast segment dimensions hit road infrastructure limits beyond 150 kilometers from coastal manufacturing sites, concentrating supply risk in Denmark and northern Germany.
- Crane capacity scarcity:Tall hybrid towers require 1,000-tonne crawler cranes with limited availability in Baltic Sea port zones during summer installation windows.
Strategic Opportunities
- Polish Baltic offshore pipeline:Poland's 10.5 GW offshore auction schedule lacks domestic tower manufacturing, creating first-mover positioning for precast exporters with port access at Gdańsk.
- Lightweight concrete formulations:Density reductions below 2,200 kg/m³ using cenospheres and expanded clay aggregates enable taller monopole designs without crane upgrades.
- ISO 14025 EPD gating:Environmental product declarations are becoming mandatory in Swedish and Dutch utility procurements, rewarding early certification investments.
Industry Challenges
- Fatigue certification timelines:IEC 61400-6 full-scale testing protocols require 18-24 months for new hybrid tower geometries, delaying project financial close.
- Seismic design standard fragmentation:German DIN codes and Danish DS standards impose conflicting damping requirements for turbine-tower interaction models.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Concrete Wind Tower Market |
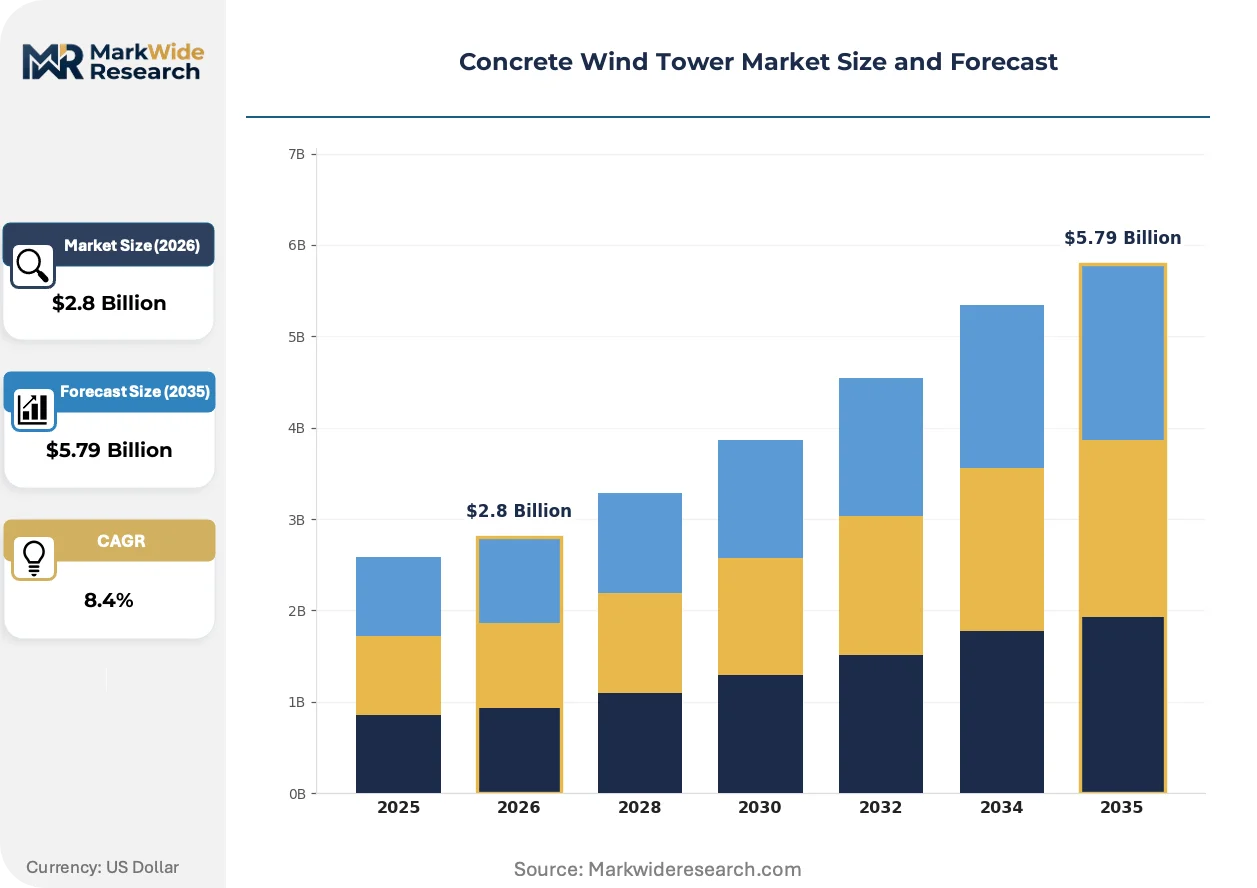
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.79 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monopole, Hybrid, Modular, Self-Supporting Technology: Precast Concrete, Reinforced Concrete, Lightweight Concrete, High-Strength Concrete Installation Method: Onshore, Offshore, Crane Assembly, Pre-Configured Modules End User: Utility Companies, Independent Power Producers, Government Agencies, Renewable Energy Developers |
| Companies Covered | Norten PH, Arcosa Wind Towers, Windtechnic Engineering, Titan Wind Energy, Valmont Industries, Max Bögl Wind, CS Wind Corporation, Marmen, Goldwind, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Concrete Wind Tower Market Strategic Shifts
Material science advances and procurement protocol tightening are rewriting how tower specifications get locked during project development, compressing the window between conceptual design and final investment decision.
Ultra-high-performance concrete (UHPC) with steel fiber reinforcement is rewriting durability expectations for offshore splash-zone sections. Developers in the Danish North Sea cluster specify UHPC jacketing for monopile transitions, accepting 30% material cost premiums to eliminate cathodic protection systems. This substitution is compressing lifetime maintenance schedules from 25-year cycles to 40-year design lives.
Germany's F-Gas Regulation and parallel EU Green Deal implementation are mandating embodied-carbon disclosure for all public-utility procurements above 50 MW. Project developers now face binding penalties for concrete mixes exceeding 250 kg CO₂/m³, forcing reformulation around ground granulated blast-furnace slag and calcined clay cements. Danish certification bodies have responded by fast-tracking EPD verification for low-carbon precast suppliers.
Long-term service agreements are displacing traditional equipment-only contracts in utility procurement. Offshore wind farm operators in the German Bight now bundle tower supply with 15-year structural monitoring and predictive maintenance, transferring fatigue-risk liability to manufacturers. This unbundling is most visible where insurance markets refuse to underwrite tower performance without continuous sensor coverage.
Concrete Wind Tower Market Segmentation
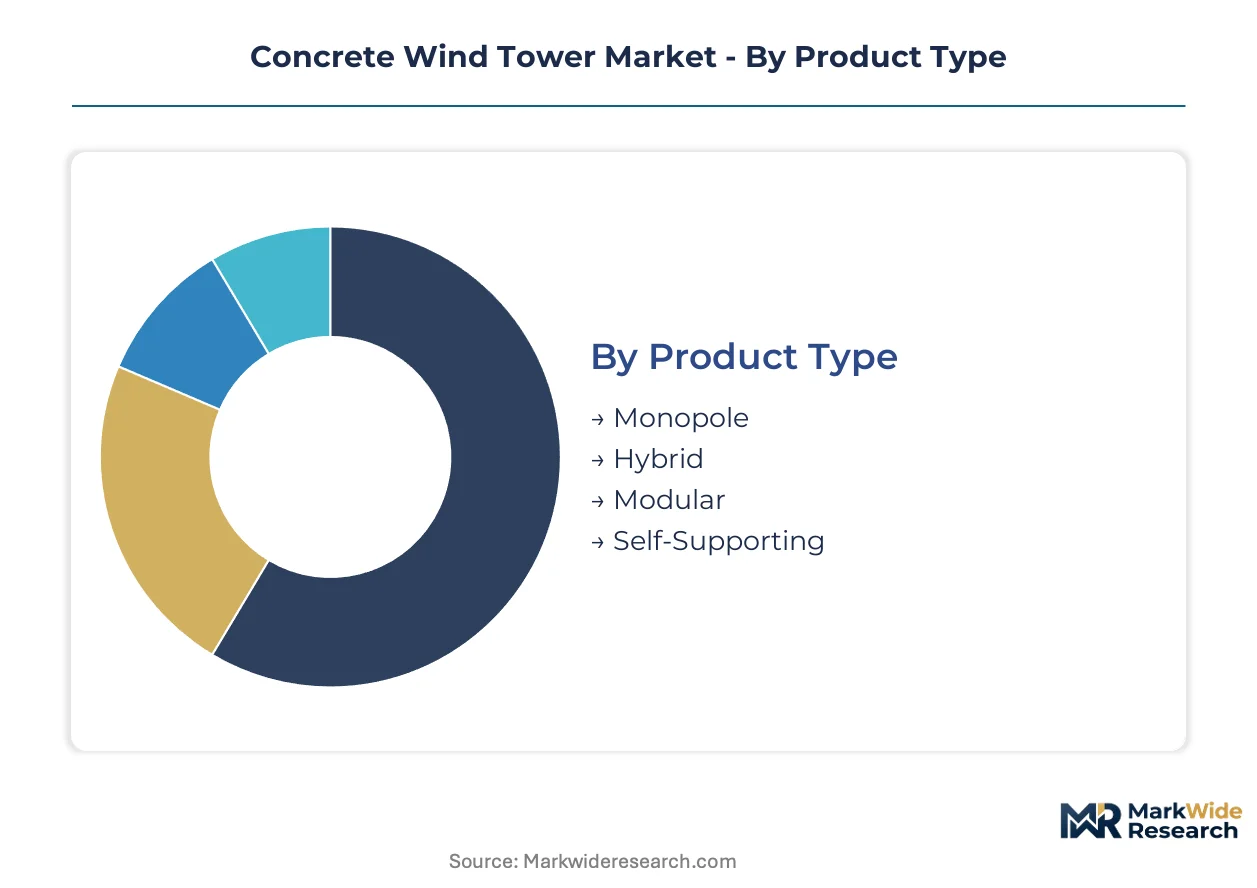
Concrete wind tower procurement diverges sharply across installation environment, structural configuration, and buyer risk tolerance. Segment boundaries determine manufacturing automation investments, transport logistics, and certification timelines for suppliers competing in North Sea offshore clusters and continental onshore markets.
Product Type:
Buyers select tower configurations based on hub height targets, crane availability, and fatigue-life requirements for specific wind regimes.
- Monopole:Single-cast reinforced concrete shafts dominate onshore installations below 120 meters. German utilities specify monopole designs for Baltic corridor projects where transport infrastructure accommodates full-length casting delivery.
- Hybrid:Steel base sections paired with concrete upper towers extend hub heights beyond 140 meters. Danish developers at Horns Rev and Kriegers Flak deploy hybrid systems to access high-altitude wind speeds without exceeding crane lift limits.
- Modular:Segment-stacked configurations enable road transport of precast rings to remote sites. Polish renewable energy developers favor modular delivery for inland wind farms lacking coastal manufacturing proximity.
- Self-Supporting:Tapered concrete shells eliminate external bracing for aesthetic-sensitive installations. German municipal utilities specify self-supporting towers near residential zones to minimize visual impact objections.
Monopole designs lead volumes today; hybrid configurations are gaining share fastest in offshore tenders.
Technology:
Material formulation choices reflect embodied-carbon accounting pressures and height-extension engineering constraints.
- Precast Concrete:Factory-cast segments with robotic cage welding dominate current manufacturing. Vestas and Siemens Gamesa supplier clusters in Denmark achieve quality consistency through automated segment casting for North Sea projects.
- Lightweight Concrete:Density reductions below 2,200 kg/m³ using cenospheres and expanded clay aggregates enable taller monopole designs. Developers in crane-constrained Baltic Sea ports specify lightweight formulations to avoid 1,000-tonne crawler upgrades.
- Reinforced Concrete:Traditional steel-rebar construction retains cost leadership in standard-height onshore markets. German EPC contractors specify reinforced concrete for fixed-price contracts where material cost certainty outweighs weight optimization.
- High-Strength Concrete:Ultra-high-performance mixes with steel fiber reinforcement target offshore splash-zone durability. Danish North Sea developers accept 30% material premiums for UHPC jacketing that eliminates cathodic protection systems.
Precast concrete anchors current procurement volumes; lightweight concrete formulations are expanding most quickly as hub height requirements escalate.
Installation Method:
Deployment logistics separate coastal manufacturing clusters from inland markets with infrastructure constraints.
- Onshore:Road-transportable precast segments serve continental European wind corridors. German and Polish developers specify onshore-optimized designs for sites beyond 150 kilometers from coastal manufacturing nodes.
- Offshore:Pre-assembly at port facilities with heavy-lift vessel transport dominates North Sea deployment. Danish port zones at Esbjerg and Grenaa anchor offshore installation capacity for utility-scale arrays.
- Crane Assembly:Traditional lift-and-stack erection requires 600-tonne crawler availability. Baltic Sea summer installation windows face crane capacity scarcity that compresses project schedules.
- Pre-Configured Modules:Factory-integrated tower-nacelle assemblies reduce offshore weather risk. Siemens Gamesa tests pre-configured modules at Danish test centers to minimize offshore hook time.
Onshore installation retains volume leadership; offshore methods are climbing the fastest as auction pipelines expand in Polish and German waters.
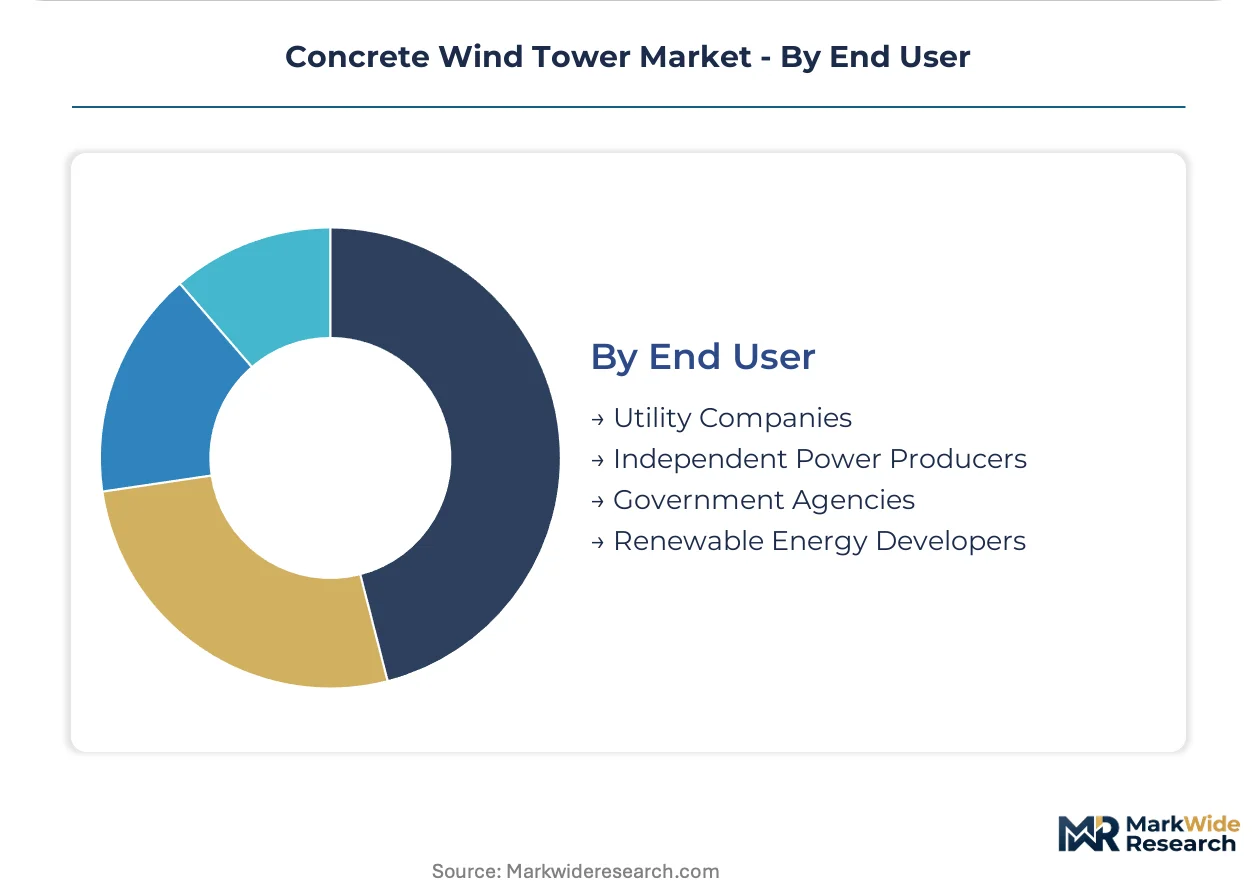
End User:
Procurement sophistication and contract duration preferences segment buyer categories.
- Utility Companies:Vertically integrated European utilities lock multi-year supply contracts before carbon-border adjustments take full effect. German municipal utilities bundle tower supply with 15-year structural monitoring agreements.
- Renewable Energy Developers:Project finance-dependent developers prioritize equipment-only contracts with transfer of fatigue-risk liability. Danish independent developers favor developers with ISO 14025 EPD certification to satisfy lender environmental covenants.
- Independent Power Producers:Merchant power investors seek standardized tower specifications to accelerate financial close timelines. Polish IPPs entering Baltic offshore auctions specify pre-certified designs to avoid IEC 61400-6 testing delays.
- Government Agencies:State-owned procurement entities mandate embodied-carbon disclosure above 50 MW under EU Green Deal implementation. German federal agencies enforce F-Gas Regulation compliance through binding penalties for high-carbon concrete mixes.
Utility companies dominate current procurement volumes; renewable energy developers are capturing share fastest as merchant offshore projects multiply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Danish North Sea cluster anchors manufacturing scale for utility-scale offshore arrays, with Vestas and Siemens Gamesa supplier networks concentrating precast production at Esbjerg and Grenaa port zones.
Germany
Utility companies expand procurement of precast concrete towers as steel price volatility persists. The F-Gas Regulation and EU Green Deal carbon-border adjustments penalize high-carbon concrete mixes exceeding 250 kg CO₂/m³. Manufacturing concentrates in northern Germany, where Baltic corridor projects accommodate full-length monopole casting delivery.
Denmark
Developers at Horns Rev and Kriegers Flak deploy hybrid concrete-steel systems to access wind speeds above 140 meters. Danish certification bodies fast-track ISO 14025 EPD verification for low-carbon precast suppliers. The Esbjerg port zone anchors offshore installation capacity with automated segment casting from Vestas and Siemens Gamesa clusters.
Poland
The 10.5 GW Baltic offshore auction schedule lacks domestic tower manufacturing, creating export positioning for precast suppliers. Polish renewable energy developers favor modular segment delivery for inland wind farms beyond 150 kilometers from coastal nodes. Gdańsk port access enables first-mover positioning for North Sea fabricators.
Sweden
Utility procurements mandate ISO 14025 environmental product declarations above 50 MW under EU Green Deal implementation. Swedish developers specify lightweight concrete formulations to avoid 1,000-tonne crawler crane upgrades in Baltic Sea ports. Manufacturing concentrates at coastal facilities serving North Sea merchant offshore projects.
Netherlands
Environmental product declarations gate market access for European utility tenders, rewarding early certification investments. Dutch procurement protocols enforce embodied-carbon disclosure for public-utility contracts. Rotterdam port infrastructure supports heavy-lift vessel transport for offshore pre-assembly operations.
Concrete Wind Tower Market Competitive Environment
Global majors compete with regional champions across manufacturing automation and carbon-certification capabilities. The vendor base organizes around scale-driven volume producers, technology-integrated hybrid specialists, and port-proximate precast fabricators. Three archetypes dominate: vertically integrated conglomerates controlling batching-to-assembly workflows, mid-cap specialists in lightweight formulations, and coastal logistics-anchored exporters. Capacity expansion and strategic partnerships represent the dominant competitive moves, with players locking multi-year supply contracts before carbon-border adjustments take full effect.
Among named participants, Arcosa Wind Towers exemplifies vertical integration across concrete batching and steel cage fabrication. Max Bögl Wind occupies a position within hybrid tower systems that extend hub heights beyond conventional limits. CS Wind Corporation anchors Asian-Pacific supply positioning through manufacturing scale at regional nodes. These three represent distinct strategic archetypes: input-cost control, height-extension engineering, and geographic diversification.
| Leading Market Players |
|---|
| Norten PH |
| Arcosa Wind Towers |
| Windtechnic Engineering |
| Titan Wind Energy |
| Valmont Industries |
| Max Bögl Wind |
| CS Wind Corporation |
| Marmen |
| Goldwind |
| Others |
Value Chain & Pricing Dynamics
EU Green Deal carbon-border adjustments are forcing utilities to lock multi-year supply contracts before penalties take full effect, compressing supplier lead times and shifting pricing power toward precast fabricators with certified low-carbon formulations. This procurement acceleration rewards early movers with port-proximate manufacturing while penalizing distant suppliers facing transport radius constraints.
Pricing Analysis
Input-cost pass-through from rebar and cement price volatility dominates contract structures, with fixed-price EPC agreements absorbing 40% quarterly steel swings. Pricing stratifies across premium, standard, and economy tiers based on ISO 14025 EPD certification status and after-sales monitoring bundling. Cost compression in standard-height monopole segments is intensifying because German utilities are consolidating procurement volumes. Renewable energy developers exhibit highest price sensitivity due to project finance leverage constraints, while integrated utilities accept premiums for fatigue-risk transfer.
Supply Chain Analysis
Regional distribution centers at Esbjerg and Grenaa anchor hub-and-spoke patterns serving North Sea offshore clusters, with precast segments flowing through Baltic Sea port zones during compressed summer installation windows. Manufacturing concentrates in Denmark, Germany, and Poland, drawing from rebar suppliers in Turkey and Ukraine, cement from regional European producers, and specialized aggregates from Scandinavian quarries. Single-source vulnerability around 1,000-tonne crawler crane availability at Baltic ports presents structural risk. Distribution runs through coastal manufacturing nodes with 150-kilometer road-transport radii for inland markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story. Danish and German utilities are shifting procurement toward hybrid tower systems with 15-year structural monitoring agreements, elevating specification premiums for certified suppliers.
For Market Incumbents: Lock in multi-year supply contracts with Polish Baltic offshore developers before domestic manufacturing emerges. Prioritize backward integration into steel cage fabrication to buffer rebar volatility. Defend against emerging lightweight concrete specialists by accelerating ISO 14025 EPD certification across product lines. For New Entrants and Emerging Players: Enter via Poland's 10.5 GW offshore auction pipeline where domestic tower manufacturing is absent. Target modular segment delivery for inland Polish wind farms beyond coastal manufacturing radii. Lead with Gdańsk port access and fast-tracked Danish certification to bypass incumbent logistics advantages. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-cap precast fabricators possessing automated segment casting and existing EPD certification. Long-term viability hinges on 5-10 year positioning within Baltic offshore installation corridors. Watch for Polish auction award announcements as inflection indicators for capacity utilization rates.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Automated precast segment casting at Danish port zones reduces production cycle times for Vestas and Siemens Gamesa supplier clusters. |
| Backward Integration | In-house steel cage fabrication buffers Arcosa Wind Towers against rebar price volatility destabilizing fixed-price EPC contracts. |
| Green Certification Program | ISO 14025 EPD investments unlock Swedish and Dutch utility procurements mandating embodied-carbon disclosure above 50 MW. |
| Long-term Supply Agreement | 15-year structural monitoring bundles transfer fatigue-risk liability from German municipal utilities to tower manufacturers. |
| Joint Venture | Polish Baltic partnerships with Gdańsk port operators enable first-mover positioning for North Sea fabricators entering auction pipeline. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary discussions with utility planning officers, EPC contractors, precast manufacturing plant managers, and wind farm project developers informed demand-side assumptions. Secondary validation drew from EIA wind installation data, IEA renewable energy reports, EU Green Deal implementation documents, and national auction pipeline databases. Bottom-up project economics modeling and top-down sector expenditure analysis were cross-referenced for triangulation.
Segment-weighting approaches applied differential growth assumptions across product types, technologies, and installation methods. The analytical framework incorporated hub height extension trends, carbon-border adjustment phase-in schedules, and crane capacity constraints throughout the projection horizon. CAGRs were derived from installed capacity forecasts and tower-specific cost curves. Industry-specific inputs included IEC 61400-6 certification timelines and F-Gas Regulation compliance cost structures.
Inputs from utility procurement databases and national auction registries were available through the study window; gaps in real-time rebar price indices and crane fleet utilization data introduce uncertainty bands around margin projections. Forecasts reflect documented assumptions about regulatory implementation pace and technology adoption curves. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Structural Engineering
Global Concrete Restoration Market
Structural Engineering
Civil Engineering Market
Structural Engineering
Self-Healing Concrete Market
Structural Engineering
Asia-Pacific Structural Health Monitoring Market
Structural Engineering
Europe Bridge Bearings Market
Structural Engineering
Self-Compacting Concrete Market
Structural Engineering
Metal Structural Insulation Panels Market
Structural Engineering
Bridge Bearing Pad Market
Structural Engineering
Offshore Structural Analysis Software Market
Structural Engineering
Fabricated Structural Steel Market
Structural Engineering
Cold-Formed Steel Market
Structural Engineering
Structural Lightweight Concrete Market
Structural Engineering
Structural Steel Market
Structural Engineering
Steel Structure Anchor Bolt Market
Structural Engineering
Self-Levelling Concrete Market
Structural Engineering
High Damping Rubber Bearing (HDRB) Market