
 Metal Grating Market | 2026-2036
Metal Grating Market Size, Share, and Industry Trends Forecast 2026-2036
Metal Grating Market Outlook
Heavy-duty specification upgrades across industrial flooring is rotating demand toward higher-load-capacity products. Nucor Corporation leverages its integrated steel supply chain to dominate North American production of welded bar grating. Valmont Industries sustains competitive positioning through its specialized focus on engineered access products for utility and infrastructure clients. Ohio Gratings anchors regional distribution density across the Midwest manufacturing belt.
Metal grating consists of bearing bars and cross rods welded, swaged, or press-locked into open-grid panels, typically fabricated from carbon steel, aluminum, or stainless steel with load ratings spanning 3 to 15 kN per square meter, designed to provide structural support, drainage, and safe passage in industrial environments. Steel grating retains the largest share of material demand due to its cost-efficiency in heavy industrial applications, while aluminum grating captures premium segments where corrosion resistance and weight reduction matter. Heavy duty and ultra heavy duty load capacity tiers command the strongest margin pools as engineering certification requirements intensify for energy and marine infrastructure.
The US Occupational Safety and Health Administration and the American National Standards Institute enforce load-testing and slip-resistance protocols that directly shape product specifications and procurement criteria for domestic installations. The European Committee for Standardization mandates CE-marked gratings under EN ISO 14122 for machinery access, creating compliance barriers for non-certified imports. Stakeholders must monitor evolving harmonization between regional safety codes and material sustainability disclosures as specification authority shifts from general contractors to asset owner engineering teams.
Market Dynamics
OSHA's elevated load-bearing mandates for industrial walkways are compressing specification cycles and forcing asset owners to pre-certify grating suppliers before project bidding, reshaping competitive access to energy and marine infrastructure contracts.
Growth Catalysts
- Offshore platform retrofit mandates:Gulf Coast petrochemical operators are replacing legacy flooring ahead of insurance renewal cycles, pulling heavy-duty steel grating into maintenance budgets.
- EN ISO 14122 harmonization:European machinery access standards are creating export certification pull for CE-marked gratings in adjacent industrial safety markets.
- Corrosion-resistant alloys:Aluminum grating specifications are penetrating coastal desalination and chemical processing where salt exposure degrades carbon steel life cycles.
Market Restraints
- Scrap steel price volatility:Electric arc furnace feedstock costs swing with demolition and automotive shredder output, compressing margin predictability for welded bar producers.
- Import concentration risk:Asian fabricated grating shipments face extended customs holds at US ports when documentation gaps trigger CE-marking verification delays.
- Composite material substitution:Fiber-reinforced polymer access platforms are displacing metal grating in weight-critical rooftop and mezzanine applications.
Strategic Opportunities
- US inland waterway lock rehabilitation:Army Corps of Engineers maintenance backlogs are opening specification windows for stainless steel grating in marine navigation infrastructure.
- Green hydrogen electrolyzer buildout:Gulf Coast and North Sea facility developers require explosion-rated aluminum walkways around pressurized gas handling skids.
- Direct-to-fabricator digital channels:Configurator-enabled ordering is compressing lead times for custom-cut panels in maintenance-repair-operations procurement.
Industry Challenges
- Welding certification scarcity:AWS D1.1 structural welding qualifications lag demand for coded welders in bar-to-cross-rod fabrication cells.
- Load-test documentation backlog:Third-party laboratory capacity constraints extend UL or Intertek certification timelines for new heavy-duty product introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Metal Grating Market |
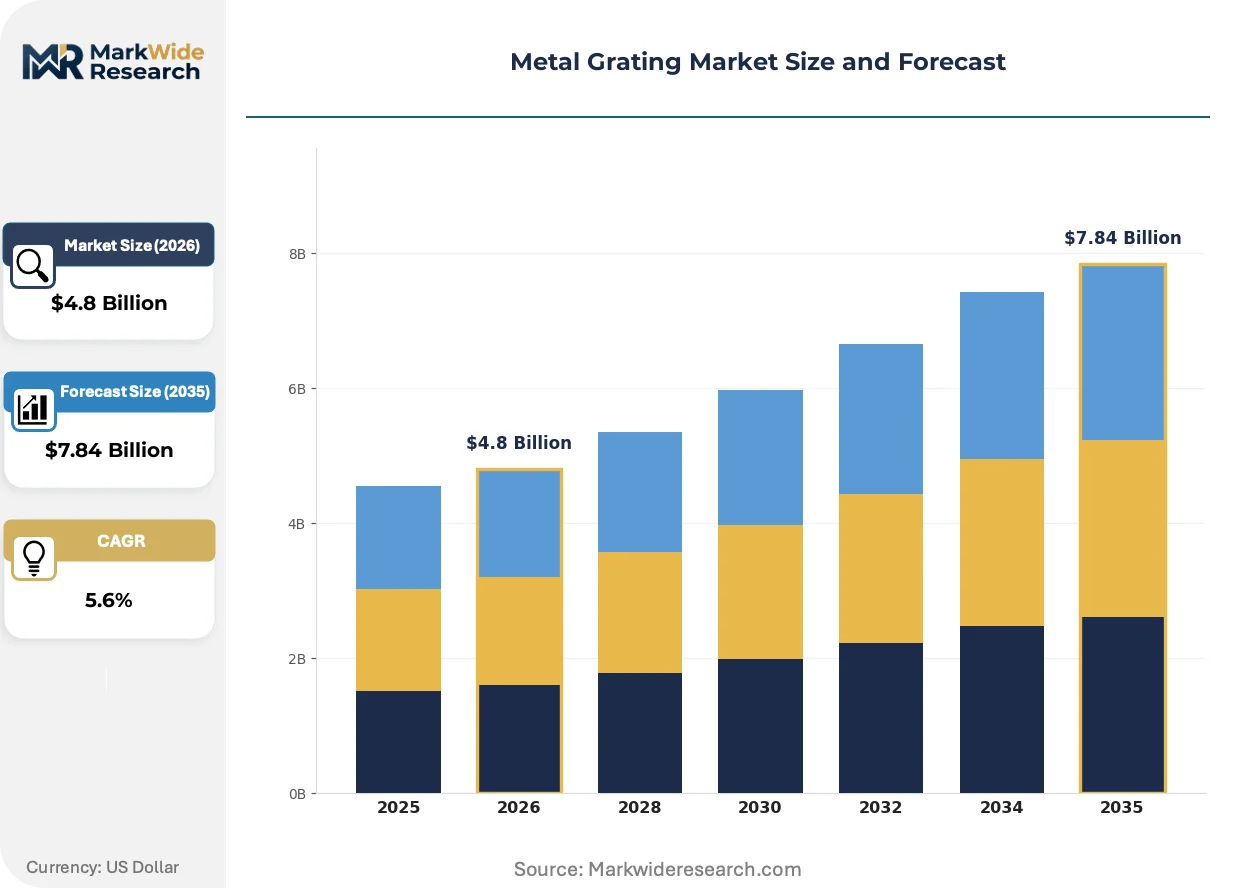
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.84 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Aluminum, Steel, Stainless Steel, Fiber Reinforced Plastic Load Capacity: Light Duty, Medium Duty, Heavy Duty, Ultra Heavy Duty Application: Industrial Flooring, Walkways, Trench Covers, Stair Treads Installation Type: Permanent, Portable, Modular, Custom Fabrication |
| Companies Covered | Nucor Corporation, Valmont Industries, Ohio Gratings, Interstate Gratings, Alabama Metal Industries Corporation, P&R Metals, Lionweld Kennedy, Lichtgitter GmbH, Grating Pacific, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Metal Grating Market Strategic Shifts
Digital specification tools and modular fabrication methods are compressing traditional engineer-to-order cycles, while regulatory load-testing protocols are hardening into procurement gatekeepers that filter supplier pools before commercial negotiations begin.
Modular press-locked grating systems are decomposing the traditional welded-bar dominance in platform construction. Offshore wind turbine service vessel operators specify these lighter aluminum assemblies to reduce topside weight while maintaining heel-angle slip resistance. The shift is compressing supplier qualification timelines as shipyards demand pre-certified panel systems rather than site-fabricated solutions.
OSHA's updated Walking-Working Surfaces standard is forcing slip-resistance testing documentation into every industrial bid package. Facility owners now require coefficient-of-friction certificates traceable to specific lot production runs. Gulf Coast chemical plants and Great Lakes ore docks are the most aggressive enforcers, rejecting shipments that lack ASTM F1679 test data.
Asset owners are consolidating specification authority away from general contractors and into captive engineering teams. Energy majors and port authorities now issue master service agreements directly with grating fabricators, locking in volume commitments and bypassing distributor markups. This concentration is most visible in Texas-Louisiana petrochemical clusters where owner-operators maintain permanent vendor qualification staff.
Metal Grating Market Segmentation
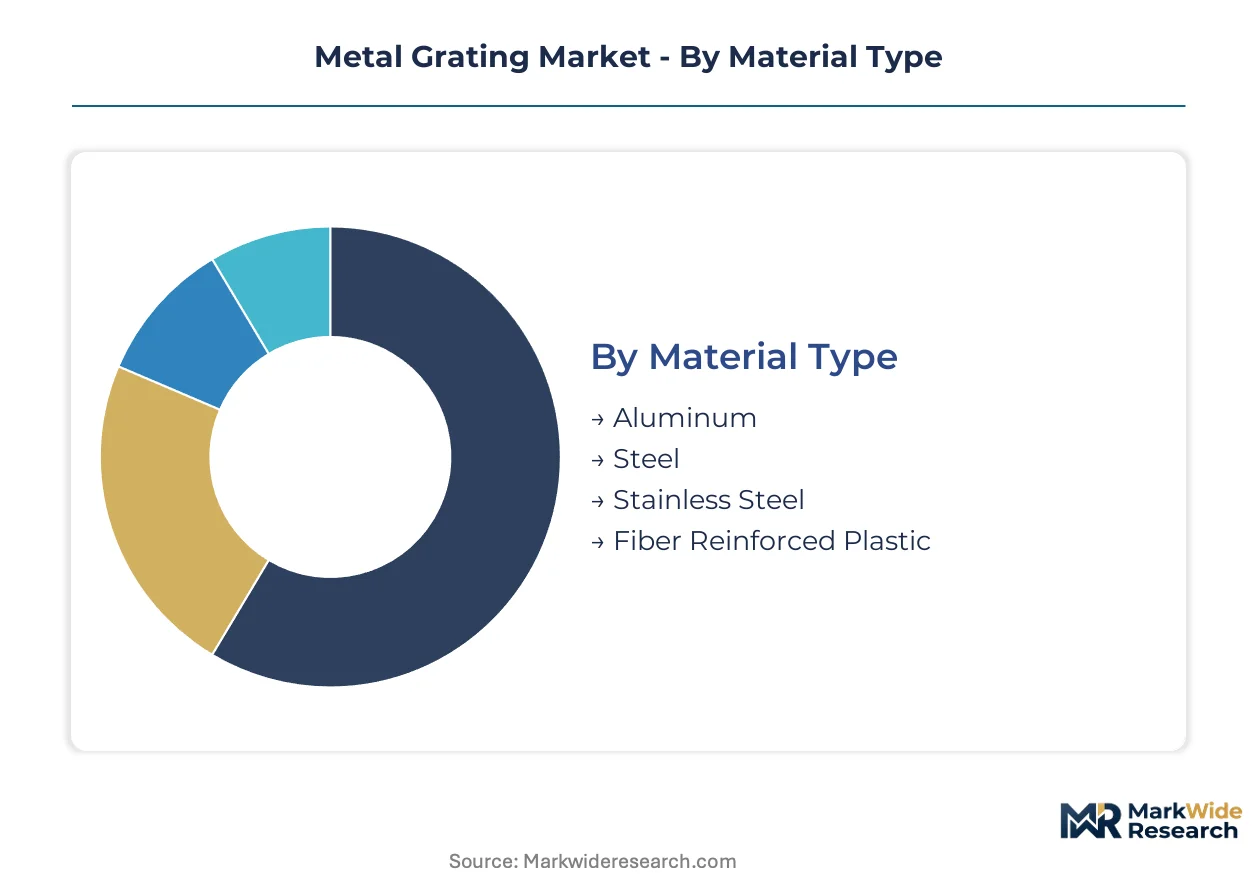
Metal grating procurement splits across material chemistry, structural rating, and installation context. Specification authority increasingly rests with asset owner engineering teams who weight lifecycle cost against regulatory compliance.
Material Type:
Steel commands the deepest margin pools due to volume scale in heavy industrial procurement, while aluminum extracts premium pricing in corrosion-critical environments.
- Steel:Carbon steel bearing bars welded to cross rods deliver the highest load capacity per dollar. Gulf Coast petrochemical operators specify steel grating for offshore platform retrofits where insurance mandates drive replacement cycles.
- Aluminum:Press-locked aluminum panels reduce topside weight on offshore wind service vessels while maintaining heel-angle slip resistance. Coastal desalination plants in Florida and chemical processors along the Houston Ship Channel specify aluminum for salt exposure durability.
- Stainless Steel:Marine navigation infrastructure and food processing facilities demand 316-grade stainless for chloride resistance.
- Fiber Reinforced Plastic:Weight-critical rooftop access platforms and electrical substations specify FRP for dielectric properties.
The dominant share belongs to Steel, while Aluminum is closing the gap fastest.
Load Capacity:
Engineering certification requirements concentrate procurement in the upper tiers where specification barriers filter supplier pools.
- Heavy Duty:Rated 5 to 15 kN per square meter, these panels satisfy OSHA elevated walkway mandates. Texas-Louisiana petrochemical clusters require heavy duty certification traceable to specific production lots.
- Ultra Heavy Duty:Exceeding 15 kN ratings, this tier serves offshore drilling platforms and Great Lakes ore dock loading zones. Third-party laboratory capacity constraints extend UL certification timelines for new product introductions.
- Medium Duty:General manufacturing floors and warehouse mezzanines specify this tier for pedestrian and light cart traffic.
- Light Duty:Maintenance access and rooftop walkways utilize these panels where load requirements remain minimal.
Heavy Duty retains the largest specification volume, though Ultra Heavy Duty is expanding most quickly on energy infrastructure mandates.
Application:
End-use fragmentation follows facility type safety codes and maintenance budget cycles.
- Industrial Flooring:Open-grid panels span process equipment pits and tank farm perimeters. OSHA Walking-Working Surfaces standards force coefficient-of-friction documentation into every bid package.
- Walkways:Elevated access routes in refineries and ports require ASTM F1679 slip-resistance test data. Gulf Coast chemical plants reject shipments lacking traceable lot certificates.
- Trench Covers:Drainage infrastructure and utility vaults utilize these panels for load-bearing access.
- Stair Treads:Anti-slip nosings and abrasive coatings dominate specifications for vertical circulation safety.
Industrial Flooring holds the largest installed base, while Walkways is gaining share fastest on regulatory retrofit mandates.
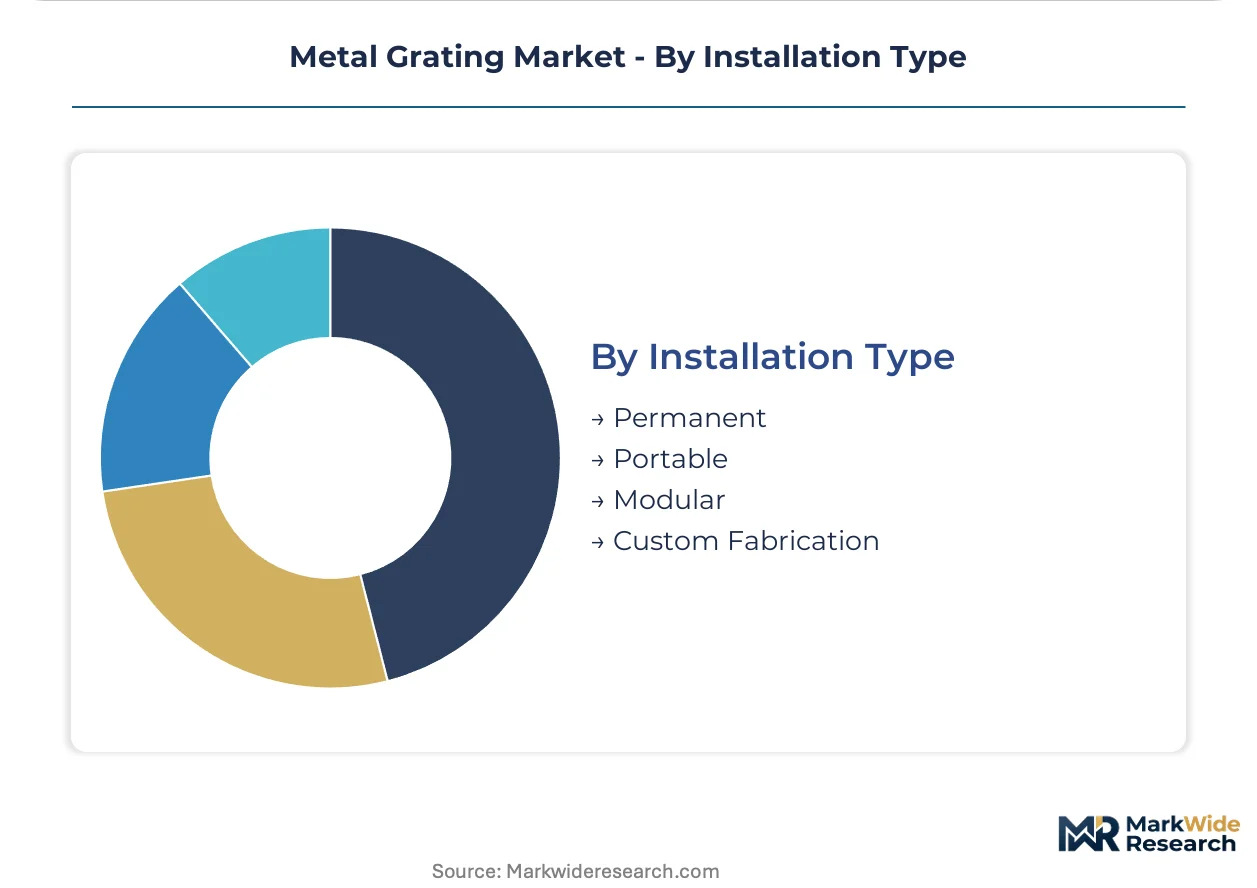
Installation Type:
Fabrication method determines lead time compression and field labor requirements.
- Permanent:Welded steel panels anchored to structural steel framing dominate heavy industrial construction. AWS D1.1 welding certification scarcity constrains fabrication cell throughput.
- Modular:Press-locked aluminum systems ship pre-certified for shipyard assembly. Offshore wind turbine service vessel operators demand these panel systems to reduce topside weight.
- Portable:Temporary access platforms for maintenance operations utilize quick-connect framing.
- Custom Fabrication:Configurator-enabled ordering compresses lead times for irregular dimensions in MRO procurement.
Permanent installation retains the dominant specification share, though Modular is climbing the fastest on offshore wind buildout timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in fabricated metal grating track closely to regional industrial safety mandates and energy infrastructure buildouts, with net exporters concentrated in steel-producing economies and coastal importers driven by offshore platform retrofit cycles.
United States
Gulf Coast petrochemical operators are expanding heavy-duty steel grating procurement for offshore platform retrofits ahead of insurance renewal deadlines. OSHA mandates elevated load-bearing standards for industrial walkways, compressing specification cycles and forcing pre-certification of suppliers. The Texas-Louisiana petrochemical corridor concentrates demand, with Houston Ship Channel facilities rejecting shipments lacking ASTM F1679 slip-resistance documentation.
Germany
Industrial machinery and chemical processing sectors drive specification demand for CE-marked gratings under EN ISO 14122 machinery access standards. The European Committee for Standardization mandates compliance barriers that filter non-certified imports, protecting domestic fabricators. The Ruhr industrial belt and Bavarian chemical clusters anchor production capacity, with Stuttgart-area engineering firms specifying press-locked aluminum systems for weight-critical applications.
China
Coastal desalination buildouts and chemical processing expansions are rotating demand toward corrosion-resistant aluminum grating specifications. MIIT and GB standards govern structural safety protocols, though enforcement varies by provincial industrial bureau. The Yangtze River Delta manufacturing belt and Pearl River Delta port infrastructure concentrate both production and consumption, with Shanghai-area fabricators serving domestic wind turbine service vessel construction.
Saudi Arabia
Green hydrogen electrolyzer facilities along the Gulf Coast require explosion-rated aluminum walkways around pressurized gas handling skids. The country's national industrial regulator mandates compliance with evolving safety codes for energy infrastructure. The Eastern Province industrial cities of Jubail and Yanbu concentrate petrochemical and emerging hydrogen project demand, with local specification authority shifting to owner-operator engineering teams.
United Kingdom
Offshore wind turbine service vessel operators specify modular press-locked aluminum grating to reduce topside weight while maintaining heel-angle slip resistance. Health and Safety Executive protocols align with EN ISO 14122 for machinery access, creating certification requirements for domestic installations. Scottish port facilities and North Sea marine infrastructure clusters drive specification windows, with Aberdeen-area shipyards demanding pre-certified panel systems.
Metal Grating Market Competitive Environment
Listed leaders compete with private specialists across certification capacity and regional distribution density, producing a tiered structure where scale-driven producers anchor heavy industrial procurement while regional fabricators capture maintenance-repair-operations volumes. Strategic archetypes include integrated steel producers leveraging captive raw material supply, specialized access product engineers, and regional distribution-focused fabricators. Competitive moves concentrate on welding certification expansion and direct-to-fabricator digital channel development.
Within the integrated steel producer archetype, Nucor Corporation occupies a position exemplifying backward integration into bearing bar supply. Among regional distribution-focused fabricators, Ohio Gratings and Alabama Metal Industries Corporation represent the Midwest and Southeast density strategies respectively. Valmont Industries sits within the specialized engineered access products tier, anchoring utility and infrastructure client relationships. These three named entities illustrate the competitive structure without exhausting its full composition.
| Leading Market Players |
|---|
| Nucor Corporation |
| Valmont Industries |
| Ohio Gratings |
| Interstate Gratings |
| Alabama Metal Industries Corporation |
| P&R Metals |
| Lionweld Kennedy |
| Lichtgitter GmbH |
| Grating Pacific |
| Others |
Value Chain & Pricing Dynamics
Integrated electric arc furnace capacity utilization across the US Gulf Coast anchors bearing bar supply concentration, compressing price floors for welded steel grating while elevating margin capture for producers with captive scrap feedstock. Scale-driven producers leverage backward integration into raw steel supply to defend pricing power against volatile scrap demolition flows.
Pricing Analysis
Industrial OEM buyers anchor a contract-based long-term offtake pricing structure across heavy-duty and ultra-heavy-duty tiers. Price differentiation centers on AWS D1.1 welding certification grade and UL/Intertek third-party load-test documentation, with premium tiers commanding substantial markups for traceable lot production. Cost compression in standard welded bar products is intensifying because Asian import shipments face extended customs verification delays. Maintenance-repair-operations procurement teams exhibit highest price sensitivity, while offshore platform operators prioritize certification compliance over unit economics.
Supply Chain Analysis
The United States, China, and Germany anchor fabricated grating production capacity across distinct specification tiers. Raw material inputs draw from electric arc furnace steel scrap, primary aluminum ingot, and 316-grade stainless steel billet. Tariff exposure on Asian fabricated shipments creates structural risk for distributors dependent on import arbitrage. Distribution runs through direct-to-fabricator digital channels and regional stocking distributors serving Texas-Louisiana petrochemical clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-entrenchment defensive moat where OSHA and EN ISO 14122 certification requirements create switching costs that lock asset owners into pre-qualified supplier relationships. Engineering specification authority consolidation amplifies incumbent advantage.
For Market Incumbents: Secure AWS D1.1 welding certification expansion in fabrication cells to constrain throughput bottlenecks that emerging competitors exploit. Extend backward integration into scrap steel brokerage to buffer margin pressure from automotive shredder output volatility. Defend against fiber-reinforced polymer substitution by embedding coefficient-of-friction testing documentation into master service agreement templates.
For New Entrants and Emerging Players: CE-marking fast-track certification under EN ISO 14122 machinery access standards opens specification windows in European export markets and adjacent industrial safety sectors. Target modular press-locked aluminum systems for offshore wind turbine service vessel construction where shipyards demand pre-certified panel assemblies. Pursue direct-to-fabricator digital channel partnerships to compress lead times in maintenance-repair-operations procurement.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among regional fabricators with dense Midwest distribution networks and captive engineering specification relationships. Long-term viability over a multi-year horizon rests on welding certification capacity and digital configurator deployment. Target acquisition archetypes include second-generation family-owned fabricators with untapped AWS D1.1 coded welder benches. Monitor Army Corps of Engineers inland waterway lock rehabilitation appropriations as inflection signal for stainless steel grating demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| AWS D1.1 Welding Certification Expansion | Addresses coded welder scarcity constraining heavy-duty fabrication cell throughput across Gulf Coast producers. |
| Backward Integration into Scrap Steel Brokerage | Buffers margin volatility from automotive demolition output swings affecting electric arc furnace feedstock costs. |
| CE-Marking Fast-Track Certification | Unlocks European machinery access specification windows under EN ISO 14122 compliance barriers. |
| Direct-to-Fabricator Digital Channel Deployment | Compresses lead times for custom-cut panels in maintenance-repair-operations procurement cycles. |
| Modular Press-Locked Aluminum System Launch | Captures offshore wind turbine service vessel demand for weight-reduced, pre-certified panel assemblies. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of customs trade data, SEC manufacturing filings, OSHA regulatory dockets, and EN ISO standard harmonization records. Primary interviews engaged plant engineers at Gulf Coast petrochemical operators, procurement leads at offshore platform contractors, AWS-certified welding supervisors, and aftermarket service heads at regional distribution fabricators. Bottom-up demand modeling triangulated against top-down steel consumption benchmarks validates volume estimates.
Segmentation dimensions modeled span material chemistry, load capacity tier, application context, and installation type across the projection horizon. CAGRs derive from regression analysis of historic procurement cycles correlated with insurance renewal timelines and regulatory retrofit mandates. Industry-specific forecast inputs incorporate Army Corps of Engineers maintenance backlogs and green hydrogen electrolyzer facility development pipelines.
Underlying assumptions cover OSHA enforcement continuity and EN ISO 14122 harmonization stability, with deviation risk concentrated in scrap steel price volatility and composite material substitution acceleration. Recalibration cycles align with material shifts in regulatory load-bearing mandates and offshore wind installation timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Thin Wall Mould Market
Building & Construction Materials
Fire Rated Glass Market
Building & Construction Materials
Geogrid Market
Building & Construction Materials
Sound Barriers Market
Building & Construction Materials
Global Wooden Formwork Systems Market
Building & Construction Materials
Mosaic Tiles Market
Building & Construction Materials
Fiberglass Light Poles Market
Building & Construction Materials
Roofing Underlayment Market
Building & Construction Materials
South Africa Wall Putty Market
Building & Construction Materials
Global Shotcrete/Sprayed Concrete Market
Building & Construction Materials
GCC Exterior Sheathing Market
Building & Construction Materials
Silos Market
Building & Construction Materials
US Geosynthetics Market
Building & Construction Materials
Fiberglass Doors Market
Building & Construction Materials
Exterior Wall System Market
Building & Construction Materials
Magnesium Oxide Boards Market